
 Glasses Free 3D Display Market | 2026-2036
Glasses Free 3D Display Market Size, Share, and Industry Trends Forecast 2026-2036
Glasses Free 3D Display Market Foresight
Parallax barrier-to-lenticular lens migration is tilting the manufacturing stack toward thinner, brighter panels with wider viewing angles. Samsung Electronics leverages its semiconductor foundry integration to sustain captive supply of custom backlight drivers. AUO Corporation anchors Taiwan's display ecosystem with dedicated autostereoscopic production lines. Leia Inc. differentiates through light field software layers that extend hardware utility across mobile and automotive endpoints.
Glasses free 3D displays render stereoscopic depth without wearable optics through lenticular lens arrays or parallax barriers that direct discrete image columns to each eye, typically operating at refresh rates above 120 Hz to suppress motion artifacts in multi-view configurations. The technology serves commercial purposes ranging from medical volumetric visualization to automotive head-up displays where driver distraction must be minimized. Autostereoscopic displays occupy the dominant revenue position due to established manufacturing tooling and immediate compatibility with existing LCD infrastructure. Light field displays represent the fastest-expanding technology segment as computational photography advances reduce rendering overhead for real-time applications. Holographic displays concentrate margin pools in defense simulation and medical imaging where true volumetric representation commands premium pricing.
FCC emissions standards in the United States constrain wireless-enabled 3D signage deployments, while REACH compliance in Europe limits certain phosphor and rare-earth element formulations in backlight assemblies. China's GB standards for display energy efficiency and MIIT directives on indigenous technology procurement reshape competitive access for foreign panel suppliers. Stakeholders must monitor regulatory divergence between jurisdictions where electromagnetic compatibility rules and content localization mandates increasingly determine product certification timelines and market entry sequencing.
Market Dynamics
The transition from parallax barrier to lenticular lens architectures is compressing panel thickness while widening effective viewing cones, forcing display manufacturers to retool legacy LCD lines or risk obsolescence in premium segments.
Growth Catalysts
- MIIT indigenous procurement directives:China's mandates for domestic technology adoption in government and healthcare procurement channels accelerate local panel vendor qualification cycles and captive demand formation.
- Surgical planning visualization:Healthcare systems in Japan and South Korea deploy autostereoscopic monitors for pre-operative volumetric review, creating pull for high-resolution multi-view configurations.
- Lenticular lens maturation:Precision micro-lens array manufacturing advances reduce optical crosstalk below perceptual thresholds, enabling thinner form factors without brightness penalties.
Market Restraints
- Rare-earth phosphor cost volatility:Backlight assembly formulations depend on terbium and europium supply concentrated in Chinese refining operations, exposing margin stability to export quota fluctuations.
- FCC emissions compliance:Wireless-enabled 3D signage deployments face extended certification timelines for electromagnetic compatibility testing, delaying retail and out-of-home network rollouts.
- Viewing angle technical limitation:Current autostereoscopic implementations restrict effective depth perception to narrow positional windows, limiting shared-screen applications in automotive and public settings.
Strategic Opportunities
- Automotive HUD convergence:Light field display integration with augmented reality navigation systems addresses driver distraction mandates while opening premium vehicle trim differentiation.
- India medical imaging penetration:Radiology infrastructure expansion under government health schemes creates first-mover positioning for diagnostic-grade autostereoscopic workstations.
- EU CSRD sustainability reporting:Mandatory supply chain disclosure requirements favor panel suppliers with verified low-carbon manufacturing, rewarding early REACH and RoHS compliance investments.
Industry Challenges
- Computational optics talent scarcity:Light field rendering algorithm development requires rare cross-training in wave optics and real-time graphics pipelines, constraining R&D velocity.
- Multi-jurisdiction certification complexity:Simultaneous FCC, CE marking, and GB standard compliance for wireless-integrated displays extends product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glasses Free 3D Display Market |
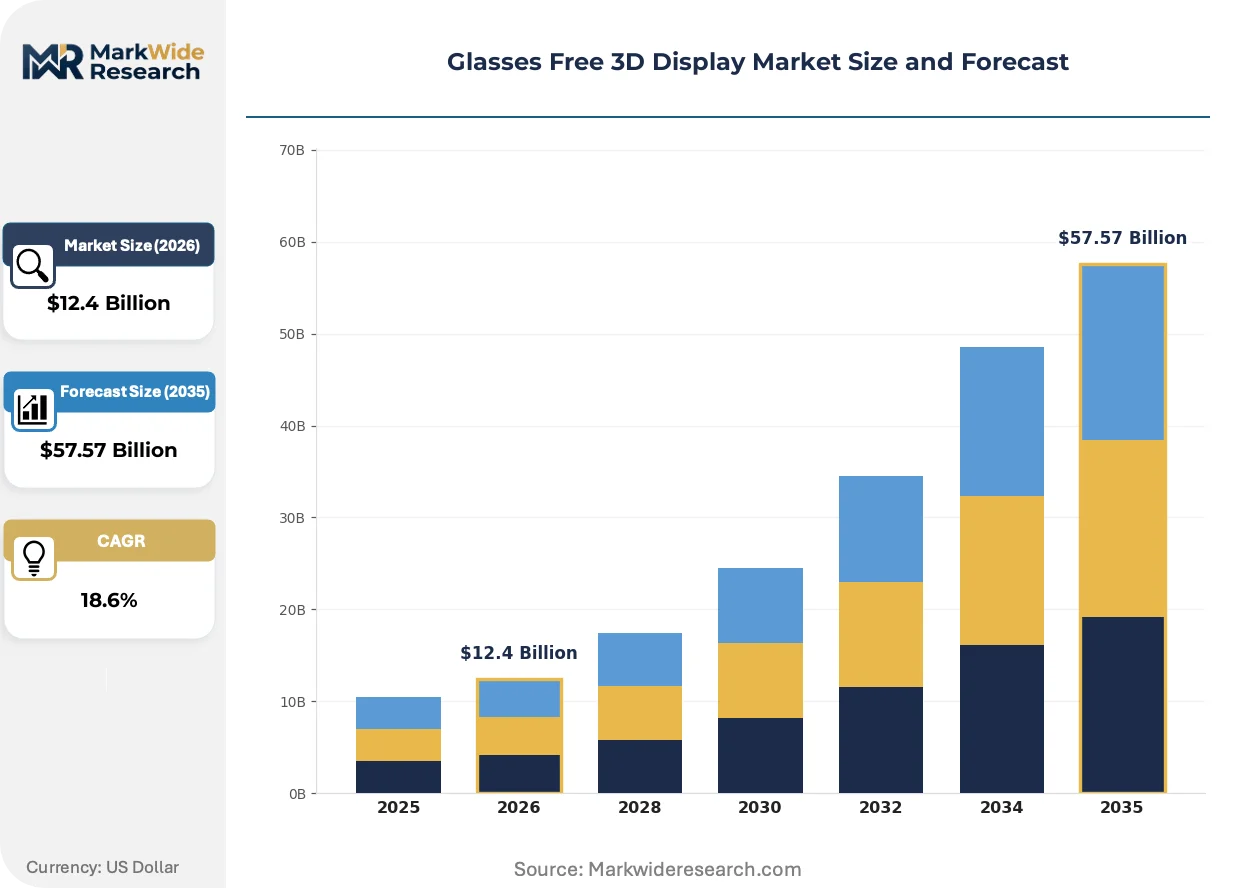
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $57.57 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autostereoscopic Displays, Light Field Displays, Holographic Displays, Integral Imaging Displays, Volumetric Displays Technology: Parallax Barrier, Lenticular Lens, Multi-view, Electro-Holography, Digital Light Processing, Integral Imaging Application: Entertainment Systems, Public Signage, Medical Imaging, Defense Simulations, Automotive HUDs, Retail Kiosks End User: Consumer Electronics Manufacturers, Healthcare Providers, Defense Agencies, Automotive Suppliers, Advertising Agencies |
| Companies Covered | Alioscopy, Leyard, TCL Corporation, AUO Corporation, Evistek, Exceptional 3D, Dimenco, Leia Inc., Samsung Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glasses Free 3D Display Market Shifts & Advancements
Display architecture decisions are increasingly driven by software-defined viewing experiences rather than fixed hardware configurations, blurring traditional boundaries between panel manufacturing and computational imaging.
Lenticular lens arrays with sub-pixel-aligned cylindrical optics are migrating from parallax barrier legacy implementations in mobile and tablet form factors. Automotive Tier 1 suppliers adopt these thinner stacks for head-up display integration at accelerated qualification paces. The technology is migrating from niche medical visualization toward mass-market consumer electronics, compressing price positioning for established LCD vendors.
REACH restrictions on cadmium and certain rare-earth phosphor formulations are forcing backlight unit redesigns across European-bound product lines. ECHA substance evaluation updates are eliminating legacy phosphor options without immediate drop-in replacements. Medical imaging OEMs face the steepest reformulation costs, driving consolidation toward qualified Asian phosphor compounders with pre-certified alternative chemistries.
Healthcare procurement departments now specify volumetric visualization capability as a discrete tender requirement, displacing traditional 2D diagnostic monitor specifications. Radiology group purchasing organizations in Germany and France embed autostereoscopic compatibility into multi-year equipment contracts. This specification-driven preference shift concentrates demand among panel vendors with FDA and CE-MDR dual certifications, favoring established medical display specialists over consumer electronics entrants.
Glasses Free 3D Display Market Segmentation
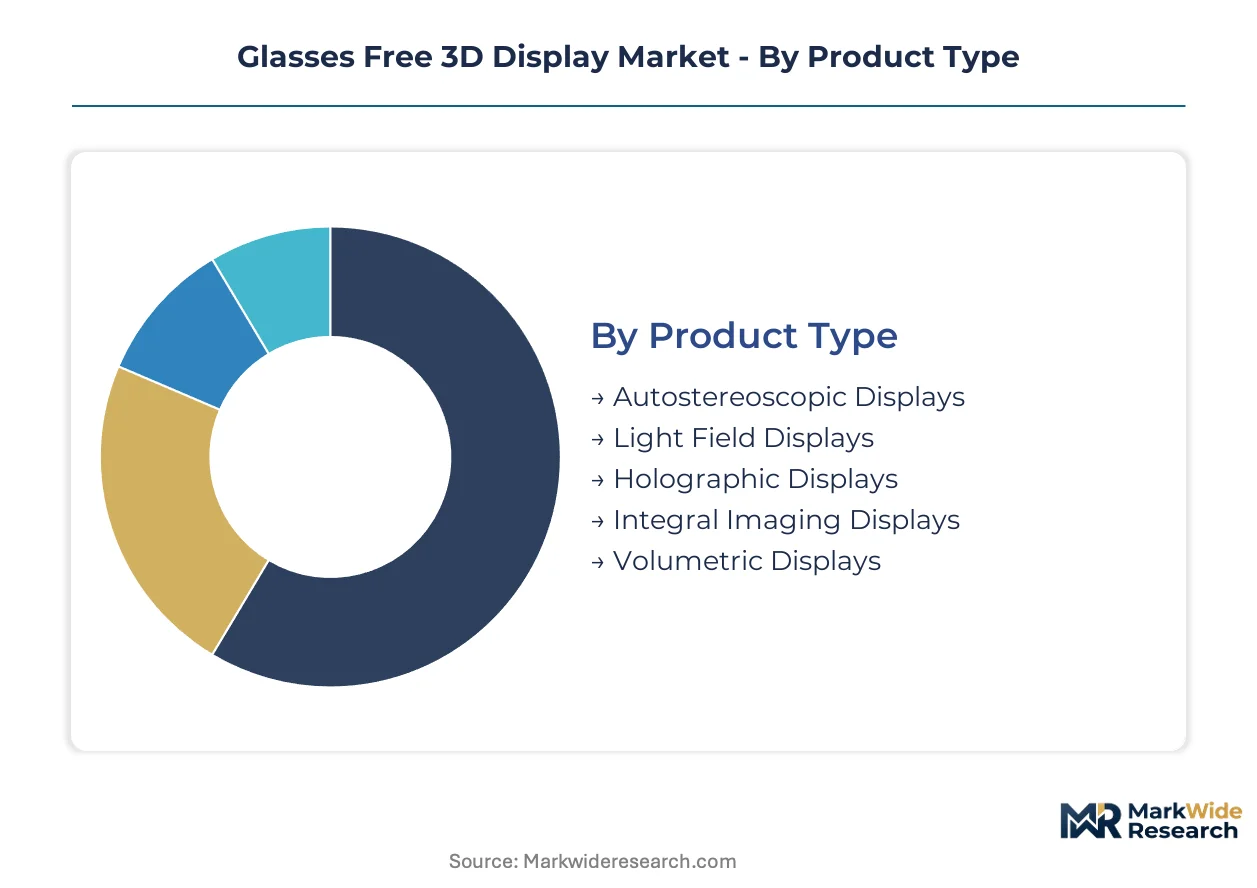
Technology architecture choices in glasses-free 3D displays cascade through manufacturing cost structures, certification requirements, and end-user procurement criteria. Each segmentation dimension reveals distinct margin pools and competitive entry barriers.
Product Type:
Cost tier stratification separates established volume production from emerging premium formats requiring specialized fabrication equipment.
- Autostereoscopic Displays:Lenticular lens or parallax barrier architectures direct discrete image columns to each eye without wearable optics, typically operating above 120 Hz refresh rates. Medical imaging departments in Japan and South Korea specify these monitors for pre-operative volumetric review, pulling demand toward high-resolution multi-view configurations with FDA and CE-MDR dual certifications.
- Light Field Displays:Computational photography arrays capture and reproduce continuous parallax across viewing positions, enabling focus cues that reduce vergence-accommodation conflict. Automotive Tier 1 suppliers integrate these thinner stacks for augmented reality head-up displays, accelerating qualification paces under NHTSA distraction mandates and EU General Safety Regulation requirements.
- Holographic Displays:Electro-holographic interference patterns reconstruct true volumetric light fields for defense simulation and premium medical visualization where spatial fidelity commands specialized procurement budgets.
- Integral Imaging Displays:Microlens arrays capture multiple perspectives through a single aperture, finding niche deployment in museum exhibits and architectural visualization where static viewing positions predominate.
- Volumetric Displays:Swept-volume or static volume techniques render imagery in physical three-dimensional space, concentrating in command-and-control centers requiring 360-degree collaborative viewing without head-tracking constraints.
Autostereoscopic displays hold installed capacity. Light field displays are rotating up the share rankings.
Technology:
Application requirements dictate optical engine selection, with brightness constraints and viewing angle specifications filtering viable architectures for each deployment context.
- Parallax Barrier:Alternating opaque and transparent stripes block light paths to create binocular disparity, sacrificing luminance for manufacturing simplicity in cost-sensitive mobile implementations.
- Lenticular Lens:Precision-molded cylindrical lens arrays overlay display panels to direct angularly separated images, compressing module thickness while widening effective viewing cones compared to barrier alternatives. Samsung Electronics leverages semiconductor foundry integration for captive backlight driver supply supporting these transitions.
- Multi-view:Simultaneous projection of eight or more perspectives enables motion parallax without head tracking, serving digital signage networks in Shanghai and Seoul transit hubs where viewer position varies unpredictably.
- Electro-Holography:Spatial light modulators reconstruct interference patterns in real time, requiring computational throughput that limits current implementations to specialized medical and defense workstations.
- Digital Light Processing:Micromirror arrays project structured light patterns for volumetric or multi-view reconstruction, finding application in theme park attractions and large-venue entertainment systems.
- Integral Imaging:Lenslet arrays integrated directly with image sensors or displays capture light field information, deployed in metrology and quality inspection systems where precise depth measurement replaces human viewing.
Lenticular lens architectures are gaining share fastest. Parallax barrier retains position in entry-level mobile specifications.
Application:
Customer procurement cycles range from consumer electronics seasonal refresh patterns to multi-year healthcare equipment tenders with embedded service contracts.
- Entertainment Systems:Gaming monitors and handheld devices integrate autostereoscopic panels for immersive content consumption without accessory dependencies.
- Public Signage:Transit hubs and retail environments deploy multi-view displays for advertising effectiveness measurement through gaze tracking integration.
- Medical Imaging:Pre-operative surgical planning and diagnostic radiology specify volumetric visualization capability as discrete tender requirements, displacing traditional 2D monitor specifications in German and French group purchasing organization contracts.
- Defense Simulations:True volumetric holographic displays command premium positioning for pilot training and battlefield visualization where spatial depth accuracy affects operational decision rehearsal.
- Automotive HUDs:Light field integration with augmented reality navigation addresses driver distraction mandates under NHTSA guidelines and EU General Safety Regulation, opening premium vehicle trim differentiation for Tier 1 suppliers.
- Retail Kiosks:Interactive product visualization stations in duty-free and electronics retail deploy autostereoscopic screens for engagement metrics without hygiene concerns of shared eyewear.
Medical imaging holds the steepest expansion trajectory. Automotive HUDs are climbing the share rankings fastest.
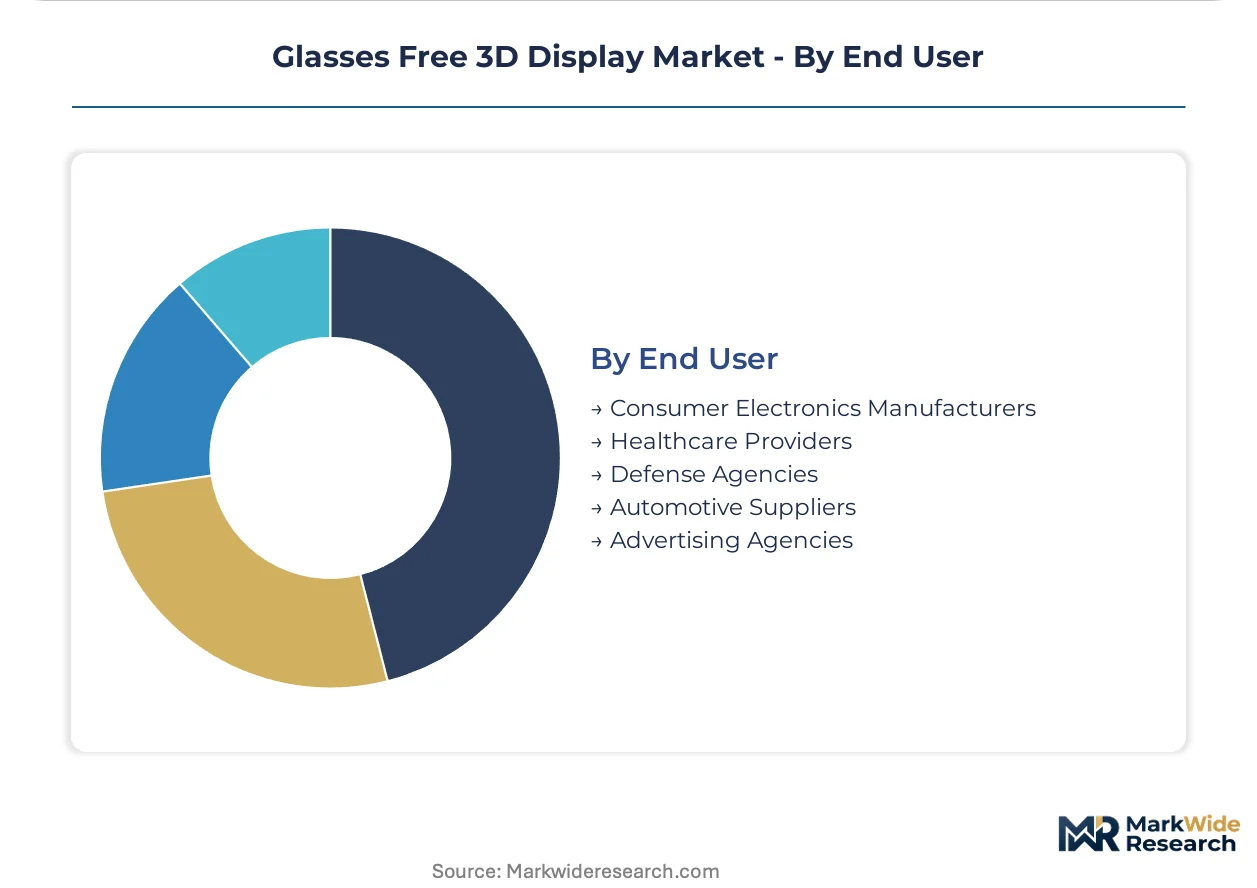
End User:
Volume concentration and margin structure diverge sharply between consumer electronics scale production and specialized vertical procurements with certification barriers.
- Consumer Electronics Manufacturers:Smartphone and tablet OEMs in China, Japan, and South Korea drive panel ecosystem scale, with MIIT indigenous procurement directives accelerating local vendor qualification.
- Healthcare Providers:Radiology departments and surgical centers specify diagnostic-grade autostereoscopic workstations, concentrating demand among vendors with FDA and CE-MDR dual certifications.
- Defense Agencies:Simulation and training commands prioritize true volumetric representation for mission rehearsal accuracy, sustaining premium pricing pools despite limited volume.
- Automotive Suppliers:Tier 1 display integrators qualify light field architectures for head-up display convergence with augmented reality navigation systems.
- Advertising Agencies:Out-of-home network operators face extended FCC emissions certification timelines for wireless-enabled 3D signage deployments, delaying retail rollout schedules.
Consumer electronics manufacturers hold installed capacity. Healthcare providers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare procurement departments and consumer electronics OEMs concentrate demand across distinct national clusters, each shaped by indigenous technology mandates and specialized manufacturing ecosystems.
China
MIIT procurement directives accelerate local panel vendor qualification for government and healthcare channels. GB standards for display energy efficiency reshape competitive access for foreign suppliers. Shenzhen and Suzhou manufacturing clusters anchor lenticular lens production capacity serving domestic smartphone OEMs.
Japan
Radiology departments specify autostereoscopic monitors for pre-operative volumetric review in multi-year equipment tenders. PMDA medical device regulations favor vendors with established quality management systems. Tokyo-Osaka industrial corridors concentrate precision optics fabrication for diagnostic-grade displays.
South Korea
Samsung Electronics and domestic display ecosystem drive captive demand for custom backlight driver integration. MFDS medical device certification requirements filter market entry for foreign panel suppliers. Gyeonggi-do and Daegu-Gyeongbuk regions host dedicated autostereoscopic production lines.
United States
FCC emissions standards constrain wireless-enabled 3D signage deployment timelines for retail network operators. FDA 510(k) pathways for diagnostic displays create certification barriers for consumer electronics entrants. California and Texas technology corridors concentrate light field software development for automotive HUD applications.
Germany
Group purchasing organizations in radiology embed autostereoscopic compatibility into multi-year equipment contracts. ECHA REACH restrictions on rare-earth phosphor formulations force backlight unit redesigns for European-bound product lines. Bavaria and Baden-Württemberg precision engineering clusters support medical display specialist manufacturing.
Glasses Free 3D Display Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Samsung Electronics and TCL Corporation leverage semiconductor and consumer electronics scale against medical imaging specialists like AUO Corporation. Three archetypes dominate: integrated electronics conglomerates with captive display fabs, precision optics specialists serving certified medical verticals, and light field software layer providers extending hardware utility. Dominant competitive moves include backward integration into custom backlight driver supply and geographic expansion through MIIT-compliant local production partnerships.
Within the integrated electronics tier, Samsung Electronics exemplifies channel control through semiconductor foundry integration, while TCL Corporation represents scale-driven consumer electronics positioning. AUO Corporation anchors the precision optics specialist archetype with dedicated autostereoscopic production lines. Leia Inc. occupies a distinct software-defined positioning, extending hardware utility across mobile and automotive endpoints through computational imaging layers.
| Leading Market Players |
|---|
| Alioscopy |
| Leyard |
| TCL Corporation |
| AUO Corporation |
| Evistek |
| Exceptional 3D |
| Dimenco |
| Leia Inc. |
| Samsung Electronics |
| Others |
Supply & Pricing Matrix
Shenzhen and Suzhou manufacturing clusters anchor lenticular lens production capacity, concentrating optical component supply among domestic Chinese vendors who command pricing leverage over foreign panel assemblers seeking GB standards compliance.
Pricing Analysis
Long-term offtake contracts with terbium and europium indexation dominate backlight unit procurement, with pricing stratifying across FDA-certified medical tiers, standard commercial specifications, and economy-grade mobile implementations. Cost compression in entry-level mobile panels is intensifying because MIIT indigenous procurement directives favor domestic vendors with captive rare-earth refining access. Healthcare providers exhibit the lowest price sensitivity due to volumetric visualization mandates in German and French radiology tenders, while consumer electronics OEMs negotiate aggressively on volume scale.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for wireless-enabled 3D signage deployments facing extended FCC certification timelines. Precision micro-lens array fabrication concentrates in China, Japan, and South Korea, with rare-earth phosphor formulations drawing from Chinese refining operations concentrated in Jiangxi and Inner Mongolia. Single-source vulnerability in terbium supply exposes margin stability to export quota fluctuations. Distribution runs through display panel OEMs with captive integration into smartphone, automotive Tier 1, and medical imaging OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The glasses-free 3D display market is entering a cyclical recovery phase as healthcare procurement cycles normalize and automotive HUD qualification paces accelerate under NHTSA distraction mandates.
For Market Incumbents: Pre-empt emerging light field software competitors by deepening captive control over custom backlight driver supply through semiconductor foundry integration, and accelerate FDA 510(k) pathway investments to defend medical imaging share against consumer electronics entrants seeking diagnostic-grade certification.
For New Entrants and Emerging Players: India's radiology infrastructure expansion under government health schemes offers first-mover positioning for diagnostic-grade autostereoscopic workstations, with EU CSRD sustainability reporting creating procurement preference for verified low-carbon manufacturing among REACH-compliant panel suppliers.
For Investors and Strategic Acquirers: Long-term, this sits as a vertical specialization play because computational optics talent scarcity constrains R&D velocity for light field rendering algorithms, favoring acquisition targets with cross-trained wave optics and real-time graphics capabilities; watch for automotive HUD design win announcements as inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Phosphor Supply | Mitigates terbium cost volatility from Chinese export quotas for backlight unit stability. |
| FDA 510(k) Dual Certification Investment | Unlocks German and French radiology GPO contracts displacing 2D monitor specifications. |
| Automotive Tier 1 HUD Design Partnership | Accelerates NHTSA-compliant qualification for augmented reality navigation integration. |
| MIIT-Compliant Local Production Partnership | Secures government and healthcare procurement channel access under indigenous technology mandates. |
| Light Field Software Layer Development | Extends hardware utility across mobile and automotive endpoints through computational imaging. |
Research Methodology
Cross-validation between primary interviews with display panel procurement managers, automotive Tier 1 integration engineers, and hospital biomedical equipment committees and secondary validation against SEC 10-K filings, MIIT directive publications, and FDA 510(k) clearance databases anchors the qualitative findings. Bottom-up and top-down triangulation reconciles vendor shipment data with end-user procurement records.
Calibration against historical technology adoption curves and medical equipment replacement cycles shapes the analytical framework across the projection horizon, with segmentation modeling across product type, technology architecture, application vertical, and end-user procurement tier. CAGRs derive from weighted average of scenario-based growth paths incorporating lenticular lens maturation trajectories and regulatory certification timeline assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese panel vendors or accelerated REACH phosphor restrictions would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Multi-Touch Screen Market
Display Technologies
Thin Display Technology Market
Display Technologies
AMOLED Display Market
Display Technologies
4K Technology Market
Display Technologies
Glass-Free HD 3D Display Market
Display Technologies
Electronic Display Market
Display Technologies
Laptop Panels Market
Display Technologies
Quantum Dot Display Market
Display Technologies
Display Semiconductor Components Market
Display Technologies
Video Wall Display Market
Display Technologies
Rental Outdoor LED Display Market
Display Technologies
Commercial Touch Display Market
Display Technologies
Smart Display Market
Display Technologies
Global Smartphone Display Panel Market
Display Technologies
3LCD Projector Market
Display Technologies
Global Portable Monitor Market