
 Polarizing Film for Displays Market | 2026-2036
Polarizing Film for Displays Market Size, Share, and Industry Trends Forecast 2026-2036
Polarizing Film for Displays Market Insights
Automotive display buyers are unwinding the historical dominance of television and smartphone OEMs in polarizer procurement. Nitto Denko anchors the high-performance segment through its iodine-dye hybrid technology leadership. Samsung SDI competes aggressively in OLED-grade circular polarizers for foldable panels. Sumitomo Chemical leverages captive polyvinyl alcohol resin production to sustain margin control across the value chain.
Polarizing film for displays is an optical polymer laminate that selectively transmits light waves oriented along a single plane, typically constructed from stretched polyvinyl alcohol layers bonded to triacetate cellulose protective substrates with iodine or dichroic dye absorption. Its primary commercial purpose is to modulate light transmission in liquid crystal and organic light-emitting diode panels, enabling contrast control and color fidelity in electronic displays. Circular polarizers lead the premium tier due to OLED proliferation in mobile devices and automotive curved screens, while linear polarizers retain volume dominance in LCD television applications where cost efficiency outweighs performance differentiation. Transmissive film configurations command the largest application share across television screens and digital signage installations, whereas reflective film variants serve niche industrial equipment and outdoor instrumentation markets with lower backlight power requirements.
Japan's METI enforces JIS standards on optical film durability and haze specifications, while South Korea's MFDS and environmental regulators impose substance restrictions on adhesive chemistries used in polarizer lamination. China's SAMR and GB standards mandate energy efficiency disclosures that cascade into polarizer transmission ratio requirements for domestic panel exports. REACH compliance in Europe constrains halogenated compound usage in film coatings, reshaping supplier qualification protocols. Stakeholders must monitor how automotive safety regulators in Germany and Japan integrate display readability standards into type-approval frameworks for next-generation cockpit architectures.
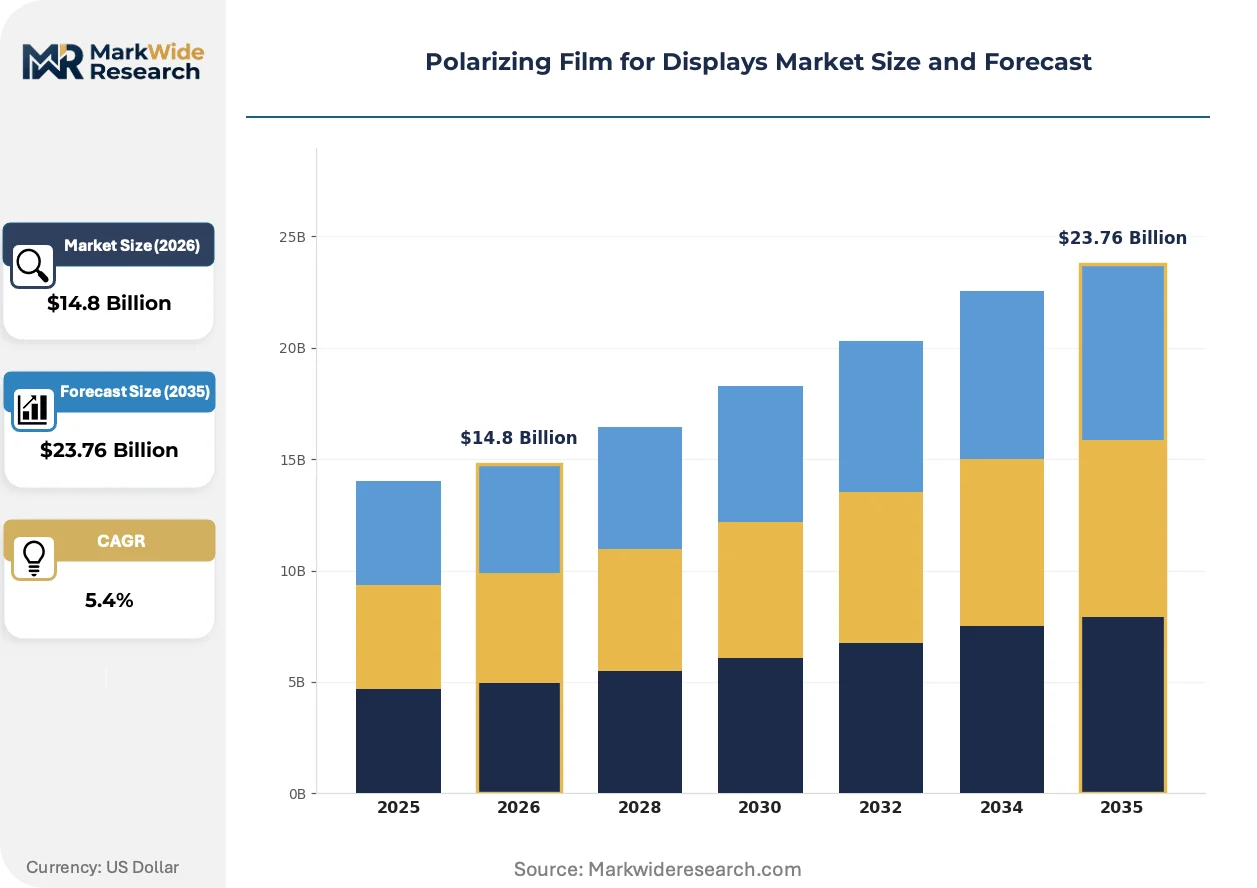
Market Dynamics
Automotive OEM procurement of polarizing films is fragmenting the historical concentration of demand around consumer electronics manufacturers, as curved OLED panels in electric vehicle cockpits require specialized circular polarizer specifications that differ from television and smartphone applications.
Growth Catalysts
- China's dual carbon goals:Energy efficiency mandates under MEE and GB standards are forcing panel makers to source higher-transmission polarizers for domestic display exports, tightening material specifications across the supply chain.
- Foldable OLED proliferation:Mechanical durability requirements for bendable panels are accelerating adoption of dye-based polarizer chemistries that resist humidity degradation better than traditional iodine-doped films.
- South Korean manufacturing clusters:Captive polarizer supply relationships between Seoul-based panel makers and dedicated film converters are compressing qualification timelines for next-generation display technologies.
Market Restraints
- Polyvinyl alcohol resin concentration:Japanese chemical conglomerates control over 70% of specialized PVA feedstock production, creating input cost volatility and supply security risks for downstream film laminators.
- REACH substance restrictions:ECHA constraints on halogenated compounds in European-bound film coatings are forcing reformulation of adhesive chemistries and extending supplier qualification protocols by 12-18 months.
- LCD volume compression:Linear polarizer demand tied to television panel production faces structural pressure as OLED gains share in premium display segments, stranding capacity optimized for older absorption technologies.
Strategic Opportunities
- Head-up display integration:Windshield-projection systems in premium electric vehicles require wide-view-angle polarizers with anti-reflective properties, opening a white-space application beyond conventional panel formats.
- India's PLI scheme for display manufacturing:Central government incentives for domestic panel fabs are creating first-mover advantages for polarizer suppliers establishing local lamination and finishing operations.
- Quantum dot-OLED convergence:Hybrid display architectures combining color conversion layers with emissive backplanes demand polarizers with refined spectral transmission profiles, enabling premium pricing for specialized film grades.
Industry Challenges
- Optical film metrology talent scarcity:Specialized expertise in birefringence measurement and haze characterization is concentrating at Japanese and South Korean equipment vendors, constraining quality control scaling for new market entrants.
- Automotive qualification timelines:KBA and Japan's Ministry of Land, Infrastructure, Transport and Tourism are integrating display readability standards into vehicle type-approval frameworks, extending certification cycles for cockpit panel suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polarizing Film for Displays Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $23.76 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reflective Film, Transmissive Film, Circular Polarizer, Linear Polarizer End User: Consumer Electronics, Automotive Displays, Industrial Equipment, Medical Devices Technology: LCD Technology, OLED Technology, LED Technology, Projection Technology Application: Mobile Devices, Television Screens, Digital Signage, Instrumentation |
| Companies Covered | Nitto Denko, Sumitomo Chemical, LG Chem, Samsung SDI, BenQ Materials, CMMT, SAPO, Dai Nippon Printing, Optimax, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polarizing Film for Displays Market Trends and Innovations
Competition between iodine-dye hybrid formulations and pure dye-based chemistries is fragmenting the technical basis of polarizer manufacturing, as performance requirements diverge across mobile, automotive, and television end-uses.
Water-resistant polarizer stacks are fragmenting the traditional protective film architecture. These laminates replace conventional triacetate cellulose with cyclic olefin polymer substrates to withstand high-humidity automotive environments. Tier 1 panel suppliers in Stuttgart and Nagoya are qualifying these stacks for curved instrument clusters. The shift is fragmenting equipment vendor relationships as new substrate handling protocols displace legacy TAC-optimized production lines.
Japan's METI is tightening JIS durability standards for optical films used in outdoor and vehicular applications. The revised specifications mandate extended thermal cycling performance and reduced haze degradation under UV exposure. Automotive display module assemblers in Toyota City and Munich are now requiring polarizer suppliers to submit accelerated aging test data beyond previous television-grade benchmarks.
Direct procurement relationships between automotive OEMs and polarizer manufacturers are compressing the traditional panel-maker intermediary layer. Hyundai Motor and BYD have established technical exchange programs with film laminators to co-develop curved panel specifications. This disintermediation is most visible in South Korea and China, where electric vehicle production volumes justify dedicated polarizer development programs outside consumer electronics supply chains.
Polarizing Film for Displays Market Segmentation
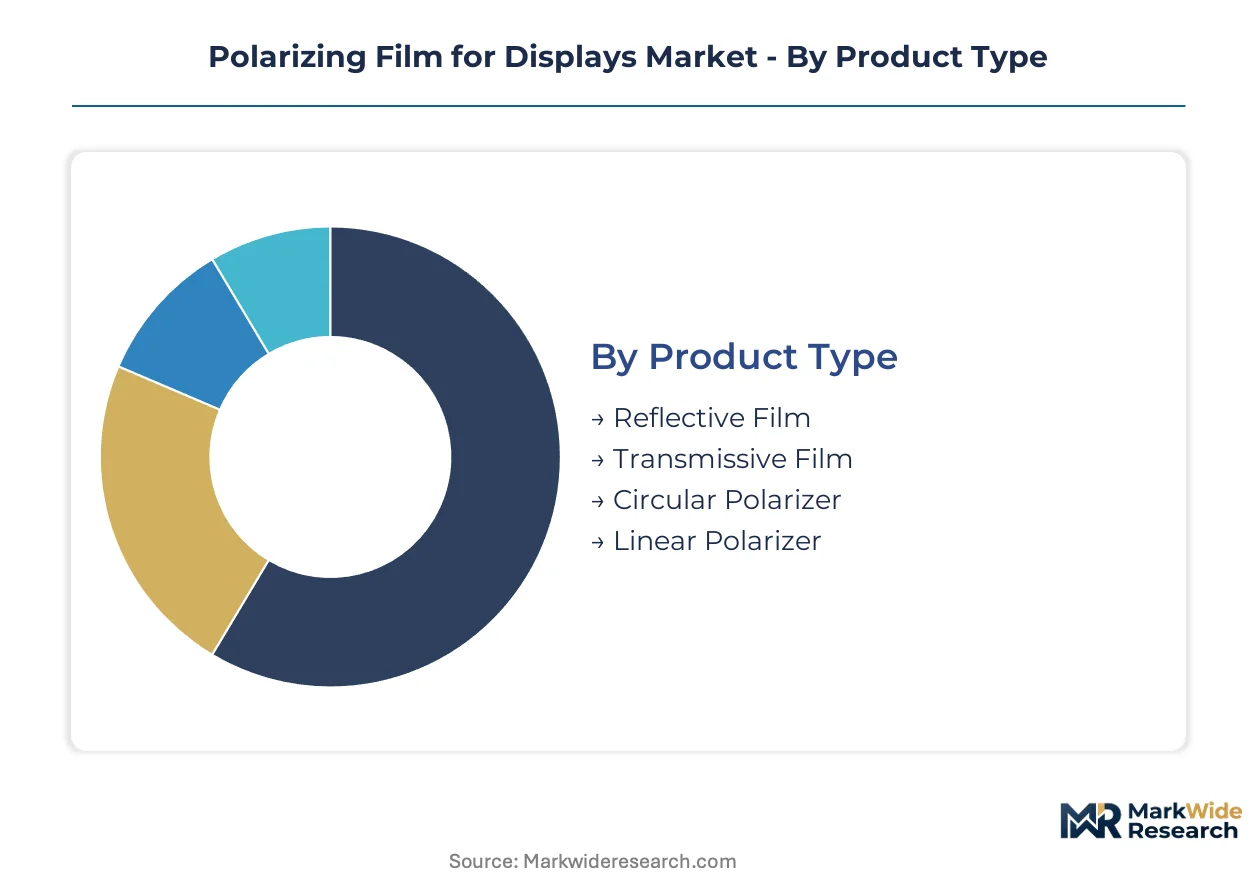
Polarizing film procurement channels diverge sharply across end-use applications, with automotive OEMs now demanding direct supplier relationships that bypass traditional panel-maker intermediaries. Each segmentation dimension reveals distinct margin structures, qualification protocols, and technical specifications that reshape competitive positioning.
Product Type:
Circular polarizers flow predominantly through mobile and automotive channels requiring OLED compatibility, while linear variants serve high-volume television manufacturing through established panel supply chains.
- Circular Polarizer:Constructed from quarter-wave retarder layers laminated to linear polarizer substrates with precise optical axis alignment. Demand concentrates in South Korean foldable smartphone manufacturing and German premium electric vehicle cockpit programs, where humidity-resistant dye formulations command premium positioning against iodine-doped alternatives.
- Linear Polarizer:Comprises stretched polyvinyl alcohol films with iodine absorption sandwiched between triacetate cellulose protective layers. Volume concentrates in Chinese television panel fabs serving domestic and export LCD markets, facing structural pressure as OLED gains share in premium display tiers.
- Transmissive Film:Optimized for backlight-dependent display architectures with high optical transmission ratios. Dominates digital signage installations and commercial television production.
- Reflective Film:Incorporates diffuse reflector layers for ambient light utilization in low-power applications. Serves industrial instrumentation and outdoor equipment segments with limited backlight infrastructure.
By volume, linear polarizers lead. By growth pace, circular polarizers are expanding most quickly.
End User:
Cost tier stratification separates premium automotive specifications from commodity consumer electronics procurement, with medical and industrial applications occupying mid-tier pricing bands.
- Automotive Displays:Curved OLED instrument clusters and head-up projection systems demand wide-view-angle polarizers with cyclic olefin polymer substrates replacing conventional TAC. Procurement by Hyundai Motor and BYD technical programs in South Korea and China is fragmenting traditional supply chains.
- Consumer Electronics:Television and smartphone panel manufacturing drives volume demand for standardized polarizer specifications. South Korean and Taiwanese manufacturing clusters maintain captive supply relationships with dedicated film converters.
- Medical Devices:Diagnostic imaging and surgical display applications require extended color gamut compliance and reduced haze degradation under sterilization protocols.
- Industrial Equipment:HMI panels and process control displays prioritize durability over optical performance, accepting lower transmission ratios for extended operational lifespan.
Consumer electronics captures the largest revenue base. Automotive displays show the steepest expansion trajectory.
Technology:
Application alignment determines specification intensity, with OLED architectures demanding the most sophisticated polarizer engineering and LCD retaining volume dominance.
- OLED Technology:Emissive display architectures require circular polarizers to suppress ambient light reflection from metallic electrode layers. Foldable panel mechanical durability mandates dye-based chemistries resistant to repeated bending stress in Samsung SDI and Chinese panel maker supply chains.
- LCD Technology:Twisted nematic and in-plane switching configurations utilize linear polarizers with iodine-dye hybrid formulations for cost-optimized contrast control. Dominates television and desktop monitor production volumes.
- LED Technology:Direct-lit and edge-lit backlight systems impose transmission ratio requirements that cascade into polarizer absorption specifications.
- Projection Technology:Polarizing beam splitters and reflective polarizers serve niche cinema and large-venue display applications with specialized optical coating requirements.
LCD technology maintains volume leadership. OLED technology is gaining share fastest.
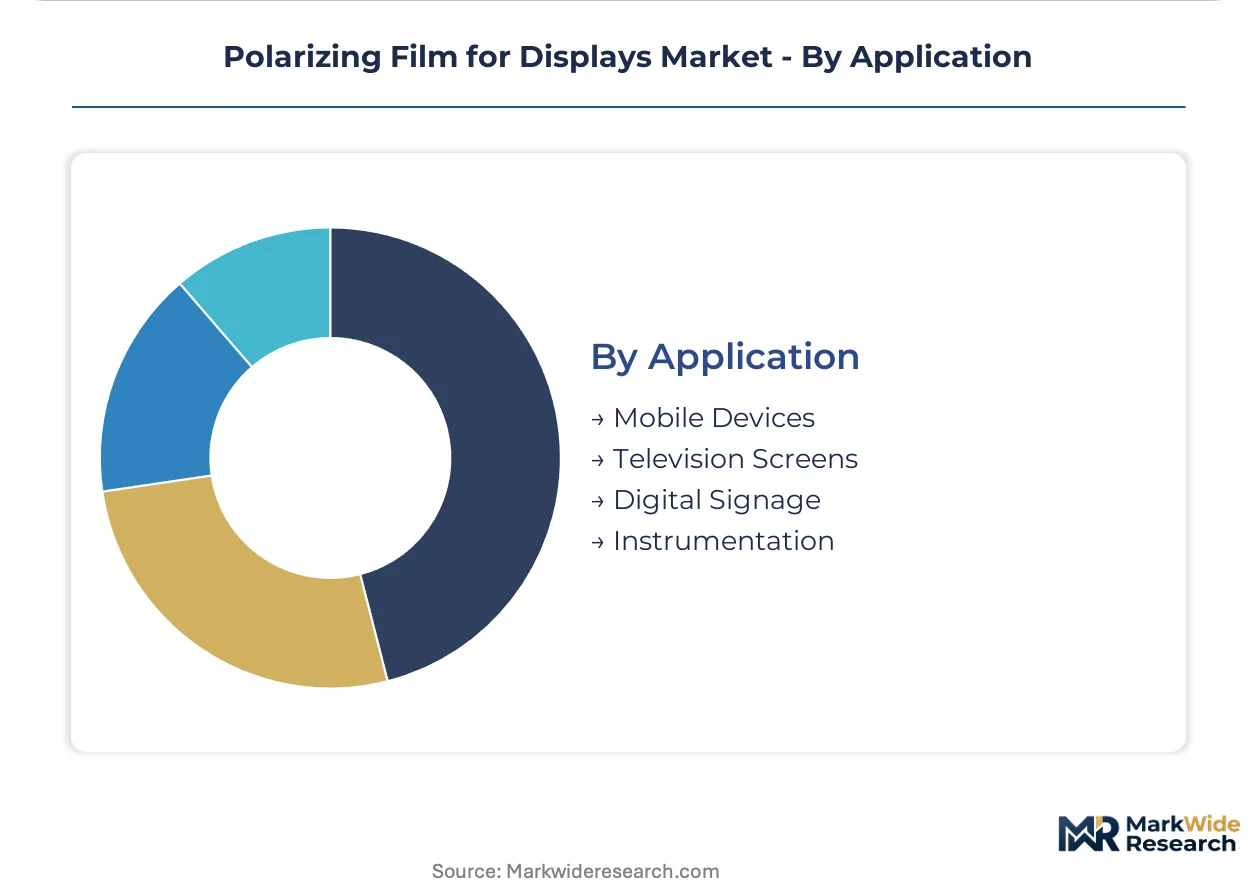
Application:
Customer type segmentation separates OEM direct procurement from tiered supply through panel integrators, with mobile devices commanding the most stringent qualification protocols.
- Mobile Devices:Smartphone and tablet panels require ultra-thin polarizer stacks with bend radius compatibility below 5mm for foldable form factors. Japanese iodine-dye hybrid technology from Nitto Denko anchors high-performance supply to Seoul-based panel makers.
- Television Screens:Large-format LCD production in Chinese and Taiwanese fabs drives linear polarizer consumption at standardized specifications with compressed margin structures.
- Digital Signage:Commercial display installations prioritize luminance retention and thermal stability for extended outdoor operation.
- Instrumentation:Medical and industrial control panels demand extended operating temperature ranges and electromagnetic interference shielding integration.
Television screens dominate unit volumes. Mobile devices lead on value per square meter.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Busan handles the majority of East Asian optical film exports, underwriting South Korea's central role in polarizer logistics. Taiwan's Kaohsiung container terminals and Japan's Yokohama port complex complete the maritime infrastructure triangle that moves specialized polymer laminates to panel fabrication sites worldwide.
China
Domestic panel fabs in Hefei and Shenzhen are scaling circular polarizer procurement for foldable OLED smartphone production. SAMR and GB standards mandate energy efficiency disclosures that cascade into transmission ratio specifications for export-bound displays. Yangtze River Delta manufacturing clusters around Suzhou and Ningbo host captive lamination operations serving BOE and TCL CSOT supply chains.
South Korea
Seoul-based display makers are qualifying water-resistant polarizer stacks for curved automotive instrument clusters under Hyundai Motor technical programs. MFDS substance restrictions on adhesive chemistries are extending supplier qualification timelines for European-bound film exports. Busan-Ulsan industrial corridors concentrate dye-based polarizer finishing capacity for Samsung Display and LG Display foldable panel lines.
Japan
Specialized polyvinyl alcohol resin production in Kanto and Kansai regions sustains input cost control for downstream film laminators. METI enforces revised JIS durability standards requiring extended thermal cycling performance for outdoor and vehicular optical films. Nagoya automotive display module assemblers now demand accelerated aging test data beyond previous television-grade benchmarks from polarizer suppliers.
Taiwan
BenQ Materials and CMMT maintain captive supply relationships with AU Optronics and Innolux panel operations in Taichung and Tainan science parks. Environmental regulators impose substance restrictions on halogenated compounds in adhesive chemistries used for European-bound film coatings. Kaohsiung port infrastructure supports just-in-time delivery schedules for high-volume LCD television polarizer consumption.
Germany
Premium electric vehicle OEMs in Stuttgart and Munich are establishing direct procurement channels with polarizer manufacturers for head-up display integration. KBA vehicle type-approval frameworks are incorporating display readability standards that extend certification cycles for cockpit panel suppliers. Bavarian automotive clusters are qualifying wide-view-angle polarizers with cyclic olefin polymer substrates for windshield-projection systems.
Polarizing Film for Displays Market Competitive Landscape
Concentration sits with Japanese chemical conglomerates controlling specialized polyvinyl alcohol resin feedstock and South Korean electronics-integrated fabricators. The vendor base separates into three strategic tiers: upstream resin specialists, integrated film laminators with captive PVA supply, and regional converters serving specific panel maker relationships. Dominant competitive moves include backward integration into polyvinyl alcohol production and geographic expansion into Indian PLI-subsidized display manufacturing zones.
Among Japanese-integrated chemical groups, Nitto Denko and Sumitomo Chemical exemplify the resin-to-film value chain archetype. South Korean electronics-affiliated suppliers Samsung SDI and LG Chem occupy positions within display-maker captive procurement networks. BenQ Materials represents the Taiwan-based regional converter model serving dedicated panel fabrication partnerships.
| Leading Market Players |
|---|
| Nitto Denko |
| Sumitomo Chemical |
| LG Chem |
| Samsung SDI |
| BenQ Materials |
| CMMT |
| SAPO |
| Dai Nippon Printing |
| Optimax |
| Others |
Pricing and Supply Chain Analysis
Ninety-day inventory cycles at Taiwanese panel fabs concentrate pricing leverage with polyvinyl alcohol resin suppliers in Japan and South Korea, compressing margin buffers for downstream film laminators serving cost-sensitive television OEMs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates automotive-grade circular polarizers with cyclic olefin polymer substrates from commodity linear variants for LCD televisions. Price differentiation hinges on certification grade for METI JIS durability standards and volume scale of panel-maker procurement. Cost compression in standard-grade linear polarizers is intensifying because Chinese domestic fabs are backward-integrating into captive lamination capacity. Automotive OEMs exhibit the least price sensitivity due to co-development programs, while digital signage integrators remain most price-sensitive.
Supply Chain Analysis
Just-in-time delivery schedules dominate downstream relationships, though strategic stockpiling of specialized PVA feedstock is emerging among South Korean film converters facing Japanese resin allocation constraints. Supply concentrates in Japan, South Korea, and Taiwan, with Kanto-region chemical conglomerates controlling upstream polyvinyl alcohol production. The chain rests on iodine and dichroic dye chemistries, triacetate cellulose protective substrates, and precision retarder films. Single-source vulnerability sits with Japanese PVA resin concentration. Distribution runs through dedicated converter relationships with Seoul-based and Taichung-based panel makers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polarizing film procurement is becoming a service-attach opportunity as automotive OEMs demand accelerated aging test data and co-development support that outpaces hardware margin expansion.
For Market Incumbents: Compound technical service capabilities around humidity-resistant dye formulation consulting to defend against emerging Chinese resin-to-film integrators. Deepen backward integration into captive polyvinyl alcohol production to secure input cost control against Japanese chemical conglomerate pricing power. For New Entrants and Emerging Players: Anchor in India's PLI-subsidized display manufacturing zones where domestic panel fabs lack established polarizer supply relationships. Target head-up display integration programs for premium electric vehicles in Stuttgart and Munich, where wide-view-angle specifications remain under-supplied. Lead with technical exchange partnerships rather than commodity volume plays. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with under-optimized optical film divisions facing strategic review pressure. Long-term viability favors suppliers with demonstrated automotive qualification timelines and captive resin access. Watch for inflection when KBA and Japan's Ministry of Land, Infrastructure, Transport and Tourism finalize display readability standards in vehicle type-approval frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PVA Resin | Secures input cost control against Japanese chemical conglomerate supply constraints. |
| Automotive Qualification Investment | Accelerates certification cycles with KBA and Japan's Ministry of Land, Infrastructure, Transport and Tourism. |
| Water-Resistant Stack Development | Replaces TAC substrates with cyclic olefin polymers for curved OLED cockpit panels. |
| India PLI Zone Establishment | Captures first-mover advantage in domestic panel fab supply relationships. |
| Dye-Based Chemistry Scale-Up | Addresses foldable panel mechanical durability requirements from Seoul-based manufacturers. |
Research Methodology
The analysis maps circular polarizer, linear polarizer, transmissive film, and reflective film sub-sectors, each validated through procurement directors at panel makers, optical film R&D leads, automotive display module engineers, and resin supply planners. Primary interviews with these stakeholders combined with secondary validation against customs trade data, SEC filings of listed chemical conglomerates, METI JIS standard documentation, and SAMR GB efficiency disclosures. Bottom-up unit economics triangulated against top-down market sizing from production capacity announcements.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, end user, technology, and application segmentation dimensions, with regional regulatory cluster as an overlay. CAGRs derived from shipment trend extrapolation adjusted for technology substitution effects. Forecast inputs included foldable OLED penetration curves and automotive display content-per-vehicle trajectories.
Material uncertainties — resin supply allocation disruptions, REACH substance restriction expansions, and automotive qualification timeline extensions — sit outside the modeled envelope. Forecasts reflect assumptions about sustained East Asian manufacturing cluster concentration and gradual dye-based chemistry substitution rates. Practitioners should keep alternative scenarios live as KBA and Japan's Ministry of Land, Infrastructure, Transport and Tourism integrate display readability standards into vehicle type-approval frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Cathode Ray Tube Display Market
Display Technologies
Europe E-Paper Display Market
Display Technologies
Electronic Display Market
Display Technologies
Next Generation 3D Display Market
Display Technologies
Low Power Display Market
Display Technologies
Dot Matrix Display Market
Display Technologies
Backlit Displays Market
Display Technologies
4K Drawing Tablet with Screen Market
Display Technologies
Flexible Display Market
Display Technologies
Seven Segment Display Market
Display Technologies
Global 5K Display Resolution Market
Display Technologies
OLED Display Market
Display Technologies
Touch Screen Film Market
Display Technologies
Electronic Paper Display (EPD) Market
Display Technologies
MEMS Microdisplay Market
Display Technologies
Global Center Stack Display Market