
 Interferometric Modulator Display Market | 2026-2036
Interferometric Modulator Display Market Size, Share, and Industry Trends Forecast 2026-2036
Interferometric Modulator Display Market Analysis
Taiwan is reconfiguring its display component supply base to accommodate next-generation reflective panel architectures. E Ink Holdings leverages decades of electrophoretic expertise to anchor its position in low-power signage segments. CLEARink Displays competes through proprietary color-capable reflective technology that extends readability into bright ambient conditions. Solomon Systech specializes in driver IC solutions that sustain interoperability across emerging interferometric architectures.
An interferometric modulator display exploits micro-electromechanical structures to manipulate light interference, producing images through selective reflection rather than emission, with power draw dropping to near-zero in static states. This architecture serves applications demanding persistent visibility without battery drain, from shelf labels to vehicle instrumentation. Wearable Displays lead current shipment volumes due to smartwatch integration, while Automotive Displays represent the fastest-expanding margin pool as HUD specifications tighten. Reflective Technology dominates technical roadmaps, though Adaptive Brightness is gaining traction in premium mobile configurations where ambient compensation matters.
The US FCC governs electromagnetic emissions from MEMS-based display controllers, while the EU RoHS directive restricts hazardous substances in micro-scale mechanical assemblies. REACH compliance in Europe further complicates material selection for cavity structures and sacrificial layers. South Korea's MFDS influences medical device display standards where interferometric panels target diagnostic readability. Stakeholders must weigh regulatory certification timelines against the pace of automotive platform design cycles.
Market Dynamics
The EU F-Gas Regulation is compressing fluorinated gas availability across display manufacturing, forcing a structural pivot toward solid-state reflective architectures that eliminate backlighting and gas-filled cavities entirely.
Growth Catalysts
- Automotive HUD specifications:Tier-1 suppliers are embedding interferometric modulators into head-up displays to meet NHTSA visibility standards while cutting thermal management overhead.
- REACH material restrictions:European cavity structure mandates are accelerating sacrificial layer innovation that favors MEMS-based reflective panels over liquid-crystal alternatives.
- East Asian cluster concentration:South Korea and Taiwan display ecosystems provide captive driver IC development, wafer-level packaging, and test infrastructure within single metropolitan radii.
Market Restraints
- Indium tin oxide volatility:Transparent electrode supply concentrates in Chinese smelting operations, exposing cost structures to export quota fluctuations.
- MEMS yield fragility:Micro-electromechanical cavity fabrication requires sub-micron sacrificial layer control that only three foundry groups currently master.
- Electrophoretic substitution:E Ink Holdings and CLEARink Displays already occupy shelf-label and e-reader segments with mature reflective alternatives.
Strategic Opportunities
- Medical device readability:South Korea's MFDS diagnostic display standards create a certification pathway for interferometric panels in portable imaging equipment.
- Smartwatch integration white space:Wearable OEMs seek always-on architectures that OLED cannot sustain without battery penalty.
- RoHS technical adaptation:European micro-scale assembly restrictions favor lead-free MEMS bonding processes that incumbent liquid-crystal lines cannot retrofit.
Industry Challenges
- MEMS process engineering scarcity:Foundry talent capable of interferometric cavity etching and release commands premium compensation in Taiwan and South Korea.
- Automotive platform synchronization:HUD design cycles span 48-60 months, misaligned with MEMS display qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Interferometric Modulator Display Market |
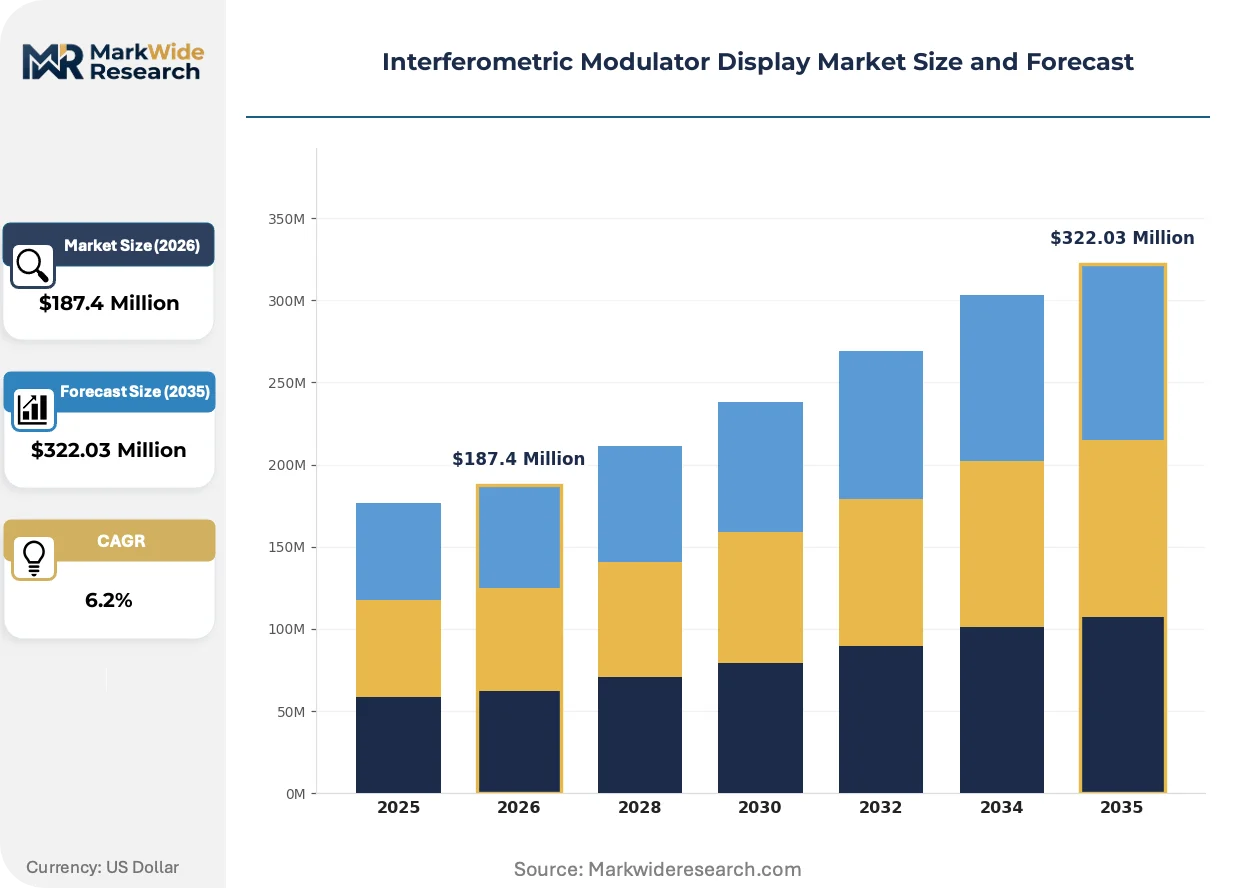
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $322.03 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Displays, Mobile Displays, TV Displays, Automotive Displays Technology: Reflective Technology, Transparent Technology, Color Filters, Adaptive Brightness End User: Consumer Electronics, Automotive OEMs, Industrial Applications, Medical Devices Application: Advertising Signage, Smart Home Devices, Head-Up Displays, Interactive Panels |
| Companies Covered | CLEARink Displays, Solomon Systech, E Ink Holdings, Pervasive Displays, LG Display, Plastic Logic, Motion Display, GDS, Visionect, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Interferometric Modulator Display Market Emerging Trajectories
Reflective display architectures are bifurcating between static low-power signage and dynamic automotive instrumentation, with technical roadmaps diverging around color fidelity versus refresh rate priorities.
Monochrome interferometric modulator stacks are collapsing power budgets for persistent visibility applications. Smartwatch OEMs are adopting these architectures for always-on watch faces that maintain readability without backlight drain. The technology is collapsing the traditional trade-off between battery life and ambient contrast that has constrained wearable display selection.
The EU F-Gas Regulation tightens fluorinated gas controls across manufacturing operations with phased reduction targets through 2030. Display panel producers face retrofit costs for etching and cleaning processes previously dependent on sulfur hexafluoride and nitrogen trifluoride. Automotive display specifications in Germany and France are accelerating qualification of solid-state reflective alternatives that bypass gas-dependent fabrication entirely.
Fleet procurement of commercial signage is consolidating around lifecycle cost metrics rather than upfront hardware expenditure. Retail and logistics operators are unbundling display hardware from content management subscriptions, favoring reflective technologies that eliminate recurring energy costs. This pattern is most visible in German grocery and Scandinavian logistics networks where sustainability reporting requirements amplify total-cost-of-ownership visibility.
Interferometric Modulator Display Market Segmentation
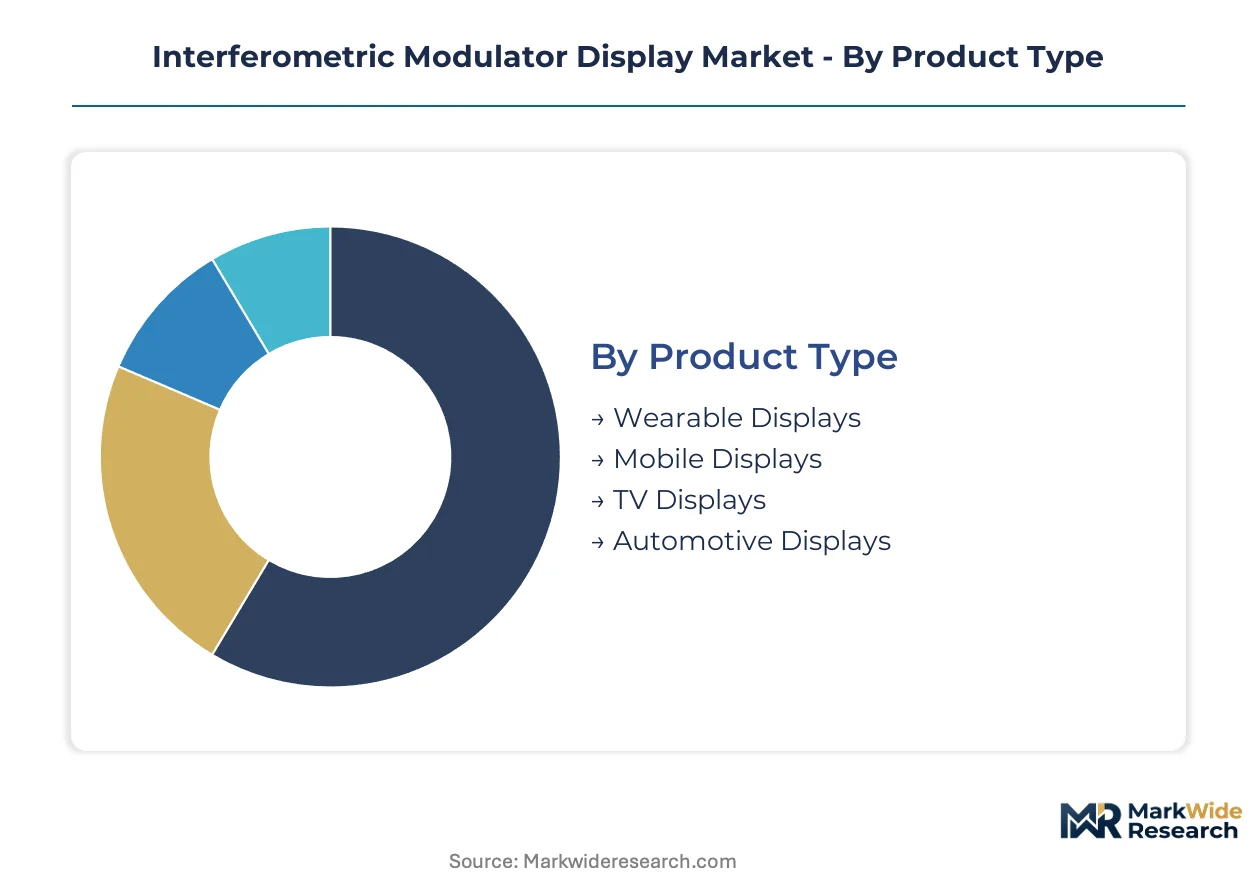
Interferometric modulator displays fragment across four distinct dimensions. Product architecture determines power budgets and form factor constraints. Technology selection governs ambient readability and color fidelity trade-offs.
Product Type:
Application volume and margin structure diverge sharply across display form factors.
- Automotive Displays:Head-up display integration exploits near-zero static power draw to meet NHTSA visibility standards without thermal management overhead. German and French OEM qualification timelines are compressing adoption windows for Tier-1 suppliers.
- Wearable Displays:Smartwatch form factors prioritize always-on readability with minimal battery penalty. South Korean and Taiwanese OEMs dominate current shipment volumes through captive driver IC ecosystems.
- Mobile Displays:Handheld devices balance reflective efficiency against touch-layer integration complexity.
- TV Displays:Large-format interferometric architectures face yield constraints from sacrificial layer uniformity requirements.
Automotive Displays holds installed capacity. Wearable Displays is rotating up the share rankings.
Technology:
Technical roadmaps bifurcate around color fidelity versus refresh rate optimization.
- Reflective Technology:Micro-electromechanical cavity structures manipulate light interference through selective reflection. Persistent visibility applications in retail signage and vehicle instrumentation drive demand concentration.
- Adaptive Brightness:Ambient compensation circuits extend readability into direct sunlight conditions. Premium mobile configurations in South Korea and Taiwan adopt these stacks for outdoor usability.
- Transparent Technology:See-through architectures target augmented reality overlays and smart glass integration.
- Color Filters:Subtractive color layering expands gamut at the cost of reflectivity efficiency.
Reflective Technology anchors current production. Adaptive Brightness is climbing the fastest.
End User:
Customer procurement patterns separate volume buyers from specification-driven adopters.
- Automotive OEMs:Platform design cycles spanning 48-60 months demand qualification stability that only three MEMS foundry groups currently guarantee. HUD specifications in Germany and France are tightening visibility requirements.
- Consumer Electronics:Wearable and mobile OEMs prioritize battery life metrics in competitive positioning. Smartwatch integration white space is attracting reflective architecture pilots from South Korean manufacturers.
- Industrial Applications:Fleet signage procurement in German grocery and Scandinavian logistics networks emphasizes lifecycle cost over upfront hardware expenditure.
- Medical Devices:South Korea's MFDS diagnostic display standards create certification pathways for portable imaging equipment readability.
Consumer Electronics holds installed capacity. Automotive OEMs is gaining share fastest.
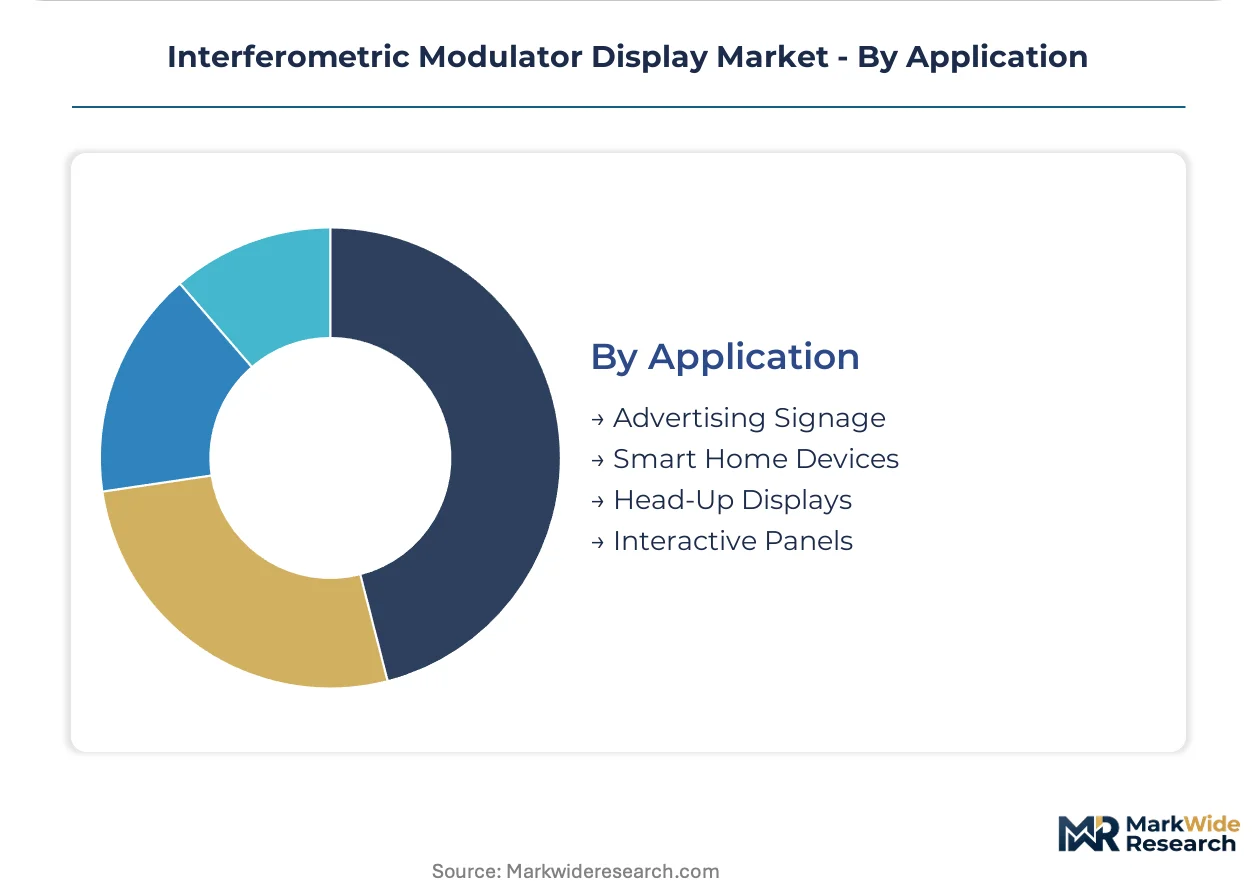
Application:
Use case requirements determine the trade-off between static power minimization and dynamic refresh capability.
- Head-Up Displays:Vehicle instrumentation demands persistent visibility without backlight drain or thermal loading. NHTSA standards and EU F-Gas Regulation compliance are accelerating solid-state reflective qualification.
- Advertising Signage:Retail and logistics operators unbundle hardware from content subscriptions, favoring zero-energy persistent displays. German sustainability reporting requirements amplify total-cost-of-ownership visibility.
- Smart Home Devices:Ambient information panels balance aesthetic integration with intermittent update requirements.
- Interactive Panels:Touch-responsive interferometric layers sacrifice reflectivity for capacitive sensing integration.
Advertising Signage holds installed capacity. Head-Up Displays is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU F-Gas Regulation anchors European demand compression, while East Asian manufacturing clusters supply the technical infrastructure for interferometric modulator production. National regulatory frameworks and industrial concentration patterns shape adoption trajectories across major economies.
United States
Automotive HUD procurement from German and French OEMs drives specification alignment for Tier-1 suppliers operating US design centers. The FCC governs electromagnetic emissions from MEMS-based display controllers, creating certification requirements for vehicle integration. Detroit-area engineering teams coordinate with South Korean wafer foundries to synchronize automotive platform timelines.
Germany
NHTSA visibility standard equivalency and domestic OEM qualification timelines compress adoption windows for reflective display architectures. The KBA enforces type-approval protocols for head-up display systems in passenger vehicles. Stuttgart and Munich engineering clusters host Tier-1 supplier development centers targeting 48-60 month automotive design cycles.
South Korea
Smartwatch OEMs and captive driver IC ecosystems concentrate demand for wearable display volumes. The MFDS influences medical device display standards where interferometric panels target diagnostic readability. Seoul Capital Area foundry groups command premium compensation for MEMS cavity etching and release process engineering.
Taiwan
Display component supply base reconfiguration accommodates next-generation reflective panel architectures. REACH-compliant material selection for cavity structures accelerates sacrificial layer innovation favoring MEMS-based panels. Hsinchu and Tainan metropolitan radii provide captive wafer-level packaging and test infrastructure.
France
Automotive HUD specifications tighten visibility requirements alongside German OEM coordination. ANSM and CNIL frameworks intersect with medical device display certification where reflective architectures target portable imaging. Paris-Saclay research clusters interface with German automotive engineering networks on solid-state reflective qualification.
Interferometric Modulator Display Market Vendor Landscape
Electrophoretic specialists and MEMS component suppliers split the market between mature reflective alternatives and emerging interferometric architectures. The vendor base concentrates around display technology incumbents with captive driver IC capabilities and foundry relationships. Two strategic archetypes dominate: low-power signage incumbents with decades of reflective expertise, and MEMS-focused component suppliers enabling next-generation cavity structures. Competitive moves center on automotive qualification partnerships and sacrificial layer process licensing.
Within the electrophoretic incumbent tier, E Ink Holdings anchors low-power signage segments through decades of specialized expertise. CLEARink Displays occupies a position exemplifying proprietary color-capable reflective technology extending readability into bright ambient conditions. Solomon Systech represents the MEMS component supplier archetype, specializing in driver IC solutions that sustain interoperability across emerging interferometric architectures. These three entities collectively illustrate the competitive tension between mature reflective platforms and next-generation MEMS-based alternatives.
| Leading Market Players |
|---|
| CLEARink Displays |
| Solomon Systech |
| E Ink Holdings |
| Pervasive Displays |
| LG Display |
| Plastic Logic |
| Motion Display |
| GDS |
| Visionect |
| Others |
Supply Flow & Price Mechanics
Kaohsiung-to-Long Beach container rates govern landed cost differentials between Taiwanese MEMS foundries and North American automotive Tier 1s, compressing margin pools for non-integrated suppliers while amplifying price premiums for REACH-compliant cavity structures. This corridor's volatility feeds directly into procurement negotiations, with buyers facing stark choice architecture between captive East Asian supply and European qualification premiums.
Pricing Analysis
Price spreads between automotive-grade and consumer-grade interferometric modulators diverge by certification tier, with MFDS-compliant medical display stacks commanding substantial premiums over standard wearable configurations. Three-tier pricing structure across premium, standard, and economy levels tracks sacrificial layer yield rates and foundry process maturity. Pricing pressure stems from electrophoretic substitution in retail signage, where E Ink Holdings and CLEARink Displays have established reference pricing. Automotive OEMs exhibit lowest price sensitivity due to 48-60 month platform lock-in, while fleet signage operators prioritize lifecycle cost minimization.
Supply Chain Analysis
Tariff exposure between the United States and China concentrates risk in indium tin oxide supply, where Chinese smelting operations control transparent electrode feedstock. Manufacturing gravity centers on Taiwan, South Korea, and Japan, with Hsinchu and Seoul Capital Area metropolitan radii providing captive wafer-level packaging and driver IC test infrastructure. Raw material dependencies span indium compounds, silicon-on-insulator wafers, and fluorine-free etchant chemistries. Distribution runs through display panel ecosystem integrators who bundle interferometric layers with touch sensors and cover glass.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation is accelerating as automotive HUD specifications diverge from wearable power budgets, creating distinct competitive arenas with divergent technical roadmaps and procurement patterns.
For Market Incumbents: Insulate automotive qualification pipelines from MEMS yield fragility by securing secondary foundry relationships in Taiwan beyond the three dominant cavity-etching groups. Deepen backward integration into driver IC design to defend against Solomon Systech's interoperability licensing position, while accelerating REACH-compliant sacrificial layer R&D to preempt European regulatory compression.
For New Entrants and Emerging Players: Establish a beachhead in medical device display segments where South Korea's MFDS certification creates barrier-protected demand pools with limited incumbent presence. Target portable imaging equipment OEMs seeking diagnostic readability without OLED thermal constraints, leveraging the certification pathway gap between electrophoretic alternatives and emerging interferometric architectures.
For Investors and Strategic Acquirers: MEMS process engineering boutiques with captive automotive relationships represent the highest-conviction acquisition archetype for portfolio exposure to HUD platform cycles. Long-term viability hinges on qualification timeline synchronization with 48-60 month automotive design windows. Watch for Tier 1 supplier consolidation announcements as the inflection signal for foundry capacity scarcity premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Automotive Qualification Partnership | Secures NHTSA-compliant HUD supply position with German OEM platform teams. |
| Sacrificial Layer Process Licensing | Monetizes sub-micron cavity etching IP across Taiwan and South Korea foundries. |
| MFDS Certification Pathway Investment | Unlocks portable imaging equipment procurement governed by South Korean diagnostic standards. |
| REACH-Compliant Material Transition | Eliminates fluorinated gas dependencies ahead of EU F-Gas Regulation phase-down targets. |
| Driver IC Ecosystem Integration | Captures interoperability rents across emerging interferometric architectures via Solomon Systech-type positioning. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, EU F-Gas Regulation implementation documents, and automotive platform engineering disclosures, with inputs drawn from MEMS foundry operations heads, Tier 1 supplier procurement directors, and display panel ecosystem integrators. Bottom-up shipment estimates triangulate against top-down value projections derived from foundry capacity announcements and automotive HUD content-per-vehicle assumptions.
Forecast inputs span product architecture splits across automotive, wearable, mobile, and TV form factors; technology roadmaps bifurcating between reflective and adaptive brightness stacks; and end-user procurement patterns separating automotive OEMs from consumer electronics and industrial fleet operators. CAGRs derive from segment-level volume trajectories indexed to qualification timeline visibility and regulatory compliance cost curves, with specific weighting applied to EU F-Gas Regulation retrofit schedules and MFDS medical device certification pipelines.
Sensitivities concentrate around MEMS yield recovery rates, indium export quota volatility, and automotive platform delay cascades. Forecasts embed assumptions regarding foundry capacity expansion timing and electrophoretic substitution elasticity in retail signage. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Global Display Controllers Market
Display Technologies
Mono LCD Displays Market
Display Technologies
Video Wall Display Market
Display Technologies
Paper-Thin Display Market
Display Technologies
Vietnam Digital Signage Market
Display Technologies
Laptop Panels Market
Display Technologies
Digital Kiosk Display Market
Display Technologies
Portable Projector Market
Display Technologies
Screenless Display Market
Display Technologies
Multi-Touch Screen Market
Display Technologies
Global LED Digital Signage Market
Display Technologies
Holographic Display Market
Display Technologies
OLED Display Market
Display Technologies
Tablets and Notebook Display Market
Display Technologies
United States Microdisplay Market
Display Technologies
Portable Video Wall Market