
 Paraneoplastic Syndromes Market | 2026-2036
Paraneoplastic Syndromes Market Size, Share, and Industry Trends Forecast 2026-2036
Paraneoplastic Syndromes Market Analytics
Maintenance contracts for immunomonitoring platforms is pivoting how pharmaceutical firms monetize paraneoplastic care. F. Hoffmann-La Roche Ltd. leverages its diagnostic-installed base to sustain recurring revenue streams across European oncology networks. Grifols S.A. anchors its position through specialized immunoglobulin manufacturing scale. Pfizer Inc. competes by extending its rare disease portfolio into autoimmune-mediated oncology complications.
Paraneoplastic syndromes constitute remote effects of malignancy wherein tumor-derived antigens trigger pathological immune responses against normal tissues, with neurological variants involving anti-Hu, anti-Yo, or anti-Ri antibody targeting of neuronal proteins. Their primary clinical purpose lies in early cancer detection, as syndrome presentation frequently precedes tumor diagnosis by months. Neurological manifestations command the deepest therapeutic investment due to irreversible neuronal damage risk, while immunotherapy approaches attract the fastest development velocity amid checkpoint inhibitor expansion. Tumor-type segmentation reveals lung cancer associations dominating antibody-positive cases, though breast cancer-linked presentations sustain significant clinical trial activity.
The FDA's orphan drug designation framework and the EMA's PRIME scheme for rare disease therapies are accelerating paraneoplastic treatment development timelines by reducing regulatory burden. ISO 13485 quality standards and the EU MDR reshape diagnostic device market access requirements for antibody detection kits. Stakeholders must monitor evolving payer evidence thresholds for combination immunotherapy regimens in antibody-negative syndromes.
Market Dynamics
Checkpoint inhibitor expansion is redefining therapeutic development velocity, compressing timelines between biomarker discovery and clinical application while elevating immunomonitoring from ancillary service to core revenue pillar.
Growth Catalysts
- FDA Accelerated Approval:The FDA's orphan drug designation framework reduces regulatory burden for rare disease therapeutics, shortening development cycles for antibody-targeted interventions.
- Immunoglobulin Manufacturing Scale:Specialized plasma fractionation infrastructure in European university hospitals enables rapid therapeutic antibody production for acute neurological presentations.
- Oncology Network Expansion:Dedicated paraneoplastic neurology units in German academic medical centers concentrate diagnostic expertise and patient volume.
Market Restraints
- Diagnostic Kit Fragmentation:EU MDR compliance costs and ISO 13485 certification timelines delay antibody detection platform commercialization.
- Plasma Supply Concentration:Immunoglobulin raw material dependence on US and European donor pools creates input vulnerability.
- Antibody-Negative Diagnostic Gap:Seronegative syndrome identification lacks standardized biomarkers, limiting addressable patient populations.
Strategic Opportunities
- EMA PRIME Scheme Access:Priority medicines designation offers enhanced regulatory support for novel immunotherapy combinations in antibody-negative presentations.
- Maintenance Contract Models:Recurring revenue from immunomonitoring platform servicing displaces transactional diagnostic sales in European oncology networks.
- Lung Cancer Screening Integration:Syndromic presentation preceding tumor diagnosis creates early detection partnerships with thoracic surgery programs.
Industry Challenges
- Neuronal Damage Irreversibility:Therapeutic windows close before treatment initiation, demanding compressed diagnostic workflows.
- Payer Evidence Thresholds:Combination immunotherapy regimens face reimbursement scrutiny without randomized controlled trial data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paraneoplastic Syndromes Market |
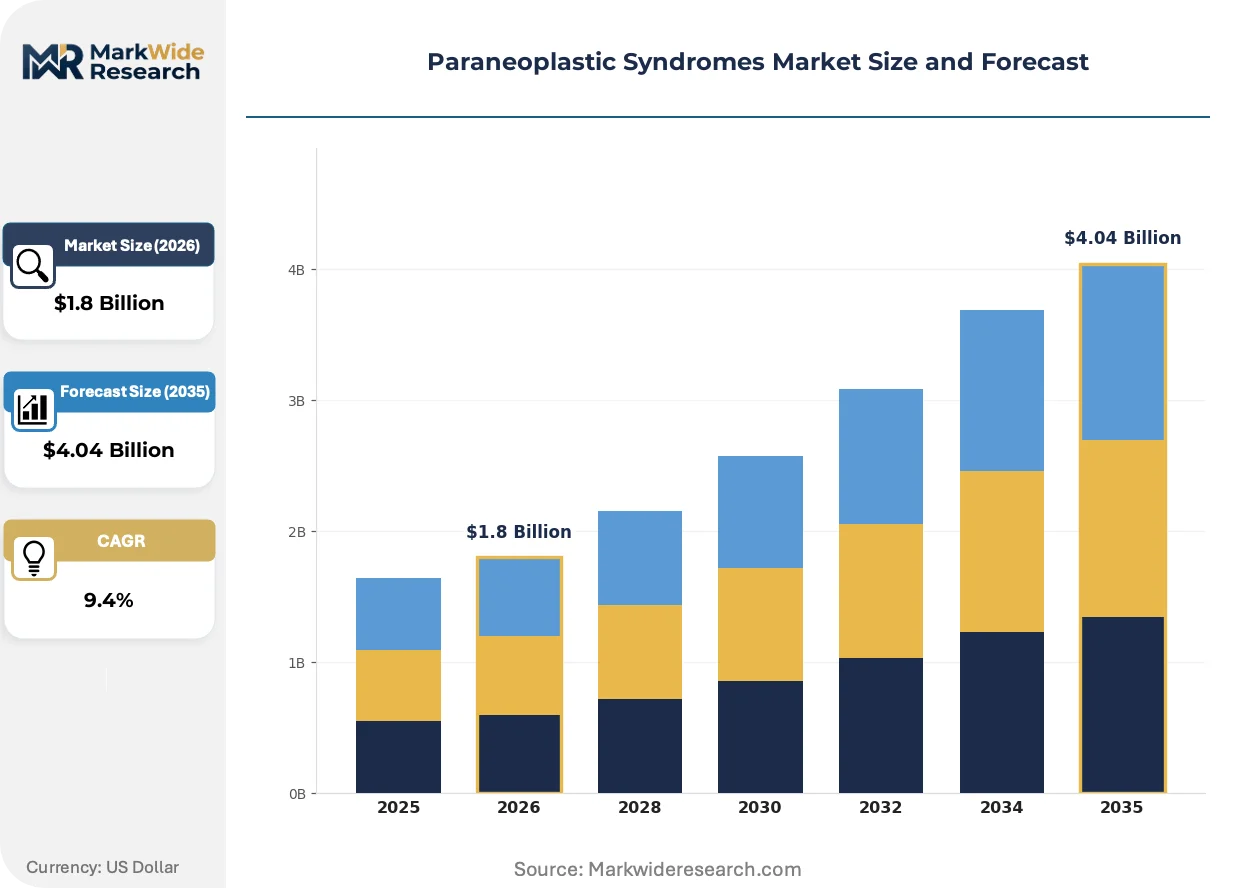
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Neurological, Endocrine, Dermatological, Hematological Onset: Rapid, Insidious, Chronic, Acute Tumor Type: Lung Cancer, Breast Cancer, Lymphoma, Gastrointestinal Cancer Treatment Approach: Immunotherapy, Chemotherapy, Radiation Therapy, Surgery |
| Companies Covered | F. Hoffmann-La Roche Ltd., Grifols S.A., Merck & Co. Inc., Johnson & Johnson, Novartis AG, Pfizer Inc., GlaxoSmithKline plc, AbbVie Inc., Amgen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paraneoplastic Syndromes Market Evolving Landscape
Next-generation sequencing is collapsing the latency between symptom presentation and antibody identification, while regulatory pathways adapt to accommodate ultra-rare disease modalities.
Cell-based immunofluorescence assays are decentralizing diagnostic authority from centralized reference laboratories to regional oncology centers. Community hospital pathology departments in the United States are adopting automated slide scanners with cloud-based specialist interpretation. This technology is decentralizing patient access timelines from weeks to days.
REACH substance restrictions and RoHS compliance mandates are reshaping reagent chemistry formulations for antibody detection kits. European manufacturers are reformulating fluorescent conjugates to eliminate restricted substances. Diagnostic device producers are responding by dual-registering US and EU product variants to maintain market access.
Hospital procurement committees are unbundling diagnostic service contracts from therapeutic purchasing agreements. Oncology centers now negotiate immunomonitoring platforms separately from immunoglobulin supply contracts. This pattern is most pronounced in German university hospital networks seeking operational flexibility.
Paraneoplastic Syndromes Market Segmentation
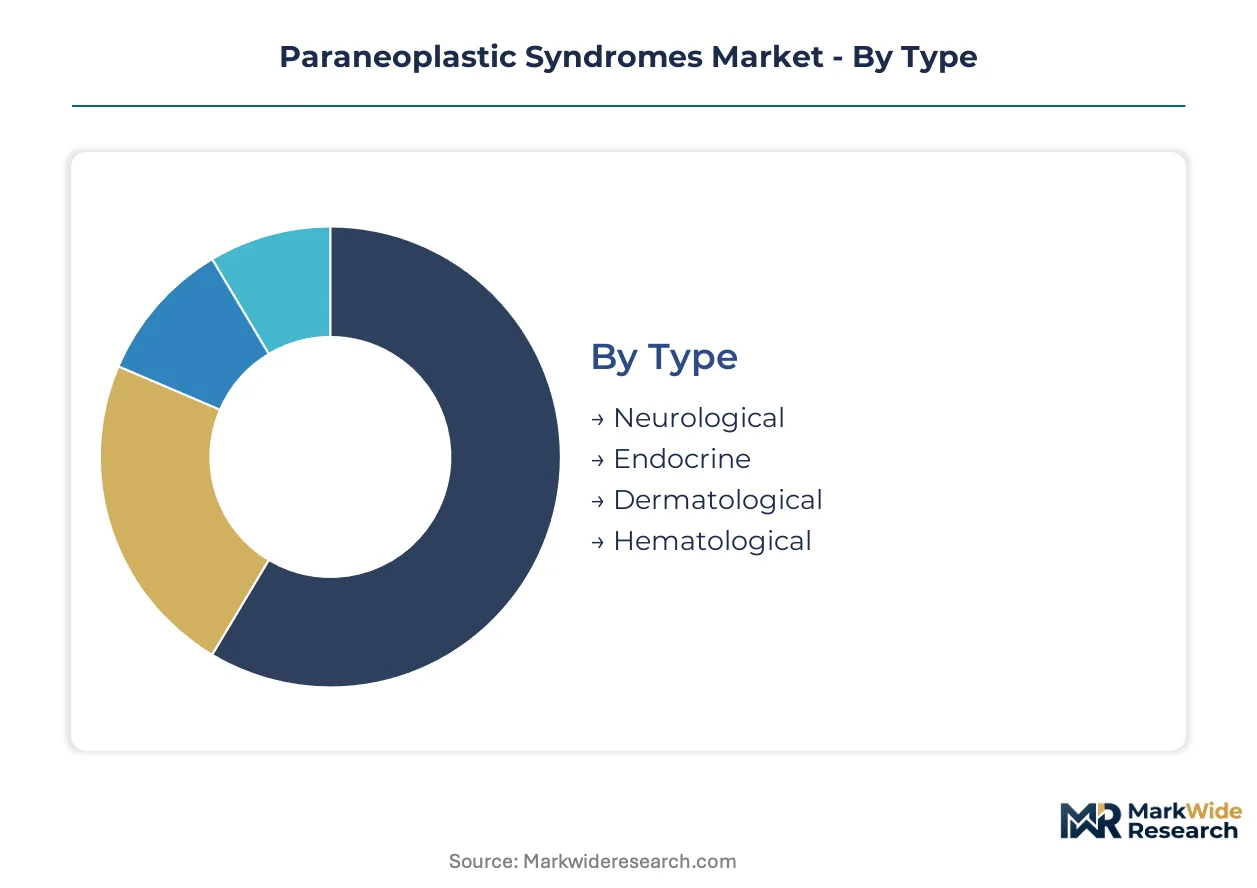
Paraneoplastic syndromes demand precise clinical stratification because treatment windows close before tumor identification in many neurological presentations. Diagnostic and therapeutic investment flows toward antibody-positive subtypes where immunomodulation offers measurable outcomes.
Type:
Treatment complexity and reversibility potential determine how hospital procurement committees allocate diagnostic platform budgets across syndrome categories.
- Neurological:Anti-Hu, anti-Yo, and anti-Ri antibodies target intracellular neuronal proteins, causing limbic encephalitis, cerebellar degeneration, and opsoclonus-myoclonus. German university hospitals concentrate dedicated paraneoplastic neurology units here due to irreversible neuronal damage risk and compressed therapeutic windows.
- Endocrine:Ectopic hormone production—ACTH, PTHrP, or vasopressin—creates metabolic emergencies that resolve with tumor resection. Demand clusters in US oncology centers where endocrinologists coordinate with thoracic surgery for small cell lung cancer detection.
- Dermatological:Dermatomyositis and acanthosis nigricans serve as visible cutaneous markers of underlying malignancy. Diagnostic confirmation relies on dermatopathology expertise in academic medical centers.
- Hematological:Erythrocytosis, thrombocytosis, and hypercoagulability complicate cancer staging and perioperative management. Treatment focuses on underlying tumor control rather than syndrome-specific intervention.
Volume sits with Neurological presentations; growth tilts toward Endocrine as lung cancer screening programs expand detection of ectopic ACTH syndromes.
Onset:
Symptom progression velocity dictates whether patients enter emergency departments or outpatient neurology referral pathways.
- Rapid:Days-to-weeks symptom escalation triggers emergency MRI and lumbar puncture protocols. US emergency departments activate paraneoplastic antibody panels for subacute encephalopathy presentations.
- Insidious:Months-long subtle decline permits outpatient antibody testing but risks missed diagnosis until tumor advances. European oncology networks favor this category for maintenance contract immunomonitoring models.
- Chronic:Persistent low-grade symptoms without acute decompensation challenge diagnostic prioritization. Patients cycle through multiple specialties before paraneoplastic evaluation.
- Acute:Hours-to-days catastrophic presentation demands immediate plasma exchange or IVIG administration. Specialized immunoglobulin manufacturing scale in Spanish and German facilities supports this segment.
Acute presentations command premium pricing; Insidious onset cases expand addressable volume through screening integration.
Tumor Type:
Antibody specificity and epidemiological prevalence shape pharmaceutical development priorities and diagnostic kit commercialization strategies.
- Lung Cancer:Small cell and non-small cell carcinomas generate the highest antibody-positive syndrome burden, with Lambert-Eaton myasthenic syndrome and limbic encephalitis dominating. US thoracic surgery programs integrate syndromic screening into nodule evaluation protocols.
- Breast Cancer:Anti-Yo antibody-associated cerebellar degeneration and dermatomyositis sustain significant clinical trial activity. Academic medical centers in Germany maintain longitudinal outcome registries for these presentations.
- Lymphoma:Hodgkin and non-Hodgkin subtypes produce neurologic paraneoplasia through cytokine dysregulation and direct immune cross-reactivity. Diagnostic complexity elevates referral concentration to hematology-oncology centers.
- Gastrointestinal Cancer:Pancreatic and gastric malignancies generate less frequent but severe neurological syndromes. Delayed tumor detection compresses therapeutic opportunity.
Lung Cancer associations dominate current antibody detection kit demand; Breast Cancer-linked presentations show steepest expansion trajectory in immunotherapy combination trials.
Treatment Approach:
Reimbursement pathways and evidence requirements determine how hospital pharmacy committees sequence therapeutic interventions.
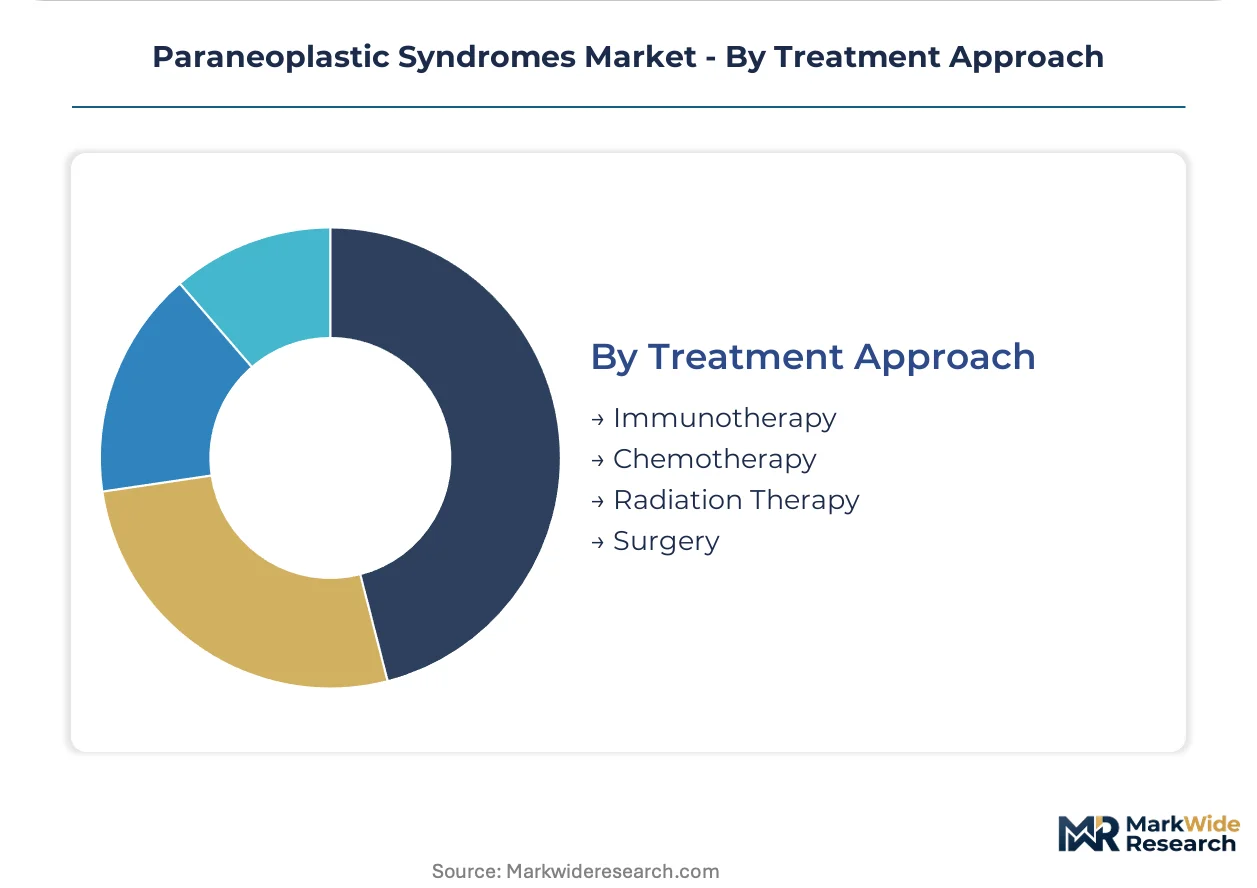
- Immunotherapy:Corticosteroids, IVIG, plasma exchange, and emerging checkpoint inhibitors target pathological immune response. EMA PRIME scheme access accelerates novel combination development for antibody-negative cases.
- Chemotherapy:Tumor-directed cytotoxic therapy remains foundational, with syndrome resolution correlating to oncologic response. Payer evidence thresholds demand randomized data for combination regimens.
- Radiation Therapy:Localized control of radiosensitive tumors—particularly small cell lung cancer—can produce rapid antibody titer decline. Treatment planning integrates with neurology monitoring.
- Surgery:Resection of localized malignancy offers definitive syndrome resolution when tumor is resectable. Preoperative paraneoplastic evaluation influences surgical urgency determinations.
Immunotherapy captures development investment; Surgery delivers clearest outcomes where tumor localization permits complete resection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic platform manufacturing clusters in Germany and the United States supply antibody detection systems to oncology centers worldwide, while patient volume concentrates in university hospital networks across Western Europe and North America.
United States
Oncology centers in Massachusetts and California are expanding dedicated paraneoplastic neurology protocols to capture patients presenting with subacute limbic encephalitis. The FDA's orphan drug designation framework accelerates development timelines for rare disease therapeutics targeting antibody-mediated presentations. Academic medical centers in Boston maintain longitudinal outcome registries for anti-Hu and anti-Yo antibody syndromes.
Germany
University hospitals in Munich and Heidelberg operate dedicated paraneoplastic neurology units that concentrate diagnostic expertise and immunoglobulin therapeutic administration. The EU MDR and ISO 13485 quality standards reshape market access requirements for antibody detection kits manufactured in Baden-Württemberg. The EMA's PRIME scheme for priority medicines offers enhanced regulatory support for novel immunotherapy combinations developed in Frankfurt-based research clusters.
Spain
Specialized immunoglobulin manufacturing facilities in Barcelona and Madrid support acute neurological presentations requiring rapid plasma exchange or IVIG administration. REACH substance restrictions and RoHS compliance mandates are driving reformulation of fluorescent conjugates in diagnostic reagent production. Hospital procurement committees in Catalonia are unbundling diagnostic service contracts from therapeutic purchasing agreements to secure operational flexibility.
Switzerland
Swissmedic regulatory pathways accommodate ultra-rare disease modalities through accelerated assessment procedures for paraneoplastic syndrome therapeutics. Diagnostic device producers in Basel are dual-registering US and EU product variants to maintain market access across divergent quality standards. The country's pharmaceutical research clusters coordinate with university hospitals in Zurich for biomarker discovery in antibody-negative presentations.
Japan
PMDA consultation frameworks support clinical trial design for checkpoint inhibitor combinations in paraneoplastic neurological syndromes. Oncology networks in Tokyo and Osaka are integrating cell-based immunofluorescence assays into community hospital pathology departments. METI funding programs accelerate adoption of automated slide scanners with cloud-based specialist interpretation to compress diagnostic timelines from weeks to days.
Paraneoplastic Syndromes Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the paraneoplastic syndrome therapeutic landscape, with plasma fractionation infrastructure owners facing off against specialized diagnostic platform developers. The market structure tilts toward consolidated immunoglobulin supply chains alongside fragmented antibody detection kit commercialization. Three archetypes dominate: integrated diagnostic-therapeutic conglomerates, specialized plasma protein manufacturers, and rare disease portfolio extenders. Competitive moves center on maintenance contract monetization of immunomonitoring platforms and strategic partnerships with thoracic surgery programs for early cancer detection.
Within the integrated diagnostic-therapeutic tier, F. Hoffmann-La Roche Ltd. and Grifols S.A. exemplify divergent strategic positions. The Basel-based pharmaceutical conglomerate leverages its diagnostic-installed base to sustain recurring revenue streams across European oncology networks through platform servicing agreements. The Spanish plasma fractionation specialist anchors market position through captive immunoglobulin manufacturing scale serving acute neurological presentations. Pfizer Inc. occupies a position among rare disease portfolio extenders, extending therapeutic development into autoimmune-mediated oncology complications.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd. |
| Grifols S.A. |
| Merck & Co. Inc. |
| Johnson & Johnson |
| Novartis AG |
| Pfizer Inc. |
| GlaxoSmithKline plc |
| AbbVie Inc. |
| Amgen Inc. |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between ISO 13485-compliant antibody detection kits and uncertified laboratory-developed tests manifests in both procurement premiums and manufacturing location choices, with EU MDR compliance costs pushing production toward established regulatory hubs while pricing stratifies across premium, standard, and economy tiers based on automation level and after-sales service bundling.
Pricing Analysis
Margin tightening in automated immunomonitoring platforms reflects concentrated manufacturing scale among plasma fractionation specialists in Spain and Germany. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and service contract duration. Pricing pressure stems from hospital procurement committees unbundling diagnostic service contracts from therapeutic purchasing agreements. Academic medical centers show lowest price sensitivity; community hospitals in the United States demonstrate highest.
Supply Chain Analysis
Regional distribution centers in Barcelona, Frankfurt, and Basel coordinate hub-and-spoke patterns for antibody detection reagents across European oncology networks. Geographic supply concentration centers on Spain, Germany, and Switzerland for diagnostic platforms and immunoglobulin therapeutics. Raw material dependencies include US and European donor plasma pools, fluorescent conjugates, and specialized assay substrates. Single-source vulnerability in plasma supply creates structural risk. Distribution runs through university hospital procurement consortia and specialized oncology distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plasma fractionation capacity constraints prop pricing power for incumbent immunoglobulin manufacturers, with donor pool expansion lagging therapeutic demand growth across acute neurological presentations.
For Market Incumbents: Lock in exclusive maintenance contracts for immunomonitoring platforms across German university hospital networks before competitors establish servicing footholds. Secure backward integration into donor plasma collection networks to reduce raw material vulnerability. Invest in automated slide scanner deployment to capture cloud-based interpretation revenue streams. For New Entrants and Emerging Players: FDA accelerated approval pathways in the United States open a window for novel checkpoint inhibitor combinations in antibody-negative paraneoplastic syndromes. Target seronegative diagnostic gaps through next-generation sequencing approaches. Pursue strategic partnerships with thoracic surgery programs for lung cancer screening integration. For Investors and Strategic Acquirers: Re-rating potential sits with specialized immunoglobulin manufacturers given EMA PRIME scheme access accelerating novel therapeutic development. Long-term viability favors plasma fractionation infrastructure owners with captive donor relationships. Watch immunomonitoring platform adoption rates in community hospital settings as inflection indicator for recurring revenue scalability.| Strategic Initiative | Industry Significance |
|---|---|
| EMA PRIME Scheme Access | Priority medicines designation accelerates novel immunotherapy combinations for antibody-negative presentations. |
| Plasma Supply Integration | Captive donor pool access reduces raw material vulnerability for immunoglobulin manufacturers in Spain and Germany. |
| Diagnostic Platform Servicing | Recurring revenue from immunomonitoring maintenance contracts displaces transactional sales in European oncology networks. |
| Lung Cancer Screening Partnership | Thoracic surgery program alliances enable early syndrome detection before tumor identification. |
| Automated Slide Scanner Deployment | Cloud-based specialist interpretation compresses diagnostic timelines from weeks to days in US community hospitals. |
Research Methodology
FDA orphan drug designations, EMA PRIME scheme submissions, and ClinicalTrials.gov records formed the secondary backbone for therapeutic development tracking. Primary interviews with plasma fractionation executives, diagnostic platform R&D directors, hospital procurement managers, and neurology department heads validated antibody detection demand patterns. Bottom-up patient volume estimates and top-down pharmaceutical revenue triangulation anchored market sizing across syndrome subtypes.
Historical trendline analysis of immunoglobulin pricing and diagnostic kit shipment volumes informed projection parameters. Segmentation modeling incorporated syndrome type, onset velocity, tumor association, and treatment approach across the analysis window. CAGR derivation weighted regulatory approval timelines, payer reimbursement thresholds, and manufacturing capacity expansion plans. Forecast inputs included plasma donor pool growth rates and cell-based assay adoption curves.
The model assumes a particular technology adoption path; alternative pathways for next-generation sequencing-based antibody identification would alter the outlook. Forecasts reflect documented assumptions regarding regulatory pathway efficiency and payer evidence requirements. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Vulvar Cancer Market
Oncology
Europe Tumor Ablation Market
Oncology
Non-Small Cell Lung Carcinoma (NSCLC) Market
Oncology
Metastatic Breast Cancer Market
Oncology
Global Neuroendocrine Tumor Treatment Market
Oncology
Ustekinumab Market
Oncology
Peritoneal Cancer Treatment Market
Oncology
Gallbladder Cancer Treatment Market
Oncology
Cancer API Market
Oncology
Asia-Pacific Radiation Oncology Market
Oncology
Thymus Cancer Market
Oncology
Pituitary Cancer Market
Oncology
Cancer/Tumor Profiling Market
Oncology
Ewing Sarcoma Treatment Market
Oncology
Europe Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Immuno-Oncology Clinical Trials Market