
 Ewing Sarcoma Treatment Market | 2026-2036
Ewing Sarcoma Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Ewing Sarcoma Treatment Market Analysis
Combination protocol bundling is broadening buyer choice in Ewing sarcoma care, as clinics seek integrated chemotherapy-radiation-immunotherapy packages rather than discrete service lines. Pfizer Inc. leverages its oncology manufacturing scale to supply vincristine-doxorubicin backbone regimens across North American hospital networks. Bristol-Myers Squibb Company anchors its position through sustained investment in checkpoint inhibitor research for pediatric sarcoma applications. Novartis AG differentiates via targeted therapy development aligned with EWSR1-FLI1 fusion biology.
Ewing sarcoma treatment encompasses multimodal therapeutic intervention against a rare malignant bone and soft tissue tumor characterized by EWSR1-ETS gene fusions, primarily affecting children and adolescents. Standard protocols integrate cytotoxic agents, localized radiation, and surgical resection to address micrometastatic disease inherent to this cancer's aggressive biology. Chemotherapy retains the largest patient volume footprint as first-line induction and consolidation backbone, while immunotherapy represents the fastest-expanding segment driven by checkpoint and adoptive cell therapy trials. Radiation therapy occupies a mature margin position where precision delivery technologies are reshaping reimbursement dynamics.
FDA orphan drug incentives and EMA pediatric investigation plans shape clinical development economics, compressing trial recruitment timelines and extending market exclusivity windows for sponsors. The EU's F-Gas Regulation and REACH frameworks constrain radiopharmaceutical manufacturing inputs, redirecting supply chain investment toward compliant production infrastructure. Stakeholders must monitor how FDA's Project Orbis parallel review with Health Canada and TGA reshapes regulatory submission strategies for novel Ewing sarcoma agents.
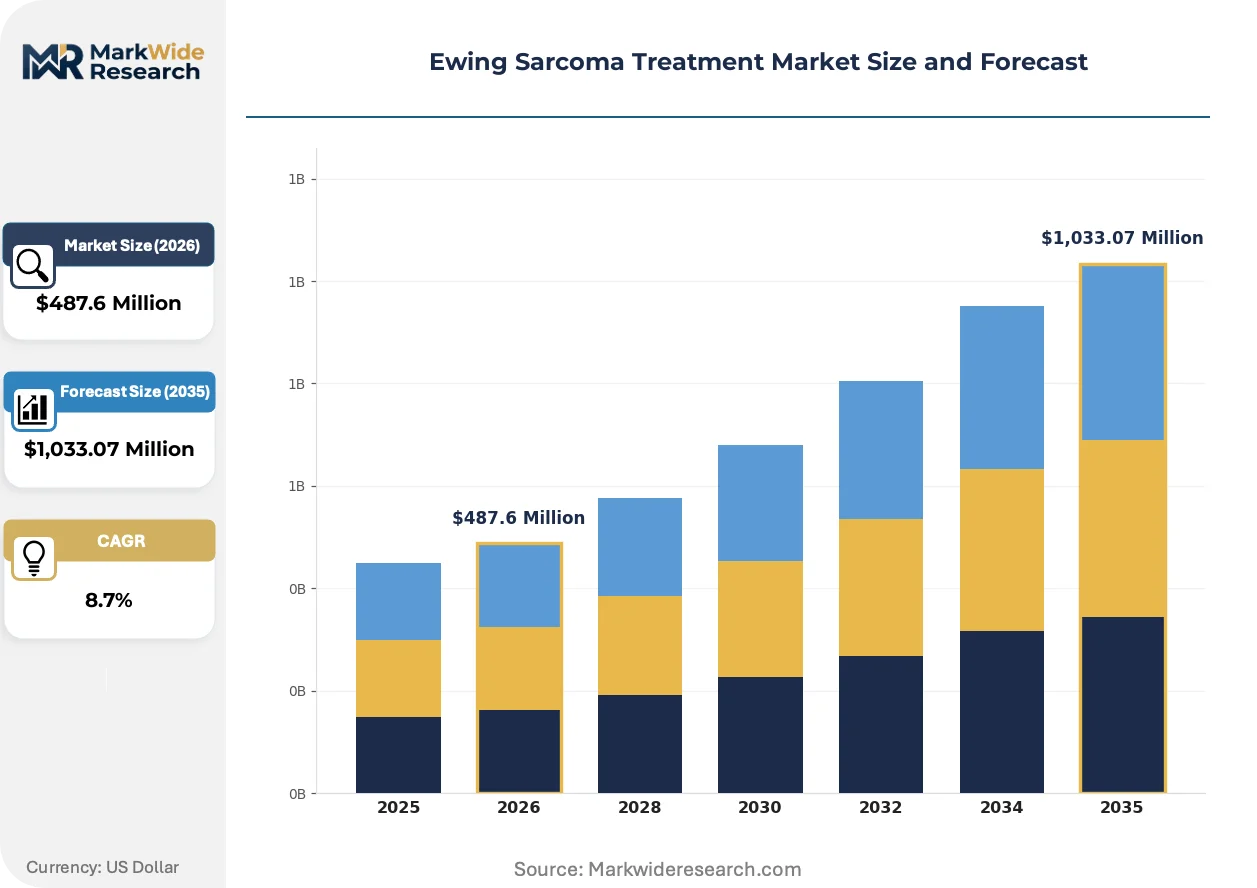
Market Dynamics
Orphan drug incentives from FDA and EMA are compressing clinical trial timelines for Ewing sarcoma therapies, while pediatric oncology departments at academic medical centers drive demand toward integrated multimodal care bundles rather than discrete treatment lines.
Growth Catalysts
- Orphan Drug Designation:FDA and EMA incentives accelerate trial recruitment and extend market exclusivity for novel agents targeting EWSR1-FLI1 fusion biology.
- Checkpoint Inhibitor Research:Sustained investment in immunotherapy trials for pediatric sarcoma applications expands the therapeutic armamentarium beyond cytotoxic backbones.
- Academic Medical Center Expansion:Major pediatric oncology departments in the United States, Germany, and Japan are broadening adoption of combination chemotherapy-radiation-immunotherapy protocols.
Market Restraints
- Radiopharmaceutical Input Constraints:The EU's F-Gas Regulation and REACH frameworks limit compliant manufacturing inputs for radiation therapy agents, redirecting supply chain investment toward certified production infrastructure.
- Small Patient Cohorts:Ewing sarcoma rarity compresses addressable populations per geography, fragmenting trial recruitment across dispersed referral networks.
- Fusion-Driven Biology Complexity:EWSR1-ETS translocation heterogeneity limits target conservation across patient subgroups, complicating biomarker-driven patient selection.
Strategic Opportunities
- Project Orbis Parallel Review:FDA's coordinated submission pathway with Health Canada and TGA offers sponsors simultaneous multi-territory approval for novel Ewing sarcoma agents.
- Precision Radiation Delivery:Advanced proton and stereotactic technologies enable margin reduction and reimbursement differentiation in mature radiation therapy segments.
- Adoptive Cell Therapy Pipelines:CAR-T and TCR-T platforms targeting EWSR1-FLI1 neoantigens represent underdeveloped white space with limited competitive entrants.
Industry Challenges
- Pediatric Trial Design Complexity:Ethical constraints on placebo-controlled studies in children with life-threatening disease complicate endpoint validation and regulatory acceptance.
- Manufacturing Scale Mismatch:Orphan indications require flexible batch sizing that conflicts with standard oncology production economics, pressuring unit cost structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ewing Sarcoma Treatment Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Radiation Therapy, Immunotherapy, Surgery Delivery Mode: Intravenous, Oral, Targeted, Local End User: Hospitals, Oncology Clinics, Research Institutions, Home Healthcare Therapy Area: Pediatric Oncology, Sarcoma Treatment, Rare Cancers, Bone Cancer |
| Companies Covered | Pfizer Inc., Bristol-Myers Squibb Company, Merck & Co., Inc., Novartis AG, Amgen Inc., Jazz Pharmaceuticals, Inhibrx, Inc., Roche, Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ewing Sarcoma Treatment Market Emerging Trajectories
Clinical development and care delivery in Ewing sarcoma are converging toward biology-directed precision approaches, with regulatory frameworks and procurement patterns adapting to accommodate smaller-population evidence generation.
Next-generation sequencing panels for EWSR1-ETS fusion detection are modularizing diagnostic workflows in pediatric oncology departments. Academic medical centers in the United States and Germany are integrating these platforms into standard workup protocols. This technology is compressing time-to-treatment initiation while enabling prospective biomarker stratification for trial enrollment.
The EU's F-Gas Regulation is reshaping radiopharmaceutical manufacturing economics by constraining fluorinated gas inputs for cyclotron operations. Production facilities must retrofit or relocate to compliant infrastructure, elevating capital requirements for European radiation therapy supply. German and French hospital networks are consolidating procurement toward suppliers with certified green chemistry capabilities.
Hospital procurement departments are unbundling after-sales service contracts from capital equipment purchases for radiation delivery systems. Buyers in Japan and the United States now negotiate maintenance, training, and upgrade terms separately from hardware acquisition. This shift transfers lifecycle cost risk to vendors while enabling transparent total-cost-of-ownership comparisons across proton and photon therapy platforms.
Ewing Sarcoma Treatment Market Segmentation
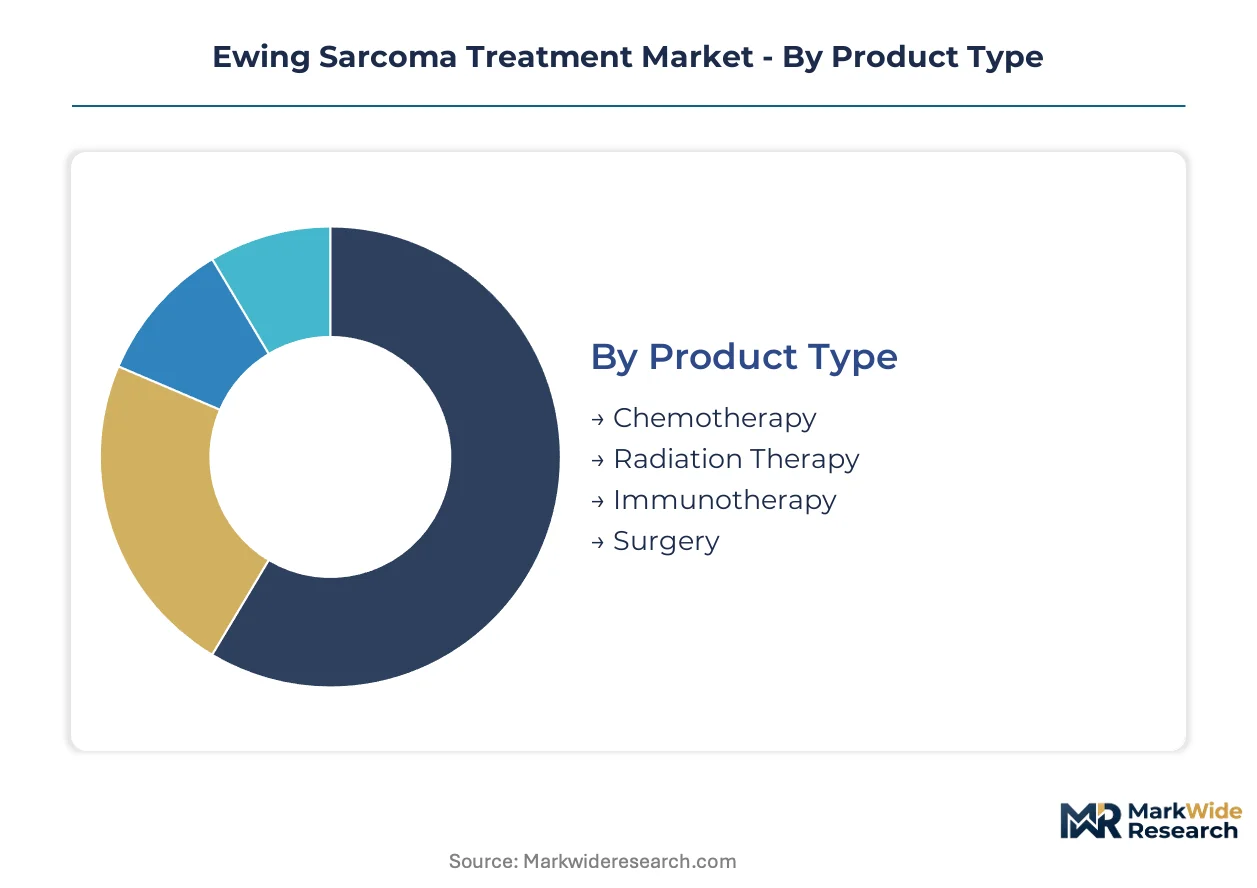
Ewing sarcoma treatment segmentation reflects capital intensity disparities across therapeutic modalities. Hospital procurement departments evaluate segments based on infrastructure requirements, reimbursement pathways, and patient throughput economics.
Product Type:
Chemotherapy and radiation therapy demand the heaviest upfront capital investment in manufacturing infrastructure and clinical delivery systems.
- Chemotherapy:Cytotoxic agent production requires sterile manufacturing suites and cold chain distribution networks. Demand concentrates in United States academic medical centers where VDC-IE backbone protocols anchor first-line induction therapy.
- Radiation Therapy:Proton and photon delivery systems entail capital expenditures exceeding photon platforms by multiples. German hospital networks are consolidating procurement toward suppliers with certified green chemistry capabilities under EU F-Gas Regulation compliance requirements.
- Immunotherapy:Checkpoint inhibitor and adoptive cell therapy manufacturing requires flexible batch sizing for orphan indications.
- Surgery:Limb-salvage and metastasectomy procedures depend on orthopedic oncology specialist availability.
Most installed capacity flows through Chemotherapy. Expansion is steepest in Immunotherapy.
Delivery Mode:
Route of administration shapes patient compliance, treatment setting economics, and pharmaceutical formulation complexity.
- Intravenous:Infusion center infrastructure dominates pediatric oncology departments. United States hospital networks optimize throughput through centralized chemotherapy suites with pharmacy oversight.
- Oral:Bioavailability challenges constrain Ewing-specific agents. Japanese regulators at PMDA have accelerated review pathways for pediatric formulations.
- Targeted:EWSR1-FLI1 fusion-directed delivery mechanisms remain investigational.
- Local:Intratumoral and regional perfusion techniques serve relapsed or metastatic presentations.
Patient volume concentrates in Intravenous delivery. Oral formulation development is climbing the fastest as sponsors seek outpatient administration models.
End User:
Site-of-care economics fragment procurement authority across integrated delivery networks and specialized outpatient settings.
- Hospitals:Academic medical centers in Germany and Japan capture complex case referrals through established sarcoma multidisciplinary tumor boards.
- Oncology Clinics:Community-based infusion centers in the United States handle stable-phase maintenance therapy.
- Research Institutions:Early-phase trial enrollment concentrates at NCI-designated comprehensive cancer centers.
- Home Healthcare:Oral agent administration and supportive care monitoring extend care beyond institutional settings.
Revenue concentration sits with Hospitals. Home Healthcare infrastructure is expanding most quickly as payors push site-of-care optimization.
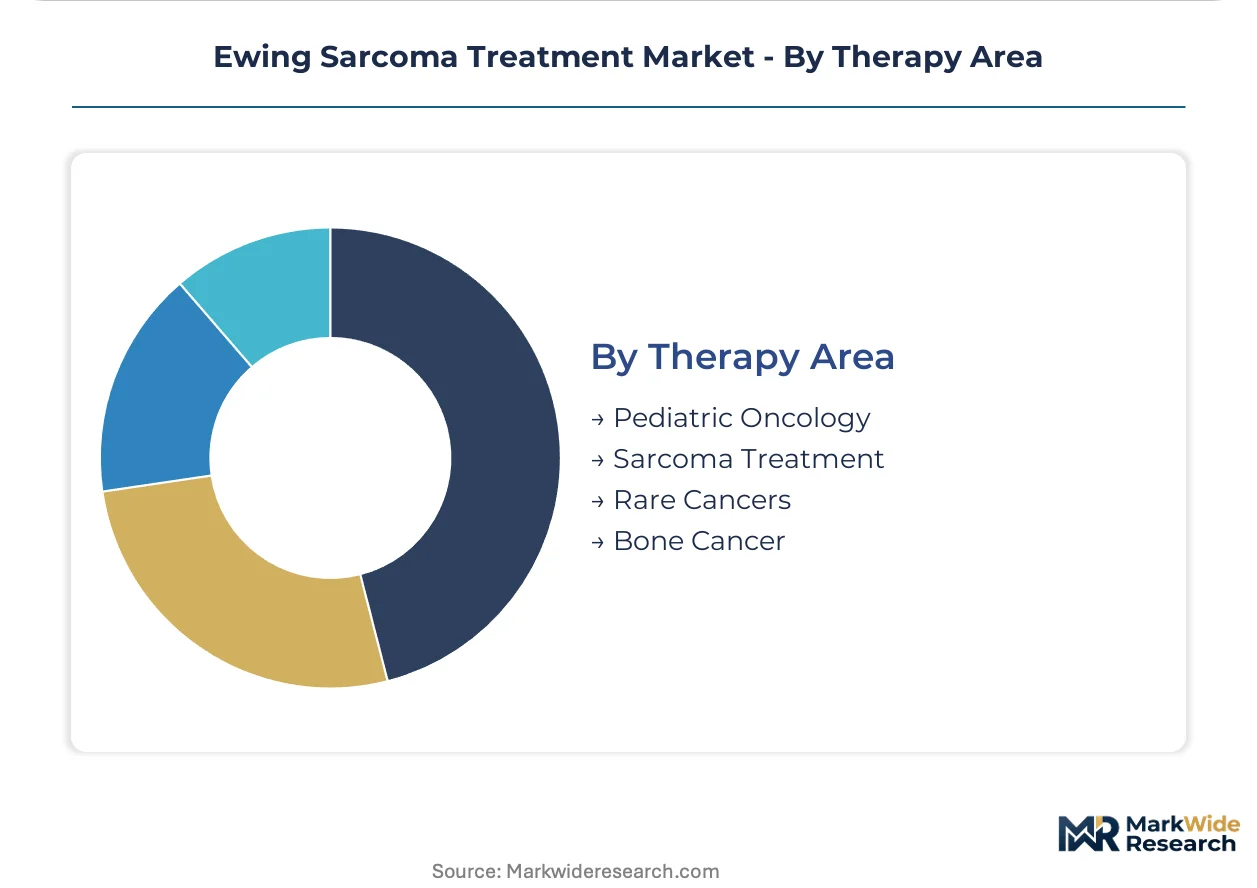
Therapy Area:
Clinical indication framing determines regulatory pathway, trial design, and reimbursement coding.
- Pediatric Oncology:Ethical constraints on placebo-controlled studies complicate endpoint validation. FDA pediatric investigation plans and EMA pediatric investigation plans compress development timelines for sponsors.
- Sarcoma Treatment:Cross-histology basket trials enable broader patient access but dilute indication-specific evidence.
- Rare Cancers:Orphan drug designation incentives from FDA and EMA extend market exclusivity windows.
- Bone Cancer:Distinct from soft tissue presentations in surgical and radiation planning protocols.
Trial enrollment flows predominantly through Pediatric Oncology. Rare Cancers designation pathways are gaining share fastest as sponsors navigate compressed recruitment timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ewing sarcoma treatment protocols were pioneered and standardized at United States academic medical centers during the 1970s and 1980s, establishing the VDC-IE chemotherapy backbone that remains the global reference standard today.
United States
NCI-designated comprehensive cancer centers in Houston and New York City drive protocol innovation through the Children's Oncology Group. FDA orphan drug designation compresses clinical trial timelines for sponsors targeting EWSR1-FLI1 fusion biology. Boston's Dana-Farber Cancer Institute anchors multidisciplinary sarcoma boards that integrate next-generation sequencing into standard diagnostic workflows.
Germany
University hospitals in Heidelberg and Berlin capture complex case referrals through established European Ewing sarcoma trial networks. The EU's F-Gas Regulation constrains radiopharmaceutical manufacturing inputs, redirecting supply chain investment toward compliant cyclotron infrastructure. Munich's proton therapy centers are consolidating procurement toward suppliers with certified green chemistry capabilities.
Japan
Pediatric oncology departments at Tokyo and Osaka academic medical centers are expanding adoption of combination immunotherapy protocols. PMDA accelerated review pathways for pediatric formulations compress regulatory timelines for novel agents. The Kansai region's hospital networks are unbundling after-sales service contracts from radiation delivery system purchases.
United Kingdom
The Royal Marsden Hospital and Birmingham Children's Hospital anchor national sarcoma referral pathways. NHS England's specialized commissioning framework concentrates complex cases at designated centers of excellence. London's research institutions are driving early-phase trial enrollment for checkpoint inhibitor combinations in relapsed disease.
France
Institut Gustave Roussy near Paris coordinates European pediatric sarcoma trials through the European Paediatric Soft Tissue Sarcoma Study Group. ANSM streamlined pediatric investigation plan reviews align with EMA frameworks. Lyon and Marseille hospital networks are integrating precision radiation delivery technologies into standard consolidation protocols.
Ewing Sarcoma Treatment Market Vendor Landscape
The competitive structure tilts toward diversified pharmaceutical conglomerates with oncology manufacturing scale. Large-cap developers dominate cytotoxic backbone supply through established hospital network relationships, while biotechnology specialists occupy the immunotherapy development frontier. Three archetypes define positioning: integrated oncology manufacturers with sterile production infrastructure, checkpoint inhibitor specialists with pediatric trial capabilities, and targeted therapy developers aligned with fusion-driven biology. Capacity expansion in compliant radiopharmaceutical facilities and strategic partnerships for adoptive cell therapy manufacturing represent the dominant competitive moves.
Among United States-based pharmaceutical conglomerates, Pfizer Inc. and Bristol-Myers Squibb Company exemplify the integrated oncology manufacturer archetype, with the former representing scale-driven cytotoxic supply and the latter occupying the checkpoint inhibitor research tier. Swiss-headquartered Novartis AG sits within the targeted therapy specialist category, its development focus aligned with EWSR1-FLI1 fusion biology. These three companies anchor the competitive landscape through distinct strategic positioning rather than overlapping capability claims.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Bristol-Myers Squibb Company |
| Merck & Co., Inc. |
| Novartis AG |
| Amgen Inc. |
| Jazz Pharmaceuticals |
| Inhibrx, Inc. |
| Roche |
| Eli Lilly and Company |
| Others |
Supply Flow & Price Mechanics
Orphan drug certification tiers bifurcate Ewing sarcoma treatment economics between premium-priced novel agents and commoditized cytotoxic backbones, with this divergence manifesting in divergent supply chain configurations: fusion-targeted therapies command dedicated biologics manufacturing suites while generic chemotherapy flows through high-volume sterile production networks in the United States and Germany. Pricing power concentrates with sponsors holding FDA breakthrough therapy or EMA PRIME designations, whereas vincristine-doxorubicin backbone suppliers compete on batch reliability and cold chain execution.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs Ewing sarcoma therapeutics. Premium tiers capture checkpoint inhibitors and adoptive cell therapies with EWSR1-FLI1 specificity, commanding price differentiation through biomarker-driven patient selection and orphan exclusivity. Standard tiers anchor on VDC-IE backbone protocols where volume scale and manufacturing efficiency determine competitive positioning. Cost compression in the economy tier intensifies as hospital procurement departments unbundle after-sales service contracts from radiation delivery system purchases, transferring lifecycle cost risk to vendors. Academic medical centers in the United States exhibit least price sensitivity due to dedicated sarcoma program funding, while community oncology clinics in Japan face greatest pressure from site-of-care optimization mandates.
Supply Chain Analysis
Reverse-logistics capabilities for radiopharmaceuticals remain underdeveloped in Ewing sarcoma care, with spent cyclotron targets and depleted isotope generators requiring specialized disposal pathways that few vendors have certified. Geographic supply concentration centers on the United States, Germany, and Switzerland for active pharmaceutical ingredients, with sterile manufacturing suites for cytotoxic agents clustering in North Carolina and Basel. Cold chain distribution for biologics draws from specialized logistics networks anchored in Memphis and Liege. Single-source vulnerability pervades the radiopharmaceutical segment where EU F-Gas Regulation compliance has eliminated non-certified cyclotron operators. Distribution runs through hospital-centric procurement with limited wholesale intermediation, reflecting direct manufacturer-to-academic medical center relationships for orphan indications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ewing sarcoma treatment represents a late-cycle quality story where demand shifts decisively toward precision-matched combination protocols rather than commodity cytotoxic backbones, rewarding sponsors with biomarker-stratified trial capabilities and compliant radiopharmaceutical infrastructure.
For Market Incumbents: Extend manufacturing scale advantages into adoptive cell therapy platforms through strategic partnerships with CAR-T developers targeting EWSR1-FLI1 neoantigens. Defend against emerging biotechnology specialists by securing exclusive supply agreements with proton therapy centers in Germany and Japan. Prioritize backward integration into radiopharmaceutical production to mitigate EU F-Gas Regulation compliance risks.
For New Entrants and Emerging Players: FDA's Project Orbis parallel review pathway with Health Canada and TGA opens a window for simultaneous multi-territory approval of novel Ewing sarcoma agents. Target the relapsed/refractory patient population where unmet need is greatest and competitive density lowest. Pursue white-space positioning through EWSR1-ETS fusion-directed targeted delivery mechanisms, leveraging academic medical center trial networks for rapid enrollment.
For Investors and Strategic Acquirers: Consolidation pressure builds where manufacturing scale mismatches with orphan indication batch economics, creating acquisition opportunities for flexible biologics production specialists. Long-term viability favors platforms with dual capability in checkpoint inhibitor research and radiopharmaceutical compliance infrastructure. Monitor FDA pediatric investigation plan submission volumes as an inflection indicator for competitive pipeline maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Children's Oncology Group protocols in Houston compress recruitment timelines for novel agents. |
| Regulatory Approval Pathway | EMA pediatric investigation plans extend market exclusivity windows for EWSR1-FLI1 targeted therapies. |
| Manufacturing Scale-Up | Flexible batch sizing for orphan indications addresses unit cost pressures in adoptive cell therapy. |
| Strategic Partnership | Proton therapy center alliances in Munich enable precision radiation delivery differentiation. |
| Pipeline Diversification | CAR-T and TCR-T platforms targeting fusion neoantigens occupy limited competitive white space. |
Methodological Framework
Direct dialogue with pediatric oncology department heads, hospital procurement managers, regulatory affairs leads at pharmaceutical sponsors, and formulary directors at United States academic medical centers grounded this analysis. Secondary validation drew from FDA orphan drug designation filings, EMA pediatric investigation plan submissions, ClinicalTrials.gov protocol records, and hospital procurement database extracts. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates.
Output projections across the analysis window reflect epidemiological incidence modeling, treatment protocol adoption curves, and pricing elasticity assumptions by payer archetype. Segmentation dimensions encompassed therapeutic modality, delivery route, site-of-care setting, and regional regulatory cluster. CAGRs were derived from log-linear trend fitting with scenario-weighted probability distributions. Forecast inputs incorporated EWSR1-ETS fusion detection technology diffusion rates and EU F-Gas Regulation compliance cost pass-through estimates.
Revisions become necessary when pediatric trial enrollment assumptions, radiopharmaceutical manufacturing capacity expansions, or checkpoint inhibitor approval timelines materialize differently than modeled. Forecasts reflect documented assumptions about referral network consolidation and orphan drug incentive continuity. Practitioners should monitor FDA Project Orbis expansion announcements and German proton therapy procurement patterns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Outpatient Oncology Infusion Market
Oncology
Asia-Pacific Radiation Oncology Market
Oncology
AI in Oncology Market
Oncology
Global Nasopharyngeal Cancer Market
Oncology
Peritoneal Cancer Treatment Market
Oncology
Paranasal Sinus Cancer Market
Oncology
US Veterinary Oncology Market
Oncology
Particle Therapy Systems Market
Oncology
Esophageal Cancer Market
Oncology
Australia Cancer Treatment Market
Oncology
Middle East and Africa Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Thyroid Cancer Market
Oncology
Liposarcoma Treatment Market
Oncology
Solid Tumor Market
Oncology
Global Skin Cancer Diagnostics and Therapeutics Market
Oncology
Vulvar Cancer Market