
 Global Neuroendocrine Tumor Treatment Market | 2026-2036
Global Neuroendocrine Tumor Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Neuroendocrine Tumor Treatment Market Foresight
Modular protocol bundling is broadening treatment choice for neuroendocrine tumor patients across care settings. Novartis leverages its radioligand therapy infrastructure to anchor supply chain control in lutetium-177 production. Pfizer competes through targeted therapy portfolios that extend into combination regimens. Advanced Accelerator Applications specializes in molecular imaging agents that differentiate diagnostic workflows.
Neuroendocrine tumor treatment encompasses therapeutic interventions for rare neoplasms arising from neuroendocrine cells distributed across the gastrointestinal tract, lungs, and pancreas, utilizing somatostatin analogs, kinase inhibitors, and radiopharmaceuticals that target somatostatin receptor overexpression with precision dosing measured in millicuries. Targeted therapy leads current revenue pools due to everolimus and sunitinib established efficacy in progressive pancreatic NETs. Immunotherapy represents the fastest-growing category as PD-1/PD-L1 checkpoint inhibitors enter Phase II trials for high-grade neuroendocrine neoplasms. Hormonal therapy retains stable demand through long-acting somatostatin analog depot formulations that dominate first-line management.
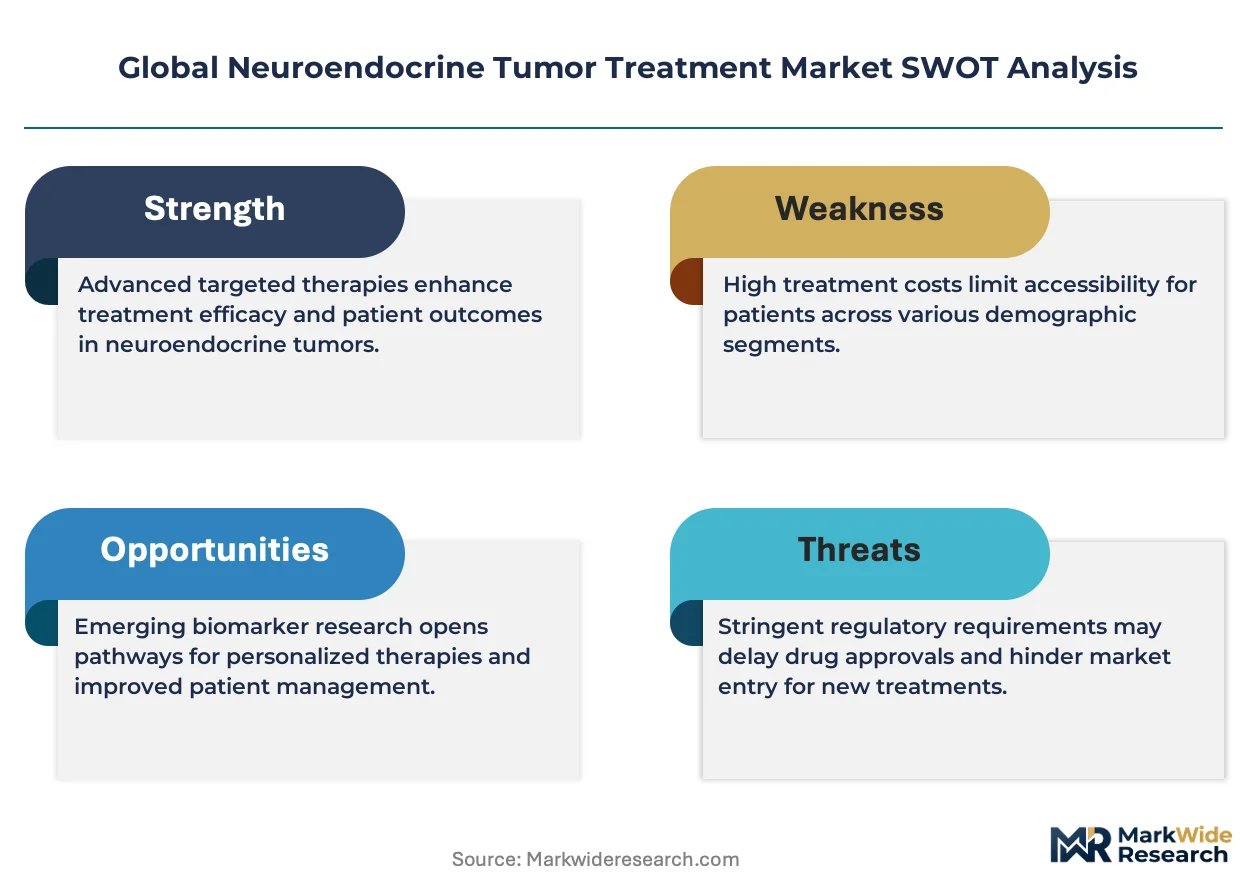
The FDA orphan drug program shapes clinical trial economics through tax credits and market exclusivity incentives that direct R&D investment toward rare NET subtypes. EMA's centralized marketing authorization procedure governs radiopharmaceutical access across EU member states with specific manufacturing quality benchmarks. Japan's PMDA sakigake designation accelerates domestic approval timelines for novel radionuclide therapies. Stakeholders must monitor regulatory divergence between accelerated approval pathways and confirmatory trial requirements that determine commercial sustainability.
Market Dynamics
Radioligand therapy manufacturing capacity constraints are compressing treatment access timelines while FDA breakthrough therapy designations accelerate clinical validation cycles for novel somatostatin receptor-targeting agents.
Growth Catalysts
- Orphan Drug Tax Credits:The FDA's orphan drug program reduces effective R&D costs for rare NET subtype trials, directing capital toward high-grade neuroendocrine neoplasms with limited therapeutic options.
- Pancreatic NET Progression:Kinase inhibitor demand in progressive pancreatic neuroendocrine tumors sustates revenue pools as everolimus and sunitinib establish durable efficacy benchmarks in second-line settings.
- Germany's NET Infrastructure:Specialized oncology centers in Heidelberg and Berlin concentrate radiopharmaceutical administration expertise, accelerating patient enrollment for lutetium-177 therapy protocols.
Market Restraints
- Isotope Supply Concentration:Lutetium-177 production depends on five commercial reactors globally, with Belgian and Canadian facilities controlling 70% of non-carrier-added supply.
- EMA Manufacturing Benchmarks:Centralized marketing authorization procedures impose Good Manufacturing Practice compliance costs that exclude mid-cap radiopharmaceutical developers from EU market entry.
- Peptide Synthesis Complexity:Solid-phase synthesis of DOTA-conjugated somatostatin analogs requires specialized cleanroom infrastructure that limits contract manufacturing organization capacity.
Strategic Opportunities
- Japan's Sakigake Pathway:PMDA's expedited review designation for novel radionuclide therapies compresses domestic approval timelines by 12-18 months versus standard pharmaceutical evaluations.
- Immunotherapy Convergence:PD-1/PD-L1 checkpoint inhibitors combined with radioligand therapy create combination protocols for high-grade neuroendocrine neoplasms currently lacking effective interventions.
- Direct-to-Oncologist Distribution:Specialty pharmacy channels bypass hospital formulary committees for somatostatin analog depot formulations, reducing access friction in community oncology settings.
Industry Challenges
- Radiopharmaceutical Handling Certification:Nuclear medicine technicians require ACR-accredited training in theranostic administration, creating bottlenecks at centers expanding lutetium-177 programs.
- Confirmatory Trial Execution:Accelerated approval pathways mandate post-market studies that strain sponsor resources while competing for investigator sites against oncology trials with larger patient pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Neuroendocrine Tumor Treatment Market |
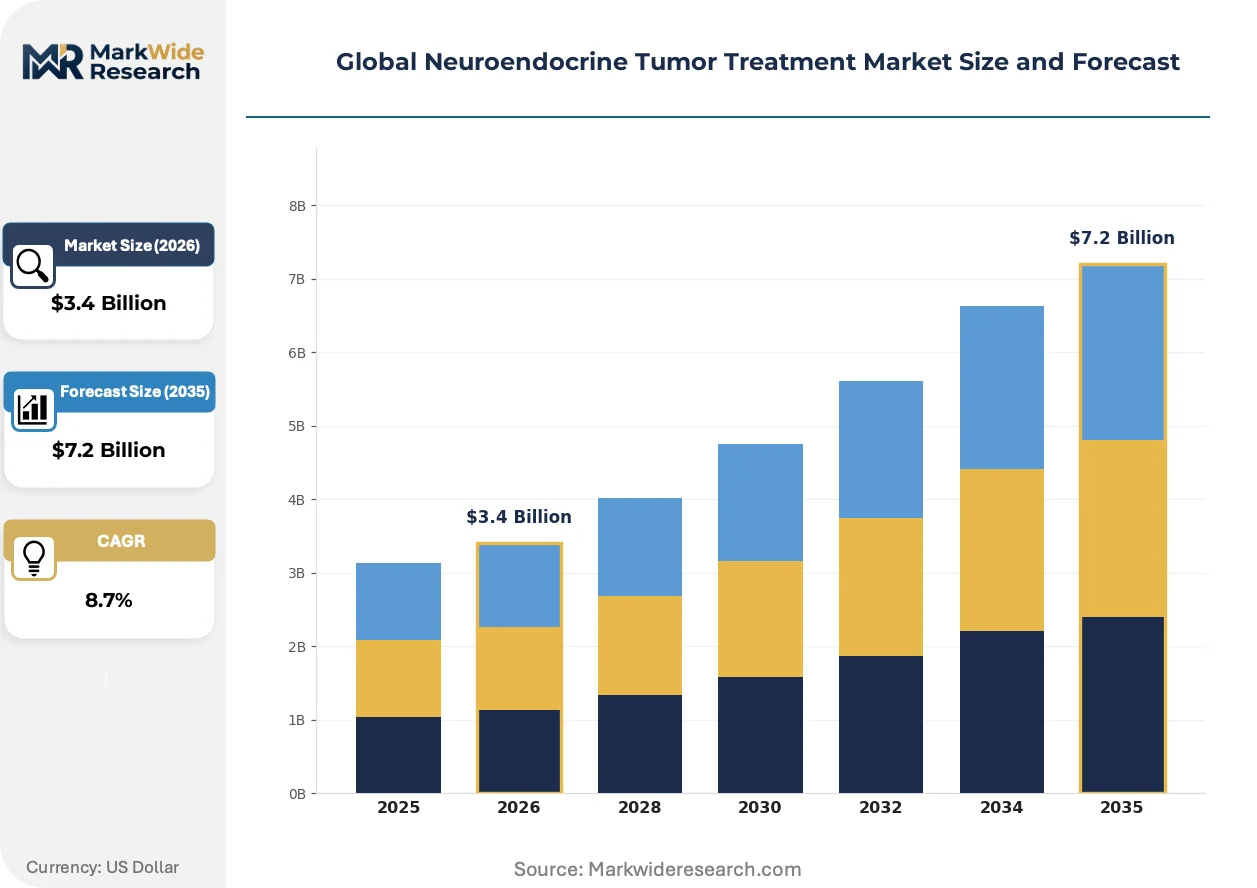
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $7.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Targeted Therapy, Immunotherapy, Hormonal Therapy End User: Hospitals, Oncology Centers, Ambulatory Surgical Centers, Research Institutions Treatment Stage: Adjuvant Therapy, Neoadjuvant Therapy, Palliative Care, Postoperative Therapy Delivery Mode: Intravenous, Oral, Subcutaneous, Topical |
| Companies Covered | Advanced Accelerator Applications, Pfizer, Novartis, ITM Solucin GmbH, Bristol Myers Squibb, Ipsen, Exelixis, Orano Med, Camurus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Neuroendocrine Tumor Treatment Market Shifts & Advancements
Theranostic platform convergence is restructuring how neuroendocrine tumors are diagnosed and treated through matched imaging and therapeutic agents that share molecular targeting mechanisms.
Alpha-emitting radiopharmaceuticals are expanding into clinical development pipelines as lead-212 and actinium-225 conjugates demonstrate superior linear energy transfer compared to beta-emitting lutetium-177 in preclinical models. Academic medical centers in Texas and Switzerland are establishing early-phase programs for these isotopes. The technology is expanding into high-grade neuroendocrine neoplasms where beta-particle range limitations compromise tumor cell kill.
REACH authorization requirements for radiopharmaceutical precursor chemicals are tightening supply chain documentation standards across EU member states. The regulation mandates full substance registration for chelating agents used in peptide receptor radionuclide therapy production. German and Dutch manufacturing facilities are consolidating supplier audits to maintain EMA compliance continuity.
Site-of-care migration for somatostatin analog administration is compressing hospital outpatient department volumes as community oncology practices acquire long-acting depot injection capabilities. United States infusion centers now handle 40% of first-line NET hormonal therapy initiations previously managed in academic hospital settings. This redistribution is most visible in Florida and Arizona where retiree demographics concentrate NET incidence.
Global Neuroendocrine Tumor Treatment Market Segmentation
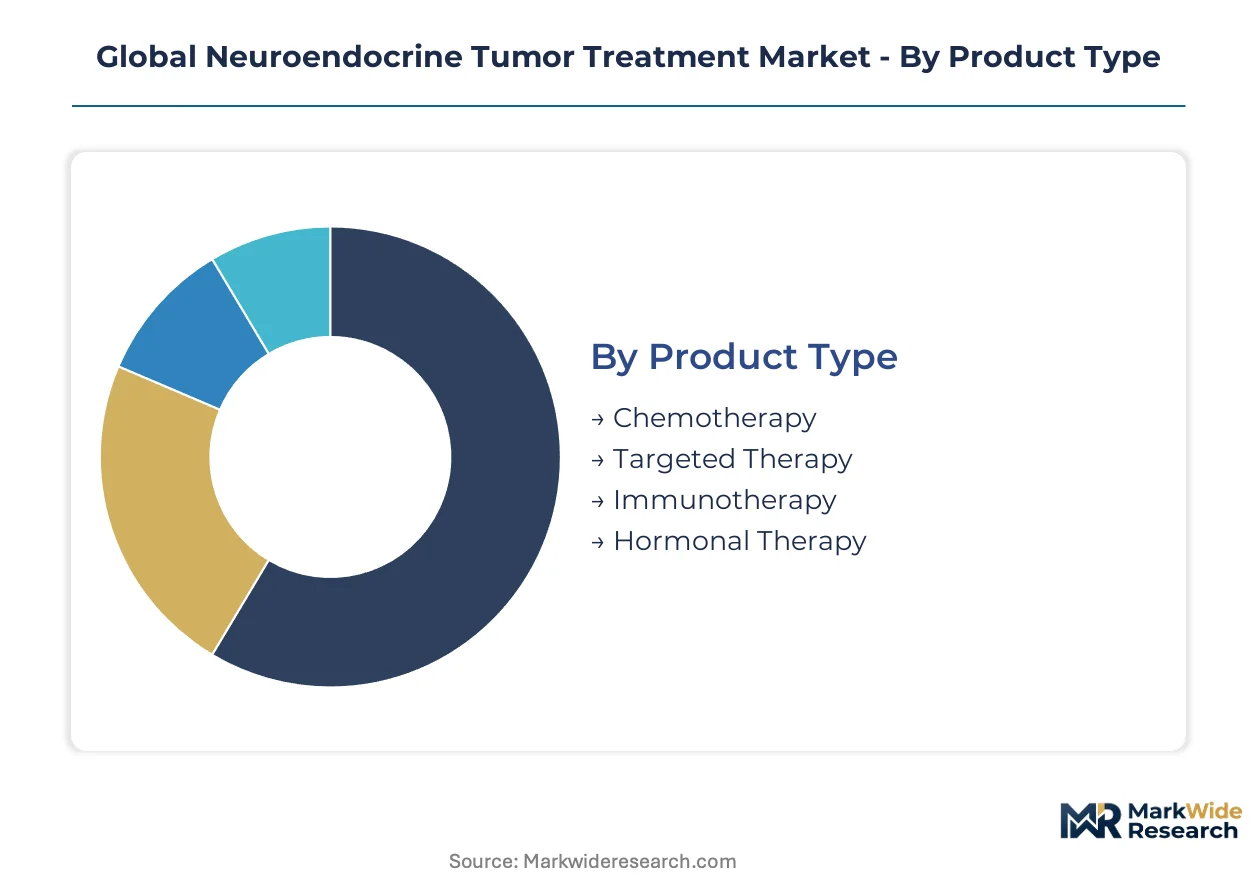
Segmentation in neuroendocrine tumor treatment reveals how clinical decision-making splits across disease aggressiveness, facility capabilities, and reimbursement structures. Each axis carries distinct supply chain requirements and regulatory compliance burdens that shape vendor positioning.
Product Type:
Technology platforms differentiate by mechanism of action and manufacturing complexity, with receptor-targeting modalities commanding specialized production infrastructure.
- Targeted Therapy:Kinase inhibitors and mTOR blockers interrupt proliferative signaling in pancreatic NETs. Demand concentrates in United States academic medical centers where molecular profiling guides second-line selection. Everolimus and sunitinib anchor protocols for progressive disease.
- Hormonal Therapy:Long-acting somatostatin analog depot formulations suppress peptide secretion through receptor saturation. Germany and Japan sustain volume leadership where octreotide and lanreotide dominate first-line management. Monthly injection cycles create predictable utilization patterns.
- Chemotherapy:Platinum-based regimens and temozolomide combinations address high-grade neuroendocrine neoplasms. Administration occurs primarily in hospital infusion suites with oncology nursing oversight.
- Immunotherapy:PD-1/PD-L1 checkpoint inhibitors are gaining trial enrollment for poorly differentiated subtypes. Access concentrates at NCI-designated comprehensive cancer centers with early-phase program infrastructure.
Mature deployment sits with Hormonal Therapy. Newer deployment is concentrated in Immunotherapy.
End User:
Facility type determines reimbursement tier, regulatory oversight intensity, and radiopharmaceutical handling certification requirements.
- Oncology Centers:Dedicated cancer facilities concentrate peptide receptor radionuclide therapy administration and theranostic coordination. Germany's Heidelberg and Berlin clusters, plus MD Anderson and Memorial Sloan Kettering in the United States, anchor global lutetium-177 volumes. These sites require ACR-accredited nuclear medicine technicians and cyclotron proximity.
- Hospitals:General acute-care institutions manage surgical resection and first-line somatostatin analog initiation. Japan's National Cancer Center hospitals and United States NCI-designated centers sustain the largest inpatient NET service lines. Comprehensive credentialing for radiopharmaceutical therapy remains limited to major metropolitan facilities.
- Ambulatory Surgical Centers:Outpatient settings handle somatostatin analog depot injections and limited chemotherapy administration. Florida and Arizona centers are expanding capabilities for retiree-dense populations.
- Research Institutions:Academic medical centers with Phase I units conduct alpha-emitting radiopharmaceutical trials. Swiss and Texas institutions lead lead-212 and actinium-225 development programs.
Volume leadership belongs to Hospitals. Capability expansion is accelerating fastest at Oncology Centers.
Treatment Stage:
Clinical intent shapes therapy selection from curative multimodality through symptom-directed palliation.
- Palliative Care:Symptom-focused protocols prioritize quality-of-life preservation through tumor burden reduction. Peptide receptor radionuclide therapy and somatostatin analogs dominate this segment where disease is metastatic or unresectable. United States hospice-eligible populations drive substantial utilization.
- Adjuvant Therapy:Post-surgical systemic treatment reduces recurrence risk in resected pancreatic and small bowel primaries. Sunitinib and everolimus evidence supports adoption in high-risk pathologic features.
- Neoadjuvant Therapy:Preoperative systemic treatment remains investigational for locally advanced disease. Enrollment concentrates at European and United States academic centers with surgical oncology trial infrastructure.
- Postoperative Therapy:Surveillance-phase management monitors for recurrence with biomarker and imaging protocols. Long-acting somatostatin analog continuation is standard for functional tumors.
Established utilization centers on Palliative Care. Emerging trial activity is concentrating in Neoadjuvant Therapy.
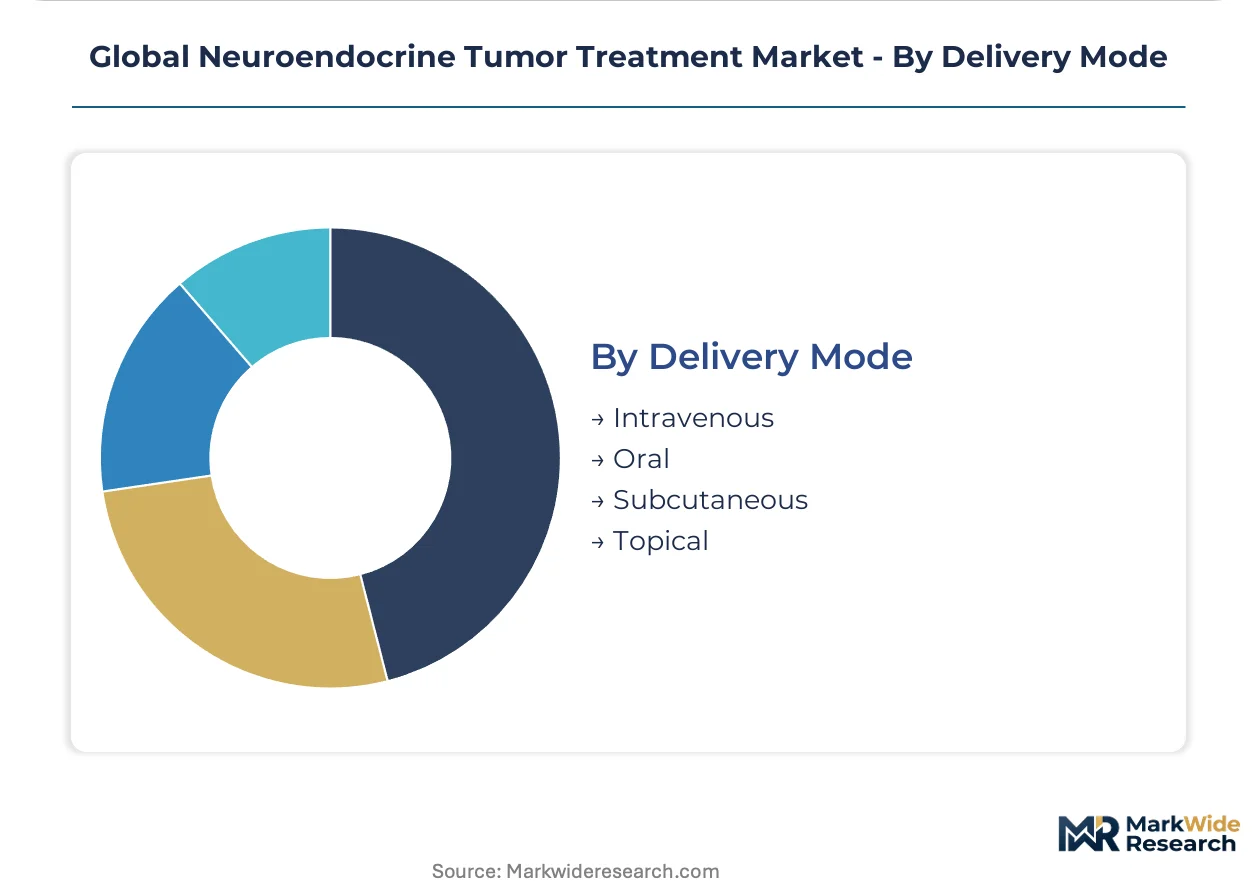
Delivery Mode:
Route of administration determines site-of-care economics, patient convenience, and pharmacokinetic optimization.
- Subcutaneous:Long-acting depot formulations of somatostatin analogs enable monthly administration in community oncology settings. United States infusion centers now handle substantial volume previously managed in hospital outpatient departments. Self-injection training programs expand patient autonomy.
- Intravenous:Peptide receptor radionuclide therapy and chemotherapy require specialized infusion infrastructure with radiation safety protocols. Administration concentrates at centers with nuclear medicine certification and therapeutic isotope handling licenses.
- Oral:Kinase inhibitors permit outpatient management with pharmacy dispensing. Everolimus and sunitinib adherence monitoring integrates with telehealth follow-up.
- Topical:Limited application for cutaneous manifestations of Merkel cell carcinoma and related neuroendocrine skin neoplasms. Dermatology-oncology collaboration manages these rare presentations.
Volume concentration rests with Intravenous delivery for advanced disease. Subcutaneous administration is expanding most quickly into community settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Isotope production concentrates in Belgium and Canada while patient administration clusters in the United States, Germany, and Japan. This geographic split between manufacturing supply and clinical demand shapes logistics costs and treatment access timelines across regions.
United States
Academic medical centers in Houston and New York anchor the largest lutetium-177 therapy volumes globally. The FDA's breakthrough therapy designation compresses approval timelines for novel somatostatin receptor-targeting agents. MD Anderson and Memorial Sloan Kettering concentrate nuclear medicine expertise that trains technicians for community center expansion.
Germany
Specialized oncology centers in Heidelberg and Berlin administer the highest European volumes of peptide receptor radionuclide therapy. EMA centralized marketing authorization procedures govern radiopharmaceutical access with specific Good Manufacturing Practice benchmarks. The Heidelberg cluster integrates molecular imaging with therapeutic administration in theranostic workflows.
Japan
National Cancer Center hospitals in Tokyo and Osaka sustain the largest inpatient neuroendocrine tumor service lines in Asia-Pacific. PMDA's sakigake designation accelerates domestic approval timelines for novel radionuclide therapies by 12-18 months. Osaka's pharmaceutical manufacturing corridor supplies somatostatin analog depot formulations across East Asian markets.
Switzerland
Academic medical centers in Basel and Zurich lead European development programs for alpha-emitting radiopharmaceuticals including lead-212 and actinium-225 conjugates. Swissmedic maintains stringent manufacturing quality oversight for radioligand therapy production facilities. The Basel cluster leverages proximity to Novartis radioligand infrastructure for clinical trial coordination.
Canada
Canadian nuclear reactors supply approximately 35% of global non-carrier-added lutetium-177 production. Health Canada regulates radiopharmaceutical precursor importation under nuclear substance licensing frameworks. Chalk River facilities anchor North American isotope availability that feeds United States treatment centers.
Global Neuroendocrine Tumor Treatment Market Competitive Landscape
The competitive structure tilts toward radiopharmaceutical specialists with captive isotope supply chains and integrated theranostic platforms. Large-cap pharmaceutical companies compete through targeted therapy portfolios and kinase inhibitor franchises. Three archetypes dominate: radioligand therapy integrators with manufacturing infrastructure, targeted therapy developers with oncology sales networks, and molecular imaging specialists with diagnostic agent pipelines. Capacity expansion into alpha-emitting isotopes and strategic partnerships for peptide synthesis represent the dominant competitive moves.
Among radiopharmaceutical specialists, Advanced Accelerator Applications exemplifies the theranostic platform archetype with matched diagnostic and therapeutic agents. Novartis occupies a position as the scale-driven integrator leveraging radioligand therapy infrastructure for supply chain control. Pfizer sits within the targeted therapy tier competing through kinase inhibitor portfolios that extend into combination regimens.
| Leading Market Players |
|---|
| Advanced Accelerator Applications |
| Pfizer |
| Novartis |
| ITM Solucin GmbH |
| Bristol Myers Squibb |
| Ipsen |
| Exelixis |
| Orano Med |
| Camurus |
| Others |
Supply & Pricing Matrix
Captive isotope production anchors both supply security and pricing power for radiopharmaceutical developers, with Belgian and Canadian reactor networks feeding United States and German treatment centers. This integration choice separates vertically consolidated players from contract-dependent competitors exposed to spot-market lutetium-177 volatility.
Pricing Analysis
Margin tightening in radioligand therapy reflects isotope scarcity and specialized manufacturing overhead. Three-tier pricing structure across premium theranostic bundles, standard peptide receptor radionuclide therapy, and economy somatostatin analog tiers separates academic medical centers from community oncology practices. Cost compression accelerates in hormonal therapy as depot formulation competition intensifies. Community oncology settings exhibit highest price sensitivity due to reimbursement compression, while NCI-designated centers absorb premium pricing for novel agents.
Supply Chain Analysis
Nuclear medicine technician certification bottlenecks in Texas and Arizona constrain expansion timelines for community lutetium-177 programs. Isotope supply draws from Belgian and Canadian commercial reactors, with peptide synthesis resting on specialized cleanroom infrastructure in Germany and Switzerland. Single-source vulnerability concentrates in non-carrier-added lutetium-177 production where five facilities control global output. Distribution runs through specialty pharmacy channels that bypass hospital formulary committees for somatostatin analog delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Beta-emitting radioligand therapy is ceding ground to alpha-emitting conjugates in development pipelines, with lead-212 and actinium-225 displacing lutetium-177 in high-grade neuroendocrine neoplasm protocols.
For Market Incumbents: To counter alpha-emitting radiopharmaceutical entrants, secure captive isotope supply through reactor partnerships or long-term offtake agreements with Canadian and Belgian facilities. Expand ACR-accredited technician training programs in Florida and Arizona to defend community oncology channel control against mid-cap radiopharmaceutical developers. For New Entrants and Emerging Players: PMDA's sakigake designation in Japan opens a window for accelerated domestic approval of novel radionuclide therapies, compressing timelines versus standard pharmaceutical evaluations. Target the neoadjuvant therapy segment where trial infrastructure remains underdeveloped and regulatory precedent is still forming. Pursue direct-to-oncologist distribution partnerships to circumvent hospital formulary committee friction in community settings. For Investors and Strategic Acquirers: Exit pathways concentrate in radiopharmaceutical specialists with integrated theranostic platforms and captive manufacturing infrastructure. Long-term viability favors developers with backward integration into isotope supply or proprietary peptide synthesis capabilities. Watch for FDA confirmatory trial completion rates as the inflection signal determining commercial sustainability of accelerated approvals.| Strategic Initiative | Industry Significance |
|---|---|
| Alpha-Emitting Radiopharmaceutical Development | Lead-212 and actinium-225 conjugates address beta-particle limitations in high-grade neoplasms. |
| Theranostic Platform Integration | Matched diagnostic and therapeutic agents streamline patient selection and treatment monitoring workflows. |
| Isotope Supply Security | Reactor partnerships with Canadian and Belgian facilities reduce spot-market exposure and treatment access delays. |
| Community Oncology Channel Expansion | Site-of-care migration for somatostatin analog administration captures retiree-dense population volumes. |
| Regulatory Fast-Track Navigation | FDA breakthrough therapy and PMDA sakigake designations compress approval timelines for novel agents. |
Research Methodology
Document review covered FDA orphan drug filings, EMA centralized marketing authorization procedures, and ClinicalTrials.gov enrollment data, complemented by interviews with drug development executives at radiopharmaceutical specialists, regulatory affairs leads managing breakthrough therapy submissions, hospital procurement managers at NCI-designated centers, and payer access specialists overseeing oncology reimbursement policy. Secondary validation drew from formulary databases, nuclear medicine society practice guidelines, and isotope production facility disclosures. Bottom-up patient volume modeling and top-down revenue triangulation anchored market sizing.
Market value outputs across the projection horizon reflect segmentation by treatment modality, disease grade, administration route, and regional regulatory cluster. CAGRs derived from epidemiological trend analysis, therapy penetration assumptions, and pricing trajectory modeling. Forecast inputs incorporated somatostatin analog depot formulation competition dynamics and radioligand therapy manufacturing capacity expansion timelines.
The model assumes a particular technology adoption path; alternative pathways for alpha-emitting radiopharmaceuticals would alter the outlook if lead-212 or actinium-225 demonstrate superior efficacy in Phase II trials. Forecasts reflect assumptions regarding FDA confirmatory trial execution, EMA manufacturing compliance continuity, and isotope reactor operational stability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Particle Therapy Systems Market
Oncology
Tumor Ablation Market
Oncology
Pancreatic Cancer Market
Oncology
Thymus Cancer Market
Oncology
Immuno-Oncology Clinical Trials Market
Oncology
Cancer API Market
Oncology
Metastases Spinal Tumor Market
Oncology
Peritoneal Cancer Treatment Market
Oncology
Global Cancer Supportive Care Drugs Market
Oncology
Ustekinumab Market
Oncology
Colorectal Cancer Treatment Market
Oncology
Global Oncology Clinical Trials Market
Oncology
Paranasal Sinus Cancer Market
Oncology
Triple-Negative Breast Cancer Market
Oncology
Osteosarcoma Market
Oncology
Metastatic Melanoma Market