
 Pharyngeal Neoplasm Market | 2026-2036
Pharyngeal Neoplasm Market Size, Share, and Industry Trends Forecast 2026-2036
Pharyngeal Neoplasm Market Analytics
The price-performance gap between branded biologics and biosimilar chemotherapy agents is hardening in pharyngeal cancer care. Merck & Co. anchors its position through deep vertical integration in Keytruda manufacturing, while Bristol-Myers Squibb competes via sustained R&D intensity across its immuno-oncology pipeline. AstraZeneca differentiates through targeted therapy specialization in EGFR-mutated populations, and Roche dominates diagnostic-therapeutic pairing with its companion testing platforms.
Pharyngeal neoplasm denotes malignant growths arising in the nasopharynx, oropharynx, or hypopharynx, typically squamous cell carcinomas requiring histopathological confirmation and HPV status determination to guide therapeutic selection. Immunotherapy now leads treatment paradigms for recurrent or metastatic disease, with PD-1 inhibitors displacing platinum-based chemotherapy as first-line standard in oropharyngeal subsets. Hospitals retain the largest patient volume share, though oncology clinics capture faster growth as outpatient infusion capacity expands and payers push site-of-care optimization.
FDA breakthrough therapy designation and EMA conditional marketing authorization compress development timelines for novel pharyngeal cancer agents, while NMPA priority review pathways in China accelerate regional market entry for multinational sponsors. The WHO Essential Medicines List inclusion criteria increasingly influence national reimbursement decisions across emerging markets. Stakeholders must monitor evolving biomarker-defined subpopulations and real-world evidence requirements that will determine which therapeutic modalities secure durable formulary placement.
Market Dynamics
PD-1 inhibitor displacement of platinum chemotherapy in first-line oropharyngeal settings is restructuring prescriber behavior, payer reimbursement hierarchies, and site-of-care economics across the treatment continuum.
Growth Catalysts
- EMA Conditional Marketing Authorization:Compresses development timelines for novel pharyngeal cancer agents, enabling earlier patient access while confirmatory trials continue.
- HPV-positive subpopulation stratification:Biomarker-defined patient selection improves response rates and justifies premium positioning for immunotherapy regimens.
- Outpatient infusion capacity expansion:Oncology clinics capture faster volume growth as payers mandate site-of-care optimization away from hospital-based administration.
Market Restraints
- Cold-chain biologics distribution:Temperature-sensitive PD-1 antibodies require specialized logistics that limit reach into rural and emerging markets.
- Companion diagnostic dependency:EGFR and PD-L1 testing infrastructure gaps in community oncology settings delay treatment initiation.
- Platinum agent price erosion:Generic cisplatin and carboplatin availability creates downward pressure on overall regimen reimbursement benchmarks.
Strategic Opportunities
- Real-world evidence platforms:Electronic health record integration enables post-marketing efficacy demonstration for accelerated label expansions.
- Multidisciplinary tumor board digitization:Remote consultation platforms extend specialist reach into community hospital networks lacking head-and-neck expertise.
- China NMPA priority review:Streamlined pathways for innovative oncology agents accelerate commercial entry in the world's second-largest pharmaceutical market.
Industry Challenges
- Pathologist workforce constraints:Specialized head-and-neck histopathology expertise concentrates in academic medical centers, creating diagnostic bottlenecks.
- Cross-border reference laboratory coordination:HPV testing and next-generation sequencing sample routing introduces treatment-delay risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharyngeal Neoplasm Market |
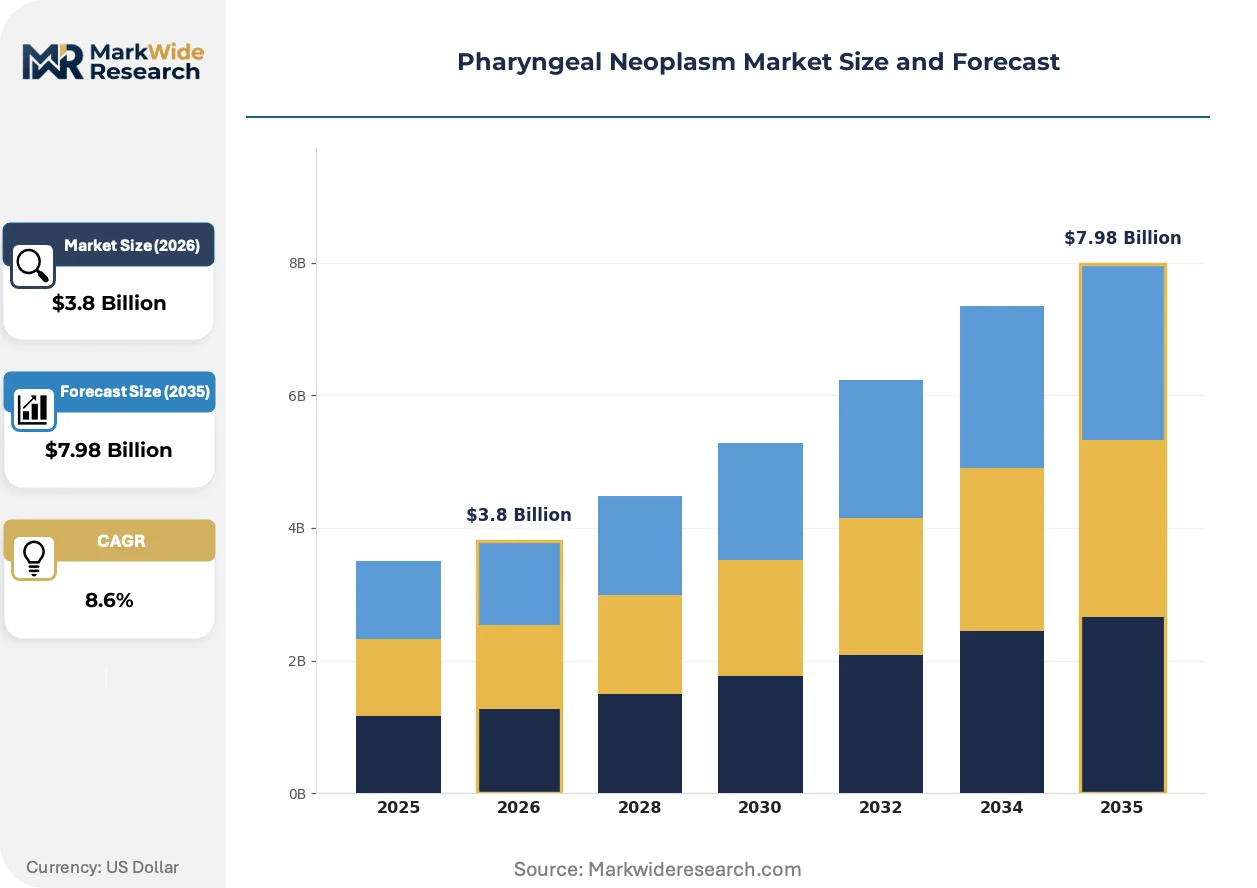
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Radiation Therapy, Immunotherapy, Targeted Therapy End User: Hospitals, Oncology Clinics, Ambulatory Surgical Centers, Research Institutions Treatment Stage: Early Stage, Locally Advanced Stage, Metastatic Stage, Recurrence Administration Route: Oral, Intravenous, Injection, Topical |
| Companies Covered | Merck & Co., Inc., Bristol-Myers Squibb, AstraZeneca, Pfizer, Roche, Eli Lilly and Company, Sanofi, GlaxoSmithKline, Innate Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharyngeal Neoplasm Market Evolving Landscape
Therapeutic modality convergence, diagnostic-therapeutic pairing, and site-of-care redistribution are compressing traditional boundaries between hospital and outpatient oncology delivery.
Neoadjuvant immunotherapy is expanding into locally advanced pharyngeal cancer, enabling organ-preservation strategies that reduce surgical morbidity. Academic medical centers in Germany and Japan are adopting this approach ahead of formal guideline updates. Pathologic complete response rates are reshaping surgical candidacy criteria and adjuvant radiation protocols.
FDA breakthrough therapy designation creates parallel review tracks that compress the interval between phase II data and commercial availability. Sponsors gain rolling submission privileges and intensive agency guidance. Oropharyngeal subsets with unmet need receive disproportionate regulatory resource allocation.
Site-of-care economics now govern prescriber decisions as payers impose reimbursement differentials between hospital outpatient departments and independent oncology clinics. United States Medicare site-neutral payment policies accelerate this behavioral shift. Infusion center capacity constraints in dense urban markets create geographic access disparities.
Pharyngeal Neoplasm Market Segmentation
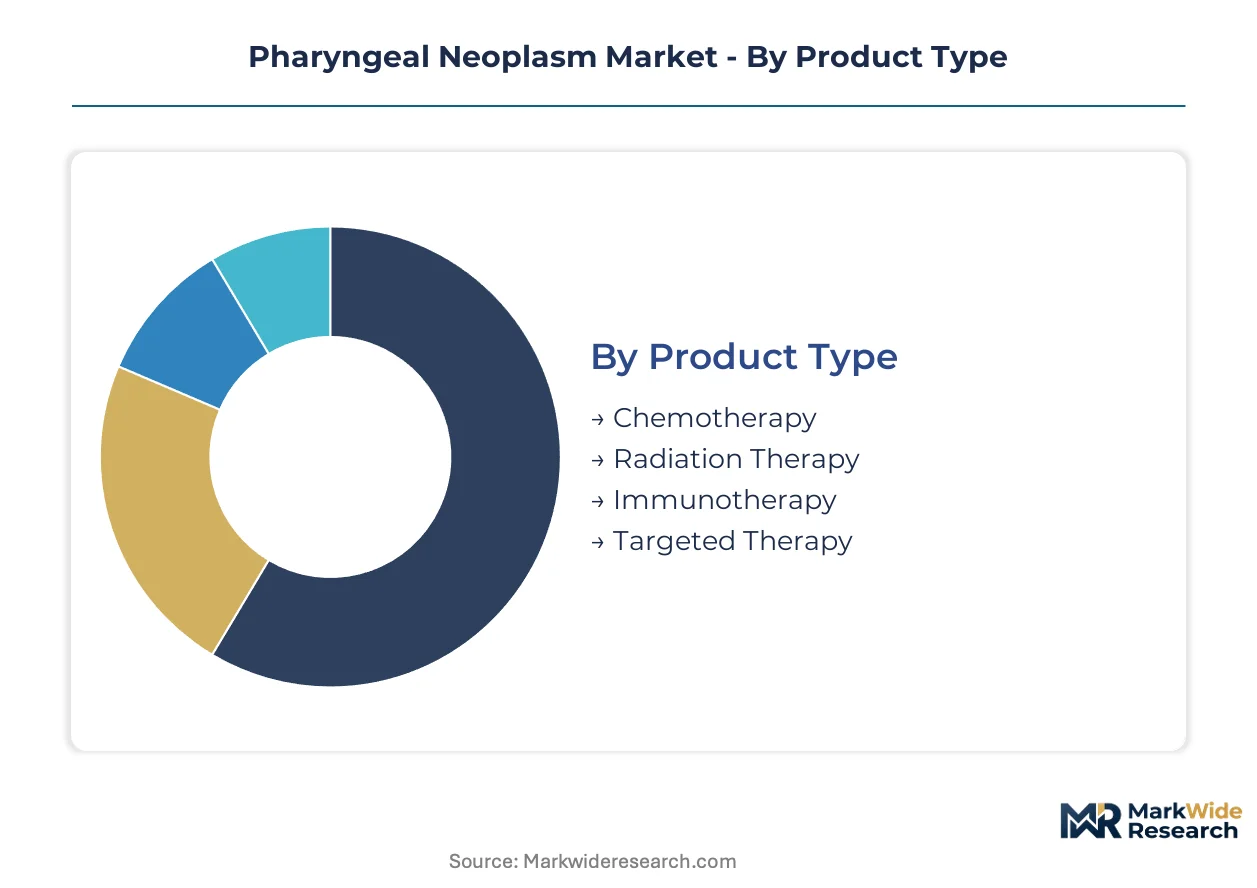
Pharyngeal neoplasm treatment selection hinges on precise patient stratification across therapeutic modality, care setting, disease stage, and delivery mechanism. Each segmentation dimension carries distinct regulatory requirements and reimbursement pathways that shape commercial strategy and access outcomes.
Product Type:
FDA approval pathways vary sharply across these modalities, with PD-1 inhibitors requiring breakthrough therapy designation while generic chemotherapy agents face abbreviated ANDA review.
- Immunotherapy:PD-1 and PD-L1 checkpoint inhibitors demonstrate superior overall survival in recurrent or metastatic oropharyngeal subsets with PD-L1 expression above 50%. Demand concentrates in United States oncology clinics where Medicare reimbursement for pembrolizumab and nivolumab has displaced platinum-based standards. Cold-chain distribution requirements and companion diagnostic dependency constrain penetration into community settings lacking on-site pathology.
- Targeted Therapy:EGFR inhibitors and angiogenesis blockers address biomarker-defined subpopulations with specific mutation profiles or tumor microenvironment characteristics. Cetuximab retains formulary placement in cetuximab-naive patients despite immunotherapy displacement, particularly in German university hospitals where head-and-neck tumor boards maintain protocol flexibility.
- Chemotherapy:Platinum agents and taxanes serve as backbone regimens in combination protocols and resource-limited settings where immunotherapy access remains restricted.
- Radiation Therapy:External beam and brachytherapy modalities integrate with systemic therapy in curative-intent protocols for locally advanced disease.
Immunotherapy sits at the top of the volume ranking, with targeted therapy climbing the fastest as biomarker testing infrastructure expands.
End User:
Site-of-care economics now govern prescriber decisions as payers impose reimbursement differentials between hospital outpatient departments and independent delivery settings.
- Hospitals:Academic medical centers retain complex case volume requiring multidisciplinary coordination, inpatient toxicity management, and integrated radiation oncology. These institutions anchor clinical trial enrollment and protocol development for neoadjuvant immunotherapy expansion.
- Oncology Clinics:Independent infusion centers capture faster volume growth as United States Medicare site-neutral payment policies accelerate behavioral shift away from hospital-based administration. Capacity constraints in dense urban markets create geographic access disparities.
- Ambulatory Surgical Centers:Limited role in pharyngeal neoplasm care given systemic therapy predominance and toxicity monitoring requirements.
- Research Institutions:Phase I-II trial sites in Japan and Germany drive early adoption of neoadjuvant immunotherapy approaches ahead of formal guideline updates.
Hospitals maintain the largest patient volume share, with oncology clinics expanding most quickly as outpatient infusion capacity scales.
Treatment Stage:
Disease extent at presentation determines curative versus palliative intent, organ preservation feasibility, and regimen intensity.
- Metastatic Stage:First-line immunotherapy monotherapy or combination protocols dominate, with PD-L1 expression and HPV status guiding selection between pembrolizumab, nivolumab-ipilimumab, or platinum-doublet backbones.
- Locally Advanced Stage:Concurrent chemoradiation remains standard, though neoadjuvant immunotherapy trials are reshaping surgical candidacy criteria and adjuvant radiation protocols in German and Japanese academic centers.
- Early Stage:Surgical resection with selective adjuvant radiation for high-risk pathologic features.
- Recurrence:Salvage surgery, re-irradiation, or systemic therapy selection depends heavily on prior treatment exposure and performance status.
Locally advanced stage sits at the top of the volume ranking, with metastatic stage gaining share fastest as detection patterns shift toward symptomatic presentation.
Administration Route:
Delivery mechanism shapes site-of-care requirements, nursing intensity, and patient adherence profiles across the treatment continuum.
- Intravenous:PD-1 inhibitors, platinum agents, and taxanes require infusion center capacity with cardiac monitoring capabilities. United States oncology clinics invest in chair expansion to capture site-of-care optimization incentives.
- Oral:Tyrosine kinase inhibitors and capecitabine enable home-based administration with periodic monitoring, reducing travel burden for rural patients.
- Injection:Subcutaneous formulations of select agents shorten administration duration and reduce infusion center capacity constraints.
- Topical:Limited applicability in pharyngeal neoplasms given anatomic location and mucosal surface characteristics.
Intravenous delivery sits at the top of the volume ranking, with oral administration climbing the fastest as patient convenience and site-of-care economics converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized head-and-neck oncologists concentrate in academic medical centers across the United States, Germany, and Japan, anchoring regional treatment capacity and clinical trial enrollment. These talent clusters drive adoption of neoadjuvant immunotherapy and multidisciplinary tumor board protocols. Geographic variation in pathology workforce density creates diagnostic access disparities that shape market penetration patterns.
United States
Medicare site-neutral payment policies accelerate patient migration from hospital outpatient departments to independent oncology clinics. FDA breakthrough therapy designation compresses commercialization timelines for PD-1 inhibitors in oropharyngeal subsets. The MD Anderson Cancer Center in Houston anchors neoadjuvant immunotherapy protocol development, with early adoption data influencing national guideline updates.
Germany
University hospital networks retain complex case volume requiring integrated radiation oncology and surgical expertise. EMA conditional marketing authorization enables earlier patient access to novel agents while confirmatory trials continue. The Heidelberg University Hospital cluster drives biomarker-defined patient stratification research, with HPV-positive subpopulation protocols spreading to community tumor boards.
Japan
PMDA priority review pathways accelerate commercial entry for multinational immunotherapy sponsors in the world's second-largest pharmaceutical market. METI funding supports domestic clinical trial infrastructure for head-and-neck malignancies. The National Cancer Center Hospital in Tokyo leads neoadjuvant immunotherapy adoption ahead of formal guideline revisions, with protocol data influencing regional treatment standards.
China
NMPA priority review streams reduce regulatory lag for innovative oncology agents targeting pharyngeal subtypes. Domestic biopharma investment expands biosimilar PD-1 manufacturing capacity to serve price-sensitive patient populations. Beijing-Tianjin-Hebei hospital networks concentrate multidisciplinary head-and-neck expertise, with tier-one cities driving companion diagnostic infrastructure deployment.
United Kingdom
NICE technology appraisal processes determine formulary placement for premium immunotherapy regimens in National Health Service trusts. MHRA post-Brexit regulatory autonomy enables accelerated access schemes for unmet need indications. The Royal Marsden NHS Foundation Trust in London anchors specialist head-and-neck surgical oncology capacity, with regional cancer centers adopting centralized pathology review protocols.
Pharyngeal Neoplasm Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the pharyngeal neoplasm therapeutic landscape, with integrated pharmaceutical conglomerates controlling manufacturing infrastructure while biotechnology specialists advance novel mechanisms through partnership structures. The market structure concentrates around three archetypes: vertically integrated immunotherapy platforms, targeted therapy specialists with diagnostic pairing capabilities, and diversified oncology portfolios with broad chemotherapy legacies. Dominant competitive moves include strategic partnerships for companion diagnostic co-development and geographic expansion through regional licensing arrangements to overcome cold-chain distribution constraints.
Within the integrated immunotherapy tier, Merck & Co., Inc. and Bristol-Myers Squibb occupy positions exemplifying scale-driven checkpoint inhibitor commercialization, while AstraZeneca represents targeted therapy specialization with EGFR-directed portfolio emphasis. These three anchors demonstrate how therapeutic modality focus shapes competitive positioning across biomarker-defined patient segments and regional reimbursement environments.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Bristol-Myers Squibb |
| AstraZeneca |
| Pfizer |
| Roche |
| Eli Lilly and Company |
| Sanofi |
| GlaxoSmithKline |
| Innate Pharma |
| Others |
Value Network & Pricing Analysis
Oncology clinic procurement concentration in the United States Medicare site-neutral payment environment anchors value-based contracting as the dominant pricing model for PD-1 inhibitors. Payer consolidation into three national pharmacy benefit managers concentrates price negotiation leverage, forcing manufacturers toward outcomes-based agreements with companion diagnostic bundling.
Pricing Analysis
Bundled regimen pricing with companion diagnostic testing separates from unbundled component purchasing across hospital outpatient and independent clinic settings. Three-tier pricing structure across premium immunotherapy, standard targeted therapy, and economy generic chemotherapy levels reflects biomarker stratification and site-of-care economics. Pricing pressure stems from biosimilar PD-1 manufacturing expansion in China compressing originator margins. Community oncology clinics exhibit highest price sensitivity due to Medicare reimbursement differentials, while academic medical centers maintain formulary flexibility for premium agents.
Supply Chain Analysis
Cold-chain freight costs for temperature-sensitive monoclonal antibodies constitute 12-18% of delivered product cost in pharyngeal cancer therapeutics. Active pharmaceutical ingredient manufacturing concentrates in China and India, with fill-finish operations in Ireland, Switzerland, and the United States. Supply chain vulnerability rests on single-source fermentation capacity for PD-1 antibody production. Distribution runs through specialty pharmacy networks with direct-to-clinic cold-chain logistics rather than wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
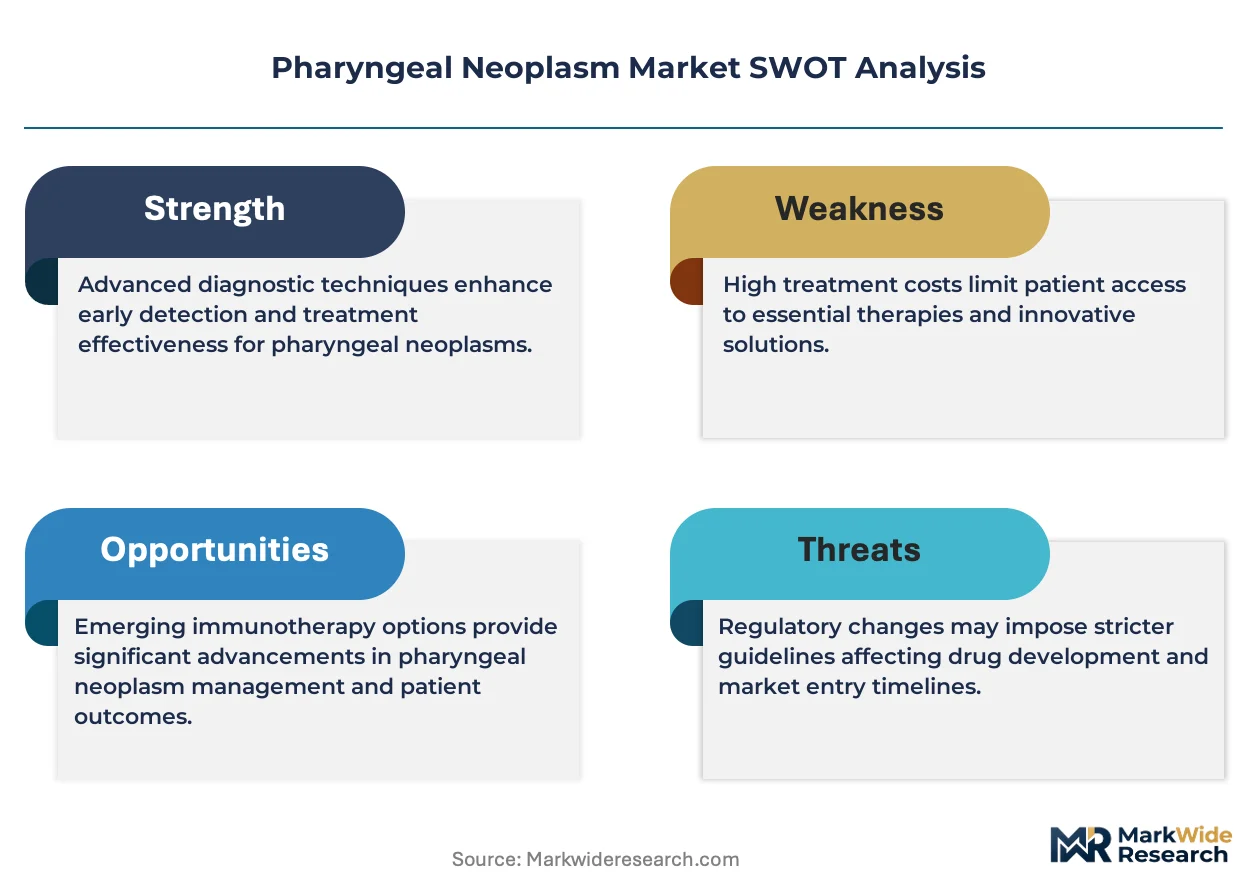
The pharyngeal neoplasm market represents a late-cycle quality story where biomarker-defined patient stratification shifts demand toward premium immunotherapy regimens with companion diagnostic pairing. Outcome-based contracting now separates sustainable positioning from commodity substitution risk.
For Market Incumbents: Deploy real-world evidence generation infrastructure as the primary defensive lever. Expand in-house biologics manufacturing capacity in Singapore or Switzerland to reduce tariff exposure on Chinese-sourced APIs. Deepen partnerships with diagnostic platform developers to lock in companion testing co-development ahead of biosimilar entry. Counter emerging Chinese PD-1 biosimilar threats through longitudinal patient outcome databases that demonstrate sustained efficacy differentiation. For New Entrants and Emerging Players: Enter via neoadjuvant immunotherapy protocols in locally advanced disease as the most penetrable white space. Target German and Japanese academic medical centers where tumor board adoption precedes formal guideline inclusion. Pursue EMA conditional marketing authorization pathways to compress development-to-commercialization timelines. Differentiate through organ-preservation endpoints rather than overall survival parity with existing PD-1 standards. For Investors and Strategic Acquirers: Large-cap immunotherapy platforms with exhausted pipeline optionality are the most active acquirers in this space. The five-to-ten year viability window favors assets with biomarker-specific mechanisms beyond PD-1/PD-L1 inhibition. Acquisition targets should demonstrate Phase II neoadjuvant data in head-and-neck subsets with pathologic complete response endpoints. Watch FDA breakthrough therapy designation frequency in oropharyngeal indications as the signal for competitive intensity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-development | Diagnostic-therapeutic pairing secures formulary placement and differentiates from biosimilar substitution. |
| Neoadjuvant Immunotherapy Expansion | Organ-preservation protocols in German and Japanese academic centers reshape surgical candidacy criteria. |
| Real-World Evidence Platform Investment | Electronic health record integration enables post-marketing label expansion and payer contract renewal. |
| Cold-Chain Distribution Infrastructure | Specialized logistics networks extend reach into community oncology settings beyond academic centers. |
| EMA Conditional Marketing Authorization | Accelerated European access while confirmatory trials continue compresses competitive launch windows. |
Research Methodology
Bottom-up oncology clinic volume modeling reconciled against top-down pharmaceutical manufacturer shipment tracking forms the analytical core of this study. Primary interviews with head-and-neck medical oncologists, formulary directors at national payers, regulatory affairs leads at immunotherapy developers, and pathology laboratory directors informed demand-side assumptions. Secondary validation drew from FDA breakthrough therapy designation filings, EMA conditional marketing authorization decisions, ClinicalTrials.gov protocol registrations, and Medicare Part B reimbursement databases.
Input-output matrices mapped patient flow from diagnosis through treatment lines across biomarker-defined subpopulations. Segmentation dimensions modeled include therapeutic modality, care setting, disease stage, and administration route. CAGRs were derived from regression analysis of historical volume trends applied to epidemiological incidence projections and treatment paradigm shift assumptions. Forecast inputs incorporated HPV-positive oropharyngeal cancer detection rates and site-of-care migration patterns under Medicare payment policy.
Inputs from clinical trial registries and payer formulary databases were available through the study window; gaps in real-world treatment sequencing data introduce uncertainty bands around metastatic stage volume shares. Forecasts reflect assumptions about immunotherapy displacement rates and biosimilar penetration timelines that could revise substantially with regulatory or competitive developments. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Interventional Oncology Ablation Market
Oncology
Global Veterinary Oncology Market
Oncology
Europe Radiotherapy Patient Positioning Market
Oncology
Global Metastatic Melanoma Drugs Market
Oncology
Australia Cancer Treatment Market
Oncology
Cancer/Tumor Profiling Market
Oncology
Non-Small Cell Lung Carcinoma (NSCLC) Market
Oncology
Triple-Negative Breast Cancer Market
Oncology
Ovarian Cancer Market
Oncology
Musculoskeletal Oncology Therapeutics Market
Oncology
South Korea Radiotherapy Market
Oncology
South America Bladder Cancer Therapeutics and Diagnostics Market
Oncology
Colorectal Cancer Market
Oncology
Metastases Spinal Tumor Market
Oncology
North America Bone Metastasis Market
Oncology
France Radiation Oncology Market