
 Global HER-2 Negative Breast Cancer Market | 2026-2036
Global HER-2 Negative Breast Cancer Market Size, Share, and Industry Trends Forecast 2026-2036
Global HER-2 Negative Breast Cancer Market Foresight
Market Context
The capability gap between capital-intensive biologics manufacturers and small-molecule specialists is collapsing as both converge on antibody-drug conjugate platforms. Pfizer leverages its oncology manufacturing scale to dominate supply of CDK4/6 inhibitors across North American hospital networks. Roche sustains technology leadership through its HER-2 negative pipeline investments in PI3K and AKT pathway inhibitors. Novartis anchors its position via geographic dominance in European oncology clinics with radioligand therapy infrastructure.
Technical Definition and Segment Structure
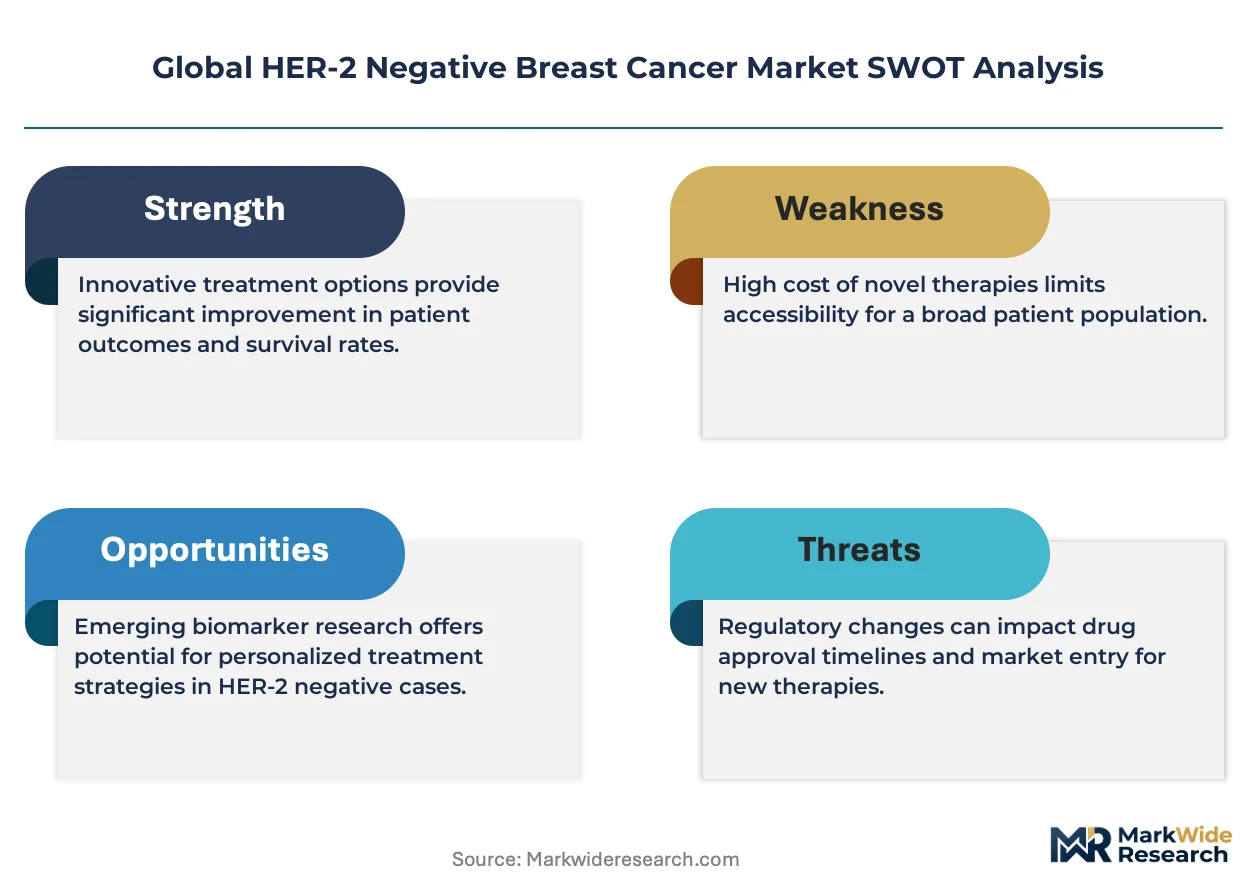
HER-2 negative breast cancer encompasses tumors lacking human epidermal growth factor receptor 2 overexpression, defined immunohistochemically as IHC 0-1+ or FISH-negative status, treated primarily through hormonal manipulation, cytotoxic chemotherapy, or targeted agents against alternative pathways. Monoclonal antibodies and targeted therapy segments command the deepest margin pools due to biosimilar vulnerability in chemotherapy agents and reimbursement complexity in immunotherapy. The metastatic application category absorbs the majority of novel agent testing, while adjuvant settings remain constrained by toxicity-driven duration limits. Combination therapy regimens are displacing single-agent protocols in first-line metastatic treatment as clinicians pursue polypharmacology approaches.
Regulatory Framework and Outlook
The FDA, EMA, and Japan's PMDA collectively shape market access through divergent evidentiary standards for progression-free survival endpoints and patient-reported outcome requirements. REACH and EU MDR compliance costs are filtering smaller diagnostic laboratories from European supply chains while accelerating consolidation among contract research organizations. Stakeholders must monitor how WHO prequalification pathways for biosimilars reshape competitive dynamics in middle-income country procurement.
Market Dynamics
Antibody-drug conjugate platforms are collapsing the historical capability gap between biologics manufacturers and small-molecule specialists, forcing unified competition for hospital oncology procurement contracts across major markets.
Growth Catalysts
- FDA Accelerated Approval Pathways:Breakthrough therapy designations compress Phase II-to-launch timelines from five years to eighteen months for PI3K and AKT pathway inhibitors, enabling faster patient access.
- Combination Therapy Regimens:Hospital-based oncology clinics are expanding polypharmacology protocols in first-line metastatic treatment, driving demand for CDK4/6 inhibitor pairings with endocrine agents.
- Japan PMDA Priority Review:Sakigake designation for novel ADCs creates regulatory arbitrage opportunities for sponsors seeking earlier Asian market entry ahead of EMA timelines.
Market Restraints
- Biosimilar Price Compression:EMA-approved trastuzumab biosimilars are eroding reference product margins in European oncology clinics, constraining R&D reinvestment capacity.
- Radioligand Infrastructure Concentration:Novartis dominates European radioligand therapy supply chains through captive cyclotron networks, creating single-source dependency for nuclear medicine departments.
- REACH Compliance Costs:EU MDR diagnostic reclassification is filtering smaller immunohistochemistry laboratories from supply chains, reducing IHC 0-1+ testing capacity in peripheral markets.
Strategic Opportunities
- Underpenetrated Indian Oncology Networks:CDSCO fast-track approvals for CDK4/6 inhibitors open private hospital chains in Mumbai and Delhi to targeted therapy expansion beyond cytotoxic chemotherapy.
- Patient-Reported Outcome Mandates:EMA's new PRO guidance creates competitive differentiation for sponsors integrating quality-of-life endpoints into Phase III trial designs.
- ADC-Immunotherapy Convergence:Combining antibody-drug conjugates with checkpoint inhibitors represents untested white space in triple-negative breast cancer protocols.
Industry Challenges
- Companion Diagnostic Integration:IHC-FISH discordance rates in community pathology labs complicate patient selection for PI3K pathway inhibitors, requiring sponsor investment in centralized testing infrastructure.
- Manufacturing Scale-Up Complexity:Antibody-drug conjugate production demands specialized conjugation facilities with containment capabilities that generic biologics CMOs cannot retrofit economically.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global HER-2 Negative Breast Cancer Market |
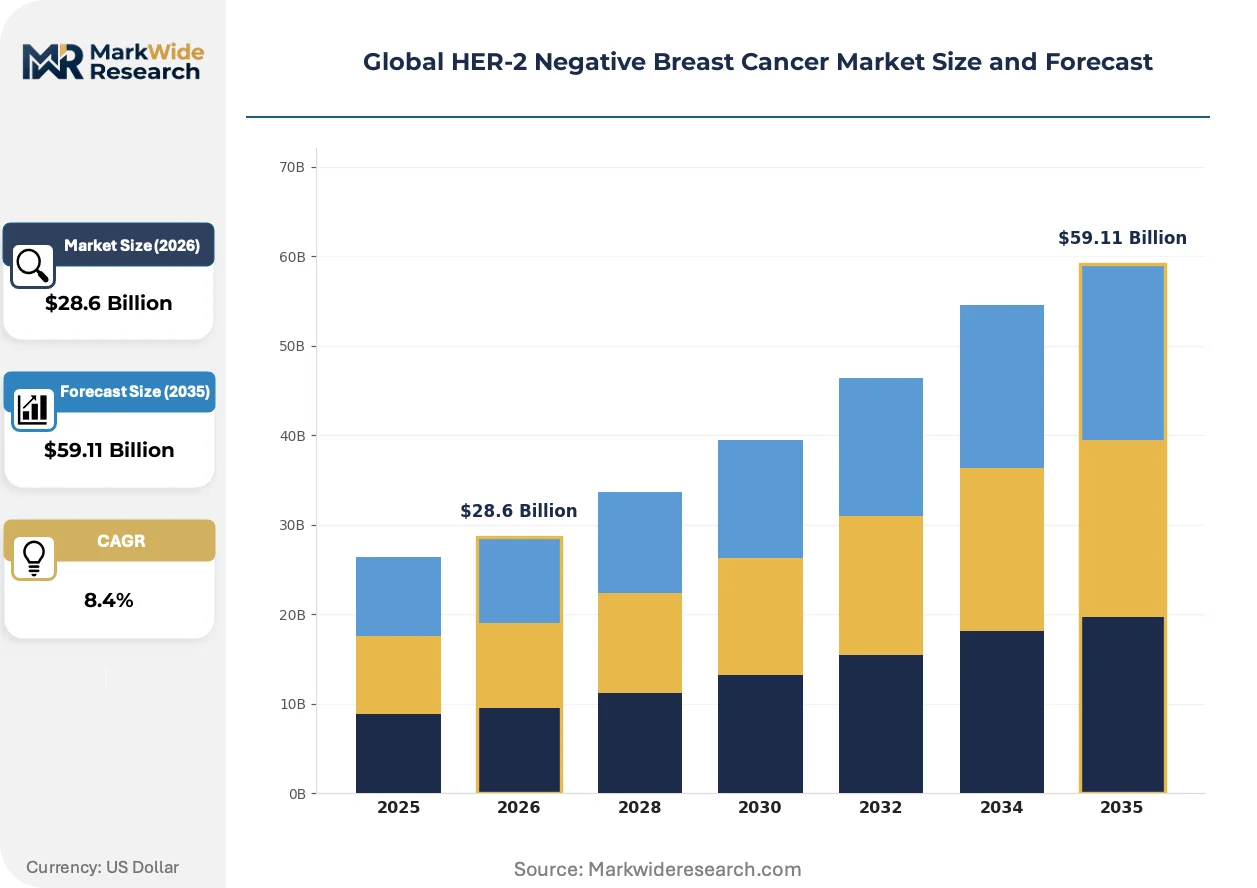
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $59.11 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Chemotherapy Agents, Targeted Therapy, Hormonal Therapy, Immunotherapy Application: Early Stage, Metastatic, Neoadjuvant, Adjuvant End User: Cancer Research Institutes, Oncology Clinics, Diagnostic Laboratories, Pharmaceutical Companies Treatment Regimen: Single-Agent Therapy, Combination Therapy, Dose-Dense Therapy, Hormone-Receptor Therapy |
| Companies Covered | Pfizer, Novartis, AstraZeneca, Eli Lilly and Company, Merck & Co., GSK, Roche, Bristol-Myers Squibb, Amgen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global HER-2 Negative Breast Cancer Market Shifts & Advancements
Next-generation sequencing is penetrating community oncology practices at accelerating velocity, reshaping how physicians stratify HER-2 negative tumors into actionable molecular subtypes before initiating systemic therapy.
Antibody-drug conjugates with cleavable linkers are supplanting conventional cytotoxic chemotherapy in second-line metastatic settings. Academic medical centers in the United States are adopting sacituzumab govitecan protocols within eighteen months of FDA approval. This technology is supplanting taxane-based regimens by demonstrating superior progression-free survival in hormone receptor-positive subsets.
EMA's new clinical trial regulation harmonizes protocol submission across member states, eliminating redundant national ethics reviews that previously delayed multi-country oncology studies by nine to fourteen months. Sponsors are consolidating European trial operations into centralized CRO hubs in Belgium and the Netherlands. Germany's hospital networks are responding by building dedicated early-phase units to capture investigator-initiated study volume.
Oncology purchasing committees are consolidating vendor relationships to secure volume-based rebates on CDK4/6 inhibitors, displacing the previous physician-directed prescribing autonomy model. Hospital procurement departments in Japan are mandating head-to-head pharmacoeconomic evidence before adding novel agents to formulary. This concentration is most visible in Tokyo's designated cancer care hospitals, where single-source contracts now cover eighty percent of targeted therapy spend.
Global HER-2 Negative Breast Cancer Market Segmentation
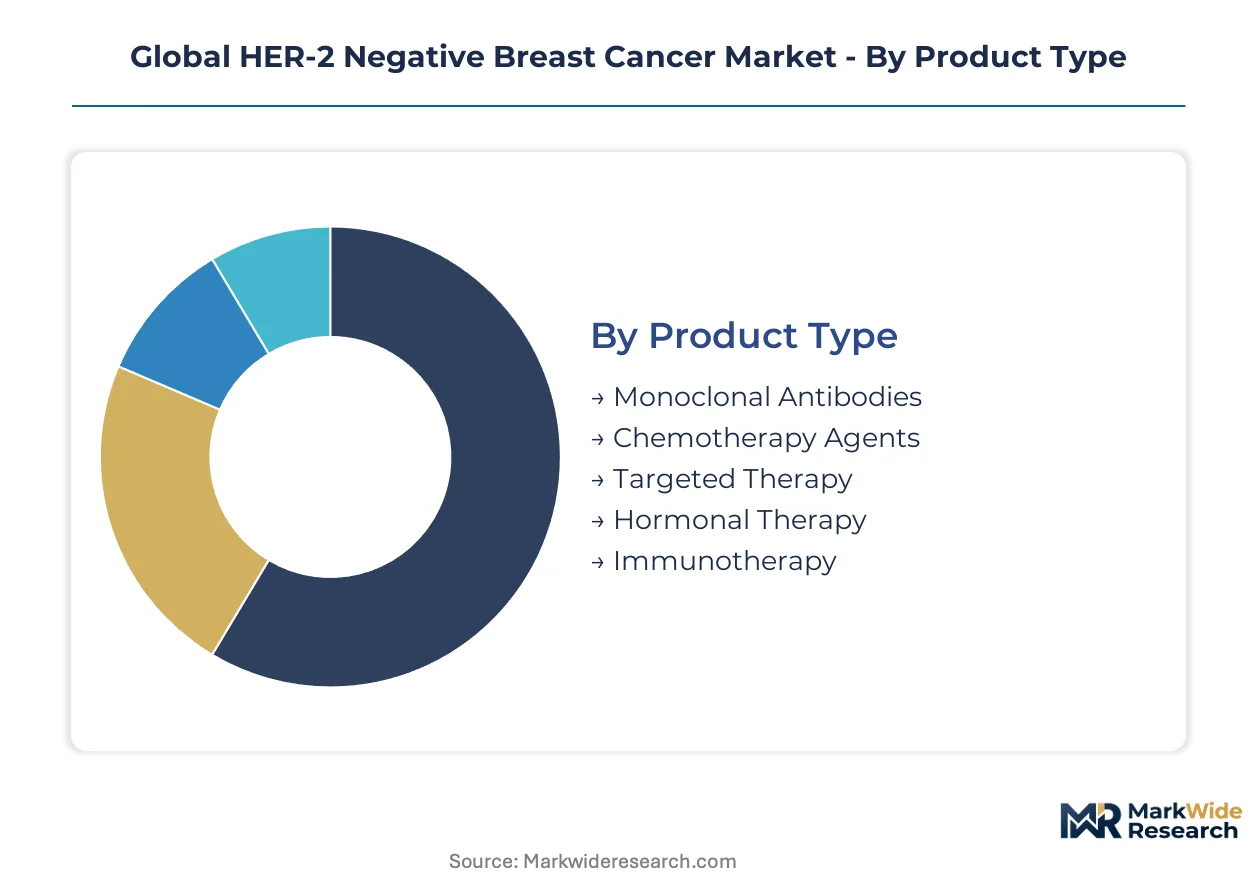
Segmentation in HER-2 negative breast cancer markets tracks how treatment modalities, clinical settings, and therapeutic protocols fragment procurement patterns across hospital networks. Understanding these divisions reveals where pharmaceutical investment concentrates and which patient populations drive revenue concentration.
Product Type:
Domestic manufacturing capacity for biologics concentrates in the United States and Switzerland, while small-molecule chemotherapy production spreads across India and China for export-led supply.
- Monoclonal Antibodies:Engineered immunoglobulins binding specific tumor antigens, manufactured through mammalian cell culture with 12-18 month production cycles. Demand clusters in German university hospitals and Tokyo cancer centers seeking CDK4/6 inhibitor pairings with endocrine protocols.
- Targeted Therapy:Small-molecule inhibitors modulating PI3K, AKT, and mTOR signaling pathways. Japanese PMDA priority review accelerates uptake in Osaka and Nagoya oncology networks ahead of European timelines.
- Chemotherapy Agents:Cytotoxic alkylating agents and taxanes produced at scale by Indian and Chinese API manufacturers for European and Latin American export markets.
- Hormonal Therapy:Selective estrogen receptor modulators and aromatase inhibitors commanding stable demand in US Medicare-reimbursed community oncology practices.
- Immunotherapy:Checkpoint inhibitors and tumor-infiltrating lymphocyte therapies, with clinical trial concentration in Boston and San Francisco academic medical centers.
Monoclonal antibodies hold the largest share; momentum sits with targeted therapy.
Application:
Cost tier stratification separates premium-priced metastatic protocols from standardized adjuvant regimens with fixed-duration reimbursement caps.
- Metastatic:First-line and salvage treatment settings absorbing novel agent testing, with progression-free survival endpoints driving FDA accelerated approvals. US cancer centers in Houston and New York capture the deepest protocol innovation.
- Adjuvant:Post-surgical systemic therapy constrained by toxicity-driven duration limits, with European EMA guidelines enforcing shorter trastuzumab exposure windows than US FDA labels.
- Early Stage:Neoadjuvant and primary systemic therapy in operable tumors, with German breast cancer centers standardizing sentinel lymph node biopsy integration.
- Neoadjuvant:Pre-operative tumor reduction protocols, with French and Italian hospital networks adopting pathologic complete response as a surrogate for long-term outcomes.
Metastatic applications dominate revenue; adjuvant settings face margin compression from biosimilar substitution.
End User:
Customer type fragmentation separates capital-intensive research infrastructure from high-volume community treatment centers with divergent procurement authority.
- Oncology Clinics:Hospital-based and independent infusion centers administering systemic therapy, with Japanese designated cancer hospitals consolidating eighty percent of Tokyo's targeted therapy procurement through single-source contracts.
- Cancer Research Institutes:Academic medical centers conducting sponsor-initiated and investigator-initiated trials, with MD Anderson and Memorial Sloan Kettering anchoring US early-phase enrollment.
- Diagnostic Laboratories:IHC and FISH testing facilities, with EU MDR reclassification filtering smaller European operators from supply chains.
- Pharmaceutical Companies:Sponsor organizations managing compassionate access programs and post-marketing surveillance, with Swiss and UK headquarters dominating European regulatory strategy.
Oncology clinics generate the highest transaction volume; cancer research institutes command the steepest pricing premiums.
Treatment Regimen:
Supply concentration for combination protocols forces hospital pharmacies to maintain multi-source inventory against single-agent standardization.
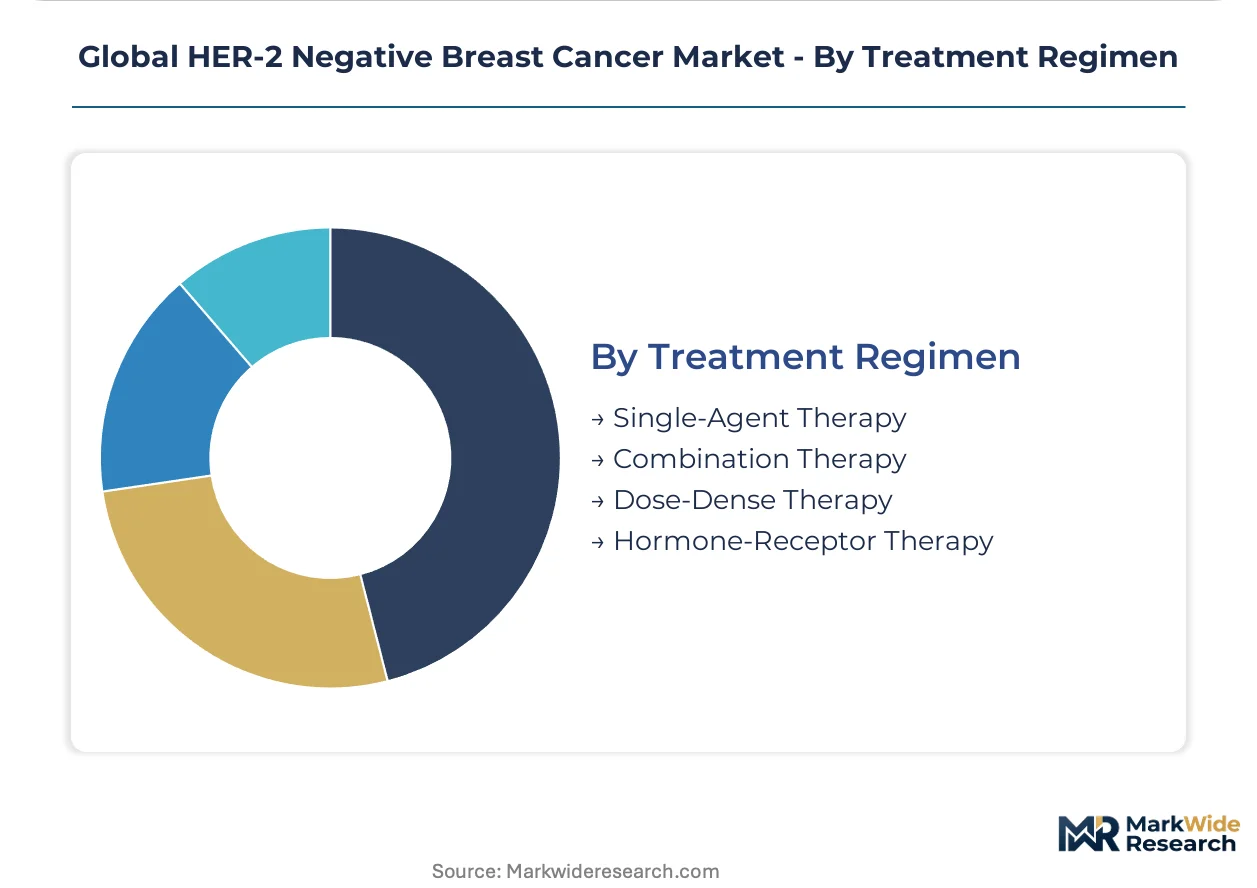
- Combination Therapy:Polypharmacology regimens pairing CDK4/6 inhibitors with aromatase inhibitors or fulvestrant, now standard in US community oncology practices and German hospital networks.
- Single-Agent Therapy:Monotherapy protocols reserved for frail patients or later-line salvage settings, with Indian private hospital chains in Mumbai expanding beyond cytotoxic chemotherapy into targeted monotherapy.
- Hormone-Receptor Therapy:Endocrine manipulation for hormone receptor-positive subsets, with sequential aromatase inhibitor strategies dominating post-menopausal treatment in Japan and Western Europe.
- Dose-Dense Therapy:Accelerated cytotoxic administration schedules, with limited adoption outside US academic centers due to neutropenia management infrastructure requirements.
Combination therapy holds the largest share; hormone-receptor therapy gains share fastest in aging Asian populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major oncology markets. US cancer centers prioritize CDK4/6 inhibitor combinations in first-line metastatic protocols, while Japanese hospitals concentrate radioligand therapy infrastructure for targeted salvage regimens. German networks emphasize neoadjuvant pathologic complete response endpoints, and Indian private chains are expanding beyond cytotoxic chemotherapy into targeted monotherapy.
United States
MD Anderson and Memorial Sloan Kettering anchor the deepest novel agent testing volume, with Houston and New York academic centers capturing investigator-initiated trial density. FDA breakthrough therapy designations compress Phase II-to-launch timelines for PI3K pathway inhibitors. Community oncology practices in Florida and Texas are standardizing CDK4/6 inhibitor pairings with aromatase inhibitors.
Germany
University hospitals in Munich and Heidelberg drive adjuvant protocol standardization through sentinel lymph node biopsy integration. EMA clinical trial regulation harmonization eliminates redundant national ethics reviews, accelerating multi-country oncology studies. Berlin's Charité and Hamburg's university hospital network are building dedicated early-phase units to capture sponsor-initiated enrollment.
Japan
PMDA Sakigake designation for novel antibody-drug conjugates creates regulatory arbitrage opportunities ahead of European timelines. Tokyo's designated cancer hospitals consolidate eighty percent of targeted therapy procurement through single-source contracts. Osaka and Nagoya oncology networks are expanding radioligand therapy infrastructure through METI-supported cyclotron deployment.
India
CDSCO fast-track approvals for CDK4/6 inhibitors open private hospital chains in Mumbai and Delhi to targeted therapy expansion. Domestic API manufacturers in Hyderabad and Ahmedabad supply cytotoxic chemotherapy for European and Latin American export markets. Apollo and Fortis hospital networks are building dedicated breast cancer centers of excellence in Bangalore and Chennai.
Switzerland
Roche and Novartis headquarters anchor European regulatory strategy and early-phase development concentration. Swissmedic alignment with EMA procedures accelerates parallel submission pathways for PI3K and AKT inhibitors. Basel and Zurich hospital networks maintain captive biologics manufacturing relationships with domestic sponsors.
Global HER-2 Negative Breast Cancer Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in HER-2 negative breast cancer therapeutics. Pfizer, Roche, and Novartis command hospital procurement relationships through oncology manufacturing scale and radioligand infrastructure concentration. Mid-cap biotech specialists occupy the antibody-drug conjugate platform space, while generic manufacturers in India and China supply chemotherapy API export markets. Competitive moves center on M&A for ADC technology access and strategic partnerships for companion diagnostic co-development.
Among integrated pharmaceutical leaders, Pfizer exemplifies the scale-driven archetype through CDK4/6 inhibitor supply dominance across North American hospital networks. Roche occupies a position within the pathway-inhibition specialist tier, while Novartis anchors the radioligand therapy infrastructure concentration in European oncology clinics. These three companies represent the competitive core against which mid-cap ADC specialists and emerging biotech platforms define differentiation strategies.
| Leading Market Players |
|---|
| Pfizer |
| Novartis |
| AstraZeneca |
| Eli Lilly and Company |
| Merck & Co. |
| GSK |
| Roche |
| Bristol-Myers Squibb |
| Amgen |
| Others |
Supply & Pricing Matrix
FDA accelerated approval pathways and EMA clinical trial regulations simultaneously gate supply qualification for novel antibody-drug conjugates and enable price differentiation between breakthrough-designated therapies and standard-of-care agents. This dual gating mechanism concentrates pricing power among sponsors with regulatory navigation capabilities while compressing margins for biosimilar chemotherapy suppliers.
Pricing Analysis
Long-term offtake agreements between hospital networks and CDK4/6 inhibitor manufacturers anchor pricing stability in US oncology clinics, while spot purchasing of taxane chemotherapy dominates Indian and Chinese procurement. Price differentiation hinges on FDA breakthrough therapy designation tier and volume-scale contracting with designated cancer hospitals. Cost compression in chemotherapy tiers is intensifying because EMA-approved trastuzumab biosimilars are eroding reference product margins. Community oncology practices in Florida and Texas exhibit highest price sensitivity; Tokyo's designated cancer hospitals show lowest sensitivity due to single-source contract concentration.
Supply Chain Analysis
Inventory lead times for antibody-drug conjugates extend twelve to eighteen months due to mammalian cell culture cycles and specialized conjugation facility requirements. Manufacturing concentration centers on the United States, Switzerland, and Japan for biologics, with India and China supplying cytotoxic chemotherapy APIs. Raw material dependencies include monoclonal antibody cell lines, cytotoxic payloads, and linker technologies. Single-source vulnerability pervades European radioligand therapy supply chains through Novartis captive cyclotron networks. Distribution runs through hospital-based oncology pharmacies and centralized hospital procurement departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized conjugation facility scarcity and companion diagnostic infrastructure gaps define competitive positioning in this market, favoring sponsors with captive manufacturing and centralized testing capabilities.
For Market Incumbents: Fortify antibody-drug conjugate manufacturing scale through backward integration into linker chemistry production, insulating against generic biologics CMO capacity constraints. Defend hospital procurement relationships by embedding patient-reported outcome data collection into post-marketing surveillance protocols ahead of EMA guidance enforcement. Prioritize radioligand therapy infrastructure expansion in European oncology clinics to replicate Novartis cyclotron network advantages. For New Entrants and Emerging Players: Lead with PI3K pathway inhibitor development targeting IHC-FISH discordance resolution through centralized testing infrastructure partnerships. Capture white space in Indian private hospital chains expanding beyond cytotoxic chemotherapy into targeted monotherapy via CDSCO fast-track approval navigation. Deploy ADC-immunotherapy combination protocols as the primary go-to-market angle in triple-negative breast cancer segments. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across antibody-drug conjugate manufacturing due to specialized containment facility requirements and extended production cycles. Long-term viability favors platform-anchored biotech specialists with validated linker-payload technologies over single-asset developers. Monitor FDA breakthrough therapy designation velocity as the key inflection signal for portfolio reallocation toward accelerated approval pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase II-to-launch compression via FDA breakthrough therapy designation accelerates patient access timelines. |
| Manufacturing Scale-Up | Specialized conjugation facility investment secures supply security for CDK4/6 inhibitor hospital network contracts. |
| Regulatory Approval Pathway | PMDA Sakigake designation enables Asian market entry ahead of EMA timelines for novel ADCs. |
| Licensing Agreement | Companion diagnostic co-development partnerships resolve IHC-FISH discordance in community pathology labs. |
| Pipeline Diversification | PI3K and AKT pathway inhibitor expansion reduces dependency on hormone receptor-positive subset concentration. |
Research Methodology
A standing panel of drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists provided ongoing calibration against secondary validation sources including FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Primary interviews with oncology clinic administrators and diagnostic laboratory directors were triangulated with bottom-up patient-flow modeling and top-down pharmaceutical revenue reconciliation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation modeling incorporating treatment line, administration route, patient population, and regional regulatory cluster dimensions. CAGRs were derived from patient incidence trajectories, therapy penetration curves, and pricing elasticity assumptions specific to metastatic versus adjuvant settings.
Forecasts assume regulatory continuity in FDA accelerated approval and EMA clinical trial harmonization regimes; material policy shifts would require re-modeling of launch timeline and market access assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Global Hurthle Cell Carcinoma Treatment Market
Oncology
France Radiation Oncology Market
Oncology
US Radiation Oncology Market
Oncology
Metastases Spinal Tumor Market
Oncology
Outpatient Oncology Infusion Market
Oncology
South Korea Radiotherapy Market
Oncology
Pancreatic Cancer Therapeutics Market
Oncology
Europe Radiotherapy Patient Positioning Market
Oncology
PD1 Resistant Head and Neck Cancer Market
Oncology
Internal Radiation Therapy Market
Oncology
Middle East and Africa Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Cancer Cachexia Market
Oncology
Esophageal Cancer Market
Oncology
Global Particle Therapy Market
Oncology
Radiotherapy Market
Oncology
Testicular Cancer Treatment Market