
 Global Silicone Fluid Market | 2026-2036
Global Silicone Fluid Market Size, Share, and Industry Trends Forecast 2026-2036
Global Silicone Fluid Market Intelligence
New production capacity in China is fragmenting the traditional supply base once concentrated in Europe and Japan. Dow Inc. leverages its vast scale in basic chemical production to compete on cost for commodity grades. In contrast, Wacker Chemie AG specializes in high-purity fluids for demanding medical and electronics applications. Shin-Etsu Chemical Co., Ltd. dominates the market for specialized fluids used in advanced semiconductor manufacturing processes.
Silicone fluids are synthetic polymers characterized by a silicon-oxygen backbone, known as siloxane, with attached organic side groups. Their unique properties, including high thermal stability and low surface tension, make them ideal for use as lubricants, hydraulic fluids, and surfactants. Dimethyl silicone fluid constitutes the largest product segment by volume due to its widespread use across multiple industries. However, specialized amino silicone fluids used in personal care and textile applications command significantly higher price points and margins.
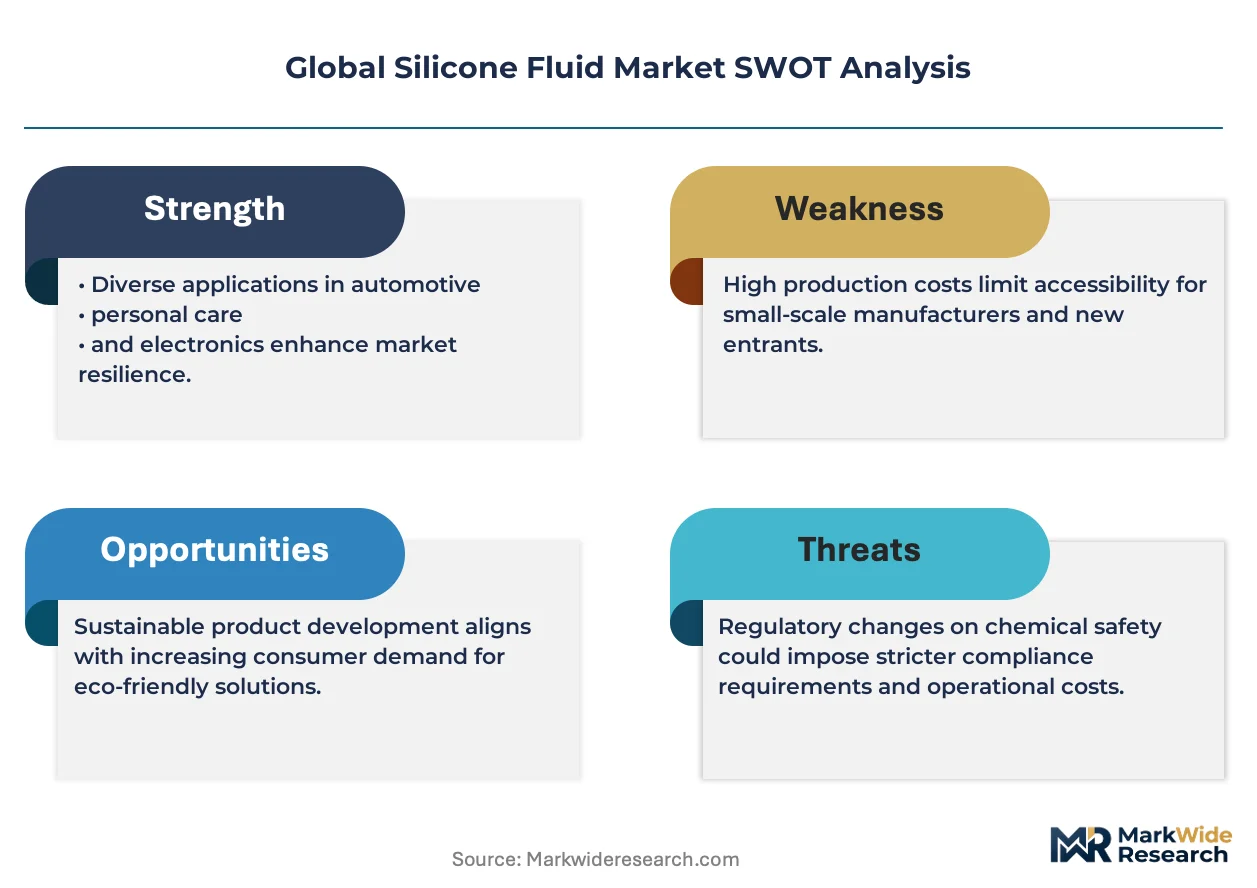
The European Union's REACH regulation and the US EPA's oversight under the Toxic Substances Control Act create a complex compliance landscape. These frameworks impose restrictions on specific siloxanes, particularly in wash-off cosmetic products and other consumer-facing applications. Consequently, formulators must continually adapt product chemistry to navigate divergent international chemical control laws and evolving safety expectations.
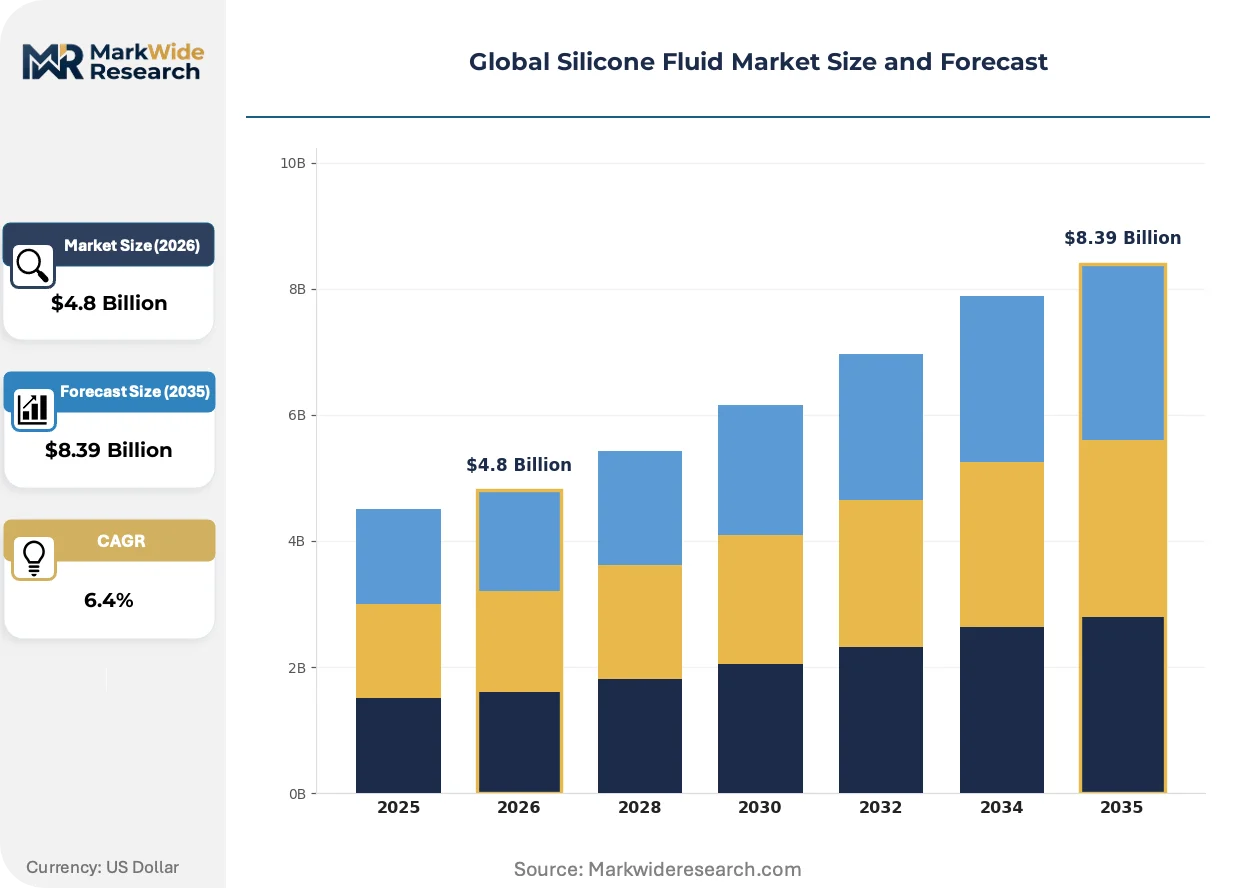
Market Dynamics
The central structural force in the silicone fluid market is the geographic rebalancing of production. A surge in Chinese capacity additions is fragmenting a supply base historically dominated by producers in Germany, Japan, and the United States.
Growth Catalysts
- Electric Vehicle Thermal Management:The transition to electric vehicles creates substantial new demand for dielectric silicone fluids for battery cooling and powertrain lubrication, necessitating materials with high thermal stability and electrical resistivity.
- Advanced Personal Care Formulations:Consumer demand for cosmetics and skincare with enhanced sensory feel and long-wear properties drives consumption of specialized amino and phenyl silicone fluids in premium product lines.
- China's Industrial Policy:National industrial expansion in electronics, automotive, and construction manufacturing within China provides a massive, localized demand base for both commodity and specialty grade silicone fluids.
Market Restraints
- Raw Material Volatility:The cost of silicone fluids is directly linked to the price of silicon metal and methanol, key precursors whose markets are subject to energy costs and global supply chain disruptions.
- Regulatory Scrutiny:The European Union's REACH regulation and the US EPA's TSCA framework impose restrictions on specific siloxanes, particularly cyclic variants, increasing compliance costs and formulation complexity.
- Substitution in Low-End Applications:In less demanding applications like basic mold release agents or lubricants, mineral oils or other synthetic fluids can offer a lower-cost alternative, capping price potential for commodity grades.
Strategic Opportunities
- Biocompatible Medical Fluids:Development of high-purity, low-volatility silicone fluids for use as lubricants in medical devices and as fluids in prosthetic components represents a high-margin growth vector.
- Bio-Based Silicone Precursors:Research into deriving siloxane precursors from biological sources or through greener chemical pathways offers a path to reduce carbon footprint and appeal to sustainability-focused customers.
- Southeast Asian Electronics Hubs:As electronics and semiconductor manufacturing expands in countries like Vietnam and Malaysia, there is an opportunity to establish localized supply and technical support for specialized fluids.
Industry Challenges
- Divergent Chemical Regulations:Manufacturers face significant operational hurdles in managing product portfolios that must comply with a patchwork of conflicting international chemical control laws, hindering global product launches.
- Capital for Purity Upgrades:Achieving the purity levels required for electronics and medical applications necessitates substantial capital investment in advanced distillation and filtration equipment for production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Silicone Fluid Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dimethyl Silicone Fluid, Phenyl Silicone Fluid, Amino Silicone Fluid, Chloropropyl Silicone Fluid, Others Application: Personal Care, Automotive OEMs, Textile Processing, Paints & Coatings, Electrical Insulation End User Industry: Consumer Goods Manufacturers, Vehicle Assemblers, Fabric Mills, Coating Producers, Electronics Manufacturers Form: Liquid, Emulsion, Microemulsion, Gel |
| Companies Covered | Momentive Performance Materials, KCC Corporation, Dow Inc., Evonik Industries AG, BRB International BV, Wacker Chemie AG, Elkem ASA, Siltech Corporation, Shin-Etsu Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Silicone Fluid Market Strategic Shifts & Innovations
The evolution from commodity-centric supply to application-specific, high-performance formulations defines current market development. This shift is driven by technical imperatives in advanced manufacturing and evolving regulatory standards for consumer and environmental safety.
Formulation science is advancing toward functional fluids that incorporate sensing or responsive properties. These materials can change viscosity, thermal conductivity, or other characteristics in response to external stimuli like temperature or an electric field. Adoption is gaining traction in high-value industrial sectors, such as aerospace and robotics, for adaptive hydraulic and damping systems. This innovation is digitizing the role of the fluid from a passive medium to an active component within a larger mechanical or electronic system.
European chemical policy creates significant reformulation pressure across the industry. The EU's REACH regulation, specifically its restrictions on certain cyclic siloxanes like D4 and D5, directly impacts product composition. Formulators in the personal care sector are most affected, compelled to engineer new cosmetic and skincare products using alternative, compliant silicone polymers or entirely different chemistry platforms to maintain market access in Europe.
Buyer behavior is moving away from bulk, long-term contracts for commodity grades toward more flexible, specification-driven purchasing for specialized fluids. This change disrupts traditional distribution channels that rely on large-volume logistics. The trend is most visible in the North American and European medical device and semiconductor industries, where R&D cycles demand smaller, iterative orders of highly specific, certified materials.
Global Silicone Fluid Market Segmentation
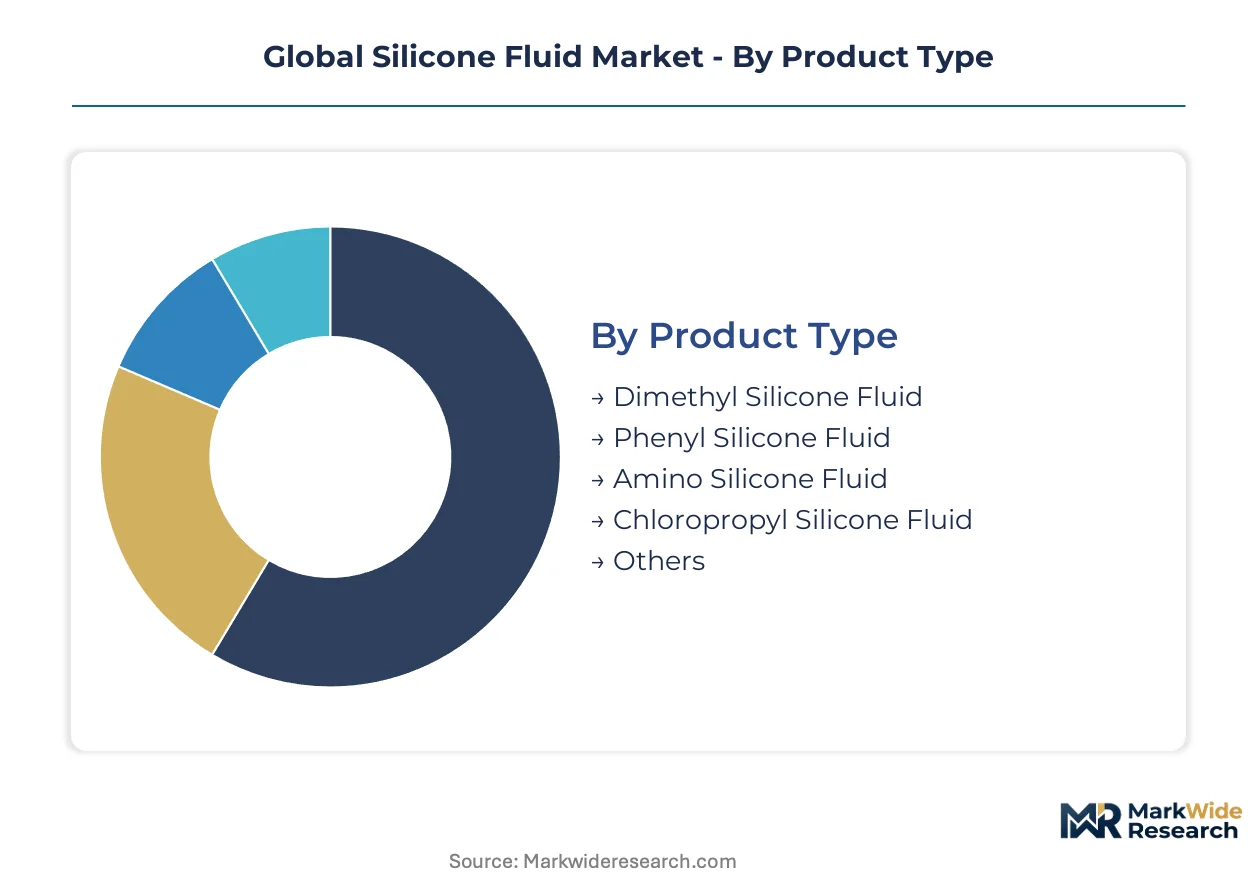
Understanding the varied applications and chemical compositions of silicone fluids is critical for market participants. Segmentation reveals where value creation concentrates and how different product forms address specific industrial and consumer needs across diverse geographic markets.
Product Type:
The use-case spectrum for silicone fluids ranges from high-volume industrial applications to highly specialized, high-purity formulations.
- Dimethyl Silicone Fluid:This linear polydimethylsiloxane polymer offers excellent thermal stability, low surface tension, and good dielectric properties, making it a versatile base fluid. Demand concentrates in lubricants and hydraulic fluids for general industrial machinery and automotive applications in China.
- Amino Silicone Fluid:Characterized by reactive amino groups, these fluids provide superior conditioning and softness to textiles and hair. Demand is strong in advanced personal care formulations in Europe and premium textile finishing in Southeast Asia, driven by consumer preference for enhanced sensory feel.
- Phenyl Silicone Fluid:These fluids incorporate phenyl groups, enhancing thermal stability, radiation resistance, and refractive index, making them suitable for optical and high-temperature applications.
- Chloropropyl Silicone Fluid: Featuring chloropropyl groups, these fluids offer improved compatibility with organic materials and enhanced lubricity, finding use in specialty release agents and coatings.
- Others: This category includes various specialty fluids such as alkyl, fluoro, and epoxy-modified silicones, designed for niche applications requiring specific chemical resistances or functional properties.
The dominant share belongs to Dimethyl Silicone Fluid, while Amino Silicone Fluid is closing the gap fastest.
Application:
Margin differentiation across application segments reflects the varying performance requirements and regulatory hurdles for silicone fluids.
- Personal Care:Silicone fluids provide unique sensory attributes, long-lasting effects, and improved spreadability in cosmetics, skincare, and hair care products. Consumption is high in Europe and North America, driven by evolving consumer preferences and innovative product development.
- Automotive OEMs:These fluids serve as thermal management solutions for electric vehicle batteries, lubricants for powertrain components, and damping fluids in vehicle systems. Demand is accelerating in Germany and China, propelled by the global transition to electric mobility.
- Textile Processing:Silicone fluids enhance fabric softness, water repellency, and wrinkle resistance in textile finishing processes.
- Paints & Coatings: Used as additives, silicone fluids improve flow, leveling, and scratch resistance in various paint and coating formulations.
- Electrical Insulation: These fluids provide excellent dielectric properties and thermal stability for insulating transformers, cables, and electronic components.
Personal Care and Automotive OEMs represent the most strategically important segments for future growth initiatives.
End User Industry:
Volume consumption patterns for silicone fluids are heavily influenced by the scale and technological advancement of end-user manufacturing sectors.
- Consumer Goods Manufacturers:This segment utilizes silicone fluids extensively in personal care products, household cleaners, and other consumer formulations. This segment's demand is broadly distributed across major economies like the United States and Japan.
- Electronics Manufacturers:Silicone fluids are crucial for thermal management, encapsulation, and dielectric insulation in semiconductor devices and electronic assemblies. China's expansive electronics manufacturing base drives significant localized demand.
- Vehicle Assemblers:This industry integrates silicone fluids into various automotive components, including braking systems, airbags, and engine parts.
- Fabric Mills: Textile production facilities use silicone fluids for finishing treatments that impart desired properties to fabrics.
- Coating Producers: Manufacturers of paints, varnishes, and protective coatings incorporate silicone fluids to enhance product performance.
The industrial expansion within China's Electronics Manufacturers and Vehicle Assemblers is significantly impacting demand dynamics.
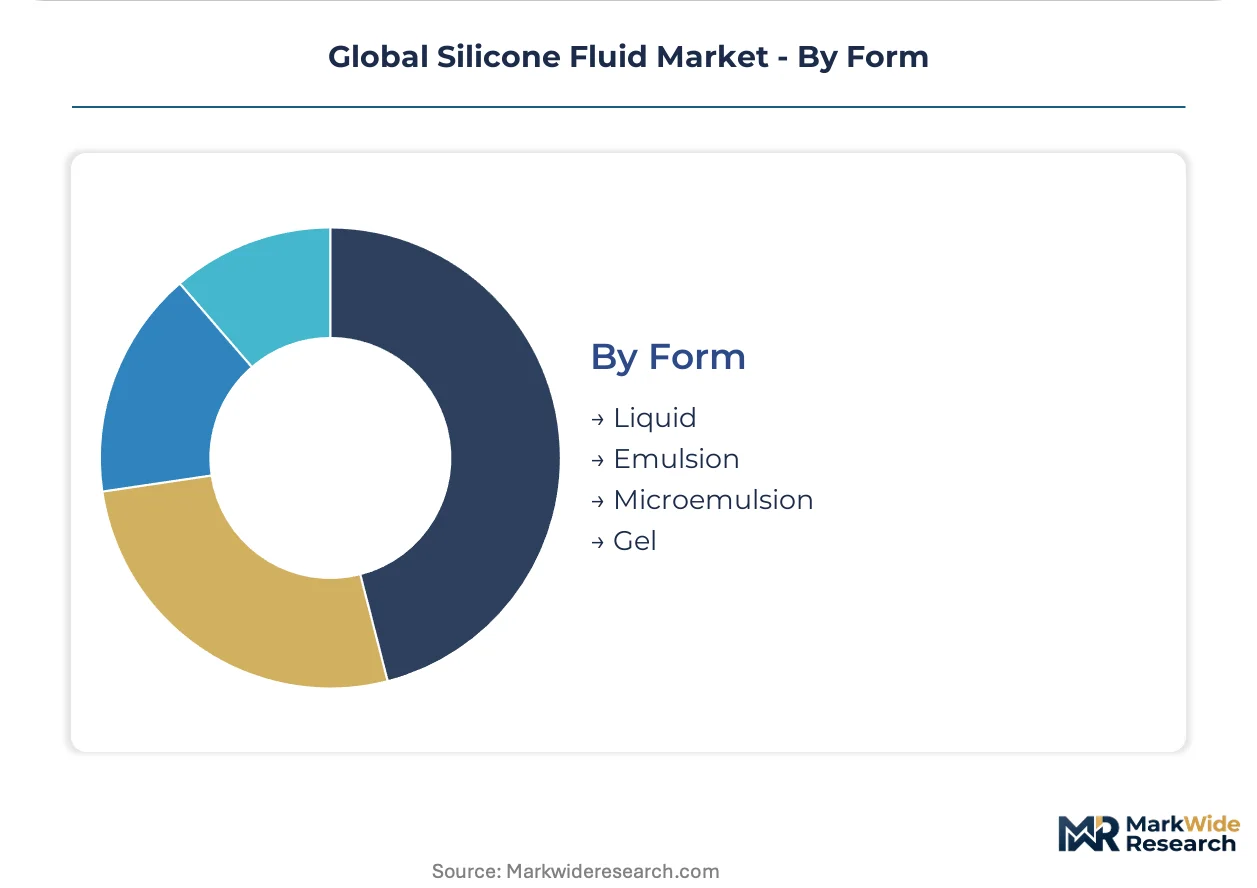
Form:
Delivery mechanism versatility allows silicone fluids to integrate into a wide array of manufacturing processes and product formulations.
- Liquid:This primary form of silicone fluid is used directly as a lubricant, hydraulic fluid, or base for various formulations. Its ease of handling and broad compatibility make it ubiquitous across industrial sectors.
- Emulsion:Silicone emulsions consist of silicone fluids dispersed in a water base, offering easier application and compatibility with water-based systems, especially in personal care and textile processing. These are widely adopted in Europe for water-based cosmetic products.
- Microemulsion:These are thermodynamically stable, transparent dispersions of silicone fluids in water, offering enhanced penetration and film formation for specific applications.
- Gel: Silicone gels provide a soft, tacky, or non-tacky consistency, often used in medical devices, scar treatment, and specialty cosmetic applications.
The market is seeing a shift towards more specialized forms like Emulsion as formulation requirements evolve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Chinese Ministry of Ecology and Environment (MEE) regulations influence the global silicone fluid market, particularly as production capacity shifts. This rebalancing impacts supply chains for both commodity and specialty grades. China's industrial expansion fuels significant localized demand.
China
China's expansive electronics manufacturing and automotive production drive substantial localized demand for silicone fluids. National industrial policies, including GB standards, support domestic production and application development. The Yangtze River Delta region, a hub for electronics and vehicle assemblers, sees concentrated consumption of both commodity and specialty fluids.
United States
The United States market sees strong demand from consumer goods manufacturers and the electronics sector. US EPA's oversight under the Toxic Substances Control Act (TSCA) influences formulation choices for consumer-facing products. Silicon Valley's semiconductor manufacturing requires specialized, high-purity silicone fluids for advanced processes.
Germany
Germany's automotive OEMs, particularly in electric vehicle thermal management, represent a significant demand segment. The European Union's REACH regulation imposes stringent restrictions on certain siloxanes, driving reformulation efforts. Bavaria, with its strong automotive and chemical industries, maintains a robust demand for high-performance silicone fluids.
Japan
Japan's advanced semiconductor manufacturing processes and sophisticated personal care formulations create demand for specialized silicone fluids. The Ministry of Economy, Trade and Industry (METI) promotes innovation and compliance within the chemical industry. Kyushu, known as "Silicon Island," remains a key region for semiconductor fabrication requiring ultra-high purity materials.
France
French demand for silicone fluids is driven by its premium personal care sector and specialized aerospace applications. Compliance with the European Union's REACH regulation is a critical factor for market access and product development. Cosmetic Valley, a prominent cluster for beauty product innovation, actively seeks compliant and high-performance silicone fluid solutions.
Global Silicone Fluid Market Key Industry Players
Established multinational chemical conglomerates and emerging regional specialists split the market for silicone fluids. The market exhibits a tiered structure, with high-volume commodity grades contrasting with niche, high-purity formulations. New production capacity in China is fragmenting the traditional supply base, while established players focus on portfolio diversification. Strategic partnerships and targeted capacity expansion remain key competitive moves.
Within the established multinational segment, Dow Inc., a US-based chemical giant, leverages its vast scale in basic chemical production for commodity grades. Germany's Wacker Chemie AG exemplifies a focus on high-purity fluids, serving demanding medical and electronics applications. Shin-Etsu Chemical Co., Ltd., a Japanese corporation, occupies a dominant position in specialized fluids for advanced semiconductor manufacturing processes. These companies continuously adapt product chemistry to navigate international chemical control laws.
| Leading Market Players |
|---|
| Momentive Performance Materials |
| KCC Corporation |
| Dow Inc. |
| Evonik Industries AG |
| BRB International BV |
| Wacker Chemie AG |
| Elkem ASA |
| Siltech Corporation |
| Shin-Etsu Chemical Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Raw material volatility, specifically for silicon metal and methanol, determines both pricing tier spreads and the supply chain shape for silicone fluids. This commodity price sensitivity impacts margins across all product grades.
Pricing Analysis
Geographic price-spreads exist, with lower commodity-grade pricing in China due to new production capacity. The dominant pricing model for commodity grades is contract-based long-term offtake, while specialty fluids often use a value-based or project-based approach. Price differentiation stems from purity levels required for specific applications and the cost of regional delivery. Pricing softness is evident in commodity segments due to oversupply in Asia. Consumer goods manufacturers are highly price-sensitive for basic formulations, whereas electronics and medical device manufacturers prioritize performance and certification, exhibiting lower price sensitivity.
Supply Chain Analysis
Regulatory restrictions, particularly the EU's REACH regulation and US EPA's TSCA framework, limit the flow of certain siloxanes, impacting global supply. Geographic supply concentration for basic silicone fluids centers on China, with specialized production hubs in Germany and Japan. The industry relies on silicon metal and methanol as key precursors. A structural risk involves the potential for logistics chokepoints, especially for high-purity materials requiring specialized handling. Downstream distribution runs through a mix of direct sales to large OEMs and a network of specialized chemical distributors for smaller formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a cyclical recovery, driven by the global transition to electric vehicles and renewed investment in advanced electronics manufacturing.
For Market Incumbents: Entrench market position by investing in advanced purification technologies for high-purity fluids, countering the margin pressure from new Chinese entrants in commodity grades. Consolidate R&D efforts on bio-based silicone precursors to address evolving sustainability demands and regulatory shifts. Expand technical support infrastructure in emerging electronics hubs like Southeast Asia to maintain customer loyalty against regional specialists.
For New Entrants and Emerging Players: Build out niche capabilities in specialized fluid formulations for high-growth, high-margin applications. The most penetrable segment is advanced personal care, driven by demand for specialized amino and phenyl silicone fluids. Focus on developing compliant, high-performance alternatives to restricted cyclic siloxanes. A successful go-to-market angle involves offering tailored solutions with rapid prototyping and certification support for specific customer needs.
For Investors and Strategic Acquirers: Mid-sized specialty chemical firms with proprietary high-purity fluid technologies represent attractive acquisition targets. The long-term viability of the silicone fluid market is strong, supported by its indispensable role in electronics, automotive, and personal care. A signal to watch is the pace of regulatory harmonization or divergence, which will indicate future market access and reformulation costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for High-Purity Fluids | Increases supply of critical materials for medical and electronics applications, securing market share. |
| Green Manufacturing Transition | Reduces carbon footprint and appeals to sustainability-focused customers and regulatory bodies. |
| Long-term Supply Agreements with EV OEMs | Secures demand for thermal management fluids, leveraging electric vehicle growth. |
| Joint Venture in Southeast Asian Electronics Hubs | Establishes localized production and technical support for regional electronics manufacturers. |
| Investment in Bio-Based Silicone Precursor R&D | Addresses future regulatory requirements and consumer demand for sustainable chemical inputs. |
Research Approach
Initial hypotheses were tested against primary input from plant managers, procurement leads at downstream OEMs, distribution channel partners, and technical R&D directors, then refined through iterative analysis. Secondary validation involved reviewing customs and trade data, chemical industry association reports, and SEC 10-K filings from major chemical producers. This approach utilized both bottom-up market sizing and top-down validation for comprehensive insights.
Demand-supply-balance framing informed the quantitative modeling across the analysis window, projecting market volume and value. Segmentation dimensions modeled included product type, application, end-user industry, and form, alongside regional regulatory clusters. Compound annual growth rates were derived from historical data trends and projected demand drivers. Key industry-specific forecast inputs included electric vehicle production forecasts and semiconductor manufacturing capacity expansions.
Practitioners should monitor significant shifts in raw material costs, new regulatory mandates, or major technological breakthroughs for early signals of market change. Forecasts reflect assumptions documented at the time of publication. Material shifts in global economic growth or sustained supply chain disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Surface Treatment Chemicals Market
Industrial Chemicals
Thermally Stable Antiscalant Market
Industrial Chemicals
Dimethylacetamide (Dmac) Market
Industrial Chemicals
India Thermic Fluid Market
Industrial Chemicals
Fluorine-Based Plasma Surface Treatment Machine for Leather Market
Industrial Chemicals
Detergent Making Machinery Market
Industrial Chemicals
Chemical Process Mixers Market
Industrial Chemicals
Naphthenic Acid Market
Industrial Chemicals
Indonesia Construction Chemicals Market
Industrial Chemicals
Drag Reducing Agents Market
Industrial Chemicals
Lithium Hexafluorophosphate Market
Industrial Chemicals
Global Electronic Grade Sulfuric Acid Market
Industrial Chemicals
Global Lignosulfonate Based Concrete Admixtures Market
Industrial Chemicals
Aerosol Sprayers Market
Industrial Chemicals
Global Flow Chemistry Market
Industrial Chemicals
Molecular Sieve for Air Separation Market