
 Aerosol Sprayers Market | 2026-2036
Aerosol Sprayers Market Size, Share, and Industry Trends Forecast 2026-2036
Aerosol Sprayers Market Outlook
Automotive refinishing is shifting toward precision aerosol systems as collision repair networks standardize color-matched touch-up protocols. Ball Corporation leverages its aluminum can manufacturing scale to supply lightweight, corrosion-resistant aerosol containers to industrial coating lines. Crown anchors North American supply through integrated metal packaging operations that sustain long-term contracts with automotive chemical formulators. Coster Tecnologie Speciali specializes in metered-dose valve engineering, differentiating its portfolio through propellant compatibility across hydrocarbon and compressed-gas platforms.
Aerosol sprayers are pressurized dispensing systems comprising a container, propellant, valve, and actuator that deliver liquids, foams, or powders as controlled spray patterns; typical operating pressures range from 2 to 8 bar depending on propellant type and product viscosity, with aluminum and tinplate cans dominating structural applications due to their collapse resistance and barrier properties. The product-type dimension shows valves capturing concentrated margin pools because precision metering technology commands premium positioning in pharmaceutical and personal care segments. Material-grade segmentation reveals metal cans leading volume while plastic alternatives accelerate in household applications where weight reduction and dent resistance outweigh barrier requirements.
The EPA regulates volatile organic compound emissions under 40 CFR Part 59, restricting propellant formulations and mandating reformulation timelines for domestic manufacturers. REACH compliance in Europe governs substance registration and restricts candidate chemicals in aerosol formulations, forcing suppliers to maintain dual formulation portfolios for transatlantic markets. ECHA's ongoing substance evaluation cycles will determine which propellant chemistries retain market access, compelling stakeholders to monitor regulatory divergence between US and European frameworks as they allocate R&D budgets and qualify alternative delivery systems.
Market Dynamics
REACH and EU F-Gas Regulation compliance requirements are redirecting procurement toward low-VOC propellant systems, forcing European manufacturing bases to requalify their entire aerosol formulation portfolios and supplier relationships.
Growth Catalysts
- Automotive collision repair networks:Standardized color-matched touch-up protocols are expanding aerosol touch-up programs across certified body shop chains, creating pull-through demand for precision valve systems.
- REACH substance registration:Chemical registration and evaluation frameworks are consolidating supplier bases toward compliant formulators with pre-qualified dossiers, advantaging incumbents with regulatory infrastructure.
- Compressed gas propellant platforms:Hydrocarbon alternatives are gaining traction in pharmaceutical and personal care metering applications where dose precision requirements exceed mechanical pump capabilities.
Market Restraints
- Aluminum sheet supply concentration:Container manufacturing depends on narrow rolling mill capacity in select geographies, exposing can makers to input volatility and long lead times for specialty alloy grades.
- Valve engineering complexity:Metered-dose precision requires specialized elastomer compatibility testing across propellant chemistries, extending qualification timelines and freezing out smaller formulators.
- Substitution by trigger sprayers:Non-pressurized mechanical alternatives are capturing household and industrial cleaning applications where barrier properties matter less than cost and dent resistance.
Strategic Opportunities
- India personal care penetration:Deodorant and dry shampoo aerosol adoption in tier-2 cities remains below saturation, offering volume expansion for brands with localized formulation and distribution.
- EU Green Deal propellant mandates:Biogenic and recycled-content propellant incentives are creating first-mover advantage windows for suppliers with certified low-carbon chemistries.
- E-commerce direct-to-consumer channels:Subscription refill models for household aerosol products are bypassing traditional retail shelf-space constraints and building recurring revenue streams.
Industry Challenges
- Propellant chemist scarcity:Formulation expertise in compressed gas and hydrocarbon blend optimization is concentrating at a handful of specialized consultancies, inflating R&D labor costs.
- Dual-portfolio compliance overhead:Maintaining separate US EPA 40 CFR Part 59 and REACH-compliant formulations is fragmenting production runs and complicating inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerosol Sprayers Market |
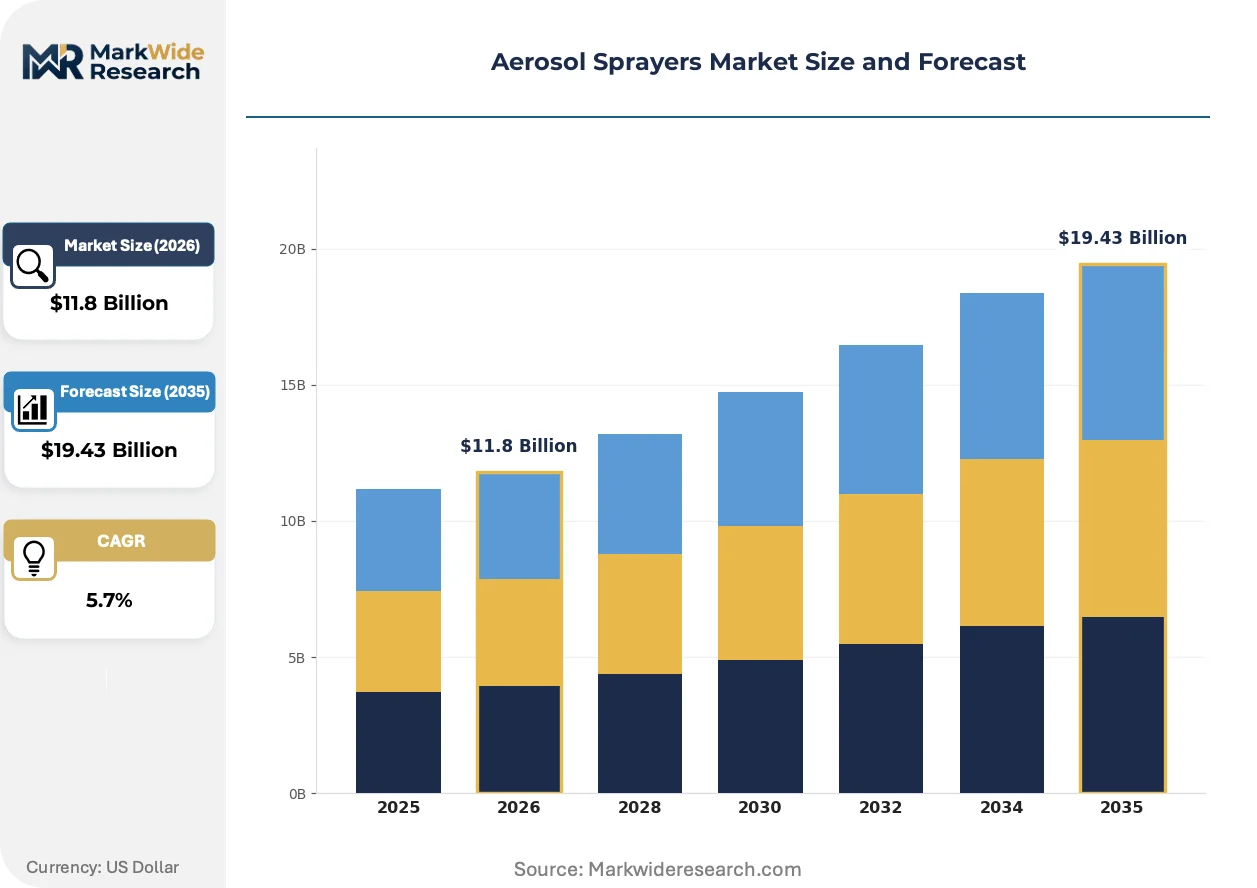
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $19.43 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pumps, Valves, Nozzles, Cans Application: Personal Care, Household, Automotive, Industrial Material: Plastic, Metal, Glass, Others Distribution Channel: Online, Offline, Retail Stores, Wholesale |
| Companies Covered | AptarGroup, Ball Corporation, Crown, Ardagh Group, Coster Tecnologie Speciali, Lindal, Silgan Holdings, Albéa Group, Rieke Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerosol Sprayers Market Strategic Shifts
Propellant chemistry and container engineering are converging to address barrier performance and environmental compliance simultaneously, with compressed gas systems and aluminum container innovations commanding disproportionate R&D investment.
Compressed gas propellant systems are overtaking hydrocarbon alternatives in pharmaceutical and food-grade applications where flammability restrictions and VOC thresholds are tightening. Metered-dose inhaler manufacturers and specialty food spray formulators are accelerating adoption. This shift is compressing the addressable market for traditional liquefied gas propellants in high-specification segments.
EU F-Gas Regulation phase-down schedules are forcing reformulation of HFC-based propellant blends before 2030 deadlines. Aerosol manufacturers serving European personal care and industrial markets are qualifying hydrofluoroolefin and hydrocarbon alternatives. Germany-based automotive OEM supplier parks are experiencing the most concentrated qualification activity due to coating and sealing application volumes.
Refillable aerosol systems with user-rechargeable compressed gas canisters are disrupting single-use can economics in professional cleaning and automotive detailing segments. Distributor and janitorial supply channels are piloting closed-loop container programs. This pattern is most visible in Netherlands and Scandinavian markets where extended producer responsibility frameworks have normalized deposit-return infrastructure.
Aerosol Sprayers Market Segmentation
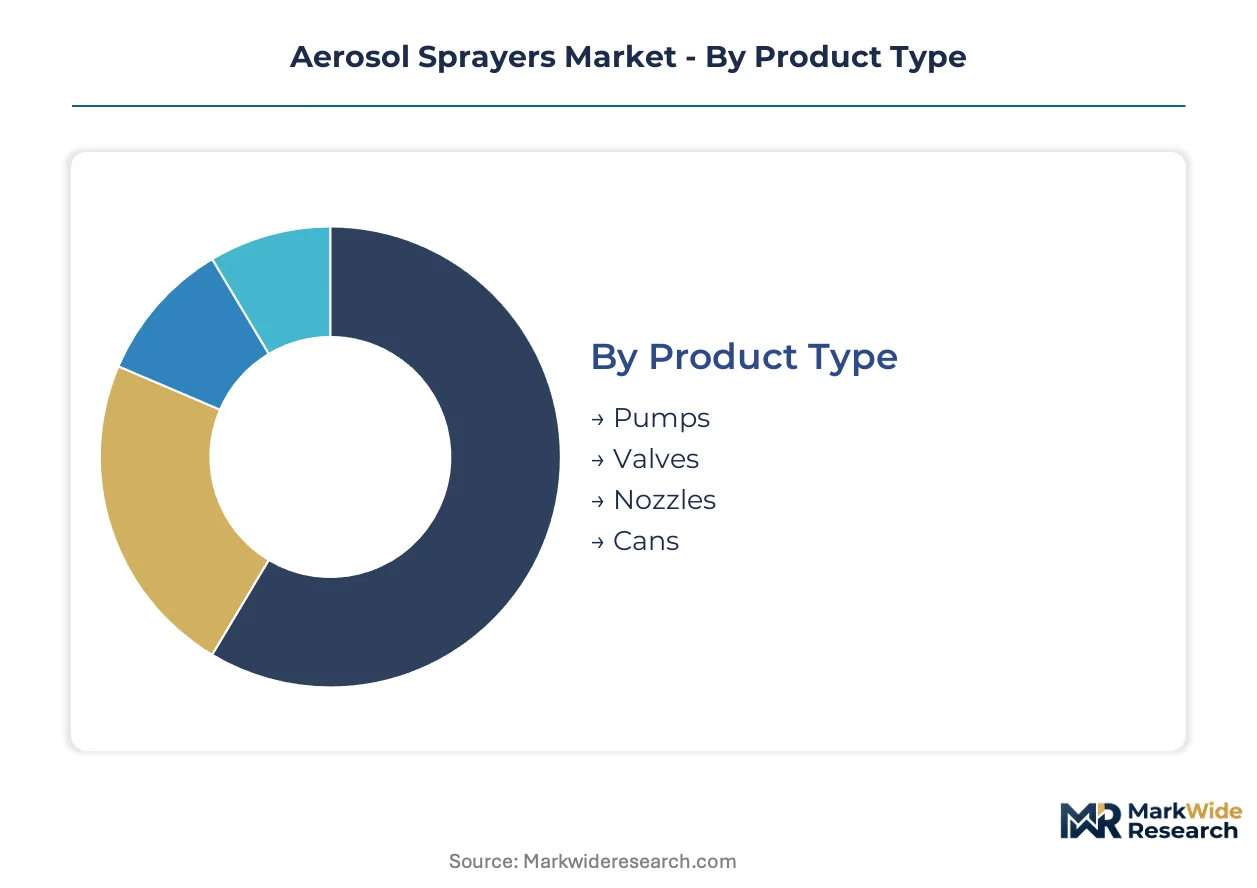
Aerosol sprayer segmentation reveals how component specialization, material science, and channel economics fragment procurement decisions across end-use verticals. Technical specifications in valve engineering and propellant compatibility create divergent margin structures that reshape competitive positioning.
Product Type:
Precision metering technology defines competitive differentiation across pressurized dispensing components.
- Valves:Metered-dose and continuous-spray valve architectures command concentrated margin pools in pharmaceutical and automotive refinishing applications. Coster Tecnologie Speciali dominates precision engineering for hydrocarbon and compressed-gas propellant compatibility. REACH substance evaluation cycles are forcing extended qualification timelines that freeze out smaller formulators.
- Cans:Aluminum and tinplate containers provide collapse resistance and barrier properties for industrial coating lines. Ball Corporation leverages rolling mill scale to supply lightweight corrosion-resistant formats. Supply concentration in narrow specialty alloy grades exposes manufacturers to input volatility and extended lead times.
- Pumps:Mechanical pressurization systems serve non-aerosol alternatives in household cleaning where cost sensitivity outweighs barrier requirements.
- Nozzles:Actuator designs determine spray pattern precision for touch-up protocols in collision repair networks.
Mature deployment sits with Cans. Newer deployment is concentrated in Valves as precision dosing requirements expand beyond traditional pharmaceutical into food-grade and industrial segments.
Application:
End-use concentration patterns reflect regulatory stringency and formulation complexity thresholds.
- Automotive:Collision repair networks are standardizing color-matched touch-up protocols that pull through demand for precision valve systems. Germany-based OEM supplier parks concentrate coating and sealing application volumes. EU F-Gas Regulation phase-down schedules are accelerating HFC alternative qualification timelines.
- Personal Care:Deodorant and dry shampoo adoption in tier-2 Indian cities remains below saturation, offering volume expansion for localized formulation strategies. Compressed gas propellant platforms are gaining traction where dose precision exceeds mechanical pump capabilities.
- Household:Trigger sprayer substitution is capturing cleaning applications where barrier properties matter less than cost and dent resistance.
- Industrial:Protective coating and lubricant dispensing requires corrosion-resistant container formats for aggressive chemical environments.
Volume leadership resides with Personal Care. Steepest expansion trajectory is emerging in Automotive as certified body shop chains proliferate aerosol touch-up programs.
Material:
Barrier performance requirements and weight reduction imperatives drive material selection across application tiers.
- Metal:Aluminum and tinplate cans dominate structural applications requiring collapse resistance and chemical barrier properties. Crown anchors North American supply through integrated metal packaging operations sustaining long-term automotive chemical contracts.
- Plastic:PET and engineered polymer alternatives accelerate in household segments where weight reduction and dent resistance outweigh barrier requirements. Refillable compressed gas systems are disrupting single-use economics in professional cleaning segments.
- Glass:Limited penetration in specialty pharmaceutical and cosmetic applications requiring inert contact surfaces.
- Others:Composite and biodegradable formats remain experimental for extended producer responsibility compliance in Netherlands and Scandinavian markets.
Revenue concentration favors Metal. Technology investment is concentrating in Plastic as closed-loop container programs normalize deposit-return infrastructure.
Distribution Channel:
Channel economics fragment between bulk industrial procurement and direct-to-consumer subscription models.
- Online:E-commerce direct-to-consumer channels are bypassing traditional retail shelf-space constraints for household aerosol products. Subscription refill models are building recurring revenue streams in janitorial supply segments.
- Wholesale:Industrial coating and automotive chemical formulators procure through distributor networks sustaining long-term contract structures.
- Retail Stores:Mass merchandising dominates personal care volume with localized assortment strategies for tier-2 city penetration.
- Offline:Traditional trade remains significant in emerging markets with underdeveloped logistics infrastructure.
Margin capture concentrates in Online. Operational scale sits with Wholesale serving dense automotive supplier parks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Bavaria and supplier parks around Stuttgart concentrate European aerosol sprayer procurement for automotive coating applications.
Germany
Automotive OEM supplier parks in Baden-Württemberg and Lower Saxony drive concentrated demand for precision valve systems in coating and sealing operations. EU F-Gas Regulation phase-down schedules under ECHA oversight are accelerating HFC alternative qualification timelines before 2030. Stuttgart's dense automotive chemical cluster hosts the most active reformulation activity for low-VOC propellant systems.
United States
Collision repair network expansion across Texas and California is standardizing color-matched aerosol touch-up protocols. EPA 40 CFR Part 59 restricts volatile organic compound emissions and mandates specific reformulation timelines for domestic manufacturers. Michigan's automotive chemical corridor sustains long-term contracts between metal packaging suppliers and industrial coating formulators.
India
Deodorant and dry shampoo aerosol penetration in tier-2 cities across Maharashtra and Gujarat remains below saturation thresholds. BIS certification requirements and DGFT import regulations shape localized formulation strategies for personal care brands. Mumbai-Pune industrial belt concentrates contract manufacturing capacity for multinational aerosol brands seeking regional production.
China
Personal care and household aerosol production clusters in Guangdong and Jiangsu provinces serve domestic consumption and export markets. NMPA and MIIT standards govern propellant safety and container integrity for pharmaceutical and food-grade applications. Yangtze River Delta manufacturing bases are qualifying compressed gas alternatives to hydrocarbon propellants under dual carbon policy frameworks.
Netherlands
Professional cleaning and automotive detailing segments are piloting refillable aerosol systems with user-rechargeable compressed gas canisters. Extended producer responsibility frameworks under EU Green Deal implementation have normalized deposit-return infrastructure. Rotterdam-Amsterdam logistics corridor supports closed-loop container programs linking distributor networks with janitorial supply channels.
Aerosol Sprayers Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated metal packaging groups dominating industrial procurement while precision valve engineers capture pharmaceutical margins. The vendor base concentrates around three strategic archetypes: aluminum can fabricators with rolling mill scale, metered-dose valve specialists with elastomer chemistry expertise, and diversified packaging conglomerates with cross-sector formulation relationships. Capacity expansion and strategic partnerships represent the dominant competitive moves, particularly around low-VOC propellant qualification and refillable system development.
Among North American metal packaging groups, Ball Corporation and Crown exemplify scale-driven container supply positions, while Coster Tecnologie Speciali occupies the precision engineering tier for hydrocarbon and compressed-gas valve compatibility. These three anchors illustrate how technical specialization and manufacturing scale create divergent margin structures across automotive, pharmaceutical, and personal care end-use verticals.
| Leading Market Players |
|---|
| AptarGroup |
| Ball Corporation |
| Crown |
| Ardagh Group |
| Coster Tecnologie Speciali |
| Lindal |
| Silgan Holdings |
| Albéa Group |
| Rieke Packaging |
| Others |
Value Chain & Pricing Dynamics
REACH-mandated propellant reformulation is forcing European automotive OEMs to requalify supplier relationships, compressing procurement timelines and inflating premiums for pre-certified valve systems with validated low-VOC compatibility dossiers.
Pricing Analysis
Short lead-time premiums now separate qualified suppliers from spot-market alternatives in aluminum can procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with Ball Corporation and Crown commanding top-tier positioning through long-term automotive contracts. Cost compression in mid-tier valve sourcing is intensifying because REACH substance evaluation cycles are freezing out smaller formulators. Household cleaning segments exhibit highest price sensitivity, while pharmaceutical metered-dose applications show least elasticity due to dose precision requirements.
Supply Chain Analysis
Dual-sourcing mandates from German automotive OEMs require valve suppliers to maintain parallel qualification tracks with at least two elastomer compounders. Manufacturing concentrates in Germany, the United States, and China, with raw material flows drawing from specialty aluminum rolling mills in Russia and Kazakhstan and precision elastomer feedstocks from Japan. Single-source vulnerability sits with narrow specialty alloy grades for corrosion-resistant cans. Distribution runs through certified body shop networks and janitorial supply channels rather than mass retail for industrial volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as can makers pursue captive valve engineering capabilities to capture margin pools currently concentrated at Coster Tecnologie Speciali and Lindal.
For Market Incumbents: Anchor market position through backward integration into precision elastomer compounding for metered-dose applications, insulating against propellant chemist scarcity. Defend automotive share by locking in multi-year coating line contracts with Stuttgart-area OEM supplier parks before HFC alternative qualification deadlines pass. Prioritize certification investment in EU F-Gas Regulation-compliant propellant platforms to freeze out reformulation-lagged competitors. For New Entrants and Emerging Players: EU F-Gas Regulation in Germany opens a window for hydrofluoroolefin propellant specialists to capture share from incumbents burdened by legacy HFC inventory. Target tier-2 Indian cities for deodorant and dry shampoo contract manufacturing, where BIS certification barriers are lower than multinational brand entry costs. Pursue direct-to-consumer subscription refill models in Netherlands and Scandinavian markets, leveraging existing deposit-return infrastructure to bypass retail shelf-space constraints. For Investors and Strategic Acquirers: The window for entry favors mid-cap valve engineers with compressed-gas platform expertise and pre-qualified REACH dossiers. Long-term viability hinges on propellant chemistry flexibility across hydrocarbon, HFO, and compressed-gas alternatives. Watch ECHA substance evaluation cycle announcements as the inflection signal for which propellant chemistries retain market access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Elastomer Compounding | Captures margin pools currently concentrated at Japanese specialty chemical suppliers serving Coster Tecnologie Speciali. |
| EU F-Gas Regulation Compliance Program | Qualifies HFO and compressed-gas alternatives before 2030 phase-down deadlines in Stuttgart supplier parks. |
| India Contract Manufacturing Scale-Up | Localizes production for deodorant and dry shampoo brands seeking BIS-certified supply in Maharashtra and Gujarat. |
| Refillable System Pilot Launch | Tests user-rechargeable compressed gas canisters in Netherlands janitorial channels with established deposit-return infrastructure. |
| Automotive Collision Repair Network Partnership | Locks in long-term valve supply contracts with certified body shop chains standardizing color-matched touch-up protocols. |
Study Parameters
Multi-period observation of propellant qualification timelines, REACH dossier submission rates, and automotive coating line procurement patterns anchored the trend analysis, supplemented by interviews with valve engineering directors, aluminum can plant managers, automotive chemical formulators, and extended producer responsibility framework administrators. Secondary validation drew from ECHA substance evaluation databases, EPA 40 CFR Part 59 regulatory filings, BIS certification registries, and customs trade data for specialty aluminum alloy grades. Bottom-up segment sizing triangulated against top-down market consolidation estimates.
Input-output matrices mapped valve, can, and propellant component flows across end-use verticals, with segmentation dimensions covering product architecture, material grade, application intensity, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion announcements across the analysis window. Industry-specific forecast inputs included collision repair network penetration rates and EU F-Gas Regulation phase-down compliance schedules.
The model assumes a particular technology adoption path; alternative pathways for compressed gas propellant platforms would alter the outlook if hydrocarbon blends retain regulatory tolerance longer than projected. Deviation in ECHA substance evaluation cycle timing or EPA reformulation mandate enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Methyl Isobutyl Carbinol Market
Industrial Chemicals
Adblue Market
Industrial Chemicals
Ferrocene Market
Industrial Chemicals
Dipropylene Glycol (DPG) Market
Industrial Chemicals
Rotomolding Powder Market
Industrial Chemicals
Europe Bitumen Market
Industrial Chemicals
Ceramic Corona Discharge Ozone Generator Market
Industrial Chemicals
Europe Hydrocarbon Refrigerants Market
Industrial Chemicals
North America Paper Machine Oil Market
Industrial Chemicals
Backing Material Market
Industrial Chemicals
Bio Derived Enzymes for Detergents Market
Industrial Chemicals
Ethyl Acrylate Market
Industrial Chemicals
Welding Electrodes Market
Industrial Chemicals
Screw Separators Market
Industrial Chemicals
South America Starch Derivatives Market
Industrial Chemicals
Europe Antifreeze Coolant Market