
 Drag Reducing Agents Market | 2026-2036
Drag Reducing Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Drag Reducing Agents Market Analysis
A shortage of petroleum chemists with polymer synthesis expertise is reorganizing how drag reducing agent suppliers staff technical service teams. Innospec Inc. leverages its integrated surfactant manufacturing to secure long-term supply agreements with midstream operators. Baker Hughes Company anchors its position through deep relationships with national oil companies in the Middle East and Latin America.
Drag reducing agents are long-chain polymer or surfactant additives that suppress turbulent flow in pipelines, typically reducing frictional pressure loss by 40-80% at concentrations below 50 ppm. Polymeric formulations dominate current volume, while bio-derived alternatives attract R&D investment as refineries face tightening discharge limits. Oil & gas applications generate the bulk of revenue, though water treatment represents the fastest-expanding end-use as utility providers retrofit aging distribution infrastructure.
The EPA regulates chemical additives under the Clean Water Act and Toxic Substances Control Act, compelling manufacturers to submit environmental fate data before commercial deployment. OSHA's process safety management standards govern handling protocols at blending facilities and injection sites. Stakeholders must weigh biodegradability certification timelines against project bid deadlines when selecting formulation partners.
Market Dynamics
The EPA's evolving discharge framework for chemical additives is compressing formulation timelines while pipeline operators in the Permian Basin accelerate chemical injection programs to offset rising pumping costs.
Growth Catalysts
- Pipeline modernization mandates:Aging crude oil infrastructure in the Gulf Coast corridor requires drag reducing agent retrofitting to maintain throughput without capital-intensive pump station upgrades.
- REACH compliance differentiation:European water utilities prioritize biodegradable polymeric formulations certified under ECHA biodegradability protocols for distribution network rehabilitation projects.
- Surfactant manufacturing integration:Backward integration into long-chain polymer feedstocks secures supply continuity for midstream operators facing volatile alpha-olefin pricing.
Market Restraints
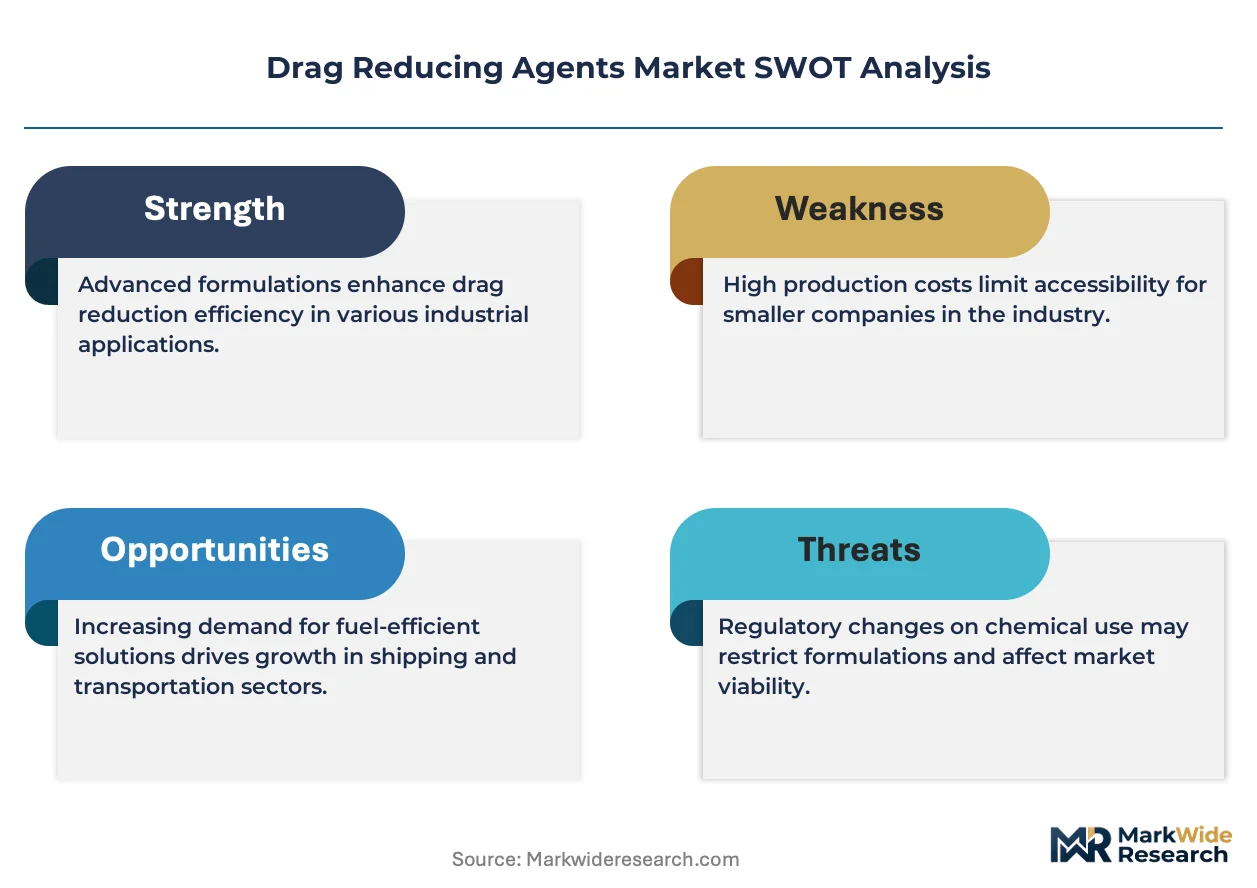
- Petroleum chemist scarcity:Polymer synthesis expertise shortages limit technical service team scaling for formulation customization at remote injection sites.
- High-purity monomer concentration:North American specialty chemical producers control 80% of ultra-high molecular weight polyethylene feedstock supply for premium drag reducing agents.
- Shear degradation limitations:Polymeric formulations lose efficacy beyond 50 ppm in high-velocity multiphase flow conditions common in deepwater production tiebacks.
Strategic Opportunities
- Bio-derived formulation R&D:Cellulose-derived alternatives attract investment as refineries face tightening EPA discharge limits under Clean Water Act Section 402 permitting.
- Water treatment vertical expansion:Municipal utility providers in Texas and California retrofit aging distribution infrastructure with drag reducing agents to reduce pumping energy consumption.
- Performance-guaranteed contracting:Midstream operators in the Middle East adopt friction-reduction-as-a-service models tying supplier payments to measured pressure drop improvements.
Industry Challenges
- Environmental fate data compilation:EPA Toxic Substances Control Act pre-manufacture notification timelines extend 18-24 months, compressing project bid windows for formulation partners.
- Injection system integration complexity:Legacy pipeline SCADA architectures require costly retrofitting to accommodate real-time drag reducing agent dosing optimization algorithms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drag Reducing Agents Market |
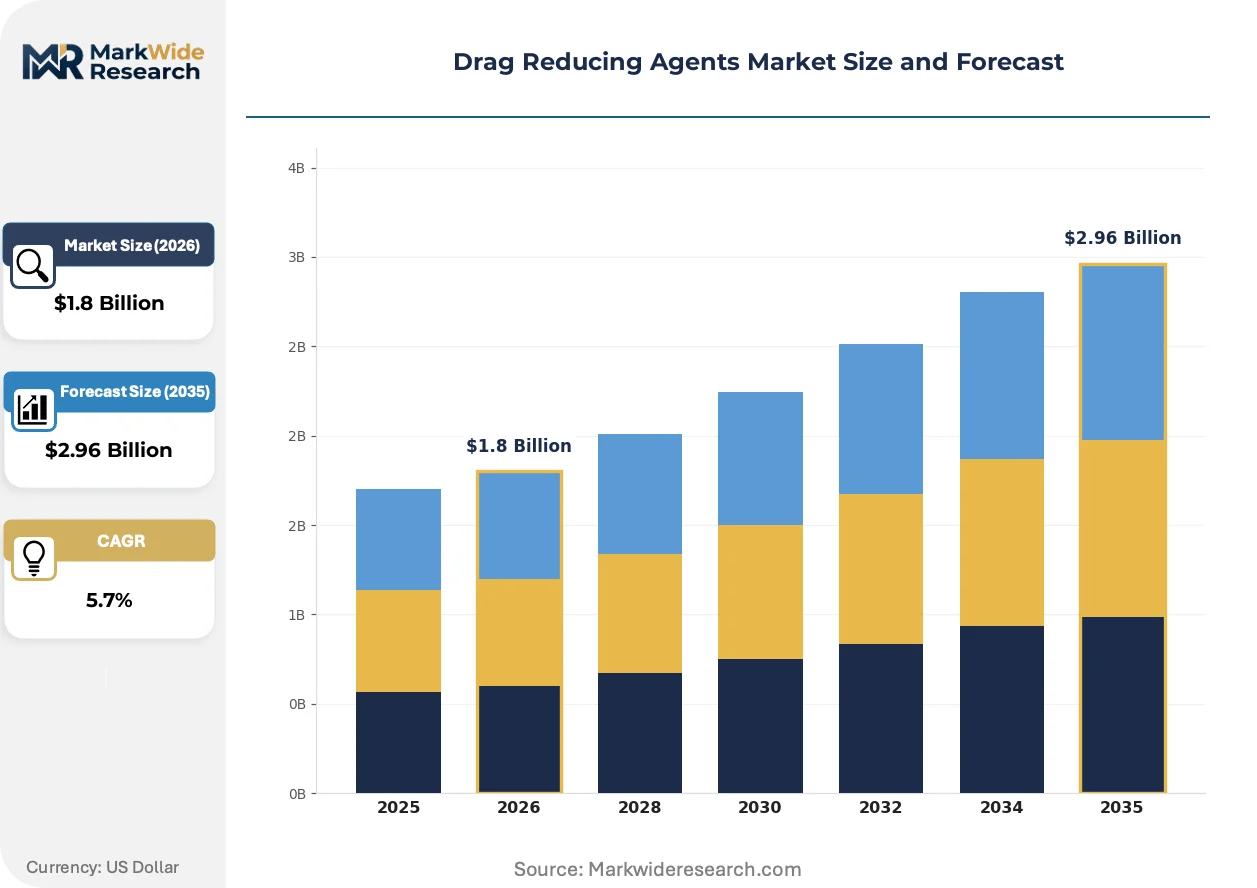
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymeric, Surfactant-based, Bio-derived, Synthetic Application: Oil & Gas, Pipeline Transportation, Water Treatment, Industrial Processes End User: Refineries, Utility Providers, Chemical Manufacturers, Transportation Services Technology: Liquid Formulation, Powder Formulation, Emulsions, Granules |
| Companies Covered | Innospec Inc., Clariant AG, LiquidPower Specialty Products, Schlumberger Limited, Ecolab Inc., Baker Hughes Company, ChampionX Corporation, Dorf Ketal Chemicals, Flowchem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drag Reducing Agents Market Emerging Trajectories
Formulation chemistry is pivoting toward shear-stable architectures as operators push pipeline velocities beyond conventional polymeric limits. Three developments are compressing competitive positioning.
Ultra-high molecular weight polyethylene dispersions with enhanced shear recovery properties are displacing conventional polyacrylamide formulations in high-rate crude gathering systems. Bakken shale producers are adopting these architectures for 24-inch trunk lines operating above 4 meters per second. The technology is displacing incumbent suppliers lacking proprietary dispersion stabilization expertise.
REACH Annex XVII restrictions on microplastic-containing formulations are compelling European manufacturers to accelerate bio-based polymer platform development. The regulation forces reformulation of existing products ahead of 2027 compliance deadlines. Water treatment applications in Germany and the Netherlands are most affected, with utilities now requiring OECD 301B biodegradability certification in procurement specifications.
Midstream procurement teams are consolidating supplier rosters from twelve-plus vendors to three preferred partners with integrated surfactant manufacturing capabilities. Long-term supply agreements now span five-to-seven years with embedded price escalation clauses tied to ethylene feedstock indices. This concentration is most visible in the Permian Basin, where Pioneer Natural Resources and Diamondback Energy have executed exclusive formulation partnerships.
Drag Reducing Agents Market Segmentation
Drag reducing agent procurement decisions hinge on formulation compatibility with pipeline metallurgy, discharge permit constraints, and injection infrastructure. Segment boundaries blur as suppliers develop hybrid architectures spanning multiple technology platforms.
Product Type:
EPA Clean Water Act and Toxic Substances Control Act requirements differentiate commercial viability across formulation chemistries, with biodegradability certification timelines compressing product development cycles.
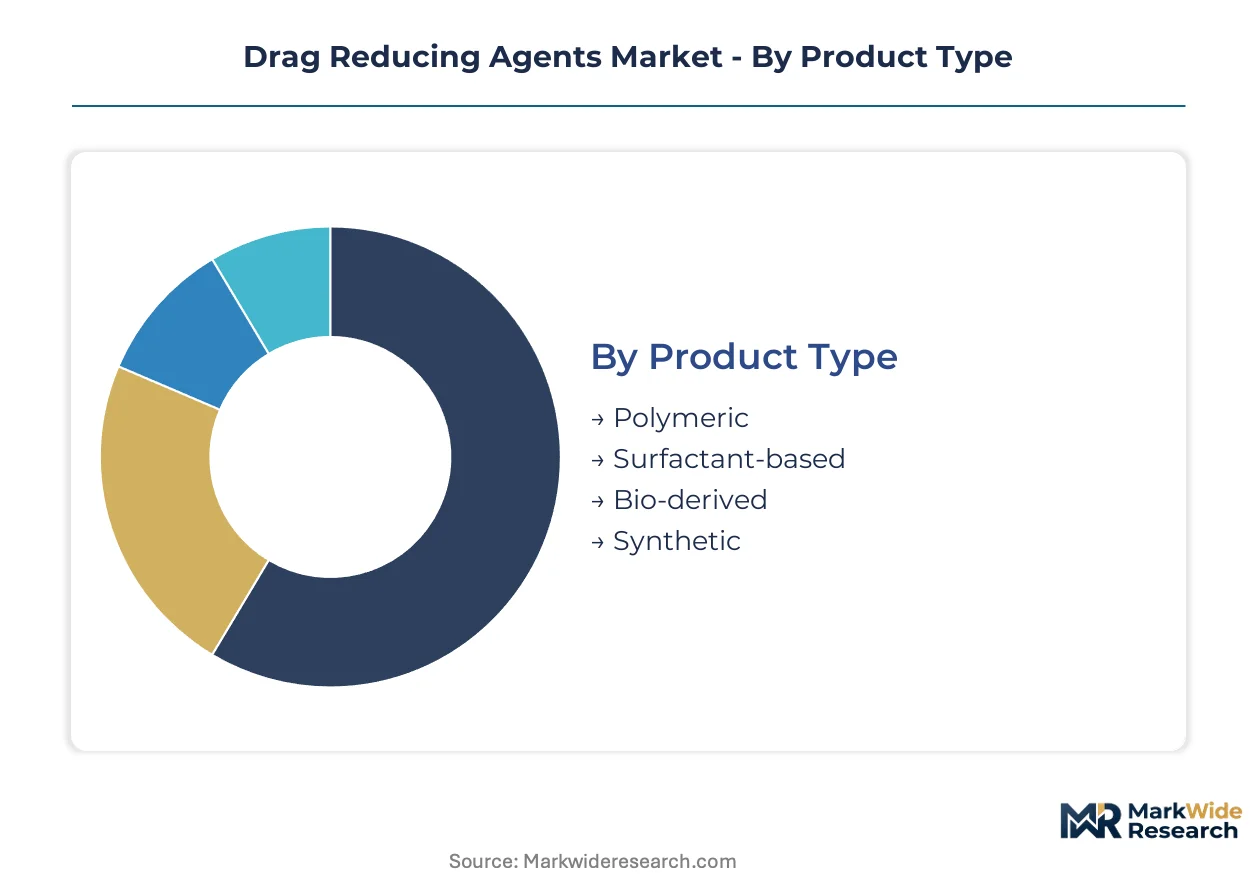
- Polymeric:Ultra-high molecular weight polyethylene and polyacrylamide architectures dominate crude oil trunk lines, delivering 40-80% friction reduction at sub-50 ppm dosing. Permian Basin operators specify these formulations for high-velocity multiphase gathering systems where shear recovery properties determine batch economics.
- Surfactant-based:Long-chain surfactant micelle structures suppress turbulent flow in refined product pipelines without the mechanical degradation susceptibility of polymer chains. Gulf Coast refined product terminals favor these architectures for gasoline and diesel distribution networks subject to seasonal throughput variations.
- Bio-derived:Cellulose-derived and plant-based polymer platforms attract R&D investment as refineries face tightening EPA discharge limits.
- Synthetic:Petroleum-derived specialty polymers offer cost positioning for bulk chemical transport applications with less stringent environmental fate requirements.
Polymeric formulations handle the majority of throughput; bio-derived alternatives are gaining share fastest as ECHA biodegradability protocols reshape European procurement specifications.
Application:
End-use concentration patterns reflect infrastructure age, energy cost structures, and regulatory enforcement intensity across operating jurisdictions.
- Oil & Gas:Crude oil gathering systems and transmission pipelines generate the dominant revenue share, with drag reducing agents enabling deferred pump station capital across the Permian Basin and Bakken shale. Midstream operators calculate payback periods against ethylene feedstock price volatility.
- Pipeline Transportation:Refined product and NGL lines specify surfactant formulations for lower-viscosity hydrocarbons where polymeric shear degradation limits efficacy. Colonial Pipeline and comparable trunk systems optimize dosing through SCADA-integrated injection skids.
- Water Treatment:Municipal distribution network rehabilitation represents the steepest expansion trajectory, with Texas and California utilities retrofitting aging infrastructure to reduce pumping energy consumption.
- Industrial Processes:Cooling water and process fluid systems in chemical manufacturing deploy drag reducing agents for heat transfer efficiency gains.
Oil & gas applications anchor current volume; water treatment climbs the fastest on share as utility infrastructure modernization accelerates.
End User:
Customer procurement sophistication varies by balance sheet capacity, technical staffing depth, and exposure to environmental enforcement actions.
- Refineries:Integrated petroleum processors specify drag reducing agents for crude receipt lines and product export infrastructure, with EPA discharge permits driving biodegradable formulation preferences.
- Utility Providers:Municipal water authorities in drought-stressed regions prioritize energy-efficient distribution, with California Public Utilities Commission efficiency mandates accelerating adoption.
- Chemical Manufacturers:Process industries deploy drag reducing agents for internal fluid transport optimization.
- Transportation Services:Third-party pipeline operators structure performance-guaranteed contracts tying supplier compensation to measured pressure drop improvements.
Refineries command the largest formulation volumes; utility providers expand most quickly as municipal infrastructure retrofit programs scale.
Technology:
Physical form factors determine storage requirements, injection system compatibility, and field handling logistics at remote pipeline stations.
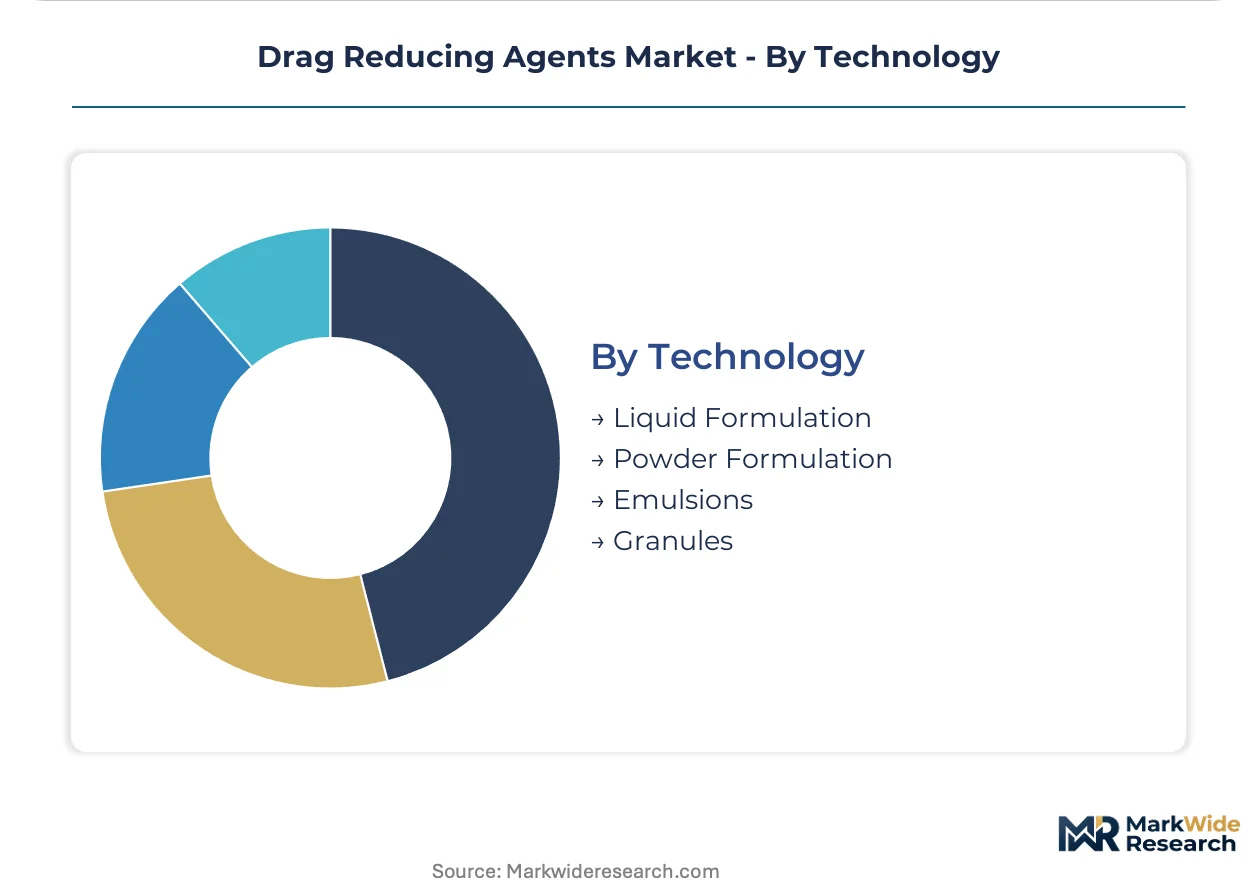
- Liquid Formulation:Pre-dispersed polymer solutions enable rapid deployment without on-site dissolution equipment, dominating Permian Basin chemical injection programs where staffing constraints limit technical service presence.
- Powder Formulation:Concentrated dry polymer requires controlled dissolution systems but offers freight cost advantages for remote locations with established blending infrastructure.
- Emulsions:Oil-in-water dispersions stabilize ultra-high molecular weight polymers for high-shear injection environments.
- Granules:Solid granular products suit automated dosing systems in water treatment facilities with standardized material handling protocols.
Liquid formulations capture the dominant procurement share; emulsions are expanding fastest as operators push pipeline velocities beyond conventional polymeric limits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. The United States deploys drag reducing agents primarily for crude oil throughput optimization, while European procurement prioritizes biodegradability certification under ECHA protocols and Asian markets emphasize cost-efficient surfactant formulations for refined product distribution.
United States
Permian Basin midstream operators anchor domestic demand through aggressive chemical injection programs targeting pumping cost reduction. EPA Clean Water Act Section 402 permitting shapes formulation selection for discharge-intensive applications. The Gulf Coast corridor hosts concentrated infrastructure retrofit activity as aging pipelines require drag reducing agent deployment to maintain throughput without capital-intensive pump station upgrades.
Germany
REACH Annex XVII microplastic restrictions are accelerating bio-based polymer platform development ahead of 2027 compliance deadlines. ECHA biodegradability protocols under OECD 301B certification now appear in utility procurement specifications for distribution network rehabilitation. The Rhine-Ruhr industrial cluster drives formulation R&D investment as water treatment providers seek cellulose-derived alternatives to conventional petroleum-based architectures.
Saudi Arabia
National oil company procurement frameworks emphasize performance-guaranteed contracting models tying supplier compensation to measured pressure drop improvements. The country's national petroleum regulator maintains strict chemical additive approval timelines for injection system deployment. The Eastern Province concentration of pipeline infrastructure generates concentrated demand for ultra-high molecular weight polyethylene formulations in high-velocity crude gathering systems.
China
Dual carbon goals and tightening environmental discharge standards under MEE authority are reshaping formulation preferences toward lower-carbon polymer synthesis pathways. GB standards for chemical additives in industrial water systems create compliance-driven procurement segmentation. The Yangtze River Delta petrochemical corridor represents the dominant domestic consumption cluster for surfactant-based drag reducing agents in refined product logistics.
Brazil
Pre-salt deepwater production tiebacks generate specialized demand for shear-stable formulations capable of maintaining efficacy in high-velocity multiphase flow conditions. ANVISA regulatory frameworks for chemical handling at offshore facilities influence supplier qualification requirements. The Rio de Janeiro coastal industrial zone concentrates technical service team deployment for remote injection site support.
Drag Reducing Agents Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in drag reducing agent supply. The upper tier commands preferred partner status through captive surfactant manufacturing capabilities and long-term supply agreement structures spanning five-to-seven years. Specialist players compete on formulation customization velocity and regional technical service density. Strategic differentiation centers on backward integration into alpha-olefin feedstocks and biodegradability certification speed.
Among integrated chemical suppliers, Innospec Inc., Clariant AG, and Baker Hughes Company occupy positions exemplifying distinct competitive archetypes. Innospec represents the surfactant manufacturing integration model through its specialty chemical production infrastructure. Clariant AG anchors the European REACH compliance specialization tier with bio-based platform development capabilities. Baker Hughes exemplifies the national oil company relationship depth archetype through its Middle East and Latin America market positioning.
| Leading Market Players |
|---|
| Innospec Inc. |
| Clariant AG |
| LiquidPower Specialty Products |
| Schlumberger Limited |
| Ecolab Inc. |
| Baker Hughes Company |
| ChampionX Corporation |
| Dorf Ketal Chemicals |
| Flowchem |
| Others |
Supply Flow & Price Mechanics
Long-term supply agreements spanning five-to-seven years with embedded ethylene feedstock index clauses lock in supply continuity for Permian Basin midstream operators while anchoring price visibility against volatile alpha-olefin markets. These structures concentrate procurement power among integrated suppliers with captive surfactant manufacturing, compressing margins for non-integrated competitors.
Pricing Analysis
Contract-based long-term offtake dominates drag reducing agent procurement, with pricing stratifying across premium, standard, and economy tiers tied to molecular weight specifications and biodegradability certification status. Price differentiation rests on EPA environmental fate data completeness and REACH Annex XVII compliance velocity, with certified bio-derived formulations commanding substantial premia. Cost compression in standard polyacrylamide formulations is intensifying due to concentrated ultra-high molecular weight polyethylene feedstock supply controlled by North American specialty chemical producers. Midstream operators with performance-guaranteed contracting frameworks exhibit lowest price sensitivity, while municipal water utilities in Texas and California face acute budget constraints.
Supply Chain Analysis
Port congestion on Houston Ship Channel trade lanes elevates inbound logistics costs for alpha-olefin monomer shipments feeding Gulf Coast polymer synthesis facilities. Geographic supply concentrates in the United States, Germany, and Saudi Arabia, with ultra-high molecular weight polyethylene feedstock drawing from Texas petrochemical corridors and European specialty polymer hubs. Raw material dependencies center on ethylene derivatives, long-chain surfactant precursors, and cellulose-derived feedstocks for bio-based platforms. Single-source vulnerability pervades the 80% concentration of premium polymer feedstock among North American producers. Distribution runs through midstream operator chemical injection skids at remote pipeline stations, with liquid formulation tanker deliveries dominating Permian Basin logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The drag reducing agents market sits in early-cycle recovery as pipeline infrastructure modernization mandates accelerate following deferred maintenance through the 2020-2022 period. Capital deployment into chemical injection programs is expanding as operators prioritize pumping cost reduction over pump station capital expenditure.
For Market Incumbents: Compound technical service team density in the Permian Basin and Bakken shale to defend against formulation customization demands from remote injection sites. Deepen backward integration into alpha-olefin feedstocks to offset volatility in specialty polymer supply. Prioritize EPA environmental fate data compilation speed to compress pre-manufacture notification timelines and secure preferred partner status in consolidating procurement rosters.
For New Entrants and Emerging Players: OECD 301B biodegradability certification fast-tracks entry into European water utility procurement specifications as REACH Annex XVII deadlines approach. White-space opportunities concentrate in cellulose-derived bio-based platforms for refineries facing tightening discharge limits and in shear-stable emulsion formulations for high-velocity multiphase flow applications. Target municipal water treatment verticals in drought-stressed Texas and California regions with energy-efficient distribution retrofit value propositions.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated surfactant manufacturers with established ethylene feedstock linkages and five-to-seven year supply agreement backlogs. Long-term viability over the next decade hinges on biodegradability certification capabilities and SCADA-integrated injection system expertise. Watch EPA Clean Water Act Section 402 permitting velocity as the inflection signal for bio-derived formulation demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alpha-Olefin Feedstocks | Captive supply of ultra-high molecular weight polyethylene precursors insulates margins from volatile ethylene pricing. |
| Bio-Derived Platform Development | Cellulose-derived alternatives position suppliers ahead of EPA discharge limit tightening under Clean Water Act frameworks. |
| Performance-Guaranteed Contracting Models | Friction-reduction-as-a-service structures tie Baker Hughes and ChampionX compensation to measured pressure drop improvements. |
| SCADA-Integrated Injection System Deployment | Real-time dosing optimization algorithms require costly legacy pipeline architecture retrofitting by midstream operators. |
| Long-Term Supply Agreement Structuring | Five-to-seven year contracts with ethylene index escalation clauses secure Pioneer Natural Resources and Diamondback Energy procurement slots. |
Methodological Framework
Initial hypotheses were tested against primary input from midstream operator procurement directors, petroleum chemists with polymer synthesis expertise, EPA regulatory affairs consultants, and municipal utility engineering managers, then refined through secondary validation. Primary stakeholder engagement combined structured interviews with technical service team leads at drag reducing agent injection sites and procurement officers at national oil companies. Secondary sources encompassed EPA pre-manufacture notification filings under Toxic Substances Control Act, ECHA REACH registration dossiers, SEC 10-K disclosures from integrated chemical suppliers, and trade data from Gulf Coast petrochemical corridors. Bottom-up formulation demand estimates triangulated against top-down pipeline throughput projections.
Variance decomposition across the projection horizon isolates volume drivers by formulation chemistry, application vertical, and regional regulatory cluster. The analytical framework models segmentation dimensions spanning polymeric versus surfactant versus bio-derived platforms, oil and gas versus water treatment end-uses, and liquid versus emulsion physical forms. CAGRs were derived from ethylene feedstock price trajectory assumptions and pipeline infrastructure age profiles. Industry-specific forecast inputs include EPA environmental fate data approval timelines and ECHA biodegradability certification completion rates.
Underlying assumptions cover sustained Permian Basin production levels, REACH Annex XVII enforcement intensity, and alpha-olefin supply concentration stability, with deviation risk concentrated in EPA regulatory timeline extensions and cellulose feedstock cost volatility. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Industrial Cyclohexylamine Market
Industrial Chemicals
Fireworks and Firecrackers Market
Industrial Chemicals
Diisobutylaluminum Chloride Market
Industrial Chemicals
Asia-Pacific Bio Transformer Oil Market
Industrial Chemicals
Tall Oil Fatty Acid Market
Industrial Chemicals
Gypsum-Based Products Market
Industrial Chemicals
Automotive Chemicals Market
Industrial Chemicals
Ethoxy Propanol Market
Industrial Chemicals
Screw Separators Market
Industrial Chemicals
Hydrogenated Bisphenol a Market
Industrial Chemicals
Global Foundry Chemicals Market
Industrial Chemicals
E-Fluids Market
Industrial Chemicals
Global Sponge Applicator Market
Industrial Chemicals
Lime Market
Industrial Chemicals
VOC Concentrator Market
Industrial Chemicals
Global Industrial Oils Market