
 China Methanol Market | 2026-2036
China Methanol Market Size, Share, and Industry Trends Forecast 2026-2036
China Methanol Market Insights
Petrochemical buyers seeking olefin feedstock alternatives is redrawing procurement patterns across China's methanol value chain. China Petrochemical Corp sustains integrated refinery-methanol operations that captive-supply downstream derivatives. Shanxi Lanhua Sci-Tech Venture Company Limited dominates coal-based production corridors in Shanxi Province. Henan Shuncheng Group leverages regional logistics networks to serve central China industrial clusters.
Methanol is a light, volatile alcohol (CH₃OH) produced primarily through coal gasification or natural gas reforming, with Chinese output heavily weighted toward coal-based synthesis featuring 99.85% minimum purity grades for industrial acceptance. The chemical serves as a foundational feedstock for formaldehyde, acetic acid, and methyl tert-butyl ether production across Chinese manufacturing. Chemical feedstock applications anchor volume consumption given entrenched formaldehyde and acetic acid derivative demand. Methanol-to-olefins represents the fastest-expanding product type as MTO units proliferate along China's eastern seaboard. Fuel-grade methanol occupies a narrower but strategically defended niche supported by provincial blending mandates in Shanxi and Shaanxi.
MEE enforces dual carbon emission intensity benchmarks that constrain new coal-to-methanol approvals while SAMR administers GB standards governing fuel-grade product quality and industrial methanol specifications. The PLI scheme for clean hydrogen and green chemical pathways is redirecting capital toward low-carbon methanol demonstration projects in Ningxia and Inner Mongolia. Stakeholders must track how provincial carbon quotas and green hydrogen cost curves reshape the economics of coal-versus-biomass feedstock selection.
Market Dynamics
Coal-to-methanol economics are under acute pressure from MEE dual carbon benchmarks and rising carbon quota costs, forcing producers toward green hydrogen retrofits or biomass gasification pilots. This structural tension between incumbent feedstock infrastructure and decarbonization mandates defines competitive positioning across the value chain.
Growth Catalysts
- Methanol-to-olefins conversion:Petrochemical buyers in Jiangsu and Zhejiang are deepening MTO unit deployment to reduce naphtha dependency. This feedstock substitution pulls methanol volumes into coastal olefin production clusters.
- Provincial fuel-blending mandates:Shanxi and Shaanxi regulations require gasoline-methanol blends that defend fuel-grade methanol offtake. These provincial policies create guaranteed demand floors for designated producers.
- Green hydrogen demonstration corridors:PLI scheme funding for clean hydrogen pathways is accelerating low-carbon methanol pilots in Ningxia. Capital redirection toward biomass and electrolysis-based synthesis is expanding project pipelines.
Market Restraints
- Coal price volatility:Input cost swings for gasification feedstock compress margins for Shanxi-based producers. Coal procurement exposure remains unhedged for most domestic capacity.
- Carbon quota scarcity:MEE emission intensity benchmarks constrain new plant approvals and inflate compliance costs for existing coal-to-methanol assets. Permit bottlenecks are lengthening project timelines.
- Natural gas supply concentration:Pipeline dependency on three state-owned distributors creates feedstock security risks for gas-based methanol units in Sichuan and Chongqing.
Strategic Opportunities
- Biomass gasification scale-up:Agricultural residue feedstock access in Heilongjiang and Jilin offers untapped low-carbon methanol production potential. Rural biomass collection networks remain underdeveloped.
- Maritime fuel certification:IMO 2020 sulfur caps and EU FuelEU Maritime rules are opening methanol bunkering demand for coastal shipping. Port infrastructure in Ningbo-Zhoushan is adapting.
- Carbon capture integration:Post-combustion capture retrofits at coal-based plants can generate CCUS credits under MEE frameworks. This technology convergence offers compliance cost offsets.
Industry Challenges
- Process engineering talent scarcity:Green hydrogen-to-methanol synthesis requires electrochemist and catalyst specialist expertise that domestic universities are not yet producing at scale.
- Legacy asset stranding risk:Coal gasification infrastructure in Shanxi and Inner Mongolia faces accelerated depreciation under tightening carbon quotas. Write-down timelines are compressing.
- Biomass supply chain standardization:Agricultural residue quality variability and collection logistics fragmentation impede consistent gasifier feedstock delivery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Methanol Market |
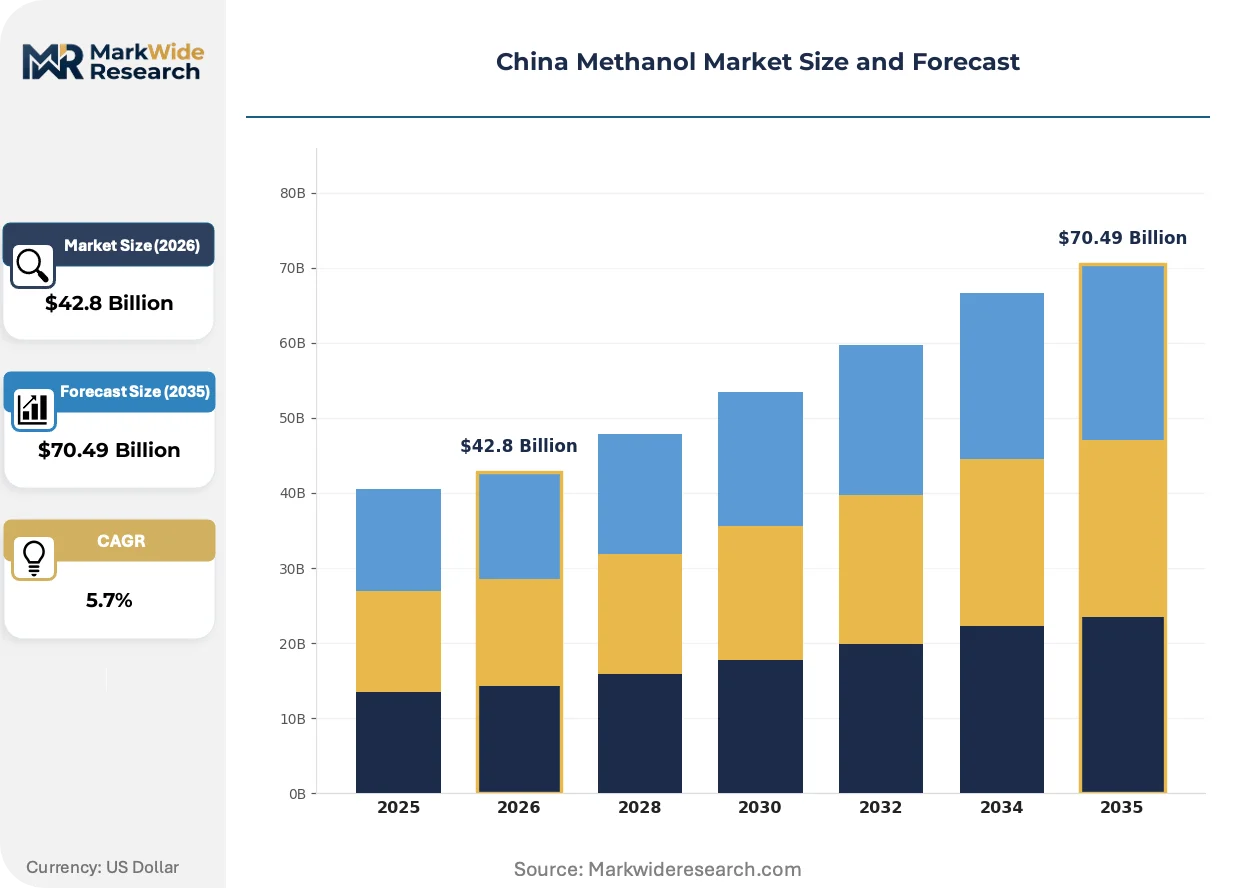
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $70.49 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fuel, Chemical Feedstock, Solvent, Methanol-to-Olefins End User: Automotive, Energy, Construction, Pharmaceuticals Application: Energy Production, Coatings, Adhesives, Plastics Delivery Mode: Pipeline, Tanker, Rail, Truck |
| Companies Covered | Henan Shuncheng Group, China Petrochemical Corp, Shanxi Lanhua Sci-Tech Venture Company Limited, Nanjing Kapsom Engineering Limited, CIMC Enric Holdings Limited, Nanjing Chemistry Industry Company Limited, Tianjin Bohai Chemical Industry Co Ltd, China National Petroleum, Shunli, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Methanol Market Trends and Innovations
Electrolyzer-scale methanol synthesis and carbon capture integration are converging to redefine production economics. These technical trajectories are compressing the cost gap between fossil and renewable feedstock pathways.
Solid oxide electrolyzer cell technology is miniaturizing modular hydrogen production units for distributed methanol synthesis. Chemical park operators in Jiangsu are piloting containerized SOEC-integrated methanol skids that eliminate pipeline hydrogen transport. This architecture is compressing capital requirements for green methanol demonstration projects and enabling site-specific carbon capture integration.
MEE dual carbon emission intensity benchmarks are tightening approval thresholds for new coal-to-methanol capacity. Industrial consequence includes accelerated retrofit spending at incumbent Shanxi and Inner Mongolia plants to meet 2025-2030 benchmark trajectories. Coal-based producers with stranded asset exposure are responding with biomass co-gasification trials and CCUS project partnerships.
Petrochemical buyers are consolidating methanol procurement through long-term offtake contracts tied to carbon intensity certification. Direct producer relationships are displacing spot market purchasing for MTO units in Zhejiang. This contract concentration is most visible among coastal olefin producers seeking supply security and Scope 3 emission reporting compliance.
China Methanol Market Segmentation
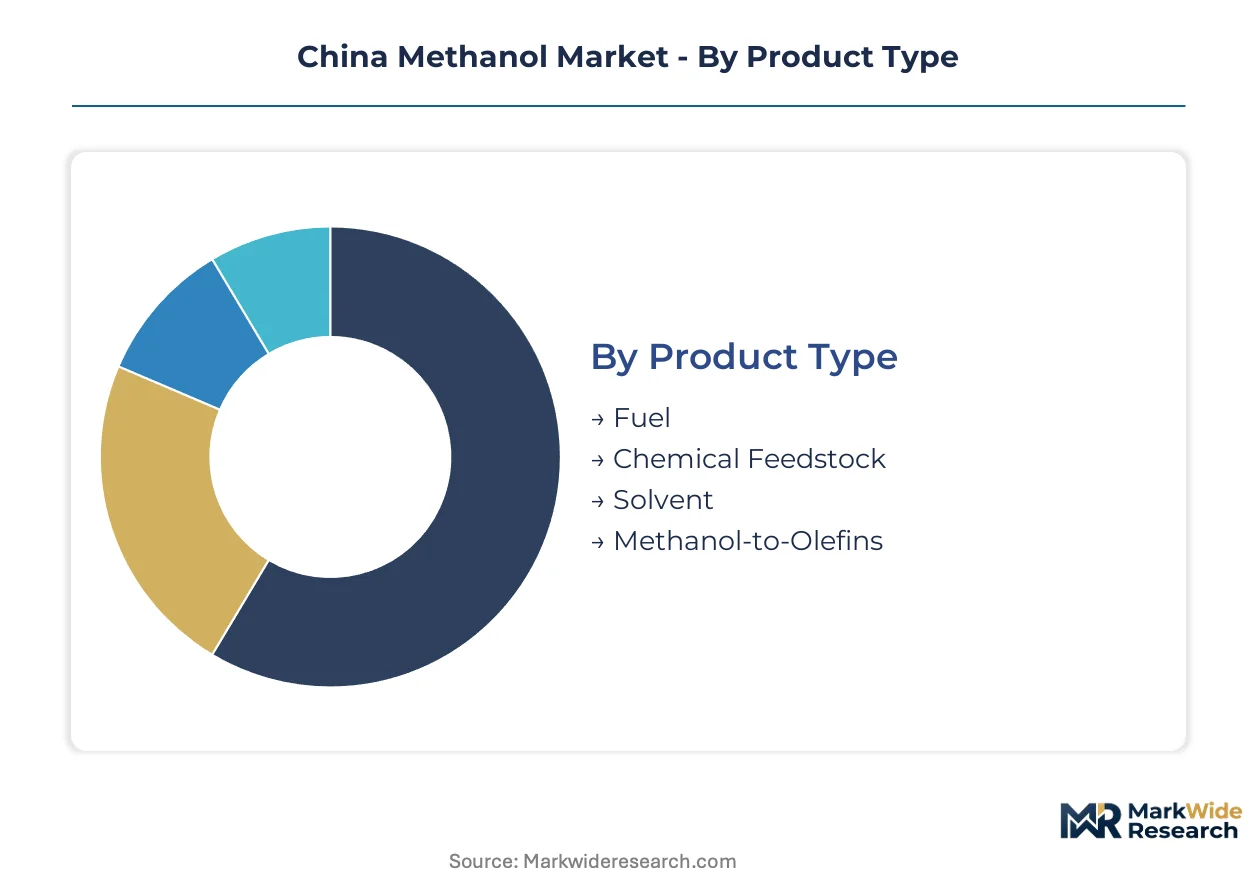
Segmentation in China's methanol market reveals how MEE carbon benchmarks and feedstock substitution pressures are redistributing volume across product categories and delivery channels. Understanding these splits exposes where procurement consolidation and infrastructure investment are concentrating.
Product Type:
Chemical feedstock grades move predominantly through dedicated pipeline corridors into integrated petrochemical parks, while fuel-grade volumes rely on tanker and rail networks serving provincial blending mandates.
- Chemical Feedstock:Industrial-grade methanol with 99.85% minimum purity serves formaldehyde and acetic acid synthesis. Demand concentrates in Jiangsu and Zhejiang chemical parks where MTO units pull volumes through long-term offtake contracts rather than spot procurement.
- Methanol-to-Olefins:Dedicated MTO-grade specifications with controlled impurity profiles enable direct olefin conversion. Coastal Zhejiang and Jiangsu installations are expanding capacity fastest as petrochemical buyers reduce naphtha dependency.
- Fuel:Blending-grade methanol meets provincial gasoline-mandate specifications in Shanxi and Shaanxi. Rail and tanker delivery dominates given dispersed retail fuel infrastructure.
- Solvent:High-purity solvent grades serve coatings and pharmaceutical extraction. Smaller batch volumes move through truck distribution to dispersed industrial users.
Chemical feedstock dominates installed base. Methanol-to-olefins is where expansion concentrates.
End User:
Volume concentration varies sharply by customer scale, with integrated petrochemical complexes commanding pipeline delivery while fragmented construction and pharmaceutical buyers absorb higher logistics costs.
- Energy:Power generation and heating applications in northern provinces absorb fuel-grade methanol through rail-fed storage terminals. MEE emission benchmarks are redirecting some volumes toward cleaner hydrogen-blended combustion trials.
- Automotive:Methanol-fueled vehicle fleets operate under provincial pilot programs in Shanxi and Guizhou. Dedicated refueling infrastructure and vehicle certification requirements create captive supply relationships.
- Construction:Formaldehyde-derived resins for engineered wood products drive methanol consumption. Dispersed manufacturing locations force reliance on truck delivery with higher per-ton logistics costs.
- Pharmaceuticals:Solvent-grade methanol for active ingredient extraction requires pharmaceutical GMP compliance. Smaller volumes command premium pricing through certified supply chains.
Energy sector absorbs the largest volume share. Automotive applications are climbing the fastest as provincial fleet electrification alternatives mature.
Application:
Application-level demand splits reveal how downstream process requirements dictate purity specifications and delivery reliability thresholds.
- Plastics:MTO-derived ethylene and propylene feed polymerization units in Zhejiang and Jiangsu. Pipeline delivery from coastal methanol terminals ensures continuous olefin production without inventory interruption.
- Energy Production:Boiler and turbine combustion applications in industrial heat and power plants. Coal price volatility is compressing methanol's cost competitiveness against incumbent fossil fuels.
- Coatings:Solvent-grade methanol for industrial and automotive paint formulations. Quality variability tolerance allows multi-source procurement from regional distributors.
- Adhesives:Formaldehyde-based resin systems for wood panel and construction bonding. Construction cycle seasonality creates demand fluctuation that truck logistics accommodate better than fixed pipeline commitments.
Plastics applications command the steepest expansion trajectory. Energy production retains the largest existing offtake base.
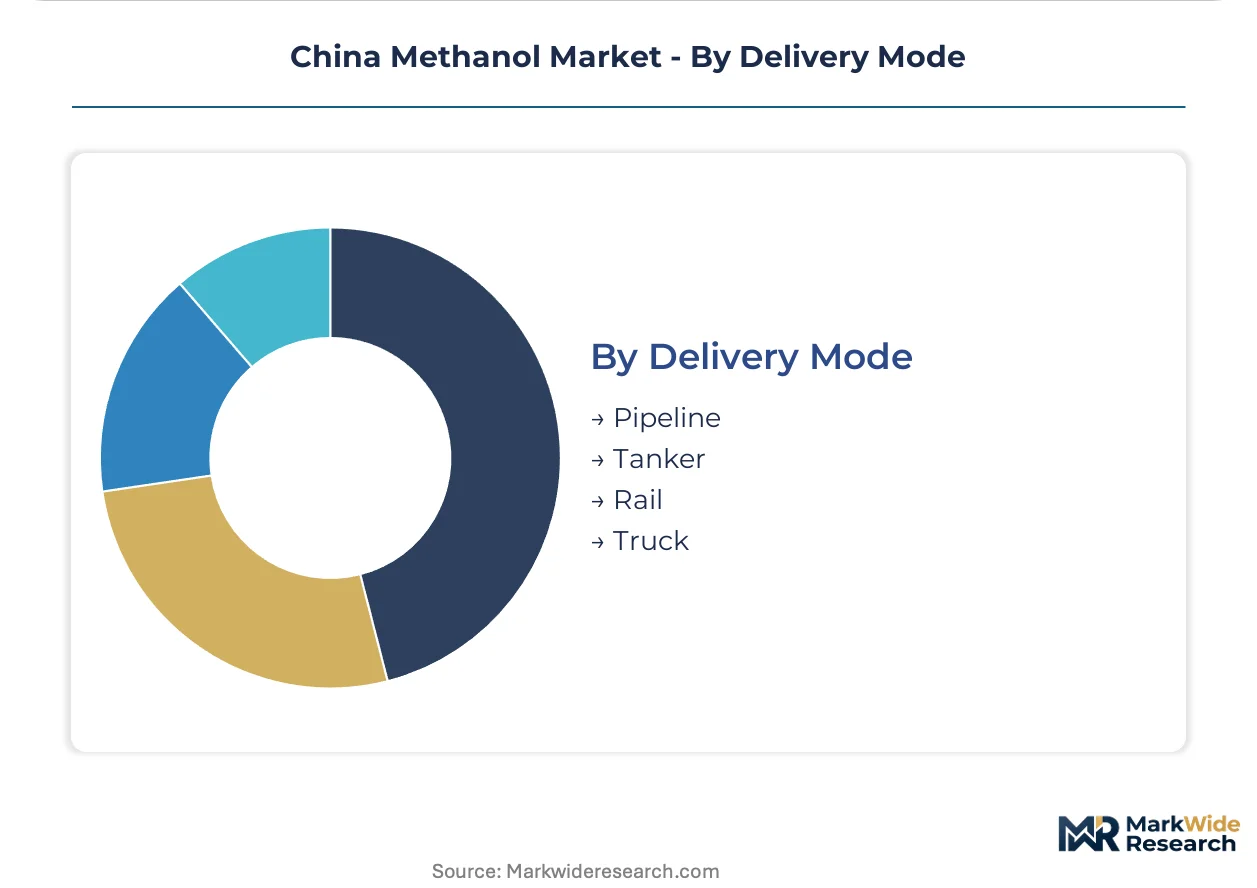
Delivery Mode:
Infrastructure configuration directly determines which production sites can serve which end-use segments, with pipeline access conferring structural cost advantages.
- Pipeline:Dedicated methanol corridors connect Shanxi and Inner Mongolia production basins to coastal chemical parks. Carbon quota costs at origin plants are eroding the feedstock cost advantage this mode was designed to exploit.
- Tanker:Coastal waterborne delivery from Ningbo-Zhoushan and other port terminals enables import substitution and export positioning. IMO maritime fuel certification is opening methanol bunkering demand at these same port complexes.
- Rail:Bulk railcar networks serve inland fuel-blending terminals and dispersed industrial users. Provincial rail capacity allocation priorities can constrain peak-season availability.
- Truck:Last-mile distribution to small-volume solvent and construction chemical buyers. Higher per-unit logistics costs limit this mode to premium-margin specialty grades.
Pipeline infrastructure anchors current supply chain economics. Tanker delivery is gaining share fastest as coastal MTO capacity expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ningbo-Zhoushan port complex anchors methanol import flows and bunkering infrastructure along China's eastern seaboard. Pipeline corridors from Shanxi and Inner Mongolia production basins feed coastal olefin clusters through dedicated methanol arteries. Provincial carbon quotas and MEE dual carbon benchmarks are redistributing capacity investment toward western hydrogen demonstration zones.
Shanxi Province
Coal gasification corridors supply formaldehyde and acetic acid derivatives through rail-fed distribution networks. MEE emission intensity benchmarks constrain new plant approvals while inflating compliance costs for incumbent producers. Taiyuan industrial clusters host retrofit spending toward biomass co-gasification trials and CCUS integration partnerships.
Inner Mongolia
Abundant coal reserves and renewable energy potential position the region for dual-track methanol production. PLI scheme funding accelerates green hydrogen demonstration projects in Ningxia-adjacent zones. Ordos chemical parks pilot electrolyzer-scale methanol synthesis using stranded wind power assets.
Jiangsu Province
MTO unit expansion pulls methanol volumes through pipeline delivery from coastal terminals. SAMR-administered GB standards govern product quality specifications for olefin feedstock applications. Nanjing chemical parks concentrate long-term offtake contracting as petrochemical buyers reduce naphtha dependency.
Zhejiang Province
Coastal olefin production clusters drive fastest capacity absorption for methanol-to-olefins conversion. Provincial industrial policy supports integrated refinery-petrochemical complexes with captive methanol supply. Ningbo-Zhoushan port infrastructure enables import substitution and emerging methanol bunkering demand for maritime fuel compliance.
Sichuan-Chongqing
Natural gas reforming corridors serve dispersed industrial demand through pipeline and rail networks. Pipeline dependency on state-owned distributors creates feedstock security risks during peak consumption periods. Chongqing chemical parks explore hydrogen-blended methanol combustion trials under MEE cleaner fuel pathways.
China Methanol Market Competitive Landscape
Concentration sits with state-owned petrochemical conglomerates and regional coal-chemistry specialists. China Petrochemical Corp and China National Petroleum anchor integrated refinery-methanol operations with captive downstream derivatives. Shanxi-based coal gasification specialists and coastal engineering fabricators populate the mid-tier. Competitive moves center on capacity expansion along eastern seaboard MTO corridors and green hydrogen retrofit partnerships under PLI scheme funding.
Among state-owned integrated operators, China Petrochemical Corp exemplifies the captive-supply archetype through refinery-methanol-derivative linkages. Shanxi Lanhua Sci-Tech Venture Company Limited occupies a position within coal-based production corridors facing accelerated depreciation pressure from tightening carbon quotas. Henan Shuncheng Group represents regional logistics-integrated suppliers serving central China industrial clusters through rail and tanker networks.
| Leading Market Players |
|---|
| Henan Shuncheng Group |
| China Petrochemical Corp |
| Shanxi Lanhua Sci-Tech Venture Company Limited |
| Nanjing Kapsom Engineering Limited |
| CIMC Enric Holdings Limited |
| Nanjing Chemistry Industry Company Limited |
| Tianjin Bohai Chemical Industry Co Ltd |
| China National Petroleum |
| Shunli |
| Others |
Pricing and Supply Chain Analysis
SAMR-administered GB standards gate both supply qualification and price differentiation simultaneously, separating certified MTO-grade methanol for coastal olefin producers from fuel-grade volumes serving provincial blending mandates. MEE dual carbon benchmarks add compliance-cost layering that widens spreads between coal-based origins and low-carbon certified alternatives.
Pricing Analysis
Volume-discount tiering structures dominate contract negotiations, with coastal MTO operators securing sub-market rates through multi-year offtake commitments while dispersed construction chemical buyers absorb premium truck-delivery surcharges. Price differentiation rests on carbon-intensity certification and pipeline-access proximity, with Shanxi-origin volumes facing compression from rising quota costs. Margins are tightening for coal-gasification incumbents as biomass co-gasification trials inflate unit economics. Petrochemical buyers exhibit lowest price sensitivity given feedstock substitution imperatives; small solvent-grade purchasers remain most exposed to spot volatility.
Supply Chain Analysis
Strategic stockpile preferences prevail among coastal MTO operators maintaining 15-20 day pipeline-fed inventories, while fuel-blending terminals in Shanxi and Shaanxi run lean just-in-turn railcar rotations. Geographic supply concentration centers on Shanxi, Inner Mongolia, and Ningxia production basins. Raw material dependencies draw from steam coal, agricultural residues, and electrolyzer-scale hydrogen. Single-source vulnerability runs through pipeline corridors from carbon-quota-constrained origins. Distribution feeds from dedicated methanol arteries into coastal chemical parks, with tanker delivery gaining share at Ningbo-Zhoushan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Methanol-to-olefins adoption is accelerating across eastern seaboard petrochemical complexes, creating early-cycle expansion conditions as MTO unit deployment outpaces legacy naphtha cracking capacity.
For Market Incumbents: Compound defensive positioning through CCUS integration partnerships at Shanxi and Inner Mongolia coal-gasification assets to offset MEE emission intensity benchmark compliance costs. Accelerate biomass co-gasification pilot scale-up before carbon quota scarcity forces stranded asset write-downs. Prioritize long-term offtake contracting with Zhejiang and Jiangsu MTO operators to lock volume commitments ahead of green hydrogen demonstration corridor maturation.
For New Entrants and Emerging Players: Lead with maritime fuel certification pathways at Ningbo-Zhoushan port infrastructure, where IMO sulfur caps and EU FuelEU Maritime rules are opening methanol bunkering demand. Target Heilongjiang and Jilin agricultural residue supply zones for biomass gasification scale-up, exploiting underdeveloped rural collection networks. Pursue electrolyzer-scale modular synthesis skids for chemical park deployment as a capital-light entry vector.
For Investors and Strategic Acquirers: MEE dual carbon milestone trajectories through 2030 reshape the acquisition landscape toward low-carbon methanol demonstration assets in Ningxia and Inner Mongolia. Long-term viability favors producers with renewable hydrogen feedstock pathways and carbon capture integration capabilities. Acquisition target archetype: coastal engineering fabricators with SOEC-integrated methanol skid deployment experience. Signal to watch: green hydrogen cost curves crossing coal-gasification breakeven thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Hydrogen Retrofit Partnership | PLI scheme funding accelerates low-carbon methanol pilots in Ningxia corridor zones. |
| Biomass Gasification Scale-Up | Agricultural residue access in Heilongjiang unlocks carbon-negative production pathway certification. |
| CCUS Integration Deployment | Post-combustion capture retrofits generate MEE compliance credit offsets at Shanxi plants. |
| Maritime Fuel Certification | IMO 2020 sulfur caps open methanol bunkering demand at Ningbo-Zhoushan terminal complexes. |
| Long-Term Offtake Contracting | Direct producer relationships displace spot purchasing for Zhejiang MTO Scope 3 compliance. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant managers, procurement leads at downstream MTO operators, distribution channel partners, and technical R&D directors; and secondary validation through customs/trade data, MEE emission benchmark disclosures, SAMR GB standard filings, and provincial industrial policy documents. Bottom-up capacity and consumption modeling triangulated against top-down macroeconomic indicators.
Across the projection horizon, analytical frameworks segmented volume and value outputs by grade tier, end-use industry, delivery mode, and regional production hub. CAGRs derived from production capacity buildout schedules, MTO unit deployment timelines, and feedstock substitution elasticity estimates. Industry-specific forecast inputs incorporated coal price volatility bands and carbon quota cost trajectories.
Forecasts assume regulatory continuity in MEE dual carbon benchmarks and SAMR quality enforcement; material policy shifts would require re-modeling. Revision becomes warranted when green hydrogen production costs cross coal-gasification breakeven thresholds or when provincial fuel-blending mandates suspend.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Chromium Trioxide Market
Chemicals
Isooctyl Alcohol Market
Chemicals
Fluorene Market
Chemicals
Hydrogenated Dimer Acid Market
Chemicals
Global E Series Glycol Ether Market
Chemicals
Fluoroboric Acid Market
Chemicals
Global Zinc Pyrithione Market
Chemicals
South America Construction Chemicals Market
Chemicals
Lead Tetracetate Market
Chemicals
Mining Flotation Chemicals Market
Chemicals
Fatty Alcohol Ethoxylates Market
Chemicals
Global Biotechnology-Based Chemical Market
Chemicals
Europe Calcium Peroxide Market
Chemicals
Global Pine Chemicals Market
Chemicals
China Amines Market
Chemicals
Global Monochloroacetic Acid Market