
 Naphthenic Acid Market | 2026-2036
Naphthenic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Naphthenic Acid Market Intelligence
ISO 9001 quality management certification is rotating as the baseline threshold for supplier qualification among Western buyers. Merichem Company leverages its integrated refinery-to-specialty-chemical infrastructure across North American supply corridors. Umicore Cobalt & Specialty Materials anchors European demand through its controlled metal-organic precursor streams. Shenyang Zhang Ming Chemical Co. Ltd dominates domestic distribution networks within China's industrial northeast.
Naphthenic acid comprises a mixture of substituted cyclopentyl and cyclohexyl carboxylic acids derived from refined petroleum fractions, typically containing 8–20 carbon atoms and functioning primarily as corrosion inhibitors, metal soap precursors, and surfactant intermediates in industrial formulations. Heavy naphthenic acid grades sustain higher margin pools due to specialized applications in tire rubber compounding and grease manufacturing, while light naphthenic acid competes on volume in bulk surfactant and paint additive markets. Specialty and purified grades are capturing expanded share in personal care and automotive end uses where low-color and low-odor specifications command premium positioning.
EPA regulations under the Toxic Substances Control Act constrain allowable impurity profiles in U.S.-distributed naphthenic acid formulations, while REACH registration requirements in Europe mandate full substance characterization for import authorization. China's MEE enforces escalating wastewater discharge standards that affect refinery-derived acid production economics. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation costs and qualification timelines.
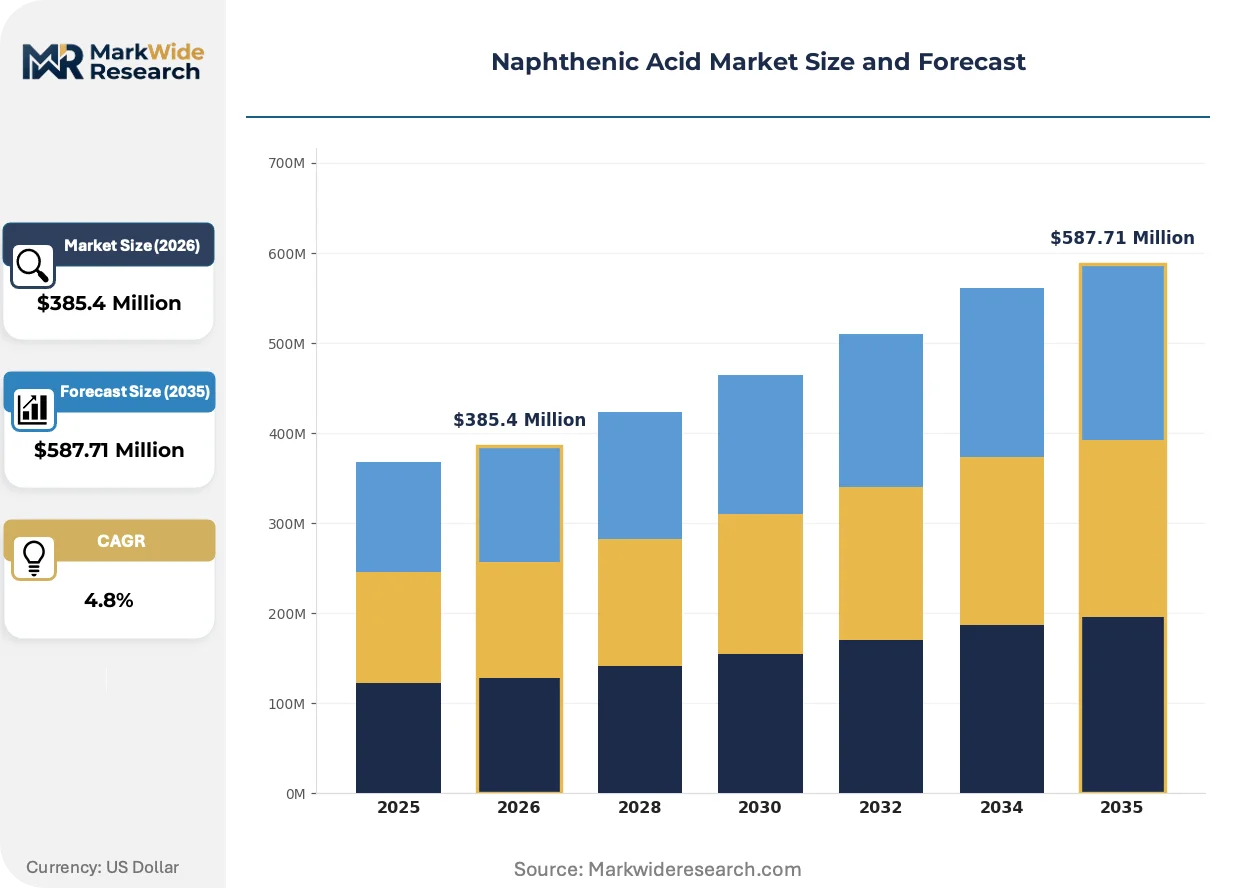
Market Dynamics
Specialty grade specifications are tightening across automotive and personal care end uses, compressing margins for undifferentiated producers while rewarding purification investments. Refinery output concentration in China and North America is reshaping supply availability for downstream formulators.
Growth Catalysts
- Automotive corrosion inhibitor demand:Specialty naphthenic acid grades are penetrating EV battery thermal management fluids and underbody coatings as OEMs reformulate for extended vehicle lifecycles.
- REACH substance characterization:European import authorization requirements are filtering out low-purity suppliers, creating qualification barriers that benefit registered producers with full dossier compliance.
- China refinery scaling:Domestic petrochemical complexes in Liaoning and Shandong are expanding acid fractionation capacity, reducing import dependency for downstream metal soap manufacturers.
Market Restraints
- Crude slate volatility:Naphthenic crude availability fluctuates with North Sea and West African production decisions, creating feedstock cost instability for acid refiners.
- Substitution by synthetic carboxylic acids:Sebacic acid and azelaic acid from bio-based routes are displacing light naphthenic grades in surfactant applications where color specifications permit.
- EPA impurity constraints:Toxic Substances Control Act enforcement on polynuclear aromatic hydrocarbon content is forcing reformulation costs for U.S.-distributed industrial grades.
Strategic Opportunities
- Personal care grade purification:Low-odor, low-color specifications for cosmetic emulsifiers command premium positioning as formulators seek alternatives to oleic acid derivatives.
- India industrial chemical expansion:BIS certification adoption and domestic lubricant blending growth are creating entry points for acid suppliers with established Asia-Pacific logistics.
- Metal-organic precursor convergence:Cobalt and manganese naphthenate demand from battery cathode material synthesis is opening high-purity acid applications beyond traditional drier markets.
Industry Challenges
- ISO 9001 baseline qualification:Western buyer procurement systems now auto-reject suppliers lacking certified quality management, extending onboarding timelines for emerging market entrants.
- Refinery-to-acid integration complexity:Captive acid production requires sulfuric acid extraction unit investments that strain capital allocation against commodity margin environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Naphthenic Acid Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $587.71 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Naphthenic Acid, Heavy Naphthenic Acid, Specialty Naphthenic Acid, Purified Naphthenic Acid Application: Textiles, Paints, Rubber, Surfactants End User: Personal Care, Automotive, Chemicals, Coatings Delivery Mode: Bulk Delivery, Drums, IBC Totes, Customized Packaging |
| Companies Covered | Merichem Company, Merck KGaA, Haihang Industry Co. Ltd, Umicore Cobalt & Specialty Materials, Tokyo Chemical Industry Co. Ltd, Shenyang Zhang Ming Chemical Co. Ltd, Midas Chemical Company Limited, Shanghai Changfeng Chemical Industrial Factory, Anhui Fulltime Specialized Solvent & Reagent Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Naphthenic Acid Market Strategic Shifts & Innovations
Molecular separation technologies and regulatory substance tracking are fragmenting the competitive landscape into purity-tiered supply tiers. Formulators now specify acid grades by individual component profiles rather than traditional broad categories.
Membrane filtration and molecular distillation systems are bifurcating the market into commodity and ultra-pure supply streams. Automotive thermal fluid manufacturers are adopting component-specified acid blends. The technology is compressing volumes for traditional acid-refined grades while expanding addressable market for purified fractions.
REACH registration deadlines and EPA TSCA section 8(e) reporting obligations are forcing substance-level transparency across supply chains. Importers must now disclose full compositional data to maintain market access. Specialty grade producers with existing dossier investments are capturing share from unregistered competitors in European and U.S. markets.
Specification-driven procurement is consolidating buyer relationships around certified suppliers with documented impurity profiles. Industrial lubricant blenders are reducing approved vendor lists from regional distributors to integrated refinery operators. China and Germany display the most pronounced concentration, with state-owned refiners and integrated chemical groups securing multi-year supply agreements.
Naphthenic Acid Market Segmentation
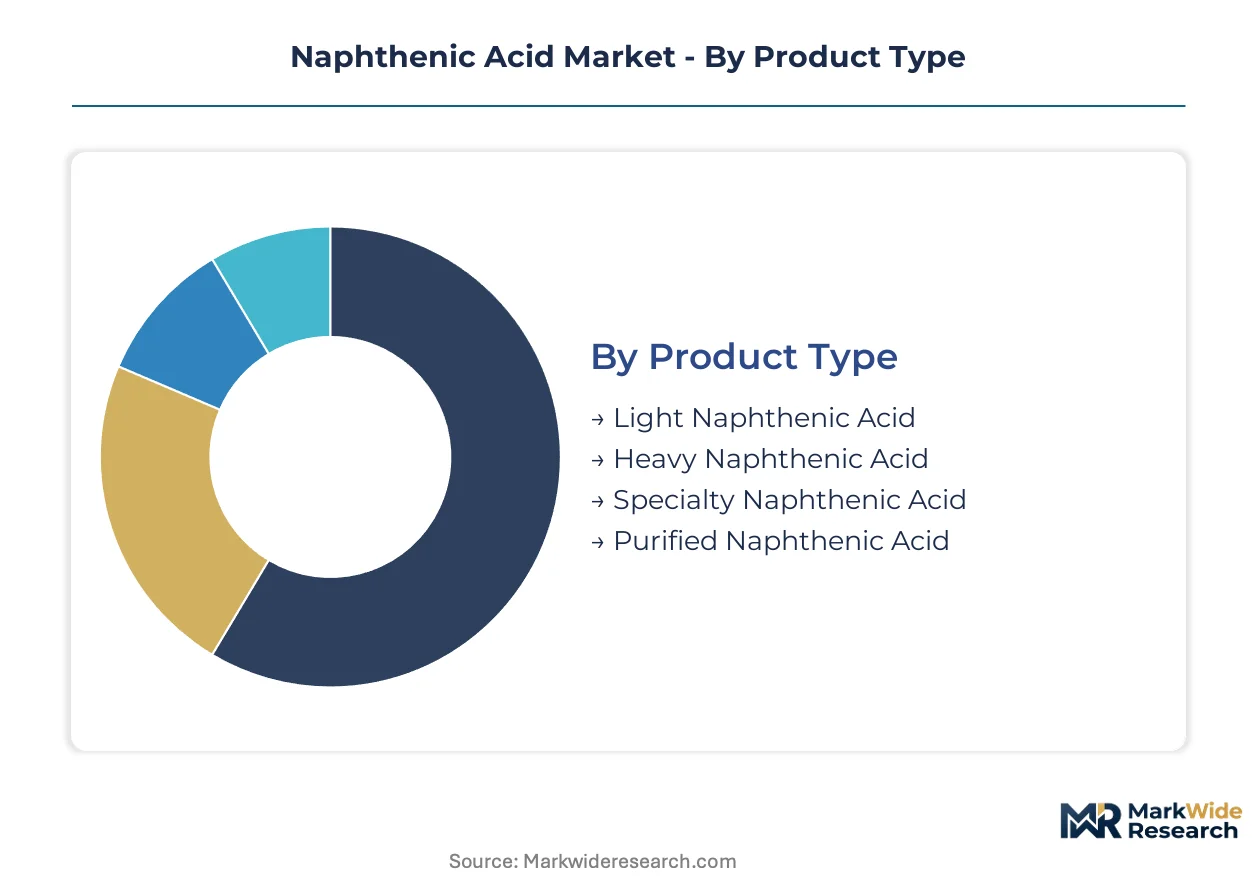
Naphthenic acid producers navigate divergent specification requirements across automotive, personal care, and industrial chemical channels. Segmentation by purity grade and delivery format determines margin capture and regulatory compliance pathways in fragmented downstream markets.
Product Type:
Domestic refinery output in China concentrates heavy and light grades, while specialty and purified variants flow through export-oriented purification facilities in Germany and the United States.
- Light Naphthenic Acid:Lower molecular weight fractions with 8–12 carbon chains serve bulk surfactant and paint additive formulations. Demand clusters in Shandong Province's chemical processing corridor where domestic soap manufacturers source feedstock for cost-sensitive detergent applications.
- Heavy Naphthenic Acid:Higher molecular weight species with 13–20 carbon atoms sustain tire rubber compounding and grease manufacturing. Liaoning refinery complexes supply domestic automotive sealant producers, though EPA polynuclear aromatic hydrocarbon constraints limit U.S. import volumes of unrefined grades.
- Specialty Naphthenic Acid:Controlled impurity profiles for automotive corrosion inhibitors and metal-organic precursors.
- Purified Naphthenic Acid:Ultra-low color and odor specifications for personal care emulsifier markets.
Heavy naphthenic acid commands the established base. The steepest expansion runs through purified grades.
Application:
Cost tier differentiation separates commodity surfactant volumes from specification-driven rubber and coatings segments.
- Textiles:Fiber lubricant and softening agent applications in polyester and nylon processing. Jiangsu Province's textile belt consumes drum-packaged light grades for spinning oil formulations.
- Paints:Drier metal soap production for alkyd resin curing dominates volume. REACH-registered cobalt and manganese naphthenates penetrate European architectural coatings as lead-free alternatives.
- Rubber:Tire compounding and conveyor belt manufacturing anchor heavy grade consumption.
- Surfactants:Bulk emulsifier and dispersant intermediate for industrial cleaners.
Paint drier applications anchor volume throughput. Rubber compounding is climbing the fastest as tire manufacturers reformulate for durability specifications.
End User:
Customer type fragmentation splits procurement between multinational formulators with ISO 9001 mandates and regional blenders prioritizing bulk pricing.
- Personal Care:Cosmetic emulsifier demand for low-odor, low-color purified grades. Formulators in France and Germany specify REACH-compliant fractions as oleic acid alternatives.
- Automotive:EV battery thermal management fluids and underbody corrosion coatings drive specialty grade qualification. OEM thermal fluid specifications now require component-level acid profiling.
- Chemicals:Metal soap and catalyst precursor manufacturing for industrial driers.
- Coatings:Marine and protective paint formulations for infrastructure and shipping.
Chemicals processing represents the volume foundation. Personal care is gaining share fastest on premium positioning.
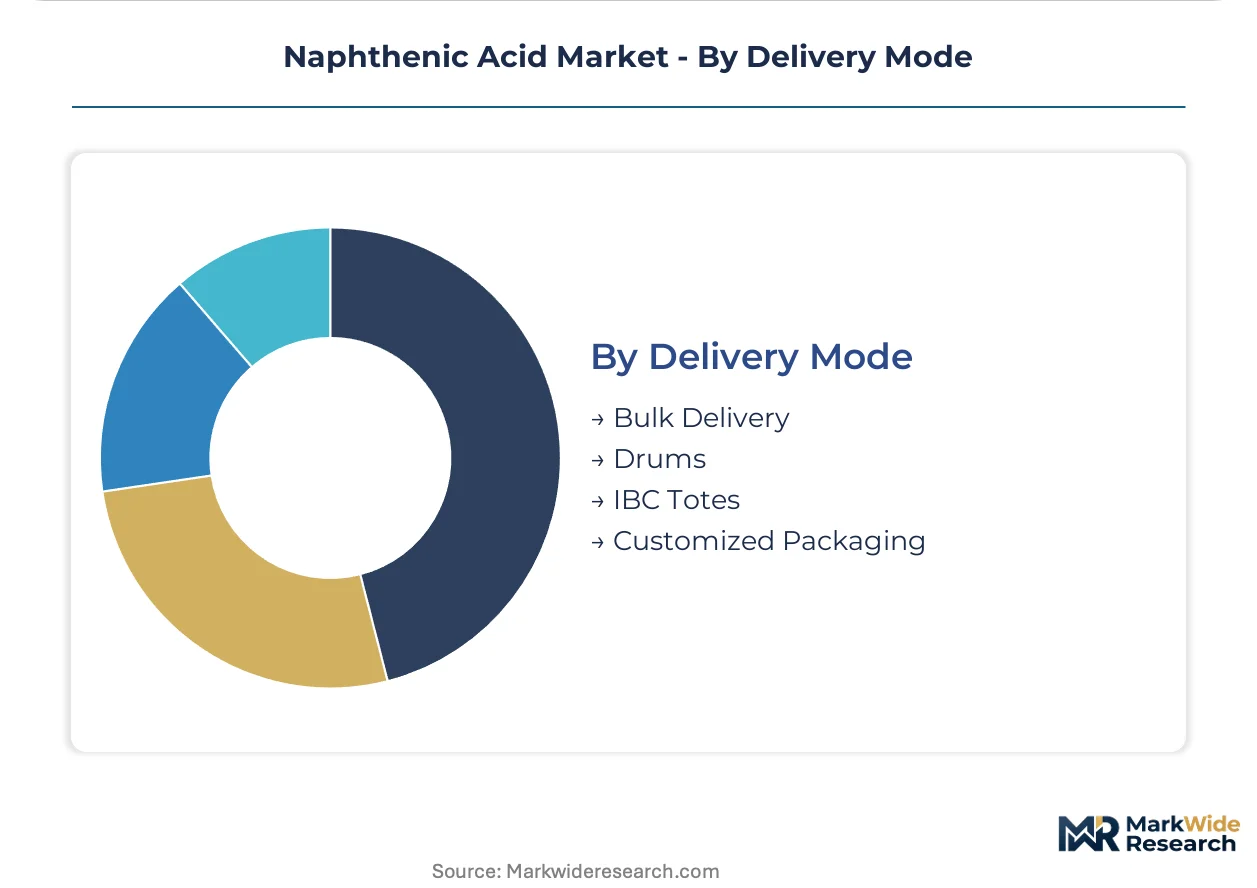
Delivery Mode:
Supply concentration in coastal refinery zones shapes logistics economics across packaging tiers.
- Bulk Delivery:Tanker and railcar shipments for high-volume surfactant and rubber compounders. Dalian and Qingdao port terminals enable cost-efficient coastal distribution to Korean and Japanese formulators.
- Drums:Standard 200-liter steel packaging for mid-scale coatings and textile processors.
- IBC Totes:Intermediate bulk containers for chemical manufacturers with just-in-time inventory systems.
- Customized Packaging:Nitrogen-blanketed totes and dedicated tankers for moisture-sensitive purified grades.
Bulk delivery commands the established base. Customized packaging shows the steepest expansion trajectory as personal care and battery material specifications tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial buyers cluster around integrated refinery zones where acid fractionation capacity connects to downstream metal soap and drier manufacturing. Procurement patterns favor suppliers with documented impurity profiles and ISO 9001 certification. Geographic concentration follows coastal petrochemical corridors with established logistics infrastructure.
China
Liaoning and Shandong provinces host expanding acid fractionation capacity serving domestic tire rubber and grease manufacturers. MEE wastewater discharge standards escalate production costs for refinery-derived acid operations. Dalian and Qingdao port terminals enable bulk distribution to Korean and Japanese formulators seeking cost-competitive heavy grades.
United States
Gulf Coast refineries supply specialty grades for automotive corrosion inhibitor and EV thermal fluid applications. EPA TSCA section 8(e) reporting obligations enforce polynuclear aromatic hydrocarbon disclosure across import channels. Merichem Company leverages integrated infrastructure across Texas and Louisiana supply corridors.
Germany
Ruhr Valley chemical clusters consume REACH-registered cobalt and manganese naphthenates for architectural coatings. ECHA substance characterization requirements filter unregistered suppliers from European import authorization. BASF and Lanxess downstream operations in Ludwigshafen anchor specialty acid demand for metal-organic precursors.
India
Gujarat and Maharashtra lubricant blenders drive light grade consumption for cost-sensitive surfactant formulations. BIS certification adoption creates qualification barriers for uncertified imports. Reliance Industries' Jamnagar refinery complex evaluates captive acid extraction for domestic metal soap manufacturers.
Japan
Chubu and Kansai industrial belts source purified grades for precision electronics and automotive coatings. METI chemical substance management frameworks align with REACH-equivalent disclosure standards. Tokyo Chemical Industry Co. Ltd distributes through established technical chemical channels serving battery material researchers.
Naphthenic Acid Market Key Industry Players
Player mix skews toward integrated refinery operators and export-oriented purification specialists. Market structure concentrates around three archetypes: captive producers with backward integration into crude fractionation, independent refiners serving regional bulk markets, and specialty purifiers targeting personal care and battery material specifications. Competitive moves center on membrane filtration technology licensing and multi-year supply agreements with automotive OEMs.
Within the integrated refinery tier, Merichem Company and Umicore Cobalt & Specialty Materials represent contrasting geographic anchors—Gulf Coast petrochemical infrastructure versus European metal-organic precursor integration. Shenyang Zhang Ming Chemical Co. Ltd occupies a position exemplifying domestic Chinese distribution dominance. Merck KGaA and Tokyo Chemical Industry Co. Ltd sit within the specialty chemical distributor archetype, channeling purified grades through technical sales networks rather than captive production.
| Leading Market Players |
|---|
| Merichem Company |
| Merck KGaA |
| Haihang Industry Co. Ltd |
| Umicore Cobalt & Specialty Materials |
| Tokyo Chemical Industry Co. Ltd |
| Shenyang Zhang Ming Chemical Co. Ltd |
| Midas Chemical Company Limited |
| Shanghai Changfeng Chemical Industrial Factory |
| Anhui Fulltime Specialized Solvent & Reagent Co. Ltd |
| Others |
Cost & Logistics Intelligence
Capacity utilization at Liaoning and Shandong refinery complexes shapes price floors across heavy and light grade tiers, concentrating supply-side leverage among integrated operators while compressing margins for independent fractionators lacking backward integration into crude sourcing.
Pricing Analysis
Cost-plus contracts with naphthenic crude indexation dominate procurement between Chinese refiners and Korean rubber compounders. Three-tier pricing structure across purified, specialty, and industrial grades reflects REACH certification status and ISO 9001 documentation depth. Cost compression in light grades intensifies as bio-based sebacic acid displaces volume in surfactant applications. Regional blenders in India exhibit highest price sensitivity, while European automotive OEMs prioritize specification compliance over unit cost.
Supply Chain Analysis
Inventory cycles for moisture-sensitive purified grades extend lead times to six weeks for nitrogen-blanketed totes. Supply concentrates in China, the United States, and Germany, with Dalian and Qingdao ports serving as export hubs. Feedstock draws from North Sea and West African naphthenic crude streams, with sulfuric acid extraction units representing critical capital bottlenecks. Single-source vulnerability runs through Liaoning refinery concentration for heavy grades. Distribution runs through integrated refinery operators with captive acid fractionation rather than merchant distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as specification-driven procurement splits demand between commodity bulk volumes and premium purified grades, with automotive thermal fluid and personal care emulsifier requirements creating defensible niche positions for qualified suppliers.
For Market Incumbents: Secure multi-year supply agreements with automotive OEMs thermal fluid programs before secondary purifiers achieve qualification. Deepen backward integration into membrane filtration technology licensing to defend margin position against emerging Chinese specialty producers. Lock in cobalt and manganese naphthenate offtake with battery cathode material manufacturers as metal-organic precursor demand accelerates. For New Entrants and Emerging Players: Anchor in India's Gujarat lubricant blending corridor where BIS certification gaps create qualification windows for ISO 9001-ready suppliers. Target personal care grade purification as the most penetrable tier, leveraging low-odor specifications that command premium positioning over oleic acid alternatives. Pursue technical partnership routes with established German distributors rather than direct refinery competition. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialty purifiers with REACH dossier investments and automotive OEM qualification. Long-term viability favors integrated operators with captive crude fractionation and downstream metal soap synthesis. Monitor EPA TSCA enforcement intensity as the critical inflection signal for U.S. import authorization barriers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crude Fractionation | Captive naphthenic acid supply secures margin control against feedstock volatility from North Sea production decisions. |
| Membrane Filtration Technology Licensing | Ultra-purification capability unlocks personal care and battery material specifications beyond commodity grade reach. |
| REACH Dossier Completion | Full substance characterization enables European import authorization while filtering unregistered competitors from supply chains. |
| Long-term Supply Agreement with Automotive OEMs | EV thermal fluid qualification creates multi-year revenue visibility as component-specified acid blends become mandatory. |
| Joint Venture with Metal Soap Manufacturers | Cobalt and manganese naphthenate integration captures battery cathode precursor demand beyond traditional drier markets. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, including refinery operations managers, downstream procurement leads at tire manufacturers, personal care formulators, and specialty chemical distributors. Secondary validation drew from customs trade data, ACC and Cefic industry reports, SEC 10-K filings from integrated chemical groups, and EPA TSCA substance tracking databases. Bottom-up volume estimates from individual refinery capacity were triangulated against top-down demand segmentation from end-use industry consumption patterns.
Across the analysis window, the forecasting framework modeled grade tier, end-use industry, packaging format, and regional production hub dimensions. CAGRs were derived from segment-level growth trajectory analysis rather than single-point extrapolation. Forecast inputs incorporated refinery capacity expansion announcements, REACH registration timelines, and automotive OEM thermal fluid specification evolution.
Decision-makers should treat outputs as directional under assumptions of sustained crude slate availability and regulatory enforcement continuity; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Multi Component Injection Moulding Technology Market
Industrial Chemicals
US Anhydrous Hydrogen Fluoride Market
Industrial Chemicals
Global Phosphate Esters Market
Industrial Chemicals
Pulp and Paper Enzymes Market
Industrial Chemicals
South America Starch Derivatives Market
Industrial Chemicals
Global Biochemical Market
Industrial Chemicals
Metal Removal Fluids Market
Industrial Chemicals
1-Octanol Market
Industrial Chemicals
Europe Isocyanates Market
Industrial Chemicals
Wood Preservative Market
Industrial Chemicals
Urea Strippers Market
Industrial Chemicals
Anhydrous Ammonia Storage Tank Market
Industrial Chemicals
Rotomolding Powder Market
Industrial Chemicals
Diisononyl Phthalate (DINP) Market
Industrial Chemicals
Hydro Fluorocarbon Market
Industrial Chemicals
Chrome Plating Market