
 Cosmetic Grade Warming Agents Market | 2026-2036
Cosmetic Grade Warming Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetic Grade Warming Agents Market Analytics
Specialized cosmetic chemists with thermogenic formulation expertise is bifurcating the competitive landscape as brands race to patent warming delivery systems. Symrise AG leverages its fragrance-actives integration platform to cross-sell warming agents into prestige skin care lines. Croda International Plc anchors its position through lipid-based warming technologies derived from sustainable feedstocks. Givaudan competes by extending its sensory modifier portfolio into clean-label warming solutions for indie beauty brands.
Cosmetic grade warming agents comprise thermogenic compounds—typically vanillyl butyl ether, capsaicin derivatives, or gingerol extracts—engineered to produce controlled cutaneous warming at concentrations between 0.1% and 2.0% w/w without irritation. These actives function by activating transient receptor potential vanilloid channels to enhance microcirculation and product absorption in topical applications. Gels and creams command the largest volume share due to their compatibility with leave-on facial and body formulations, while oils represent the fastest-expanding format as massage and aromatherapy segments gain traction. Natural ingredient sourcing dominates premium positioning, though synthetic vanillyl butyl ether sustains cost-competitive supply for mass-market hair care and body treatment launches.
REACH registration requirements govern thermogenic additive safety dossiers across European supply chains, while FDA cosmetic ingredient scrutiny under the Modernization of Cosmetics Regulation Act elevates toxicological documentation burdens for US market entry. ISO 16128 natural origin standards and ECHA skin sensitization protocols further stratify product qualification tiers between premium and commodity warming agents. Stakeholders must monitor evolving preservative-warming agent incompatibility data and pre-empt reformulation cycles before regulatory deadlines compress development timelines.
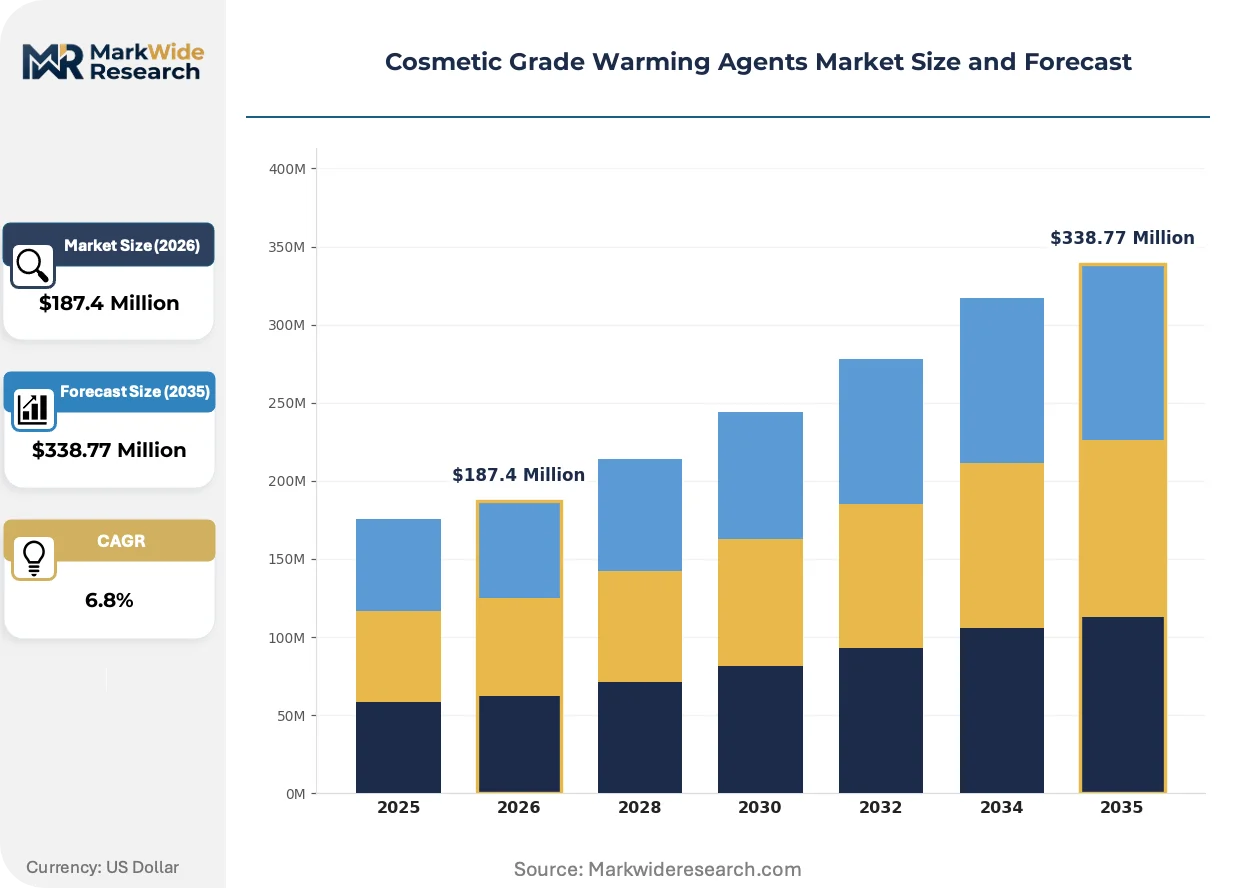
Market Dynamics
REACH registration dossiers and FDA cosmetic ingredient scrutiny under MoCRA are compressing supplier qualification timelines while wellness tourism recovery in Southeast Asia accelerates thermogenic active demand across spa and professional treatment channels.
Growth Catalysts
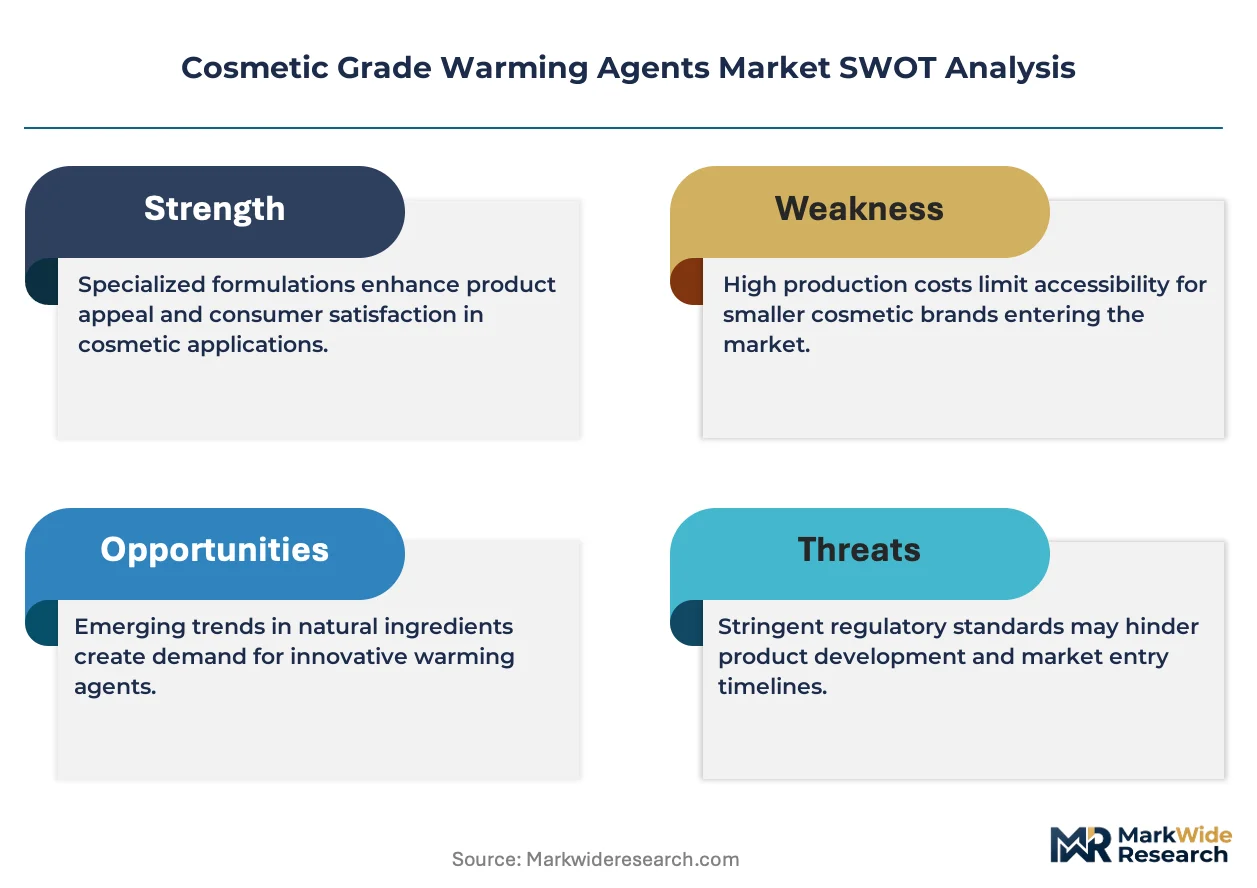
- Wellness tourism infrastructure:Southeast Asian spa destinations in Thailand, Indonesia, and Vietnam are rebuilding treatment menus with thermogenic body wraps and massage protocols that specify cosmetic-grade warming agents at precise concentrations.
- K-beauty routine expansion:South Korean multi-step skin care regimens now integrate warming essences and ampoules as penetration enhancers, creating pull-through demand for vanillyl butyl ether and gingerol extracts in leave-on facial formats.
- ISO 16128 natural origin certification:Premium positioning strategies increasingly require documented natural origin percentages, driving reformulation investment toward plant-derived thermogenic actives that meet ECHA skin sensitization protocols.
Market Restraints
- Capsaicin supply concentration:Botanical extraction capacity for natural capsaicin concentrates in India and China creates input cost volatility when harvest yields fluctuate or climate disruptions affect Capsicum annum cultivation cycles.
- Preservative-warming agent incompatibility:Formulation stability testing reveals unexpected interactions between phenoxyethanol-based preservation systems and vanillyl butyl ether, forcing extended compatibility studies that delay product launches.
- Synthetic substitute price floors:Petrochemical-derived warming agents from Asian contract manufacturers establish cost-competitive baselines that compress margin structures for natural-origin suppliers targeting premium positioning.
Strategic Opportunities
- Men's grooming penetration:Underdeveloped thermogenic active use in male-targeted beard oils, pre-shave treatments, and scalp therapies offers first-mover positioning as grooming brands seek sensory differentiation beyond cooling menthol conventions.
- EU Green Deal alignment:REACH-registered suppliers with documented carbon footprint reductions and bio-based feedstock chains qualify for preferential procurement from cosmetics groups with Science Based Targets initiative commitments.
- Professional channel direct supply:Bypassing traditional distribution through certified aesthetician training programs and spa-exclusive product lines captures margin currently allocated to multi-brand beauty distributors.
Industry Challenges
- Thermogenic formulation chemist scarcity:Specialized expertise in transient receptor potential channel activation kinetics and irritation threshold modeling remains concentrated among legacy fragrance-flavor houses, limiting independent brand access.
- MoCRA toxicological documentation:FDA's expanded safety substantiation requirements for topical sensory ingredients demand new clinical endpoint studies that extend qualification timelines by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetic Grade Warming Agents Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gels, Creams, Lotions, Oils Ingredient Source: Natural, Synthetic, Organic, Inorganic Application: Skin Care, Hair Care, Body Treatment, Spa Products Packaging Type: Tubes, Bottles, Jars, Sachets |
| Companies Covered | Symrise AG, Givaudan, BASF SE, Croda International Plc, Ashland Global Holdings Inc., Evonik Industries AG, Clariant AG, Dow Inc., DSM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetic Grade Warming Agents Market Evolving Landscape
Microencapsulation technologies and bio-fermentation pathways are redefining warming agent delivery precision, while regulatory data requirements and procurement model evolution reshape competitive positioning across premium and mass-market tiers.
Encapsulated vanillyl butyl ether systems with melamine-formaldehyde or polysaccharide shells enable time-release warming profiles that extend sensory duration from minutes to hours. Prestige facial brands in South Korea and Japan are adopting these systems for overnight mask formulations. This technology is bifurcating the market between basic unencapsulated commodity supply and value-added delivery platform licensing.
ECHA's evolving skin sensitization assessment protocols under REACH are mandating additional in vitro test batteries for thermogenic actives previously qualified under older annexes. Small and mid-sized ingredient suppliers face disproportionate compliance cost burdens relative to integrated multinationals with existing toxicology infrastructure. The professional spa segment is responding by consolidating supplier relationships toward REACH-registered partners with complete safety dossiers.
Direct-to-aesthetician sampling and education platforms are displacing traditional ingredient distributor networks for thermogenic active promotion. Indie beauty founders in California and New York now source warming agents through vertically integrated suppliers offering formulation guidance alongside raw material supply. This channel shift concentrates most visibly among clean-label brands targeting Sephora's conscious beauty certification requirements.
Cosmetic Grade Warming Agents Market Segmentation
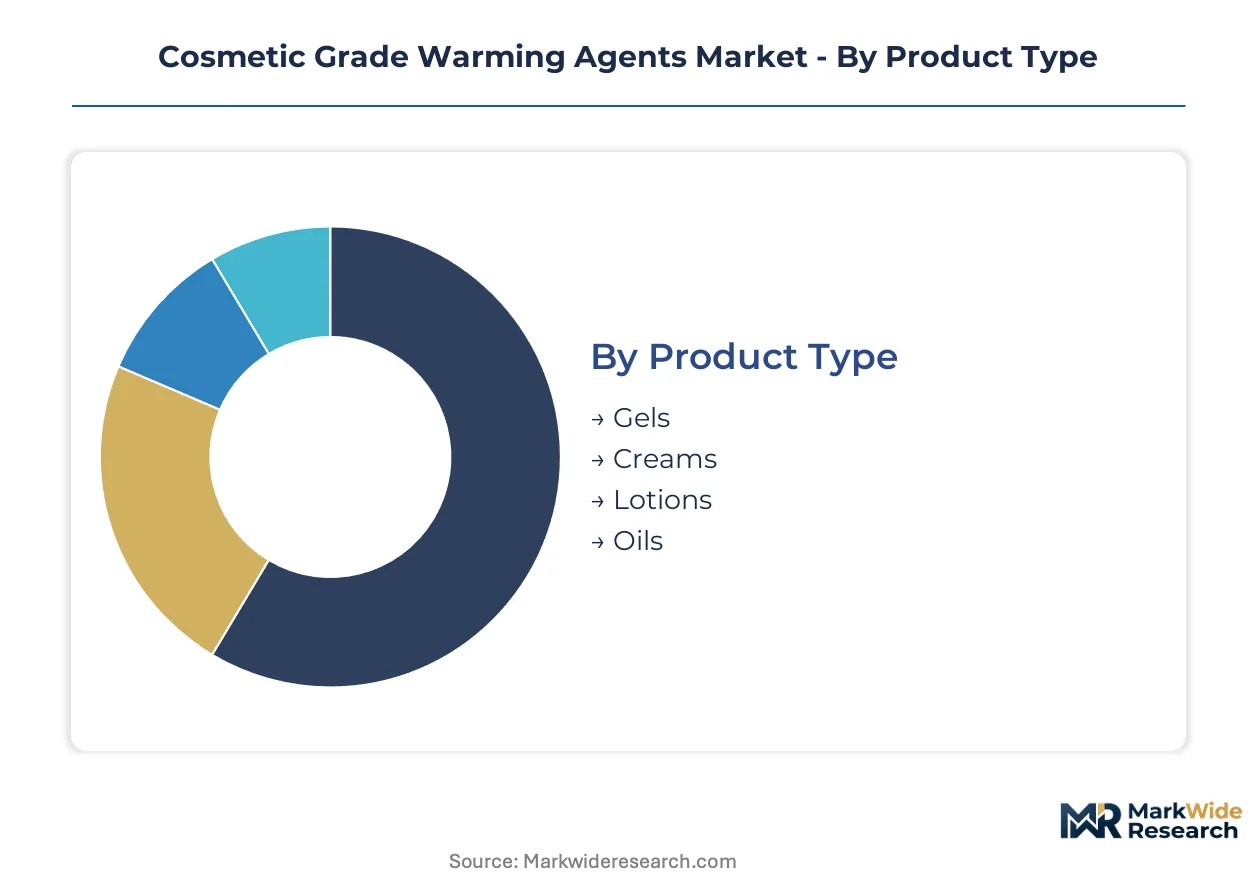
Formulation chemists segment cosmetic warming agents across four critical dimensions that determine sensory performance, regulatory pathway, and channel access. Each segmentation axis carries distinct substitution pressures as natural-origin positioning clashes with synthetic cost efficiency across global supply chains.
Product Type:
Substitute pressure concentrates most intensely in aqueous formats where water-based actives compete directly with anhydrous oil systems for massage and treatment applications.
- Gels:Hydrocolloid matrices suspend vanillyl butyl ether at precise viscosities for controlled spreadability across facial contours. South Korean essence-to-ampoule routines pull concentrated gel formats for multi-step layering protocols. Leave-on compatibility with phenoxyethanol preservation systems remains the critical technical hurdle.
- Creams:Oil-in-water emulsions dominate mass-market body treatment launches due to manufacturing scalability and familiar skin-feel expectations. Thai and Indonesian spa chains specify cream-based warming protocols for post-treatment home care continuity.
- Lotions:Lower viscosity aqueous systems serve pump-dispense hair care applications where scalp warming claims differentiate pre-wash treatments.
- Oils:Anhydrous carriers bypass preservative-warming agent incompatibility risks entirely while delivering extended thermogenic duration for professional massage modalities.
Creams retain volume leadership across retail channels; oils gain share fastest as professional spa procurement consolidates toward anhydrous stability.
Ingredient Source:
Cost tier stratification separates premium-positioned botanical extracts from commodity petrochemical derivatives serving price-sensitive hair care formulations.
- Natural:Gingerol concentrates from Zingiber officinale rhizomes and capsaicin from Indian Capsicum annum cultivations command ISO 16128-compliant positioning for Sephora Conscious Beauty and equivalent clean-label certifications. ECHA skin sensitization dossiers for botanical thermogenics extend qualification timelines by eight to fourteen months versus synthetic equivalents.
- Synthetic:Petrochemical-derived vanillyl butyl ether manufactured at scale across Chinese and Korean contract facilities establishes the cost floor that compresses margin structures for natural-origin competitors. REACH-registered synthetic supply chains offer the fastest US MoCRA compliance pathway.
- Organic:Certified organic ginger and chili extracts serve the narrow premium tier where Ecocert and COSMOS standards command measurable price premiums in German and French markets.
- Inorganic:Mineral-based warming technologies occupy niche professional channels where chemical sensitization concerns exclude organic actives from medical spa protocols.
Synthetic supply retains volume leadership across mass-market launches; natural-origin sourcing climbs fastest as K-beauty and clean-label indie brands reformulate for certification compliance.
Application:
Customer type divergence separates professional treatment specifications from retail self-application formats with distinct concentration and packaging requirements.
- Skin Care:Facial warming essences and overnight masks leverage microencapsulated delivery systems for time-release penetration enhancement. Japanese prestige brands lead adoption of melamine-formaldehyde shell technologies.
- Hair Care:Scalp warming treatments in pre-shampoo and mask formats represent the most underdeveloped application with first-mover opportunity for thermogenic differentiation beyond established menthol cooling conventions.
- Body Treatment:Home-use cellulite and firming creams incorporate thermogenic actives at higher concentrations than facial formats, driving volume concentration among mass-market personal care brands.
- Spa Products:Professional-only warming wraps and massage mediums specify precise TRPV1 activation thresholds calibrated to treatment duration, creating specification lock-in with trained aesthetician channels.
Body treatment applications retain volume leadership across retail distribution; spa products expand most quickly as Southeast Asian wellness tourism infrastructure rebuilds post-pandemic capacity.
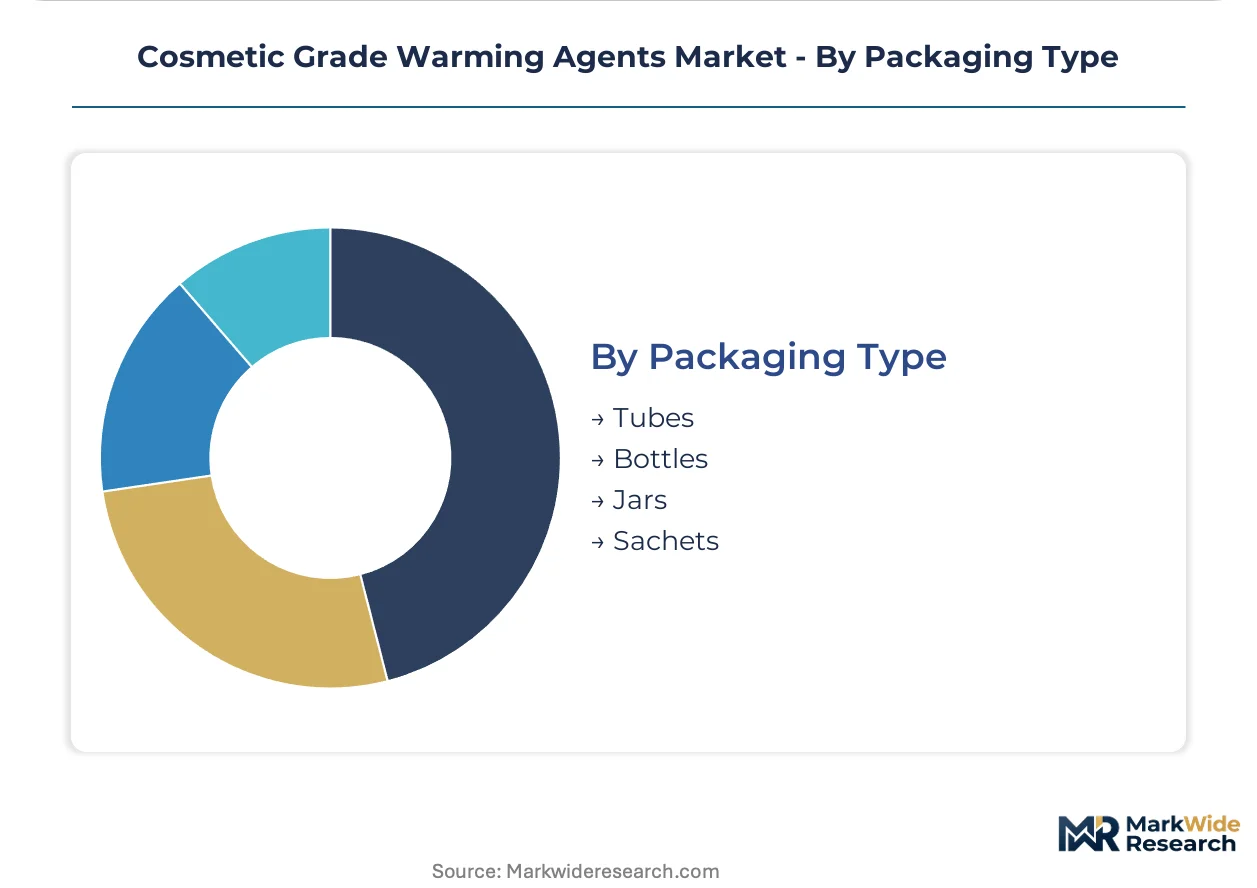
Packaging Type:
Supply concentration in tube and bottle manufacturing shapes format availability across regional production clusters.
- Tubes:Laminate and extruded plastic tubes dominate gel and cream formats for controlled dispensing precision in leave-on facial applications.
- Bottles:Pump and flip-cap bottles serve lotion and oil viscosities across hair care and body treatment segments with established filling line compatibility.
- Jars:Wide-mouth containers accommodate thick cream and balm textures for professional spa bulk supply and premium retail positioning.
- Sachets:Single-use foil pouches enable sampling programs and travel-size distribution for hotel amenity and airline amenity channels.
Tubes retain volume leadership across facial and body care launches; sachets climb fastest as direct-to-aesthetician sampling platforms displace traditional distributor networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA cosmetic ingredient scrutiny under MoCRA anchors United States market entry protocols, while REACH-registered supply chains govern European qualification timelines. South Korean MFDS standards and K-beauty formulation conventions concentrate thermogenic active demand in Seoul's innovation corridor.
United States
MoCRA toxicological documentation requirements compress supplier qualification timelines for topical sensory ingredients. FDA's expanded safety substantiation mandates extend development cycles by twelve to eighteen months. California-based indie beauty brands drive clean-label warming agent procurement through Sephora's Conscious Beauty certification pathway.
South Korea
MFDS cosmetic regulations align with K-beauty multi-step routines integrating thermogenic essences and ampoules. Seoul Capital Area formulators patent microencapsulated delivery systems for overnight mask applications. Busan-Ulsan manufacturing clusters scale vanillyl butyl ether production for regional export.
Germany
ECHA skin sensitization protocols under REACH stratify natural-origin warming agents into premium qualification tiers. Bavarian fragrance-flavor houses leverage existing toxicology infrastructure for compliance cost advantages. Frankfurt-Rhine-Main distribution hubs consolidate EU Green Deal-aligned procurement for carbon-footprint-certified supply chains.
China
SAMR cosmetic ingredient registration and GB standards govern thermogenic active import and domestic manufacture. Yangtze River Delta contract manufacturers establish synthetic vanillyl butyl ether cost floors that compress global margin structures. Zhejiang and Jiangsu provinces concentrate petrochemical-derived warming agent capacity.
Thailand
Wellness tourism recovery in Phuket and Bangkok spa destinations rebuilds treatment menus specifying cosmetic-grade warming agents. Thai FDA cosmetic regulations harmonize with ASEAN cosmetic directive frameworks. Chonburi and Rayong industrial estates host contract manufacturing for regional body treatment exports.
Cosmetic Grade Warming Agents Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with fragrance-flavor multinationals commanding formulation expertise and Asian contract manufacturers anchoring synthetic supply. The vendor base separates into REACH-registered integrated players, bio-fermentation specialists, and petrochemical-scale commodity suppliers. Three strategic archetypes dominate: sensory platform licensors, sustainable feedstock innovators, and direct-to-aesthetician vertical suppliers. Competitive moves concentrate on microencapsulation technology licensing and carbon-footprint certification for EU Green Deal procurement eligibility.
Within the integrated sensory platform tier, Symrise AG and Givaudan represent archetypes of fragrance-actives convergence, while Croda International Plc exemplifies lipid-based sustainable feedstock positioning. These three companies anchor different vectors of competitive differentiation—Symrise through cross-selling integration, Givaudan through clean-label extension, and Croda through bio-based technology claims—without any single archetype commanding unified market control.
| Leading Market Players |
|---|
| Symrise AG |
| Givaudan |
| BASF SE |
| Croda International Plc |
| Ashland Global Holdings Inc. |
| Evonik Industries AG |
| Clariant AG |
| Dow Inc. |
| DSM |
| Others |
Value Network & Pricing Analysis
Synthetic vanillyl butyl ether substitution for natural capsaicin extracts simultaneously redraws supply geography toward Chinese and Korean petrochemical clusters while compressing margin structures for botanical extractors across India and Southeast Asia. This displacement dynamic forces natural-origin suppliers to recertify under ISO 16128 and ECHA protocols to defend premium positioning against commodity cost floors.
Pricing Analysis
Chinese contract manufacturers quote synthetic warming agents at 40-60% discounts to Indian botanical extracts, creating geographic price spreads that stratify procurement decisions. Three-tier pricing structure across premium natural-origin, standard synthetic, and economy unregistered grades dominates qualification pathways. Pricing pressure stems from Yangtze River Delta capacity additions flooding spot markets with REACH-registered synthetic supply. Mass-market hair care brands exhibit highest price sensitivity, while Seoul-based prestige facial brands absorb premiums for microencapsulated delivery systems.
Supply Chain Analysis
China and South Korea anchor synthetic vanillyl butyl ether manufacturing across Zhejiang, Jiangsu, and Busan-Ulsan chemical estates. Raw material flows draw from para-cresol feedstocks and methanol derivatives sourced through integrated petrochemical complexes. Single-source vulnerability concentrates in Indian Capsicum annum harvests supplying natural capsaicin to European fragrance-flavor houses. Distribution runs through ASEAN cosmetic ingredient distributors serving Thai and Indonesian spa chains, with direct-to-aesthetician platforms displacing traditional wholesale channels in North American indie beauty segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as wellness tourism infrastructure rebuilds across Southeast Asia and K-beauty routines integrate thermogenic penetration enhancers at unprecedented rates.
For Market Incumbents: Secure REACH-registered toxicology dossiers ahead of MoCRA enforcement waves to compress competitor qualification timelines by twelve to eighteen months. Defend margin structures through captive bio-fermentation capacity for natural-origin gingerol extracts, insulating against Chinese synthetic price floors while serving Sephora Conscious Beauty certification requirements. For New Entrants and Emerging Players: Anchor in men's grooming white space where beard oils and scalp therapies remain thermogenically underpenetrated versus established menthol conventions. Target direct-to-aesthetician sampling platforms displacing traditional distributor networks, leveraging formulation guidance services as differentiation against commodity suppliers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed bio-fermentation specialists holding carbon-footprint-certified supply chains aligned with EU Green Deal procurement criteria. Five-to-ten year viability hinges on MoCRA compliance infrastructure scalability. Monitor FDA guidance publication velocity as inflection signal for toxicological documentation cost curves.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Licensing | Seoul-based prestige brands patent melamine-formaldehyde shell systems for overnight mask duration extension. |
| Backward Integration into Bio-Fermentation | Croda International Plc secures captive gingerol supply chains exempt from Indian harvest volatility. |
| REACH Registration Pre-Investment | Symrise AG leverages existing toxicology infrastructure to compress ECHA skin sensitization timelines versus mid-tier competitors. |
| Direct-to-Aesthetician Platform Launch | California indie beauty founders bypass multi-brand distributors through vertically integrated supplier education programs. |
| Carbon-Footprint Certification Program | EU Green Deal alignment qualifies preferential procurement from cosmetics groups with Science Based Targets commitments. |
Research Methodology
Cross-validation between primary interviews with cosmetic formulation chemists, spa procurement directors, and regulatory affairs specialists and secondary validation through ECHA registration databases, FDA MoCRA guidance documents, and MFDS cosmetic ingredient filings anchors the qualitative findings. Bottom-up demand modeling triangulates against top-down supply capacity assessments across Chinese and Korean manufacturing clusters.
Sensitivity analysis frameworks test CAGRs across the projection horizon against variables including wellness tourism recovery velocity, MoCRA enforcement timing, and natural harvest yield fluctuations. Segmentation dimensions span product type, ingredient source, application, and packaging format alongside regulatory qualification tier. Industry-specific inputs incorporate transient receptor potential channel activation kinetics and preservative-warming agent compatibility matrices.
Underlying assumptions cover REACH registration continuity, MFDS-K-beauty alignment stability, and Southeast Asian spa infrastructure rebuild rates, with deviation risk concentrated in FDA toxicological documentation timeline extensions and Indian climate disruption frequency. Recalibration cycles align with material shifts in MoCRA guidance publication, EU Green Deal procurement mandate expansion, and K-beauty routine evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Sun Protection Products Market
Cosmetic Chemicals
US Minoxidil Market
Cosmetic Chemicals
Cosmetic Kaolin Powder Market
Cosmetic Chemicals
Minoxidil API Market
Cosmetic Chemicals
Global Argireline Market
Cosmetic Chemicals
Sodium Methylparaben Market
Cosmetic Chemicals
Fractionated Shea Butter in Cosmetics and Personal Care Market
Cosmetic Chemicals
Hair Gloss Market
Cosmetic Chemicals
Asia Pacific Cosmetic Preservatives Market
Cosmetic Chemicals
Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Jojoba Oil Derivatives Market
Cosmetic Chemicals
Arbutin for Cosmetics Market
Cosmetic Chemicals
Global Skin Lightening Market
Cosmetic Chemicals
Shea Butter Market
Cosmetic Chemicals
Anti-Aging Products Market
Cosmetic Chemicals
Chemicals for Cosmetics and Toiletries Market