
 Silicon Metal Market | 2026-2036
Silicon Metal Market Size, Share, and Industry Trends Forecast 2026-2036
Silicon Metal Market Intelligence
Silicon carbide in power electronics is broadening the addressable market for high-purity silicon metal as electric vehicle inverters and renewable energy converters demand semiconductor-grade feedstock. Ferroglobe leverages integrated quartz mining and smelting assets across Spain, France, and South Africa to sustain cost leadership in European supply. Elkem ASA anchors its position through R&D intensity in carbon-neutral silicon production at its Norwegian facilities. Hoshine Silicon Industry Co., Ltd. dominates metallurgical-grade output through massive furnace scale in China's southwestern provinces.
Silicon metal is a crystalline metalloid element produced by carbothermic reduction of quartz in submerged-arc electric furnaces at temperatures exceeding 1,900°C, yielding material with purity grades from 98.5% to 99.99% depending on end-use requirements; primary applications span aluminum alloying, silicone chemistry, semiconductor wafers, and solar photovoltaic cells. Silicon metal in solar cell applications leads volume growth as polysilicon producers expand capacity to serve photovoltaic module manufacturers. Aluminum alloy applications remain the mature revenue base, though margin pools increasingly concentrate in chemical-grade and semiconductor-grade segments where purity premiums command structural price differentiation. Powdered and granular forms are gaining share in automated foundry and chemical processing lines that require precise dosing and reduced handling losses.
EPA emissions rules in the United States and China's MEE environmental compliance mandates are forcing smelter upgrades and reshaping cost structures across production networks. REACH registration requirements in Europe and RoHS material restrictions constrain impurity thresholds for silicon destined for electronics and automotive supply chains. Stakeholders must monitor carbon border adjustment mechanisms and low-carbon certification schemes as these frameworks increasingly determine market access and contract eligibility for silicon metal suppliers.
Market Dynamics
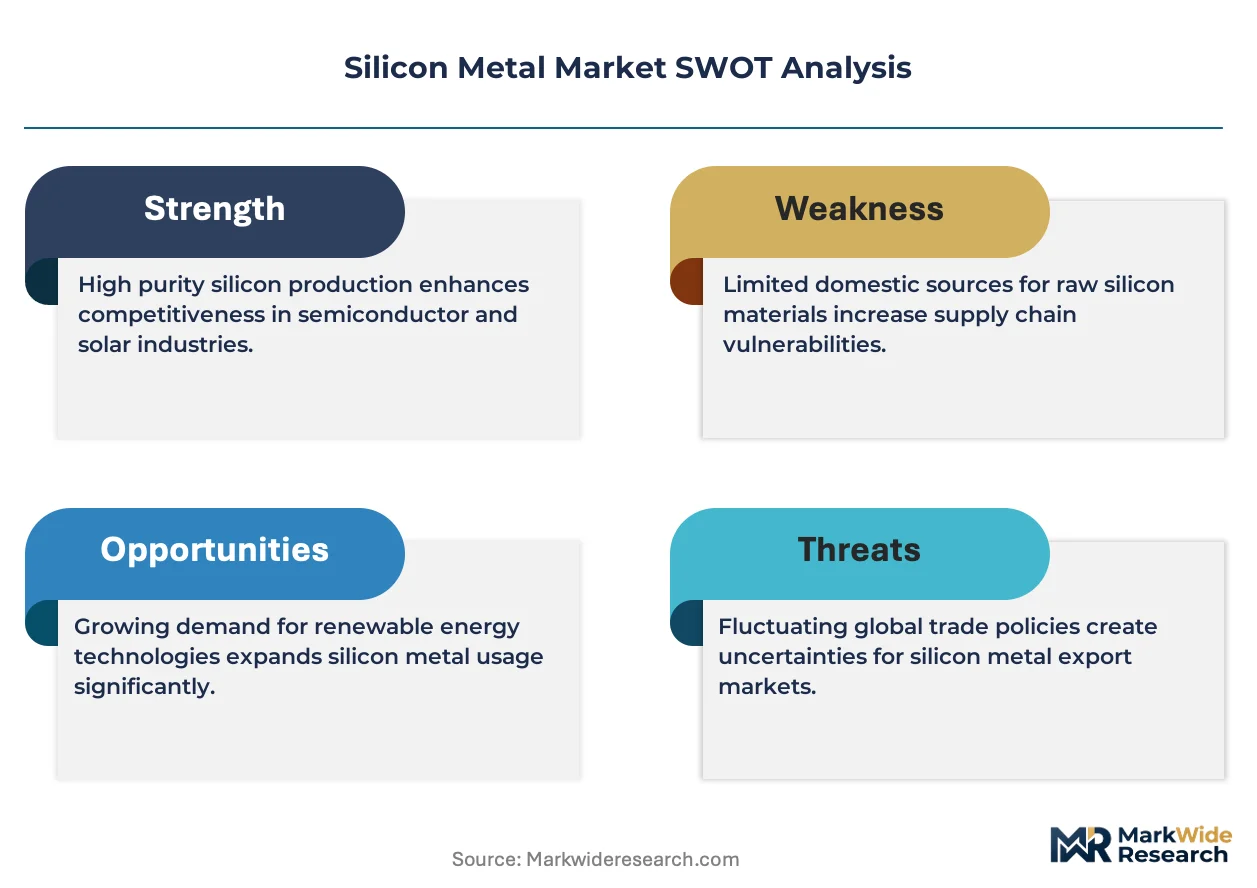
China's dual carbon goals are forcing smelter operators to abandon coal-powered furnaces and relocate to hydropower-rich southwestern provinces, compressing legacy capacity while rewarding low-carbon producers with preferential grid access and export eligibility.
Growth Catalysts
- Photovoltaic cell expansion:Polysilicon producers are scaling metallurgical-grade silicon procurement to feed ingot and wafer manufacturing lines serving module assembly plants.
- REACH registration compliance:European chemical-grade silicon buyers now mandate full substance dossiers, locking in qualified suppliers and creating switching costs for incumbents.
- Silicon carbide power electronics:Electric vehicle inverters and renewable energy converters demand semiconductor-grade feedstock, pulling high-purity silicon metal into automotive and grid-scale storage supply chains.
Market Restraints
- Quartz supply concentration:High-purity silica deposits cluster in limited geographies, exposing smelters to concentrate pricing volatility and long-haul logistics costs.
- Energy cost asymmetry:Submerged-arc furnace operations in coal-dependent regions face margin erosion against hydropower-based competitors in Yunnan and Xinjiang.
- Ferrosilicon substitution:Lower-grade silicon alloys capture some aluminum alloying applications where purity thresholds permit, capping price premiums in commodity segments.
Strategic Opportunities
- Carbon border adjustment mechanisms:EU CBAM implementation creates first-mover advantage for smelters with verified low-carbon production processes and lifecycle emissions documentation.
- Semiconductor reshoring:United States CHIPS Act incentives are pulling polysilicon purification capacity toward domestic wafer fabrication facilities, opening new demand nodes.
- Automotive silicones:Battery thermal management systems and electric powertrain encapsulation are expanding chemical-grade consumption in vehicle manufacturing.
Industry Challenges
- Smelter engineering talent scarcity:Submerged-arc furnace design and carbon electrode optimization require specialized metallurgical expertise that retiring workforces and limited university programs struggle to replenish.
- EPA emissions compliance timelines:United States smelters face compressed upgrade schedules for particulate and sulfur dioxide controls, forcing production curtailments during retrofit periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicon Metal Market |
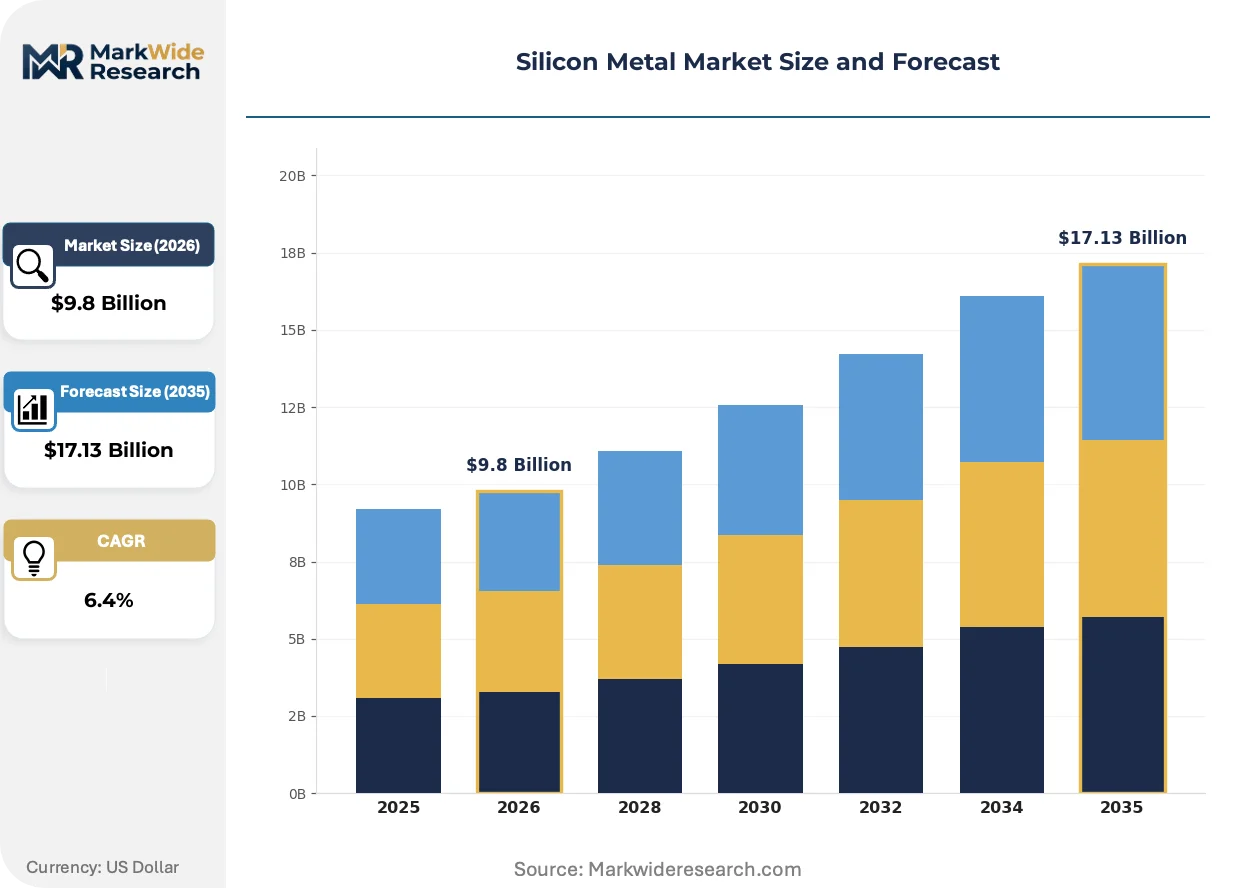
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.13 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicon Briquettes, Silicon Powder, Silicon Granules, Metal Silicon Application: Aluminum Alloys, Solar Cells, Chemicals, Steel Manufacturing Customer Type: Automakers, Solar Panel Manufacturers, Chemical Producers, Steel Companies Form: Chunk, Powdered, Granular, Alloy |
| Companies Covered | Ferroglobe, Elkem ASA, Hoshine Silicon Industry Co., Ltd., Dow, RIMA Industrial, Wacker Chemie AG, RusAL, Anyang Huatuo Metallurgy Co., Ltd., Mississippi Silicon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicon Metal Market Strategic Shifts & Innovations
Silicon metal production and consumption patterns are restructuring around energy decarbonization mandates, semiconductor supply chain security imperatives, and automated materials handling requirements in downstream processing.
Plasma-enhanced purification is electrifying the pathway from metallurgical-grade to solar-grade silicon by reducing energy intensity and carbon emissions in polysilicon feedstock preparation. Solar cell manufacturers in Southeast Asia are piloting plasma-based refining to bypass traditional Siemens process bottlenecks. This technology is compressing the cost gap between regional polysilicon producers and incumbent Chinese suppliers.
China's MEE environmental compliance mandates are forcing smelter consolidation and equipment upgrades across Shanxi and Inner Mongolia production bases. Facilities failing emissions intensity thresholds face operating license suspensions and exclusion from government procurement programs. Chemical-grade silicon destined for electronics and automotive supply chains now requires third-party verification of impurity thresholds under tightened enforcement protocols.
Automated dosing systems in aluminum foundries and silicone polymerization plants are displacing bulk ingot handling with precision-delivered granular and powdered silicon metal formats. Buyers in Germany and Japan are specifying particle size distributions and moisture specifications that legacy crushing operations cannot consistently achieve. This specification tightening is fragmenting supplier tiers between integrated powder processors and conventional ingot sellers.
Silicon Metal Market Segmentation
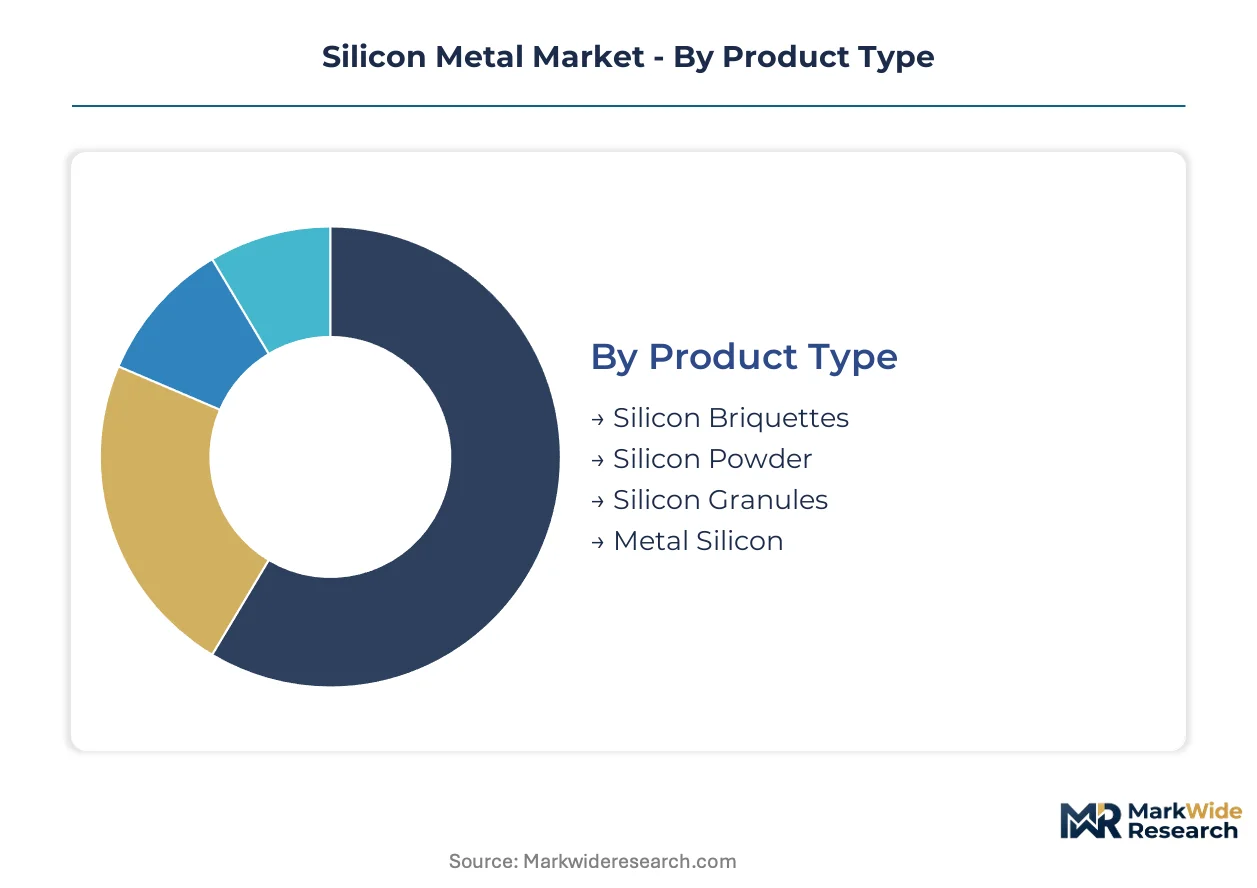
Silicon metal segmentation reveals how physical form and purity specifications determine integration depth across supply chains. Manufacturers configure product portfolios around furnace economics, downstream handling automation, and end-use certification requirements.
Product Type:
Integration depth varies sharply across product types, with some formats serving as direct feedstock while others require intermediate processing before entering final manufacturing stages.
- Metal Silicon:Standard ingot and lump forms produced directly from submerged-arc furnace reduction of quartz with carbon reductants. Aluminum smelters in China's Shandong province and Germany's Rhineland region source these primary forms for direct alloying operations where furnace-side addition tolerates irregular sizing.
- Silicon Powder:Atomized or milled particulate with controlled particle size distributions between 45 and 150 microns. Chemical-grade powder demand concentrates at silicone polymerization plants in Japan's Chiba prefecture and Germany's Bavaria region, where pneumatic conveying systems require precise flow characteristics and low moisture content.
- Silicon Granules:Spheroidized particles optimized for automated dosing systems in foundry operations. Steel mini-mills in Italy's Lombardy region specify narrow size fractions to minimize segregation during ladle metallurgy.
- Silicon Briquettes:Compacted forms combining silicon fines with binding agents for remelting efficiency. Secondary aluminum producers in Turkey's Kocaeli industrial zone favor briquettes to recover furnace dust while controlling melt chemistry.
Volume placements concentrate in Metal Silicon; the faster expansion belongs to Silicon Powder.
Application:
Application segments stratify by margin structure, with purity thresholds and certification burdens creating distinct commercial territories.
- Solar Cells:Metallurgical-grade silicon refined into polysilicon for photovoltaic ingot production. Ingot manufacturers in Vietnam's Thai Nguyen province and Malaysia's Sarawak state are expanding procurement as module assembly shifts toward Southeast Asia.
- Aluminum Alloys:Silicon additions between 5% and 20% by weight to improve castability and mechanical properties. Die-casting operations in Mexico's Queretaro state and Poland's Upper Silesia region consume standard-grade material for automotive structural components.
- Chemicals:Feedstock for silicone monomers, silanes, and fumed silica production. Dow Corning's manufacturing complex in Kentucky and Wacker Chemie's Burghausen facility in Germany anchor demand for low-boron, low-phosphorus grades.
- Steel Manufacturing:Deoxidizing agent and alloying addition for electrical steels. ArcelorMittal's integrated mills in Spain's Asturias region specify tightly controlled calcium and aluminum levels to prevent nozzle clogging during continuous casting.
Margin pools concentrate in Chemicals; Solar Cells is climbing the fastest.
Customer Type:
Customer segmentation tracks procurement sophistication, from commodity spot purchasing to long-term contracted supply with embedded technical services.
- Chemical Producers:Integrated silicone manufacturers requiring multi-year supply agreements with guaranteed impurity ceilings. Momentive Performance Materials and Shin-Etsu Chemical negotiate specifications covering trace elements to parts-per-billion thresholds.
- Solar Panel Manufacturers:Polysilicon producers and integrated photovoltaic companies procuring metallurgical-grade feedstock for ingot pulling. LONGi Green Energy and JA Solar anchor procurement volumes through offtake contracts with smelters in Yunnan province.
- Automakers:Aluminum foundry divisions and tier-one casting suppliers specifying silicon for engine blocks and structural components. Tesla's casting operations in Texas and Volkswagen's Kassel plant in Germany enforce automotive-grade certification protocols.
- Steel Companies:Integrated mills and specialty steel producers requiring deoxidation-grade silicon with flexible sizing. Nippon Steel's Yawata works and Tata Steel's Port Talbot facility manage inventory through quarterly tender processes.
Contract durations concentrate in Chemical Producers; Solar Panel Manufacturers is gaining share fastest.
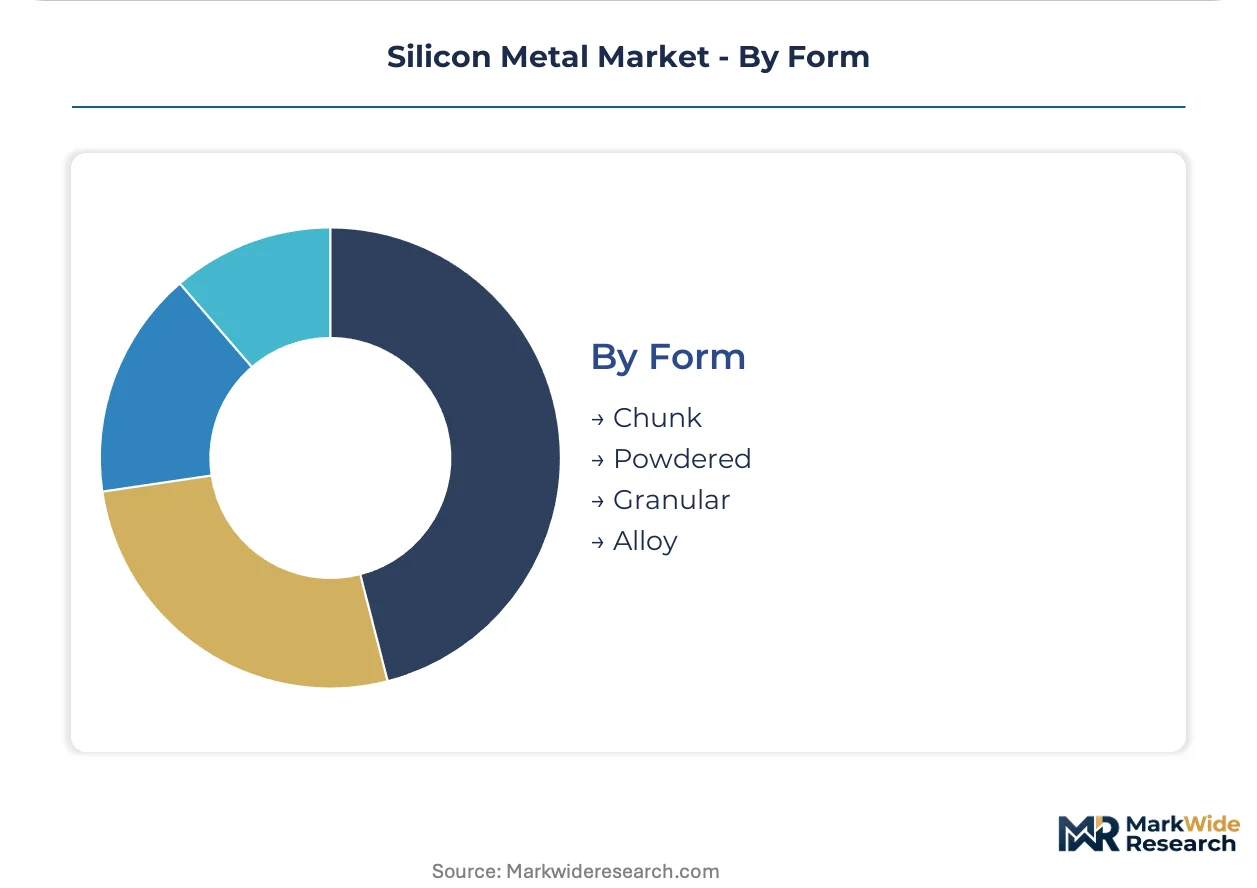
Form:
Physical form selection reflects materials handling infrastructure maturity and labor cost structures at consumption points.
- Chunk:Irregular furnace-cast pieces requiring manual or mechanical handling. Legacy foundries in India's Punjab region and Brazil's Minas Gerais state continue chunk consumption where automation investment lags.
- Powdered:Fine particulate for chemical reaction kinetics and pneumatic transport. Elkem's processing facilities in Norway and Ferroglobe's Spanish operations supply powder specifications meeting REACH registration dossier requirements.
- Granular:Uniform particles for automated weighing and conveying systems. BMW's light-metal foundry in Landshut, Germany specifies granular silicon for robotic dosing cells producing electric vehicle housing castings.
- Alloy:Pre-alloyed forms such as ferrosilicon or silicon-aluminum master alloys. Steelmakers in South Korea's Pohang complex and Turkey's Iskenderun bay prefer ferrosilicon where silicon recovery efficiency outweighs purity requirements.
Installed base concentrates in Chunk; Granular is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates over half of global silicon metal consumption through photovoltaic and aluminum alloying demand. Smelter investment gravitates toward southwestern provinces where hydropower availability shapes cost competitiveness.
China
Solar-grade polysilicon producers and aluminum foundries absorb the majority of domestic metallurgical-grade output. MEE environmental compliance mandates force smelter consolidation across Shanxi and Inner Mongolia, pushing capacity toward Yunnan and Xinjiang provinces where clean energy access secures operating licenses.
United States
Semiconductor wafer fabrication and automotive aluminum casting drive chemical-grade and metallurgical-grade procurement. EPA emissions rules compress upgrade timelines for submerged-arc furnace operations, forcing production curtailments during retrofit periods at facilities in the Southeast and Ohio River Valley.
Germany
Silicone polymerization plants and automotive foundries anchor European chemical-grade consumption. REACH registration requirements lock in qualified suppliers and create switching costs for incumbents serving Dow Corning's Burghausen complex and BMW's Landshut light-metal foundry.
Norway
Carbon-neutral silicon production R&D and hydropower-based smelting operations serve premium chemical-grade and semiconductor-grade segments. Elkem ASA anchors capacity at Norwegian facilities where renewable energy integration supports low-carbon certification schemes demanded by EU buyers.
Japan
Silicone monomer production and semiconductor materials processing concentrate demand in Chiba prefecture and Kyushu region. METI industrial policy incentives and JIS standards enforcement tighten impurity thresholds for silicon destined for electronics and automotive supply chains.
Silicon Metal Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated miners and standalone smelters occupying distinct competitive territories. The vendor base organizes around three strategic archetypes: integrated quartz-to-silicon operators controlling upstream feedstock, regional smelters leveraging localized energy access, and diversified chemical conglomerates backward-integrating into feedstock supply. Dominant competitive moves include capacity relocation toward low-carbon power zones and portfolio diversification into high-purity grades for semiconductor applications.
Among integrated mining and smelting specialists, Ferroglobe and Elkem ASA exemplify the European archetype of quartz asset control combined with furnace operations. Hoshine Silicon Industry Co., Ltd. occupies a position within the massive-scale metallurgical-grade tier, representing Chinese producers that dominate volume through furnace scale in hydropower-rich southwestern provinces. These three entities anchor the competitive structure by demonstrating how geographic positioning and energy access determine sustainable cost position.
| Leading Market Players |
|---|
| Ferroglobe |
| Elkem ASA |
| Hoshine Silicon Industry Co., Ltd. |
| Dow |
| RIMA Industrial |
| Wacker Chemie AG |
| RusAL |
| Anyang Huatuo Metallurgy Co., Ltd. |
| Mississippi Silicon |
| Others |
Cost & Logistics Intelligence
China's dual carbon goals gate qualified supply and premium-tier pricing access for silicon metal, restricting export eligibility to smelters with verified low-carbon production while concentrating margin pools among hydropower-based operators in Yunnan and Xinjiang.
Pricing Analysis
Volume placements concentrate in standard metallurgical-grade ingots; margin pools accrue to chemical-grade and semiconductor-grade tiers where purity premiums command structural price differentiation. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with REACH-registered and low-carbon-certified material capturing sustained premiums. Cost compression in commodity-grade segments is intensifying because coal-dependent smelters in Shanxi and Inner Mongolia face margin erosion against hydropower competitors. Aluminum foundries exhibit highest price sensitivity due to ferrosilicon substitution options; semiconductor-grade buyers show lowest sensitivity given purity thresholds that lock in qualified suppliers.
Supply Chain Analysis
Furnace dust recovery and silicon fines briquetting create reverse-logistics value streams for secondary aluminum producers seeking remelting efficiency. Raw material supply concentrates in China, Norway, and the United States, with quartz deposits clustering in limited geographies that expose smelters to concentrate pricing volatility. Production draws from high-purity silica, carbon reductants, and submerged-arc furnace electrodes as critical inputs. Single-source vulnerability runs through China's dominance of metallurgical-grade output. Distribution runs through long-term offtake contracts with polysilicon producers and quarterly tender processes serving steelmakers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon metal operates as a supply-constrained market where smelter consolidation under MEE environmental mandates props pricing for qualified low-carbon producers.
For Market Incumbents: Lock in quartz mining assets and hydropower purchase agreements to defend cost position against emerging furnace operators in Southeast Asia. Secure REACH registration dossiers and EU CBAM lifecycle emissions documentation to create switching costs for European chemical-grade buyers facing tightening impurity thresholds. Prioritize R&D investment in plasma-enhanced purification to capture semiconductor-grade premiums. For New Entrants and Emerging Players: Capture stranded solar-grade demand in Vietnam and Malaysia as module assembly shifts toward Southeast Asia and polysilicon producers seek regional feedstock diversification. Target automotive silicones for battery thermal management systems where specification tightening outpaces incumbent capacity expansion. Lead with automated dosing system compatibility and granular format supply to differentiate from legacy ingot sellers. For Investors and Strategic Acquirers: MEE license suspensions exceeding six months is the leading indicator that Chinese smelter consolidation will accelerate and concentrate export-eligible supply among southwestern hydropower operators. Long-term viability over the next decade rests on verified low-carbon production processes and third-party certification schemes. Target integrated quartz-to-silicon operators with captive mining assets and furnace operations in clean energy zones. Monitor EU CBAM implementation timelines for inflection signals on premium-tier pricing expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Relocation to Hydropower Zones | MEE compliance in Yunnan and Xinjiang secures operating licenses and export eligibility for low-carbon producers. |
| Backward Integration into Quartz Mining | Ferroglobe's Spanish and French silica deposits anchor cost leadership against concentrate price volatility. |
| Plasma-Enhanced Purification Scale-Up | Southeast Asian polysilicon producers bypass Siemens process bottlenecks to compress cost gaps with Chinese suppliers. |
| REACH Registration Dossier Completion | Elkem's Norwegian facilities lock in European chemical-grade supply with verified impurity thresholds. |
| Long-Term Offtake with Solar Manufacturers | LONGi and JA Solar contracts in Yunnan province de-risk capacity investment for metallurgical-grade expansion. |
Research Approach
Trade flow databases, SEC filings from listed silicon producers, and ECHA REACH registration records formed the secondary backbone for this analysis. Primary interviews with submerged-arc furnace operators, procurement leads at polysilicon manufacturers, and technical directors at silicone polymerization plants combined with secondary validation to build bottom-up and top-down triangulation. Customs data on quartz concentrate shipments and smelter energy sourcing disclosures anchored supply-side modeling.
Historical trendline analysis across production volumes, grade-specific pricing spreads, and capacity utilization rates informed the analytical framework over the projection horizon. Segmentation dimensions modeled include product form, purity grade tier, end-use application, and regional production hub energy source. CAGRs derived from fitted trend extrapolation adjusted for policy intervention impacts. Forecast inputs incorporated MEE environmental compliance timelines and EU CBAM implementation phases.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to hydropower availability fluctuations and semiconductor reshoring policy shifts. Forecasts reflect documented assumptions on smelter relocation velocity and polysilicon capacity expansion trajectories. Practitioners should monitor MEE license suspension announcements and EU carbon border adjustment mechanism trial phase outcomes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Asia-Pacific Semiconductor Materials Market
Semiconductor Material
Big Size Synthetic Diamond Market
Semiconductor Material
Silicon Carbide (Sic) Coating Market
Semiconductor Material
Global Scintillator Market
Semiconductor Material
Global Silicone Market
Semiconductor Material
Polyvinylidene Fluoride (PVDF) Market
Semiconductor Material
Global Electronic Materials Market
Semiconductor Material
Middle East Silicon Carbide (Sic) Market
Semiconductor Material
LED Materials Market
Semiconductor Material
Silicon Nitride Balls Market
Semiconductor Material
Niobium Hydride Market
Semiconductor Material
Yttrium Oxide Market
Semiconductor Material
Sapphire Ingot Market
Semiconductor Material
Global Semiconductor Epoxy Mold Compound Market
Semiconductor Material
Germanium Market
Semiconductor Material
Titanium Diboride Market