
 Global RTD Tea Drinks Market | 2026-2036
Global RTD Tea Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Global RTD Tea Drinks Market Foresight
Single-serve multipack bundling is recalibrating how households and offices purchase RTD tea, shifting volume from individual impulse buys toward planned pantry stocking. The Coca-Cola Company leverages its fountain and cooler infrastructure to dominate foodservice channels for chilled tea distribution. Tingyi Holding Corp. anchors its position through captive production of PET resin and bottle preforms across eastern China. Ito En specializes in unsweetened green tea formulations that command premium placement in Japanese convenience stores.
Ready-to-drink tea encompasses brewed, blended, or extracted tea beverages that are commercially processed, packaged in bottles, cans, or cartons, and sold for immediate consumption without further preparation, typically containing tea solids, water, and optional sweeteners or flavor modifiers at specific Brix levels for shelf stability. The product serves as a portable hydration and caffeine-delivery alternative to carbonated beverages and coffee across retail and foodservice channels. Black tea formulations occupy the largest volume share due to established consumer familiarity and lower raw material costs, while green tea segments capture margin premiums through antioxidant positioning and cleaner-label formulations. PET bottle packaging leads unit economics through lightweighting and recycling stream compatibility, though aluminum cans are gaining traction in convenience and vending channels for chill-speed and portability advantages.
The FDA governs GRAS status and nutrition labeling for RTD tea sold in the United States, while EFSA and the EU Green Deal framework shape sugar-reduction targets and packaging recyclability mandates across European markets. Japan's Ministry of Health, Labour and Welfare sets caffeine disclosure thresholds that constrain formulation choices for energy-positioned tea blends. Stakeholders must monitor evolving extended producer responsibility schemes for beverage containers and anticipate how sugar taxation spreads across additional jurisdictions.
Market Dynamics
Younger consumers in Vietnam, Indonesia, and Thailand are abandoning carbonated soft drinks for chilled RTD tea, forcing convenience stores and supermarket chains to reallocate shelf space and rewrite procurement contracts with beverage distributors.
Growth Catalysts
- China's GB standards for beverage labeling:Clearer ingredient disclosure requirements are building consumer trust and accelerating trial among health-conscious urban buyers in tier-one cities.
- Japan's METI energy-efficiency guidelines:Production facility upgrades are reducing per-unit energy costs and enabling manufacturers to absorb sugar-tax pressures without passing full costs to consumers.
- On-the-go tea consumption habits:Urban middle-class adoption across Southeast Asian cities is expanding addressable demand beyond traditional home consumption occasions.
Market Restraints
- PET resin price volatility:Crude oil-linked input costs create margin compression for producers without captive resin production or long-term supply agreements.
- China's eastern coastal production concentration:Tingyi Holding Corp's dominance in bottle preform manufacturing creates supply vulnerability for mid-tier brands without backward integration.
- Japan's caffeine disclosure thresholds:Ministry of Health, Labour and Welfare constraints limit formulation innovation for energy-positioned tea blends targeting young professionals.
Strategic Opportunities
- Vietnam's underpenetrated convenience channel:Modern trade expansion in Ho Chi Minh City and Hanoi offers first-mover advantage for brands establishing direct-store-delivery infrastructure.
- EU Green Deal packaging recyclability mandates:Early alignment with extended producer responsibility schemes positions exporters for preferential retail access as tariffs on non-compliant imports harden.
- Aluminum can and PET bottle convergence:Hybrid packaging strategies combining chill-speed advantages of cans with recycling economics of bottles unlock vending and foodservice simultaneously.
Industry Challenges
- Food safety certification timelines:FSSAI clearance for India market entry and China's SAMR registration create 12-18 month lag between formulation finalization and commercial launch.
- Legacy cooler infrastructure incompatibility:Coca-Cola's fountain and cooler dominance in foodservice channels blocks rival brands from achieving optimal chilled placement without separate capital investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global RTD Tea Drinks Market |
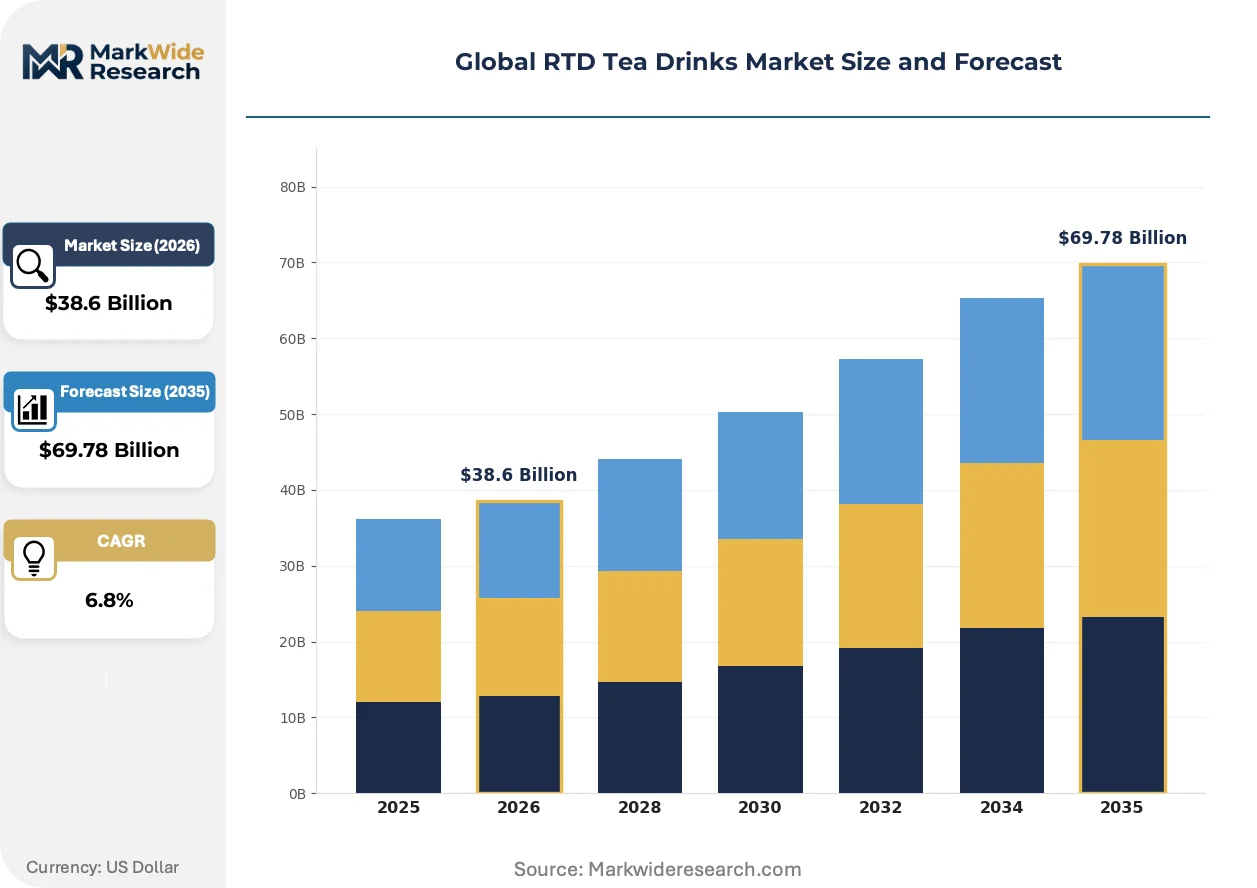
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Black Tea, Green Tea, Oolong Tea, Herbal Tea, White Tea Packaging Type: Bottle, Can, Tetra Pak, Glass, PET Bottle Sales Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Stores, Vending Machines Consumer Age Group: Generation Z, Millennials, Generation X, Baby Boomers |
| Companies Covered | The Coca-Cola Company, PepsiCo, Suntory Holdings Limited, Tingyi Holding Corp., Uni-President Enterprises Corp., Nestlé, Unilever, Ito En, Kirin Holdings Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global RTD Tea Drinks Market Shifts & Advancements
Formulation science and packaging engineering are converging to deliver shelf-stable tea with cleaner labels, while regulatory pressure on sugar content and container recyclability forces simultaneous reformulation and supply chain redesign.
Aseptic cold-fill processing is electrifying how unsweetened green tea achieves ambient shelf life without chemical preservatives. Japanese convenience store chains are adopting this technology fastest, compressing the traditional hot-fill quality gap between premium refrigerated and ambient-stable products. The structural consequence is margin expansion for antioxidant-positioned formulations previously constrained by chilled distribution costs.
EFSA sugar-reduction targets under the EU Green Deal framework are forcing reformulation investments across European export portfolios. Industrial consequence includes accelerated stevia and monk fruit adoption despite aftertaste challenges, with German and Dutch retailers now rejecting shipments above specified Brix thresholds. Black tea segments face the steepest compliance costs given established consumer sweetness expectations.
Single-serve multipack bundling is rotating household purchasing from impulse convenience buys toward planned pantry stocking. E-commerce subscription channels in South Korea and urban China are displacing traditional wholesale club dominance for bulk RTD tea procurement. This pattern is most visible among dual-income households in Seoul and Shanghai seeking to reduce store trip frequency.
Global RTD Tea Drinks Market Segmentation
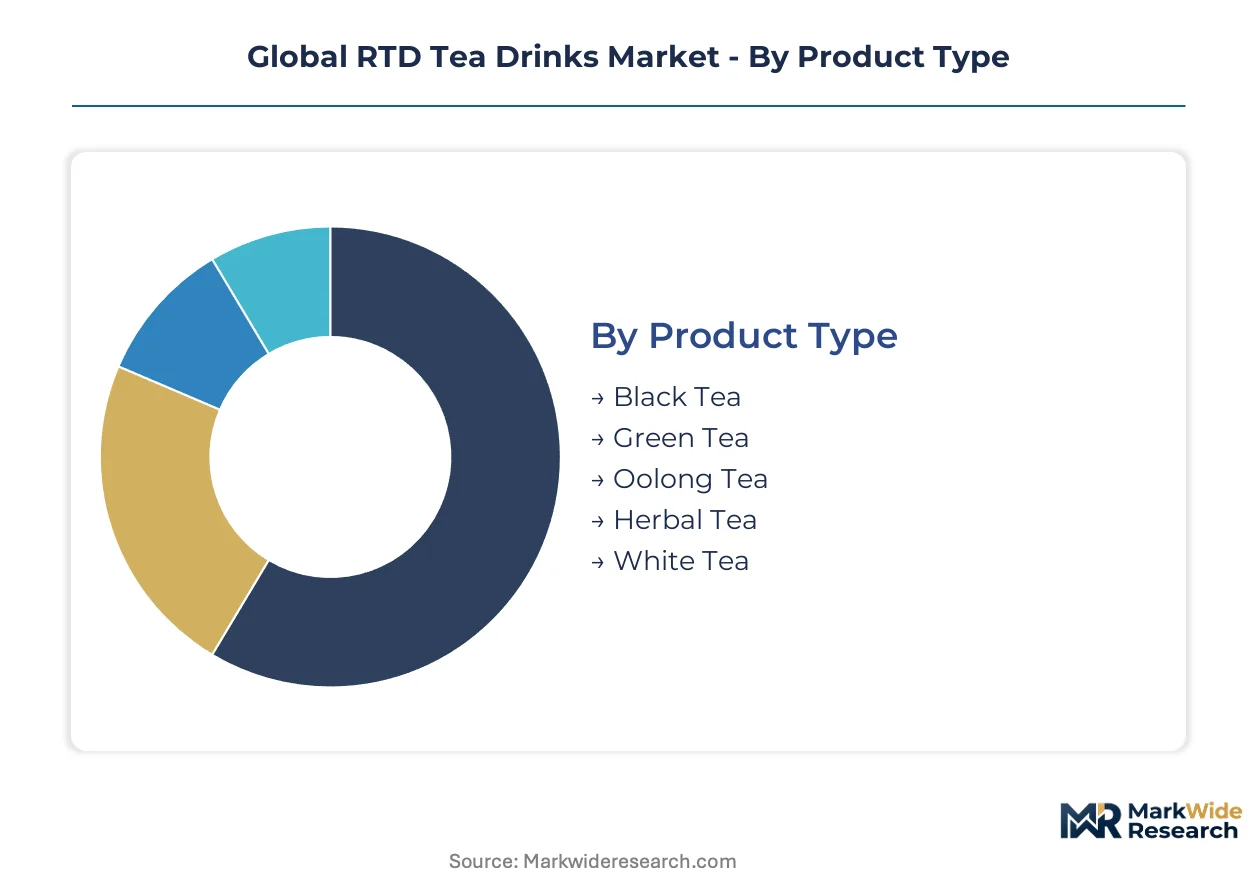
RTD tea segmentation reveals divergent margin structures across formulation types and channel economics. Packaging format and generational targeting determine whether brands capture impulse premiums or build recurring household volume.
Product Type:
Black tea dominates volume throughput while green tea commands shelf-price premiums through antioxidant positioning.
- Black Tea:Brewed Camellia sinensis with fully oxidized leaves delivers familiar taste profiles at lower raw material cost. Demand concentrates in Vietnam and Thailand convenience channels where established sweetness preferences drive repeat purchase frequency.
- Green Tea:Minimally oxidized leaf formulations retain catechins and polyphenols for clean-label positioning. Japanese convenience stores and South Korean e-commerce channels absorb premium pricing for unsweetened variants with METI-compliant production credentials.
- Oolong Tea:Semi-oxidized processing bridges black and green flavor profiles for transitional consumers in Taiwan and Fujian province.
- Herbal Tea:Non-camellia botanical infusions target caffeine-avoidant demographics through rooibos and chamomile variants.
- White Tea:Minimal processing preserves delicate flavor compounds for niche premium placement in specialty retail.
Mature deployment sits with Black Tea. Newer deployment is concentrated in Green Tea.
Packaging Type:
Material selection determines chill-speed performance, recycling economics, and vending channel compatibility.
- Bottle:Lightweight PET construction enables single-serve portability with established collection infrastructure. Supermarket chains in China and Indonesia prioritize bottle formats for household multipack bundling.
- Can:Aluminum construction accelerates cooling curves for vending and convenience placement. Thailand's 7-Eleven network and Japan's railway kiosks favor cans for grab-and-go consumption velocity.
- Tetra Pak:Aseptic carton technology supports ambient distribution with rectangular shelf efficiency.
- Glass:Premium positioning through tactile weight and perceived purity for specialty store channels.
- PET Bottle:Virgin and recycled resin grades balance clarity with EU Green Deal recyclability mandates.
Cost efficiency clusters around PET Bottle. Premium differentiation is expanding fastest in Can.
Sales Channel:
Channel selection dictates temperature control requirements and trade margin structures.
- Supermarkets:Chilled multi-door fixtures support planned pantry stocking with promotional depth. Urban middle-class households in Jakarta and Ho Chi Minh City drive volume through weekly replenishment trips.
- Convenience Stores:24-hour accessibility and immediate chill capture impulse occasions. Vietnam's Circle K and FamilyMart expansion is displacing traditional tea stalls in Hanoi and Da Nang.
- Online Retail:Subscription bundling reduces per-trip logistics cost for bulk procurement.
- Specialty Stores:Curated assortment supports premium discovery and gift occasion purchasing.
- Vending Machines:Dense urban placement captures commuter hydration with minimal labor overhead.
Volume concentration remains with Supermarkets. Fastest channel expansion is occurring in Convenience Stores.
Consumer Age Group:
Generational cohorts diverge sharply on sweetness tolerance, caffeine sensitivity, and digital purchase behavior.
- Generation Z:Digital-native consumers aged 12-27 prioritize TikTok-discovered brands with transparent ingredient lists. Seoul and Shanghai university districts show highest trial rates for zero-sugar formulations with EFSA-aligned labeling.
- Millennials:Dual-income professionals aged 28-43 balance convenience with wellness positioning. E-commerce subscription adoption in South Korea and urban China is climbing fastest among this cohort seeking to reduce store frequency.
- Generation X:Established taste preferences favor traditional black tea sweetness profiles.
- Baby Boomers:Caffeine moderation drives herbal and decaffeinated variant selection.
Established consumption patterns persist with Baby Boomers. Steepest expansion trajectory belongs to Generation Z.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of PET bottles and preforms consumed across Asia-Pacific, while Vietnam, Indonesia, and Thailand absorb the fastest-growing demand for chilled RTD tea. This production-consumption divide shapes logistics costs and shelf-price structures throughout the region.
China
Urban middle-class consumers in Shanghai and Beijing drive premium green tea adoption through e-commerce subscription channels. SAMR registration requirements and GB standards for beverage labeling extend commercialization timelines by 12-18 months. Tingyi Holding Corp. maintains captive PET resin production across eastern coastal provinces, insulating margin positions from crude oil volatility.
Japan
Unsweetened green tea formulations command premium placement in Tokyo and Osaka convenience stores as METI energy-efficiency guidelines reduce per-unit production costs. Ministry of Health, Labour and Welfare caffeine disclosure thresholds constrain energy-positioned blend innovation. Aseptic cold-fill processing adoption concentrates in Nagoya industrial corridors, compressing quality gaps between refrigerated and ambient-stable products.
Vietnam
Circle K and FamilyMart expansion in Ho Chi Minh City and Hanoi displaces traditional tea stalls among Generation Z consumers. Modern trade infrastructure investments accelerate direct-store-delivery route density. Da Nang emerging as secondary demand node as urban middle-class on-the-go consumption habits solidify.
Indonesia
Jakarta supermarket chains prioritize PET bottle multipack bundling for weekly household replenishment cycles. FSSAI-equivalent food safety certification timelines delay import launches from regional suppliers. Surabaya and Bandung convenience channels absorb spillover demand as modern trade penetration deepens beyond Java.
Thailand
7-Eleven network dominance in Bangkok and Chiang Mai favors aluminum can formats for grab-and-go velocity. Sugar taxation pressures force reformulation investments across black tea segments with established sweetness expectations. Eastern seaboard industrial zones concentrate aseptic filling capacity serving export markets.
Global RTD Tea Drinks Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation, packaging, and channel dimensions. The market structure consolidates around beverage multinationals with cooler infrastructure assets and Asian conglomerates with captive supply chain control. Three archetypes dominate: multinational soft drink giants leveraging fountain networks, integrated Asian beverage conglomerates with resin backward integration, and premium Japanese green tea specialists. Competitive moves center on direct-store-delivery infrastructure expansion and aseptic processing technology licensing.
Among multinational soft drink corporations, The Coca-Cola Company and PepsiCo anchor the foodservice channel through cooler and fountain asset dominance. Tingyi Holding Corp. exemplifies the integrated Asian conglomerate archetype with captive PET preform manufacturing across eastern China. Ito En occupies the premium specialist position within Japanese convenience store channels. These three represent the strategic poles—scale infrastructure, vertical supply control, and premium formulation—around which mid-tier competitors must differentiate.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| PepsiCo |
| Suntory Holdings Limited |
| Tingyi Holding Corp. |
| Uni-President Enterprises Corp. |
| Nestlé |
| Unilever |
| Ito En |
| Kirin Holdings Company |
| Others |
Supply & Pricing Matrix
Supermarket chain procurement concentration in Vietnam and Indonesia enforces three-tier pricing structure across premium, standard, and economy levels, with volume commitments determining netback realization for manufacturers.
Pricing Analysis
Margin tightening in economy-tier black tea reflects crude oil-linked PET resin volatility and Tingyi's captive supply advantage. Price differentiation rests on METI-compliant production credentials and GB-standard labeling clarity. Cost compression accelerates as sugar taxation spreads across Southeast Asian markets. Generation Z buyers in Seoul and Shanghai show lowest price sensitivity for zero-sugar green tea variants.
Supply Chain Analysis
Direct-store-delivery channels handle modern trade expansion in Ho Chi Minh City and Hanoi. Raw material flows draw from eastern China's PET resin concentration, Japanese aseptic processing equipment, and Thai aluminum can sheet production. Single-source vulnerability concentrates in Tingyi's bottle preform manufacturing across Fujian and Jiangsu provinces. Distribution runs through Coca-Cola's cooler infrastructure in foodservice and 7-Eleven's vending networks in Bangkok.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as GB standards and METI guidelines raise compliance costs beyond mid-tier balance sheet capacity, forcing subscale exits.
For Market Incumbents: Anchor market position through backward integration into PET resin production or long-term offtake agreements with eastern Chinese suppliers. Expand direct-store-delivery route density in Vietnam's underpenetrated convenience channel before Circle K and FamilyMart consolidate distributor relationships. Counter Ito En's aseptic cold-fill advantage through licensing Japanese processing technology. For New Entrants and Emerging Players: E-commerce subscription platforms in South Korea offer the most penetrable entry vector for zero-sugar green tea variants targeting dual-income millennials. Vietnam's Da Nang secondary market presents whitespace for aluminum can formats displacing traditional tea stalls. Lead with TikTok-native brand building in Seoul university districts to bypass Coca-Cola's cooler infrastructure block. For Investors and Strategic Acquirers: The window for entry favors mid-tier Asian beverage conglomerates with captive bottle manufacturing but lacking aseptic processing capabilities. Monitor METI energy-efficiency guideline adoption rates as inflection signal for production cost divergence between compliant and legacy facilities. Long-term viability hinges on EU Green Deal packaging alignment for export market access.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Cold-Fill Licensing | Japanese convenience store chains compress quality gaps between refrigerated and ambient-stable green tea products. |
| Direct-Store-Delivery Expansion | Vietnam's Circle K and FamilyMart networks displace traditional tea stalls in Hanoi and Da Nang. |
| PET Resin Backward Integration | Tingyi's captive preform manufacturing insulates margin positions from crude oil volatility. |
| EU Green Deal Alignment | German and Dutch retailers now reject shipments above specified Brix thresholds for sugar content. |
| E-Commerce Subscription Launch | Seoul and Shanghai dual-income households reduce store trip frequency through bulk procurement channels. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with beverage brand managers, convenience store category buyers, PET resin procurement leads, and aseptic processing equipment suppliers validated demand assumptions. Bottom-up volume modeling triangulated against top-down category spend estimates from retail audit databases.
Granularity-level modeling disaggregated projections across tea formulation type, packaging material, sales channel, and generational cohort. CAGRs derived from segment-level growth rate synthesis across the analysis window. Forecast inputs incorporated SAMR registration timelines, METI facility upgrade adoption curves, and EU sugar-reduction compliance trajectories.
Several conditions sit outside the modeled scope, including potential sugar taxation in currently unregulated Southeast Asian markets and breakthroughs in biodegradable packaging cost parity. Forecasts reflect documented assumptions on urban middle-class expansion rates and modern trade penetration. Periodic stress-testing of base assumptions is recommended given PET resin price volatility and regulatory timeline uncertainty.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Europe Soy Beverages Market
Non-Alcoholic Beverages
North America Bottled Water Market
Non-Alcoholic Beverages
Pearl Milk Tea Market
Non-Alcoholic Beverages
Non-Dairy Beverages Market
Non-Alcoholic Beverages
Iced Tea Market
Non-Alcoholic Beverages
Brazil Energy Drinks Market
Non-Alcoholic Beverages
Coffee Substitute Market
Non-Alcoholic Beverages
Bubble Tea Market
Non-Alcoholic Beverages
Non-Alcoholic Malt Beverages Market
Non-Alcoholic Beverages
Africa Energy Drinks Market
Non-Alcoholic Beverages
Zero Sugar Beverages Market
Non-Alcoholic Beverages
Isotonic Drinks Market
Non-Alcoholic Beverages
Water Vending Machine Market
Non-Alcoholic Beverages
Europe Sports and Energy Drinks Market
Non-Alcoholic Beverages
Rtd Bubble Tea Market
Non-Alcoholic Beverages
Zero Proof Spirit Market