
 Brazil Energy Drinks Market | 2026-2036
Brazil Energy Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Energy Drinks Market Outlook
A capital-intensity divergence between multinational beverage conglomerates and domestic brewers is reorganizing competitive dynamics in Brazil's energy drinks sector. Coca-Cola Brasil leverages its nationwide bottling infrastructure to dominate supermarket and convenience store shelves. Grupo Petrópolis anchors its position through deep wholesale relationships in Brazil's Northeast and interior regions. Monster Beverage Corp. differentiates via sponsorship-heavy marketing targeting extreme sports and gaming communities.
Energy drinks are non-alcoholic beverages formulated with caffeine, taurine, B-vitamins, and other stimulant compounds designed to enhance mental alertness and physical performance, typically containing 80-300mg of caffeine per serving and manufactured through hot-fill or aseptic cold-fill processes. Carbonated variants still occupy the largest volume share, though functional formulations with added electrolytes, nootropics, and adaptogens are capturing the fastest growth as athletes and professionals seek performance beyond basic stimulation. E-commerce distribution is expanding rapidly, yet supermarkets and convenience stores retain the dominant margin pool due to impulse-purchase dynamics and refrigerated point-of-sale placement.
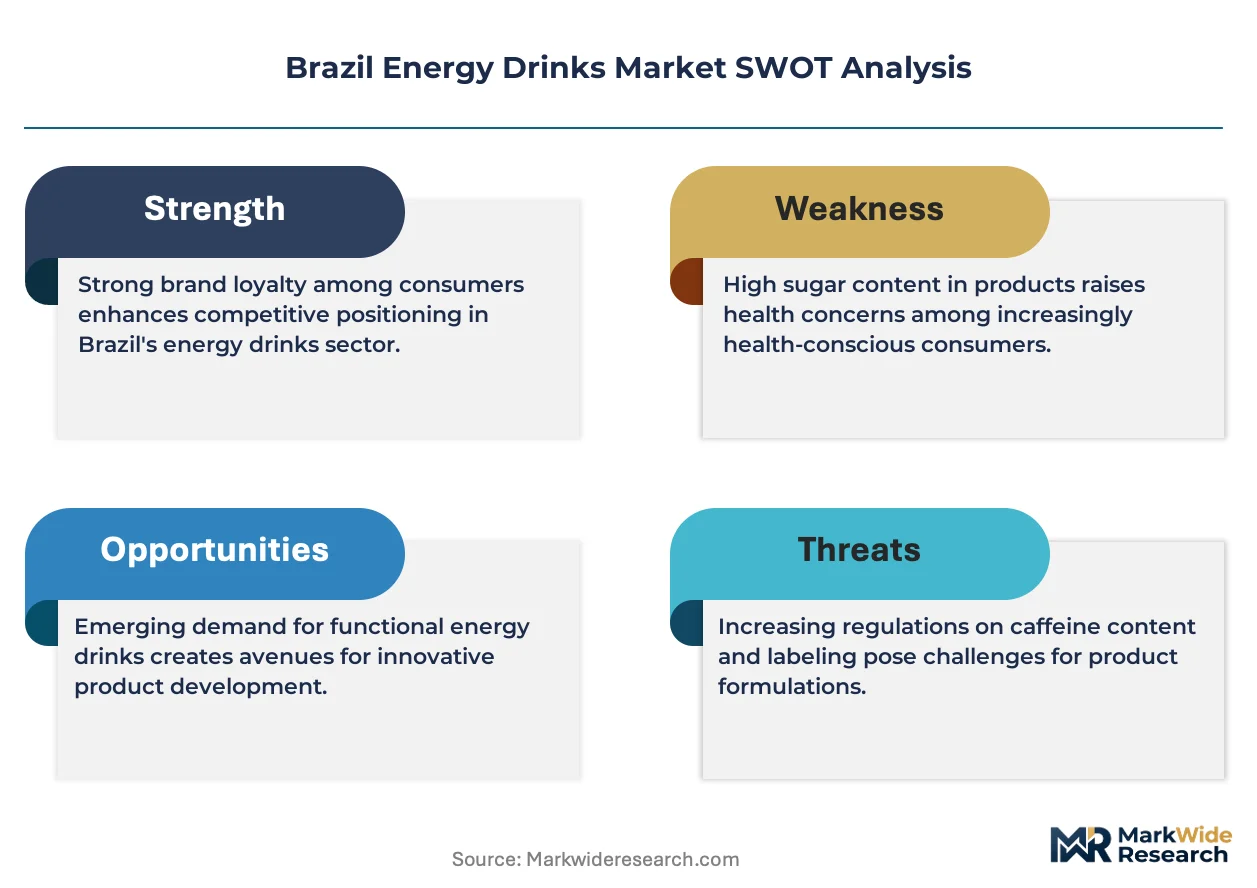
ANVISA mandates strict caffeine disclosure thresholds and prohibits health claims without clinical substantiation, while Brazil's federal sugar taxation framework pushes manufacturers toward sugar-free and low-calorie formulation portfolios. State-level consumer protection agencies in São Paulo and Rio de Janeiro actively enforce labeling compliance, creating uneven market access costs across sub-national jurisdictions. Stakeholders must monitor pending federal legislation on synthetic caffeine restrictions and decide whether to front-load reformulation investments or risk stranded inventory positions.
Market Dynamics
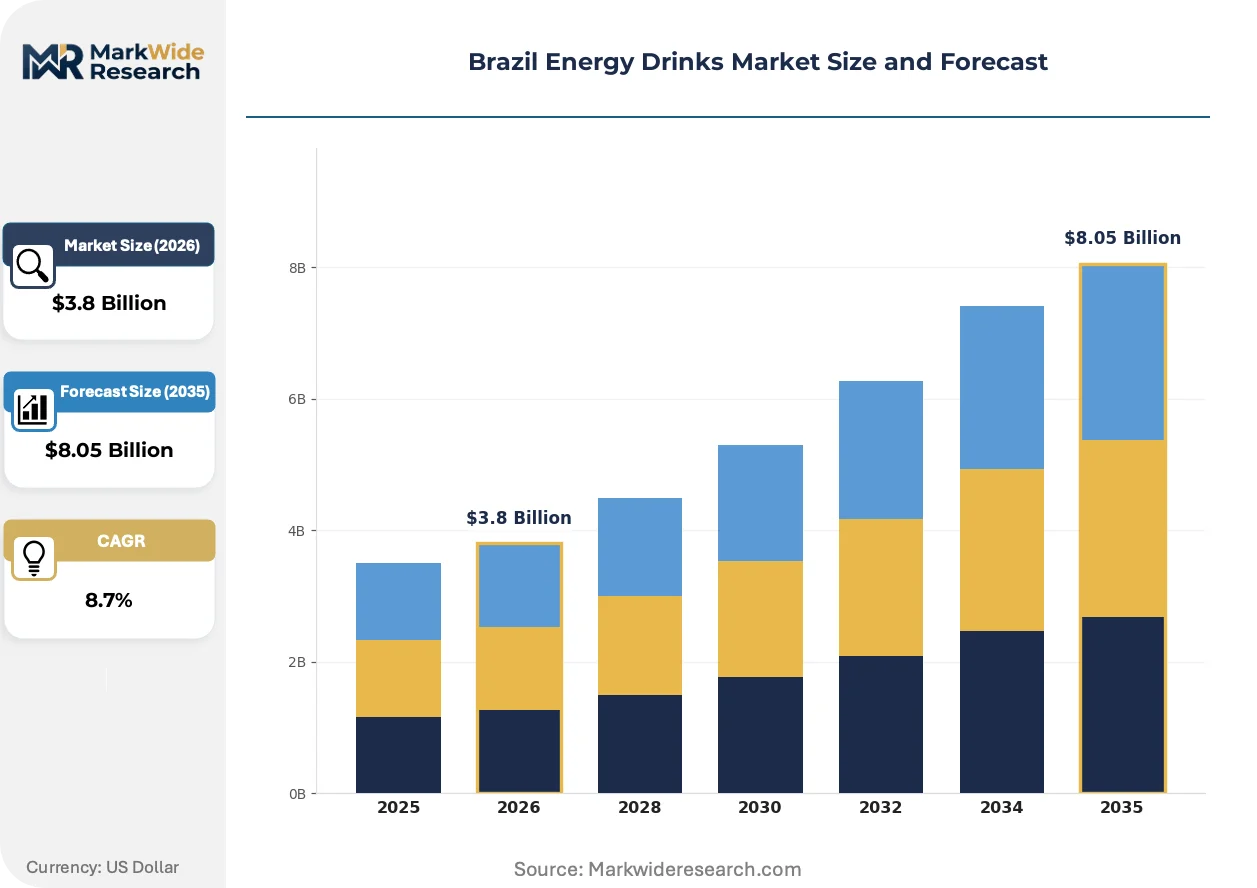
ANVISA's caffeine disclosure mandates and Brazil's federal sugar taxation framework are compressing formulation margins while accelerating portfolio migration toward sugar-free variants. Manufacturers face simultaneous pressure to reformulate and relabel without triggering stranded inventory positions.
Growth Catalysts
- Fitness culture expansion:São Paulo's urban professionals and gym chains are normalizing pre-workout functional beverage consumption, creating habitual purchase patterns among young adults aged 18-34.
- E-commerce channel maturation:Digital direct-to-consumer platforms are capturing impulse-replacement purchases through subscription models and flash promotion mechanics.
- ANVISA labeling clarity:Standardized caffeine disclosure thresholds reduce consumer confusion and build trust in clinically substantiated functional claims.
Market Restraints
- Synthetic caffeine import dependency:Brazil lacks domestic pharmaceutical-grade caffeine synthesis capacity, exposing formulators to currency-driven input cost volatility.
- Refrigerated distribution concentration:Cold-chain logistics networks cluster in São Paulo and Rio de Janeiro states, fragmenting market access in the Northeast and Amazon regions.
- Sugar taxation compression:Federal excise duties on caloric sweeteners erode margin structures for legacy full-sugar portfolios still preferred in price-sensitive interior markets.
Strategic Opportunities
- Northeast wholesale penetration:Bahia and Pernambuco states show underdeveloped modern trade coverage relative to per-capita consumption potential.
- Nootropic-adaptogen convergence:Formulations combining L-theanine, ashwagandha, and B-vitamins target knowledge workers seeking sustained focus without jitters.
- State-level consumer protection alignment:São Paulo and Rio de Janeiro enforcement harmonization could reduce sub-national compliance fragmentation costs.
Industry Challenges
- Reformulation timeline compression:Pending federal legislation on synthetic caffeine restrictions forces R&D teams to validate natural caffeine alternatives under accelerated schedules.
- Point-of-sale refrigeration capex:Convenience store chains demand manufacturer-funded cooler placement, concentrating working capital requirements among smaller domestic brewers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Energy Drinks Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbonated, Non-Carbonated, Organic, Herbal Distribution Channel: Supermarkets, Convenience Stores, E-commerce, Specialty Shops End User: Teenagers, Young Adults, Athletes, Professionals Formulation: Regular, Sugar-Free, Low-Calorie, Functional |
| Companies Covered | Grupo Petrópolis, Coca-Cola Brasil, Red Bull GmbH, Integralmedica, Cervejaria Petrópolis SA, Monster Beverage Corp., PepsiCo Inc., Celsius Holdings, Anheuser-Busch InBev, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Energy Drinks Market Strategic Shifts
Formulation science and channel mechanics are diverging from carbonated stimulation toward precision functional targeting. Three developments are compressing competitive response windows.
Aseptic cold-fill processing is miniaturizing production economics for regional bottlers. This technology enables smaller batch runs with 90-day shelf stability without preservatives. Domestic brewers in Minas Gerais and Paraná are adopting modular systems to test localized flavors. The capital barrier to test-market entry is collapsing, fragmenting share concentration.
ANVISA's prohibition of unsubstantiated health claims is tightening clinical validation requirements. Manufacturers must now commission peer-reviewed studies or remove cognitive performance assertions from packaging. Premium functional lines targeting esports and professional athletics are most affected, with several portfolios undergoing label redesigns.
Subscription replenishment models are displacing supermarket impulse purchasing among São Paulo's white-collar workforce. Office delivery services and gym partnerships now capture recurring revenue streams. This shift compresses brand switching frequency and raises customer lifetime value calculations for digital-native entrants.
Brazil Energy Drinks Market Segmentation
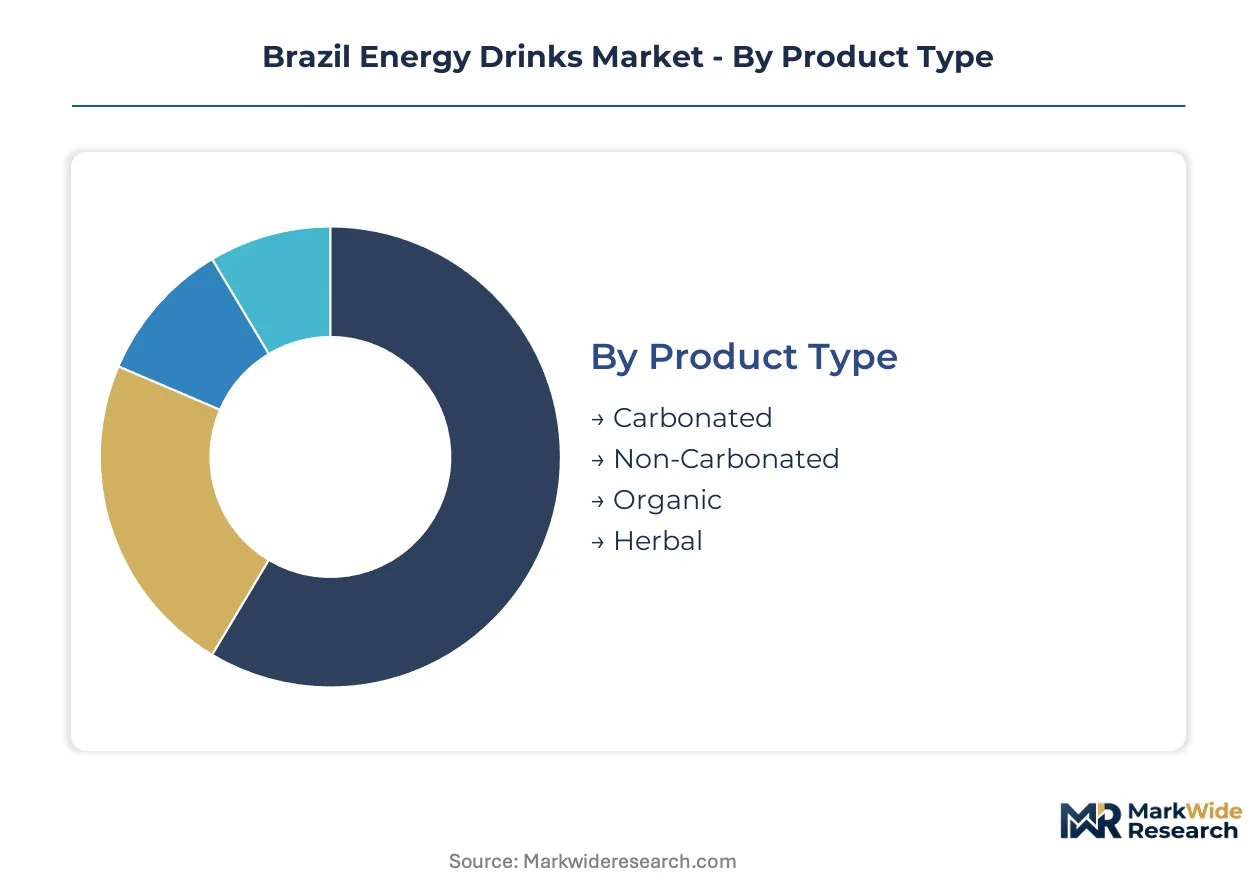
ANVISA's formulation mandates and sugar taxation rules are fragmenting competitive positions across product architectures. Manufacturers must align portfolio investments with diverging margin structures and channel access costs.
Product Type:
ANVISA's caffeine disclosure thresholds and carbonation labeling requirements create uneven compliance burdens across formulation categories.
- Carbonated:Traditional effervescent formulations deliver 80-150mg caffeine through hot-fill processing with extended ambient shelf stability. São Paulo's convenience store networks and gym chains concentrate demand for impulse-driven refreshment occasions.
- Non-Carbonated:Still variants utilize aseptic cold-fill technology enabling cleaner ingredient decks and shorter ingredient lists. Bahia and Pernambuco wholesale channels show accelerating adoption as refrigeration infrastructure expands beyond coastal metros.
- Organic:Certified organic caffeine sources and natural sweeteners command premium positioning in specialty retail.
- Herbal:Botanical stimulant blends incorporating guarana and yerba mate target regional taste preferences in Brazil's South and interior states.
Established volume favors Carbonated; emerging adoption favors Non-Carbonated.
Distribution Channel:
Capital intensity and working capital requirements stratify manufacturer access by channel tier.
- Supermarkets:Refrigerated point-of-sale placement demands slotting fees and cooler capex commitments that favor Coca-Cola Brasil's national bottling infrastructure. São Paulo's urban corridors generate the highest per-shelf velocity for multi-pack functional variants.
- Convenience Stores:Impulse-driven single-serve purchases concentrate in Rio de Janeiro and Minas Gerais highway corridors. Grupo Petrópolis leverages deep wholesale relationships to secure preferential cooler positioning in Northeast interior towns.
- E-commerce:Subscription replenishment models capture São Paulo white-collar professionals through office delivery partnerships.
- Specialty Shops:Fitness boutiques and esports cafés curate premium nootropic-adaptogen formulations for performance-oriented consumers.
Margin concentration favors Supermarkets; volume expansion favors E-commerce.
End User:
Age-based consumption patterns and professional use cases are reshaping formulation priorities.
- Young Adults:The 18-34 demographic drives habitual pre-workout and gaming-session consumption across São Paulo's fitness culture and esports venues. ANVISA's prohibition of health claims without clinical substantiation most affects marketing to this segment's performance expectations.
- Athletes:Electrolyte-enhanced and recovery-focused formulations target competitive and recreational sports participants. Sugar taxation pressures are accelerating migration toward sugar-free portfolios preferred by physique-conscious consumers.
- Teenagers:Price-sensitive trial purchases concentrate in school-adjacent convenience retail.
- Professionals:Knowledge workers seeking sustained focus without jitters gravitate toward L-theanine and ashwagandha combinations.
Revenue concentration favors Young Adults; steepest expansion trajectory favors Athletes.
Formulation:
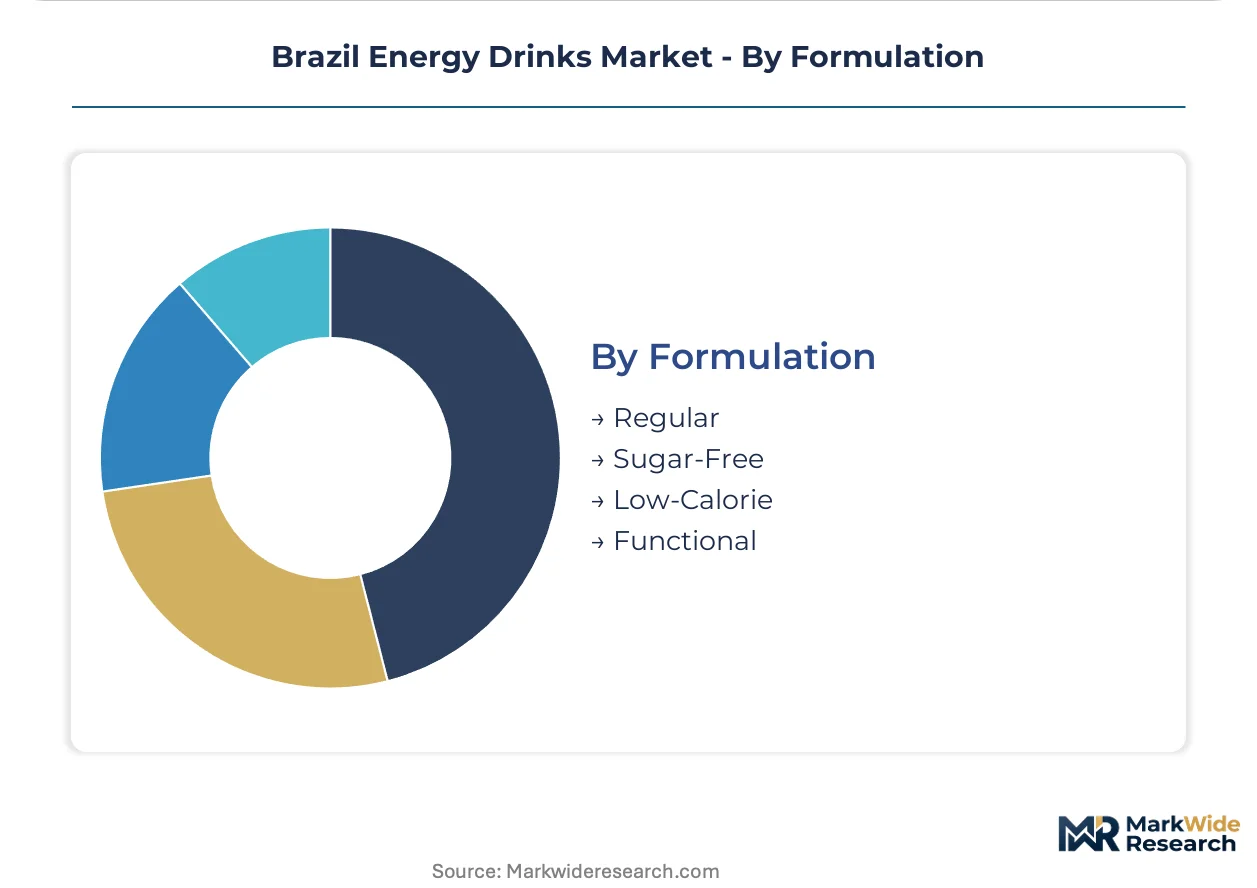
Federal sugar taxation and synthetic caffeine import dependencies compress margin structures differently across sweetener and stimulant architectures.
- Sugar-Free:Aspartame, sucralose, and stevia-based formulations dominate São Paulo premium positioning as professionals and athletes reject caloric loads. ANVISA's labeling clarity on artificial sweeteners reduces consumer hesitation versus legacy full-sugar alternatives.
- Functional:Nootropic-adaptogen convergence with B-vitamins, L-theanine, and herbal extracts commands the highest per-liter pricing. Pending federal legislation on synthetic caffeine restrictions is forcing R&D investment into natural caffeine alternatives for this tier.
- Regular:Full-sugar legacy portfolios retain price-sensitive penetration in Brazil's interior and Northeast markets.
- Low-Calorie:Mid-tier positioning bridges taste and health positioning for transitional consumers.
Margin protection favors Sugar-Free; innovation intensity favors Functional.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across Brazil's sub-regional markets. São Paulo professionals absorb premium functional pricing, while Northeast interior consumers remain tethered to legacy full-sugar value tiers. This divergence shapes manufacturer portfolio allocation and cold-chain investment priorities.
São Paulo
Urban professionals aged 25-40 drive habitual pre-workout consumption across gym chains and esports cafés. ANVISA's caffeine disclosure mandates encounter highest compliance scrutiny from São Paulo's consumer protection agency. The metropolitan corridor concentrates refrigerated point-of-sale placement and subscription delivery infrastructure.
Rio de Janeiro
Coastal tourism and beach culture sustain impulse-driven single-serve purchases at convenience stores. State-level enforcement of labeling standards runs parallel to federal ANVISA frameworks. Highway corridors linking Rio to Minas Gerais host dense cooler networks targeting commuter refreshment occasions.
Minas Gerais
Regional bottlers leverage aseptic cold-fill miniaturization to test localized herbal formulations with yerba mate extracts. ANVISA's prohibition of unsubstantiated health claims affects marketing to this state's fitness-adjacent consumer base. Belo Horizonte's emerging white-collar districts attract subscription-model entrants.
Bahia
Wholesale channel penetration lags per-capita consumption potential across Salvador and interior municipalities. Federal sugar taxation compresses margins for full-sugar portfolios still dominant in price-sensitive segments. Refrigeration infrastructure expansion beyond coastal metros enables non-carbonated variant adoption.
Rio Grande do Sul
Regional taste preferences favor herbal stimulant blends incorporating native botanicals. State consumer protection agencies enforce ANVISA-aligned labeling standards with varying inspection intensity. Porto Alegre's metropolitan area anchors southern distribution networks with emerging specialty retail channels.
Brazil Energy Drinks Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across Brazil's energy drinks sector. Multinational beverage conglomerates leverage national bottling infrastructure and refrigerated distribution scale, while domestic brewers exploit regional wholesale relationships and formulation agility. Two strategic archetypes dominate: infrastructure-heavy incumbents with cooler placement capital, and digital-native entrants capturing subscription replenishment flows. Competitive moves concentrate on portfolio diversification toward sugar-free functional tiers and geographic expansion into underpenetrated Northeast wholesale channels.
Among multinational infrastructure players, Coca-Cola Brasil and Monster Beverage Corp. exemplify divergent positioning archetypes. Coca-Cola Brasil anchors supermarket and convenience store dominance through captive bottling networks. Monster Beverage Corp. occupies sponsorship-heavy marketing terrain targeting extreme sports and gaming communities. Domestic brewer Grupo Petrópolis represents the regional wholesale specialist model, leveraging deep relationships in Brazil's Northeast and interior markets.
| Leading Market Players |
|---|
| Grupo Petrópolis |
| Coca-Cola Brasil |
| Red Bull GmbH |
| Integralmedica |
| Cervejaria Petrópolis SA |
| Monster Beverage Corp. |
| PepsiCo Inc. |
| Celsius Holdings |
| Anheuser-Busch InBev |
| Others |
Value Chain & Pricing Dynamics
Sixty-day inventory cycles for synthetic caffeine imports concentrate working capital exposure among domestic Brazilian formulators, directly compressing pricing power as currency volatility feeds through to landed costs. This lead-time structure rewards multinational players with captive offshore sourcing networks while squeezing regional bottlers dependent on spot-market procurement.
Pricing Analysis
After-sales revenue from gym partnership subscriptions and office delivery replenishment drives lifetime value beyond the initial unit transaction. Three-tier pricing structure across premium functional, standard carbonated, and economy full-sugar levels stratifies the market, with ANVISA-compliant clinical substantiation and cold-chain placement capability serving as the primary price differentiation drivers. Cost compression in the full-sugar tier intensifies because federal excise duties erode margin structures faster than reformulation investments. Price-sensitive interior consumers in Brazil's Northeast and Amazon regions resist premium migration, while São Paulo professionals absorb functional premiums without volume elasticity.
Supply Chain Analysis
Just-in-time inventory preferences dominate among supermarket and convenience store chains, forcing manufacturers to absorb demand volatility through manufacturer-funded cooler placement and safety stock positioning. Synthetic caffeine sourcing concentrates in China and India, with pharmaceutical-grade taurine and B-vitamin premix dependencies anchored in Germany and Switzerland. Single-source vulnerability for natural caffeine alternatives exposes formulators to pending federal legislation timelines. Distribution runs through refrigerated logistics networks clustering in São Paulo and Rio de Janeiro, fragmenting cold-chain access in the Northeast and interior states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's energy drinks sector sits at a platform-economics inflection where subscription replenishment interoperability between gym chains and office delivery services is displacing traditional impulse-purchase infrastructure. Ecosystem lock-in through recurring revenue partnerships now determines competitive sustainability more than shelf-space dominance.
For Market Incumbents: Fortify cold-chain infrastructure in underpenetrated Northeast corridors before regional bottlers achieve aseptic cold-fill scale economies. Secure exclusive cooler placement contracts with convenience store chains in Bahia and Pernambuco to preempt Grupo Petrópolis wholesale relationships. ANVISA's pending synthetic caffeine restrictions threaten stranded inventory positions; accelerate natural caffeine alternative validation through captive R&D or specialist acquisition. For New Entrants and Emerging Players: Lead with nootropic-adaptogen convergence formulations targeting São Paulo's knowledge worker segment, where subscription replenishment models capture recurring revenue without refrigerated point-of-sale capex. The specialty shop channel through fitness boutiques and esports cafés offers the most penetrable entry vector with minimal slotting fee barriers. Direct-to-consumer digital platforms with flash promotion mechanics enable brand building before physical retail scale. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational beverage conglomerates divesting non-core regional portfolios under sugar taxation margin pressure. Long-term viability in this sector hinges on formulation agility and subscription platform ownership rather than bottling asset scale. Monitor ANVISA enforcement harmonization across São Paulo and Rio de Janeiro consumer protection agencies as the inflection signal for compliance cost rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Sugar-Free Portfolio Migration | ANVISA labeling clarity and federal taxation accelerate consumer acceptance of reformulated variants. |
| Northeast Wholesale Channel Expansion | Bahia and Pernambuco per-capita consumption potential exceeds modern trade coverage depth. |
| Subscription Platform Development | São Paulo white-collar workforce habitual consumption patterns favor recurring revenue capture. |
| Aseptic Cold-Fill Miniaturization | Regional bottlers in Minas Gerais and Paraná collapse capital barriers to test-market entry. |
| Natural Caffeine Alternative R&D | Pending federal synthetic caffeine restrictions force accelerated validation timelines for compliant formulations. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of ANVISA regulatory filings, Nielsen retail audit data, customs import records, and federal taxation framework documentation. Brand managers at multinational beverage conglomerates, category buyers at São Paulo supermarket chains, procurement leads at regional bottlers, and regulatory affairs specialists provided stakeholder perspectives. Bottom-up channel volume triangulation against top-down macroeconomic consumption models validated market sizing.
Segmentation dimensions modeled span product architecture, distribution channel tier, end-user demographic, and formulation composition across the projection horizon. CAGRs derive from trend-line extrapolation of historical consumption patterns adjusted for regulatory impact coefficients and channel shift elasticities. Synthetic caffeine import dependency ratios and state-level refrigeration infrastructure penetration serve as Brazil-specific forecast inputs.
Forecasts assume regulatory continuity in ANVISA disclosure mandates and federal sugar taxation regimes; material policy shifts would require re-modeling. Synthetic caffeine restriction legislation timing, currency volatility bands for pharmaceutical-grade input procurement, and state-level consumer protection enforcement intensity constitute primary revision triggers. Revision becomes warranted when subscription channel penetration crosses threshold dominance in São Paulo metropolitan consumption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
GCC Non-Alcoholic Beer Market
Non-Alcoholic Beverages
Sugar Free Carbonated Drinks Market
Non-Alcoholic Beverages
Non-Carbonated Soft Drinks Market
Non-Alcoholic Beverages
North America Bottled Water Processing Market
Non-Alcoholic Beverages
Water Vending Machine Market
Non-Alcoholic Beverages
Zero Sugar Beverages Market
Non-Alcoholic Beverages
Japan Soy Beverages Market
Non-Alcoholic Beverages
Europe Energy Drink Market
Non-Alcoholic Beverages
Europe Sports Drink Market
Non-Alcoholic Beverages
North America Soy Beverages Market
Non-Alcoholic Beverages
Coffee Substitute Market
Non-Alcoholic Beverages
Diet Soda Market
Non-Alcoholic Beverages
Fruit-Infused Water Market
Non-Alcoholic Beverages
China Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
Zero Proof Spirit Market
Non-Alcoholic Beverages
United Arab Emirates Bottled Water Market