
 Non-Dairy Beverages Market | 2026-2036
Non-Dairy Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Dairy Beverages Market Insights
USDA Organic certification is unwinding competitive access for smaller entrants who lack the capital to sustain multi-year conversion audits and traceability infrastructure. Danone S.A. leverages its dairy-alternative manufacturing scale across European and North American facilities to maintain cost parity with conventional milk. Blue Diamond Growers anchors its position through captive almond supply from California's Central Valley cooperative networks. Oatly Group AB competes by controlling branded oat-base processing technology that it licenses selectively to regional partners.
Non-dairy beverages comprise plant-derived liquid formulations produced through aqueous extraction, enzymatic hydrolysis, or mechanical pressing of oilseeds, grains, or nuts, typically fortified with calcium, vitamin D, and B12 to match dairy's nutritional profile. Oat milk leads product type expansion due to its functional foaming properties and lower water footprint than almond cultivation, while soy milk retains mature volume in East Asian household consumption. Online retail channels capture the fastest growth in distribution as direct-to-subscription models reduce refrigeration intermediaries and build recurring revenue pools.
FDA nutrition labeling rules and EFSA novel food authorization pathways shape formulation standards and market entry timelines for new protein sources like pea or fava. The EU Green Deal's Farm to Fork strategy pressures conventional dairy's carbon accounting, indirectly expanding shelf access for plant-based alternatives in European retail. Stakeholders must monitor whether upcoming EPA water-use disclosures for nut cultivation alter sourcing economics for almond-dependent suppliers.
Market Dynamics
Clean-label certification requirements under FDA and EFSA frameworks are compressing formulation timelines and raising capital barriers for new entrants, concentrating competitive advantage among established processors with integrated traceability systems.
Growth Catalysts
- EU Green Deal Farm to Fork strategy:Carbon accounting pressures on conventional dairy are expanding retail shelf access for plant-based alternatives across German, French, and Dutch supermarket chains.
- Seoul-Melbourne-Los Angeles café clusters:Specialty hospitality venues specifying oat milk as default are accelerating consumer taste formation and normalizing premium pricing for barista-grade formulations.
- Enzymatic hydrolysis advances:Improved protein extraction yields from fava and pea bases are broadening formulation options beyond established oat and soy inputs.
Market Restraints
- USDA Organic multi-year conversion audits:The capital intensity of traceability infrastructure and certification timelines excludes smaller entrants lacking sustained funding capacity.
- California Central Valley almond supply concentration:Water-intensive cultivation geography creates input cost volatility and regulatory exposure under pending EPA disclosure requirements.
- FDA-EFSA novel food authorization pathways:Extended approval timelines for emerging protein sources compress first-mover advantage windows and extend R&D payback periods.
Strategic Opportunities
- Direct-to-subscription online retail:Refrigeration-eliminating distribution models build recurring revenue pools and reduce intermediary margin capture.
- German retail expansion:Fastest-growing European shelf space allocation for plant-based alternatives creates volume scaling opportunities ahead of market saturation.
- Pea-fava protein convergence:Blending legume bases with complementary amino acid profiles enables nutritional parity claims and differentiation from single-source competitors.
Industry Challenges
- Clean-label B12-calcium fortification IP:Proprietary stabilization technologies and licensing complexity create formulation bottlenecks for non-integrated processors.
- Barista-grade foaming certification:Technical skill gaps in enzymatic lipid modification constrain product development timelines for specialty café supply contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Dairy Beverages Market |
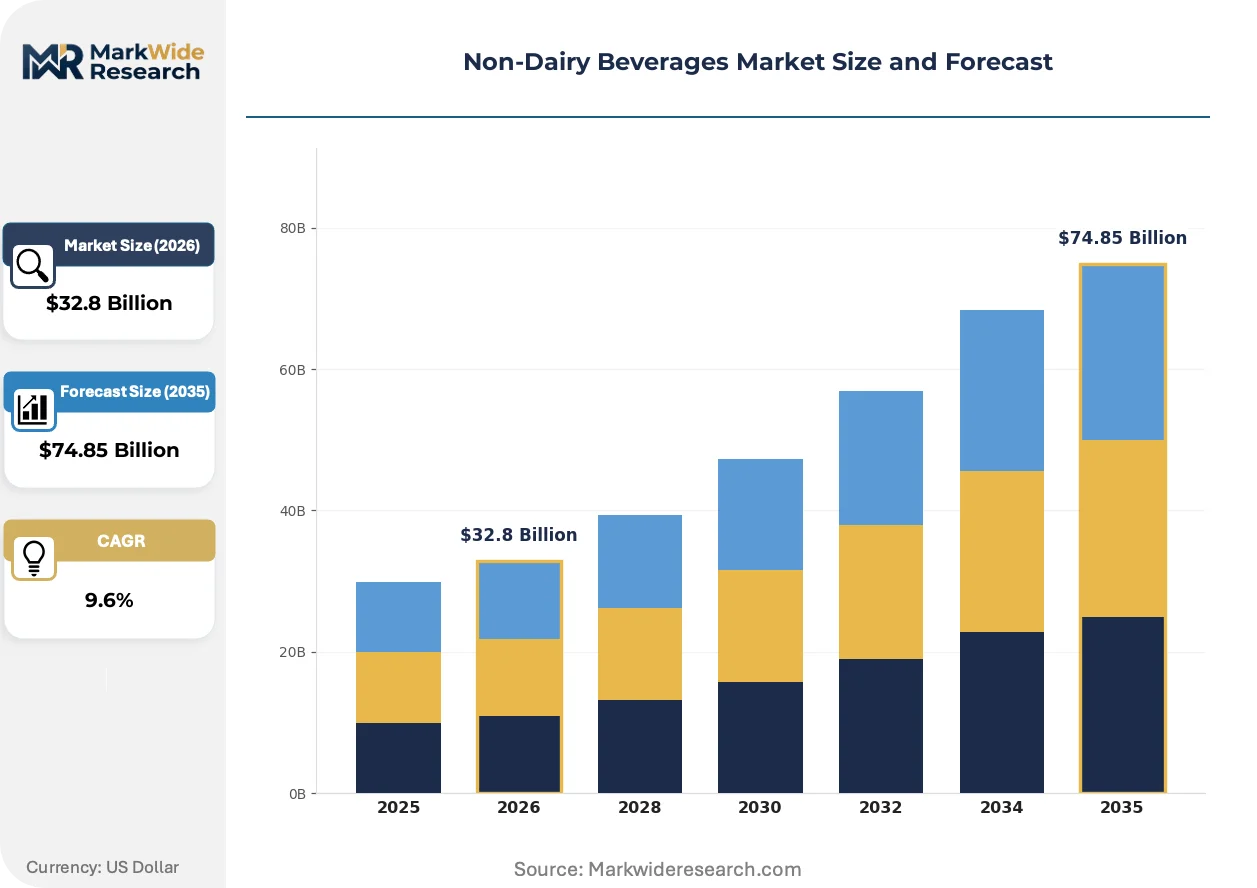
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $74.85 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almond Milk, Soy Milk, Oat Milk, Coconut Milk Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Convenience Stores End User: Households, Cafés, Restaurants, Food Industry Flavor Profile: Unsweetened, Vanilla, Chocolate, Original |
| Companies Covered | Danone S.A., Blue Diamond Growers, Oatly Group AB, Califia Farms LLC, SunOpta Inc., The Hain Celestial Group, Vitasoy International Holdings Ltd, Campbell Soup Company, Ripple Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Dairy Beverages Market Trends and Innovations
Formulation science and distribution infrastructure are converging to reshape competitive boundaries, with processing technology licensing and channel disintermediation emerging as decisive capability differentiators.
Precision enzymatic lipid modification is displacing conventional homogenization in barista-grade oat milk production. Specialty café chains in Melbourne and Los Angeles are adopting these formulations at contract-renewal pace. The technology is displacing commodity-grade suppliers unable to match foam stability performance benchmarks.
EFSA novel food authorization pathways are tightening ingredient disclosure thresholds for emerging protein sources. Extended safety evaluation timelines are compressing product launch windows for pea and fava entrants. European formulation houses are responding by front-loading toxicology studies and pre-submission consultations with EFSA scientific panels.
Subscription-based direct distribution is capturing recurring revenue pools previously held by refrigerated retail intermediaries. Online channels are eliminating cold-chain logistics layers and building proprietary customer data assets. This shift concentrates in urban hospitality clusters where café procurement managers prioritize supply reliability over brand recognition.
Non-Dairy Beverages Market Segmentation
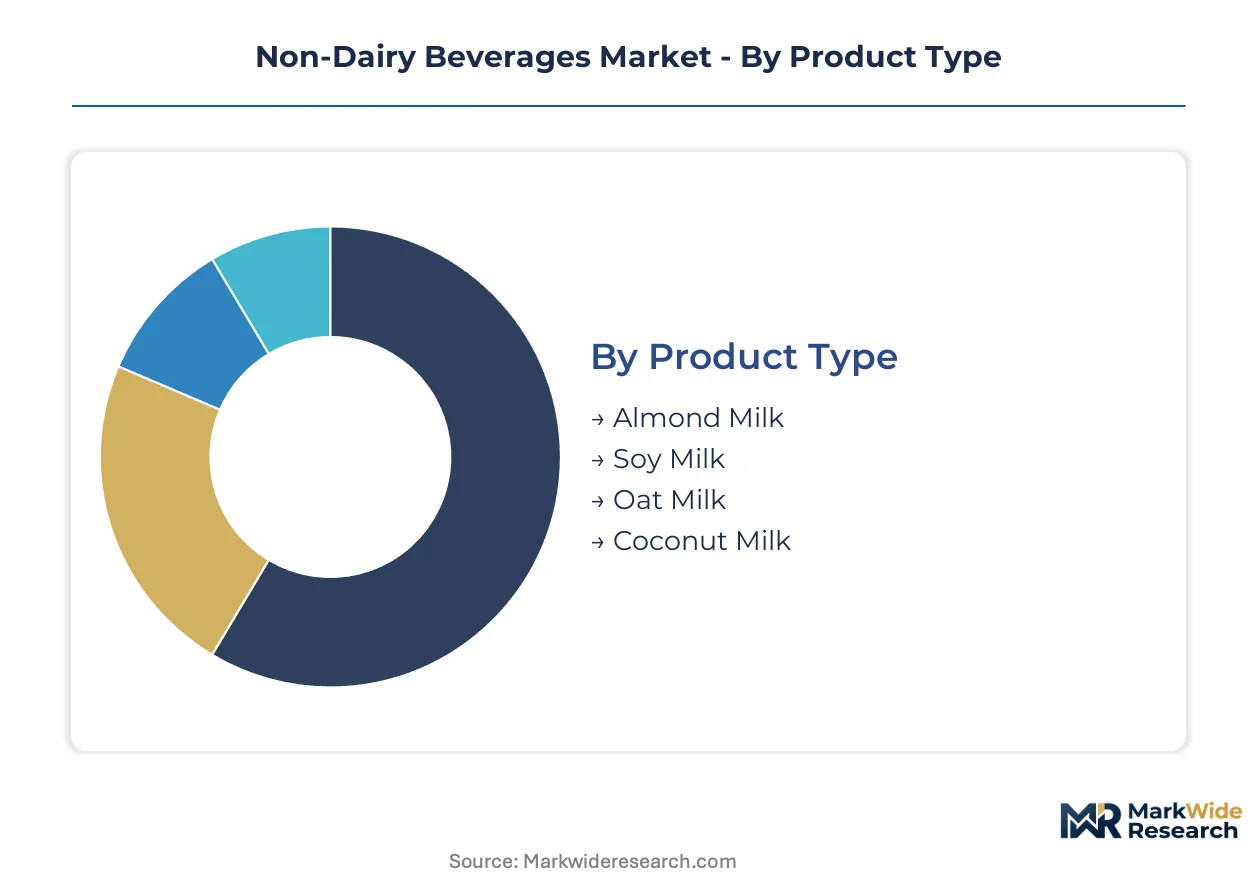
Segmentation in non-dairy beverages reveals how formulation specialization and channel economics partition margin capture. Product type and distribution channel hierarchies concentrate value differently across retail, foodservice, and industrial procurement contexts.
Product Type:
Premium extraction technologies and barista-grade certifications concentrate margin pools in functional performance tiers rather than commodity volume.
- Oat Milk:Enzymatic hydrolysis of oat starches produces creamy mouthfeel and superior foam stability for espresso applications. Specialty cafés in Seoul and Los Angeles specify oat milk as default, compressing adoption timelines for competing bases.
- Almond Milk:Cold-pressed almond extraction yields lighter viscosity suited to breakfast cereal and smoothie applications. California Central Valley water constraints under pending EPA disclosure rules are elevating input cost volatility for almond-dependent processors.
- Soy Milk:Mature fermentation protocols deliver complete protein profiles with established East Asian household penetration.
- Coconut Milk:Tropical sourcing geography limits supply chain flexibility for North American and European formulators.
The dominant share belongs to almond milk, while oat milk is closing the gap fastest.
Distribution Channel:
Refrigeration requirements and intermediary margin stacks create divergent profitability across physical and digital fulfillment paths.
- Online Retail:Direct-to-subscription models eliminate cold-chain logistics layers and build proprietary customer data assets. Urban hospitality clusters in Melbourne and Los Angeles prioritize supply reliability through digital procurement channels.
- Supermarkets:German retail chains have expanded shelf space fastest among European markets, creating volume scaling opportunities ahead of saturation.
- Health Food Stores:USDA Organic certification concentration attracts premium positioning for traceability-verified formulations.
- Convenience Stores:Ambient-stable packaging requirements favor UHT-processed varieties with extended shelf stability.
Online retail channels are expanding most quickly, though supermarkets retain the largest transaction volume base.
End User:
Application-specific formulation requirements segment procurement priorities across consumption contexts.
- Cafés:Barista-grade foaming certification demands enzymatic lipid modification capabilities that commodity suppliers cannot match.
- Households:East Asian markets sustain mature soy milk consumption patterns through traditional retail channels.
- Restaurants:Bulk procurement contracts prioritize cost stability over functional performance differentiation.
- Food Industry:Ingredient-grade specifications for bakery and confectionery applications require customized protein and fat content profiles.
Cafés command the steepest premium tier, while food industry volume is scaling fastest.
Flavor Profile:
Clean-label certification thresholds under FDA and EFSA frameworks are compressing permissible additive ranges for flavored variants.
- Unsweetened:Zero-sugar positioning aligns with tightening nutritional labeling requirements in multiple jurisdictions.
- Original:Baseline formulations serve as the reference standard for fortification parity claims with conventional dairy.
- Vanilla:Natural flavor extraction costs separate premium positioning from artificial flavoring alternatives.
- Chocolate:Cocoa sourcing sustainability credentials increasingly influence European procurement specifications.
Unsweetened formulations hold the largest volume position, while chocolate variants are gaining share fastest in children's beverage segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's cold-chain logistics infrastructure anchors Germany's role as Europe's primary distribution hub for plant-based beverages, connecting Baltic Sea shipping lanes to inland rail networks serving Central European retail chains.
Germany
Retail shelf space for plant-based alternatives has expanded faster than any European market, driven by Aldi and Rewe chain procurement shifts. The EU Green Deal's Farm to Fork strategy pressures conventional dairy carbon accounting, indirectly expanding supermarket access. Berlin and Hamburg host the densest concentration of specialty cafés specifying oat milk defaults.
United States
California Central Valley almond cooperative networks supply captive raw material to major processors, though pending EPA water-use disclosures threaten input cost stability. FDA nutrition labeling rules shape formulation standards for calcium and vitamin D fortification claims. Los Angeles café clusters normalize premium barista-grade oat milk pricing through contract-specified defaults.
South Korea
Seoul's Gangnam and Hongdae district specialty coffee chains drive taste formation for foam-stable oat formulations among urban consumers. The country's national food safety regulator enforces strict novel food authorization pathways for emerging protein sources. Domestic convenience store chains are expanding ambient-stable UHT plant-based SKUs.
Australia
Melbourne's laneway café culture specifies oat milk as default across independent hospitality venues, compressing competitor adoption timelines. Food Standards Australia New Zealand maintains clean-label certification thresholds that exceed FDA disclosure requirements. Sydney and Brisbane retail chains are replicating Melbourne's procurement specifications.
China
Mature soy milk consumption patterns persist in household breakfast rituals across eastern provinces. The national market regulator enforces GB standards for plant protein beverage labeling that diverge from Western fortification norms. Shanghai and Beijing hospitality clusters are testing oat milk adoption among younger demographics.
Non-Dairy Beverages Market Competitive Landscape
Listed leaders compete with private specialists across capital access and agility dimensions, producing a tiered structure where scale advantages clash with formulation speed. Consolidation pressures concentrate among mid-cap processors lacking integrated traceability systems. Three archetypes dominate: dairy-alternative multinationals with cross-continental manufacturing footprints, nut and grain cooperative processors with captive agricultural supply, and oat-base technology licensors with selective partnership models. M&A activity targets enzymatic processing capabilities, while capacity expansion concentrates in German and US Midwest logistics corridors.
Within the multinational tier, Danone S.A. and Blue Diamond Growers occupy positions that exemplify divergent sourcing strategies—one leveraging European and North American facility networks, the other anchored to California cooperative agricultural supply. Oatly Group AB represents the technology-licensing archetype, controlling branded oat-base processing capabilities that it deploys through selective regional partnerships rather than owned manufacturing.
| Leading Market Players |
|---|
| Danone S.A. |
| Blue Diamond Growers |
| Oatly Group AB |
| Califia Farms LLC |
| SunOpta Inc. |
| The Hain Celestial Group |
| Vitasoy International Holdings Ltd |
| Campbell Soup Company |
| Ripple Foods |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day enzymatic processing lead times for barista-grade oat formulations concentrate margin capture among processors with in-house lipid modification capabilities, while spot-market almond sourcing compresses pricing power for California-dependent suppliers lacking forward contracts.
Pricing Analysis
Volume-discount tiering structures stratify across premium barista-certified, standard retail-grade, and economy private-label levels. Price differentiation rests on USDA Organic certification status and enzymatic foam-stability performance benchmarks. Cost compression in almond-dependent tiers is intensifying because pending EPA water-use disclosures threaten California Central Valley input stability. Foodservice procurement managers exhibit lowest price sensitivity, while mass-market retail buyers negotiate aggressively on standard formulations.
Supply Chain Analysis
Sweden and the Netherlands anchor proprietary oat-base processing technology and enzymatic formulation R&D. California's Central Valley cooperative networks supply captive almond feedstock. Germany draws from Baltic Sea shipping lanes through Hamburg's cold-chain infrastructure. Single-source vulnerability concentrates in California water-intensive cultivation geography. Distribution runs through direct-to-subscription digital channels and German supermarket chain procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The non-dairy beverages sector represents a high-growth disruption as precision enzymatic lipid modification displaces conventional homogenization, with EFSA novel food authorization timelines compressing competitive windows for emerging protein sources.
For Market Incumbents: Shield formulation margins by deepening captive oat-base processing capabilities ahead of commodity-grade supplier consolidation. Acquire enzymatic lipid modification IP to defend against technology licensors expanding selective partnership networks. Prioritize USDA Organic certification maintenance as traceability infrastructure excludes undercapitalized challengers. For New Entrants and Emerging Players: FDA fast-track consultation pathways for novel protein GRAS determinations offer regulatory arbitrage against EFSA's extended safety evaluation timelines. Penetrate German retail shelf space ahead of saturation, where Aldi and Rewe procurement shifts create volume scaling windows. Launch direct-to-subscription models eliminating cold-chain intermediaries in Melbourne and Los Angeles café clusters. For Investors and Strategic Acquirers: Long-term, this sits as a processing-technology consolidation play because enzymatic capabilities determine barista-grade contract access. Target mid-cap processors lacking integrated traceability systems. Monitor EFSA pre-submission consultation volumes as inflection indicator for novel protein authorization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Processing Scale-Up | Captures barista-grade contract specifications from Seoul café clusters. |
| USDA Organic Certification Investment | Excludes undercapitalized entrants from premium retail positioning. |
| Direct-to-Subscription Channel Launch | Eliminates refrigerated intermediary margins in urban hospitality procurement. |
| Pea-Fava Protein R&D Partnership | Accelerates EFSA novel food authorization through front-loaded toxicology. |
| German Retail Distribution Expansion | Secures volume scaling ahead of European shelf space saturation. |
Research Methodology
Operator-level perspectives from plant-based beverage formulators, specialty café procurement managers, enzymatic processing engineers, retail category buyers, and cooperative agricultural supply coordinators anchored the qualitative base. Secondary validation drew from FDA GRAS notifications, EFSA novel food opinions, USDA Organic certification databases, German retail audit data, and California water board disclosures. Bottom-up volume estimates triangulated against top-down category spending analysis.
Sensitivity analysis tested input assumptions across the projection horizon against alternative regulatory timeline scenarios. Segmentation modeling incorporated product type, distribution channel, end-use application, flavor profile, and regional regulatory cluster dimensions. CAGRs derived from fitted growth curves calibrated to historical adoption patterns and elasticity estimates for oat versus almond base substitution.
Decision-makers should treat outputs as directional under sustained EU Green Deal carbon accounting pressure and stable enzymatic processing cost curves; material deviation in FDA-EFSA regulatory divergence or California water access would warrant model refresh. Recalibration cycles align with material shifts in novel protein authorization timelines and German retail shelf allocation decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Fermented Non Dairy Non Alcoholic Beverages Market
Non-Alcoholic Beverages
Diet Soda Market
Non-Alcoholic Beverages
Pearl Milk Tea Market
Non-Alcoholic Beverages
India Energy Drinks Market
Non-Alcoholic Beverages
China Energy- Drinks Market
Non-Alcoholic Beverages
Vietnam Energy Drinks Market
Non-Alcoholic Beverages
Hypertonic Drinks Market
Non-Alcoholic Beverages
Africa Energy Drinks Market
Non-Alcoholic Beverages
GCC Non-Alcoholic Beer Market
Non-Alcoholic Beverages
Global Sugar Free Beverages Market
Non-Alcoholic Beverages
Global RTD Tea Drinks Market
Non-Alcoholic Beverages
Bubble Tea Market
Non-Alcoholic Beverages
Non-Alcoholic Malt Beverages Market
Non-Alcoholic Beverages
Europe Soy Beverages Market
Non-Alcoholic Beverages
North America Bottled Water Market
Non-Alcoholic Beverages
Fruit-Infused Water Market