
 RTD Tea Market | 2026-2036
RTD Tea Market Size, Share, and Industry Trends Forecast 2026-2036
RTD Tea Market Outlook
Multi-source botanical sourcing is repositioning supply strategies across the RTD tea industry. The Coca-Cola Company leverages its global procurement network to secure tea leaf volumes across multiple origins. Ito En, Ltd. anchors its competitive stance through backward integration into Japanese tea gardens. PepsiCo, Inc. competes via diversified flavor pipelines spanning green, black, and herbal platforms.
Ready-to-drink tea denotes brewed, packaged, and shelf-stable tea beverages typically processed through hot-fill or aseptic bottling at pH levels below 4.6 for microbial stability, serving consumer demand for convenient, portable refreshment without preparation. Green tea formulations command premium shelf positioning due to antioxidant positioning and functional health claims. Bottled formats dominate volume throughput while pouches represent the fastest-growing packaging type in convenience-oriented channels. Tetra Packs sustain relevance in European food service where ambient distribution reduces cold-chain dependency.
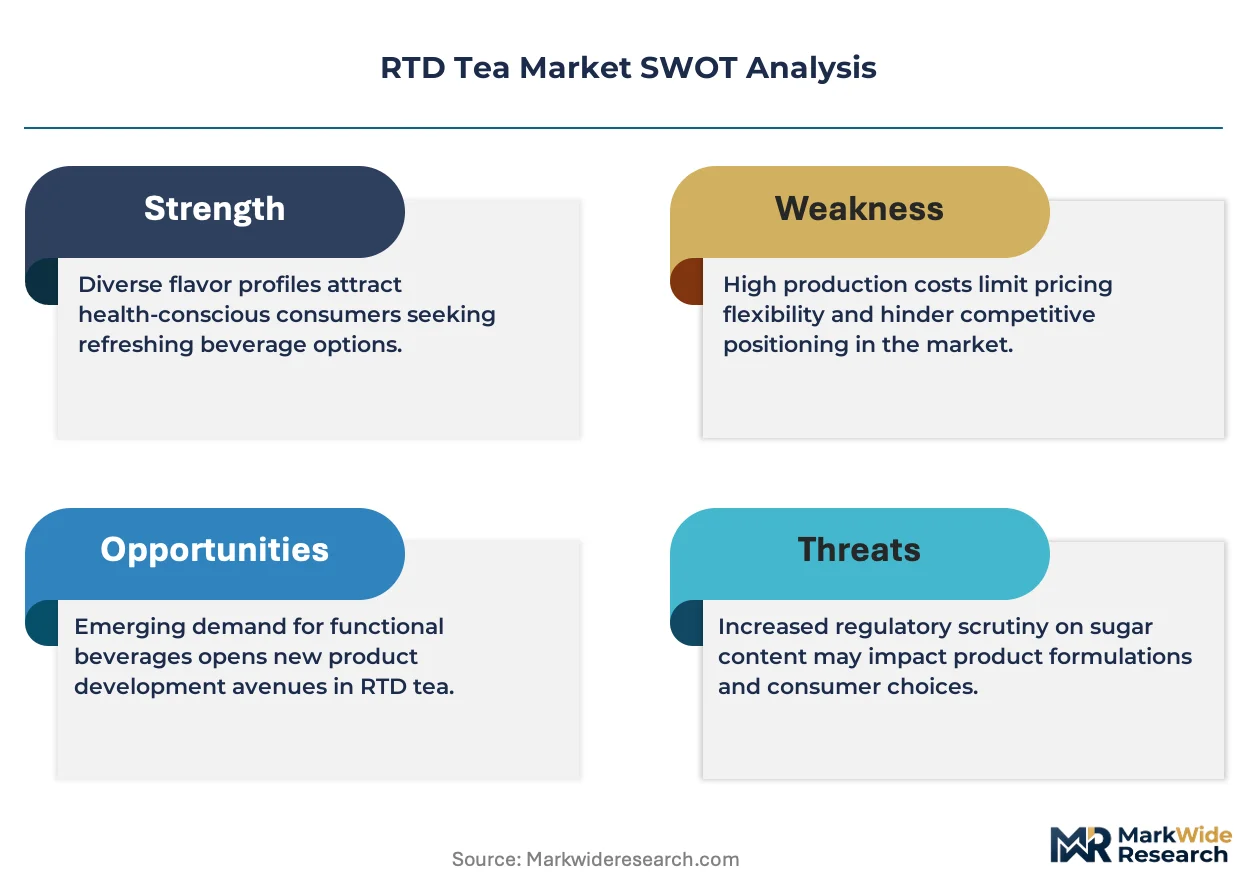
The FDA enforces juice and beverage labeling rules that constrain added-sugar declarations and nutrient content claims across US RTD tea portfolios. EFSA and EU Green Deal frameworks mandate recyclability targets and ingredient transparency that elevate packaging costs for exporters. Stakeholders must monitor evolving sugar-tax regimes and single-use packaging bans as these instruments increasingly determine market access and margin architecture.
Market Dynamics
Clean-label mandates and sugar-reduction frameworks are forcing wholesale reformulation across RTD tea portfolios, compressing legacy sweetener supply chains while opening procurement lanes for botanical extracts and natural flavor modulators.
Growth Catalysts
- EU Green Deal packaging mandates:Recyclability targets are accelerating fiber-based bottle trials and aluminum can conversions across European export portfolios.
- Functional ingredient pipelines:Adaptogen and nootropic infusions are capturing shelf space in US convenience channels as wellness-positioned SKUs command premium placement.
- China urban convenience density:Cold-chain expansion in Tier-1 and Tier-2 cities is enabling fresh-brewed RTD formats previously limited to ambient distribution.
Market Restraints
- Tea leaf supply concentration:Kenyan and Sri Lankan auction volumes dominate orthodox black tea inputs, creating price volatility exposure during regional climate events.
- Natural sweetener cost premiums:Stevia and monk fruit extracts trade at multiples above high-fructose corn syrup, compressing gross margins on reduced-sugar formulations.
- Aseptic bottling capex thresholds:Hot-fill line conversions require seven-figure investments that filter out sub-scale contract manufacturers.
Strategic Opportunities
- India modern trade expansion:Organized retail penetration in Mumbai, Delhi, and Bangalore is creating branded RTD shelf space previously monopolized by loose-leaf traditions.
- CBD and hemp-derived infusions:Evolving state-level frameworks in the US are opening regulatory pathways for cannabinoid-positioned wellness beverages.
- Direct-to-subscription models:Curated flavor discovery boxes are bypassing traditional distributor markups while building recurring revenue pools.
Industry Challenges
- Clean-label certification timelines:Organic and non-GMO verification cycles extend 12-18 months, delaying new product launches behind reformulation deadlines.
- Cold-chain integrity gaps:Refrigerated last-mile distribution remains underdeveloped in Southeast Asian secondary cities, spoiling fresh-positioned SKUs before retail.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RTD Tea Market |
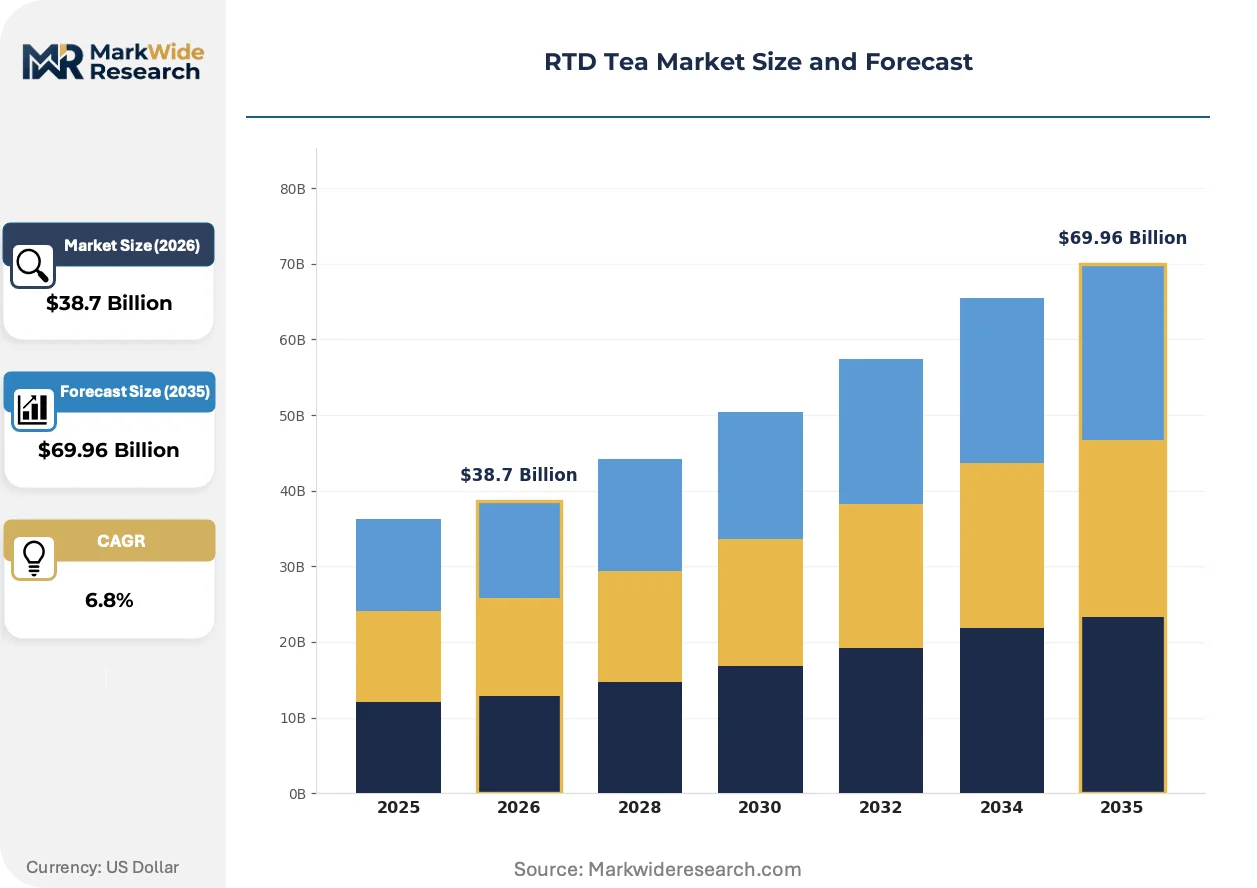
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Green Tea, Black Tea, Herbal Tea, Fruit Tea Packaging Type: Bottles, Cans, Pouches, Tetra Packs Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Food Service Flavor Profile: Citrus, Berry, Mint, Spiced |
| Companies Covered | Arizona Beverages USA LLC, Milo’s Tea Company, Inc., The Coca-Cola Company, Reily Foods Company, Ito En, Ltd., PepsiCo, Inc., Nestlé S.A., Red Diamond, Inc., Keurig Dr Pepper, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RTD Tea Market Strategic Shifts
Reformulation chemistry and packaging substrate innovation are converging to redefine what constitutes a premium RTD tea experience, collapsing the historical trade-off between shelf stability and ingredient transparency.
Pulse electric field pasteurization is integrating non-thermal microbial reduction protocols that preserve volatile aromatic compounds lost in conventional heat treatment. Premium positioned brands in Japan and South Korea are adopting PEF lines to support raw-brewed claims and extended refrigerated shelf life. The technology is integrating high-pressure processing workflows into co-packing facilities previously dedicated solely to hot-fill operations.
EFSA novel food ingredient approvals are tightening evidentiary requirements for botanical extracts and bioactive compounds entering European formulations. Manufacturers must now submit comprehensive toxicology dossiers and stability data before securing market authorization. This regulatory tightening most affects functional-positioned green tea extracts and adaptogen blends targeting cognitive health claims.
Convenience-oriented purchasing is rotating toward single-serve pouches and flexible spouted formats in grab-and-go channels across Brazil, Mexico, and Indonesia. Traditional multi-serve PET bottles are losing velocity in urban transit corridors where portability trumps per-ounce value. This format migration is most visible in São Paulo and Jakarta, where ambient-stable pouches now dominate street-vendor inventory.
RTD Tea Market Segmentation
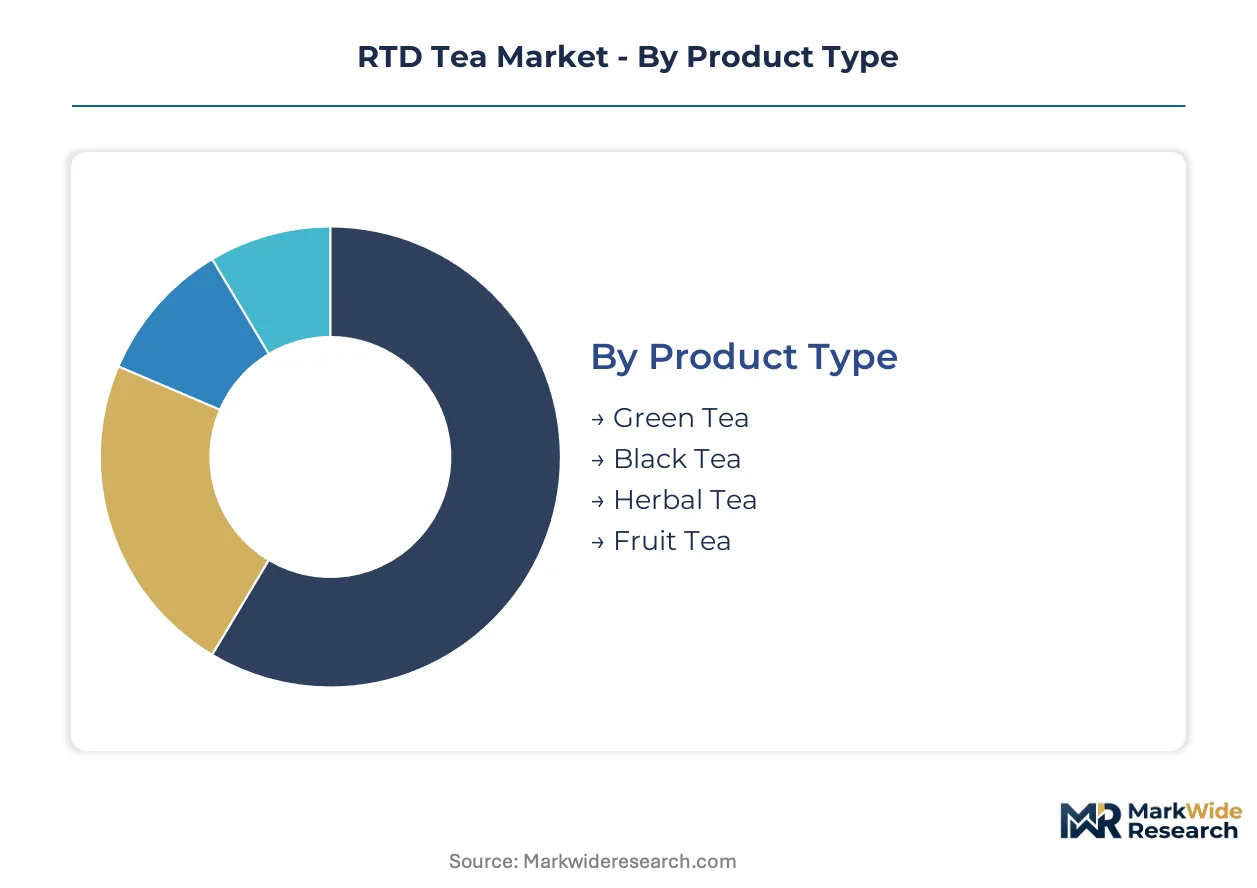
RTD tea segmentation reflects divergent consumption occasions and supply chain capabilities. Product type determines procurement geography and processing technology. Packaging format dictates cold-chain investment and retail channel access.
Product Type:
Purchase decisions pivot on perceived functional benefit and caffeine tolerance.
- Green Tea:Unoxidized Camellia sinensis leaves processed through steaming or pan-firing preserve catechins and EGCG compounds. Demand clusters in Chinese and Japanese urban centers where antioxidant claims drive premium positioning; FDA scrutiny of health claims constrains US labeling flexibility.
- Black Tea:Fully oxidized leaves deliver higher caffeine content and robust flavor profiles suited to sweetened formulations. Kenyan and Sri Lankan auction houses supply orthodox grades for premium bottling; climate volatility in East Africa creates raw material price instability.
- Herbal Tea:Botanical infusions excluding Camellia sinensis target caffeine-averse demographics and evening consumption occasions.
- Fruit Tea:Juice-blended formulations merge tea polyphenols with familiar fruit flavors for entry-level RTD trial.
Volume sits with Black Tea; growth tilts toward Green Tea.
Packaging Type:
Format selection balances shelf stability requirements against sustainability mandates and channel economics.
- Bottles:PET and rPET containers dominate ambient distribution through hot-fill or aseptic processing at pH below 4.6. Multi-serve formats anchor supermarket velocity in the United States and Germany; lightweighting initiatives respond to EU Green Deal recyclability targets.
- Cans:Aluminum formats enable rapid chilling and infinite recyclability loops. Energy-intensive production and coating chemistry costs limit adoption among mid-tier brands; deposit-return schemes in Scandinavian markets accelerate aluminum conversion.
- Pouches:Flexible laminated films with spouted closures reduce material weight and shipping cube. São Paulo and Jakarta street vendors stock ambient-stable pouches for transit-oriented consumption; aseptic filling complexity raises technical barriers for contract manufacturers.
- Tetra Packs:Aseptic carton systems sustain European food service distribution without refrigerated logistics.
Revenue concentrates in Bottles; sustainability pressure favors Cans.
Distribution Channel:
Channel strategy determines margin structure and brand control depth.
- Supermarkets:Organized retail chains in India and Brazil allocate expanding shelf space to branded RTD formats previously crowded out by loose-leaf traditions. Slotting fees and promotional calendars compress net margins for emerging entrants.
- Online Retailers:Direct-to-subscription models bypass distributor markups and build recurring revenue pools. Curated discovery boxes target flavor experimentation in US and UK metropolitan markets; last-mile refrigeration remains inconsistent for fresh-positioned SKUs.
- Convenience Stores:Grab-and-go positioning commands impulse purchase premiums in Japanese and South Korean urban corridors.
- Food Service:Ambient Tetra Pack formats reduce cold-chain dependency for European café and hospitality channels.
Transaction volume flows through Supermarkets; margin expansion favors Online Retailers.
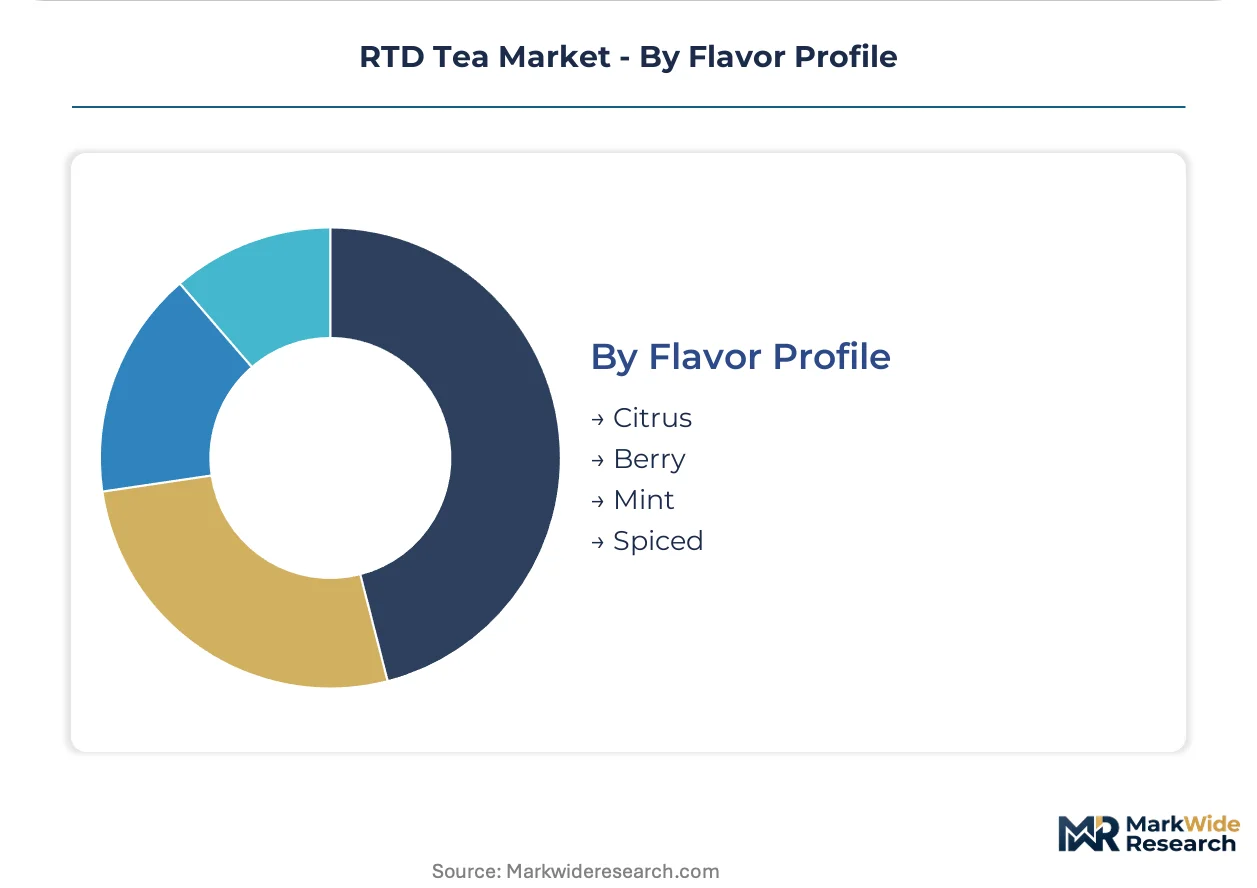
Flavor Profile:
Flavor innovation bridges tea authenticity with mass-market palatability.
- Citrus:Lemon and yuzu extracts mask astringency in reduced-sugar green tea formulations. Japanese and South Korean manufacturers lead volatile aromatic preservation through pulse electric field pasteurization.
- Berry:Anthocyanin-rich fruit blends support antioxidant positioning in North American wellness channels. Stevia and monk fruit natural sweetener cost premiums compress gross margins on berry-positioned reduced-sugar lines.
- Mint:Mentholated profiles differentiate herbal tea offerings in Middle Eastern and North African markets.
- Spiced:Chai-inspired cinnamon and cardamom formulations target South Asian diaspora communities in the United Kingdom and Canada.
Velocity concentrates in Citrus; steepest expansion trajectory belongs to Berry.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Camellia sinensis cultivation clusters in China's Fujian and Zhejiang provinces anchor raw material flows for Asia-Pacific RTD processing. Japanese tea gardens supply high-grade tencha and sencha for premium extraction. Indian Assam and Darjeeling estates feed black tea concentrate demand across South Asian bottling corridors.
China
Urban convenience density in Shanghai and Beijing accelerates cold-chain RTD penetration previously limited to ambient formats. SAMR enforces stricter nutrient labeling for sugar-reduced beverages. The Yangtze River Delta manufacturing corridor hosts aseptic bottling facilities supplying domestic and export volumes.
United States
Millennial wellness positioning drives functional green tea and adaptogen-infused SKU velocity in California and New York metropolitan markets. FDA juice and beverage labeling rules constrain added-sugar declarations and health claims. Texas and Florida distribution hubs manage refrigerated last-mile logistics for fresh-brewed product lines.
Japan
Pulse electric field pasteurization adoption preserves volatile aromatics in premium raw-brewed formulations for Tokyo and Osaka convenience channels. METI standards guide food-contact material specifications for aluminum can and bottle substrates. Shizuoka Prefecture tea cooperatives supply backward-integrated garden-to-bottle traceability for heritage brands.
Germany
EU Green Deal recyclability mandates accelerate rPET lightweighting and fiber-based bottle trials across Bavarian and North Rhine-Westphalia production sites. EFSA novel food approvals tighten botanical extract authorization timelines. Hamburg and Rotterdam port clusters manage bulk tea concentrate imports for European formulation facilities.
India
Organized retail expansion in Mumbai, Delhi, and Bangalore creates branded RTD shelf space previously monopolized by loose-leaf traditions. FSSAI packaging and labeling regulations govern ingredient disclosure and health claim substantiation. Assam and West Bengal processing plants supply black tea concentrates for domestic bottling and regional export.
RTD Tea Market Competitive Environment
Portfolio diversification dominates the current landscape as incumbents broaden flavor pipelines and functional positioning to capture wellness-oriented consumption shifts. The vendor base organizes around three strategic archetypes: multinational beverage conglomerates with global procurement networks, regional specialists leveraging backward integration into tea gardens, and mid-tier contract bottlers serving private-label programs. Two competitive moves define current dynamics: geographic expansion into underpenetrated modern trade channels and technology licensing for non-thermal pasteurization protocols.
Among multinational beverage conglomerates, The Coca-Cola Company and PepsiCo, Inc. exemplify scale-driven procurement and distribution architectures spanning multiple tea origins and flavor platforms. Ito En, Ltd. occupies a distinct position within the garden-integrated specialist tier, anchoring competitive differentiation through captive Japanese tea supply chains and heritage processing methods. These three entities collectively represent the dominant competitive vectors shaping formulation standards, packaging innovation, and channel access across key regional markets.
| Leading Market Players |
|---|
| Arizona Beverages USA LLC |
| Milo's Tea Company, Inc. |
| The Coca-Cola Company |
| Reily Foods Company |
| Ito En, Ltd. |
| PepsiCo, Inc. |
| Nestlé S.A. |
| Red Diamond, Inc. |
| Keurig Dr Pepper, Inc. |
| Others |
Value Chain & Pricing Dynamics
Specialized aseptic bottling technicians in Germany's North Rhine-Westphalia corridor command wage premiums that compress mid-tier margins while enabling premium pricing for cold-fill certified lines. Labor-cost differentials between automated European facilities and manual South Asian contract operations drive 40-60 point spreads across premium, standard, and economy positioning tiers.
Pricing Analysis
Service bundling separates premium RTD tea positioning from stripped-down economy tiers, with cold-chain integrity guarantees and organic certification maintenance included at upper levels while basic ambient-stable formats carry unbundled logistics risk. Three-tier pricing structure across premium, standard, and economy levels reflects stevia and monk fruit extract cost premiums versus high-fructose corn syrup formulations. Pricing pressure stems from natural sweetener input volatility as Kenyan auction prices for orthodox black tea fluctuate with regional drought cycles. Convenience store buyers in Japanese urban corridors show least price sensitivity, while Southeast Asian street vendors purchasing ambient pouches operate on thinnest margins.
Supply Chain Analysis
EU Green Deal local-content mandates for recyclability certification are reshaping sourcing patterns, pushing brands toward European rPET suppliers and domestic aluminum can coating facilities. Raw material flows draw from Kenya and Sri Lankan auction houses for orthodox black tea, Shizuoka Prefecture cooperatives for Japanese green tea, and Fujian province gardens for Chinese oolong inputs. Stevia leaf extraction and monk fruit concentrate processing hinge on Yunnan and Guizhou agricultural networks. Single-source vulnerability concentrates in East African tea auctions where climate events disrupt availability. Distribution runs through temperature-controlled hubs in Texas and Florida managing fresh-brewed last-mile logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The RTD tea market functions as a cost-of-compliance arena where EFSA novel food approval timelines and EU Green Deal packaging mandates erect twelve-to-eighteen-month barriers that filter out undercapitalized entrants and reward prepared incumbents.
For Market Incumbents: Lock in backward integration into Japanese tencha gardens or Kenyan orthodox auction contracts to secure volume commitments before climate volatility spikes input costs. Invest in pulse electric field pasteurization licensing to support raw-brewed premium claims that command shelf space against hot-fill commodity competitors. Channel control through direct-to-subscription platforms reduces distributor markup exposure while building recurring revenue pools insulated from slotting fee inflation.
For New Entrants and Emerging Players: Caffeine-averse evening consumers represent the most penetrable white-space segment, with herbal and adaptogen-infused formulations capturing trial among wellness-positioned millennials in California and New York metropolitan corridors. India's organized retail expansion in Mumbai, Delhi, and Bangalore offers branded shelf space previously monopolized by loose-leaf traditions. A curated discovery box go-to-market angle bypasses traditional distributor gatekeepers while generating flavor preference data for retail negotiations.
For Investors and Strategic Acquirers: Re-rating potential sits with garden-integrated specialists possessing captive Japanese tea supply chains and heritage processing methods, given functional ingredient pipeline expansion and adaptogen infusion demand acceleration. Long-term viability favors entities with demonstrated EFSA submission capabilities and established cold-chain partnerships across Southeast Asian secondary cities. Watch for FDA guidance clarity on cannabinoid-positioned wellness beverages as the inflection signal separating compliant first-movers from stranded late entrants.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tea Gardens | Captive supply from Shizuoka cooperatives insulates against Kenyan auction volatility. |
| Pulse Electric Field Licensing | Non-thermal pasteurization preserves volatile aromatics for premium raw-brewed positioning. |
| Direct-to-Subscription Launch | Curated discovery boxes bypass distributor markups in US and UK metropolitan markets. |
| EU Green Deal Packaging Conversion | rPET lightweighting and fiber-based trials secure market access across German retail channels. |
| Functional Ingredient Pipeline Expansion | Adaptogen and nootropic infusions capture premium placement in wellness-oriented convenience channels. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with RTD tea brand managers, category buyers at organized retailers, aseptic bottling facility engineers, and Japanese tea cooperative supply directors. FDA juice and beverage labeling rules, EFSA novel food ingredient approvals, and SAMR nutrient labeling guidelines provided regulatory boundary conditions. Bottom-up volume modeling across packaging formats and product types triangulated against top-down macroeconomic consumption indicators.
Granularity-level modeling operated at SKU-level for premium green tea and adaptogen-infused segments, with black tea and herbal categories aggregated to regional cluster. Segmentation dimensions included product type, packaging substrate, distribution channel, and flavor profile, with cold-chain capability serving as an industry-specific cross-cutting variable. CAGRs derived from historical trajectory analysis adjusted for regulatory intervention timing and format substitution elasticities. Stevia and monk fruit extract cost curves, plus Kenyan auction price volatility indices, fed input cost sensitivity modules.
Revisions become necessary when EFSA tightens botanical extract evidentiary requirements, FDA issues cannabinoid beverage guidance, or climate events disrupt East African tea harvests beyond historical variance bands. Forecasts reflect documented assumptions regarding cold-chain infrastructure buildout rates and organized retail penetration timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Black Tea Market
Tea
Out of Home Tea Market
Tea
Europe Green Tea Market
Tea
Tea Packaging Market
Tea
Spray-Dried Tea Products Market
Tea
Green Tea Extract Market
Tea
Green Tea Leaves Market
Tea
Matcha Products Market
Tea
Matcha Market
Tea
Nitro Tea Market
Tea
Plant Based New Tea Drink Market
Tea
Tea Concentrate Market
Tea
Edible Tea Market
Tea
Ready-To-Drink (RTD) Tea Market
Tea
Detox Tea Market
Tea
Global Tea Market