
 North America Bottled Water Market | 2026-2036
North America Bottled Water Market Size, Share, and Industry Trends Forecast 2026-2036
North America Bottled Water Market Outlook
Food service and hospitality procurement is hardening around premium and sparkling formats as restaurants rebuild post-pandemic beverage programs. Niagara Bottling sustains manufacturing scale through high-speed PET lines across California and Texas. PepsiCo leverages its direct-store-delivery network to control convenience channel placement. Danone S.A. anchors its position in mineral and spring water through regional source protection in the Northeast and Pacific Northwest.
Bottled water comprises potable water packaged in sealed containers for retail sale, sourced from springs, wells, or municipal supplies then treated through reverse osmosis, distillation, or deionization to meet potability and taste standards. Purified water commands volume leadership due to lower source dependency and flexible co-packing arrangements, while sparkling water captures faster growth as flavored carbonated variants displace sugary sodas in household refrigerators. PET bottles dominate packaging economics through lightweighting and recycled content integration, though aluminum cans and cartons gain shelf space in online retail channels.
The US FDA enforces standards of identity and current good manufacturing practices for bottled water under 21 CFR 165.110, while Health Canada's CFIA oversees labeling and microbiological limits; California's SB 270 plastic bag and extended producer responsibility frameworks pressure packaging redesign. The EPA's emerging contaminant monitoring list including PFAS compounds shapes filtration technology investments. Stakeholders must monitor state-level deposit legislation expansion and recycled content mandates to preempt compliance costs and secure source access.
Market Dynamics
California's SB 270 extended producer responsibility framework and parallel state mandates across the US Sun Belt are forcing packaging redesign investments that compress margins while creating compliance-based competitive moats for capitalized producers.
Growth Catalysts
- PFAS Filtration Mandates:The EPA's emerging contaminant monitoring list drives capital deployment toward advanced reverse osmosis and activated carbon systems at municipal-tap-fed bottling facilities.
- Fitness Center Channel Expansion:Post-pandemic gym membership recovery in Texas and Florida elevates single-serve PET placement in high-traffic wellness locations.
- Sparkling Format Premiumization:Flavored carbonated variants displace sugary sodas in household refrigerators across the US Northeast and Pacific Northwest.
Market Restraints
- rPET Feedstock Volatility:Post-consumer PET flake supply concentrates in California and Texas sorting facilities, creating regional price dislocation for lightweighting programs.
- Spring Source Access Concentration:Protected aquifer rights in the Northeast and Pacific Northwest limit new mineral water entrants to legacy permit holders.
- Aluminum Can Substitution Economics:Canned water formats in online retail channels erode PET bottle volume in premium sparkling segments.
Strategic Opportunities
- Underpenetrated Canadian Prairie Provinces:Alberta and Saskatchewan show per capita consumption gaps versus Ontario and British Columbia, creating whitespace for regional spring source development.
- Direct-to-Consumer Subscription Models:E-commerce platforms enable recurring delivery of large-format multi-packs to suburban households in Arizona and Nevada.
- Biodegradable Bottle Technology Convergence:PHA and PLA material advances align with California's recycled content mandates to create compostable packaging pathways.
Industry Challenges
- Quality Control Talent Scarcity:Microbiological testing and filtration engineering expertise concentrates at legacy facilities in California and Texas, constraining expansion timelines.
- Legacy Equipment Retrofit Complexity:High-speed PET lines require substantial capital outlay to integrate recycled content streams without throughput degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Bottled Water Market |
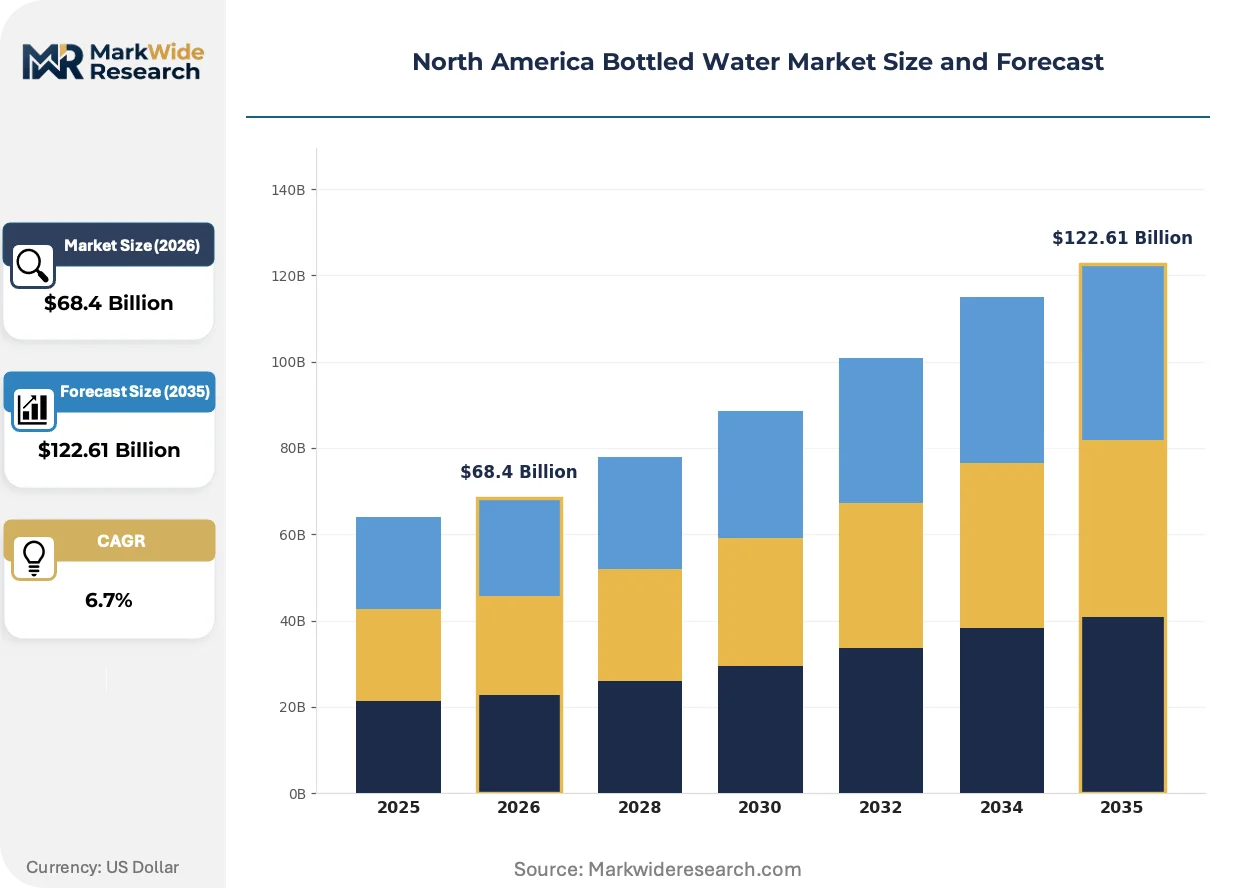
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $122.61 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spring Water, Purified Water, Mineral Water, Sparkling Water Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Vending Machines Packaging Type: Pet Bottles, Glass Bottles, Cartons, Bulk Containers End User: Household, Commercial, Food Service, Sports |
| Companies Covered | BlueTriton Brands, Inc., Niagara Bottling, LLC, PepsiCo, Inc., The Coca-Cola Company, Primo Brands Corporation, Danone S.A., Keurig Dr Pepper Inc., Crystal Geyser Water Company, Mountain Valley Spring Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Bottled Water Market Strategic Shifts
Material science breakthroughs and regulatory pressure on plastic waste are converging to reshape packaging formats and production economics across the North American bottled water value chain.
Lightweighting technology is expanding into sub-10-gram PET bottle designs through advanced preform engineering and stretch-blow molding optimization. Major retail chains in the US Sun Belt are accelerating adoption to meet corporate sustainability commitments. This compression of material intensity per unit is expanding into cost structures that favor high-volume producers with captive recycling operations.
The EPA's PFAS monitoring requirements and California's SB 270 extended producer responsibility framework are tightening filtration and labeling compliance thresholds. Bottlers sourcing from municipal supplies face stepped-up capital requirements for multi-stage treatment systems. Facilities in Texas and Arizona are responding by consolidating testing laboratories and pursuing third-party certification to preempt enforcement actions.
Food service procurement is pivoting toward premium sparkling and flavored variants as restaurants rebuild post-pandemic beverage programs. Independent dining establishments in Florida and California are displacing fountain soda contracts with branded bottled water placements. This shift concentrates most visibly in coastal metropolitan markets where menu premiumization aligns with tourist-driven traffic recovery.
North America Bottled Water Market Segmentation
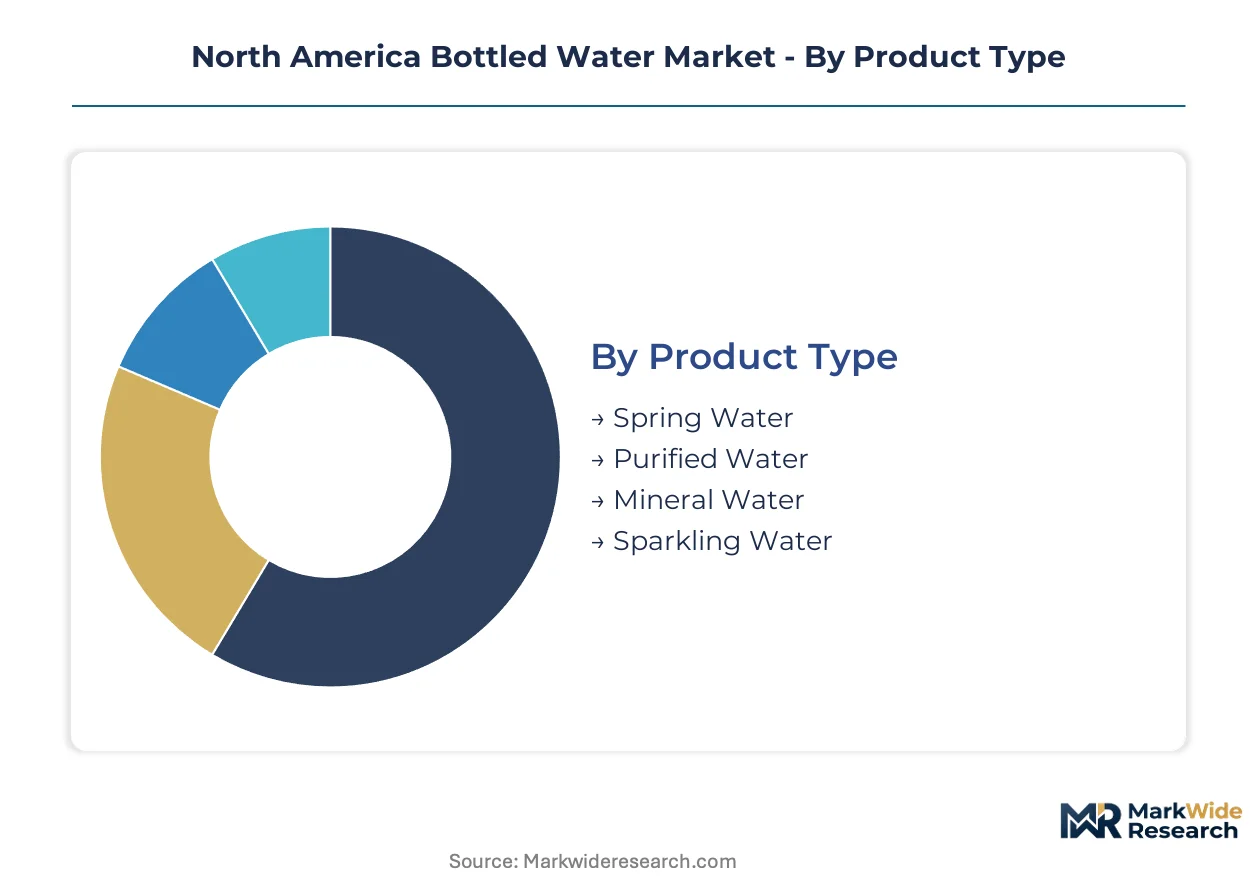
Segmentation in the North American bottled water market reveals how packaging economics, channel control, and source differentiation create distinct competitive arenas. Producers must align manufacturing configurations with the specific compliance and margin profiles of each segment cluster.
Product Type:
Customization ranges from standardized municipal-source purification to terroir-dependent spring and mineral sourcing that requires protected aquifer access.
- Spring Water:Sourced from protected underground formations in the Northeast and Pacific Northwest, this category carries premium positioning tied to regional terroir marketing. Bottlers with legacy permit holdings in Vermont and Oregon control access that new entrants cannot replicate.
- Purified Water:Reverse osmosis and deionization treatment of municipal supplies enables flexible co-packing arrangements and volume scaling. Demand concentrates in the US Sun Belt where heat stress elevates per capita consumption and private-label penetration is deepest.
- Mineral Water:Naturally occurring dissolved solids at specified levels require certified source protection and consistent mineral profiles. Regional producers in upstate New York and the Pacific Northwest maintain source exclusivity.
- Sparkling Water:Carbonated variants with natural or added flavors displace sugary sodas in household refrigerators across metropolitan markets.
Most installed capacity flows through Purified Water. Expansion is steepest in Sparkling Water.
Distribution Channel:
Channel economics separate high-frequency impulse purchases from planned household stocking and automated replenishment systems.
- Supermarkets:Multi-pack volume and promotional slotting fees dominate this channel. Retail chains in California and Texas use bottled water as traffic drivers with thin margins offset by manufacturer promotional funding.
- Convenience Stores:Single-serve PET at elevated price points captures immediate consumption occasions. Placement in Florida and Arizona locations depends on direct-store-delivery network density.
- Online Retail:Subscription models and large-format multi-packs reduce per-unit delivery costs for suburban households in Arizona and Nevada.
- Vending Machines:Automated dispensing in fitness centers and transit hubs elevates per-unit pricing with minimal labor overhead.
Supermarkets move the highest absolute volume. Online Retail is climbing the fastest.
Packaging Type:
Material selection trades off lightweighting economics against sustainability signaling and format differentiation.
- PET Bottles:Sub-10-gram lightweight designs through advanced stretch-blow molding dominate cost structures. Recycled content integration responds to California's SB 270 mandates while maintaining throughput on high-speed lines.
- Glass Bottles:Premium positioning in food service and hospitality channels supports higher price realization despite logistics constraints.
- Cartons:Shelf-stable formats gain space in online retail channels where breakage risk and weight penalties matter less.
- Bulk Containers:Refillable and dispenser-compatible formats serve commercial accounts and household subscription models.
PET Bottles carry the dominant share of unit volume. Glass Bottles show the steepest expansion trajectory in premium sparkling segments.
End User:
User context determines packaging format, purchase frequency, and price elasticity across consumption occasions.
- Household:Multi-pack procurement through supermarkets and online subscription balances convenience against per-unit cost minimization.
- Commercial:Office and institutional accounts prioritize dispenser compatibility and bulk delivery logistics.
- Food Service:Post-pandemic beverage program rebuilding in Florida and California restaurants elevates premium and sparkling placements over fountain soda contracts.
- Sports:Fitness center channel recovery in Texas and Florida drives single-serve PET placement in high-traffic wellness locations.
Household consumption absorbs the largest volume share. Food Service is expanding most quickly as dining establishments premiumize beverage offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migrates toward jurisdictions with lower compliance thresholds for recycled content mandates, creating arbitrage opportunities between US states and Canadian provinces with divergent extended producer responsibility frameworks.
United States
Heat stress and tourism elevate per capita consumption across Sun Belt states, particularly Texas and Florida where fitness center channel recovery drives single-serve PET placement. The FDA enforces standards of identity under 21 CFR 165.110 while California's SB 270 pressures packaging redesign investments. Niagara Bottling sustains manufacturing scale through high-speed PET lines across California and Texas facilities.
Canada
Per capita consumption gaps in Alberta and Saskatchewan versus Ontario and British Columbia create whitespace for regional spring source development. Health Canada's CFIA oversees labeling and microbiological limits with tightening compliance thresholds. Quebec and Ontario maintain established bottling infrastructure serving metropolitan markets with stricter provincial environmental standards.
Mexico
Municipal water quality variability elevates reliance on purified bottled formats for household consumption across Mexico City and northern industrial corridors. The national health regulator enforces potability standards while informal distribution networks dominate rural penetration. Monterrey and Guadalajara anchor formal retail channel development with expanding convenience store infrastructure.
North America Bottled Water Market Competitive Environment
Capacity expansion dominates the current landscape as producers retrofit high-speed PET lines to integrate recycled content streams without throughput degradation. The vendor base concentrates around capitalized players with captive recycling operations and legacy source permits, creating tiered competition between integrated national bottlers and regional spring-water specialists. Two strategic archetypes prevail: scale-driven purified water producers leveraging flexible co-packing arrangements, and terroir-dependent mineral water guardians controlling protected aquifer access. Geographic expansion into underpenetrated Canadian Prairie Provinces and portfolio diversification toward sparkling formats represent the dominant competitive moves.
Within the scale-driven tier, Niagara Bottling and PepsiCo exemplify manufacturing configurations optimized for high-volume purified water production across multiple US jurisdictions. Danone S.A. occupies a differentiated position representing the mineral water archetype with regional source protection strategies. BlueTriton Brands anchors the middle ground between these poles, reflecting portfolio breadth spanning spring, purified, and value-added formats.
| Leading Market Players |
|---|
| BlueTriton Brands, Inc. |
| Niagara Bottling, LLC |
| PepsiCo, Inc. |
| The Coca-Cola Company |
| Primo Brands Corporation |
| Danone S.A. |
| Keurig Dr Pepper Inc. |
| Crystal Geyser Water Company |
| Mountain Valley Spring Company |
| Others |
Value Chain & Pricing Dynamics
rPET flake price volatility cascades through North American bottling economics, compressing margins for lightweighting programs while concentrating pricing power with producers holding captive recycling operations in California and Texas.
Pricing Analysis
Retailer markup layers in the supermarket channel absorb manufacturer promotional funding to maintain traffic-driving price points. Three-tier pricing structure across premium spring, standard purified, and economy private-label levels separates terroir-protected mineral water from municipal-source purification. Cost compression in the economy tier intensifies because rPET feedstock volatility squeezes co-packing arrangements. Food service buyers show least price sensitivity as menu premiumization justifies sparkling format placements.
Supply Chain Analysis
FDA certification under 21 CFR 165.110 gates facility operation and shapes supplier qualification protocols across the value chain. Raw material flows draw from post-consumer PET sorting concentrated in California and Texas, virgin resin production along the US Gulf Coast, and aluminum can sheet from domestic rolling mills. Single-source vulnerability in spring aquifer access limits new mineral water entrants to legacy permit holders in Vermont and Oregon. Distribution runs through direct-store-delivery networks for convenience channel control and wholesale pallet delivery for supermarket volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on biodegradable packaging technology convergence reducing compliance costs under California's SB 270 mandates.
For Market Incumbents: Extend source protection agreements in the Northeast and Pacific Northwest to block mineral water challengers. Retrofit high-speed PET lines for recycled content integration without throughput degradation to defend against aluminum can substitution in sparkling segments. For New Entrants and Emerging Players: PHA and PLA material advances offer technology-first wedge positioning against legacy PET-dependent producers. Target underpenetrated Canadian Prairie Provinces with regional spring source development and direct-to-consumer subscription models for suburban Arizona and Nevada households. For Investors and Strategic Acquirers: Asymmetric upside sits with regional spring-water specialists holding protected aquifer permits in Vermont and Oregon. Long-term viability over the projection horizon hinges on portfolio diversification toward sparkling formats and biodegradable packaging pathways. Watch for state-level deposit legislation expansion as inflection indicator for compliance cost acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Source Protection Agreement Extension | Legacy permit holdings in Vermont and Oregon create mineral water entry barriers. |
| Biodegradable Packaging Transition | PHA and PLA advances align with California SB 270 recycled content mandates. |
| Direct-to-Consumer Subscription Launch | Recurring delivery models reduce per-unit logistics costs for suburban Sun Belt households. |
| High-Speed Line Recycled Content Retrofit | rPET integration without throughput degradation defends against aluminum can erosion. |
| Canadian Prairie Province Expansion | Alberta and Saskatchewan consumption gaps create whitespace for regional spring development. |
Study Parameters
Multiple input streams — bottling facility operations data, retail channel audit records, regulatory filing databases — were reconciled through bottom-up and top-down triangulation. Primary interviews with plant managers, category buyers at retail chains, distribution channel partners, and regulatory compliance officers were validated against secondary sources including FDA enforcement records, Health Canada CFIA guidance documents, EPA emerging contaminant monitoring reports, and state-level extended producer responsibility filings.
Data-stream reconciliation anchored volume and value outputs across the modeling period. Segmentation dimensions modeled include product type, packaging format, distribution channel, and regional regulatory cluster. CAGRs were derived from trend extrapolation of historical consumption patterns and forward projection of compliance cost trajectories. Forecast inputs incorporated PFAS filtration capital deployment schedules and fitness center channel recovery velocities in Texas and Florida.
The model holds under stable recycled content mandate enforcement; deviation in EPA PFAS regulatory escalation or state-level deposit legislation expansion would shift capacity investment timelines. Forecasts reflect assumptions about rPET feedstock availability and spring source permit renewal rates. A model refresh is warranted upon material change in California SB 270 implementation stringency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Global RTD Tea Drinks Market
Non-Alcoholic Beverages
Africa Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
Low- and No-Calorie Soda Market
Non-Alcoholic Beverages
Ice Tea Market
Non-Alcoholic Beverages
Zero Sugar Beverages Market
Non-Alcoholic Beverages
Global Non-Alcoholic RTD Beverages Market
Non-Alcoholic Beverages
Vietnam Energy Drinks Market
Non-Alcoholic Beverages
Isotonic Drinks Market
Non-Alcoholic Beverages
United States Energy Drink Market
Non-Alcoholic Beverages
United Arab Emirates Bottled Water Market
Non-Alcoholic Beverages
Coffee Substitute Market
Non-Alcoholic Beverages
Japan Soy Beverages Market
Non-Alcoholic Beverages
US Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
Sugar Free Carbonated Drinks Market
Non-Alcoholic Beverages
Pearl Milk Tea Market
Non-Alcoholic Beverages
Europe Sports and Energy Drinks Market