
 Europe Soy Beverages Market | 2026-2036
Europe Soy Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Soy Beverages Market Foresight
EU Organic certification is bifurcating the Europe soy beverages competitive landscape into qualified and non-qualified supply tiers. Danone S.A. leverages its refrigerated logistics network to dominate conventional retail channels across Western Europe. Valsoia S.p.A. specializes in organic and free-from formulations that command premium positioning in Italian and Iberian markets. Alpro sustains brand recognition through decades of European shelf presence and diversified flavor portfolios.
Soy beverages are aqueous extracts of whole soybeans or soy protein isolates, typically standardized to 2-4% protein content and homogenized for suspension stability, serving as functional dairy alternatives in coffee, cereal, and direct consumption applications. Unsweetened variants anchor volume in barista and culinary segments where neutral flavor profiles matter more than palatability. Flavored and organic categories capture disproportionate margin pools as health food shops and specialty stores reward clean-label positioning with shelf placement premiums. Tetra Pak aseptic packaging extends ambient distribution reach beyond refrigerated cold chains, reshaping geographic expansion economics for mid-tier producers.
EFSA novel food assessments and EU Organic Regulation 2018/848 govern ingredient sourcing claims and processing method disclosures, while REACH compliance obligations track chemical residues in packaging migration. EMA-adjacent nutritional health claim evaluations further constrain how brands communicate protein equivalence or cholesterol reduction benefits to consumers. Stakeholders must monitor evolving F-Gas Regulation impacts on refrigeration-dependent distribution networks and anticipate whether CSRD sustainability reporting requirements will reshape supplier qualification criteria ahead of the next procurement cycle.
Market Dynamics
EU Green Deal sustainability mandates are compressing conventional dairy supply chains while Tetra Pak aseptic packaging is supplanting refrigerated logistics as the dominant distribution infrastructure across mid-tier European producers.
Growth Catalysts
- EU Organic Regulation 2018/848:Certification requirements are bifurcating shelf access, rewarding compliant suppliers with placement premiums in French and German health food channels.
- Barista-grade unsweetened formulations:Neutral flavor profiles are capturing volume in coffee shop applications where functional performance outweighs palatability considerations.
- Netherlands cluster concentration:Alpro's decades-long shelf presence has normalized soy beverage consumption patterns across Benelux retail formats.
Market Restraints
- Soybean input cost volatility:Weather-driven harvest fluctuations in Argentinian and Brazilian growing regions transmit directly to European processor margins.
- EFSA novel food assessment timelines:Extended evaluation periods for new protein extraction methods delay product launch windows by 18-24 months.
- Oat and almond substitution:Alternative plant-based milks are capturing shelf space in Italian and Spanish conventional retail channels.
Strategic Opportunities
- Eastern European underpenetration:Polish and Romanian retail channels show minimal soy beverage SKU density versus Western European benchmarks.
- CSRD sustainability reporting:Mandatory disclosure requirements are creating procurement advantages for suppliers with verified carbon accounting.
- E-commerce direct-to-consumer channels:Subscription models are bypassing conventional retail slotting fee barriers for organic and specialty formulations.
Industry Challenges
- REACH compliance for packaging migration:Chemical residue testing protocols require specialized laboratory partnerships that smaller processors struggle to qualify.
- Refrigerated fleet reconfiguration:F-Gas Regulation phase-downs are forcing capital deployment into alternative cooling systems before asset end-of-life.
- EMA-adjacent health claim substantiation:Protein equivalence and cholesterol reduction messaging requires clinical trial investment that fragments marketing budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Soy Beverages Market |
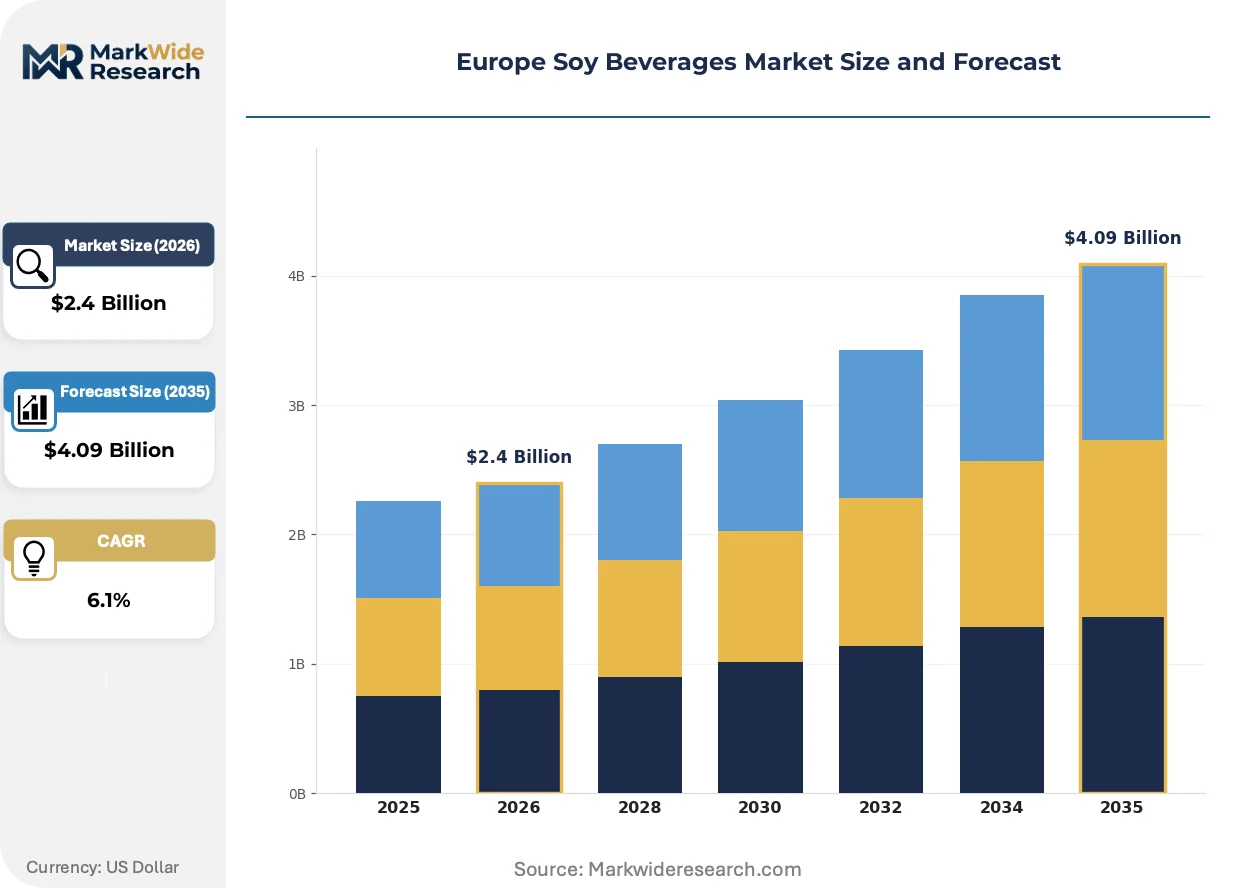
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.09 Billion |
| CAGR (2026 – 2036) | 6.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unsweetened, Sweetened, Flavored, Organic Distribution Channel: Supermarkets, Specialty Stores, Online Retail, Health Food Shops End User: Health-Conscious Consumers, Vegans, Lactose Intolerant Individuals, Athletes Packaging Type: Tetra Pak, Glass Bottles, Cans, Pouches |
| Companies Covered | Danone S.A., Vitasoy International Holdings Limited, Hain Celestial Group Inc., Valsoia S.p.A., SunOpta Inc., Alpro, Sojade, Eden Foods, Kikkoman Corp, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Soy Beverages Market Shifts & Advancements
Clean-label positioning and processing transparency are reshaping competitive differentiation as European consumers scrutinize ingredient provenance and environmental footprint claims with increasing sophistication.
Enzymatic debittering technology is supplanting conventional heat-treatment methods in soy protein extraction, preserving isoflavone bioactivity while eliminating beany off-notes. Italian organic specialists are adopting these systems at pilot scale, enabling premium positioning in Iberian markets where flavor neutrality commands price premiums. The shift is compressing capital requirements for new market entrants previously dependent on legacy thermal infrastructure.
EU F-Gas Regulation mandates are accelerating refrigeration infrastructure turnover across distribution networks serving temperature-sensitive formulations. Cold-chain operators in France and Germany are retrofitting fleets with natural refrigerant systems ahead of 2030 phase-down deadlines. Ambient-stable aseptic packaging is capturing share in Southern European markets where refrigerated logistics density remains underdeveloped.
Certification-driven purchasing patterns are fragmenting procurement criteria across European retail banners. Clean-label preferences in German metropolitan markets are diverging from price-sensitive volume purchasing in Italian discount channels. Specialty store buyers are rewarding organic and free-from formulations with preferential shelf placement, while conventional multiples negotiate standardized margin terms across plant-based categories.
Europe Soy Beverages Market Segmentation
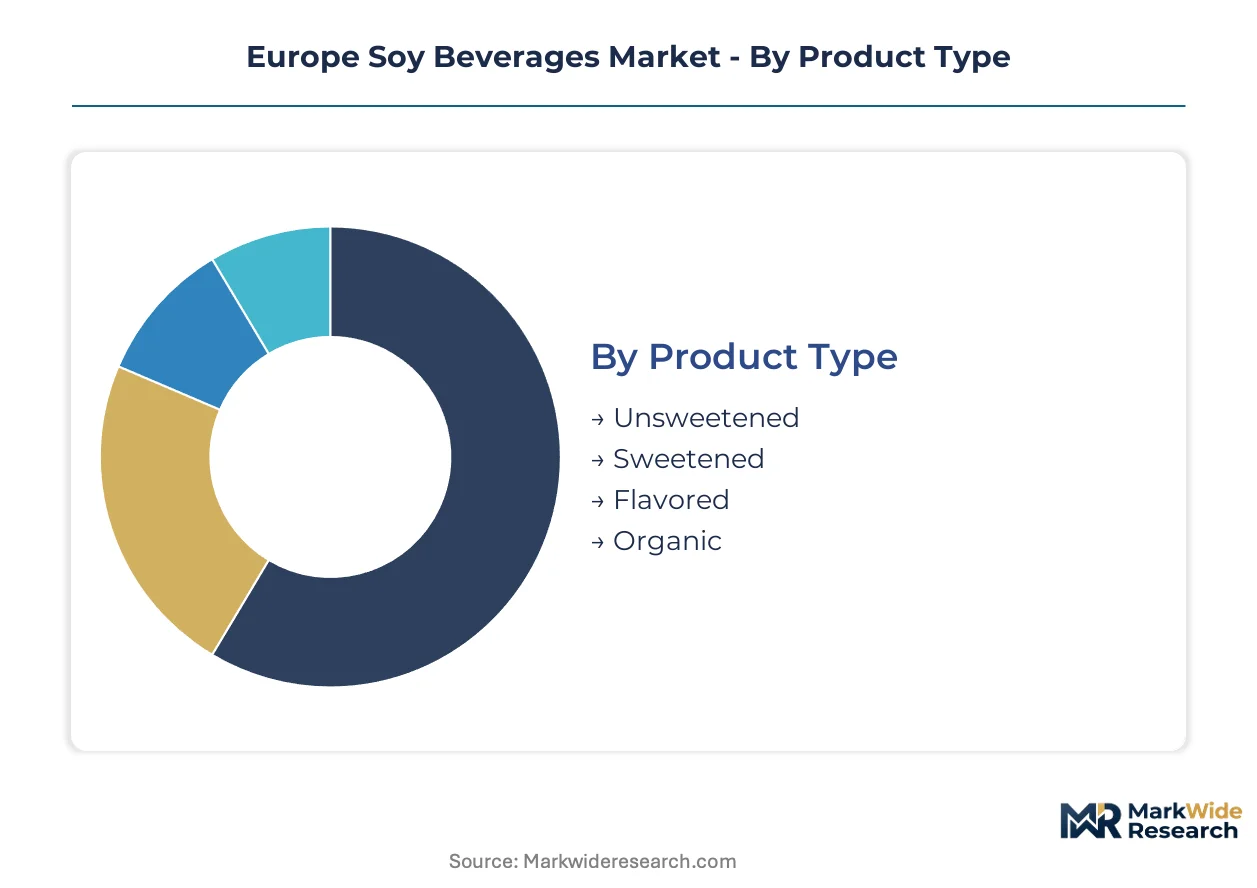
Soy beverage segmentation in Europe reflects divergent margin economics across certification tiers and channel formats. Organic and specialty variants command placement premiums in German and French health food channels, while conventional formulations compete on volume in Italian discount retail.
Product Type:
Margin pools concentrate in certified organic and clean-label formulations where EU Organic Regulation 2018/848 creates procurement barriers for non-compliant suppliers.
- Organic:EU Organic certification mandates govern ingredient sourcing and processing disclosures, restricting supply to qualified tiers. French and German health food channels reward compliant suppliers with preferential shelf placement and price premiums. The dominant share belongs to Unsweetened, while Organic is closing the gap fastest.
- Unsweetened:Neutral flavor profiles with 2-4% protein content anchor volume in barista and culinary applications across Benelux coffee shop chains. Functional performance outweighs palatability in these channels.
- Sweetened:Palatability-focused formulations target direct consumption in Italian and Iberian conventional retail.
- Flavored:Vanilla and chocolate variants capture impulse purchasing in French supermarket chilled sections.
Unsweetened formats lead volume, though Organic variants expand most quickly as certification requirements harden.
Distribution Channel:
Channel economics bifurcate between refrigerated logistics-dependent supermarket chains and ambient-stable e-commerce direct-to-consumer models.
- Health Food Shops:Specialty buyers reward organic and free-from formulations with preferential placement. German metropolitan markets show strongest clean-label purchasing divergence from price-sensitive Italian discount channels.
- Supermarkets:Conventional multiples negotiate standardized margin terms across plant-based categories, with Tetra Pak aseptic packaging enabling ambient distribution beyond cold-chain limitations.
- Specialty Stores:Curated assortments in urban centers emphasize provenance transparency and environmental footprint claims.
- Online Retail:Subscription models bypass slotting fee barriers for organic and specialty formulations, capturing direct consumer relationships.
Supermarkets retain volume leadership, yet Online Retail climbs fastest as procurement patterns fragment.
End User:
User segmentation tracks dietary restriction severity and performance orientation rather than demographic buckets.
- Vegans:Ethical consumption drivers prioritize organic certification and processing transparency, with Italian and Spanish markets showing strongest alignment between values-based purchasing and premium positioning.
- Health-Conscious Consumers:Protein equivalence and cholesterol reduction claims require EMA-adjacent substantiation, constraining marketing messaging for mid-tier brands.
- Lactose Intolerant Individuals:Functional dairy replacement needs concentrate in cereal and coffee applications across French and German households.
- Athletes:Performance-oriented protein positioning targets recovery applications in specialty fitness channels.
Health-Conscious Consumers represent the largest addressable base, while Vegans gain share fastest on values alignment.
Packaging Type:
Packaging selection determines distribution reach and refrigeration capital requirements.
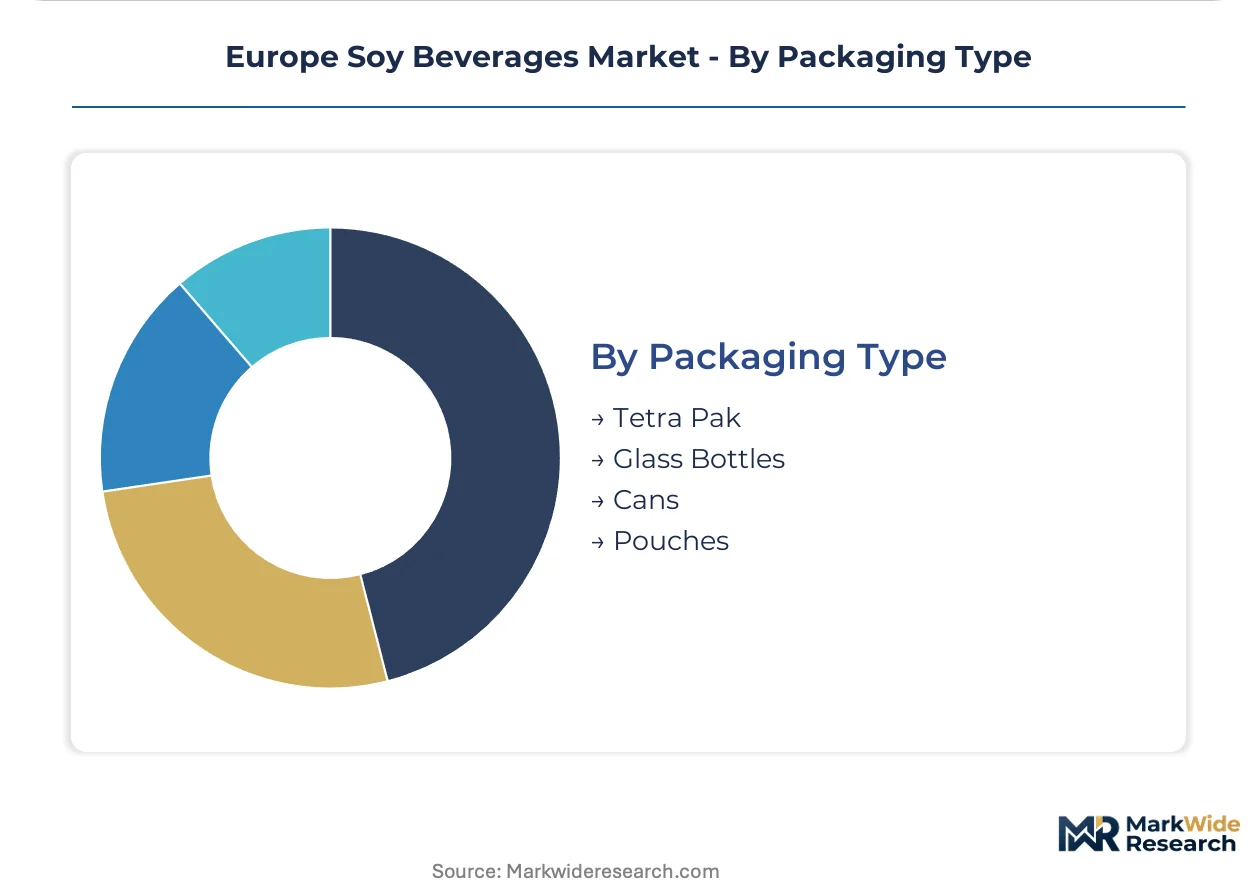
- Tetra Pak:Aseptic carton technology extends ambient shelf stability, reshaping geographic expansion economics for mid-tier producers across Southern European markets where refrigerated logistics density remains underdeveloped.
- Glass Bottles:Premium positioning in organic channels emphasizes recyclability and perceived purity, though weight increases transport costs.
- Cans:Single-serve formats target on-the-go consumption in urban convenience channels.
- Pouches:Flexible packaging reduces material intensity for bulk and foodservice applications.
Tetra Pak dominates installed base, though Glass Bottles advance quickest on sustainability signaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal sustainability mandates are compressing conventional dairy supply chains across member states while redirecting procurement budgets toward certified plant-based alternatives. National implementation of EU Organic Regulation 2018/848 is creating divergent shelf-access conditions from Paris to Warsaw. Tetra Pak aseptic packaging is supplanting refrigerated logistics as the dominant distribution infrastructure for mid-tier producers.
Germany
Health-conscious consumers in Berlin and Hamburg are driving organic certification premiums in metropolitan retail channels. EFSA novel food assessments govern protein extraction method approvals, delaying some product launches by 18-24 months. The Rhine-Ruhr industrial corridor hosts major refrigerated logistics networks that are retrofitting with natural refrigerant systems ahead of F-Gas Regulation phase-down deadlines.
France
Clean-label purchasing patterns in Paris and Lyon are diverging from price-sensitive volume buying in peripheral regions. ANSM and DGCCRF oversight of nutritional health claims constrains how brands communicate protein equivalence benefits. The Île-de-France region concentrates barista-grade formulation demand as specialty coffee chains expand unsweetened soy beverage procurement.
Italy
Values-based purchasing in Milan and Rome aligns vegan consumers with premium organic positioning. REACH compliance obligations for packaging migration testing require specialized laboratory partnerships that smaller processors struggle to qualify. The Emilia-Romagna cluster shows growing enzymatic debittering technology adoption among organic specialists targeting Iberian export markets.
Netherlands
Decades of normalized soy beverage consumption across Amsterdam and Rotterdam retail formats have created habitual purchasing patterns. CSRD sustainability reporting requirements are creating procurement advantages for suppliers with verified carbon accounting. The Randstad region anchors Benelux distribution networks that extend into underpenetrated Eastern European channels.
Poland
Minimal soy beverage SKU density in Warsaw and Kraków retail channels versus Western European benchmarks indicates expansion headroom. EMA-adjacent nutritional evaluations apply equally to imported and domestic formulations entering the market. The Silesian industrial zone is developing ambient-stable packaging capabilities to bypass refrigerated cold-chain limitations in regional distribution.
Europe Soy Beverages Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers and channel formats. The vendor base fragments across multinational conglomerates with refrigerated logistics networks, mid-tier organic specialists with regional formulations, and private-label suppliers serving discount retail. Three archetypes dominate: scale-driven conventional players, premium organic specialists, and flexible private-label manufacturers. M&A activity targets regional organic brands, while portfolio diversification into barista-grade unsweetened variants represents the second dominant competitive move.
Within the premium organic tier, Valsoia S.p.A. exemplifies Italian specialization in free-from formulations commanding shelf placement premiums. Danone S.A. occupies a position representing scale-driven conventional distribution across Western European refrigerated channels. Alpro anchors the decades-long shelf presence archetype that has normalized consumption patterns across Benelux retail formats.
| Leading Market Players |
|---|
| Danone S.A. |
| Vitasoy International Holdings Limited |
| Hain Celestial Group Inc. |
| Valsoia S.p.A. |
| SunOpta Inc. |
| Alpro |
| Sojade |
| Eden Foods |
| Kikkoman Corp |
| Others |
Supply & Pricing Matrix
EU Organic Regulation 2018/848 gates both supplier qualification and price differentiation simultaneously, bifurcating the European soy beverage landscape into certified premium tiers and conventional commodity segments where margin compression runs deeper.
Pricing Analysis
Certification level creates the primary spread between organic and conventional formulations, with EU Organic certification commanding placement premiums in German and French health food channels. Three-tier pricing structure separates certified organic from conventional from private-label economy tiers, though oat and almond substitution in Italian retail is intensifying cost compression in the conventional segment. Health-conscious consumers in metropolitan markets show least price sensitivity, while Italian discount channel buyers drive hardest volume negotiations.
Supply Chain Analysis
Just-in-time inventory preferences dominate refrigerated logistics networks serving barista-grade formulations, while strategic stockpiling of Argentine and Brazilian soybean inputs buffers weather-driven harvest volatility for larger processors. Supply concentrates in the Netherlands for packaging and formulation, Germany for refrigerated distribution infrastructure, and Italy for enzymatic debittering technology adoption. Soybean protein isolates, aseptic carton materials, and natural refrigerant systems anchor raw material dependencies. Single-source vulnerability in South American soybean sourcing exposes margin stability to climatic disruption. Distribution runs through Tetra Pak aseptic networks for ambient-stable reach and refrigerated fleets for premium chilled placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating across European retail banners as supermarket multiples and health food chains centralize procurement, compressing slotting fee negotiations and favoring suppliers with verified carbon accounting under CSRD requirements.
For Market Incumbents: Fortify refrigerated logistics networks through natural refrigerant retrofitting ahead of F-Gas Regulation deadlines, locking in distribution capacity that emerging players cannot replicate. Deepen backward integration into organic soybean sourcing to secure supply qualification under EU Organic Regulation 2018/848, insulating margin pools from Argentine harvest volatility and oat-milk substitution threats in Southern European channels.
For New Entrants and Emerging Players: EU Organic certification fast-track through specialized Italian laboratory partnerships opens shelf access in premium health food channels where incumbent concentration remains lowest. Target Polish and Romanian retail corridors where SKU density trails Western benchmarks by substantial margins, deploying subscription-based direct-to-consumer models that bypass conventional slotting fee barriers and capture consumer relationships ahead of supermarket expansion.
For Investors and Strategic Acquirers: CSRD mandatory disclosure implementation reshapes the acquisition landscape toward suppliers with verified carbon accounting and established organic certification infrastructure. Five-to-ten-year viability favors mid-tier organic specialists with regional formulation expertise and export positioning into Iberian markets. Signal to watch: F-Gas Regulation compliance cost burdens triggering distressed asset availability among refrigerated logistics-dependent conventional players.
| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Investment | EU Organic Regulation 2018/848 compliance unlocks placement premiums in German and French health food channels. |
| Enzymatic Debittering Technology Adoption | Italian organic specialists preserve isoflavone bioactivity while eliminating beany off-notes for Iberian export positioning. |
| Natural Refrigerant Fleet Retrofit | F-Gas Regulation phase-down deadlines force capital deployment into alternative cooling systems before asset obsolescence. |
| Direct-to-Consumer Subscription Launch | E-commerce models bypass conventional retail slotting fees and capture recurring revenue in underpenetrated Eastern European markets. |
| Aseptic Packaging Capacity Expansion | Tetra Pak technology extends ambient distribution reach beyond refrigerated cold-chain limitations in Southern Europe. |
Research Methodology
Operator-level perspectives from brand managers at multinational beverage conglomerates, category buyers at German and French retail banners, supply planners at refrigerated logistics operators, and procurement leads at organic certification bodies anchored the qualitative base. Secondary validation drew from EFSA novel food assessment filings, EU Organic Regulation 2018/848 compliance registries, REACH packaging migration test reports, and customs trade data tracking soybean isolate flows. Bottom-up SKU-level modeling triangulated against top-down category expenditure estimates across the analysis window.
Sensitivity analysis tested forecast robustness across alternative regulatory implementation timelines and commodity price scenarios over the projection horizon. Segmentation dimensions modeled include certification tier, distribution channel format, packaging type, and regional regulatory cluster. CAGRs were derived from trend extrapolation of volume and value trajectories, with EMA-adjacent health claim approval timelines and F-Gas Regulation compliance costs as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal policy continuity and stable South American soybean harvest conditions; material deviation would warrant model refresh. Revision becomes warranted when EFSA novel food assessment backlogs or CSRD supplier qualification criteria cross thresholds that reshape competitive access conditions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Naturally Cultured Beverages Market
Non-Alcoholic Beverages
Europe Sports Drink Market
Non-Alcoholic Beverages
Africa Energy Drinks Market
Non-Alcoholic Beverages
Global RTD Tea Drinks Market
Non-Alcoholic Beverages
Coffee Substitute Market
Non-Alcoholic Beverages
Bubble Tea Market
Non-Alcoholic Beverages
Africa Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
Non-Alcoholic Drinks Market
Non-Alcoholic Beverages
Iced Tea Market
Non-Alcoholic Beverages
Non-Alcoholic Beer Market
Non-Alcoholic Beverages
Non-Alcoholic Spirits Market
Non-Alcoholic Beverages
Vietnam Energy Drinks Market
Non-Alcoholic Beverages
Global Nonalcoholic Beverage Market
Non-Alcoholic Beverages
North America Bottled Water Market
Non-Alcoholic Beverages
Zero Sugar Beverages Market
Non-Alcoholic Beverages
Hydrogen Water Machine Market