
 Iced Tea Market | 2026-2036
Iced Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Iced Tea Market Analysis
Southeast Asia is tilting toward expanded bottling capacity for ready-to-drink tea exports. Unilever PLC leverages its Lipton brand infrastructure across multiple continents to sustain volume leadership. PepsiCo Inc. anchors its position through deep fountain and convenience store distribution in North America. Tata Consumer Products Ltd. competes aggressively in premium loose-leaf and bottled formats across Commonwealth markets.
Iced tea denotes brewed Camellia sinensis leaves, cooled and typically sweetened, packaged in formats ranging from single-serve polyethylene terephthalate bottles to multi-layer aseptic cartons with shelf lives of six to twelve months. The beverage serves commercial refreshment channels and at-home consumption occasions where chilled convenience outweighs hot-brew preparation time. Flavored iced tea occupies the fastest-expanding margin pool as mango, peach, and hibiscus variants command price premiums over traditional unsweetened formulations. Black tea still dominates ingredient volumes though green tea extracts gain traction in functional positioning. Supermarkets and convenience stores together control the majority of off-premise distribution, yet online retail shows the steepest velocity acceleration in subscription and bulk formats.
The FDA governs bottled iced tea labeling under 21 CFR regulations while the USDA Organic seal shapes premium tier access for certified ingredient sourcing. The EPA oversees water quality standards that directly affect brewing consistency and regional production siting decisions. State-level sugar taxes in jurisdictions like Philadelphia and San Francisco force reformulation toward zero-calorie sweetener systems. Stakeholders must monitor evolving front-of-package warning label requirements and clean-label certification trends to anticipate which product architectures will retain shelf space and consumer trust.
Market Dynamics
The FDA's updated Nutrition Facts labeling rules and sugar disclosure requirements are forcing reformulation across the entire ready-to-drink tea category. Manufacturers must rebuild ingredient architectures to retain shelf placement while satisfying clean-label certification trends.
Growth Catalysts
- Refrigerated distribution expansion:Convenience stores and quick-service restaurants now allocate expanded cold-chain space to iced tea lines, creating new velocity channels for perishable formats.
- USDA Organic certification:Premium tier access depends on certified ingredient sourcing, with organic seal penetration driving price realization in Commonwealth and North American markets.
- Functional green tea extracts:Antioxidant positioning and wellness claims accelerate adoption of green tea bases as black tea dominance faces ingredient diversification pressure.
Market Restraints
- State sugar tax regimes:Philadelphia and San Francisco excise taxes force costly reformulation toward zero-calorie sweetener systems that alter taste profiles and consumer acceptance.
- Water quality variance:EPA brewing consistency standards create regional production siting constraints, with municipal supply heterogeneity complicating multi-facility quality control.
- Polyethylene terephthalate cost volatility:Single-serve bottle feedstock prices fluctuate with oil markets, squeezing margin pools on the highest-volume packaging format.
Strategic Opportunities
- ASEAN bottling capacity:Southeast Asia export infrastructure expansion creates low-cost production bases for ready-to-drink tea serving Australian and Middle Eastern demand.
- Subscription online retail:Bulk and recurring delivery formats show steepest velocity acceleration, bypassing traditional supermarket and convenience store margin extraction.
- Hibiscus and botanical variants:Mango, peach, and floral flavor premiums command price multiples over unsweetened bases, expanding the fastest-growing margin pool in flavored formulations.
Industry Challenges
- Front-of-package warning compliance:Evolving label requirements across multiple jurisdictions demand simultaneous packaging redesigns and regulatory intelligence investments.
- Aseptic carton shelf-life validation:Six-to-twelve-month stability testing for multi-layer formats extends new product introduction timelines and capital lock-up periods.
- Hot-brew preparation substitution:At-home chilled convenience must continuously justify price premiums against low-cost tea bag brewing, requiring persistent innovation in format portability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iced Tea Market |
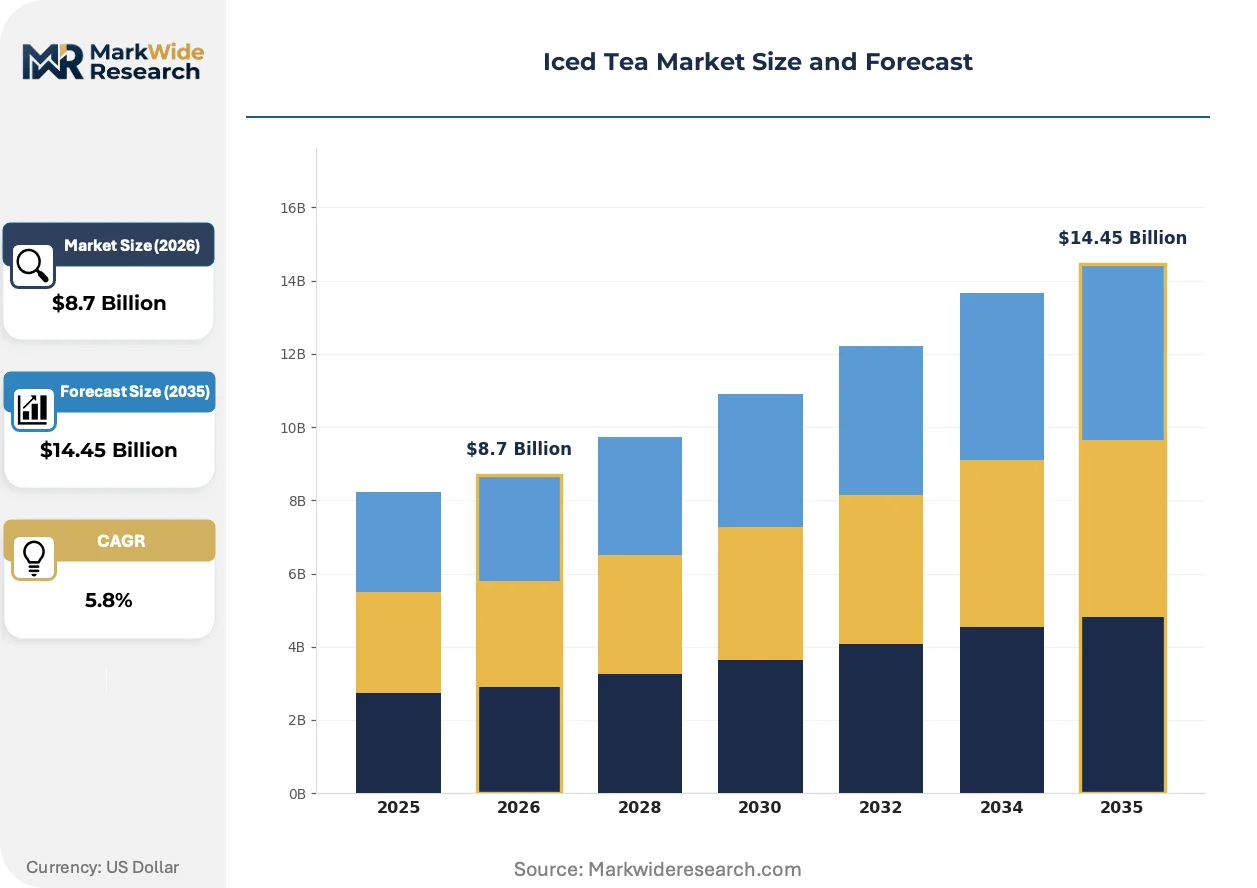
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Iced Tea, Flavored Iced Tea, Herbal Iced Tea, Sparkling Iced Tea Ingredient Type: Black Tea, Green Tea, White Tea, Fruit Extracts Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Cafes Packaging Type: Glass Bottles, Plastic Bottles, Cans, Tetra Packs |
| Companies Covered | Unilever PLC, Keurig Dr Pepper Inc., The Coca-Cola Company, 4C Foods Corp., Tata Consumer Products Ltd., PepsiCo Inc., Arizona Beverages USA, Milo’s Tea Company, Nestle SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iced Tea Market Emerging Trajectories
Formulation and packaging technologies are converging to address simultaneous pressures from sugar reduction mandates, clean-label demands, and cold-chain distribution economics.
Cold-fill aseptic processing is migrating from high-acid juice applications into neutral-pH iced tea production. Mid-size bottlers in the United States and Germany are retrofitting lines to eliminate hot-fill energy costs and thermal degradation of delicate tea polyphenols. This migration from conventional retort methods compresses capital requirements for regional entrants while extending permissible ingredient portfolios to include heat-sensitive botanical extracts.
EU Green Deal packaging regulations and extended producer responsibility frameworks are mandating recycled content minimums in beverage containers. The industrial consequence is a scramble for food-grade rPET supply that outstrips current reprocessing capacity. Premium and standard tier products across German and French retail channels are most affected, with brands accelerating deposit-return system participation to secure recycled feedstock allocations.
Direct-to-consumer subscription models are fragmenting traditional grocery channel concentration for at-home consumption occasions. Bulk formats and flavor-customization portals displace supermarket weekly purchase patterns among urban households in the United States and United Kingdom. This channel rotation is most visible in coastal metropolitan zones where delivery density supports economic last-mile economics and cold-chain integrity guarantees.
Iced Tea Market Segmentation
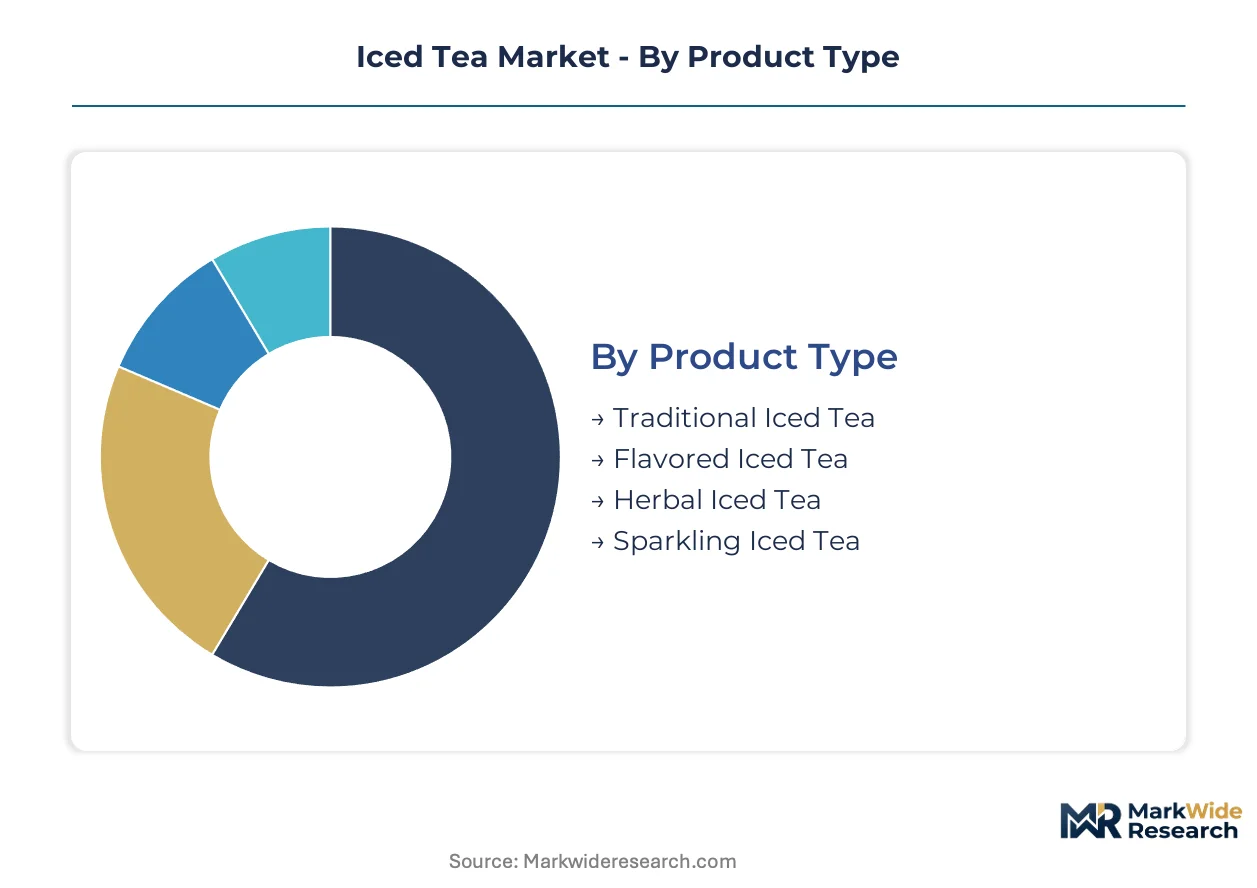
Iced tea segmentation reveals distinct velocity patterns across product architectures. Refrigerated formats turn inventory faster than shelf-stable equivalents, while premium ingredient tiers command longer production cycles and higher margin retention.
Product Type:
Cycle times vary dramatically: traditional formulations rotate weekly in convenience channels, while sparkling variants face slower uptake due to higher price points and narrower consumption occasions.
- Traditional Iced Tea:Unsweetened and lightly sweetened black tea bases dominate fountain and grab-and-go formats. Demand concentrates in the United States where quick-service restaurant penetration and 32-ounce fountain cup economics sustain volume leadership.
- Flavored Iced Tea:Peach, mango, and lemon variants carry premium price multiples over unsweetened bases. Commonwealth markets including the United Kingdom and Australia show the steepest expansion trajectory as botanical and exotic fruit positioning displaces commodity tea consumption.
- Herbal Iced Tea:Caffeine-free rooibos and chamomile bases target evening and wellness occasions.
- Sparkling Iced Tea:Carbonated tea hybrids compete for cooler space against hard seltzers and craft sodas.
Traditional iced tea dominates installed base. Flavored iced tea is where expansion concentrates.
Ingredient Type:
Cost tiers separate commodity black tea from certified organic and functional green tea extracts, with price realizations scaling steeply across the ladder.
- Black Tea:Camellia sinensis var. assamica and var. sinensis provide the standard base for mass-market formulations. Kenyan and Sri Lankan auction markets supply the bulk of global black tea extract demand.
- Green Tea:Catechin-rich extracts from Japanese and Chinese cultivars support antioxidant wellness claims. United States coastal metropolitan zones drive adoption as functional positioning displaces commodity refreshment.
- White Tea:Minimal processing preserves delicate polyphenol profiles for ultra-premium positioning.
- Fruit Extracts:Natural and nature-identical flavor systems enable clean-label flavoring without added sugar declaration.
Black tea commands volume leadership. Green tea extracts are climbing the fastest as functional claims reshape consumer selection criteria.
Distribution Channel:
Margin structures diverge sharply: supermarkets extract slotting fees and promotional allowances, while direct-to-consumer subscription models bypass traditional margin stacking.
- Supermarkets:Multi-door refrigerated cases and end-cap displays drive impulse purchase velocity. German and French retail chains enforce EU Green Deal packaging compliance as a condition of shelf placement.
- Convenience Stores:Cold-chain infrastructure expansion in Southeast Asia creates new outlet density for single-serve formats. 7-Eleven and Lawson chains in Thailand and Indonesia now allocate expanded cooler space to ready-to-drink tea.
- Online Retail:Bulk subscription and flavor-customization portals fragment traditional weekly purchase patterns.
- Cafes:Fountain and bottled formats compete for limited cooler space against coffee and energy drinks.
Supermarkets retain volume concentration. Online retail is gaining share fastest through subscription economics and cold-chain integrity guarantees.
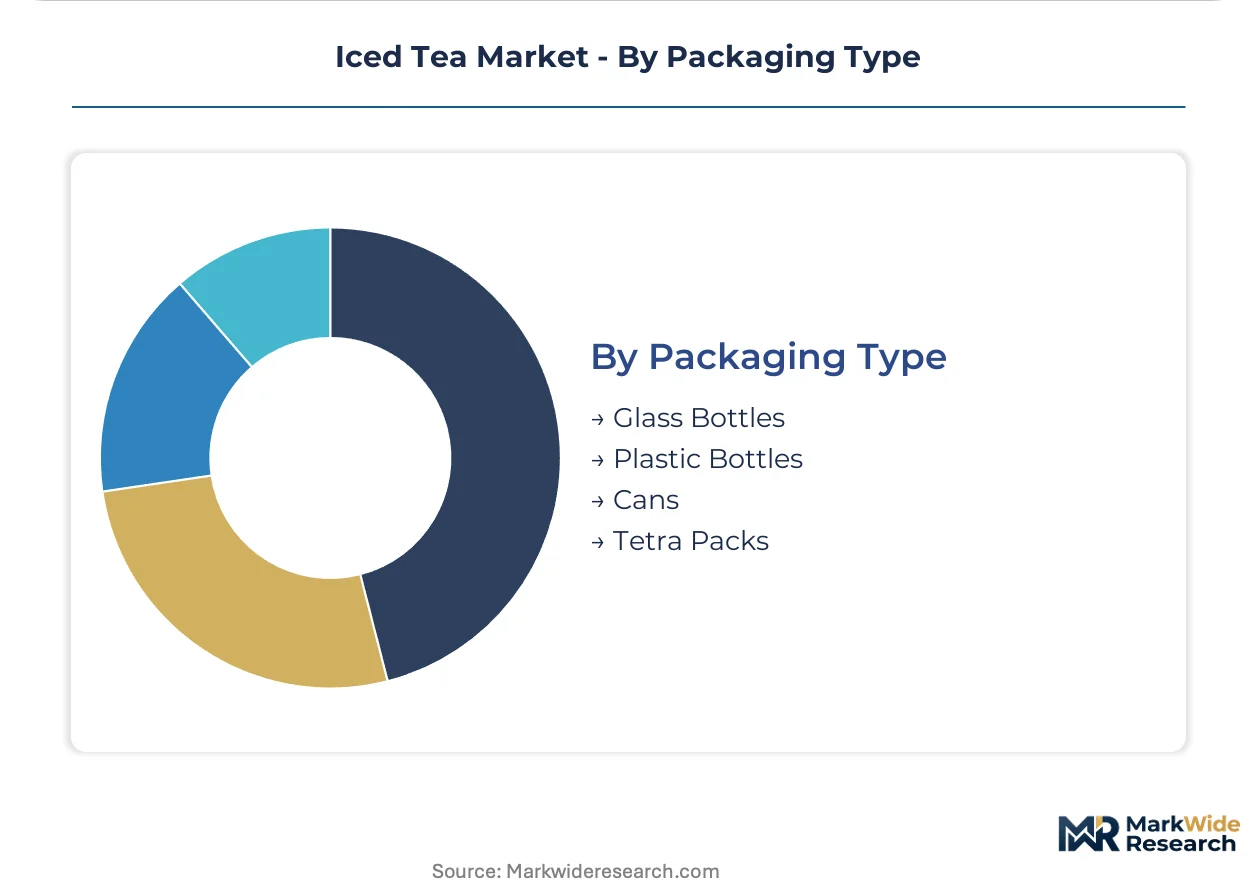
Packaging Type:
Supply concentration for food-grade recycled content is forcing rapid format migration as EU extended producer responsibility frameworks tighten.
- Plastic Bottles:Polyethylene terephthalate remains the highest-volume format for single-serve convenience. Oil market volatility squeezes margin pools, accelerating brand investment in deposit-return system participation.
- Cans:Aluminum delivers superior chilling velocity and infinite recyclability claims. United States craft and premium brands are displacing glass with 12-ounce and 16-ounce can formats for outdoor consumption occasions.
- Glass Bottles:Premium positioning and reuse deposit systems sustain niche demand in European markets.
- Tetra Packs:Aseptic carton shelf-life validation extends new product introduction timelines but enables ambient distribution in cold-chain-constrained regions.
Plastic bottles dominate installed base. Cans are where expansion concentrates as recyclability claims reshape retailer selection criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FDA governs the dominant geography through updated Nutrition Facts labeling rules and sugar disclosure requirements that reshape formulation strategies across North America.
United States
Ready-to-drink tea penetration in retail channels outpaces other developed markets, with convenience stores and quick-service restaurants allocating expanded refrigerated cooler space to iced tea lines. State-level sugar taxes in Philadelphia and San Francisco force reformulation toward zero-calorie sweetener systems. Production clusters in the Southeast and Pacific Northwest concentrate bottling capacity to serve regional distribution networks.
Germany
EU Green Deal packaging regulations and extended producer responsibility frameworks mandate recycled content minimums in beverage containers, compressing margin pools for standard-tier products. German retail chains enforce compliance as a condition of shelf placement. Industrial concentration in Bavaria and North Rhine-Westphalia hosts retrofitting operations for cold-fill aseptic processing lines.
United Kingdom
Commonwealth market demand for premium loose-leaf and bottled formats accelerates as botanical and exotic fruit positioning displaces commodity tea consumption. Deposit-return system participation secures recycled feedstock allocations for domestic brands. Greater London and Midlands distribution hubs coordinate cross-channel supply into Irish and Nordic markets.
Thailand
Southeast Asia bottling capacity expansion targets ready-to-drink tea exports serving Australian and Middle Eastern demand. 7-Eleven and Lawson chains allocate expanded cooler space to single-serve formats in Bangkok and Chiang Mai metropolitan zones. National industrial policy supports food-grade rPET reprocessing infrastructure development.
Australia
Coastal metropolitan zones drive adoption of functional green tea positioning as antioxidant wellness claims reshape consumer selection criteria. Subscription online retail shows steepest velocity acceleration in bulk and recurring delivery formats. Sydney and Melbourne cold-chain logistics clusters support direct-to-consumer fulfillment economics.
Iced Tea Market Vendor Landscape
Multinational beverage conglomerates and regional bottling specialists split the market between scale-driven distribution dominance and niche premium positioning. The vendor base concentrates around three strategic archetypes: global refreshment platforms with deep fountain infrastructure, Commonwealth-market tea heritage houses, and agile private-label formulators. Competitive moves center on cold-chain capacity expansion and aseptic packaging technology licensing to bypass hot-fill energy costs.
Among global refreshment platforms, Unilever PLC and PepsiCo Inc. exemplify scale-driven archetypes with multi-continental brand infrastructure. Tata Consumer Products Ltd. occupies a position within the Commonwealth heritage tier, leveraging premium loose-leaf credibility across British Commonwealth markets. These three anchors illustrate how strategic positioning separates volume leadership from margin retention in formulation-differentiated segments.
| Leading Market Players |
|---|
| Unilever PLC |
| Keurig Dr Pepper Inc. |
| The Coca-Cola Company |
| 4C Foods Corp. |
| Tata Consumer Products Ltd. |
| PepsiCo Inc. |
| Arizona Beverages USA |
| Milo's Tea Company |
| Nestle SA |
| Others |
Supply Flow & Price Mechanics
Trans-Pacific container freight corridors from Southeast Asian bottling hubs to Australian and Middle Eastern ports transmit cost volatility directly into landed price spreads between premium organic tiers and standard formulations. These logistics dynamics concentrate pricing power with contract manufacturers holding multi-country cold-chain certifications, while forcing brand owners to absorb margin compression or pass through freight surcharges to price-sensitive convenience store channels.
Pricing Analysis
Geographic price spreads between refrigerated single-serve formats in United States convenience stores and ambient aseptic cartons in Southeast Asian retail widen as cold-chain infrastructure investments accumulate. Three-tier pricing structure across premium organic, standard black tea, and private-label economy levels separates USDA-certified formulations from commodity bases. Pricing pressure stems from state sugar tax regimes in Philadelphia and San Francisco forcing costly reformulation. Quick-service restaurant fountain programs exhibit highest price sensitivity, while direct-to-consumer subscription buyers accept premium multiples for flavor customization.
Supply Chain Analysis
Contract manufacturing concentration rests with Unilever PLC and PepsiCo Inc. holding captive bottling networks across multiple continents, supplemented by regional specialists in Thailand and Indonesia. Raw material dependencies draw from Kenyan and Sri Lankan black tea auction markets, Japanese green tea extract suppliers, and petroleum-derived polyethylene terephthalate resin. Single-source vulnerability concentrates in food-grade rPET reprocessing capacity under EU Green Deal mandates. Distribution runs through supermarket refrigerated cases and quick-service restaurant fountain systems, with online subscription channels bypassing traditional margin stacking.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is tilting toward consolidated quick-service restaurant chains and supermarket category managers, fragmenting volume commitments across smaller brand portfolios as private-label formulators gain shelf space.
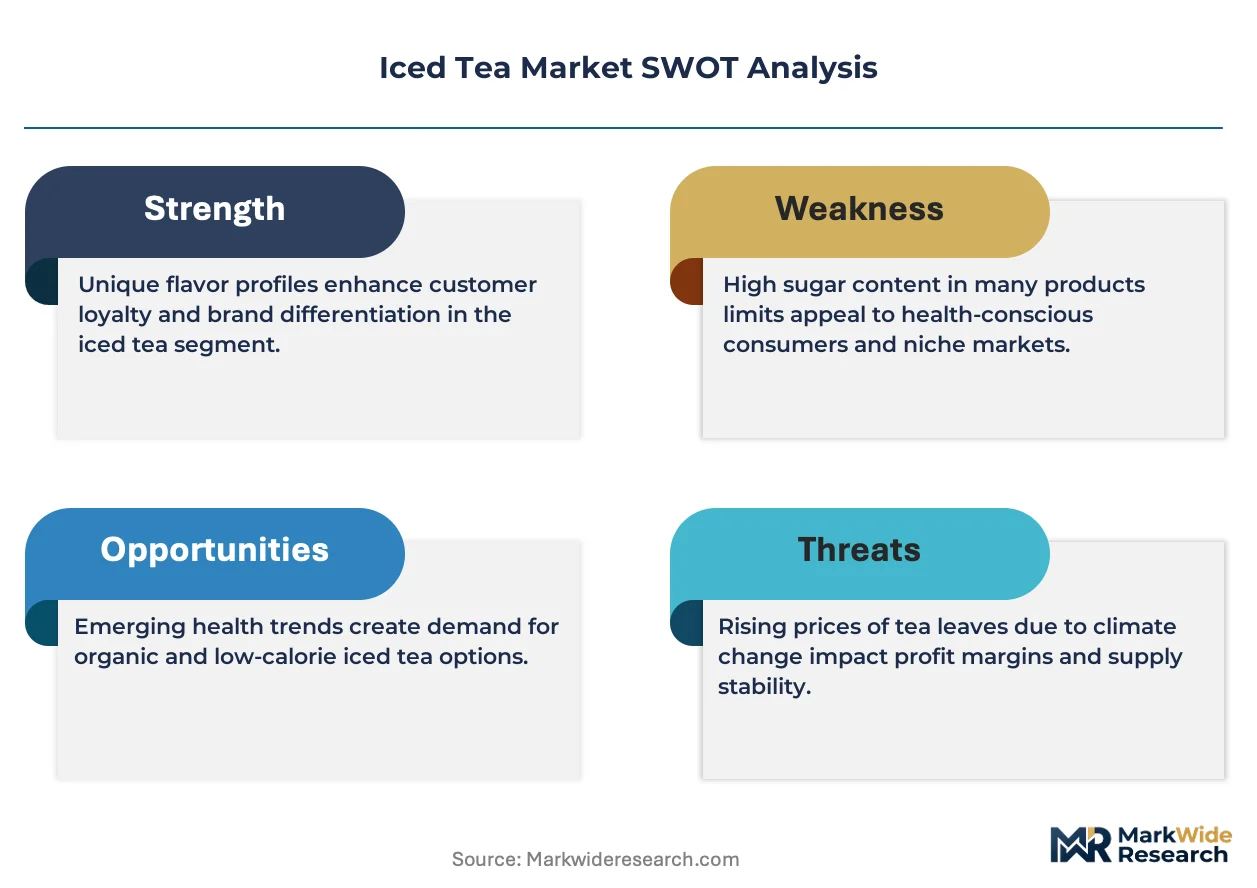
For Market Incumbents: Insulate margin pools by deepening captive supply of USDA Organic certified tea extracts through backward integration into Sri Lankan and Kenyan estate partnerships. Accelerate cold-fill aseptic processing retrofits to eliminate hot-fill energy costs and thermal degradation of polyphenols. Defend against emerging botanical wellness entrants by locking exclusive hibiscus and rooibos supply contracts before ingredient scarcity materializes. For New Entrants and Emerging Players: Establish a beachhead in direct-to-consumer subscription channels where flavor-customization portals bypass supermarket slotting fee barriers and extract full margin capture. Target coastal metropolitan zones in Australia and the United Kingdom where functional green tea positioning displaces commodity refreshment fastest. Deploy cold-chain integrity guarantees as the primary go-to-market differentiator against shelf-stable incumbents. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational beverage conglomerates spinning off regional tea heritage brands lacking global scale synergies. Long-term viability favors assets with certified organic supply chains and aseptic packaging technology licenses over hot-fill dependent operations. Watch FDA front-of-package warning label rulemaking as the inflection signal that will force simultaneous packaging redesigns across multiple jurisdictions and concentrate compliance spending among scaled players.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Fill Aseptic Processing Retrofit | Eliminates thermal degradation of tea polyphenols while compressing energy costs for regional bottlers. |
| USDA Organic Certification Investment | Unlocks premium tier shelf placement in Commonwealth and North American retail channels. |
| Direct-to-Consumer Subscription Launch | Bypasses supermarket margin extraction through bulk recurring delivery with flavor customization portals. |
| Food-Grade rPET Supply Agreement | Secures recycled feedstock allocations under EU Green Deal extended producer responsibility frameworks. |
| ASEAN Bottling Capacity Expansion | Captures low-cost production base for ready-to-drink tea exports to Australian and Middle Eastern demand. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with brand managers at multinational beverage conglomerates, category buyers at convenience store chains, cold-chain logistics coordinators, and regulatory affairs specialists navigating FDA and EU Green Deal compliance. Secondary validation drew from FDA 21 CFR filings, USDA Organic certification databases, EU extended producer responsibility framework documentation, and Nielsen retail audit data. Bottom-up volume modeling across packaging formats and ingredient tiers was triangulated against top-down category spend estimates from customs trade records.
Calibration against historical velocity patterns in refrigerated versus ambient distribution channels anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, ingredient certification tier, distribution channel economics, and regional regulatory cluster. CAGRs were derived from slope analysis of indexed consumption trends. Forecast inputs incorporated cold-chain infrastructure buildout schedules and state-level sugar tax regime expansion probabilities.
Macroeconomic conditions sit as an overlay; deviation in petroleum feedstock pricing, container freight rates, or currency volatility in tea-producing regions would shift the trajectory of margin pool distribution between brand owners and contract manufacturers. Quarterly review of FDA rulemaking timelines, EU packaging regulation enforcement intensity, and rPET reprocessing capacity utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Europe Sports Drink Market
Non-Alcoholic Beverages
North America Bottled Water Processing Market
Non-Alcoholic Beverages
Lemonade Market
Non-Alcoholic Beverages
Fermented Non Dairy Non Alcoholic Beverages Market
Non-Alcoholic Beverages
Europe Non-Alcoholic Wine and Beer Market
Non-Alcoholic Beverages
Water Vending Machine Market
Non-Alcoholic Beverages
Flavored Water Market
Non-Alcoholic Beverages
Gulf Cooperation Council (GCC) Bottled Water Market
Non-Alcoholic Beverages
Fruit-Infused Water Market
Non-Alcoholic Beverages
Zero Proof Spirit Market
Non-Alcoholic Beverages
Carbonated Ready-To-Drink Tea Market
Non-Alcoholic Beverages
Energy Drinks Market
Non-Alcoholic Beverages
Non-Carbonated Soft Drinks Market
Non-Alcoholic Beverages
Rtd Bubble Tea Market
Non-Alcoholic Beverages
Global RTD Tea Drinks Market
Non-Alcoholic Beverages
Sugar Free Carbonated Drinks Market