
 Pearl Milk Tea Market | 2026-2036
Pearl Milk Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Pearl Milk Tea Market Analytics
Automated brewing systems with IoT-enabled temperature and timing controls are reshaping how pearl milk tea chains standardize quality across franchised locations. Gong Cha leverages centralized kitchen models to sustain consistency in tapioca texture across its multi-country footprint. CoCo Fresh Tea & Juice anchors its competitive edge through vertical control over tea leaf procurement from high-altitude plantations in Taiwan and Fujian. Kung Fu Tea differentiates via proprietary shaker equipment that reduces preparation variance during peak-hour rushes.
Pearl milk tea is a cold or hot beverage composed of brewed tea, milk or non-dairy creamer, sweetener, and chewy tapioca starch pearls typically measuring 6 to 8 millimeters in diameter; the pearls undergo a precise boiling and sugar-soaking process to achieve their characteristic gelatinous texture and caramelized surface. The drink functions primarily as an affordable indulgence and social ritual anchor in urban foodservice environments. Classic milk tea and brown sugar milk tea command the deepest margin pools due to simpler ingredient stacks and shorter preparation times. Fruit tea variants are gaining traction among health-conscious consumers seeking lower-calorie alternatives with visible fresh ingredients. Online and café distribution channels capture the highest frequency purchasers, while supermarket packaged formats remain nascent with concentrated trial activity in East Asian retail corridors.
Food safety regulators in Taiwan, China's SAMR, and the FDA in the United States enforce distinct additive and labeling standards for tapioca pearls and non-dairy creamers, creating compliance complexity for chains operating across jurisdictions. The EU's F-Gas Regulation and REACH framework additionally constrain refrigerant choices and packaging material compositions for European store expansions. Stakeholders must monitor evolving sugar taxation proposals and single-use plastic restrictions, as these policy trajectories will determine whether reformulated recipes or biodegradable packaging investments become prerequisites for market access in priority expansion corridors.
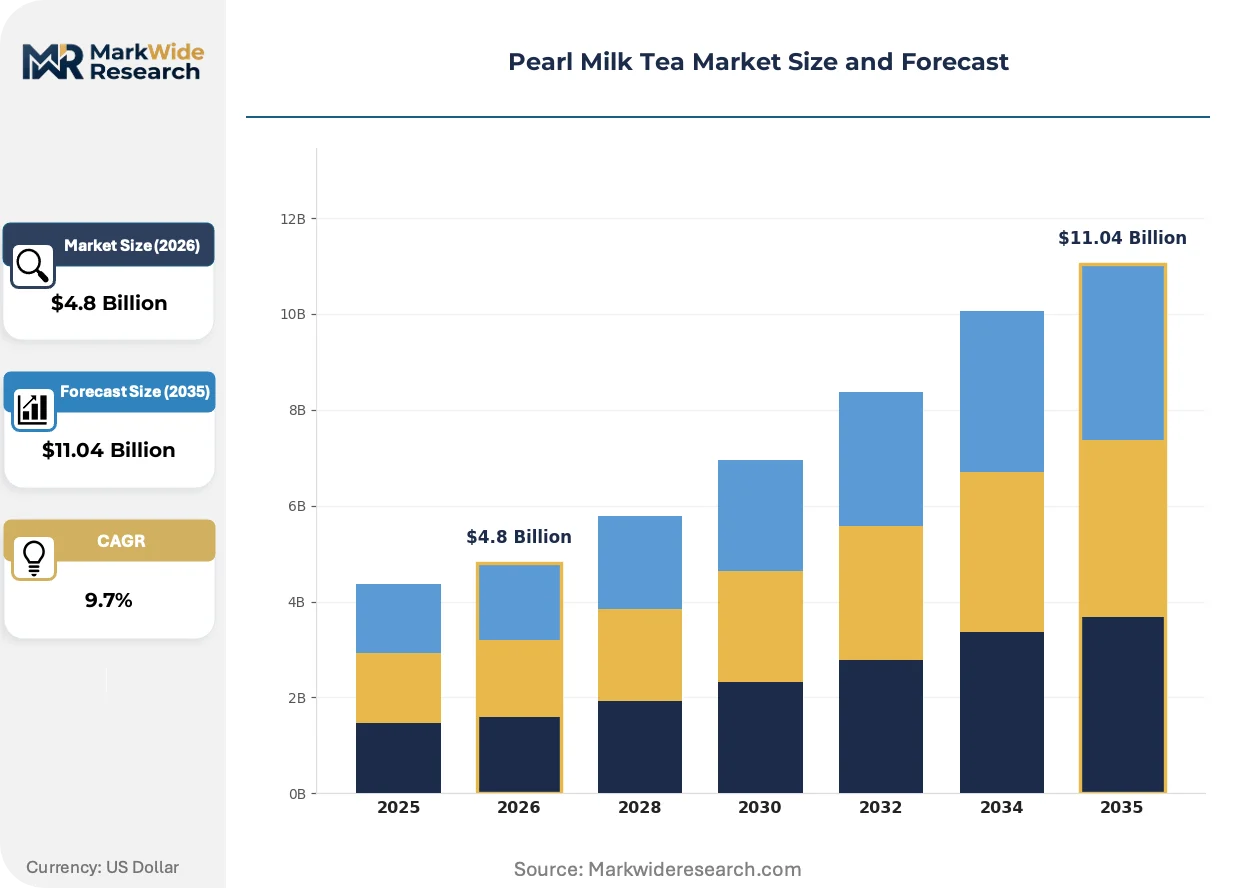
Market Dynamics
Automated brewing infrastructure is compressing preparation variance across franchised pearl milk tea networks, while sugar taxation proposals and single-use plastic bans in multiple jurisdictions force simultaneous recipe reformulation and packaging reinvestment.
Growth Catalysts
- Gen Z Social Ritualization:University corridors and urban business districts in Taiwan, South Korea, and Vietnam sustain repeat purchase frequency through customizable, Instagram-ready beverage formats.
- IoT-Enabled Quality Standardization:Temperature and timing control systems allow centralized kitchen models to replicate tapioca texture consistency across dispersed store footprints.
- REACH Framework Compliance:European expansions drive investment in biodegradable packaging alternatives, opening premium positioning for chains with certified sustainable supply chains.
Market Restraints
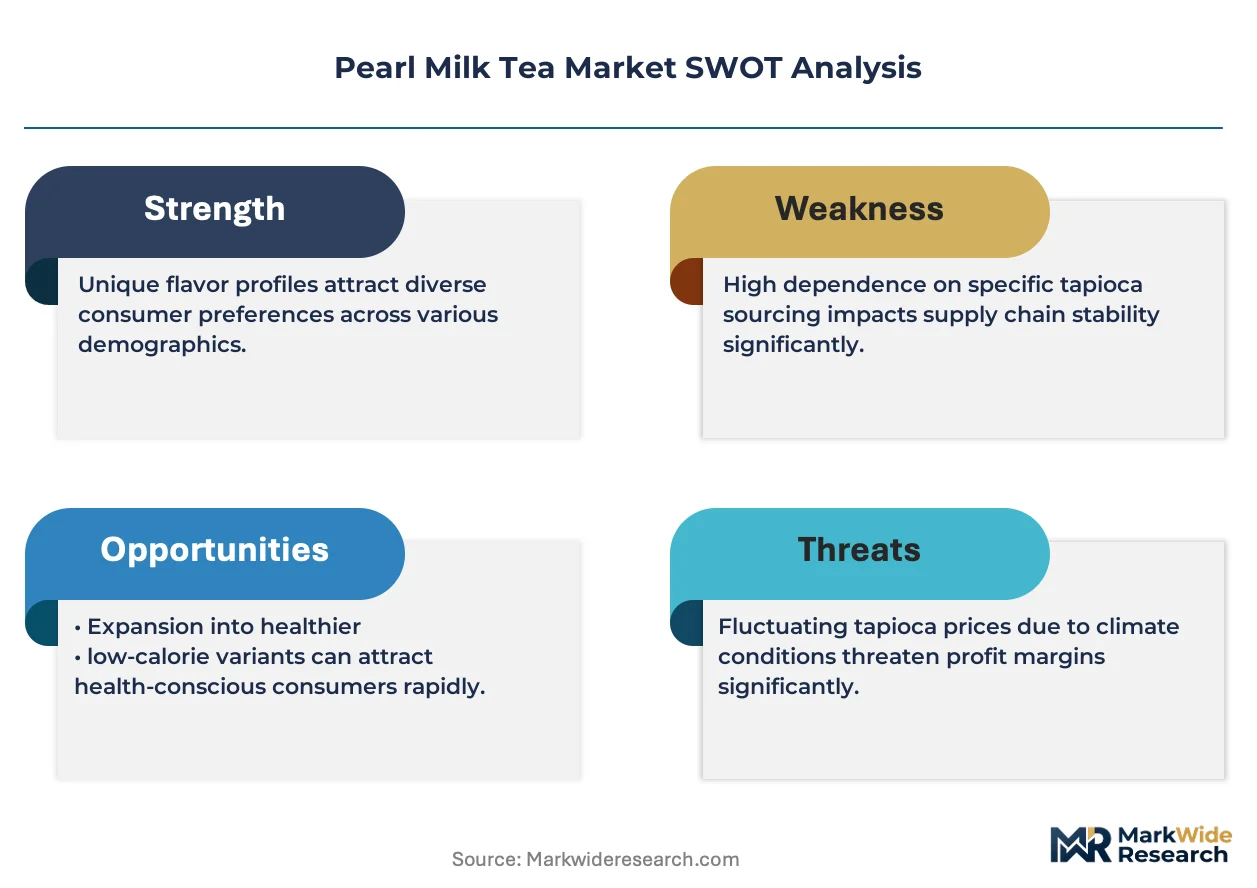
- Tapioca Starch Concentration:Nantou County and Taichung City in Taiwan control original recipe development and primary starch sourcing, creating geographic supply vulnerability.
- Sugar Taxation Proposals:Pending levies in multiple jurisdictions threaten margin compression on classic milk tea and brown sugar variants that rely on high sweetener loads.
- Non-Dairy Creamer Regulatory Divergence:Taiwan's FDA, China's SAMR, and the US FDA enforce incompatible additive standards, fragmenting formulation strategies for multi-country operators.
Strategic Opportunities
- India Urban Penetration:Tier-1 cities show concentrated trial activity for café-format pearl milk tea with localized flavor adaptations.
- Fruit Tea Health Positioning:Lower-calorie variants with visible fresh ingredients capture health-conscious consumers seeking alternatives to creamer-heavy classics.
- EU F-Gas Regulation Tailwind:Refrigerant constraints accelerate adoption of energy-efficient cold-chain equipment, subsidizing modernization costs for early movers.
Industry Challenges
- Cross-Jurisdictional Labeling Complexity:Chains operating across Taiwan, China, and the United States must maintain parallel formulation databases to satisfy divergent disclosure requirements.
- Peak-Hour Labor Throughput:Proprietary shaker equipment reduces preparation variance but requires dedicated training protocols that strain franchisee onboarding timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pearl Milk Tea Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Classic Milk Tea, Fruit Tea, Taro Milk Tea, Brown Sugar Milk Tea Distribution Channel: Online, Cafés, Supermarkets, Food Trucks Consumer Type: Millennials, Students, Health Conscious, Office Workers Flavor Profile: Sweet, Fruity, Creamy, Savory |
| Companies Covered | CoCo Fresh Tea & Juice, Gong Cha, Quickly, Chatime Global LLC, Kung Fu Tea, Possmei, Sharetea, Bubbleology, Lollicup, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pearl Milk Tea Market Evolving Landscape
Beverage preparation technology, regulatory compliance frameworks, and consumer health consciousness are simultaneously reshaping competitive requirements across the pearl milk tea sector.
Precision temperature control systems are hybridizing traditional manual brewing with automated consistency protocols. High-volume franchise operators deploy IoT-enabled equipment to synchronize tapioca cooking cycles across dispersed locations. This convergence is compressing the acceptable quality variance window and raising baseline capital requirements for market entry.
China's SAMR has tightened additive disclosure mandates for non-dairy creamers used in pearl milk tea formulations. The regulation forces reformulation of existing recipes and accelerates migration toward clean-label ingredient stacks. Multi-country chains now maintain parallel product specifications to satisfy incompatible Taiwan, China, and United States standards.
Health-conscious consumers are rotating demand toward fruit tea variants with visible fresh ingredients and reduced sweetener loads. Café channels in South Korea and Vietnam report accelerating substitution away from classic milk tea formats. This behavioral shift pressures margin structures optimized for simpler, higher-margin classic recipes.
Pearl Milk Tea Market Segmentation
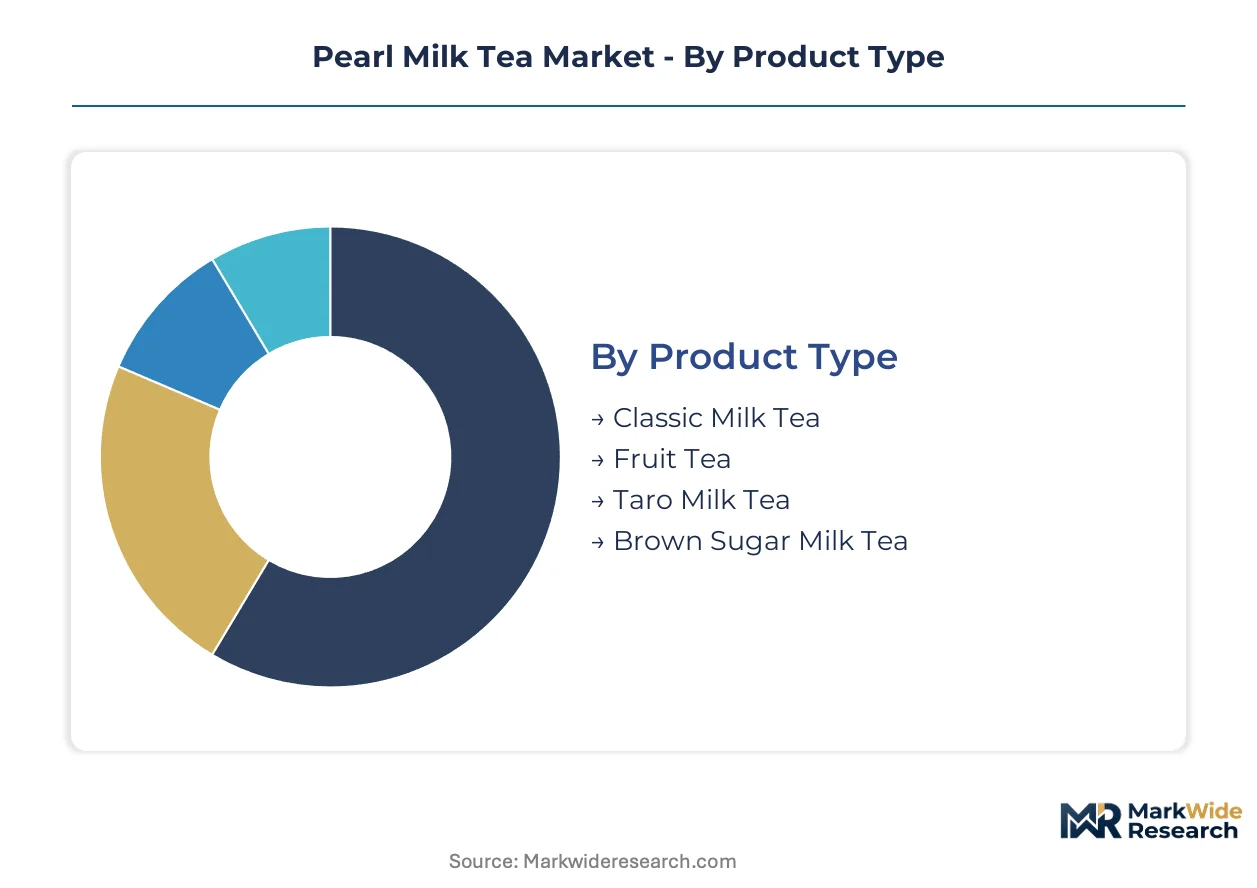
Pearl milk tea segmentation reveals divergent profit velocity across product formats and channel economics. Understanding which segments compress preparation cycles versus those requiring extended customer education shapes capital allocation and franchise development strategy.
Product Type:
Classic milk tea and brown sugar variants turn inventory fastest through standardized preparation protocols, while taro and fruit teas demand extended ingredient sourcing cycles and perishable handling.
- Classic Milk Tea:Black tea base with non-dairy creamer or fresh milk and standard tapioca pearls defines the category reference point. Demand concentrates in Taiwan's university corridors and Seoul's business districts where Gong Cha and CoCo Fresh Tea & Juice optimize for sub-three-minute service cycles during peak hours.
- Brown Sugar Milk Tea:Fresh milk layered with dark brown sugar syrup creates visual differentiation through gradient aesthetics. Instagram-driven trial in Ho Chi Minh City and Bangkok's Siam Square sustains premium pricing despite simpler ingredient stacks than fruit-forward alternatives.
- Fruit Tea:Visible fresh fruit pieces with green or oolong tea bases target health-conscious rotation away from creamer-heavy formats. Perishable sourcing requirements extend supply lead times.
- Taro Milk Tea:Purple taro root powder blended with milk delivers distinctive color signaling and nostalgic flavor profiles. Preparation variance is higher due to powder hydration consistency challenges.
Classic milk tea dominates installed base across franchised networks. Brown sugar milk tea is where expansion concentrates as chains seek premium positioning without perishable complexity.
Distribution Channel:
Café and online channels capture highest-frequency purchasers through convenience density, while supermarket and food truck formats operate on elongated purchase cycles requiring different margin architecture.
- Cafés:Dedicated beverage outlets with in-store seating and customization interfaces anchor social ritual consumption. Taiwan's Nantou County-origin chains leverage centralized kitchen models to synchronize quality across dispersed café footprints.
- Online:Delivery-optimized formats with sealed packaging and temperature-controlled logistics capture office worker demand in dense urban corridors. Platform commission structures compress net margins versus walk-in traffic.
- Supermarkets:Pre-packaged bottled formats with extended shelf stability target trial activity in East Asian retail corridors. SAMR and FDA labeling divergence forces parallel packaging specifications.
- Food Trucks:Mobile units with reduced equipment footprints serve event-based and campus-adjacent demand. Capital requirements are lowest but volume throughput is capped by spatial constraints.
Cafés hold the deepest revenue concentration across measured markets. Online delivery infrastructure is expanding most quickly as third-party platforms deepen penetration in Vietnam and South Korea.
Consumer Type:
Students and office workers generate the highest transaction frequency through habitual purchase patterns, while health-conscious segments rotate demand toward reformulated offerings with extended consideration cycles.
- Students:University corridor proximity sustains afternoon and evening clustering behavior. Price sensitivity is elevated but volume throughput compensates through repeat frequency.
- Office Workers:Business district locations capture mid-afternoon energy-seeking behavior. Delivery compatibility and mobile ordering integration determine share capture.
- Health Conscious:Reduced-sugar and fresh-fruit variants attract consumers monitoring caloric intake. Migration from classic milk tea formats pressures legacy margin structures.
- Millennials:Broad demographic bracket spanning student and professional life stages with sustained brand loyalty to Taiwan-origin chains.
Students anchor volume throughput in measured corridor economies. Health-conscious segmentation is gaining share fastest as sugar taxation proposals accelerate across multiple jurisdictions.
Flavor Profile:
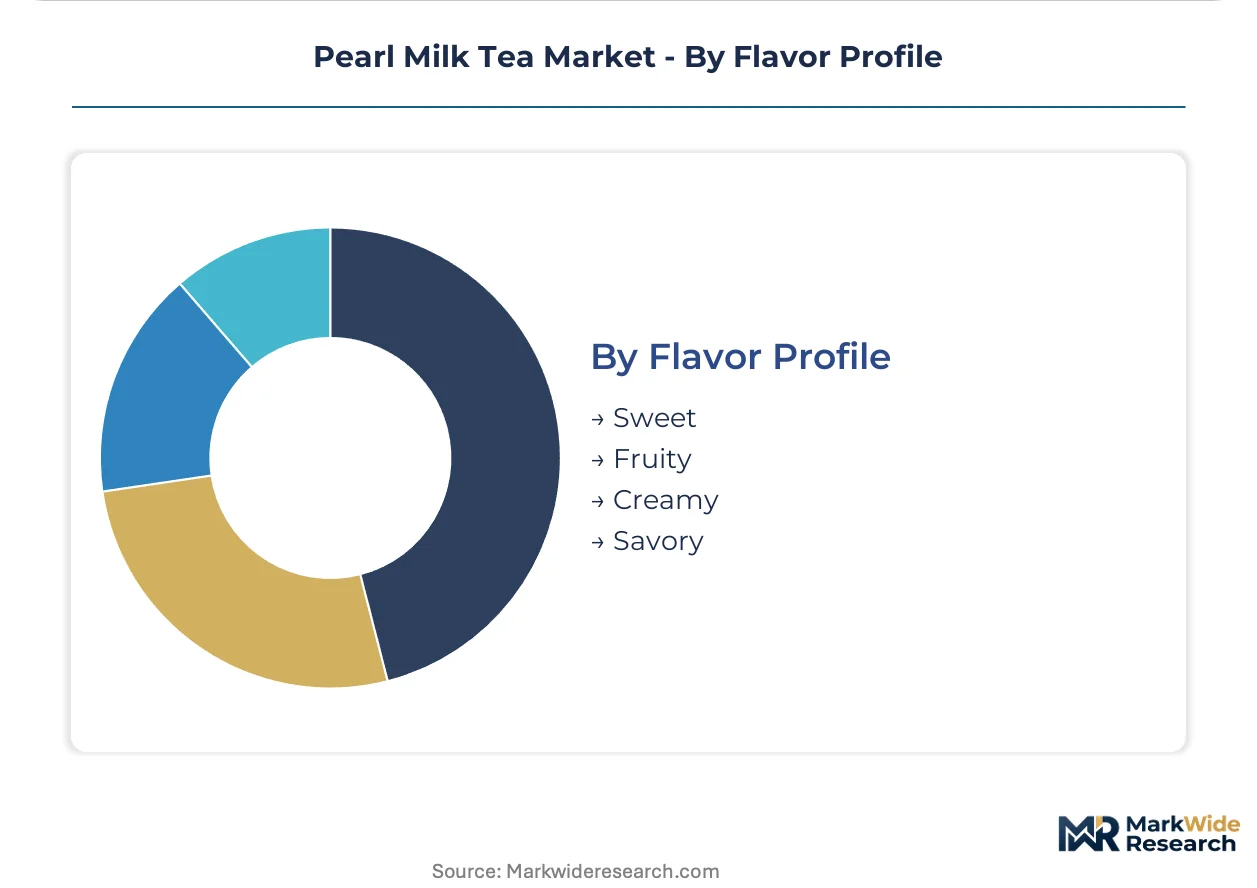
Sweet and creamy profiles dominate current formulation standards, while fruity and savory extensions test acceptance thresholds in health-positioned and experimental consumption occasions.
- Sweet:Brown sugar and traditional milk tea sweetness levels calibrated to Taiwanese palate preferences. Classic recipes face reformulation pressure from pending sugar levies.
- Creamy:Non-dairy creamer and fresh milk bases deliver mouthfeel consistency. SAMR additive disclosure mandates are accelerating clean-label migration.
- Fruity:Citrus, berry, and tropical fruit infusions with visible ingredient pieces. Fresh handling requirements elevate operational complexity.
- Savory:Cheese foam and salted cream toppings emerging in South Korean and Chinese coastal cities. Acceptance remains geographically concentrated.
Sweet formulations command the broadest installed base. Fruity profiles are where product development investment concentrates as chains seek health-permissioned expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan's Nantou County and Taichung City export tapioca starch and original recipe formulations to chains operating across East Asia, North America, and Southeast Asia. This trade corridor anchors quality benchmarks that regional operators must replicate or adapt.
Taiwan
University corridors in Taipei and Taichung sustain habitual afternoon purchase clustering among students. The Taiwan FDA enforces additive disclosure standards for non-dairy creamers that diverge from mainland Chinese requirements. Nantou County's tapioca starch cooperatives supply signature pearls to franchised networks expanding into Vietnam and South Korea.
China
SAMR's tightened additive mandates for creamer formulations force recipe reformulation across multi-province operators. The regulator's disclosure requirements accelerate migration toward clean-label ingredient stacks. Shanghai and Shenzhen café clusters test automated brewing systems to standardize quality across dispersed franchise footprints.
South Korea
Seoul's business districts generate mid-afternoon energy-seeking traffic from office workers seeking delivery-compatible formats. The MFDS monitors non-dairy creamer compositions under food additive regulations. Gangnam and Hongdae clusters drive Instagram-ready beverage innovation with cheese foam and salted cream topping experiments.
United States
Coastal metropolitan areas concentrate trial activity among Gen Z consumers seeking customizable, social-media-visible beverages. The FDA maintains distinct additive standards for tapioca pearls and creamers that fragment formulation strategies for Taiwan-origin chains. Los Angeles and New York City café corridors anchor West Coast and East Coast expansion templates.
Vietnam
Ho Chi Minh City and Hanoi's urban business districts show accelerating demand for brown sugar milk tea variants with visual gradient aesthetics. The country's national food safety authority enforces emerging standards on sweetener disclosure and packaging materials. District 1 and Old Quarter café clusters integrate mobile ordering with third-party delivery platform partnerships.
Pearl Milk Tea Market Competitive Landscape
Channel-controlling players compete with product-specialist players across café, online delivery, and packaged retail vectors. The vendor base organizes around three archetypes: Taiwan-origin heritage chains with centralized kitchen models, regional fast-followers with localized flavor adaptations, and equipment-plus-ingredient suppliers enabling independent operator entry. Consolidation pressure concentrates among café-format operators seeking multi-country footprint density. Competitive moves emphasize strategic partnerships with third-party delivery platforms and backward integration into tea leaf procurement.
Within the heritage-chain archetype, Gong Cha and CoCo Fresh Tea & Juice exemplify Taiwan-origin operators that anchor quality standardization through controlled supply relationships. Kung Fu Tea occupies a position among North America-focused specialists emphasizing equipment-driven preparation consistency. These three represent contrasting geographic expansion templates: Asia-Pacific density, multi-continental franchising, and Western market penetration.
| Leading Market Players |
|---|
| CoCo Fresh Tea & Juice |
| Gong Cha |
| Quickly |
| Chatime Global LLC |
| Kung Fu Tea |
| Possmei |
| Sharetea |
| Bubbleology |
| Lollicup |
| Others |
Value Network & Pricing Analysis
Single-source dependency on Nantou County tapioca starch cooperatives compresses margin flexibility for brown sugar and classic milk tea tiers while forcing parallel inventory buffers across Taiwan, Vietnam, and South Korea distribution nodes. This geographic chokepoint simultaneously widens premium-to-economy pricing spreads and dictates just-in-pearl sourcing strategies for chains avoiding texture variance penalties.
Pricing Analysis
Equipment-generation pricing gaps separate IoT-enabled automated brewing installations from manual kettle operations and legacy shaker systems. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade for clean-label creamer formulations and vertical integration depth in tea leaf procurement. Pricing pressure stems from sugar taxation proposals across multiple jurisdictions threatening margin compression on sweetener-heavy classics. Students in university corridors exhibit highest price sensitivity while office workers in Seoul and Ho Chi Minh City business districts accept premium positioning for Instagram-visible gradient aesthetics.
Supply Chain Analysis
Supplier-financing facilities extended by Taiwan starch cooperatives allow smaller Vietnamese and Thai franchisees to manage pearl inventory without upfront capital strain. Raw material flows draw from Nantou County tapioca starch, Fujian high-altitude tea plantations, and Malaysian non-dairy creamer blending facilities. Single-source vulnerability concentrates in Taiwan's original recipe development corridors, exposing chains to climate disruption or export restriction scenarios. Distribution runs through centralized kitchen models feeding café footprints, with third-party delivery platforms capturing growing share in dense urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pearl milk tea chains now function as service-attach businesses where mobile ordering integration and subscription loyalty programs expand recurring revenue faster than beverage hardware sales alone. Equipment suppliers capture follow-on revenue through IoT-enabled brewing system maintenance contracts and shaker equipment calibration services.
For Market Incumbents: Harden centralized kitchen quality protocols against texture variance complaints that drive churn in multi-country footprints. Defend margin position by accelerating backward integration into Fujian tea leaf procurement before SAMR disclosure mandates fully phase out legacy creamer formulations. Prioritize certification investment for biodegradable packaging alternatives that satisfy EU F-Gas Regulation and REACH framework requirements ahead of European corridor expansions. For New Entrants and Emerging Players: Build out fruit tea production capabilities targeting health-conscious rotation demand in South Korean and Vietnamese café clusters where perishable handling complexity has slowed incumbent adaptation. White-space opportunity concentrates in India's Tier-1 cities where localized flavor adaptations remain underdeveloped and delivery platform partnerships are nascent. Pursue equipment-plus-ingredient bundling as the primary go-to-market angle, supplying independent operators with IoT-enabled brewing systems locked to proprietary pearl specifications. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated chains with captive tea procurement and certified sustainable supply chains. Long-term viability hinges on regulatory compliance infrastructure spanning Taiwan FDA, SAMR, and FDA additive divergence rather than pure store-count expansion. Acquisition target archetype: regional fast-followers with localized flavor portfolios and established third-party delivery relationships in underpenetrated corridors. Monitor sugar taxation proposal progression across Southeast Asian jurisdictions as the primary inflection signal for reformulation capex cycles and margin structure resets.| Strategic Initiative | Industry Significance |
|---|---|
| IoT-Enabled Brewing System Deployment | Gong Cha and CoCo Fresh Tea & Juice synchronize tapioca texture consistency across dispersed franchise footprints. |
| Clean-Label Creamer Reformulation | SAMR disclosure mandates force migration toward additive-transparent ingredient stacks ahead of regulatory deadlines. |
| Backward Integration into Tea Procurement | Vertical control over Fujian high-altitude plantations anchors margin defense against commodity volatility. |
| Biodegradable Packaging Certification | REACH framework compliance opens premium positioning for EU expansion corridors with subsidized modernization. |
| Mobile Ordering Platform Integration | Ho Chi Minh City and Hanoi chains capture office worker demand through seamless third-party delivery partnerships. |
Research Methodology
Desk research of customs trade data, food safety authority filings, and SEC disclosures from publicly traded beverage operators preceded structured interviews with supply chain directors at Taiwan-origin chains, franchise development officers, equipment manufacturing specialists, and regulatory compliance consultants. Secondary validation drew from Taiwan FDA additive databases, SAMR disclosure registries, and EU F-Gas Regulation implementation guidance. Bottom-up store-count modeling and top-down category revenue estimates were triangulated against third-party delivery platform transaction data.
Assumption sets held sugar taxation proposal trajectories and single-use plastic restriction timelines as fixed policy vectors while varying tapioca starch price volatility and third-party delivery commission structures across sensitivity bands. Segmentation dimensions modeled include product type, distribution channel, consumer archetype, and flavor profile across the projection horizon. CAGRs were derived from installed base growth rates and per-unit economics rather than macro consumption extrapolation alone. Forecast inputs incorporated IoT equipment adoption curves and clean-label ingredient migration timelines specific to creamer reformulation cycles.
Stress conditions across starch supply disruption, regulatory acceleration, and delivery platform commission compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding policy implementation sequencing and technology substitution rates. Macroeconomic contraction, regulatory divergence beyond modeled scenarios, or breakthrough beverage preparation automation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Coffee Substitute Market
Non-Alcoholic Beverages
Low- and No-Calorie Soda Market
Non-Alcoholic Beverages
Zero Proof Spirit Market
Non-Alcoholic Beverages
Probiotic Soda Market
Non-Alcoholic Beverages
Non-Alcoholic Beer Market
Non-Alcoholic Beverages
Non-Alcoholic Spirits Market
Non-Alcoholic Beverages
Non-Alcoholic Drinks Market
Non-Alcoholic Beverages
Fruit-Infused Water Market
Non-Alcoholic Beverages
Global Nonalcoholic Beverage Market
Non-Alcoholic Beverages
Global Non Alcoholic Concentrated Syrup Market
Non-Alcoholic Beverages
Bubble Tea Market
Non-Alcoholic Beverages
Global Non-Alcoholic RTD Beverages Market
Non-Alcoholic Beverages
GCC Non-Alcoholic Beer Market
Non-Alcoholic Beverages
Non-Alcoholic Wine and Beer Market
Non-Alcoholic Beverages
Flavored Water Market
Non-Alcoholic Beverages
Zero Sugar Beverages Market