
 Isotonic Drinks Market | 2026-2036
Isotonic Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Isotonic Drinks Market Foresight
Sports nutritionist labor availability is collapsing across North American and European manufacturing hubs, forcing brands to automate formulation labs and compress product development cycles. The Coca-Cola Company leverages its fountain distribution infrastructure to lock in stadium and gym channel access. PepsiCo Inc. anchors its isotonic portfolio through Gatorade's institutional sports relationships and electrolyte research partnerships. Monster Beverage Corp. competes by extending its energy drink flavor science into hybrid isotonic-energy formulations.
Isotonic drinks are aqueous beverages formulated with dissolved minerals and carbohydrates at osmotic pressure matching human blood plasma, typically containing 6-8% carbohydrates and 460-700 mg sodium per liter to accelerate gastric emptying and intestinal absorption during physical exertion. Sports Drinks dominate value generation through decades of institutional team sponsorships and established electrolyte protocols, while Recovery Drinks capture the fastest growth as protein-carbohydrate combinations displace standalone protein shakes in post-exercise windows. Functional Beverages concentrate margin pools through premium positioning around adaptogens and nootropic additives targeting cognitive performance alongside physical hydration.
The FDA governs health claims and GRAS status for electrolyte additives in the United States, while the EU Green Deal and REACH frameworks constrain packaging materials and artificial additive portfolios across European markets. These regulatory architectures elevate compliance costs for new entrants but simultaneously protect incumbent brands with established formulation dossiers and sustainability certifications. Stakeholders must monitor evolving sugar taxation thresholds and front-of-pack labeling mandates that threaten to recategorize traditional isotonic formulations as confectionery rather than functional nutrition.
Market Dynamics
The EU Green Deal's packaging sustainability mandates are forcing rapid material transitions across European supply chains, while labor shortages in sports nutrition formulation are compressing product development cycles industry-wide.
Growth Catalysts
- Post-workout hydration protocols:Fitness Enthusiasts are adopting institutional-grade electrolyte recovery routines previously restricted to professional athletes, expanding the addressable consumer base.
- EU Green Deal packaging mandates:Regulatory pressure for recyclable and reduced-plastic formats is accelerating investment in biodegradable bottle technologies and closed-loop refill systems.
- Brazil's marathon running culture:Tropical climate conditions sustain per-capita consumption leadership, with localized flavor formulations and heat-adapted sodium concentrations driving category penetration.
Market Restraints
- Sugar taxation thresholds:Front-of-pack labeling mandates in multiple jurisdictions threaten to recategorize traditional isotonic formulations as confectionery, constraining formulation flexibility.
- Sports nutritionist labor collapse:North American and European manufacturing hubs face acute shortages of qualified formulation scientists, limiting R&D throughput and innovation velocity.
- Electrolyte additive compliance costs:FDA GRAS dossier requirements and REACH framework constraints elevate barriers for new entrants without established regulatory portfolios.
Strategic Opportunities
- Hybrid isotonic-energy convergence:Energy drink flavor science is migrating into isotonic formulations, creating new consumption occasions beyond traditional sports use cases.
- Adaptogen and nootropic integration:Functional Beverages targeting cognitive performance alongside physical hydration command premium positioning in white-collar wellness segments.
- Stadium and gym fountain infrastructure:Bulk dispensing systems reduce packaging costs while locking in institutional channel access through exclusive pouring agreements.
Industry Challenges
- Formulation lab automation complexity:Brands must compress development cycles while maintaining electrolyte precision, requiring capital-intensive robotic liquid handling and rapid prototyping equipment.
- Multi-jurisdiction labeling harmonization:Divergent front-of-pack requirements across the United States, European Union, and Brazil force SKU proliferation and inventory fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isotonic Drinks Market |
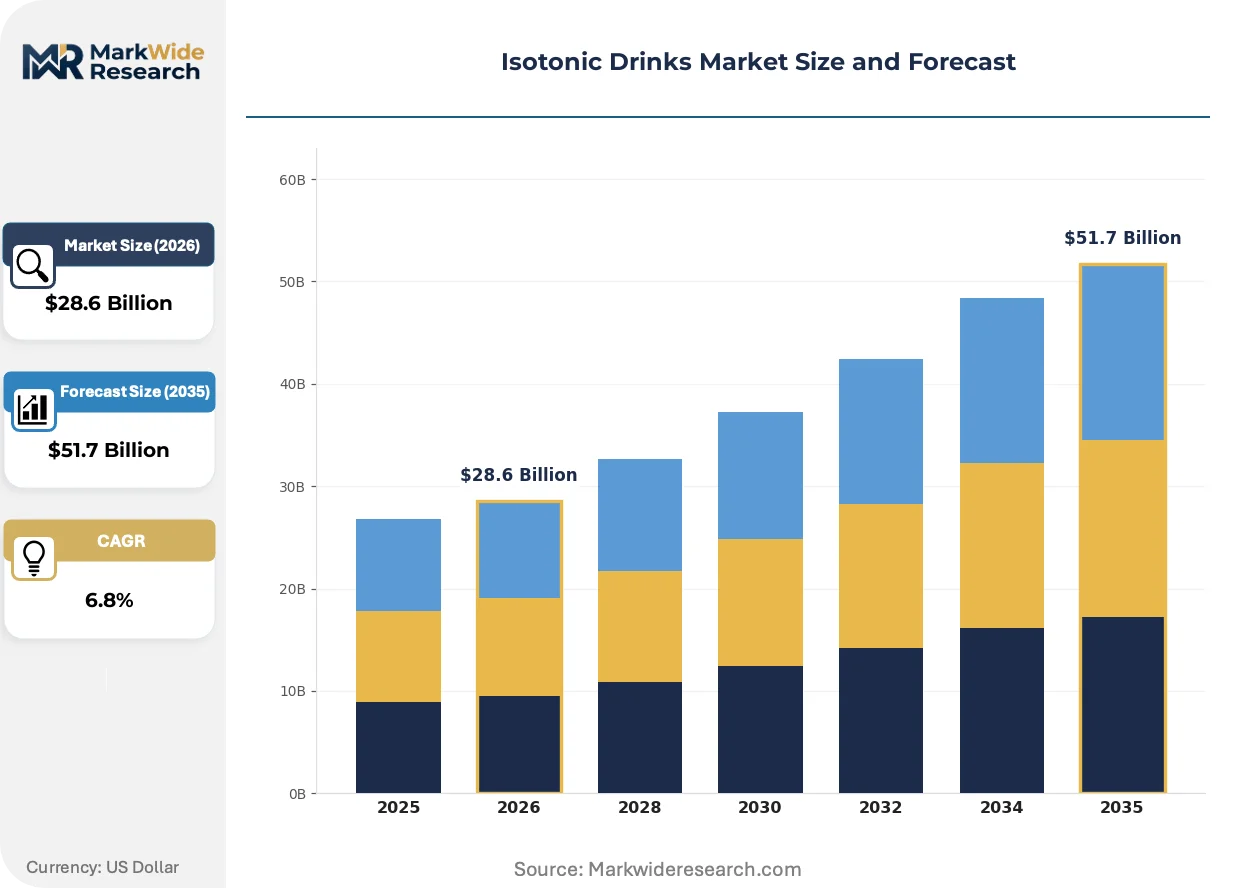
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sports Drinks, Energy Drinks, Recovery Drinks, Functional Beverages End User: Athletes, Fitness Enthusiasts, Casual Drinkers, Health-Conscious Individuals Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Specialty Stores Packaging Type: Plastic Bottles, Cans, Tetra Packs, Pouches |
| Companies Covered | Abbott Laboratories, Monster Beverage Corp., The Coca-Cola Company, Grupo Pisa, Otsuka Pharmaceutical, PepsiCo Inc., Suntory Holdings Limited, The Vita Coco Company, Nestlé S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isotonic Drinks Market Shifts & Advancements
Formulation science is fragmenting across specialized hydration protocols, with protein-carbohydrate combinations displacing standalone recovery products and institutional electrolyte research migrating into consumer-grade offerings.
Precision osmolarity tuning is decomposing the traditional one-size-fits-all sports drink category. Advanced formulation platforms now enable real-time adjustment of sodium-to-carbohydrate ratios for specific exertion intensities and ambient temperature conditions. Elite athletic programs and boutique fitness studios are adopting these personalized protocols fastest. This technology is decomposing mass-market brand loyalty by enabling private-label and direct-to-consumer alternatives with performance claims previously exclusive to institutional suppliers.
REACH framework constraints on artificial additive portfolios are reshaping European formulation strategies. The regulation's sunset clauses for specific colorants and preservatives are forcing reformulation of legacy products ahead of compliance deadlines. Recovery Drinks incorporating natural stabilizers and plant-derived electrolyte sources are capturing disproportionate shelf space in German and French retail channels as brands preempt regulatory displacement.
Fitness Enthusiasts are unbundling hydration from institutional sports contexts, creating demand for portable formats suited to hybrid work schedules and boutique studio attendance. Single-serve powder sachets and collapsible bottles are displacing traditional ready-to-drink bottles in urban commuter segments. Brazil and South Korea exhibit the most pronounced channel fragmentation, with convenience stores and direct-to-consumer subscriptions eroding supermarket dominance in replenishment purchasing.
Isotonic Drinks Market Segmentation
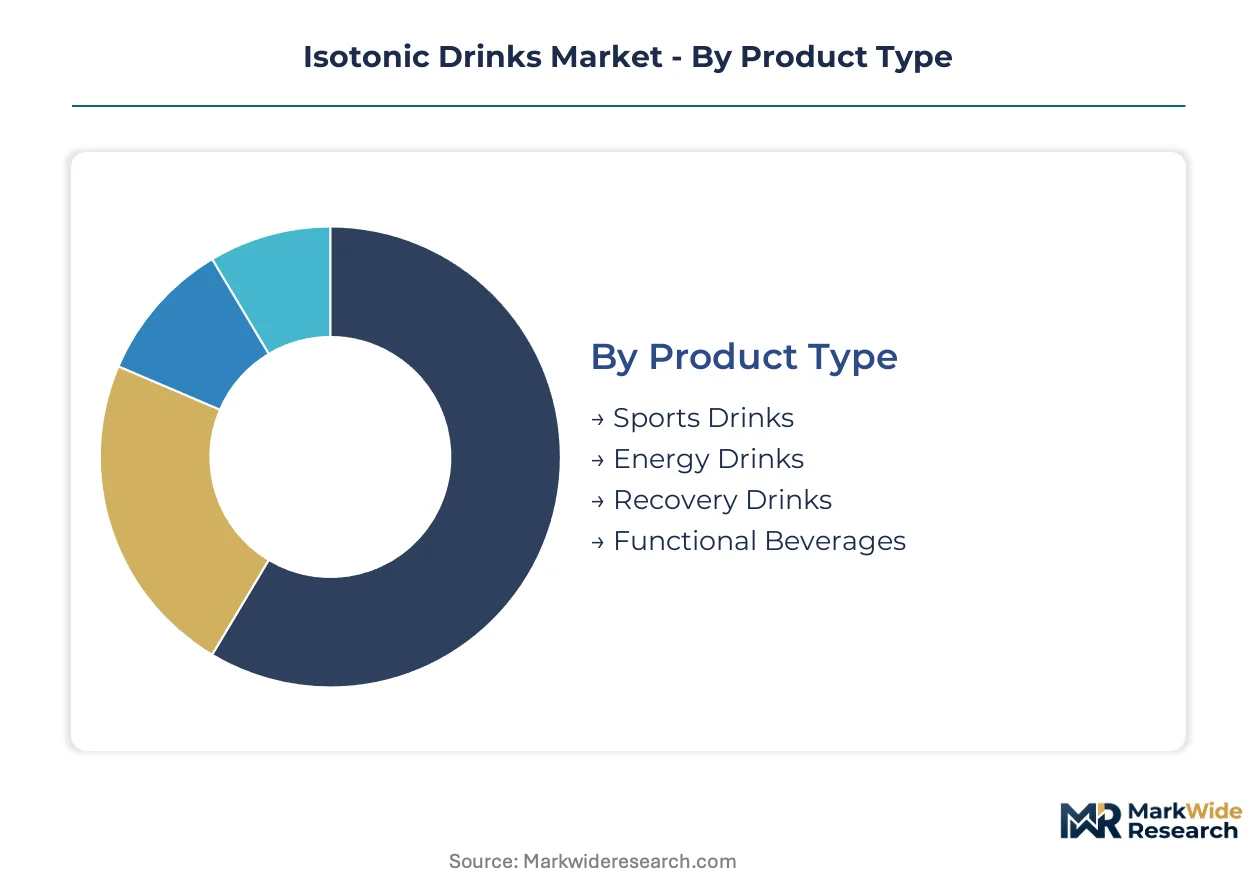
Isotonic drink manufacturers configure production lines around distinct hydration protocols and consumption rituals. Each segment demands specialized osmolarity profiles, sodium-carbohydrate ratios, and packaging formats that dictate formulation chemistry and supply chain architecture.
Product Type:
Sports Drinks anchor domestic volume in Brazil and export flows to tropical markets, while Recovery Drinks and Functional Beverages concentrate premium positioning in North American and European direct-to-consumer channels.
- Sports Drinks:Aqueous formulations with 6-8% carbohydrates and 460-700 mg sodium per liter match blood plasma osmotic pressure to accelerate gastric emptying during exertion. Brazilian marathon running culture and tropical climate conditions sustain per-capita consumption leadership, with localized heat-adapted sodium concentrations driving institutional team procurement.
- Recovery Drinks:Protein-carbohydrate combinations displace standalone protein shakes in post-exercise windows through precision electrolyte-carbohydrate synergy. Fitness Enthusiasts in North American boutique studios and European urban centers adopt these protocols fastest, compressing the traditional recovery nutrition purchase cycle.
- Energy Drinks:Caffeine and taurine additions target mental alertness alongside physical performance, with hybrid isotonic-energy formulations migrating energy drink flavor science into sports hydration.
- Functional Beverages:Adaptogens and nootropic additives command premium positioning in white-collar wellness segments, with German and French retail channels allocating disproportionate shelf space to natural stabilizer formulations ahead of REACH sunset clauses.
Sports Drinks commands the established base. The steepest expansion runs through Recovery Drinks.
End User:
Athletes concentrate demand in stadium fountain systems and institutional bulk dispensing, while Fitness Enthusiasts fragment purchasing across convenience stores and subscription channels.
- Athletes:Professional and collegiate programs require institutional-grade electrolyte protocols with batch-certified osmolarity precision. Stadium and gym fountain infrastructure locks in exclusive pouring agreements that reduce per-unit packaging costs.
- Fitness Enthusiasts:Post-workout hydration routines previously restricted to professional athletes now expand the addressable consumer base through boutique studio adoption and hybrid work schedule portability. Single-serve powder sachets and collapsible bottles displace ready-to-drink formats in urban commuter segments across Brazil and South Korea.
- Casual Drinkers:Heat-adapted consumption in tropical climates sustains replenishment purchasing outside athletic contexts, with convenience store channels capturing impulse hydration occasions.
- Health-Conscious Individuals:Front-of-pack labeling mandates and sugar taxation thresholds recategorize traditional formulations, driving demand for reduced-carbohydrate and natural additive alternatives in European markets.
Athletes anchor institutional volume. Fitness Enthusiasts generate the fastest share gains.
Distribution Channel:
Supermarkets retain replenishment purchasing for household stockpiling, while Online Retailers fragment loyalty through direct-to-consumer subscription models and personalized electrolyte protocols.
- Supermarkets:Multi-pack formats and promotional pricing sustain household inventory building, though channel dominance erodes in Brazil and South Korea where convenience stores and subscriptions capture replenishment occasions.
- Online Retailers:Direct-to-consumer platforms enable precision osmolarity tuning and personalized sodium-carbohydrate ratios, decomposing mass-market brand loyalty through private-label alternatives with performance claims previously exclusive to institutional suppliers.
- Convenience Stores:Single-serve portability targets urban commuters and boutique studio attendees, with localized flavor formulations driving heat-adapted impulse purchases.
- Specialty Stores:Premium positioning around adaptogen and nootropic additives captures white-collar wellness segments, with curated assortments emphasizing natural stabilizers and plant-derived electrolyte sources.
Supermarkets retain the volume base. Online Retailers climb the fastest as subscription models lock in recurring revenue.
Packaging Type:
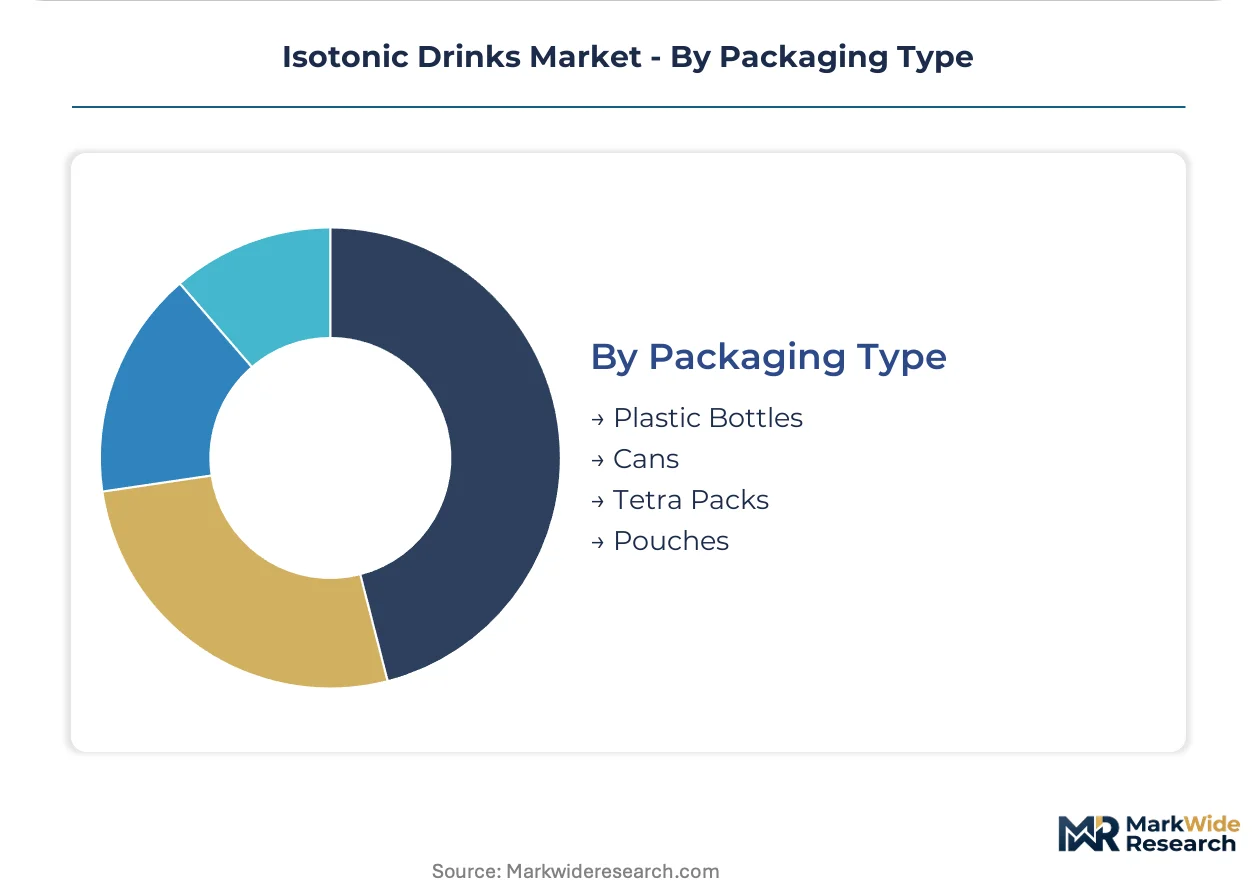
Plastic Bottles concentrate cost-sensitive mass-market production, while regulatory pressure accelerates material transitions toward recyclable and reduced-plastic formats.
- Plastic Bottles:PET formats dominate cost-optimized production lines, though EU Green Deal mandates force rapid transition toward biodegradable alternatives and closed-loop refill systems across European supply chains.
- Cans:Aluminum formats command premium positioning in stadium and gym fountain infrastructure, with bulk dispensing systems reducing per-unit material costs while locking in institutional channel access.
- Tetra Packs:Aseptic carton technology extends shelf stability for natural stabilizer formulations, capturing shelf space in German and French retail channels ahead of REACH compliance deadlines.
- Pouches:Flexible formats target portable consumption for hybrid work schedules and boutique studio attendance, with collapsible designs displacing rigid bottles in urban commuter segments.
Plastic Bottles command the installed base. The steepest expansion trajectory runs through Pouches as portability demands fragment traditional packaging preferences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil consumes isotonic drinks for marathon training in tropical heat, while German buyers prioritize post-workout recovery protocols. This demand-mix differential shapes formulation priorities across manufacturing hubs.
Brazil
Marathon running culture and year-round high temperatures sustain per-capita consumption leadership. ANVISA regulates electrolyte additive claims and front-of-pack labeling requirements. São Paulo's manufacturing corridor concentrates heat-adapted sodium formulations for domestic distribution and regional export.
United States
Fitness enthusiasts adopt institutional-grade recovery routines previously restricted to professional athletes. FDA GRAS status requirements govern electrolyte additive portfolios. Greater Los Angeles and Austin metro areas fragment purchasing across boutique studio subscriptions and convenience store channels.
Germany
REACH framework sunset clauses force reformulation of legacy products ahead of artificial additive deadlines. EU Green Deal packaging mandates accelerate transitions toward biodegradable bottle technologies. Bavaria's beverage clusters invest in closed-loop refill systems and natural stabilizer production lines.
Japan
Precise osmolarity tuning for specific exertion intensities drives demand for personalized hydration protocols. METI oversees functional food labeling and health claim substantiation. Osaka-Kobe manufacturing zones specialize in rapid-adjustment formulation platforms for elite athletic programs.
South Korea
Urban commuters favor portable formats suited to hybrid work schedules and boutique studio attendance. MFDS regulates functional beverage claims and additive safety assessments. Seoul Capital Area convenience stores and direct-to-consumer subscriptions erode supermarket dominance in replenishment purchasing.
Isotonic Drinks Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with beverage conglomerates leveraging fountain infrastructure and distribution scale against niche formulators focused on personalized electrolyte protocols. The competitive terrain rewards institutional channel access and regulatory dossier depth. Three archetypes dominate: diversified beverage majors with sports nutrition portfolios, pharmaceutical-backed functional drink specialists, and regional hydration brands with localized flavor expertise. Capacity expansion into biodegradable packaging and strategic partnerships for electrolyte research partnerships represent the dominant competitive moves.
Within the diversified beverage tier, The Coca-Cola Company and PepsiCo Inc. exemplify scale-driven channel control, while Monster Beverage Corp. occupies a hybrid position extending energy drink flavor science into isotonic formulations. Abbott Laboratories anchors the pharmaceutical-backed functional drink segment with clinical nutrition credentials. These players collectively represent the tension between mass-market distribution efficiency and precision-formulation specialization reshaping competitive positioning.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Monster Beverage Corp. |
| The Coca-Cola Company |
| Grupo Pisa |
| Otsuka Pharmaceutical |
| PepsiCo Inc. |
| Suntory Holdings Limited |
| The Vita Coco Company |
| Nestlé S.A. |
| Others |
Supply & Pricing Matrix
Biodegradable bottle technologies replacing conventional PET formats are redrawing manufacturing geography toward Bavaria's beverage clusters while compressing margin structures across European supply chains. This material transition simultaneously elevates capital requirements for compliant production and fragments pricing power between legacy scale players and regional specialists with sustainability certifications.
Pricing Analysis
Long-term offtake agreements with stadium and gym fountain infrastructure anchor volume pricing for institutional channels, while spot purchasing through convenience stores captures heat-adapted impulse premiums in tropical markets. Three-tier pricing structure across premium adaptogen formulations, standard electrolyte protocols, and economy private-label alternatives reflects certification grade and vertical integration depth. Price erosion runs through economy tiers as Brazilian and South Korean retailers consolidate procurement around house brands. Fitness enthusiasts in boutique studio subscriptions exhibit lowest price sensitivity, while casual heat-driven purchasers in convenience channels drive hardest bargain.
Supply Chain Analysis
Inventory lead times for natural stabilizers and plant-derived electrolyte sources have extended as REACH sunset clauses force accelerated reformulation cycles across German and French manufacturing hubs. Supply concentrates in Brazil for heat-adapted sodium formulations, Germany for biodegradable packaging technologies, and Japan for precision osmolarity tuning platforms. Raw material dependencies include citric acid from Chinese fermentation facilities, natural flavor extracts from Southeast Asian agricultural processors, and pharmaceutical-grade sodium chloride from German chemical clusters. Single-source vulnerability in natural stabilizer supply threatens continuity as brands preempt regulatory displacement. Distribution runs through fountain infrastructure for institutional volume, direct-to-consumer subscriptions for personalized protocols, and convenience store networks for portable replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based electrolyte protocol customization represents a service-attach layer expanding faster than ready-to-drink hardware, as Fitness enthusiasts lock in recurring revenue through personalized sodium-carbohydrate ratios.
For Market Incumbents: Shield formulation dossier advantages by accelerating GRAS portfolio expansion ahead of FDA scrutiny intensification. Deepen backward integration into natural stabilizer supply through captive agricultural partnerships in Southeast Asia. Stadium fountain exclusivity agreements remain the priority defensive lever against hybrid isotonic-energy entrants. For New Entrants and Emerging Players: Precision osmolarity tuning for boutique fitness studios represents a service-layer gap where institutional suppliers under-serve individual protocol demands. Target direct-to-consumer channels in South Korea and urban Brazil where convenience store fragmentation erodes incumbent lock-in. Go-to-market acceleration through collapsible bottle and single-serve sachet portability features captures hybrid work schedule hydration occasions. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional hydration brands possessing localized flavor expertise but lacking sustainability certification depth. Five-to-ten year viability hinges on biodegradable packaging transition completion and electrolyte research partnership durability. Signal to watch: ANVISA front-of-pack labeling mandate tightening that recategorizes traditional formulations as confectionery, compressing valuation multiples for non-compliant portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Packaging Transition | EU Green Deal compliance locks in European channel access ahead of REACH additive deadlines. |
| Electrolyte Research Partnership | Institutional sports relationships with NCAA programs validate performance claims for consumer migration. |
| Fountain Infrastructure Expansion | Bulk dispensing systems reduce per-unit material costs while creating exclusive pouring agreements. |
| Direct-to-Consumer Subscription Launch | Personalized sodium-carbohydrate protocols decompose mass-market brand loyalty through private-label alternatives. |
| Natural Stabilizer Backward Integration | Captive agricultural supply in Southeast Asia mitigates REACH-driven reformulation cost volatility. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with sports nutrition formulation scientists, stadium procurement directors, and direct-to-consumer platform operators; and secondary validation through ANVISA regulatory filings, EU ECHA REACH sunset clause documentation, and Brazilian customs trade records. Bottom-up triangulation against top-down category expenditure estimates anchored volume and value outputs. Primary fieldwork concentrated on manufacturing hubs in São Paulo, Bavaria, and Osaka-Kobe with downstream channel coverage across convenience store networks and boutique fitness studio operators.
Across the projection horizon, the analytical framework modeled demand trajectories by product type, end-user cohort, distribution channel, and packaging format with regional regulatory cluster differentiation. CAGRs derived from segment-level growth rate reconciliation against macroeconomic consumption elasticity assumptions. Industry-specific forecast inputs included marathon participation rates in tropical climates, EU packaging mandate compliance cost curves, and sports nutritionist labor availability indices in North American manufacturing corridors.
Underlying assumptions cover sustained Fitness enthusiast adoption of institutional-grade recovery protocols, with deviation risk concentrated in sugar taxation threshold revisions and front-of-pack labeling mandate harmonization failures across FDA, EFSA, and ANVISA jurisdictions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Diet Soda Market
Non-Alcoholic Beverages
Lemonade Market
Non-Alcoholic Beverages
Europe Soy Beverages Market
Non-Alcoholic Beverages
North America Bottled Water Market
Non-Alcoholic Beverages
Non-Alcoholic Wine and Beer Market
Non-Alcoholic Beverages
Europe Energy Drink Market
Non-Alcoholic Beverages
North America Soy Beverages Market
Non-Alcoholic Beverages
Africa Energy Drinks Market
Non-Alcoholic Beverages
GCC Non-Alcoholic Beer Market
Non-Alcoholic Beverages
Bubble Tea Market
Non-Alcoholic Beverages
US Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
Global Non Alcoholic Concentrated Syrup Market
Non-Alcoholic Beverages
Soy Beverage Market
Non-Alcoholic Beverages
Flavored Water Market
Non-Alcoholic Beverages
Global Sugar Free Beverages Market
Non-Alcoholic Beverages
Zero Proof Spirit Market