
 Bubble Tea Market | 2026-2036
Bubble Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Bubble Tea Market Intelligence
Customizable topping-and-base bundling is recalibrating how consumers construct orders and perceive value. Gong Cha leverages its centralized syrup production to sustain consistency across franchised locations. Mixue anchors its competitive stance through extreme price positioning and rural penetration density. Chatime Group competes via format experimentation, rolling compact express counters alongside full-service cafés.
Bubble tea denotes a cold-served beverage comprising brewed tea, milk or non-dairy creamer, sweetener, and chewy tapioca pearls typically measuring 8-10 millimeters in diameter, prepared through sequential cooking, rinsing, and sugar-soaking of starch-based spheres before assembly. The drink functions as a refreshment product and social consumption ritual, with texture contrast between liquid and solid components serving as the core sensory differentiator. Milk tea occupies the mature volume base while topping varieties command the highest per-unit margin contribution due to incremental add-on pricing. Young adults represent the fastest-expanding customer type as workplace consumption normalizes beyond traditional teenage trial occasions.
US FDA oversight of color additives and sweetener thresholds shapes permissible formulation ranges for imported flavor concentrates. Taiwan's Ministry of Health and Welfare enforces tapioca pearl starch origin labeling and preservative limits that directly affect cross-border supply qualification. China's SAMR implements GB standards for dairy analogues used in creamer blends, constraining substitution pathways for brands operating mainland production. Stakeholders must monitor evolving plant-based certification requirements across multiple Asian regulatory regimes to anticipate reformulation costs and sourcing switches.
Market Dynamics
Customizable topping-and-base bundling is recalibrating how consumers construct orders and perceive value, forcing operators to reconfigure kitchen workflows and inventory systems around modular assembly rather than fixed-menu production.
Growth Catalysts
- Taiwan NMPA-aligned additive standards:Clear formulation guidelines reduce cross-border qualification friction for concentrate exporters entering Southeast Asian markets.
- Gen Z trial expansion:University corridor density and urban retail zone clustering normalize workplace consumption beyond traditional teenage occasions.
- Non-dairy milk alternatives:Oat and coconut creamer adoption broadens addressable dietary segments without full reformulation of base tea concentrates.
Market Restraints
- Cassava starch price volatility:Tapioca pearl input costs fluctuate with Thai and Vietnamese agricultural output cycles, compressing margin on the highest-margin topping category.
- Supply concentration in Taiwan:Premium syrup and concentrate production clusters on the island, creating single-source risk for consistency-dependent franchise networks.
- GB dairy analogue constraints:China's SAMR standards limit creamer substitution pathways for brands operating mainland production facilities.
Strategic Opportunities
- Ho Chi Minh City kiosk density gaps:Underpenetrated districts beyond District 1 offer first-mover positioning before competitor saturation accelerates.
- Express counter format experimentation:Compact footprint models reduce capex per unit and unlock high-footfall transit hub placement.
- Thailand FSSAI-equivalent plant-based certification:Anticipated regulatory clarity on oat and almond milk claims creates timing advantage for early certifiers.
Industry Challenges
- Pearl cooking skill scarcity:Consistent texture execution requires trained kitchen labor that churns rapidly in high-turnover retail environments.
- Multi-regulatory compliance timelines:Simultaneous FDA color additive reviews and Taiwan starch-origin labeling create parallel certification bottlenecks for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bubble Tea Market |
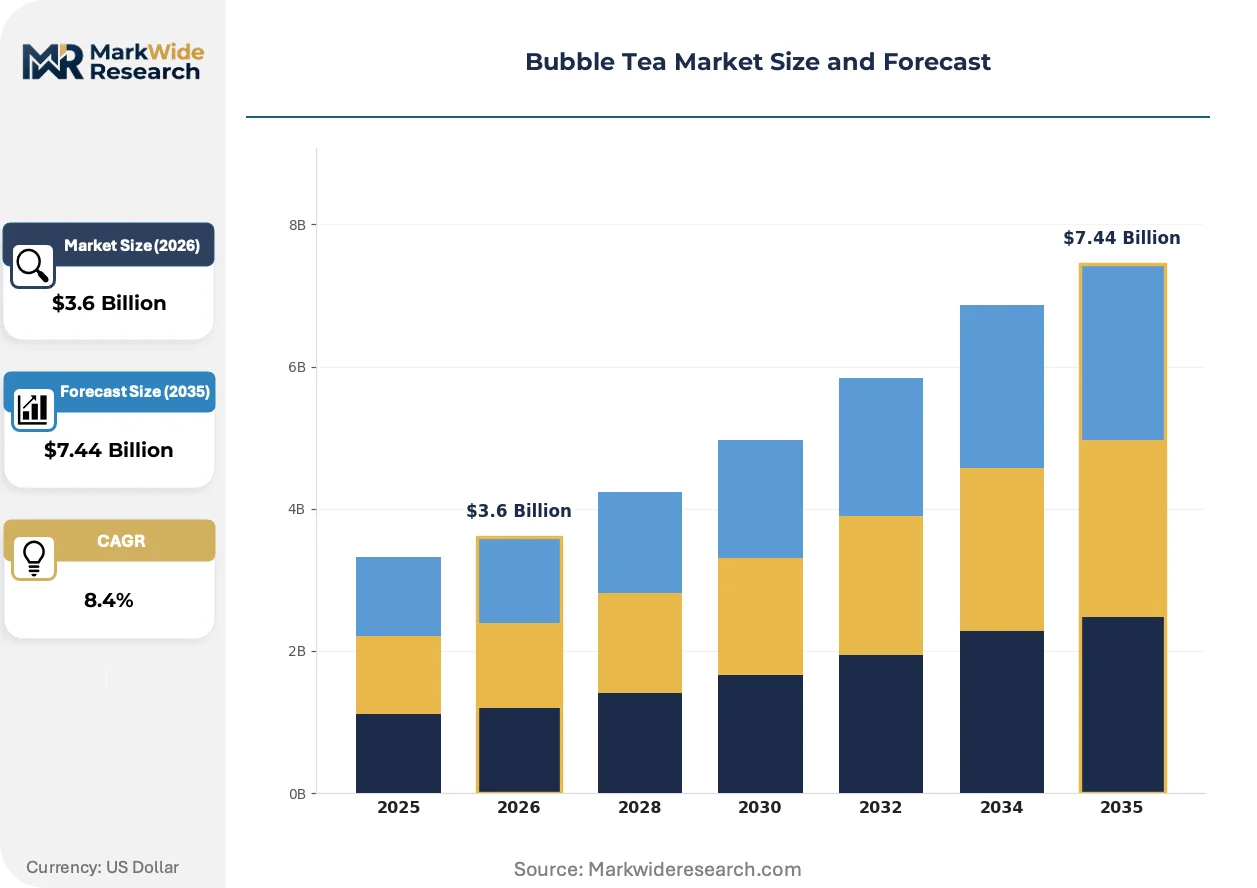
| Market Size in 2026 | $3.6 Billion |
| Market Size in 2035 | $7.44 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk Tea, Fruit Tea, Topping Varieties, Frozen Drinks Distribution Channel: Online Sales, Cafes, Supermarkets, Food Trucks Customer Type: Teens, Young Adults, Families, Professionals Flavor Profile: Classic, Fruity, Herbal, Dessert |
| Companies Covered | Kung Fu Tea, The Alley, Mixue, Boba Guys, Lollicup USA Inc., Gong Cha, CoCo Fresh Tea & Juice, Tapioca Express, Chatime Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bubble Tea Market Strategic Shifts & Innovations
Texture customization and format miniaturization are compressing traditional café economics while expanding consumption occasions beyond seated service into transit and workplace contexts.
Automated pearl cookers with IoT-enabled temperature monitoring are converging with cloud-based kitchen management systems. Franchise operators in Bangkok and Singapore are deploying these units to reduce texture variance across locations. This convergence is compressing the training burden for hourly staff while enabling real-time consistency auditing from central operations.
Taiwan's Ministry of Health and Welfare now enforces tapioca pearl starch origin labeling and preservative limits that directly affect cross-border supply qualification. Imported concentrate batches face extended customs review without documented cassava source verification. Southeast Asian distributors are responding by dual-sourcing from Thai and Vietnamese starch processors to maintain qualification continuity.
Young adult workplace consumption is displacing traditional teenage trial as the dominant demand formation pattern. Office district kiosks in Ho Chi Minh City and Bangkok are replacing mall-based full-service cafés as the primary customer acquisition channel. This rotation is most visible in Vietnam, where midday delivery bundling now exceeds evening walk-in traffic for established operators.
Bubble Tea Market Segmentation
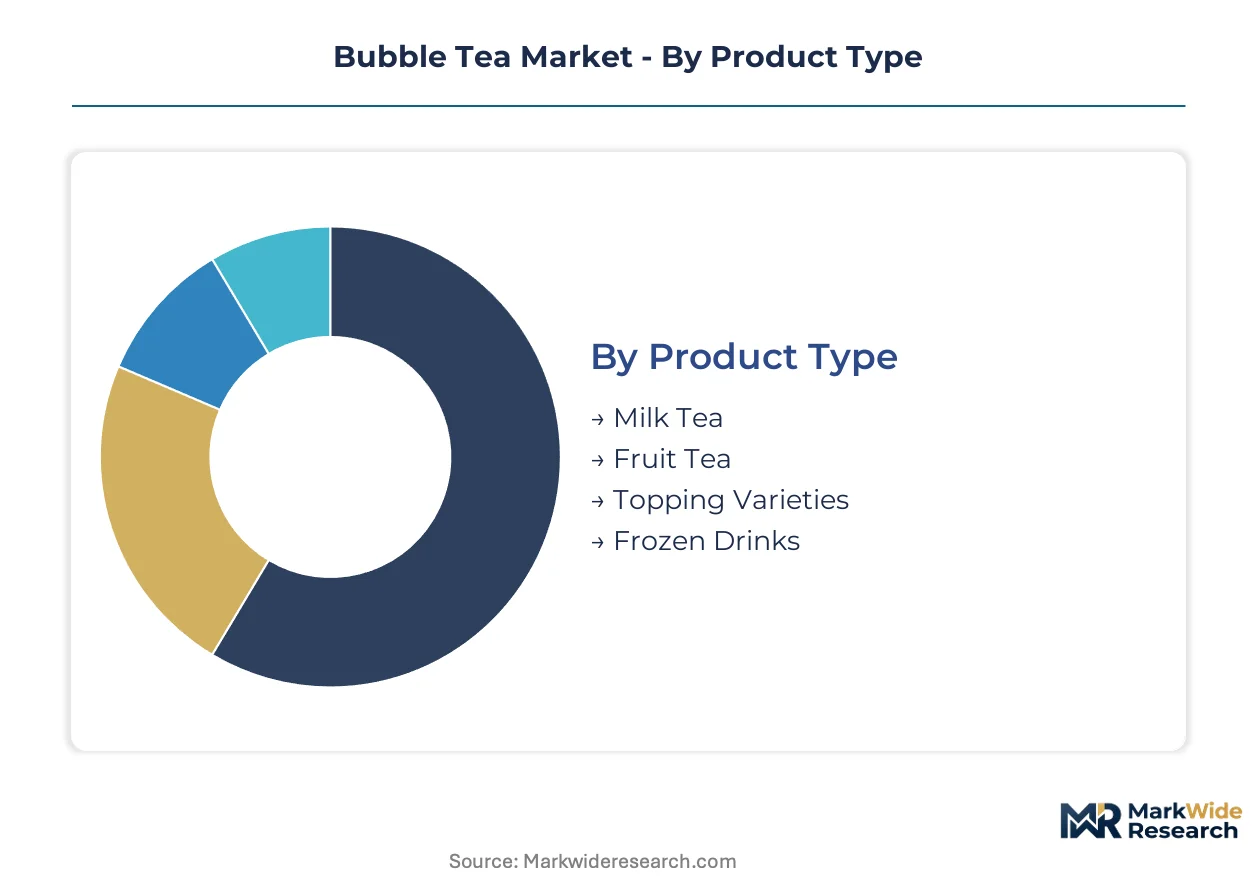
Bubble tea segmentation reveals how capital deployment, customer acquisition costs, and operational complexity vary dramatically across product formats and channel models. Understanding these structural differences helps operators prioritize expansion sequencing and margin protection strategies.
Product Type:
Capital intensity diverges sharply across preparation methods, with frozen equipment and topping infrastructure demanding substantially higher upfront outlays than base tea brewing systems.
- Milk Tea:Brewed black or green tea combined with dairy or non-dairy creamer forms the volume foundation of most franchise networks. Demand concentrates in Bangkok and Ho Chi Minh City office districts where midday consumption now exceeds evening traffic. Taiwan's NMPA-aligned additive standards constrain cross-border concentrate sourcing for operators seeking consistency.
- Topping Varieties:Tapioca pearls, popping boba, grass jelly, and pudding require dedicated cooking stations with precise temperature control and holding equipment. Thai and Vietnamese cassava starch supply volatility compresses margin on this highest-margin add-on category, forcing dual-sourcing strategies.
- Fruit Tea:Fresh fruit infusion demands cold-chain logistics and shorter inventory cycles. Most installed capacity flows through Milk Tea. Expansion is steepest in Topping Varieties.
- Frozen Drinks:Slush and smoothie formats require high-capacity blenders and freezer storage, elevating per-unit equipment costs.
Most installed capacity flows through Milk Tea. Expansion is steepest in Topping Varieties.
Distribution Channel:
Real estate and build-out economics separate channels into distinct capital tiers, with full-service cafés at the heavy end and mobile formats at the lean extreme.
- Cafes:Full-service locations with seating, kitchen infrastructure, and front-of-house staff represent the highest fixed-cost format. District 1 saturation in Ho Chi Minh City is pushing operators toward underpenetrated peripheral districts where first-mover positioning remains available.
- Food Trucks:Mobile units bypass commercial lease commitments but face permitting complexity and power limitations for pearl cooking equipment. Express counter experimentation is unlocking transit hub placement in Singapore and Bangkok where footfall density justifies compact footprints.
- Online Sales:Delivery-native operators avoid real estate entirely but absorb platform commission structures and packaging costs for temperature-sensitive products.
- Supermarkets:Pre-packaged bottled formats require manufacturing scale and retail slotting fees, shifting competitive basis toward manufacturing efficiency.
Cafes absorb the majority of sector capital deployment. Online Sales are climbing the fastest as delivery bundling normalizes workplace consumption.
Customer Type:
Acquisition cost and lifetime value calculations vary by demographic, with younger segments offering volume but professionals delivering higher per-visit spend and frequency.
- Young Adults:University corridors and early-career workplace clusters drive trial expansion beyond traditional teenage occasions. This segment commands premium pricing tolerance for customization and format experimentation.
- Teens:Mall-based social consumption established the category but faces displacement as workplace normalization shifts demand geography.
- Professionals:Midday delivery orders and office district kiosk visits generate higher average tickets with less price sensitivity.
- Families:Multi-unit purchases and weekend occasion clustering create volume spikes but lower per-capita margins.
Young Adults represent the dominant revenue pool. Professionals are gaining share fastest as workplace consumption patterns mature.
Flavor Profile:
Formulation complexity and ingredient sourcing risk differentiate flavor categories, with herbal and dessert variants requiring more specialized supply chains than classic bases.
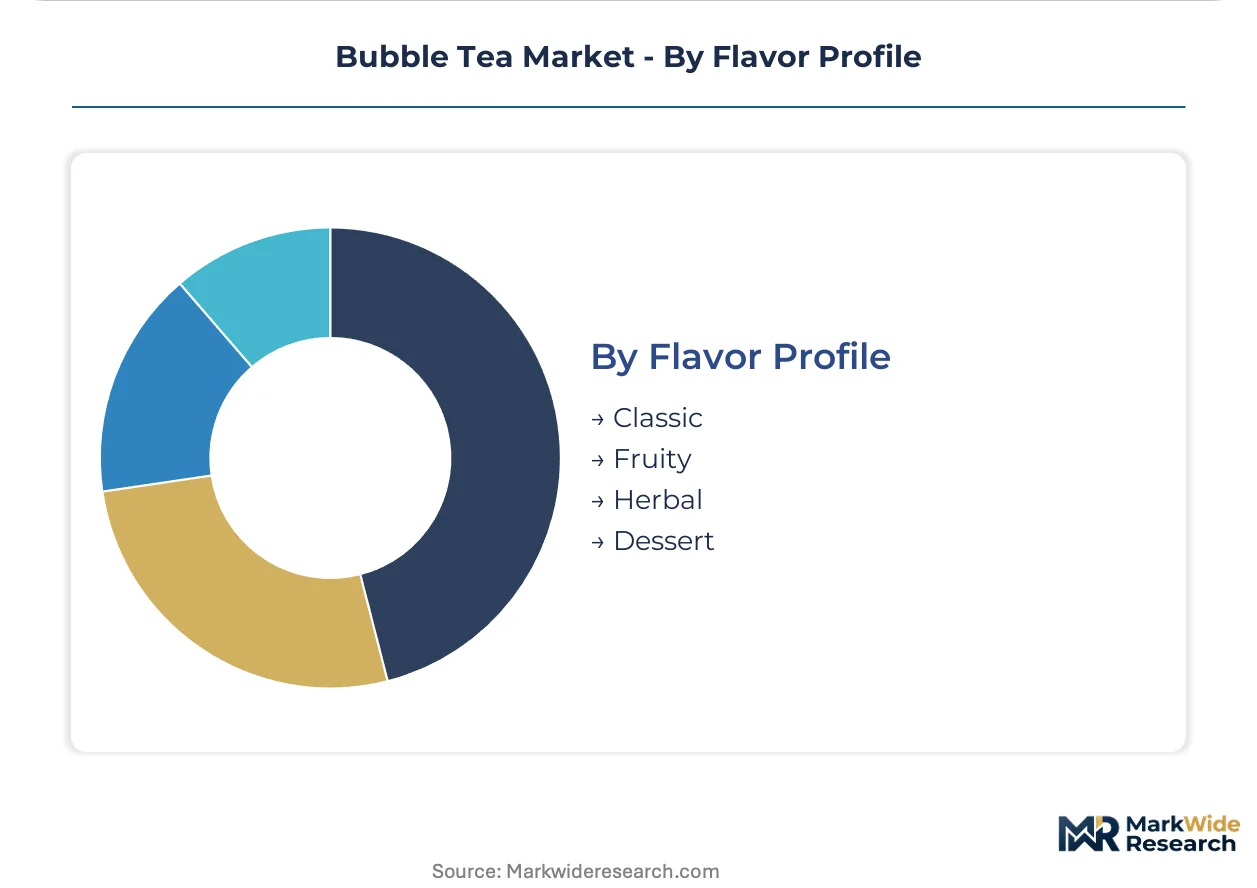
- Classic:Black milk tea and green milk tea variants rely on standardized concentrate supply with lowest reformulation risk under Taiwan's starch-origin labeling requirements.
- Fruity:Seasonal fruit availability and preservative limits under Taiwan's Ministry of Health and Welfare enforcement create batch-to-batch variability challenges.
- Herbal:Chrysanthemum, oolong, and specialty tea bases require distinct brewing protocols and supplier qualification.
- Dessert:Chocolate, taro, and cheese foam variants incorporate dairy analogues constrained by China's SAMR GB standards for creamer substitution.
Classic flavors anchor production volume. Dessert profiles are expanding most quickly as operators chase social media differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan birthed the bubble tea category in 1980s tea houses, establishing formulation standards that now propagate through Southeast Asian franchise networks. Demand geography has shifted toward metropolitan corridors in Thailand, Vietnam, and Singapore where kiosk density is accelerating fastest.
Taiwan
Domestic consumption normalizes workplace trial among young professionals beyond traditional teenage occasions. The Ministry of Health and Welfare enforces tapioca pearl starch origin labeling and preservative limits that constrain cross-border concentrate qualification. Taipei anchors premium syrup production clusters where NMPA-aligned standards reduce export friction for Southeast Asian distributors.
Thailand
Bangkok office districts drive midday consumption volumes that now exceed evening mall traffic for established operators. Anticipated FSSAI-equivalent plant-based certification clarity on oat and almond milk claims creates timing advantages for early movers. Sukhumvit and Silom corridors concentrate express counter experimentation targeting transit hub footfall.
Vietnam
Ho Chi Minh City districts beyond District 1 present first-mover positioning before competitor saturation accelerates. Delivery platform commission structures reshape unit economics for online-native operators avoiding real estate commitments. District 2 and District 7 sub-markets show fastest kiosk penetration growth among young adult workplace clusters.
China
GB standards for dairy analogues constrain creamer substitution pathways for brands operating mainland production facilities. SAMR oversight limits reformulation flexibility for operators seeking non-dairy milk alternatives. Yangtze River Delta and Pearl River Delta metropolitan zones concentrate format miniaturization trials in high-footfall transit locations.
Singapore
Compact footprint express counters unlock placement in MRT stations and central business district lobbies where seating is unnecessary. Young adult professionals generate higher average tickets with less price sensitivity than traditional teen segments. Orchard Road and Marina Bay clusters lead automated pearl cooker deployment with IoT-enabled consistency monitoring.
Bubble Tea Market Key Industry Players
Premium-margin players sit above commodity-margin players across customization depth and syrup sourcing sophistication, creating a tiered structure where consistency-dependent franchise networks compete against price-anchored kiosk operators. The vendor base spans centralized production specialists, extreme value penetrators, and format experimenters. Three archetypes dominate: Taiwan-origin concentrate-integrated chains, China-based rural density builders, and hybrid-format regional expanders. Competitive moves concentrate on express counter rollout and dual-sourcing qualification for tapioca pearl supply continuity.
Within the Taiwan-origin tier, Gong Cha exemplifies centralized syrup production integration, while Chatime Group occupies the format experimentation vector with compact express counter deployment. Mixue anchors the extreme price-positioning archetype through rural penetration density strategies. These three represent distinct competitive postures: consistency through supply control, flexibility through format innovation, and volume through price accessibility.
| Leading Market Players |
|---|
| Kung Fu Tea |
| The Alley |
| Mixue |
| Boba Guys |
| Lollicup USA Inc. |
| Gong Cha |
| CoCo Fresh Tea & Juice |
| Tapioca Express |
| Chatime Group |
| Others |
Cost & Logistics Intelligence
Premium-standard-economy tier divergence separates Gong Cha's centralized syrup integration from Mixue's rural density play, with each tier commanding distinct sourcing protocols and margin structures. Taiwan-origin concentrate qualification anchors the premium tier, while Thai-Vietnamese cassava starch dual-sourcing feeds the volume tier's cost compression tolerance.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the market, with certification grade under Taiwan's NMPA-aligned standards and brand premium for franchise network consistency serving as the primary price differentiation drivers. Pricing pressure stems from cassava starch input volatility compressing topping margins, the highest-margin add-on category. Young adult professionals in Bangkok and Ho Chi Minh City office districts show least price sensitivity, while rural kiosk customers in Vietnam's peripheral districts exhibit highest elasticity.
Supply Chain Analysis
Certification gating through Taiwan's Ministry of Health and Welfare starch-origin labeling and China's SAMR GB dairy analogue standards constrains cross-border concentrate qualification. Premium syrup production clusters in Taiwan, while Thai and Vietnamese cassava processors feed tapioca pearl supply. Single-source vulnerability concentrates in Taiwan's concentrate infrastructure, with distribution running through franchised kiosk networks and delivery platform aggregators in Southeast Asian metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bubble tea has entered a late-cycle quality phase where workplace normalization among young professionals prioritizes consistency certification over pure price competition. Premium specification demand now rewards NMPA-aligned formulation investment.
For Market Incumbents: Acquire automated pearl cooker fleets with IoT-enabled temperature monitoring to reduce texture variance across franchised locations. Defend against express counter format disruptors by securing transit hub placement rights in Bangkok's Sukhumvit corridor and Singapore's MRT stations. Certification investment in Thailand's anticipated FSSAI-equivalent plant-based standards creates timing advantage against delayed entrants. For New Entrants and Emerging Players: Delivery-native channels unlock Ho Chi Minh City districts beyond District 1 without real estate commitments. Target underpenetrated peripheral districts where first-mover kiosk density remains available before competitor saturation accelerates. Format miniaturization through compact express counters reduces capex per unit and enables high-footfall transit hub placement. For Investors and Strategic Acquirers: Consolidation pressure builds where dual-sourcing qualification capabilities separate viable franchise networks from single-source-dependent operators. Long-term viability favors concentrate-integrated chains with backward control over syrup production and cross-border regulatory navigation expertise. Watch for Thailand's plant-based certification clarity as inflection signal for oat and coconut creamer substitution economics.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Pearl Cooker Deployment | IoT-enabled temperature monitoring reduces texture variance across Gong Cha and Chatime Group franchise locations. |
| Dual-Sourcing Qualification | Thai-Vietnamese cassava starch diversification protects topping margins against agricultural output cycle volatility. |
| Express Counter Format Rollout | Compact footprint models unlock MRT station placement in Singapore and Bangkok transit corridors. |
| Plant-Based Certification Investment | Early alignment with Thailand's FSSAI-equivalent oat and almond milk standards captures timing premium. |
| Peripheral District Kiosk Expansion | Ho Chi Minh City District 2 and District 7 penetration precedes competitor saturation in office clusters. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with franchise operations directors, supply chain managers at concentrate producers, regulatory affairs leads in Taiwan and Thailand, and procurement officers at cassava starch processors. Secondary validation drew from Taiwan Ministry of Health and Welfare enforcement notices, Thailand FDA-equivalent regulatory filings, customs records for concentrate imports, and franchise disclosure documents. Bottom-up unit economics modeling and top-down market sizing triangulated volume and value estimates.
Comparable-period anchoring linked historical consumption patterns across the analysis window to projected kiosk density expansion and workplace normalization trends. Segmentation dimensions included product type, distribution channel, customer demographic, and flavor profile, with regional regulatory cluster and format miniaturization adoption rate as industry-specific overlays. CAGRs were derived from trend extrapolation of trial rates, penetration curves, and pricing elasticity assumptions, with Gen Z workplace consumption velocity and automated equipment deployment pace as key forecast inputs.
Cassava price volatility, regulatory timeline slippage in plant-based certification, and franchisee churn in high-turnover labor markets are the dominant revision risks to modeled outcomes. A model refresh is warranted upon material change in Thailand's FSSAI-equivalent regulatory clarity or Taiwan's starch-origin labeling enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Soft Drinks Market
Non-Alcoholic Beverages
Fermented Non-Dairy Beverages Market
Non-Alcoholic Beverages
North America Bottled Water Processing Market
Non-Alcoholic Beverages
Zero Sugar Beverages Market
Non-Alcoholic Beverages
North America Soy Beverages Market
Non-Alcoholic Beverages
Brazil Energy Drinks Market
Non-Alcoholic Beverages
Sugar Free Carbonated Drinks Market
Non-Alcoholic Beverages
Lemonade Market
Non-Alcoholic Beverages
Europe Sports and Energy Drinks Market
Non-Alcoholic Beverages
Iced Tea Market
Non-Alcoholic Beverages
Non-Alcoholic Drinks Market
Non-Alcoholic Beverages
Europe Soy Beverages Market
Non-Alcoholic Beverages
Non-Alcoholic Spirits Market
Non-Alcoholic Beverages
Global Sugar Free Beverages Market
Non-Alcoholic Beverages
Energy Drinks Market
Non-Alcoholic Beverages
Global Non Alcoholic Concentrated Syrup Market