
 Zero Proof Spirit Market | 2026-2036
Zero Proof Spirit Market Size, Share, and Industry Trends Forecast 2026-2036
Zero Proof Spirit Market Analytics
On-premise beverage programs is reshaping how zero proof spirits reach consumers. Ritual Zero Proof leverages direct-to-trade sampling to secure placement in upscale cocktail bars. Seedlip anchors its position through specialized distribution partnerships with premium hospitality groups. Lyre's competes by sustaining broad retail availability across multiple international markets.
Zero proof spirits are distilled or compounded beverages formulated without ethyl alcohol, typically containing botanical extracts, adaptogens, or functional ingredients that replicate the mouthfeel and aromatic complexity of traditional spirits for use in mixed drinks. The category serves consumers seeking sensory ritual without intoxication, whether for health, religious, or lifestyle reasons. Whiskey alternatives currently lead product type revenue due to higher per-unit pricing and established cocktail utility, while gin-style expressions represent the fastest-growing segment as bartenders adopt them in classic builds. Online retail channels capture expanding margin pools through subscription models, though supermarkets still dominate absolute volume for mid-range and value-positioned brands.
The FDA oversees labeling claims for non-alcoholic beverages in the United States, while the EFSA governs novel ingredient approvals across European markets, and the TTB regulates alcohol-adjacent marketing to prevent consumer confusion. These frameworks shape formulation choices, packaging language, and cross-border market access for producers. Stakeholders must monitor evolving definitions of "non-alcoholic" and "alcohol-free" as regulatory precision tightens and retail buyers demand clearer compliance documentation.
Market Dynamics
On-premise beverage programs are reshaping how zero proof spirits reach consumers, as premium bars and mixology programs across North America and Europe expand their non-alcoholic cocktail menus and demand clearer compliance documentation from suppliers.
Growth Catalysts
- FDA Labeling Frameworks:Tightening ingredient disclosure requirements in the United States are forcing producers to reformulate with cleaner labels, accelerating innovation in botanical extraction methods.
- Metropolitan Demand Concentration:Los Angeles, New York, and Chicago are anchoring volume growth as mixology-forward venues drive trial and category education.
- Adaptogen Integration:Functional ingredients that replicate mouthfeel and aromatic complexity are pulling health-conscious consumers from traditional spirits.
Market Restraints
- Botanical Input Volatility:Supply concentration for rare botanical extracts in specific growing regions creates cost instability for premium formulations.
- EFSA Novel Ingredient Approval:European regulatory friction delays market entry for innovative compounds, compressing first-mover advantages.
- Alcohol Adjacent Marketing Rules:TTB regulations in the United States restrict packaging language and cross-promotional activities, limiting brand storytelling.
Strategic Opportunities
- Subscription Channel Expansion:Direct-to-consumer models capture expanding margin pools through recurring revenue structures and personalized curation.
- Gin-Style Expression Development:The fastest-growing product segment offers white space for bartender education programs and classic build adoption.
- Upscale Hospitality Partnerships:Specialized distribution agreements with premium hotel and restaurant groups secure placement before retail saturation.
Industry Challenges
- Flavor Chemist Talent Scarcity:The specialized skill set required to replicate spirit mouthfeel without ethanol concentrates among a small pool of practitioners.
- Cross-Border Compliance Complexity:Divergent definitions of "non-alcoholic" and "alcohol-free" across jurisdictions force redundant testing and labeling investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zero Proof Spirit Market |
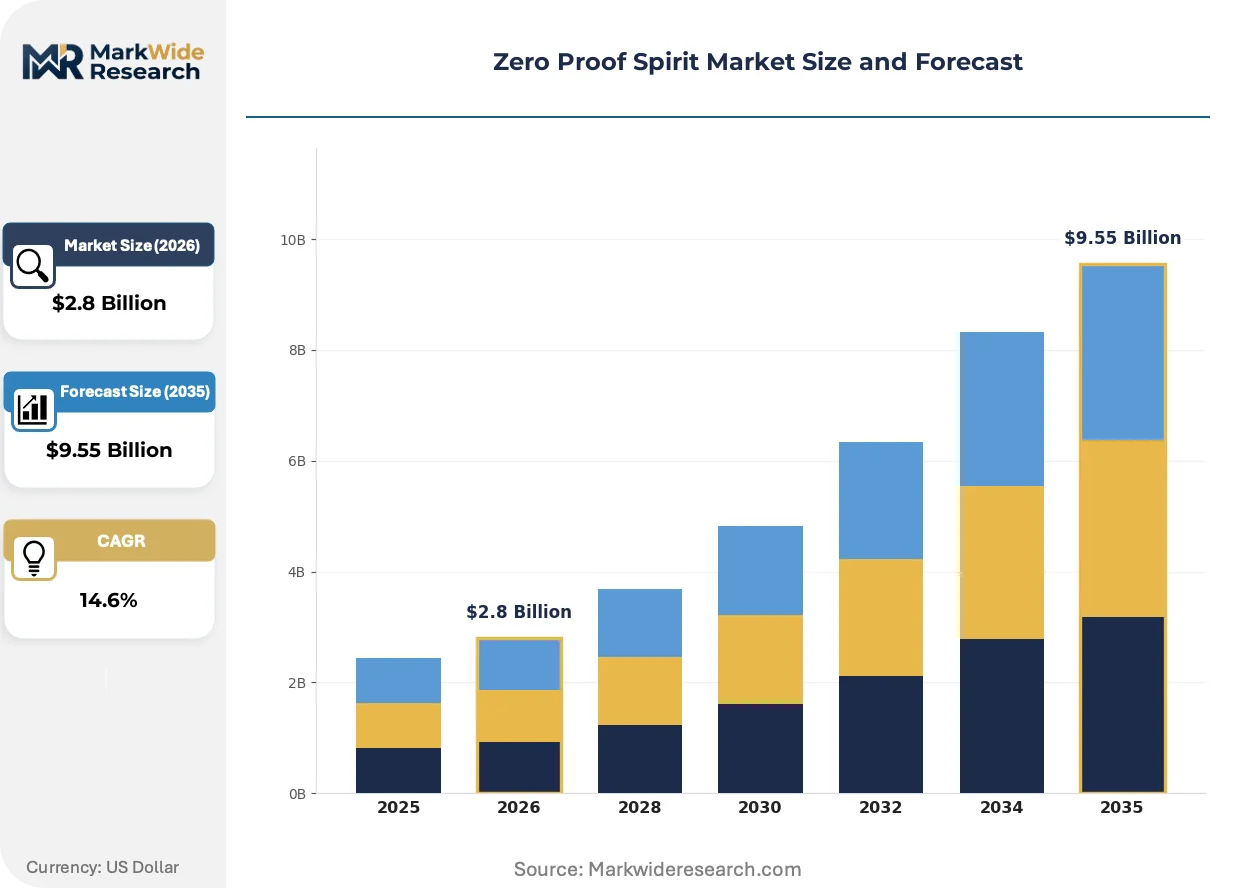
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whiskey, Gin, Vodka, Rum Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Bars Brand Positioning: Premium, Mid-Range, Value, Craft Target Consumer: Health-Conscious, Millennials, Non-Drinkers, Social Drinkers |
| Companies Covered | Aplós, The Pathfinder, Ritual Zero Proof, CleanCo, Empress 1908, Lyre's, BARE Zero Proof, Three Spirit, Seedlip, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zero Proof Spirit Market Evolving Landscape
Formulation science is advancing rapidly as producers seek to replicate the sensory ritual of traditional spirits. Three interconnected developments are reshaping competitive positioning in this category.
Distillation technology is hybridizing with compounding methods to achieve layered aromatic profiles previously unattainable without ethanol. Premium producers are adopting vacuum distillation and rotary evaporators to preserve volatile botanical compounds. This convergence is compressing the quality gap between zero proof and traditional spirits.
REACH compliance requirements in Europe are mandating full supply chain disclosure for botanical ingredients, forcing producers to map extraction sources and verify sustainability claims. The EFSA's tightening novel food approvals are most affecting adaptogen-heavy formulations, pushing brands toward established ingredient dossiers.
Bartender education investments are displacing traditional advertising as the primary demand generation mechanism. Mixology programs in the United States are prioritizing staff training over menu placement fees, with Los Angeles and New York venues leading this professional development shift. This behavioral change elevates brands that invest in technical support and recipe development.
Zero Proof Spirit Market Segmentation
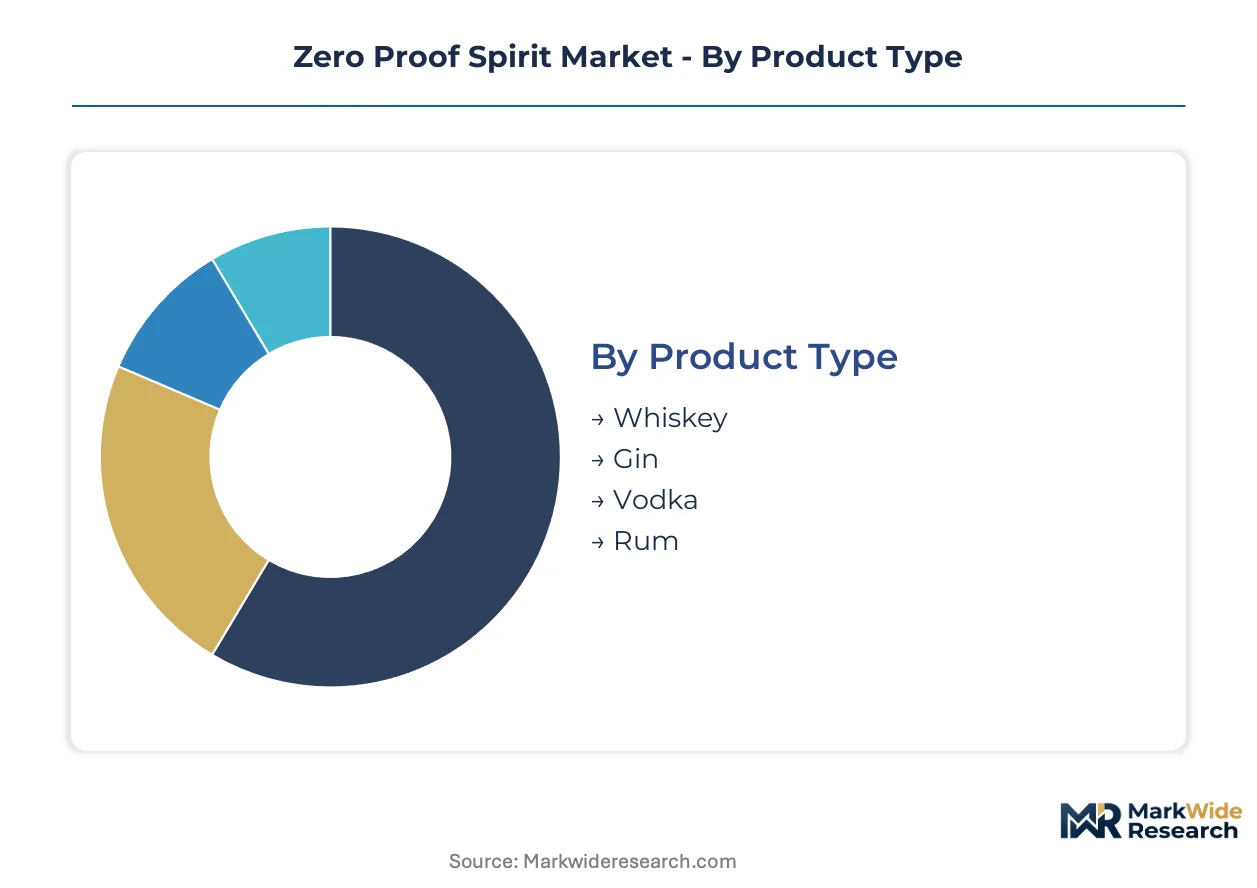
Zero proof spirits fragment across four distinct dimensions that shape procurement priorities and margin capture. Each segmentation axis reveals divergent growth trajectories and service intensity requirements that suppliers must navigate.
Product Type:
After-sales service intensity varies sharply by product type, with whiskey alternatives demanding the most technical support for bartender education and cocktail integration.
- Whiskey:Complex oak-aging simulation and caramelized sugar profiles require sophisticated flavor chemistry. Los Angeles and New York bars anchor demand as mixologists seek convincing Old Fashioned and Manhattan substitutes.
- Gin:Juniper-forward botanical layering achieves aromatic complexity through vacuum distillation. Chicago hospitality venues drive trial fastest as bartenders adopt these expressions in classic builds.
- Vodka:Neutral base spirits prioritize mouthfeel replication over flavor intensity. Health-conscious consumers in metropolitan clusters favor these for clean-label transparency.
- Rum:Molasses-derived sweetness and tropical fruit esters target tiki cocktail applications. Social drinkers seeking vacation-ritual substitutes concentrate demand in coastal urban markets.
Whiskey holds the largest share; momentum sits with gin.
Distribution Channel:
Channel selection determines margin structure and customer acquisition economics, with digital platforms capturing recurring revenue pools that physical retail cannot match.
- Online Retail:Subscription models and direct-to-consumer logistics enable personalized curation and higher per-unit margins. Health-conscious consumers drive subscription adoption for home experimentation.
- Supermarkets:Mass-market shelf placement dominates absolute volume for mid-range and value-positioned brands. Chicago and Los Angeles retail clusters anchor national distribution negotiations.
- Specialty Stores:Curated selection and staff expertise justify premium pricing for craft-positioned entrants. Millennials seek discovery experiences unavailable in conventional grocery.
- Bars:On-premise trial generates category education and brand loyalty before retail conversion. New York mixology-forward venues function as unpaid marketing infrastructure.
Supermarkets command volume leadership; online retail climbs the fastest.
Brand Positioning:
Positioning tier shapes ingredient sourcing standards and regulatory compliance burden, with premium tiers absorbing full supply chain verification costs.
- Premium:Rare botanical extracts and proprietary distillation methods justify elevated price points. EFSA novel ingredient scrutiny concentrates compliance investment here.
- Mid-Range:Balanced quality-accessibility positioning targets mainstream adoption in metropolitan markets. Los Angeles and New York retail buyers prioritize this tier for portfolio breadth.
- Value:Compounded formulations with established ingredient dossiers minimize regulatory friction. Supermarket channel concentration demands aggressive unit economics.
- Craft:Small-batch production and regional botanical sourcing appeal to authenticity-seeking Millennials. Limited distribution scale requires direct-to-trade sampling investment.
Premium commands margin leadership; craft gains share fastest.
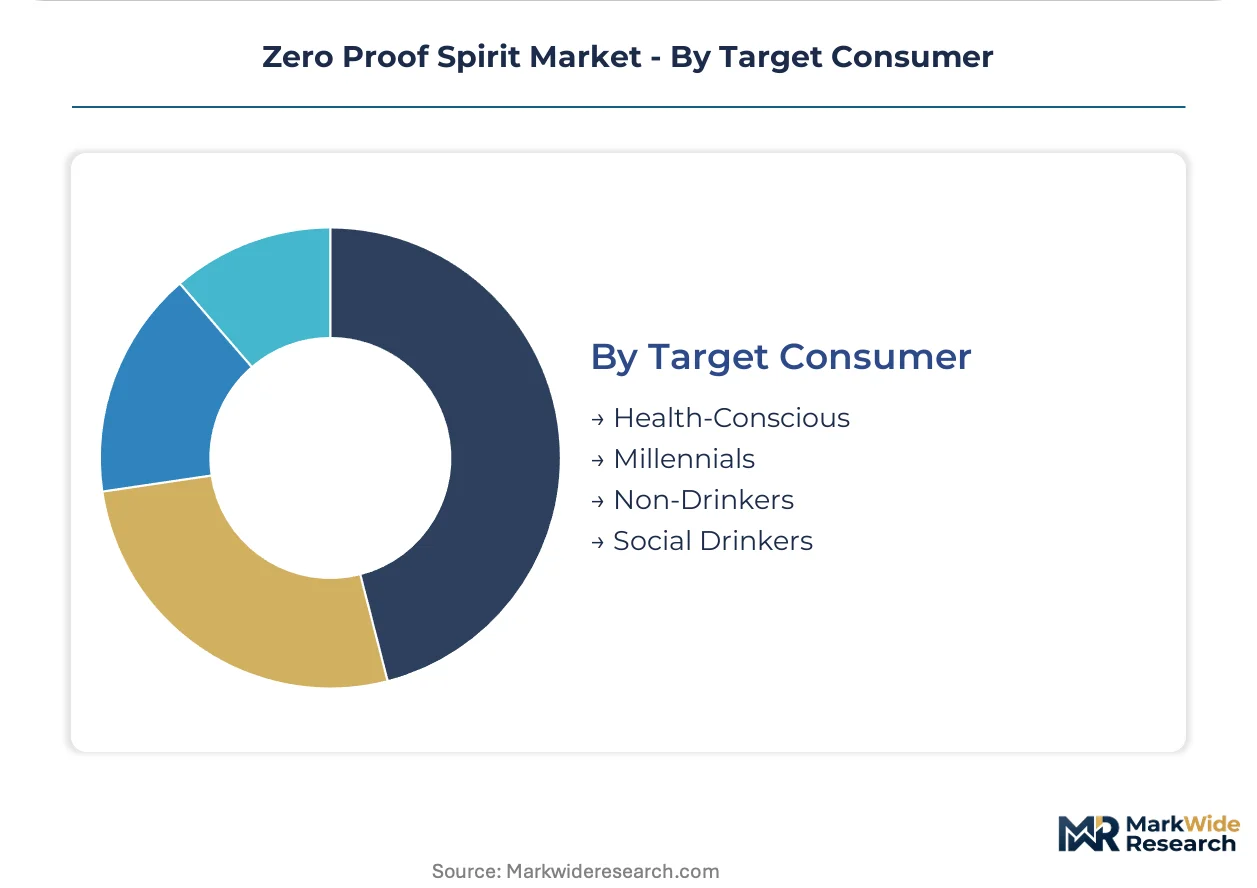
Target Consumer:
Consumer archetype determines messaging strategy and channel mix, with health-motivated buyers accepting higher price elasticity than occasion-driven purchasers.
- Health-Conscious:Functional ingredient claims and clean-label transparency drive purchase decisions. Adaptogen integration specifically targets this segment's wellness priorities.
- Millennials:Experience-seeking behavior favors discovery-oriented retail formats and social media-native brands. Chicago and Los Angeles concentration reflects demographic clustering.
- Non-Drinkers:Permanent abstention creates stable recurring demand across all distribution channels. Religious and medical motivations concentrate in specific metropolitan communities.
- Social Drinkers:Situational moderation seeks ritual replication without intoxication consequences. Bars and restaurants capture this behavior through occasion-based trial.
Health-conscious consumers anchor revenue concentration; Millennials show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles anchors trans-Pacific distribution corridors for botanical imports that supply North American formulation facilities. Container throughput volumes directly correlate with raw material availability for premium zero proof distillers.
United States
Los Angeles, New York, and Chicago concentrate metropolitan demand as mixology-forward venues drive trial and category education. The FDA's tightening ingredient disclosure requirements force producers to reformulate with cleaner labels. Los Angeles bars anchor national distribution negotiations for craft-positioned entrants seeking on-premise validation.
United Kingdom
London hospitality groups specialize in non-alcoholic cocktail program development, creating pull-through demand for sophisticated botanical formulations. The EFSA governs novel ingredient approvals that shape formulation choices for adaptogen-heavy products. Premium hotel partnerships in London secure placement before retail saturation across England.
Germany
REACH compliance requirements mandate full supply chain disclosure for botanical ingredients, forcing producers to map extraction sources. The country's national food safety regulator enforces tightening framework conditions for alcohol-adjacent marketing claims. Berlin and Hamburg retail clusters anchor national supermarket distribution negotiations for mid-range brands.
Australia
Sydney and Melbourne metropolitan areas concentrate health-conscious consumer demand for functional ingredient claims and clean-label transparency. The Therapeutic Goods Administration intersects with food standards frameworks for adaptogen classification. On-premise beverage programs in Sydney drive bartender education investments that displace traditional advertising.
Canada
Toronto and Vancouver anchor metropolitan demand concentration as social drinkers seek ritual replication without intoxication consequences. Health Canada and the Pest Management Regulatory Agency jointly oversee botanical ingredient safety assessments. Vancouver's coastal urban markets favor rum alternatives targeting tiki cocktail applications.
Zero Proof Spirit Market Competitive Landscape
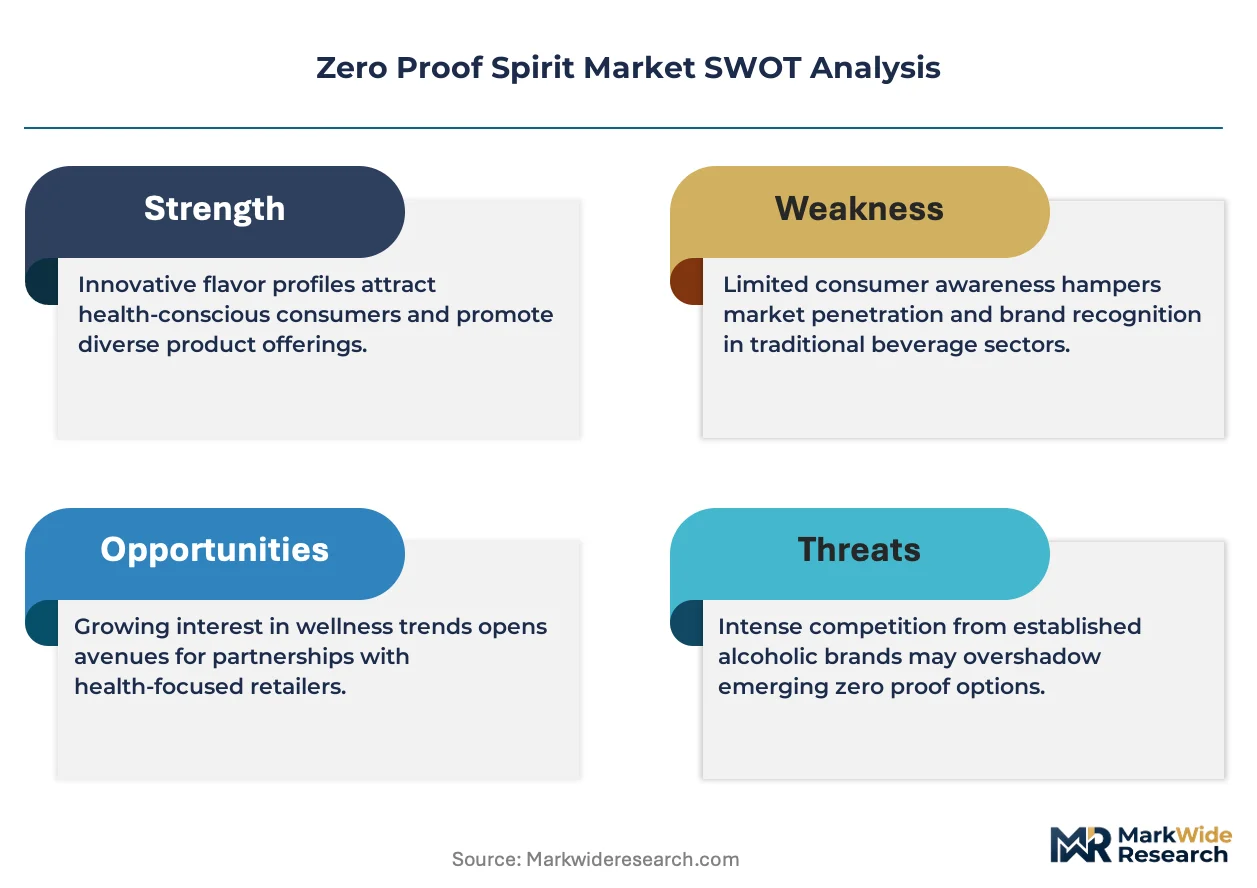
On the supply side, the industry is tiered across premium craft specialists, mid-range scaled producers, and value-positioned compounders. Strategic archetypes include direct-to-trade samplers securing bar placement, broad retail distributors capturing supermarket volume, and hospitality-exclusive partners controlling on-premise channels. Competitive moves concentrate on specialized distribution agreements with premium hotel groups and subscription channel infrastructure expansion.
Among UK-based specialists, Seedlip and Lyre's occupy positions within the premium-tier export vector, while Ritual Zero Proof anchors the North American direct-to-trade sampling archetype. These three exemplify divergent geographic anchoring strategies that shape competitive intensity across Atlantic markets.
| Leading Market Players |
|---|
| Aplós |
| The Pathfinder |
| Ritual Zero Proof |
| CleanCo |
| Empress 1908 |
| Lyre's |
| BARE Zero Proof |
| Three Spirit |
| Seedlip |
| Others |
Value Network & Pricing Analysis
The Port of Los Angeles anchors trans-Pacific distribution corridors for botanical imports, and its container throughput volatility directly compresses margin buffers for premium zero proof distillers dependent on rare extraction sources.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the category, with price differentiation resting on botanical rarity grades and EFSA novel ingredient certification status. Cost compression in the craft tier is intensifying because flavor chemist talent scarcity concentrates formulation expertise among a narrow practitioner pool. Health-conscious consumers in subscription channels show lowest price sensitivity, while value-tier supermarket buyers demand aggressive unit economics.
Supply Chain Analysis
Upstream feedstock for zero proof spirits draws from concentrated botanical growing regions in Madagascar, India, and the Mediterranean basin, with juniper berries, oak extracts, and adaptogenic roots forming critical input dependencies. Single-source vulnerability for rare botanicals creates exposure when climate events disrupt specific harvest zones. Distribution runs through specialized beverage wholesalers and direct-to-trade sampling networks that bypass conventional alcohol distribution infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Zero proof spirits face substitution pressure from functional beverages and premium mixers that replicate cocktail ritual without distillation complexity, forcing incumbents to defend sensory authenticity as a differentiated anchor.
For Market Incumbents: Insulate premium positioning by deepening backward integration into proprietary botanical extraction capabilities and securing captive supply agreements with Madagascar and Indian growing cooperatives. Defend against mid-range compounder encroachment by accelerating EFSA novel ingredient dossier investments that create regulatory moats for adaptogen-heavy formulations. For New Entrants and Emerging Players: Build out white-space presence in gin-style expressions, the fastest-growing product segment where bartender education gaps create penetrable entry points. Target Chicago hospitality venues for on-premise trial generation before retail saturation, leveraging direct-to-trade sampling to secure placement ahead of scaled competitors. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors craft specialists with vacuum distillation capabilities and established botanical supply mapping for REACH compliance. Long-term viability hinges on subscription channel infrastructure ownership and formulation IP that transcends single-product dependency. Watch EFSA novel food approval velocity as an inflection indicator for adaptogen-heavy portfolio valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Bartender Education Program Investment | Los Angeles and New York venues prioritize staff training over menu placement fees, elevating technical support brands. |
| Subscription Channel Infrastructure Buildout | Direct-to-consumer logistics capture recurring revenue pools that physical retail cannot match for health-conscious segments. |
| EFSA Novel Ingredient Dossier Expansion | Regulatory pre-approval compresses first-mover windows for adaptogen-heavy formulations seeking European market access. |
| Botanical Supply Chain Mapping for REACH | Full extraction source disclosure mandates from ECHA force verification investments that premium tiers absorb. |
| Gin-Style Expression Development | Chicago hospitality trial rates for juniper-forward builds outpace whiskey alternatives, signaling segment momentum. |
Research Methodology
Initial hypotheses were tested against primary input from brand managers at zero proof distillers, category buyers at premium supermarket chains, head bartenders at mixology-forward venues, and regulatory affairs specialists navigating FDA and EFSA frameworks, and refined through secondary validation against customs records for botanical imports, FDA ingredient disclosure filings, EFSA novel food approval databases, and Nielsen retail audit data for non-alcoholic beverage segments, with bottom-up volume triangulation against top-down category spend estimates.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, modeling volume and value outputs through segmentation dimensions spanning product type, distribution channel, brand positioning tier, and target consumer archetype. CAGRs were derived from iterative convergence of adoption curve modeling and pricing elasticity estimates, with bartender education penetration rates and subscription channel growth curves serving as category-specific forecast inputs.
Practitioners should monitor EFSA novel ingredient approval backlogs, FDA labeling framework tightening, and botanical harvest disruptions for early signals that assumptions require revision. Cross-checking against customs throughput data at the Port of Los Angeles and premium hospitality menu placement tracking is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Europe Energy Drink Market
Non-Alcoholic Beverages
Non-Alcoholic Beer Market
Non-Alcoholic Beverages
Coffee Substitute Market
Non-Alcoholic Beverages
Non-Alcoholic Malt Beverages Market
Non-Alcoholic Beverages
United States Energy Drink Market
Non-Alcoholic Beverages
Soy Beverage Market
Non-Alcoholic Beverages
North America Soy Beverages Market
Non-Alcoholic Beverages
Global RTD Tea Drinks Market
Non-Alcoholic Beverages
United Arab Emirates Bottled Water Market
Non-Alcoholic Beverages
Probiotic Soda Market
Non-Alcoholic Beverages
North America Bottled Water Market
Non-Alcoholic Beverages
Japan Soy Beverages Market
Non-Alcoholic Beverages
Global Non-Alcoholic RTD Beverages Market
Non-Alcoholic Beverages
Flavored Water Market
Non-Alcoholic Beverages
Hydrogen Water Machine Market
Non-Alcoholic Beverages
Hypertonic Drinks Market