
 Africa Energy Drinks Market | 2026-2036
Africa Energy Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Energy Drinks Market Outlook
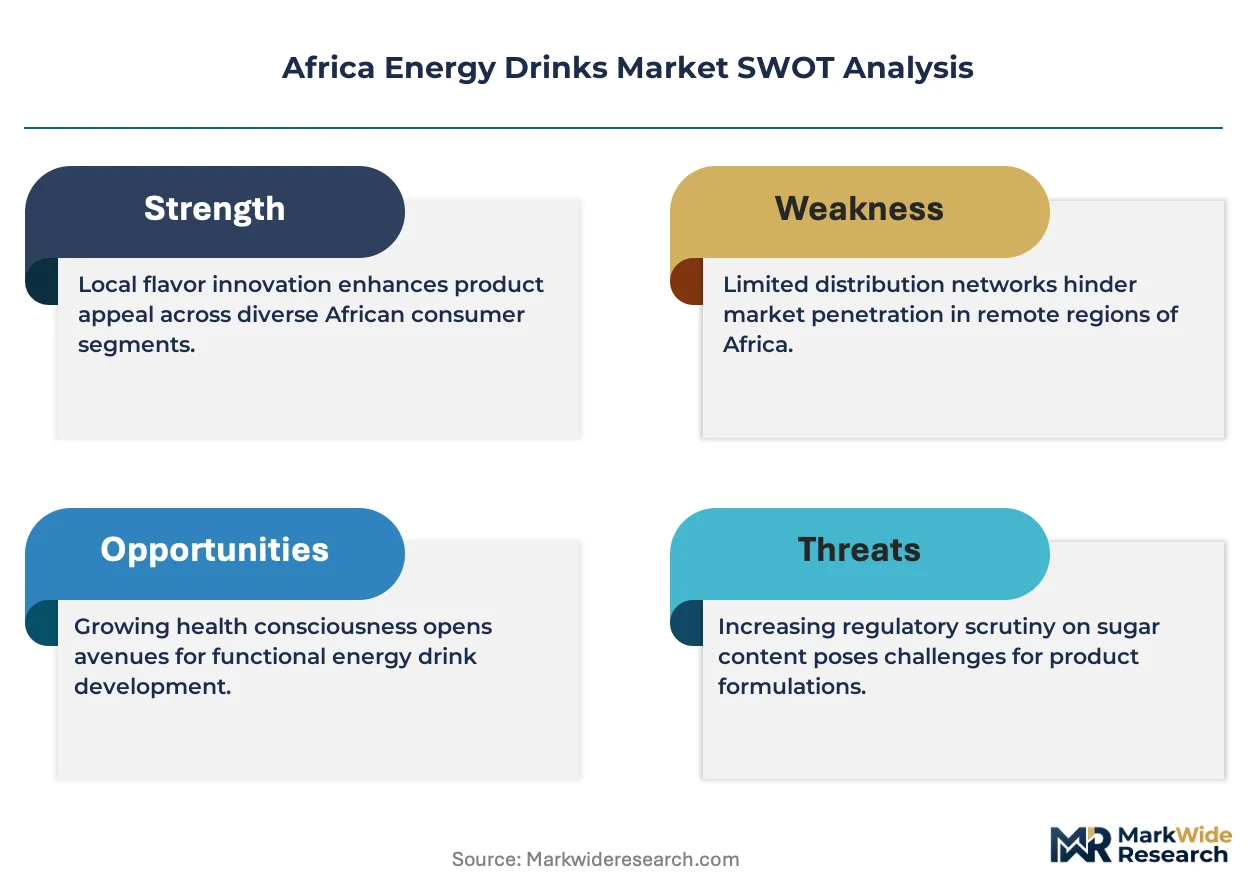
Asset-light distributor financing is fragmenting competitive access across informal retail channels in African cities. Red Bull GmbH leverages its global brand architecture to sustain premium positioning in upscale urban venues. Tiger Brands Ltd. anchors its portfolio through deep supermarket and convenience store penetration in South Africa. Mofaya Beverage Company navigates township economies with localized flavor profiles and aggressive price positioning.
Africa energy drinks are formulated beverages containing caffeine, taurine, B-vitamins, and herbal extracts, typically carbonated and packaged in aluminum cans or PET bottles for rapid consumption. These products deliver stimulant effects targeting mental alertness and physical endurance in commercial and recreational settings. The functional segment dominates volume as fitness enthusiasts and professionals seek performance-linked claims, while natural formulations gain traction among health-conscious students wary of synthetic additives. Cans remain the preferred packaging format due to portability, chill retention, and established recycling infrastructure in major African cities.
South Africa's national treasury enforces sugar-sweetened beverage taxes that compel reformulation toward low-calorie variants, while Nigeria's National Agency for Food and Drug Administration and Control monitors caffeine content labeling and health claims. Kenya's Bureau of Standards sets packaging and hygiene benchmarks that filter informal imports from unregistered suppliers. Stakeholders must track evolving excise structures and local certification requirements to secure shelf space in fragmented retail environments.
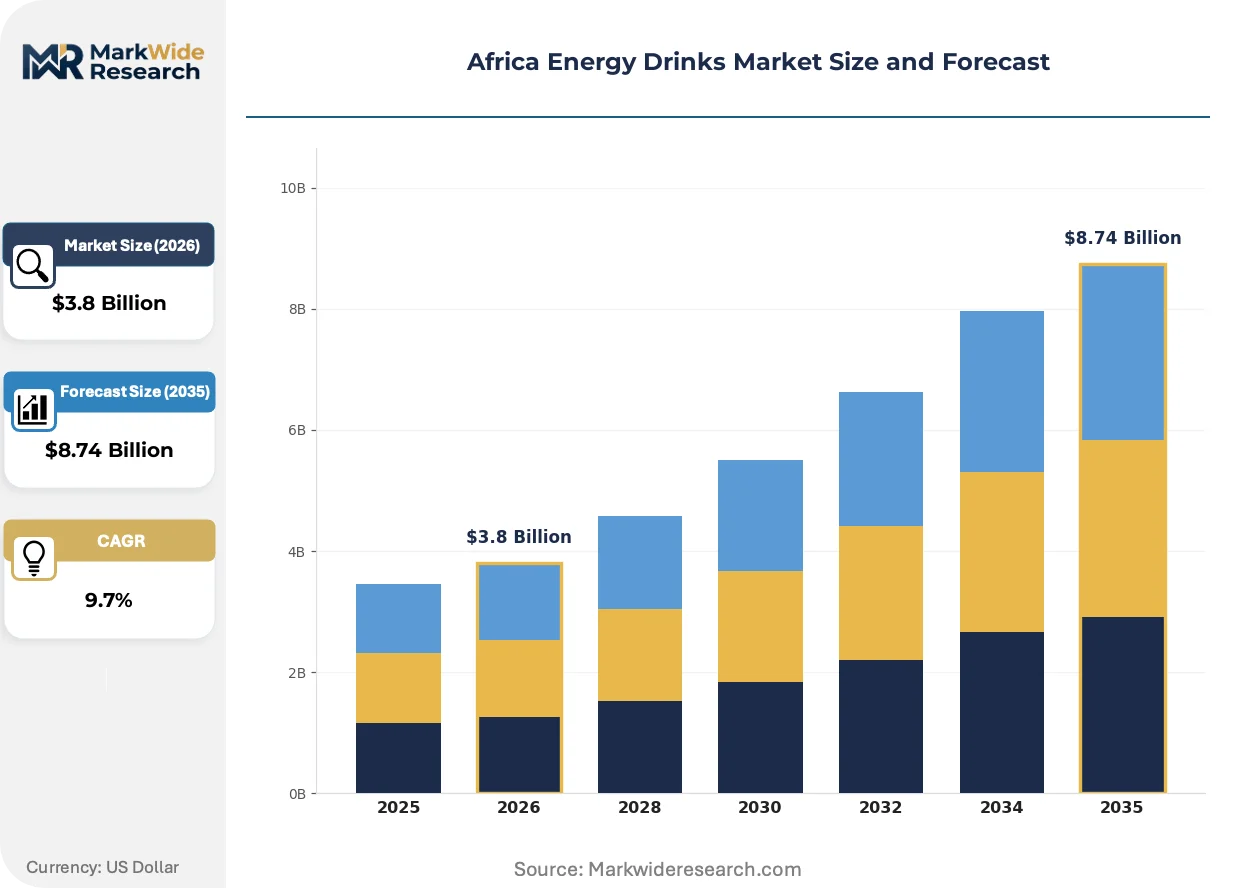
Market Dynamics
Sugar taxation policies across South Africa and Nigeria are forcing rapid reformulation toward low-calorie variants, while asset-light distributor financing fragments competitive access through informal retail channels in Lagos, Nairobi, and Johannesburg.
Growth Catalysts
- Health and Wellness Taxation:South Africa's sugar-sweetened beverage tax compels manufacturers to develop reduced-calorie portfolios that attract health-conscious professionals in urban centers.
- Township Economy Penetration:Aggressive price positioning through localized flavor profiles captures volume in South Africa's informal retail networks where traditional supermarket coverage remains thin.
- Functional Fitness Demand:Performance-linked claims targeting gym enthusiasts and amateur athletes drive premium positioning in Kenya's expanding fitness club sector.
Market Restraints
- Caffeine Content Caps:Nigeria's National Agency for Food and Drug Administration and Control enforces strict labeling requirements that limit formulation flexibility and marketing claims.
- Aluminum Input Volatility:Global aluminum price fluctuations squeeze margins for can-dependent producers across West Africa's manufacturing base.
- Import Dependency:Concentrated supply of taurine and synthetic caffeine from Asian chemical manufacturers exposes formulators to currency and shipping cost shocks.
Strategic Opportunities
- Natural Extract Formulations:Regulatory tailwinds from Kenya's Bureau of Standards hygiene benchmarks favor clean-label entrants displacing unregistered informal imports.
- Convenience Store Expansion:Deep penetration into South Africa's forecourt retail network captures impulse consumption during commuter fuel stops.
- Student Segment Targeting:Examination-period consumption patterns in Nigerian tertiary institutions present seasonal volume spikes for sustained-release caffeine variants.
Industry Challenges
- Refrigeration Infrastructure Gaps:Cold chain deficiencies in Ghana's urban corridor limit shelf-life extension for preservative-free natural formulations.
- Certification Timeline Compression:Kenya's Bureau of Standards approval windows delay product launches, allowing faster-registered competitors to capture first-mover positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Energy Drinks Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Alcoholic, Functional, Natural, Carbonated Packaging Type: Cans, Bottles, Pouches, Tetra Packs Distribution Channel: Supermarkets, Convenience Stores, Online, Health Stores End User: Fitness Enthusiasts, Students, Professionals, Athletes |
| Companies Covered | Monster Beverage Corporation, Tiger Brands Ltd., Red Bull GmbH, Halewood International South Africa (Pty) Ltd, Aje Group, The Coca-Cola Company, Suntory Holdings Limited, Mofaya Beverage Company (PTY) Ltd, PepsiCo, Inc., Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Energy Drinks Market Strategic Shifts
Reformulation science and distribution technology are compressing traditional competitive moats, enabling new entrants to challenge established shelf positions through speed-to-market and localized positioning.
Natural caffeine extraction from green coffee beans and yerba mate is collapsing the cost premium between synthetic and plant-based stimulant sourcing. Mid-tier formulators in Nigeria and Ghana are adopting these processes to bypass import duties on purified caffeine. The technology is collapsing price differentiation between premium natural positioning and standard functional claims.
South Africa's national treasury escalates sugar-sweetened beverage tax enforcement annually, compelling manufacturers to accelerate aspartame and stevia adoption timelines. Industrial consequence includes accelerated R&D spend on taste-masking technologies. The reduced-calorie segment responds fastest, with Johannesburg-based producers leading portfolio transitions ahead of Lagos competitors.
Young professionals in Kenya's Nairobi corridor compress consumption occasions from traditional nightlife-only toward morning commute and midday workplace consumption. Forecourt retailers and office-building vending machines displace supermarket bulk purchasing as the dominant channel. This pattern is most visible in Nairobi's Westlands business district, where 24-hour service stations capture repeat daily purchases.
Africa Energy Drinks Market Segmentation
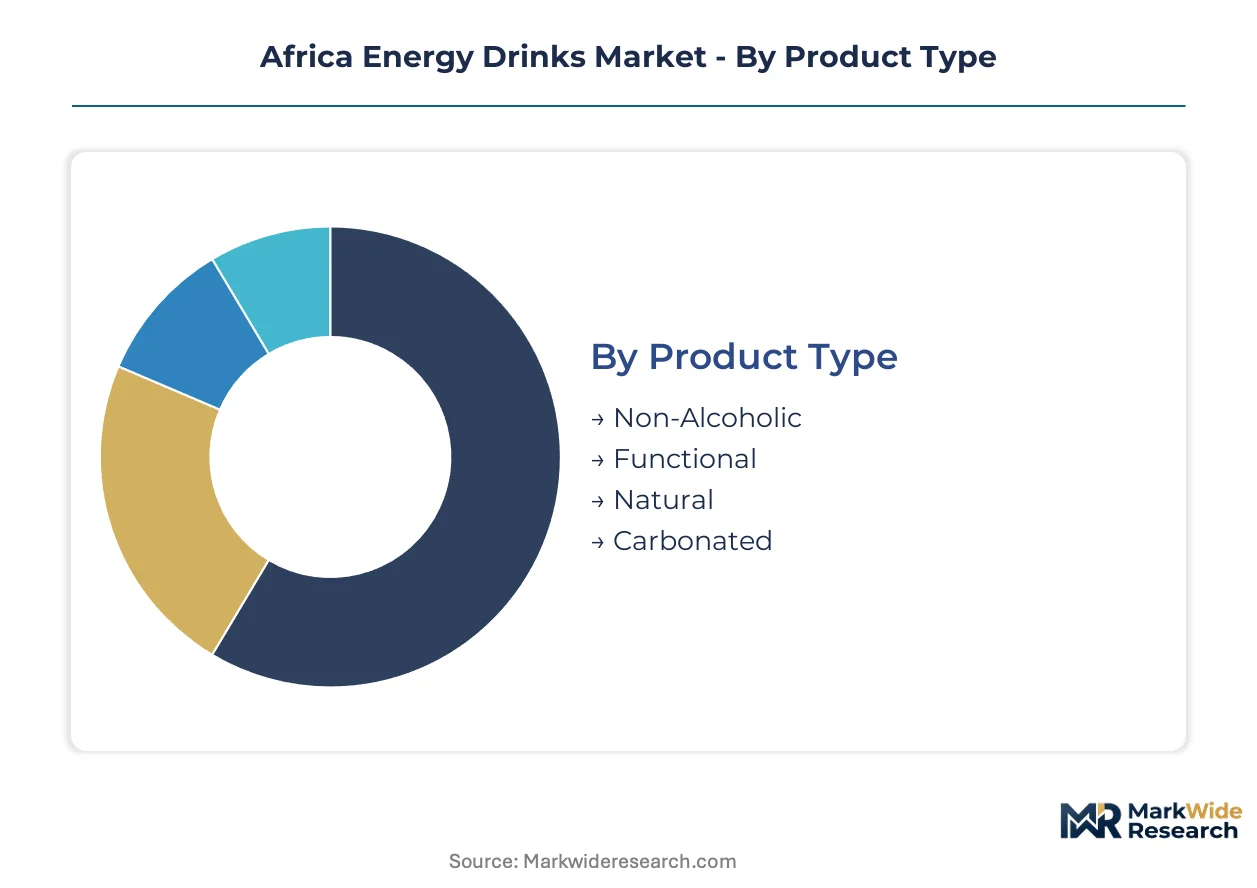
Segmentation in the Africa Energy Drinks Market reveals how consumption patterns split across functional needs, retail access, and lifestyle demographics. Manufacturers calibrate formulation, packaging, and channel strategy to capture value from Lagos professionals, Nairobi gym-goers, and Johannesburg township consumers.
Product Type:
Use-case spectrum spans recreational refreshment through performance optimization, with each formulation tier commanding distinct price positions and regulatory scrutiny.
- Functional:Caffeine-taurine-B-vitamin matrices dominate volume through gym partnerships and workplace vending in Johannesburg and Nairobi. South Africa's sugar-sweetened beverage tax accelerates reformulation toward low-calorie functional variants targeting health-conscious professionals.
- Natural:Green coffee bean and yerba mate extracts gain share among Kenyan students wary of synthetic additives. Kenya's Bureau of Standards hygiene benchmarks favor clean-label entrants displacing unregistered informal imports.
- Non-Alcoholic:Standard caffeinated formulations anchor mass-market penetration through Lagos and Accra informal retail networks.
- Carbonated:Fizz-dependent taste profiles retain loyalty in South Africa's supermarket channel despite refrigeration infrastructure gaps elsewhere.
Established volume favors Functional; emerging adoption favors Natural.
Packaging Type:
Cost tier alignment determines margin capture, with premium chill-retention formats commanding forecourt pricing power and economy formats penetrating cash-constrained township shelves.
- Cans:Aluminum containers dominate through portability, rapid chill-down, and established recycling infrastructure in major African cities. Global aluminum price volatility squeezes margins for West African can-dependent producers.
- Bottles:PET formats serve multipurpose consumption occasions in Nigerian tertiary institutions where examination-period demand spikes.
- Pouches:Flexible sachets capture ultra-price-sensitive volume in Ghana's urban corridor where refrigeration gaps limit shelf-life for preservative-free formulations.
- Tetra Packs:Aseptic cartons remain niche, constrained by limited ambient distribution infrastructure outside South Africa's formal retail network.
Margin concentration sits with Cans; volume expansion favors Pouches.
Distribution Channel:
Customer type proximity dictates channel priority, with impulse occasions migrating from planned supermarket trips toward embedded convenience and digital access.
- Convenience Stores:Forecourt retailers in Nairobi's Westlands business district capture repeat daily purchases from commuting professionals. 24-hour service stations displace supermarket bulk purchasing as the dominant channel.
- Supermarkets:Tiger Brands anchors deep penetration through South Africa's formal retail network, though township coverage remains thin.
- Online:Digital ordering gains traction among Lagos young professionals through delivery platforms, constrained by last-mile cold chain reliability.
- Health Stores:Specialty retailers in Johannesburg and Nairobi curate natural and reduced-calorie portfolios for fitness enthusiasts.
Channel maturity favors Supermarkets; growth velocity favors Convenience Stores.
End User:
Application intensity varies by professional schedule, academic calendar, and training regimen, shaping seasonal demand patterns and messaging strategy.
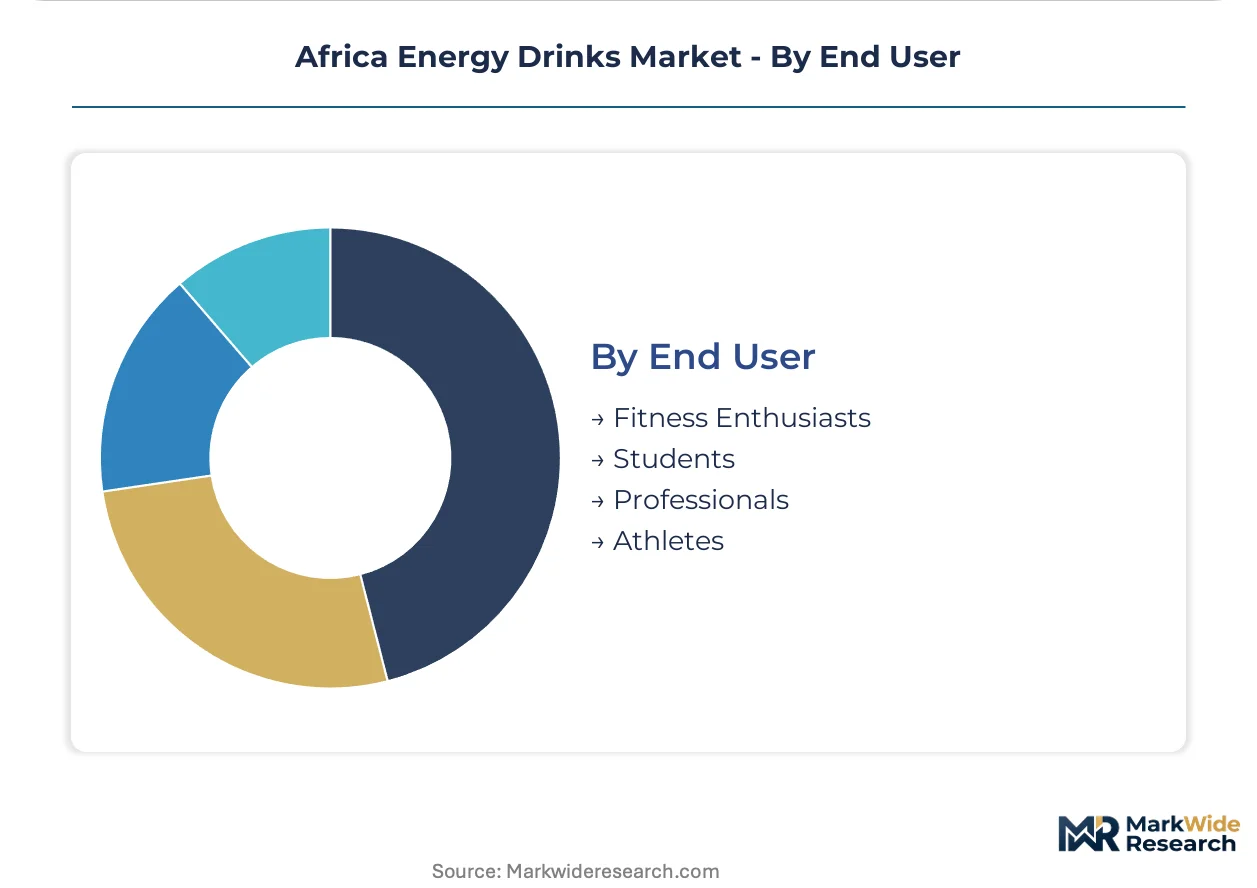
- Professionals:Long work hours and nightlife culture in Lagos, Nairobi, and Johannesburg drive adoption through sustained-release caffeine variants. Morning commute and midday workplace consumption compress traditional occasion boundaries.
- Fitness Enthusiasts:Performance-linked claims target Kenya's expanding fitness club sector, with premium positioning tied to amateur athlete communities.
- Students:Examination-period consumption patterns in Nigerian tertiary institutions present seasonal volume spikes. Price sensitivity favors aggressive positioning through localized flavor profiles.
- Athletes:Elite competitor segment remains niche, constrained by caffeine content caps enforced by Nigeria's National Agency for Food and Drug Administration and Control.
Volume depth sits with Professionals; segment momentum favors Fitness Enthusiasts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for taurine and synthetic caffeine concentrates supply risk in West African manufacturing, while South Africa's sugar taxation regime accelerates reformulation investment across the continent. Export-oriented producers in Nigeria and Ghana face margin compression from currency volatility against Asian chemical suppliers. Regional integration remains weak, with national regulatory fragmentation shaping localized competitive positioning.
South Africa
Long work hours and nightlife culture in Johannesburg drive sustained consumption among young professionals, with morning commute occasions expanding beyond traditional evening use. The national treasury escalates sugar-sweetened beverage tax enforcement annually, compelling rapid aspartame and stevia adoption in reduced-calorie portfolios. Township economies around Soweto and Alexandra capture volume through aggressive price positioning where supermarket coverage remains thin.
Nigeria
Examination-period consumption patterns in Lagos tertiary institutions generate seasonal volume spikes for sustained-release caffeine variants targeting students. The National Agency for Food and Drug Administration and Control enforces strict caffeine content labeling requirements that limit formulation flexibility and marketing claims. The urban corridor stretching from Lagos to Accra concentrates demand through informal retail networks with asset-light distributor financing.
Kenya
Fitness enthusiasts in Nairobi's expanding gym sector drive premium positioning for performance-linked functional claims among amateur athletes. The Bureau of Standards sets packaging and hygiene benchmarks that filter unregistered informal imports, favoring clean-label entrants with natural extract formulations. Westlands business district forecourt retailers capture repeat daily purchases from commuting professionals through 24-hour service station networks.
Ghana
Ultra-price-sensitive consumption in Accra's urban corridor favors flexible pouch packaging where refrigeration infrastructure gaps limit shelf-life for preservative-free natural formulations. The country's food and drug administration monitors import flows of unregistered energy drink brands from neighboring markets. Aluminum can recycling infrastructure remains underdeveloped compared to Lagos or Johannesburg, constraining premium format penetration.
Africa Energy Drinks Market Competitive Environment
On the supply side, the industry is bifurcated between global brand architecture players and localized township economy specialists. Tiered competitive positioning separates premium venue anchoring from mass-market price penetration. Three strategic archetypes dominate: multinational beverage conglomerates leveraging global distribution, regional African champions with deep supermarket penetration, and insurgent local formulators capturing informal retail through flavor localization. Capacity expansion and portfolio diversification constitute the dominant competitive moves, with reformulation science accelerating R&D spend timelines.
Among global beverage conglomerates, Red Bull GmbH and The Coca-Cola Company occupy positions defined by brand architecture and distribution scale rather than manufacturing origin. Tiger Brands Ltd. anchors the regional champion archetype through South African supermarket and convenience store penetration. Mofaya Beverage Company exemplifies the insurgent local specialist, navigating township economies through aggressive price positioning and localized flavor profiles that capture cash-constrained consumers outside formal retail coverage.
| Leading Market Players |
|---|
| Monster Beverage Corporation |
| Tiger Brands Ltd. |
| Red Bull GmbH |
| Halewood International South Africa (Pty) Ltd |
| Aje Group |
| The Coca-Cola Company |
| Suntory Holdings Limited |
| Mofaya Beverage Company (PTY) Ltd |
| PepsiCo, Inc. |
| Others |
Value Chain & Pricing Dynamics
The Lagos-Apapa port corridor's freight cost volatility feeds directly into West African manufacturer margins and downstream price stratification between premium can formats and economy pouch alternatives. Sugar taxation enforcement across South Africa and Nigeria compresses formulation cost structures while aluminum input volatility from Asian smelters forces packaging-tier price differentiation.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in Africa's energy drinks market. Price differentiation rests on brand architecture strength and distribution channel depth, with forecourt retailers commanding premium chill-retention markups over informal township shelf pricing. Cost compression in the economy tier intensifies because of aggressive localization by insurgent formulators. Students in Nigerian tertiary institutions exhibit highest price sensitivity, while young professionals in Johannesburg's Westlands district demonstrate lowest elasticity for sustained-release functional variants.
Supply Chain Analysis
Tariff exposure between China and Nigeria dominates supply chain risk for taurine and synthetic caffeine imports that feed West African manufacturing. Geographic supply concentration centers on China, India, and Vietnam for stimulant precursors and flavor compounds. Raw material dependencies hinge on aluminum sheet from Gulf smelters, PET resin from Saudi petrochemical complexes, and natural extract supply from Kenyan agricultural cooperatives. Single-source vulnerability in purified caffeine shipments through the Suez Canal constrains just-in-time formulation. Distribution runs through asset-light distributor networks that fragment competitive access across Lagos, Nairobi, and Johannesburg informal retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sugar taxation policy acceleration across South Africa and Nigeria is reshaping competitive positioning through forced reformulation investment timelines that favor capitalized incumbents with R&D scale.
For Market Incumbents: Harden formulation IP portfolios against natural extract substitution threats from Kenyan clean-label entrants. Accelerate stevia and aspartame taste-masking R&D ahead of Lagos competitors. Deepen backward integration into aluminum can manufacturing through Gulf joint ventures to offset commodity price volatility squeezing West African margins. For New Entrants and Emerging Players: Establish a beachhead in Ghana's pouch-format urban corridor where refrigeration infrastructure gaps limit incumbent natural formulation shelf-life. Target Accra's ultra-price-sensitive student segment through flexible sachet packaging and localized flavor profiles. Deploy asset-light distributor financing to penetrate informal retail networks faster than Kenya's Bureau of Standards certification timelines allow established competitors. For Investors and Strategic Acquirers: Township economy specialists with deep Soweto and Alexandra penetration represent the most defensible acquisition archetype against multinational brand architecture competition. Long-term viability in this market hinges on regulatory compliance speed and reformulation agility rather than manufacturing scale alone. Watch for Kenya's Bureau of Standards hygiene benchmark enforcement intensity as the signal indicating clean-label entrant displacement acceleration of unregistered informal imports.| Strategic Initiative | Industry Significance |
|---|---|
| Natural Extract Formulation Transition | Green coffee bean and yerba mate sourcing bypasses Nigeria's caffeine import duties while capturing health-conscious Kenyan students. |
| Forecourt Retail Network Expansion | 24-hour Nairobi service stations capture repeat daily purchases from commuting professionals displacing supermarket bulk buying. |
| Reduced-Calorie Portfolio Acceleration | Aspartame and stevia adoption ahead of South Africa's annual sugar tax escalation defends shelf position against reformulation-lagged competitors. |
| Asset-Light Distributor Financing | Fragmented informal retail access in Lagos and Accra enables rapid volume capture without fixed infrastructure investment. |
| Localized Flavor Profile Development | Township-specific taste preferences in Soweto and Alexandra build consumer loyalty resistant to multinational brand architecture. |
Study Parameters
Operator-level perspectives from brand managers, category buyers at forecourt retailers, beverage formulators, and distribution channel partners anchored the qualitative base for this study. Primary interviews with South Africa's sugar tax compliance officers and Nigeria's National Agency for Food and Drug Administration and Control labeling specialists combined with secondary validation from customs records, Nielsen retail audit data, and Bureau of Standards hygiene benchmark filings. Bottom-up volume triangulation across packaging formats and top-down value reconciliation against excise tax receipts produced convergent market estimates.
Scenario-bracketing around regulatory enforcement intensity and aluminum price volatility bands structured the analytical framework across the analysis window. Segmentation dimensions modeled include product type tier, packaging format, distribution channel depth, and end-user professional schedule intensity. CAGRs derived from trend extrapolation of consumption occasion compression patterns in Nairobi and Lagos, cross-referenced with gym sector expansion rates in Kenya and student enrollment cycles in Nigerian tertiary institutions.
Sensitivities concentrate around sugar taxation policy acceleration timelines in South Africa and Nigeria, Kenya's Bureau of Standards certification approval windows, and Suez Canal shipping disruption frequency affecting taurine and caffeine precursor supply. Forecasts reflect documented assumptions regarding urban professional work-hour extension trends and fitness club penetration rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Africa Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
Carbonated Ready-To-Drink Tea Market
Non-Alcoholic Beverages
Sugar Free Carbonated Drinks Market
Non-Alcoholic Beverages
United Arab Emirates Bottled Water Market
Non-Alcoholic Beverages
Fruit-Infused Water Market
Non-Alcoholic Beverages
Hydrogen Water Machine Market
Non-Alcoholic Beverages
Soy Beverage Market
Non-Alcoholic Beverages
Hypertonic Drinks Market
Non-Alcoholic Beverages
Water Vending Machine Market
Non-Alcoholic Beverages
Bubble Tea Market
Non-Alcoholic Beverages
Coffee Substitute Market
Non-Alcoholic Beverages
Flavored Water Market
Non-Alcoholic Beverages
Gulf Cooperation Council (GCC) Bottled Water Market
Non-Alcoholic Beverages
Diet Soda Market
Non-Alcoholic Beverages
North America Bottled Water Processing Market
Non-Alcoholic Beverages
China Non-Alcoholic Beverages Market