
 Europe Sports and Energy Drinks Market | 2026-2036
Europe Sports and Energy Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Sports and Energy Drinks Market Intelligence
The capital-intensity divergence between bottling infrastructure and digital-native marketing is reorganizing competitive hierarchies across the European functional beverage landscape. Red Bull GmbH leverages its event-sponsorship ecosystem and proprietary distribution to sustain premium positioning in convenience channels. Lucozade Ribena Suntory Limited anchors British mass-market penetration through pharmacy and grocery networks. PepsiCo competes via multi-brand portfolio scale, extending manufacturing flexibility across energy and sports variants.
Europe sports and energy drinks comprise isotonic, hypotonic, and stimulant-based formulations containing electrolytes, carbohydrates, caffeine, taurine, and B-vitamins, manufactured through aseptic cold-fill or hot-fill processes with pH stabilization below 4.5 for shelf stability; their primary purpose is rapid hydration, glycogen replenishment, and cognitive alertness during or after physical exertion. Sports drinks occupy the largest volume share among product types due to established athletic consumption rituals, while functional beverages represent the fastest-growing margin pool as adaptogens and nootropics enter European formulations. Online retail channels are accelerating fastest among distribution channels, though supermarkets retain dominant shelf-space control and promotional leverage.
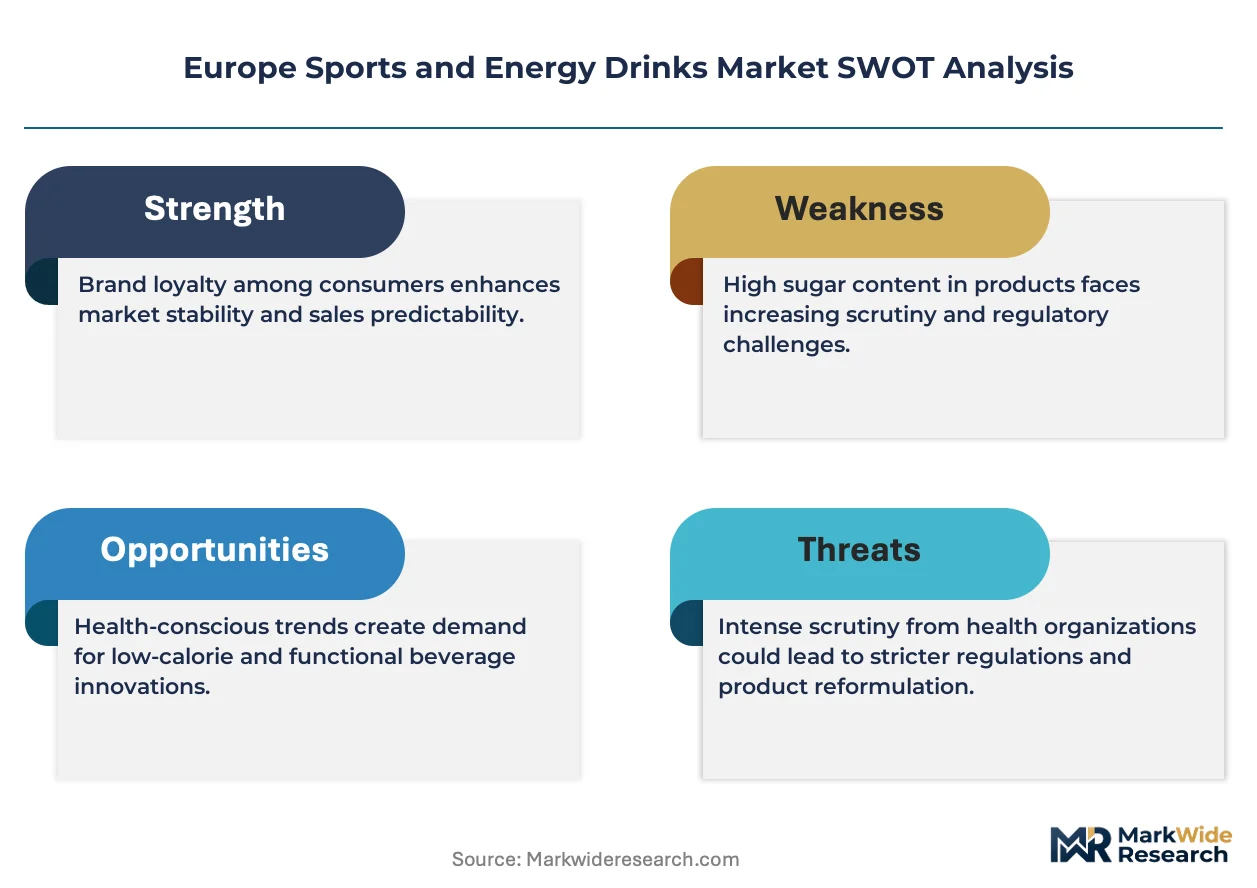
EFSA caffeine exposure thresholds, EU F-Gas Regulation impacts on cold-chain logistics, and national sugar taxes in the United Kingdom, France, and Ireland collectively constrain formulation freedom and compress price elasticity for mid-tier products. The EU Green Deal packaging directives are forcing recyclability redesigns across PET and aluminum supply chains. Stakeholders must monitor pending EU-wide harmonization of front-of-pack nutritional labeling, as this will determine which formulations retain retail access versus reformulation costs.
Market Dynamics
Gym culture penetration across European urban centers is compressing consumption occasions from dedicated athletic use toward everyday functional hydration, forcing reformulation trade-offs between performance efficacy and lifestyle palatability.
Growth Catalysts
- EFSA Caffeine Guidance Evolution:The European Food Safety Authority's tightening health-claim substantiation requirements are accelerating clean-label innovation among manufacturers seeking differentiated positioning.
- Fitness Enthusiast Segment Expansion:Boutique studio proliferation and CrossFit affiliate density in metropolitan clusters are creating habitual pre-workout consumption rituals that extend beyond traditional sports contexts.
- Adaptogen Integration:Ashwagandha and rhodiola extraction technologies are enabling nootropic-adjacent formulations that capture cognitive-performance demand from knowledge-worker demographics.
Market Restraints
- EU F-Gas Regulation Cold-Chain Compression:Refrigerated transport and retail cooling infrastructure face phase-down schedules for hydrofluorocarbon refrigerants, elevating distribution costs for temperature-sensitive functional beverages.
- National Sugar Tax Stacking:United Kingdom, French, and Irish excise duties on sugar-sweetened beverages constrain price elasticity and force margin compression on mid-tier SKUs unable to absorb reformulation costs.
- Aluminum and PET Supply Concentration:Packaging material sourcing dependencies on limited European converter capacity create input cost volatility and recyclability compliance timeline risks.
Strategic Opportunities
- Eastern European Underpenetration:Poland, Romania, and Czech Republic retail channels show sports-nutrition category development gaps relative to Western European per-capita consumption baselines.
- EU Green Deal Packaging Directives:Mandatory recyclability targets and extended producer responsibility frameworks create first-mover advantage for brands investing in rPET and aluminum-loop infrastructure.
- Direct-to-Consumer Subscription Models:E-commerce platform specialization in personalized nutrition stacks enables bypass of supermarket shelf-space gatekeeping and promotional fund requirements.
Industry Challenges
- Front-of-Pack Labeling Harmonization Uncertainty:Pending EU-wide Nutri-Score or equivalent mandatory disclosure systems require preemptive reformulation investment without finalized technical specifications.
- Aseptic Cold-Fill Technical Talent Scarcity:Specialized process engineering expertise for pH-stabilized, preservative-free manufacturing lines commands premium compensation and limited geographic availability.
- Legacy Pharmacy Channel Integration Friction:Sports-nutrition brands seeking credibility through Boots, DM, or Apotheke distribution face conflicting margin structures and category management protocols versus convenience retail.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Sports and Energy Drinks Market |
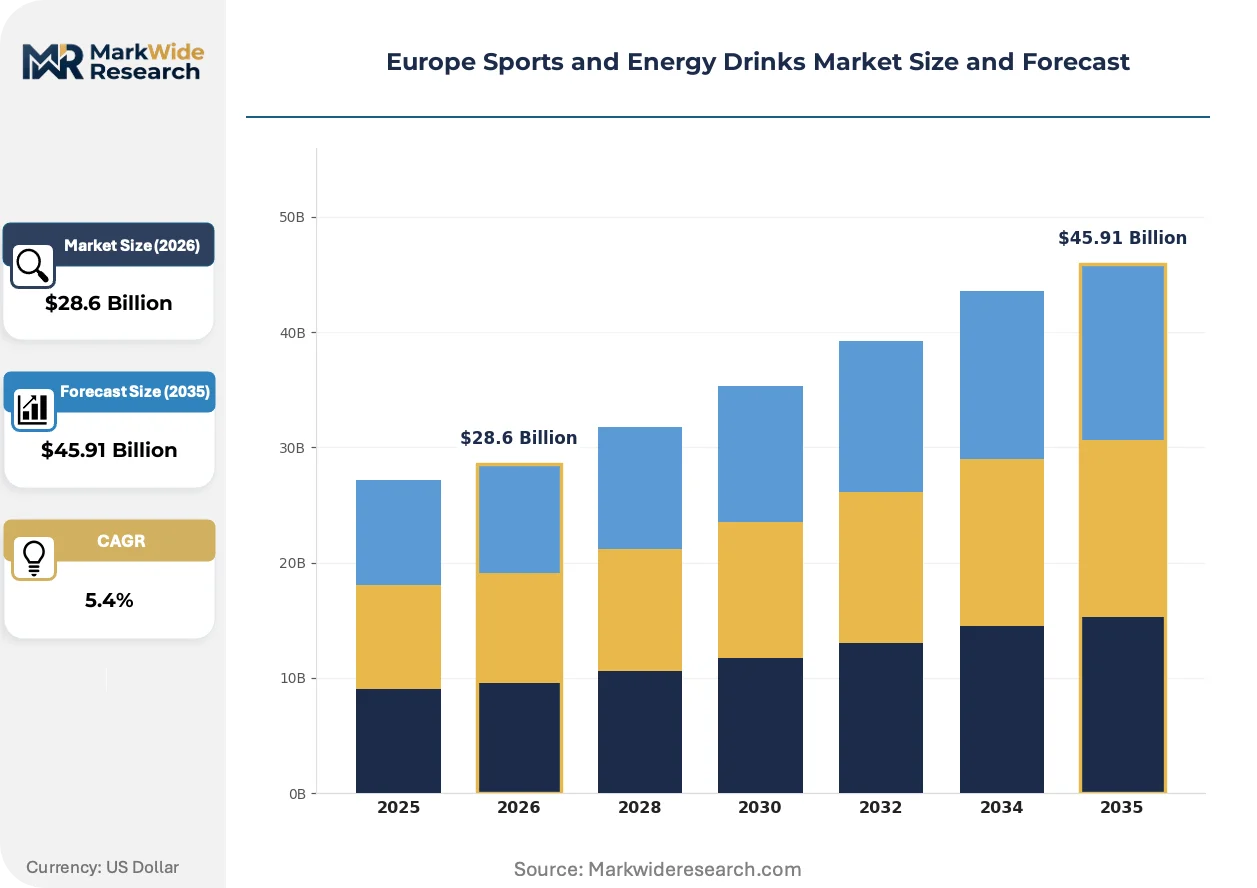
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $45.91 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sports Drinks, Energy Boosters, Protein Shakes, Functional Beverages End User: Athletes, Fitness Enthusiasts, Casual Consumers, Professionals Distribution Channel: Supermarkets, Online Retail, Health Stores, Convenience Stores Packaging Type: Bottles, Cans, Tetra Packs, Pouches |
| Companies Covered | Monster Beverage Corporation, Lucozade Ribena Suntory Limited, Red Bull GmbH, Hell Energy, Vitamin Well AB, PepsiCo, Suntory Holdings Limited, BA Sports Nutrition, The Coca-Cola Company, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Sports and Energy Drinks Market Strategic Shifts & Innovations
Formulation science and distribution architecture are converging to redefine how functional beverages reach European consumers, with technology miniaturization and regulatory pressure acting as twin accelerants of competitive divergence.
Electrolyte microencapsulation technology is miniaturizing. This process enables sustained-release sodium and potassium delivery without texture degradation in reduced-sugar matrices. Premium sports-nutrition brands in Germany and the Netherlands are adopting it for endurance-focused SKUs. The technology is miniaturizing serving-size requirements while maintaining efficacy claims, compressing packaging material costs and transport emissions per functional dose.
REACH chemical restriction expansions are tightening taurine and synthetic caffeine sourcing protocols. Industrial consequence includes accelerated botanical-caffeine substitution from green tea and yerba mate extracts. Pre-workout and energy-shot segments face the steepest compliance cost curves, with German and Nordic markets showing fastest clean-caffeine transition rates due to consumer sentiment alignment.
Urban convenience-channel fragmentation is reshaping impulse-purchase capture. Traditional petrol-station and newsagent dominance is yielding to dark-store rapid-delivery apps and gym-proximate micro-fulfillment. London, Paris, and Berlin exhibit the most pronounced channel-shift velocity, with fitness-studio vending machine retrofitting emerging as a contested real-estate category between rival beverage portfolios.
Europe Sports and Energy Drinks Market Segmentation
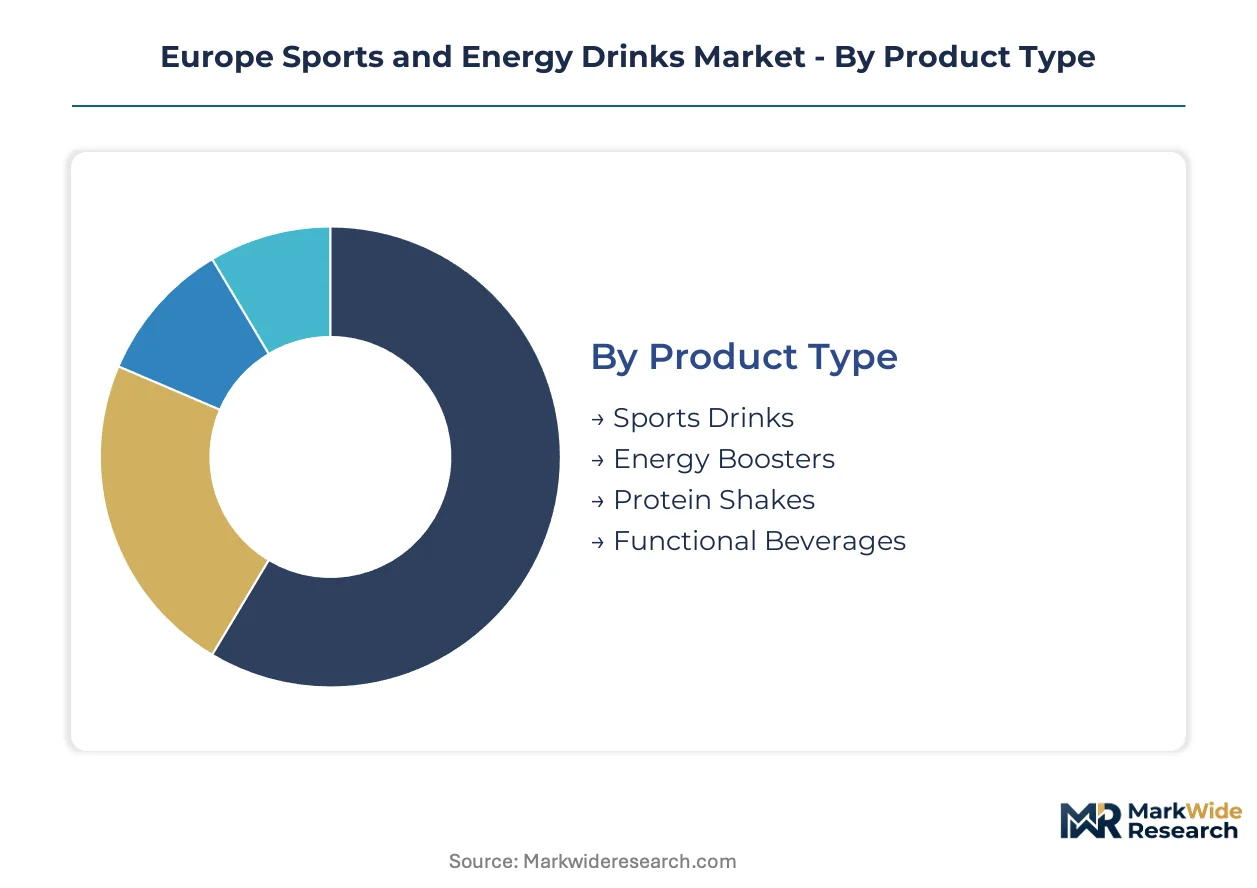
Segmentation in the European functional beverage market reveals divergent margin architectures across consumption occasions and channel economics. Manufacturers must calibrate formulation investment, packaging formats, and retail partnerships against distinct price elasticities and regulatory exposure profiles.
Product Type:
Margin pools concentrate in formulations commanding functional credibility premiums, with electrolyte science and protein bioavailability driving tiered pricing power.
- Sports Drinks:Isotonic and hypotonic formulations containing sodium, potassium, and carbohydrate matrices for rapid hydration and glycogen replenishment. Demand clusters in German and British athletic clubs and endurance event circuits, constrained by EFSA health-claim substantiation costs for electrolyte efficacy messaging.
- Functional Beverages:Adaptogen-infused and nootropic-adjacent formulations integrating ashwagandha, L-theanine, or botanical caffeine sources. Boutique studio networks in Paris and Amsterdam are rotating these into pre-workout rituals among knowledge-worker demographics seeking cognitive performance benefits.
- Energy Boosters:Stimulant-based formulations with caffeine, taurine, and B-vitamin complexes. Urban convenience channels in London and Berlin sustain volume throughput despite sugar tax compression on mid-tier SKUs.
- Protein Shakes:Ready-to-drink dairy and plant-based protein matrices targeting post-exercise recovery. Pharmacy and health store distribution in France and Italy extracts premium positioning through clinical nutrition framing.
Sports Drinks hold installed capacity across European bottling infrastructure. Functional Beverages is rotating up the share rankings as clean-label premiums displace legacy stimulant formulations.
End User:
Customer archetypes stratify around consumption ritual frequency and willingness to pay for performance substantiation, with gym culture penetration blurring traditional athletic boundaries.
- Fitness Enthusiasts:Regular gym attendees and boutique studio members consuming pre-workout and intra-workout beverages as habitual lifestyle fixtures. CrossFit affiliate density in metropolitan Spain and Poland is expanding addressable base beyond competitive athletics.
- Athletes:Competitive and semi-professional sports participants requiring batch-tested, contamination-controlled formulations. German cycling federations and British triathlon associations maintain stringent procurement protocols that filter supplier eligibility.
- Casual Consumers:Occasional purchasers seeking functional hydration or energy without performance-specific formulation premiums. Irish and Swedish sugar tax exposure compresses margin on value-positioned SKUs in this cohort.
- Professionals:Office-based knowledge workers adopting nootropic beverages for cognitive endurance. London and Frankfurt financial services clusters exhibit highest per-capita consumption of adaptogen-infused shots.
Athletes command pricing authority through certification requirements. Fitness Enthusiasts is expanding most quickly as urban studio proliferation normalizes habitual functional beverage consumption.
Distribution Channel:
Channel economics diverge sharply between shelf-space gatekeeping costs and direct relationship economics, with digital infrastructure enabling margin recapture.
- Supermarkets:Dominant volume channel controlling promotional fund structures and category management protocols. Tesco, Carrefour, and REWE networks in Britain, France, and Germany extract listing fees that disadvantage emerging brands.
- Online Retail:Fastest-climbing channel enabling subscription models and personalized nutrition stacks. Specialized platforms bypass supermarket gatekeeping while capturing consumer data for reformulation feedback loops.
- Health Stores:Pharmacy, DM, and dedicated sports nutrition retailers offering credibility premiums through clinical positioning. Boots and Apotheke networks impose conflicting margin structures versus convenience retail.
- Convenience Stores:Impulse-capture channel including petrol stations, newsagents, and urban dark-store rapid delivery. Dark-store fragmentation in Paris and Berlin is displacing traditional petrol-station dominance.
Supermarkets retain volume concentration. Online Retail is gaining share fastest as platform specialization erodes traditional retail leverage.
Packaging Type:
Material selection carries escalating compliance burden under EU Green Deal directives, with recyclability infrastructure investment determining competitive viability.
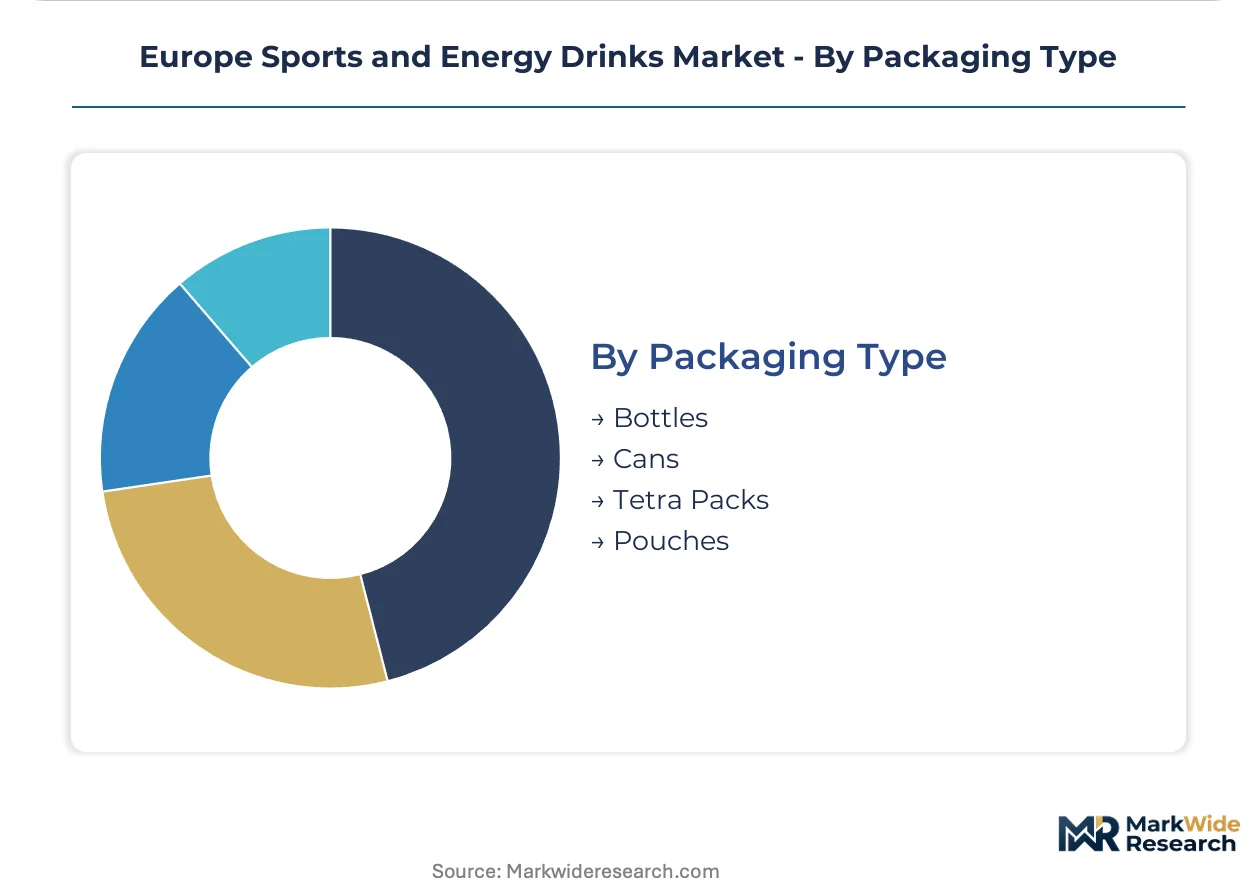
- Bottles:PET and rPET formats dominating sports drink and protein shake segments. German and Dutch recycling loop maturity supports premium rPET positioning against virgin plastic cost volatility.
- Cans:Aluminum formats preferred for energy boosters and functional beverages. Limited European converter capacity creates input cost exposure and extended producer responsibility timeline risks.
- Tetra Packs:Aseptic carton formats for ambient-stable protein and functional beverages. Shelf stability enables pharmacy channel distribution without cold-chain dependency.
- Pouches:Flexible formats emerging in gel and concentrate segments for endurance athletics. Lightweight transport economics appeal to event-sponsorship sampling strategies.
Bottles command installed filling infrastructure. Cans is rotating up the share rankings as aluminum-loop investments align with EU packaging directive timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany and the United Kingdom exceeds southern European markets by double-digit percentage points, reflecting divergent retail consolidation and sugar-tax exposure across the continent.
Germany
Bavarian cycling federations and CrossFit affiliate density in Munich and Berlin drive pre-workout consumption rituals. The national sugar tax framework remains lighter than British or French equivalents, preserving margin elasticity for mid-tier SKUs. North Rhine-Westphalia bottling infrastructure anchors continental distribution reach into Benelux and eastern markets.
United Kingdom
London dark-store rapid-delivery networks and pharmacy chain integration at Boots reshape impulse-capture economics. The Soft Drinks Industry Levy compresses price flexibility on sugar-sweetened formulations, accelerating reformulation toward stevia and monk fruit matrices. Manchester and Birmingham gym-proximate micro-fulfillment points concentrate boutique brand trial.
France
Paris boutique studio proliferation normalizes adaptogen-infused beverages among knowledge-worker demographics. The national soda tax and Nutri-Score front-of-pack labeling create dual compliance pressure on formulation teams. Île-de-France retail concentration through Carrefour and Monoprix extracts steep listing fees that filter emerging entrants.
Poland
Warsaw and Krakow fitness culture penetration lags western per-capita baselines, creating category development headroom. EU F-Gas Regulation cold-chain phase-down elevates distribution costs for temperature-sensitive functional beverages. Silesian manufacturing zones attract co-packing investment from western brands seeking eastern European production footholds.
Netherlands
Amsterdam health-store channel density and rPET recycling loop maturity support premium sustainable packaging claims. EFSA caffeine guidance evolution tightens health-claim substantiation requirements for stimulant-based formulations. Rotterdam port infrastructure facilitates botanical extract import flows for adaptogen integration into Dutch-manufactured SKUs.
Europe Sports and Energy Drinks Market Key Industry Players
Concentration sits with diversified beverage conglomerates and focused energy specialists operating at opposing ends of the margin spectrum. The competitive structure exhibits tiered segmentation between premium-positioned lifestyle brands and scale-driven portfolio players. Three archetypes dominate: event-sponsorship ecosystem builders, pharmacy-channel credibility anchors, and multi-brand manufacturing optimizers. Capacity expansion in aseptic cold-fill lines and strategic partnerships with gym-proximate retail networks constitute the dominant competitive moves reshaping market access.
Within the energy-specialist tier, Red Bull GmbH and Monster Beverage Corporation exemplify divergent route-to-market philosophies, with the former leveraging proprietary distribution against the latter's retail-scale penetration. Lucozade Ribena Suntory Limited anchors British mass-market positioning through pharmacy and grocery network density. PepsiCo and The Coca-Cola Company occupy the diversified conglomerate archetype, extending manufacturing flexibility across energy and sports variants through multi-brand portfolio scale.
| Leading Market Players |
|---|
| Monster Beverage Corporation |
| Lucozade Ribena Suntory Limited |
| Red Bull GmbH |
| Hell Energy |
| Vitamin Well AB |
| PepsiCo |
| Suntory Holdings Limited |
| BA Sports Nutrition |
| The Coca-Cola Company |
| Others |
Cost & Logistics Intelligence
Sixty-day inventory cycles for botanical caffeine extracts and aluminum can substrates simultaneously compress working capital efficiency and amplify price volatility exposure across European functional beverage portfolios. This lead-time band concentrates procurement risk with German and Dutch bottlers while forcing margin trade-offs between premium positioning and mid-tier volume defense.
Pricing Analysis
The customization-premium spread between configured-to-order adaptogen formulations and standard isotonic sports drinks spans subscription-tiered pricing for personalized nutrition stacks versus transactional per-unit retail. Price differentiation rests on EFSA health-claim certification tiers and rPET packaging sustainability premiums. Cost compression in mid-tier energy boosters is intensifying because Irish and British sugar tax stacking forces reformulation toward expensive natural sweetener matrices. Casual consumers in Eastern European markets exhibit highest price sensitivity, while certified-athlete segments in German cycling federations absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Germany and the Netherlands anchor aseptic cold-fill bottling infrastructure and rPET recycling loop maturity for European functional beverage manufacturing. Raw material dependencies draw from Brazilian yerba mate extracts for botanical caffeine substitution, Vietnamese aluminum converter capacity for can substrates, and Indian B-vitamin precursor chemicals. Single-source vulnerability concentrates in limited European aluminum converter capacity facing EU Green Deal extended producer responsibility timeline risks. Distribution runs through REWE and Carrefour supermarket networks controlling promotional fund structures, with dark-store rapid-delivery apps fragmenting urban convenience-channel economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity intensifies as gym-culture normalization splinters consumption occasions from competitive athletics toward lifestyle functional hydration, creating niche formulation white-space between performance efficacy and everyday palatability.
For Market Incumbents: Secure aseptic cold-fill technical talent pools in North Rhine-Westphalia and Bavaria before specialized process engineering scarcity elevates compensation premiums further. Deepen backward integration into rPET recycling loops to preempt EU Green Deal packaging directive compliance costs while defending margin position against sugar-tax-driven reformulation pressure from emerging clean-label entrants. For New Entrants and Emerging Players: EFSA caffeine guidance fast-track certification for botanical-extract formulations opens pharmacy-channel credibility at Boots and DM networks without legacy convenience-retail margin structure conflicts. Target Polish and Romanian fitness studio proliferation where per-capita consumption baselines lag Western European levels by substantial gaps. Deploy direct-to-consumer subscription models bypassing supermarket listing fee gatekeeping. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified beverage conglomerates seeking to divest non-core functional beverage portfolios amid sugar tax compression and reformulation cost escalation. Long-term viability over the coming decade hinges on adaptogen integration capabilities and aluminum-loop infrastructure positioning. Watch EFSA front-of-pack labeling harmonization announcements as inflection indicators for reformulation investment windows.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Cold-Fill Capacity Expansion | Specialized pH-stabilized manufacturing lines command scarcity premiums in German bottling corridors. |
| Botanical Caffeine Sourcing Agreements | Green tea and yerba mate extract contracts with Brazilian suppliers preempt REACH restriction compliance costs. |
| rPET Recycling Loop Investment | Extended producer responsibility frameworks in the Netherlands reward first-mover sustainable packaging claims. |
| Gym-Proximate Micro-Fulfillment Partnerships | Fitness studio vending retrofitting in London and Berlin captures habitual pre-workout consumption rituals. |
| Direct-to-Consumer Subscription Launch | Personalized nutrition stacks bypass Tesco and Carrefour promotional fund requirements while capturing reformulation feedback data. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across formulation scientists at German and Dutch bottling facilities, category buyers at REWE and Carrefour, pharmacy chain procurement managers at Boots and DM, and CrossFit affiliate owners in Warsaw and Madrid. Secondary validation drew from EFSA guidance documents, EU F-Gas Regulation phase-down schedules, national sugar tax legislation in Britain and France, and Nielsen retail audit data. Bottom-up SKU-level volume builds were triangulated against top-down category expenditure models.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type tiers, end-user archetype evolution, distribution channel economics, and packaging material compliance trajectories. CAGRs were derived from category penetration rate analysis and per-capita consumption convergence assumptions. Forecast inputs incorporated EFSA caffeine threshold revisions and EU Green Deal packaging directive implementation timelines.
Underlying assumptions cover EFSA health-claim substantiation cost trajectories and aluminum converter capacity expansion schedules, with deviation risk concentrated in front-of-pack labeling harmonization uncertainty and REACH chemical restriction expansion scope. Recalibration cycles align with material shifts in regulatory guidance publication and national sugar tax rate adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
North America Bottled Water Processing Market
Non-Alcoholic Beverages
Fruit-Infused Water Market
Non-Alcoholic Beverages
Europe Non-Alcoholic Wine and Beer Market
Non-Alcoholic Beverages
Hypertonic Drinks Market
Non-Alcoholic Beverages
China Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
Non-Carbonated Soft Drinks Market
Non-Alcoholic Beverages
Global Nonalcoholic Beverage Market
Non-Alcoholic Beverages
Energy Drinks Market
Non-Alcoholic Beverages
Hydrogen Water Machine Market
Non-Alcoholic Beverages
Global RTD Tea Drinks Market
Non-Alcoholic Beverages
Vietnam Energy Drinks Market
Non-Alcoholic Beverages
North America Soy Beverages Market
Non-Alcoholic Beverages
Soft Drinks Market
Non-Alcoholic Beverages
Europe Soy Beverages Market
Non-Alcoholic Beverages
Isotonic Drinks Market
Non-Alcoholic Beverages
Naturally Cultured Beverages Market