
 Military Body-Worn Camera Market | 2026-2036
Military Body-Worn Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Military Body-Worn Camera Market Outlook
United States industrial capacity for ruggedized electronics is reconfiguring supply dynamics across the military body-worn camera value chain. Axon Enterprise Inc. leverages its law enforcement technology heritage to anchor defense-adjacent product development. Motorola Solutions Inc. sustains long-standing radio and communications integration advantages that extend into wearable video systems. Panasonic i-PRO Sensing Solutions Co., Ltd. competes through specialized imaging sensor architectures purpose-built for low-light tactical environments.
Military body-worn cameras comprise compact, weather-sealed audiovisual recording devices affixed to combat helmets, load-bearing vests, or weapon systems, typically capturing 1080p to 4K resolution footage with minimum two-hour continuous operation in temperatures spanning minus twenty to plus sixty degrees Celsius. Their primary purpose centers on after-action review, rules-of-engagement verification, and intelligence documentation across contested operational theaters. Smart cameras incorporating edge analytics and wireless connectivity represent the fastest-growing product-technology intersection, while standard cameras retain volume dominance among cost-constrained infantry units. Night vision cameras command premium positioning within special operations procurement channels where infrared imaging compatibility determines mission utility.
The U.S. Department of Defense, NATO Standardization Office, and the U.S. National Institute of Standards and Technology collectively shape encryption, interoperability, and environmental hardening requirements that vendors must satisfy for contract eligibility. These frameworks effectively filter market access toward suppliers capable of meeting MIL-STD-810H shock resistance and FIPS 140-2 data security certifications. Stakeholders must monitor evolving classification protocols for footage captured on allied nation equipment during joint operations, as cross-border data governance rules will determine which technology architectures achieve multinational program adoption.
Market Dynamics
The U.S. Department of Defense's FIPS 140-2 encryption mandates are compressing vendor eligibility windows and forcing rapid architectural redesigns across the military body-worn camera supply base. This regulatory pressure is concentrating procurement authority toward suppliers capable of simultaneous MIL-STD-810H environmental certification and real-time data security compliance.
Growth Catalysts
- Special operations procurement acceleration:NATO special operations forces are expanding body-worn camera deployments for after-action review and intelligence documentation in contested theaters.
- Edge analytics integration:Smart cameras with onboard processing are reducing bandwidth dependency and enabling real-time threat detection without cloud connectivity.
- Soldier-worn sensor convergence:Army and Marine Corps modernization programs are mandating interoperable video, audio, and biometric data capture from single-platform wearables.
Market Restraints
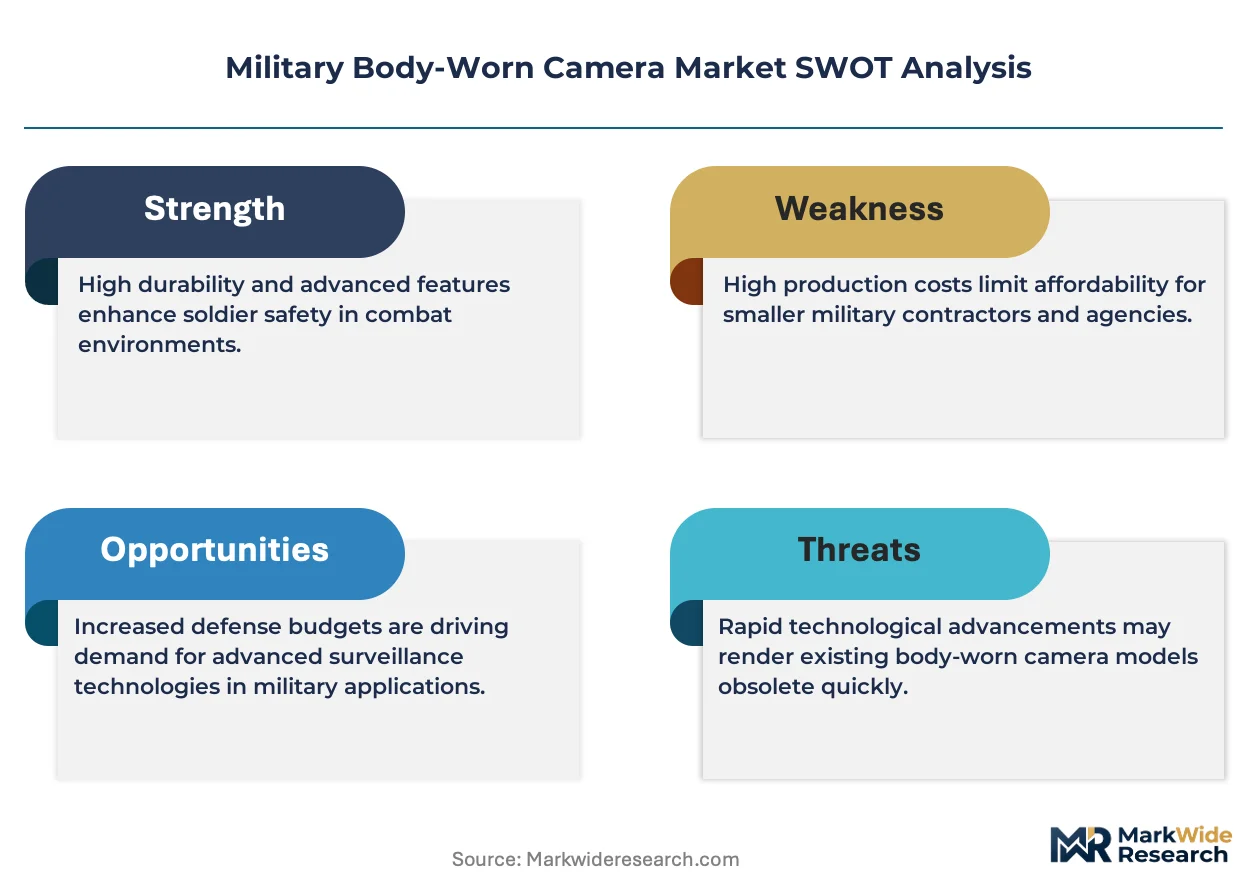
- Imaging sensor supply concentration:Specialized low-light sensor fabrication relies on a limited number of qualified foundries, creating single-source vulnerability for night vision camera production.
- Cross-border data classification friction:Footage captured on allied equipment during joint operations faces unresolved governance protocols that stall multinational program adoption.
- Battery chemistry thermal limitations:Lithium-ion cell performance degrades below minus twenty degrees Celsius, constraining continuous operation in Arctic warfare environments.
Strategic Opportunities
- Infrared imaging convergence:Fusion of thermal cores with visible-light sensors is hybridizing product architectures for special operations units requiring seamless day-night transition.
- Wireless mesh networking:Tactical teams are adopting decentralized video distribution architectures that bypass centralized command nodes for operational security.
- PLI scheme alignment:India's production-linked incentive framework for electronics manufacturing is attracting component suppliers to establish ruggedized camera assembly capacity.
Industry Challenges
- Embedded systems security engineering scarcity:Vendors struggle to recruit firmware architects capable of implementing hardware-rooted trust mechanisms for anti-tamper requirements.
- Interoperability certification backlog:NATO Standardization Office testing queues extend program timelines by twelve to eighteen months for new platform introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Body-Worn Camera Market |
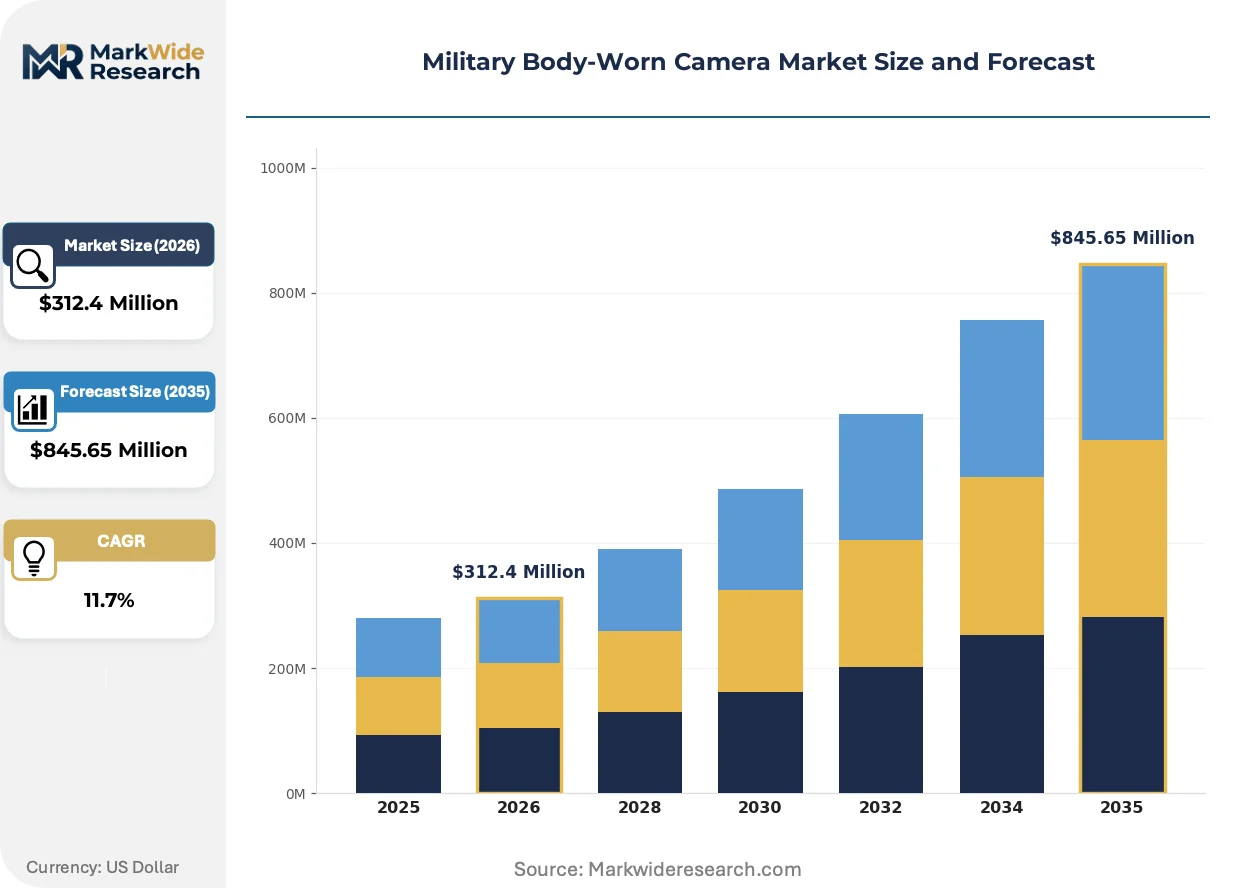
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $845.65 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Cameras, Smart Cameras, Night Vision Cameras, Multi-Function Cameras Technology: Infrared Imaging, HD Video, Motion Detection, Wireless Connectivity Application: Tactical Operations, Surveillance, Evidence Collection, Training Exercises End User: Military Personnel, Law Enforcement, Private Security, Defense Contractors |
| Companies Covered | Axon Enterprise Inc., Digital Ally Inc., Motorola Solutions Inc., Panasonic i-PRO Sensing Solutions Co., Ltd., GoPro Inc., Intrensic LLC, B Cam Ltd., Black Mamba Protection LLC, Defender LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Body-Worn Camera Market Strategic Shifts
Active hybridization between imaging modalities and data transmission architectures is compressing product development cycles while expanding functional boundaries beyond traditional video capture. Vendors are racing to integrate edge intelligence with legacy radio networks.
Multi-spectral imaging is hybridizing tactical camera functionality by combining short-wave infrared, near-infrared, and visible spectrum capture in single sensor packages. Special operations procurement channels are adopting these fused architectures fastest, driven by mission requirements for positive identification through obscurants. The technology is hybridizing competitive positioning by rewarding vendors with captive sensor design capability over assembly-only competitors.
REACH substance restrictions on restricted hazardous substances are forcing component substitutions in solder alloys and conformal coatings used in military-grade electronics. The regulation is compressing supplier qualification timelines as vendors reformulate materials to maintain MIL-STD-810H shock resistance without legacy chemistries. Night vision camera manufacturers face the steepest reformulation burden due to thermal cycling demands on optical assemblies.
Defense procurement offices are consolidating vendor relationships around platform-agnostic data formats that enable footage portability across allied systems. This behavioral shift is displacing proprietary codec ecosystems that previously locked customers into single-source maintenance contracts. The United States Army's Program Executive Office Soldier is driving standardization most aggressively through its Integrated Visual Augmentation System ecosystem requirements.
Military Body-Worn Camera Market Segmentation
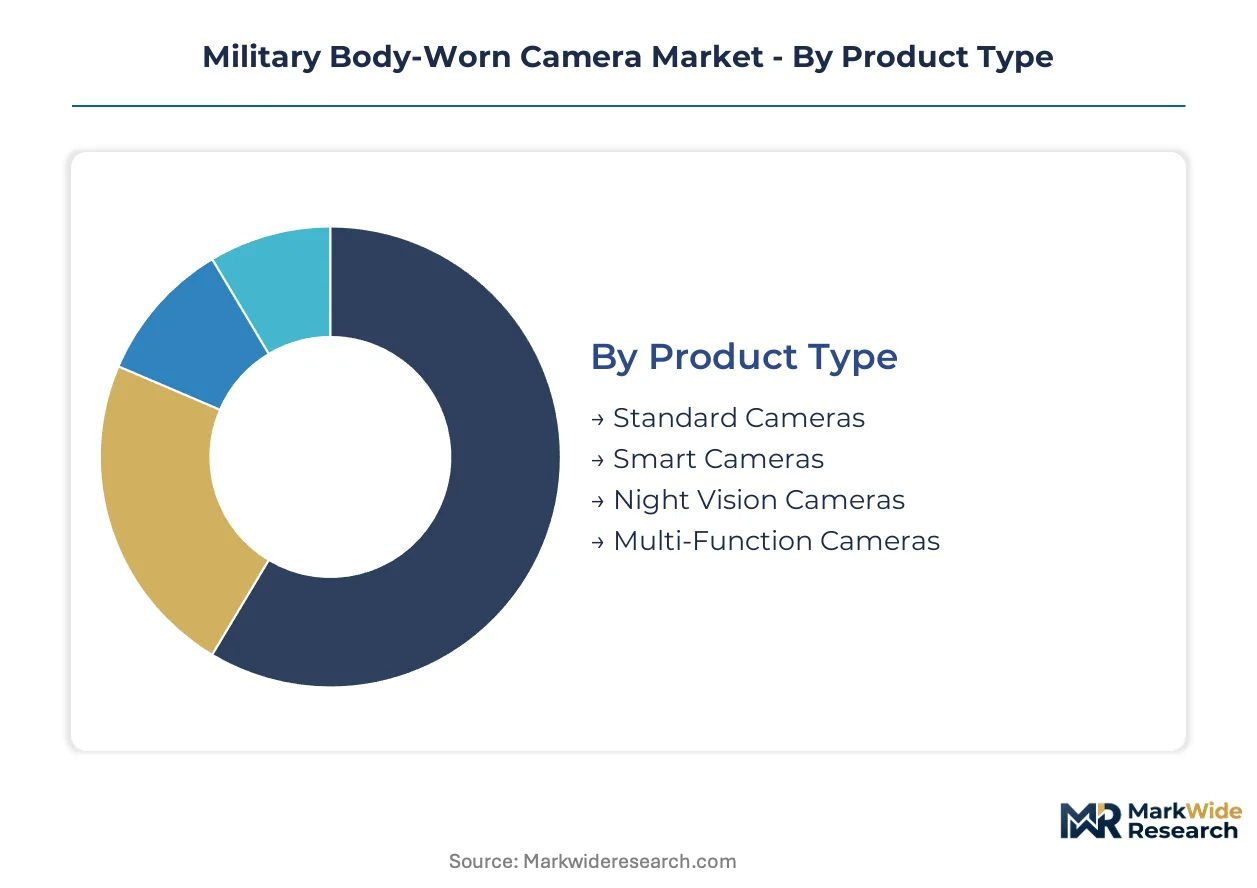
Military body-worn camera segmentation reflects divergent procurement priorities across operational echelons. Procurement officers balance unit cost constraints against mission-specific capability requirements when allocating budgets across product tiers.
Product Type:
Mature volume segments coexist with emerging premium architectures as defense modernization programs phase in advanced capabilities.
- Standard Cameras:These units deliver 1080p recording with MIL-STD-810H shock resistance and minimum two-hour battery operation. Infantry units across the United States Army and Marine Corps procure these for cost-conscious squad-level deployment where basic after-action review suffices.
- Smart Cameras:Onboard edge analytics enable real-time threat detection without cloud dependency. NATO special operations forces are accelerating procurement of these architectures for contested theaters where bandwidth is unavailable.
- Night Vision Cameras:Infrared imaging compatibility determines mission utility for special operations units requiring seamless day-night transition capability.
- Multi-Function Cameras:Fused sensor packages combine visible, near-infrared, and short-wave infrared capture for positive identification through obscurants.
Standard Cameras handles the majority of throughput; Smart Cameras is the fastest mover on share.
Technology:
Cost tier differentiation separates baseline recording functions from premium sensing capabilities in procurement specifications.
- Infrared Imaging:Specialized low-light sensor fabrication enables thermal core fusion with visible-light architectures. Night vision procurement channels command premium positioning where infrared compatibility determines contract awards.
- HD Video:1080p to 4K resolution capture represents the baseline specification across all product tiers. Volume procurement programs standardize on this capability for evidence-grade documentation requirements.
- Motion Detection:Edge-based trigger algorithms reduce storage burden and extend operational duration in field conditions.
- Wireless Connectivity:Mesh networking architectures bypass centralized command nodes for operational security in tactical team deployments.
HD Video anchors volume procurement; Infrared Imaging captures the steepest expansion trajectory as special operations requirements intensify.
Application:
Customer type segmentation reveals divergent performance thresholds between frontline combat and support functions.
- Tactical Operations:Real-time situational awareness requirements drive integration with soldier-worn sensor ecosystems. The United States Army's Program Executive Office Soldier mandates interoperable video capture through its Integrated Visual Augmentation System requirements.
- Surveillance:Extended duration recording with low-power consumption suits static observation posts and perimeter monitoring missions.
- Evidence Collection:Chain-of-custody protocols require tamper-evident encryption meeting FIPS 140-2 standards for rules-of-engagement verification.
- Training Exercises:After-action review applications prioritize durability and ease of data extraction over advanced analytics capability.
Tactical Operations dominates procurement value; Evidence Collection is gaining share fastest as rules-of-engagement accountability requirements tighten.
End User:
Supply concentration varies sharply between institutional military buyers and fragmented commercial security markets.
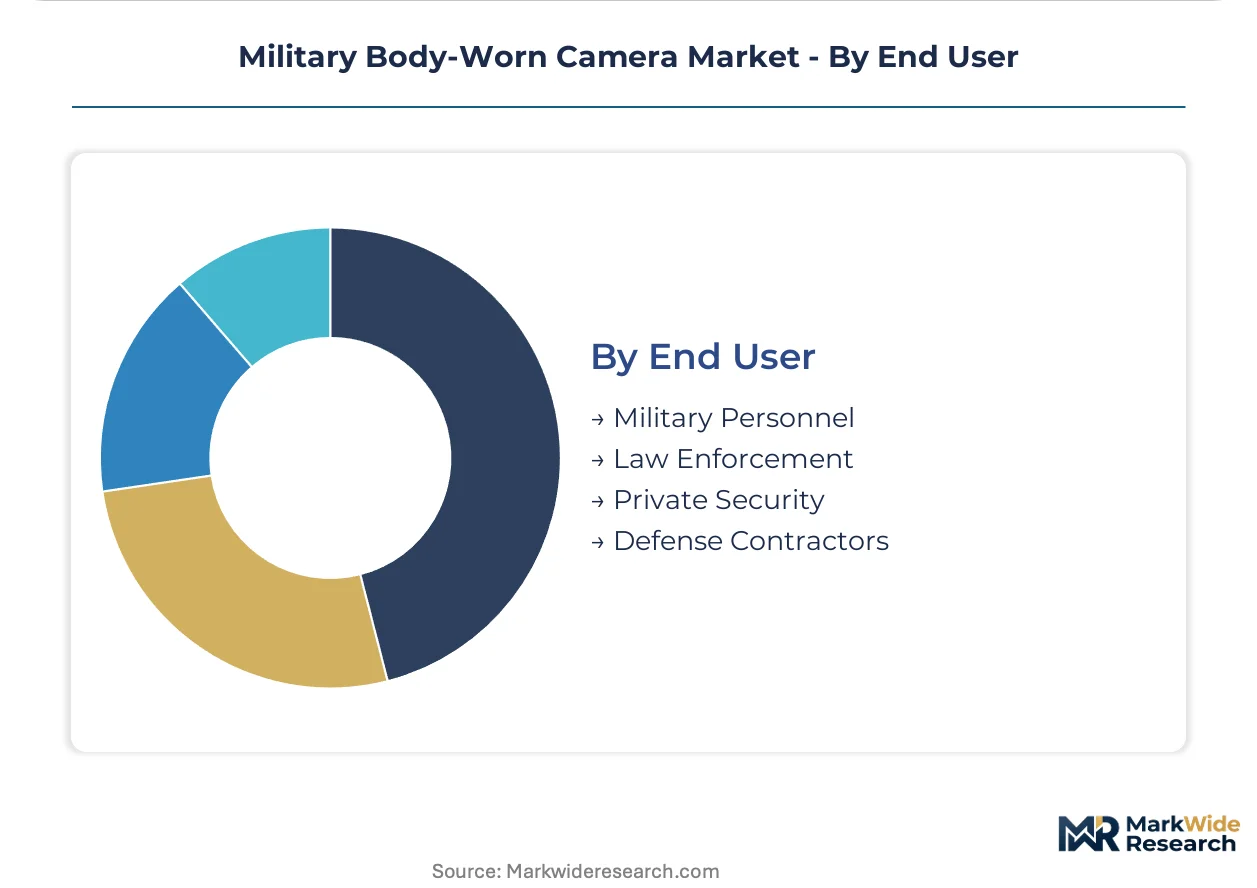
- Military Personnel:Department of Defense procurement consolidates demand around MIL-STD-810H environmental certification and FIPS 140-2 data security compliance. The U.S. Department of Defense's tightening encryption mandates filter vendor eligibility toward qualified suppliers.
- Law Enforcement:Adjacent technology heritage from civilian policing creates procurement overlap with defense-adjacent product development channels.
- Private Security:Cost-constrained buyers prioritize basic recording capability without military-grade hardening specifications.
- Defense Contractors:Training and logistics support functions generate secondary demand for documentation and quality assurance applications.
Military Personnel controls the dominant procurement volume; Defense Contractors is expanding most quickly as contractor-supported operations proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between NATO special operations forces prioritizing encrypted edge analytics and cost-conscious infantry units in emerging defense markets. The United States concentrates procurement around FIPS 140-2 compliance and IVAS ecosystem integration, while European buyers emphasize REACH-certified component sourcing and cross-border data portability.
United States
The Army's Program Executive Office Soldier and Marine Corps Systems Command drive demand through IVAS modernization and squad-level sensor convergence programs. The Department of Defense's tightening FIPS 140-2 encryption mandates filter vendor eligibility toward qualified suppliers. Boston's defense technology corridor hosts ruggedized electronics specialists developing MIL-STD-810H-certified platforms for special operations procurement channels.
Germany
The Bundeswehr's special operations command accelerates body-worn camera adoption for multinational NATO exercises and rules-of-engagement documentation. ECHA REACH substance restrictions force solder alloy and conformal coating reformulations in military-grade electronics production. Bavaria's precision optics cluster around Munich supplies specialized low-light sensor assemblies for night vision camera integration.
United Kingdom
The Ministry of Defence's Defence Equipment and Support organization consolidates procurement for Army and Royal Marine units deploying to contested theaters. UK-specific data classification protocols for joint allied operations create compliance complexity for footage governance. Greater London's security technology ecosystem bridges law enforcement heritage into defense-adjacent product development channels.
India
The Ministry of Defence's capital acquisition programs expand soldier modernization budgets for tactical surveillance and training documentation systems. India's PLI scheme for electronics manufacturing attracts component suppliers establishing ruggedized camera assembly capacity. Tamil Nadu's Sriperumbudur electronics manufacturing cluster hosts emerging defense contractors qualifying for domestic procurement preferences.
France
The Direction Générale de l'Armement procures body-worn cameras for special operations forces engaged in Sahel counterterrorism operations and domestic security missions. ANSM and CNIL data protection requirements intersect with military classification protocols for footage captured on allied equipment. The Provence-Alpes-Côte d'Azur region's photonics industry supplies infrared imaging components for multi-spectral sensor fusion.
Military Body-Worn Camera Market Competitive Environment
Capability concentration sits with one tier; scale advantage sits with another, creating bifurcated competitive dynamics across the military body-worn camera supply base. Specialized imaging sensor architects and radio-communications integrators occupy distinct premium positions, while law enforcement technology heritage provides adjacent market entry points. Three archetypes dominate: defense-pure specialists with captive MIL-STD certification capability, dual-use vendors leveraging civilian policing scale, and communications infrastructure players extending into wearable video. Consolidation pressure manifests through strategic partnerships for encryption compliance and capacity expansion for NATO standardization testing queues.
Within the dual-use heritage tier, Axon Enterprise Inc. and Motorola Solutions Inc. exemplify competitive positioning anchored in adjacent law enforcement and communications markets. Panasonic i-PRO Sensing Solutions Co., Ltd. occupies a specialized position representing the imaging sensor architecture archetype. These three entities illustrate how vendor eligibility compresses toward suppliers capable of simultaneous environmental hardening and real-time data security compliance.
| Leading Market Players |
|---|
| Axon Enterprise Inc. |
| Digital Ally Inc. |
| Motorola Solutions Inc. |
| Panasonic i-PRO Sensing Solutions Co., Ltd. |
| GoPro Inc. |
| Intrensic LLC |
| B Cam Ltd. |
| Black Mamba Protection LLC |
| Defender LLC |
| Others |
Value Chain & Pricing Dynamics
Specialized low-light sensor fabrication concentrates in Bavaria's precision optics cluster and Japan's imaging component foundries, anchoring margin capture at the sensor architecture tier rather than final assembly. Procurement officers at the U.S. Department of Defense and NATO special operations commands negotiate long-term offtake agreements that compress pricing leverage for downstream integrators lacking captive sensor supply.
Pricing Analysis
Long-term offtake contracts dominate military procurement, with NATO Standardization Office certification requirements creating pricing stratification across FIPS 140-2 compliant, MIL-STD-810H certified, and standard commercial tiers. Price differentiation hinges on encryption certification level and environmental hardening grade, with thermal cycling specifications commanding substantial premiums. Cost compression in standard camera tiers intensifies as infantry unit procurement consolidates around volume programs. Law enforcement adjacent buyers exhibit highest price sensitivity, while special operations units prioritize mission capability over unit economics.
Supply Chain Analysis
Export control regimes under the U.S. International Traffic in Arms Regulations and EU dual-use technology restrictions constrain infrared imaging component flows to qualified defense contractors. Supply concentration centers on Japan, Germany, and the United States for specialized sensor fabrication, with lithium-ion cell supply drawing from South Korean and Chinese chemistry suppliers. Single-source vulnerability pervades night vision camera production due to qualified foundry scarcity. Distribution runs through prime defense contractors and direct government procurement channels rather than commercial electronics retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware procurement cycles are elongating while encrypted data management and after-action analytics subscriptions expand at multiples of device sales, reframing vendor economics around recurring service attach rates.
For Market Incumbents: Insulate sensor architecture advantages through backward integration into low-light fabrication capacity, particularly as REACH substance restrictions force reformulation cycles that favor in-house materials engineering. Deepen NATO Standardization Office pre-certification investments to compress competitor entry timelines by twelve to eighteen months. Counter emerging dual-use entrants from law enforcement markets by bundling IVAS ecosystem compatibility as a locked-in service layer. For New Entrants and Emerging Players: Pursue India's PLI scheme qualification for electronics manufacturing as a cost-competitive entry path into Ministry of Defence procurement channels. Target defense contractor training and logistics documentation segments where military-grade certification requirements remain less stringent than frontline combat specifications. Establish partnerships with established radio-communications integrators to bypass standalone encryption compliance burdens. For Investors and Strategic Acquirers: Capital is best deployed toward imaging sensor architecture specialists with captive low-light design capability rather than assembly-only hardware vendors. Long-term viability over a multi-year horizon favors suppliers positioned at the convergence of infrared imaging fusion and edge analytics processing. Watch for NATO cross-border data classification protocol resolution as the inflection signal determining which technology architectures achieve multinational program scale.| Strategic Initiative | Industry Significance |
|---|---|
| FIPS 140-2 Encryption Certification Investment | U.S. Department of Defense procurement eligibility filters toward qualified suppliers meeting federal data security mandates. |
| Multi-Spectral Sensor Fusion Development | Special operations requirements for positive identification through obscurants reward vendors with captive infrared architecture capability. |
| Wireless Mesh Networking Integration | Tactical teams adopting decentralized video distribution bypass centralized command nodes for operational security. |
| India PLI Scheme Manufacturing Localization | Tamil Nadu's Sriperumbudur cluster attracts component suppliers establishing ruggedized camera assembly capacity. |
| REACH-Compliant Materials Reformulation | ECHA substance restrictions force solder alloy substitutions that maintain MIL-STD-810H shock resistance without legacy chemistries. |
Study Parameters
Cross-validation between primary interviews with defense procurement officers, special operations technology leads, and ruggedized electronics program managers anchors the qualitative findings against secondary validation from NATO Standardization Office documentation, U.S. Department of Defense budget justification materials, and ECHA REACH regulatory filings. Bottom-up triangulation aggregates unit procurement forecasts across Army, Marine Corps, and NATO special operations channels, while top-down analysis cross-checks against aggregated defense electronics spending patterns.
Calibration against historical procurement cycles and modernization program timelines shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, imaging technology architecture, application mission profile, and end-user procurement authority level. CAGRs derive from weighted scenario analysis across special operations acceleration, infantry unit cost constraints, and multinational standardization adoption curves. Forecast inputs incorporate battery chemistry thermal performance limits and encryption mandate compliance timelines as industry-specific variables.
Sensitivities concentrate around NATO cross-border data governance protocol resolution, lithium-ion cell supply disruptions, and REACH substance restriction enforcement intensity. Forecasts reflect documented assumptions regarding special operations procurement acceleration and IVAS ecosystem integration timelines. Material shifts in allied nation joint operation classification rules or export control regime expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
Passive Radar Market
Military Surveillance
Maritime Surveillance and Intervention Market
Military Surveillance
Military Radar Market
Military Surveillance
Military Manportable Surveillance Radar Market
Military Surveillance
Early Warning Radar Market
Military Surveillance
Global Military Man-Portable Radar System Market
Military Surveillance
Electronically Scanned Array Radar Market
Military Surveillance
Manportable Surveillance and Target Acquisition Radar Market
Military Surveillance
Tactical Scope Market
Military Surveillance
Military Electro-Optics/Infrared (EO/IR) Systems Market
Military Surveillance
Tactical Optics Market
Military Surveillance
Airborne Target Acquisition Systems Market
Military Surveillance
Missile Seeker Detector Market
Military Surveillance
Sea-Based Military Electro-Optical and Infrared Systems Market
Military Surveillance
Hydrographic Survey Equipment Market
Military Surveillance
EO/IR Gimbal Market