
 Doppler Radar Market | 2026-2036
Doppler Radar Market Size, Share, and Industry Trends Forecast 2026-2036
Doppler Radar Market Analysis
Gallium nitride is broadening transmitter efficiency thresholds across Doppler radar architectures. Northrop Grumman Corporation leverages captive semiconductor foundries to secure GaN supply chains for phased-array production. BAE Systems plc anchors European defense contracts through sovereign radar manufacturing facilities in the United Kingdom. Robert Bosch GmbH competes in automotive Doppler segments with compact 77 GHz modules for adaptive cruise control systems.
Doppler radar detects relative velocity between a transmitter and target by measuring frequency shift in reflected electromagnetic waves, typically operating in L-band through W-band frequencies with pulse repetition rates calibrated to detection range. The technology serves collision avoidance, weather monitoring, and target tracking functions across civilian and military domains. Continuous wave technology leads volume deployment in automotive blind-spot detection where cost minimization dominates procurement criteria. Pulsed systems command premium pricing in defense and meteorology applications requiring long-range discrimination and clutter suppression. Frequency modulated variants represent the fastest-expanding segment in industrial automation and drone detection systems.
The Federal Aviation Administration mandates Mode S and ADS-B interoperability standards that shape civil aviation radar procurement specifications. The European Union Aviation Safety Agency enforces certifiable Doppler weather radar performance thresholds under its meteorological equipment directives. The International Telecommunication Union allocates spectral bands that constrain frequency choices for marine and transportation applications. Stakeholders must monitor gallium nitride cost curves and semiconductor export control expansions when sizing capacity investments and supplier qualification timelines.
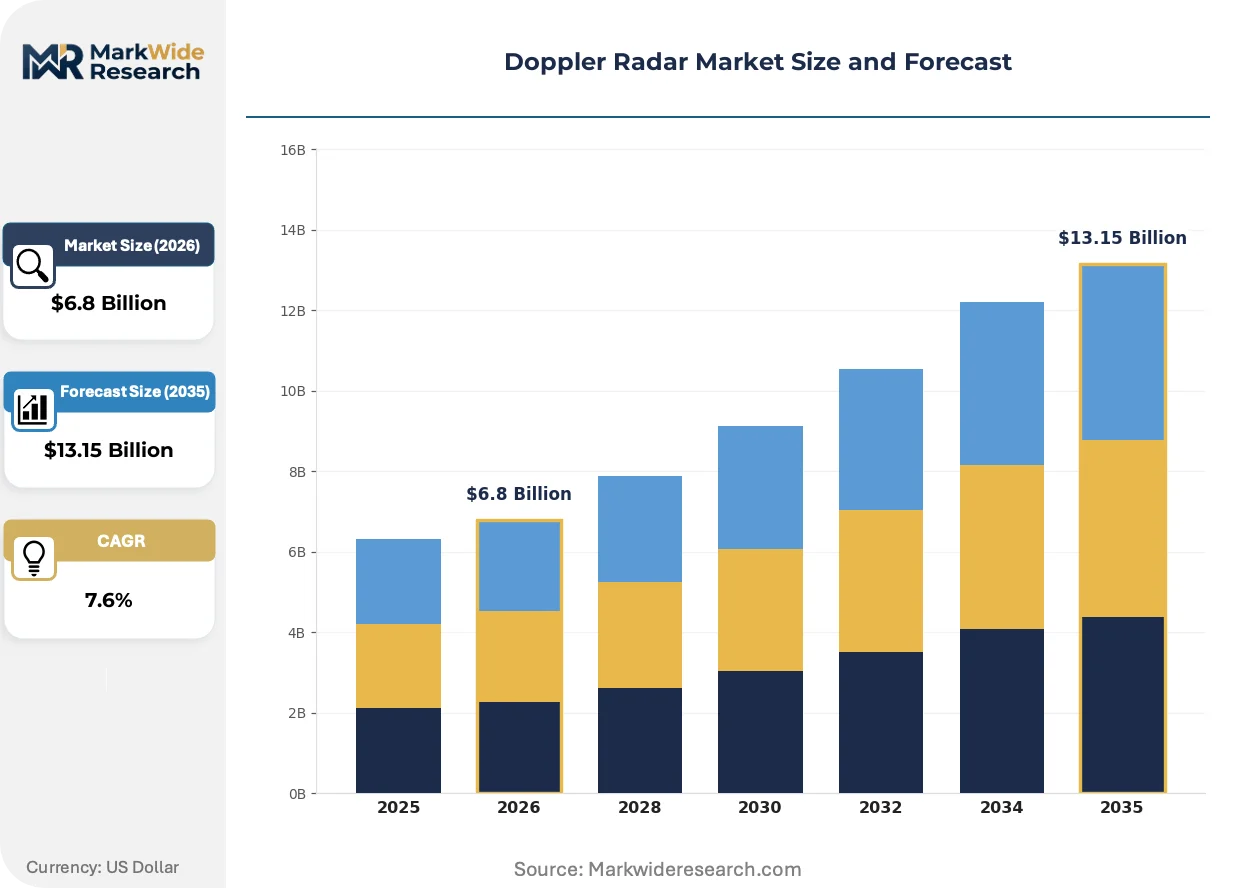
Market Dynamics
Gallium nitride semiconductor adoption is compressing transmitter size-weight-power metrics while elevating thermal tolerance, forcing incumbent radar architectures toward complete subsystem redesign.
Growth Catalysts
- NextGen Airspace Mandate:The Federal Aviation Administration's terminal radar replacement program is accelerating procurement of Mode S-compatible Doppler systems across United States commercial airports.
- Active Electronically Scanned Arrays:Defense procurement prioritization of AESA technology is displacing mechanically scanned legacy radars in fighter aircraft and naval platforms.
- Automotive Safety Regulation:European Union type-approval requirements for advanced driver-assistance systems are embedding 77 GHz Doppler modules in passenger vehicle platforms.
Market Restraints
- GaN Substrate Concentration:Epitaxial wafer supply concentrates among Japanese and United States semiconductor foundries, creating chokepoint vulnerability for phased-array manufacturers.
- Spectral Allocation Friction:International Telecommunication Union band reassignments for 5G telecommunications are compressing available L-band and C-band spectrum for meteorological radar operations.
- Substitution by Passive Sensors:Lidar and camera-fusion systems are capturing low-speed automotive collision-avoidance applications where Doppler performance exceeds functional requirements.
Strategic Opportunities
- Drone Detection Networks:Counter-UAS regulations at United States critical infrastructure sites are creating demand for frequency-modulated continuous-wave radars with micro-doppler discrimination.
- Industrial Automation:Warehouse robotics and automated guided vehicle fleets in Germany are adopting 60 GHz Doppler sensors for precise velocity feedback in confined environments.
- Dual-Use Technology Convergence:Civil-military interoperability standards are enabling weather radar manufacturers to repurpose signal-processing algorithms for defense surveillance contracts.
Industry Challenges
- GaN Process Engineering Talent:Compound semiconductor fabrication expertise concentrates among a limited cohort of process engineers, constraining foundry expansion timelines.
- Legacy System Integration:FAA-certified terminal radars must maintain backward compatibility with 1950s-era beacon interrogators, complicating software-defined radio transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Doppler Radar Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed, Portable, Mobile, Weather Application: Aviation, Automotive, Government, Marine Technology: Pulsed, Continuous Wave, Frequency Modulated, Doppler Beam End User: Defense, Meteorology, Transportation, Research |
| Companies Covered | Northrop Grumman Corporation, BAE Systems plc, Robert Bosch GmbH, Collins Aerospace, Thales Group, DENSO Corporation, Honeywell International Inc., Leonardo S.p.A., Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Doppler Radar Market Emerging Trajectories
Digital beamforming architectures are displacing analog phased-array backplanes, compressing manufacturing complexity while enabling software-reconfigurable waveforms that adapt to mission requirements without hardware modification.
Gallium nitride high-electron-mobility transistors are integrating into solid-state transmit-receive modules, replacing traveling-wave tube amplifiers in long-range surveillance radars. United States defense primes are retrofitting existing platforms with GaN-based line-replaceable units to extend service life. This integration is compressing mean-time-between-failure metrics by an order of magnitude while reducing prime power consumption.
The European Union Aviation Safety Agency's meteorological equipment directive is mandating dual-polarization capability for certifiable weather radar installations, forcing hardware upgrades across European airport infrastructure. Manufacturers must demonstrate clutter suppression ratios and velocity accuracy thresholds that exceed legacy single-polarization specifications. Civil aviation authorities in France and Germany are enforcing compliance timelines that compress procurement cycles for replacement systems.
Defense procurement offices are consolidating vendor qualifications through multi-year framework agreements, displacing transactional spot-buying for radar subsystems. Prime contractors are responding by absorbing tier-two suppliers to secure captive access to antenna fabrication and signal-processor supply. The United Kingdom Ministry of Defence and United States Department of Defense are both centralizing radar procurement through single-source indefinite-delivery contracts that lock out non-qualified competitors.
Doppler Radar Market Segmentation
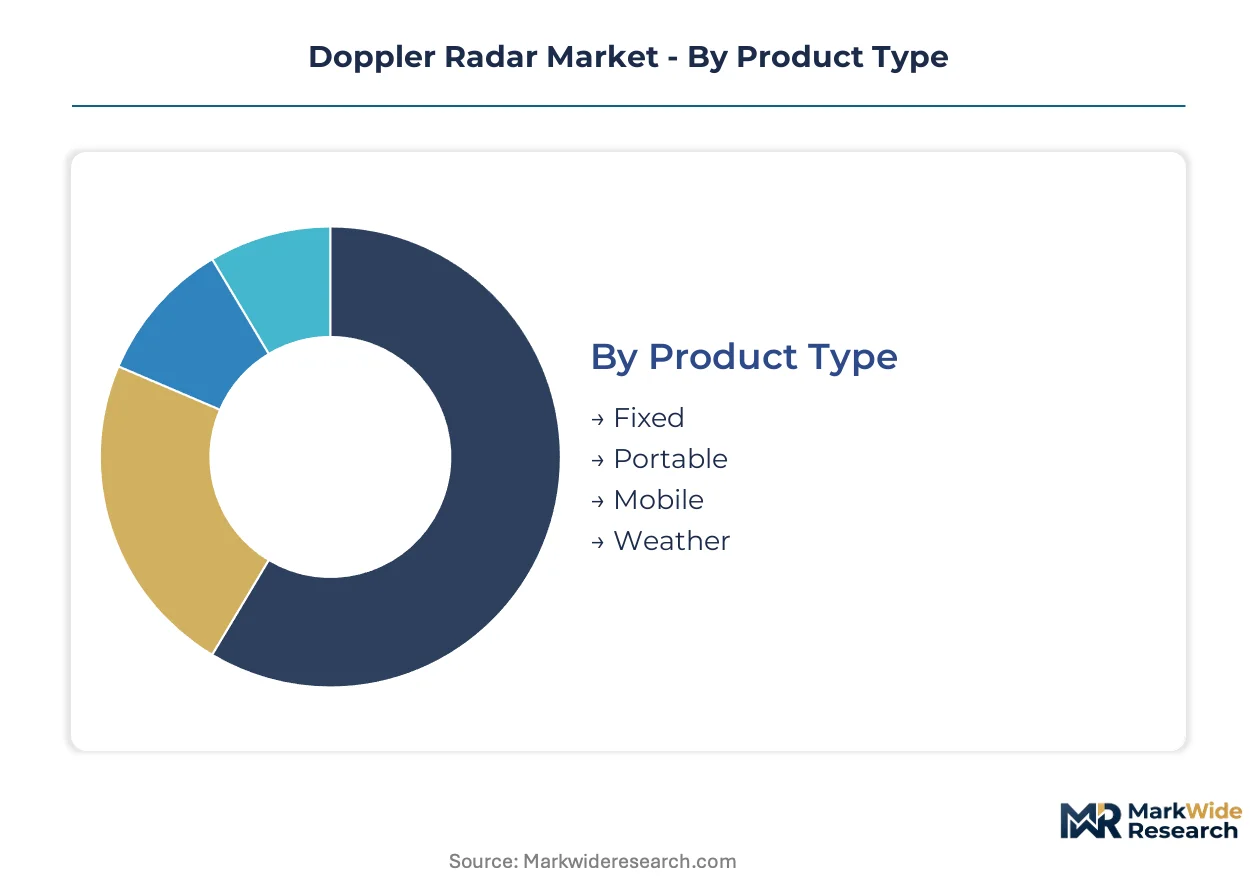
Doppler radar architectures fragment across deployment modes, signal processing methods, and institutional procurement patterns. Each segmentation axis reveals distinct margin structures, certification requirements, and supplier qualification barriers that shape competitive positioning.
Product Type:
Integration depth varies sharply—fixed installations anchor high-value defense and aviation contracts, while portable and mobile units serve tactical and emergency response scenarios requiring rapid redeployment.
- Fixed:Permanently installed ground-based or shipboard systems with high-power transmitters and large aperture antennas. The FAA's terminal radar replacement program across United States commercial airports is compressing procurement cycles for Mode S-compatible fixed installations.
- Portable:Rapidly deployable units with collapsible antennas and battery or generator power options. Field meteorology agencies in Germany and Japan are standardizing portable Doppler configurations for severe weather response teams.
- Mobile:Vehicle-mounted platforms with stabilized antenna pedestals for on-the-move operation. Military C-UAS units in the United States are fielding mobile frequency-modulated systems for expeditionary drone detection.
- Weather:Specialized precipitation and wind profiling radars with dual-polarization capability. EASA meteorological equipment directives are mandating hardware upgrades across French and German airport infrastructure.
Fixed installations lead volumes today; portable systems are gaining share fastest.
Application:
End-use concentration determines pricing power—aviation and government procurement operate under multi-year framework agreements, while automotive and marine segments compete on unit cost and integration speed.
- Aviation:Terminal approach, en-route surveillance, and weather hazard detection for commercial and military airfields. The FAA NextGen mandate and concurrent military airspace modernization in the United States are driving dual-use procurement convergence.
- Automotive:Adaptive cruise control, blind-spot monitoring, and autonomous emergency braking systems. European Union type-approval requirements for advanced driver-assistance systems are embedding 77 GHz modules in passenger vehicle platforms from German and Swedish manufacturers.
- Government:Border surveillance, critical infrastructure protection, and emergency management applications. Counter-UAS regulations at United States critical infrastructure sites are creating demand for frequency-modulated continuous-wave radars with micro-doppler discrimination.
- Marine:Vessel traffic services, collision avoidance, and offshore platform monitoring. The International Telecommunication Union's spectral allocations constrain frequency choices for marine applications, compressing available L-band and C-band spectrum.
Aviation commands the highest contract values; automotive delivers the steepest volume expansion trajectory.
Technology:
Signal generation methods separate legacy hardware from software-defined architectures, with solid-state GaN transmitters displacing vacuum-tube systems in premium segments.
- Pulsed:High-peak-power transmission with range-gated reception for long-distance target discrimination. Defense procurement prioritization of active electronically scanned arrays is displacing mechanically scanned legacy radars in fighter aircraft and naval platforms.
- Continuous Wave:Unmodulated carrier transmission enabling compact, low-cost velocity measurement. Cost minimization dominates procurement criteria for automotive blind-spot detection where volume deployment concentrates.
- Frequency Modulated:Linear or non-linear frequency sweep enabling simultaneous range and velocity measurement without ambiguity. Industrial automation and drone detection systems are expanding most quickly for this variant.
- Doppler Beam:Narrow beam steering for precision velocity profiling in meteorological and research applications. National weather services in France, Germany, and Japan operate networks of Doppler beam radars for precipitation monitoring.
Pulsed systems retain premium pricing; frequency modulated variants are climbing the fastest.
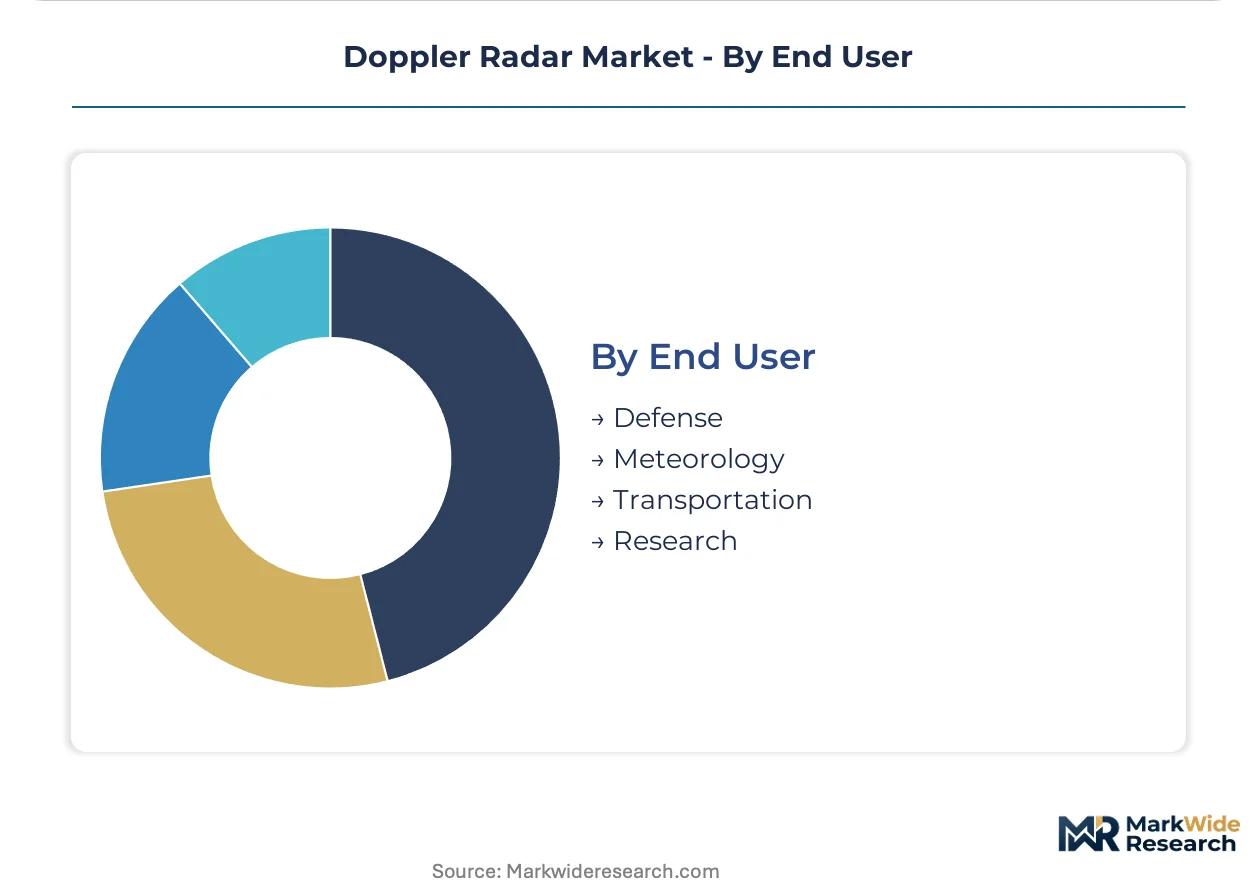
End User:
Procurement authority and certification requirements fragment the customer base—defense and meteorology operate under sovereign standards, while transportation and research segments follow commercial or academic purchasing patterns.
- Defense:Military surveillance, fire control, and electronic warfare applications with classified performance specifications. The United States Department of Defense and United Kingdom Ministry of Defence are centralizing radar procurement through single-source indefinite-delivery contracts.
- Meteorology:National weather services, commercial forecasting operations, and climate research institutions. Dual-polarization mandates from EASA are forcing hardware upgrades across European airport infrastructure.
- Transportation:Civil aviation authorities, maritime regulators, and intelligent highway system operators. The FAA's Mode S and ADS-B interoperability standards shape civil aviation radar procurement specifications.
- Research:Atmospheric science, radar cross-section measurement, and algorithm development facilities. Academic consortia in Germany and Japan operate specialized Doppler facilities for signal processing research.
Defense absorbs the largest absolute spending; meteorology is expanding most quickly under regulatory upgrade mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dallas-Fort Worth aerospace corridor anchors North American Doppler radar manufacturing, with defense primes and semiconductor foundries clustering around major military airfields and FAA technical centers.
United States
The FAA's NextGen terminal radar replacement program and concurrent Pentagon AESA procurement are compressing delivery timelines for Mode S-compatible systems. Defense procurement centralization through indefinite-delivery contracts is locking out non-qualified competitors. The Dallas-Fort Worth corridor and Greater Baltimore-Washington metro host prime contractor facilities and captive semiconductor foundries serving both civil and military programs.
Germany
Automotive OEMs are embedding 77 GHz Doppler modules in passenger vehicles under EU type-approval mandates for advanced driver-assistance systems. The KBA enforces certification standards that shape supplier qualification timelines. Bavaria's automotive electronics cluster around Munich and Stuttgart anchors Bosch and Continental module production for European vehicle platforms.
United Kingdom
The Ministry of Defence is consolidating radar procurement through sovereign manufacturing requirements that favor domestic antenna fabrication. BAE Systems operates captive radar facilities serving NATO defense contracts. The South West England aerospace cluster around Bristol and Gloucestershire hosts specialized phased-array production for naval and airborne platforms.
Japan
METI is prioritizing compound semiconductor foundry expansion to reduce GaN epitaxial wafer import dependence for defense and meteorological radar programs. National weather services operate Doppler beam radar networks for precipitation monitoring. The Kyushu semiconductor corridor and Tokyo-Yokohama industrial belt concentrate process engineering talent for solid-state transmit-receive module fabrication.
France
EASA meteorological equipment directives are mandating dual-polarization hardware upgrades across airport infrastructure with compressed compliance timelines. Thales Group anchors European defense and civil aviation radar production. The Paris-Saclay research cluster and Toulouse aerospace corridor host signal processing algorithm development and weather radar system integration facilities.
Doppler Radar Market Vendor Landscape
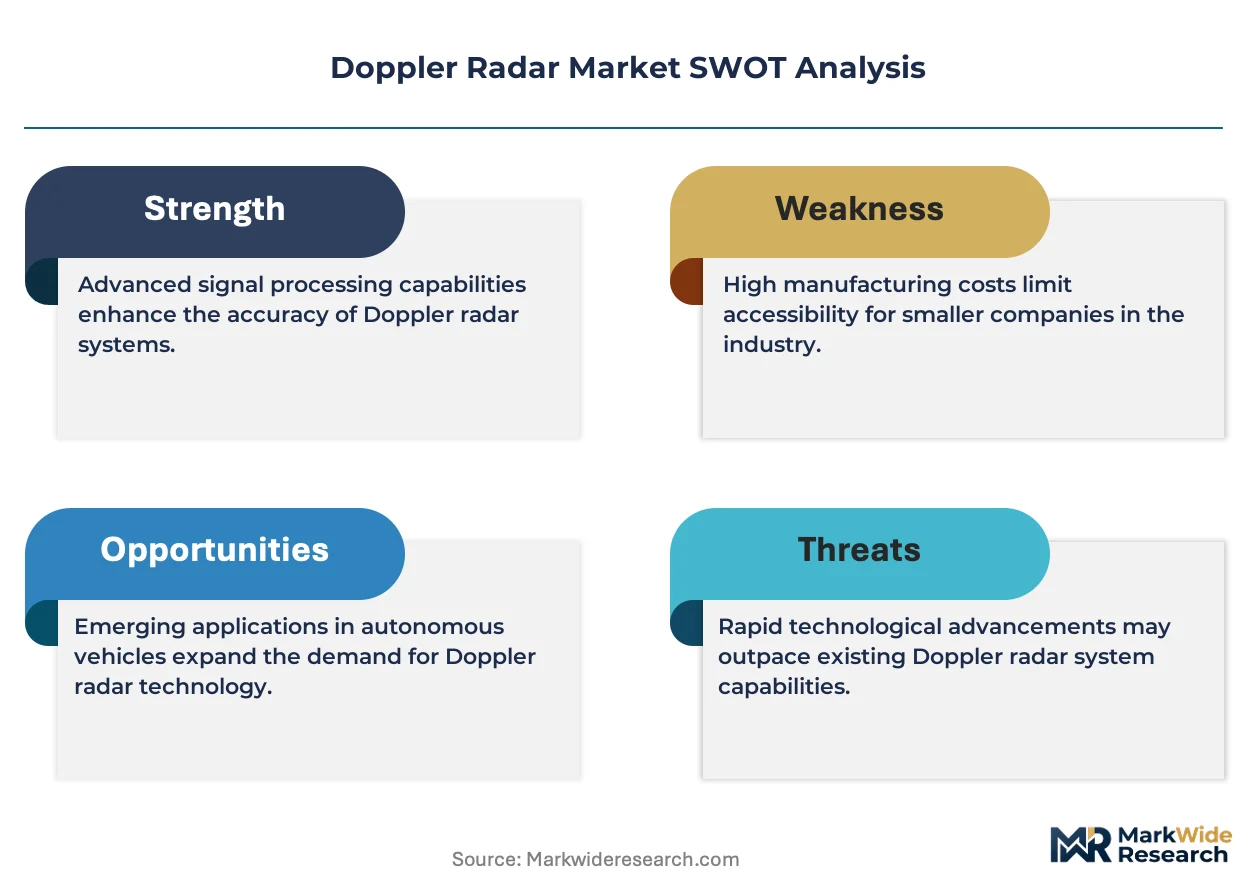
Global majors compete with regional champions across defense procurement and automotive supply chains, creating a tiered structure where scale-driven primes absorb tier-two suppliers to secure captive component access. Consolidation concentrates among United States and European defense contractors holding indefinite-delivery contracts, while automotive sensor markets fragment across German and Japanese tier-one suppliers. Three archetypes dominate: vertically integrated defense primes with captive foundries, automotive tier-one electronics suppliers with high-volume module production, and specialized meteorological equipment manufacturers with dual-use algorithm portfolios. Competitive dynamics center on backward integration into GaN semiconductor supply and absorption of antenna fabrication capabilities to defend margin position against spot-buying displacement.
Within the defense prime tier, Northrop Grumman Corporation and BAE Systems plc exemplify vertically integrated architectures with sovereign manufacturing footprints. Northrop Grumman represents United States-based consolidation around captive semiconductor foundries and phased-array production facilities. BAE Systems occupies a parallel position in European defense procurement, anchoring United Kingdom sovereign radar manufacturing. Robert Bosch GmbH sits within the automotive tier-one archetype, exemplifying German industrial conglomerate structure with high-volume electronics module production for passenger vehicle platforms. These three anchors illustrate the geographic and segment-based fragmentation shaping competitive positioning across civil and military procurement channels.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| BAE Systems plc |
| Robert Bosch GmbH |
| Collins Aerospace |
| Thales Group |
| DENSO Corporation |
| Honeywell International Inc. |
| Leonardo S.p.A. |
| Continental AG |
| Others |
Supply Flow & Price Mechanics
Gallium nitride epitaxial wafer costs cascade through Doppler radar pricing tiers, with Japanese and United States foundry premiums compressing margins for phased-array manufacturers while automotive 77 GHz module producers exploit silicon-based alternatives to defend economy-tier positioning.
Pricing Analysis
Input-cost pass-through from GaN substrate scarcity elevates pulsed-system pricing relative to continuous-wave alternatives, with defense procurement absorbing premiums through indefinite-delivery contracts while meteorology budgets face compression under EASA dual-polarization mandates. Three-tier pricing structure across premium, standard, and economy levels separates AESA military platforms from civil aviation terminals and automotive blind-spot modules. Pricing pressure stems from lidar substitution in low-speed automotive applications, where camera-fusion systems undercut Doppler cost floors. Government and defense segments exhibit lowest price sensitivity due to sovereign manufacturing requirements; automotive OEMs concentrate procurement leverage through volume scale.
Supply Chain Analysis
Reverse-logistics flows for line-replaceable GaN transmit-receive modules create secondary refurbishment channels, with United States defense primes operating captive remanufacturing facilities to extend platform service life. Supply concentrates in Japan, the United States, and Germany for compound semiconductor fabrication, with Kyushu foundries and Dallas-Fort Worth corridors anchoring upstream capacity. Raw material dependencies span high-purity gallium substrates, silicon carbide wafers, and rare-earth magnet components for antenna pedestals. Single-source vulnerability concentrates in epitaxial wafer supply from Japanese semiconductor houses. Distribution runs through prime contractor direct sales for defense, tier-one automotive electronics suppliers for vehicle platforms, and specialized meteorological equipment distributors for weather services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between United States defense procurement premiums and European automotive cost compression, with FAA NextGen mandates sustaining price floors in North America while EU type-approval standardization erodes differentiation in German vehicle platforms.
For Market Incumbents: Anticipate GaN substrate supply rationing by qualifying secondary Japanese foundries and absorbing tier-two antenna fabricators to secure captive component access. Lidar substitution in low-speed automotive collision avoidance threatens Doppler module volumes; backward integration into solid-state transmit-receive production defends margin position against spot-buying displacement.
For New Entrants and Emerging Players: Direct-to-defense channel partnerships bypass prime contractor qualification barriers for drone detection subsystems, with frequency-modulated continuous-wave architectures offering the most penetrable entry point. Target United States critical infrastructure C-UAS deployments through micro-doppler discrimination capabilities. White-space concentrates in industrial automation 60 GHz sensors for German warehouse robotics.
For Investors and Strategic Acquirers: Consolidation pressure builds where compound semiconductor process engineering talent concentrates among limited cohorts, constraining foundry expansion timelines. Long-term viability favors vertically integrated primes with captive GaN supply and dual-use algorithm portfolios. Acquisition target archetype: specialized meteorological equipment manufacturers with EASA certification and repurposable signal-processing IP. Monitor ITU 5G spectral reassignments for early signals of L-band compression affecting weather radar operations.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN Foundry Capacity Expansion | Captive semiconductor production secures supply chains for AESA manufacturing against Japanese wafer chokepoints. |
| Dual-Use Algorithm Licensing | Weather radar signal-processing IP repurposing unlocks defense surveillance contracts through civil-military interoperability. |
| Automotive Tier-1 Partnership | 77 GHz module integration into German OEM platforms leverages EU ADAS type-approval mandates for volume scaling. |
| Counter-UAS System Certification | FAA and DoD qualification for critical infrastructure drone detection opens indefinite-delivery contract access. |
| Digital Beamforming Platform Development | Software-reconfigurable architectures displace analog backplanes, compressing manufacturing complexity for multi-mission adaptability. |
Methodological Framework
Multiple input streams — procurement officer interviews at United States defense primes, regulatory affairs dialogues with EASA certification specialists, and foundry engineering assessments at Japanese semiconductor houses — were reconciled against customs trade data, FAA NextGen program disclosures, and SEC filings from tier-one automotive electronics suppliers. Bottom-up unit economics for GaN transmit-receive modules were triangulated with top-down defense budget appropriation analysis.
Historical shipment patterns for fixed, portable, and mobile installations were cross-referenced against panel input from meteorology agency procurement directors and automotive platform engineers across the projection horizon. Segmentation dimensions modeled include product architecture, signal processing technology, end-use application, and institutional procurement authority. CAGRs were derived from install-base replacement cycles and regulatory compliance timelines rather than extrapolated trend fitting. Industry-specific inputs incorporated Mode S interoperability mandates, AESA retrofit programs, and EU ADAS type-approval phase-ins.
The model assumes a particular technology adoption path; alternative pathways for solid-state GaN transmitter displacement of traveling-wave tube amplifiers would alter the outlook if thermal management breakthroughs accelerate. Forecasts embed assumptions regarding ITU spectral stability and compound semiconductor export control continuity. Practitioners should monitor Japanese METI foundry expansion announcements and United States Bureau of Industry and Security semiconductor control list revisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Integrated 3D Radar Market
Communication Navigation & Surveillance
Through the Wall Radar Market
Communication Navigation & Surveillance
Over the Horizon Radar Market
Communication Navigation & Surveillance
Surface Radars Market
Communication Navigation & Surveillance
Drone Transponders Market
Communication Navigation & Surveillance
Dual Axis Gyro Stabilized Platform Market
Communication Navigation & Surveillance
Missile Guidance Radar Market
Communication Navigation & Surveillance
Global Navigation Satellite System (GNSS) Market
Communication Navigation & Surveillance
Global Tactical Headset Market
Communication Navigation & Surveillance
Russia Autonomous Navigation Market
Communication Navigation & Surveillance
Naval Navigation and Communication Systems Market
Communication Navigation & Surveillance
Man Portable Communication Systems Market
Communication Navigation & Surveillance
Man-Portable Military Communication Systems Market
Communication Navigation & Surveillance
Military GNSS Anti-Jamming Systems Market
Communication Navigation & Surveillance
Inertial Navigation System Market
Communication Navigation & Surveillance
Infrared Search and Track (IRST) System Market