
 Russia Fertilizers Market | 2026-2036
Russia Fertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Fertilizers Market Analytics
Blended NPK formulations in bulk-ship configurations is realigning procurement patterns among Black Sea port buyers. PhosAgro Group of Companies leverages its Apatit mine-to-port pipeline to dominate phosphate-based output. EuroChem Group sustains backward integration into ammonia and urea through its Novomoskovsk and Nevinnomyssk complexes. Uralkali anchors global potash supply from its Berezniki and Solikamsk operations, competing on rail-to-port logistics scale.
Russia fertilizers encompass nitrogen, phosphate, and potash compounds manufactured through Haber-Bosch ammonia synthesis, sulfuric acid treatment of phosphate rock, and underground potash solution mining, with formulations calibrated to N-P-K ratios for specific crop yield targets. The product type split shows urea commanding volume leadership in grain belt applications, while potash retains premium positioning for soil potassium replenishment. Application patterns reveal agricultural use overwhelming horticultural and ornamental channels, though greenhouse vegetable producers in Lipetsk and Volgograd oblasts are expanding water-soluble specialty uptake.
Russia's Technical Regulation on Safety of Chemical Products and GOST standards administered by Rosstandart govern fertilizer composition labeling and heavy metal limits, while the Ministry of Agriculture's soil monitoring directives shape regional nutrient prescription requirements. The Federal Antimonopoly Service scrutinizes export quota allocations and domestic price stabilization mechanisms, constraining producer pricing autonomy during spring planting windows. Stakeholders must track how Black Sea logistics corridors and evolving EU border carbon adjustment protocols reshape competitive access to traditional export destinations.
Market Dynamics
The Ministry of Agriculture's mineral fertilizer production subsidy framework is redirecting capital toward domestic nitrogen capacity expansion while wheat and barley producers across the Central Black Earth region intensify compound fertilizer application rates to combat accelerating soil depletion.
Growth Catalysts
- Soil Depletion Intensification:Wheat and barley producers across the Central Black Earth region are expanding compound fertilizer application rates as nutrient exhaustion accelerates, pulling volume demand upward.
- Mineral Fertilizer Production Subsidy Framework:The Ministry of Agriculture's subsidy mechanism is redirecting investment toward domestic nitrogen capacity, compressing import dependency.
- Large-Scale Agricultural Holding Consolidation:Procurement concentration in Krasnodar Krai and Rostov Oblast is generating bulk-volume contracts that stabilize producer offtake commitments.
Market Restraints
- Natural Gas Feedstock Volatility:Ammonia synthesis operations face input cost instability as natural gas pricing fluctuates, compressing nitrogen fertilizer margin structures.
- Black Sea Logistics Corridor Concentration:Export dependency on constrained port capacity creates bottleneck risk for phosphate and potash rail-to-port movements.
- EU Border Carbon Adjustment Protocol Exposure:Evolving carbon border mechanisms threaten competitive access to traditional European export destinations for Russian fertilizer exporters.
Strategic Opportunities
- Greenhouse Vegetable Specialty Formulation Penetration:Water-soluble fertilizer uptake is expanding among protected-culture producers in Lipetsk and Volgograd oblasts, opening premium pricing tiers.
- Domestic Price Stabilization Mechanism Alignment:The Federal Antimonopoly Service's spring planting window interventions create compliant supply-contracting opportunities for producers.
- Blended NPK Bulk-Ship Configuration Adoption:Black Sea port buyers are realigning toward consolidated procurement patterns that favor integrated mine-to-port operators.
Industry Challenges
- GOST Standard Compliance Complexity:Rosstandart-administered Technical Regulation on Safety of Chemical Products imposes heavy metal limit testing burdens that extend certification timelines.
- Export Quota Allocation Uncertainty:Federal Antimonopoly Service scrutiny of quota distributions constrains producer pricing autonomy and demand forecasting reliability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Fertilizers Market |
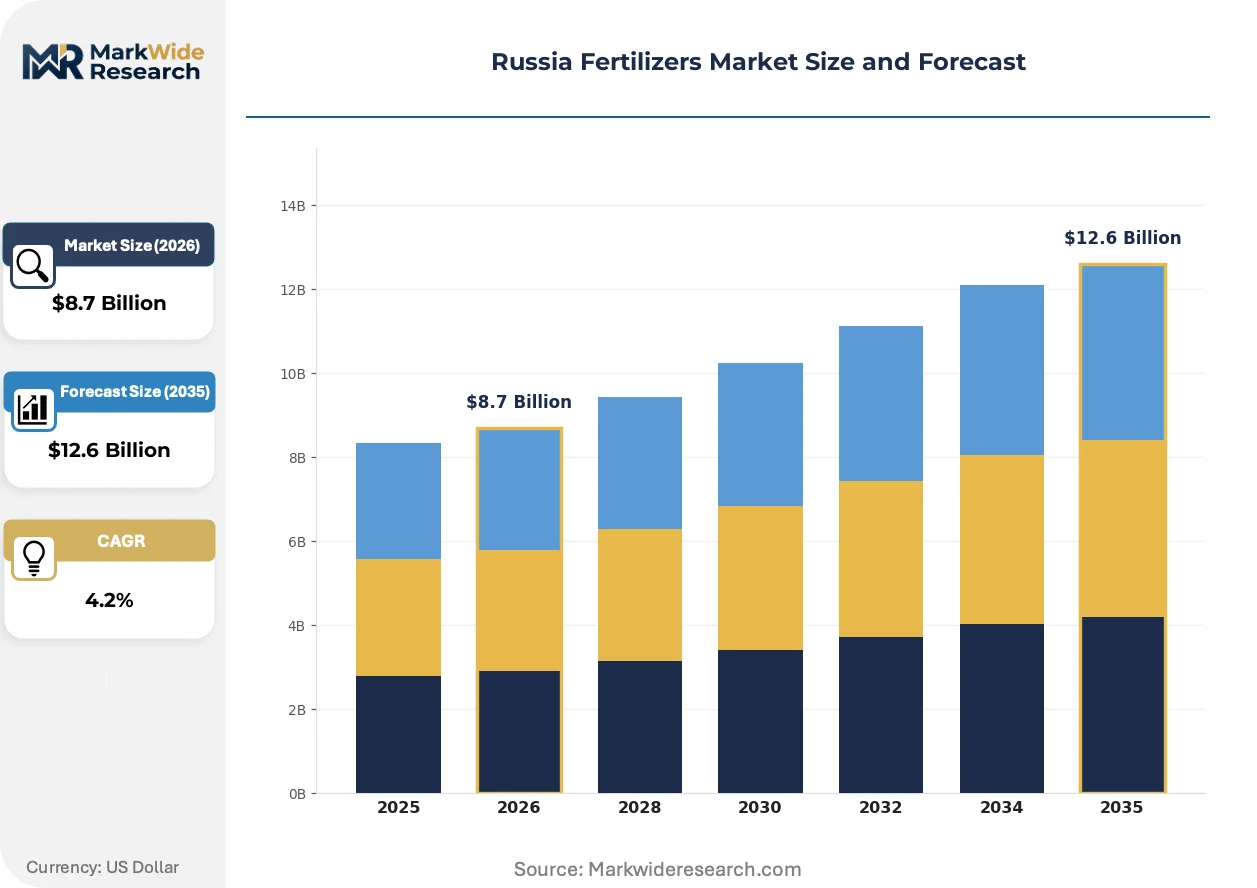
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.6 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urea, Ammonium Nitrate, Phosphate, Potash Application: Agricultural, Horticultural, Turf, Ornamental End User: Farmers, Agricultural Cooperatives, Retailers, Distributors Distribution Channel: Online, Wholesale, Direct Sales, Retail |
| Companies Covered | PhosAgro Group of Companies, EuroChem Group, Uralkali, Acron Group, Yara International ASA, Uralchem, KuibyshevAzot PJSC, Grupa Azoty S.A., ICL Group Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Fertilizers Market Evolving Landscape
Digital soil monitoring and precision application technologies are reshaping nutrient prescription workflows across Russian agricultural holdings, compressing traditional blanket-application models while elevating formulation specificity requirements.
Controlled-release fertilizer coating technology is converging with variable-rate application systems. Large-scale holdings in Krasnodar Krai are piloting GPS-guided spreaders calibrated to real-time soil sensor data. This convergence is compressing per-hectare nutrient waste while locking in multi-year supply contracts with integrated formulation suppliers.
Rosstandart's enforcement of updated GOST standards for chemical product safety is tightening heavy metal limit protocols. Fertilizer blenders must now reconfigure production lines to meet stricter cadmium and arsenic thresholds. Small regional compounders in Rostov Oblast face disproportionate retrofit costs compared to integrated miners with captive laboratory infrastructure.
Consolidated procurement through agricultural holding headquarters is displacing distributor-mediated purchasing. Black Earth region grain producers now contract directly with Apatit mine-linked blenders, stripping margin from independent traders. This disintermediation concentrates volume commitments among vertically integrated suppliers while compressing working capital cycles for remaining intermediaries.
Russia Fertilizers Market Segmentation
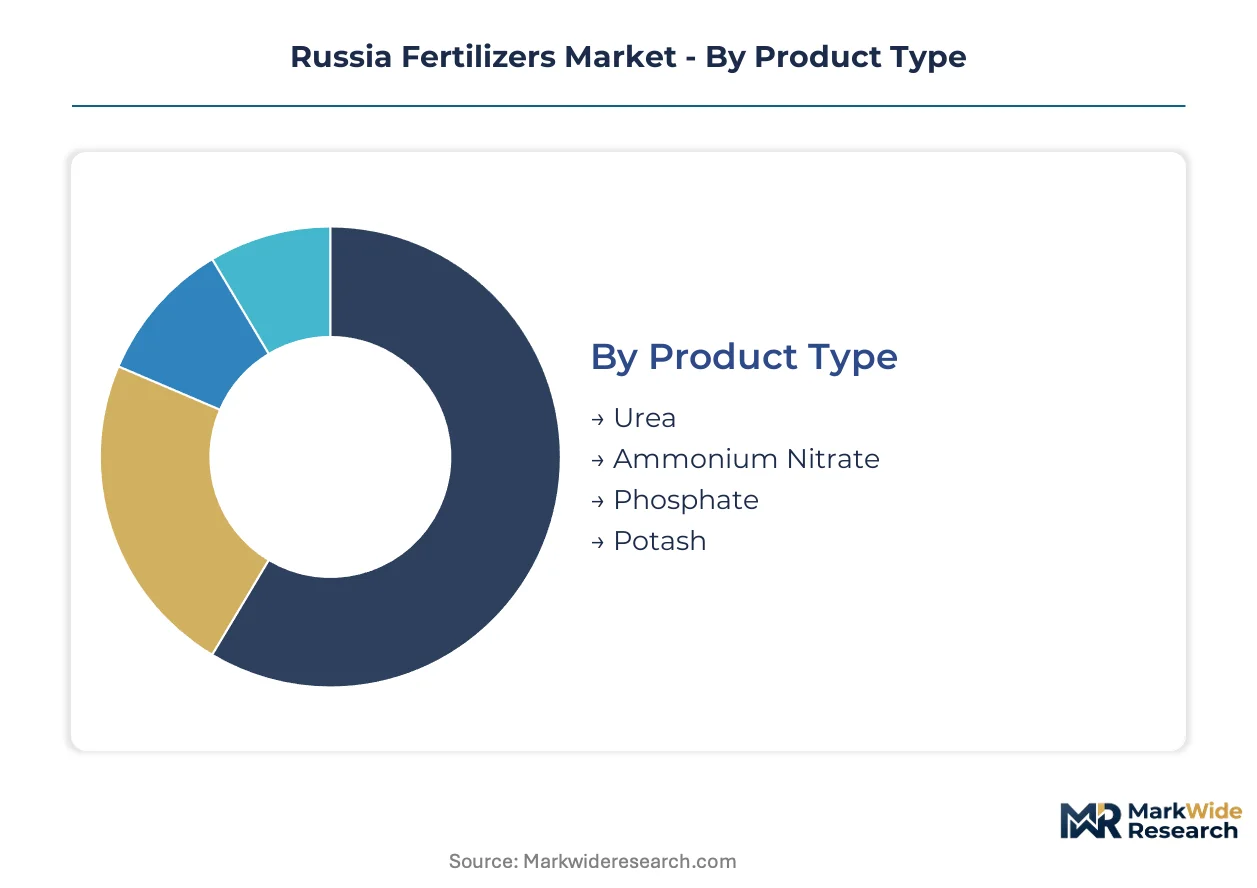
Russian fertilizer demand fragments across product chemistry, crop application, and procurement channel, with each dimension carrying distinct margin structures and logistics requirements. Understanding these splits reveals where volume concentrates versus where premium pricing endures.
Product Type:
Urea dominates tonnage through grain belt demand, while potash commands premium positioning through soil replenishment cycles and export parity pricing.
- Urea:Synthesized via Haber-Bosch ammonia conversion, this nitrogen compound delivers 46% N content optimized for wheat and barley yield response. Central Black Earth region holdings in Voronezh and Kursk oblasts are expanding application rates as soil organic matter depletion accelerates, pulling volume through domestic blenders.
- Potash:Mined via solution extraction from Berezniki and Solikamsk deposits, potassium chloride formulations address sulfur-deficient soils with 60-62% K2O grades. Rail-to-port logistics scale at Uralkali's operations anchors global supply competitiveness, though Black Sea corridor bottlenecks constrain shipment scheduling flexibility.
- Ammonium Nitrate:Dual-nutrient formulation combining nitrogen with calcium or magnesium variants for specific soil pH correction.
- Phosphate:Apatite concentrate from Murmansk Oblast feeds superphosphate and NPK compound production through sulfuric acid treatment circuits.
Today's leader: Urea. Tomorrow's challenger: Potash.
Application:
Field-scale grain production absorbs the dominant share, though protected-culture specialization opens formulation premiumization pathways.
- Agricultural:Open-field cereal and oilseed cultivation across Krasnodar Krai and Rostov Oblast drives bulk compound fertilizer consumption. Large-scale holdings consolidate procurement through direct mine-linked contracts, stripping distributor margins while locking in multi-year offtake commitments.
- Horticultural:Greenhouse vegetable producers in Lipetsk and Volgograd oblasts are expanding water-soluble specialty uptake for drip irrigation systems. Precision nutrient delivery requirements elevate formulation specificity and justify three-tier pricing stratification across premium, standard, and economy grades.
- Turf:Sports field and golf course maintenance generates seasonal demand concentrated in Moscow and St. Petersburg metropolitan zones.
- Ornamental:Nursery and landscape applications remain fragmented across regional garden center networks with limited volume concentration.
Agricultural tonnage anchors producer viability. Horticultural specialization delivers the steepest expansion trajectory.
End User:
Procurement authority is consolidating upward from individual farms toward cooperative and holding-level headquarters, reshaping sales force deployment.
- Farmers:Small and mid-scale operators in Saratov and Penza oblasts purchase through regional distributor networks with seasonal credit terms. Rosstandart-administered GOST compliance verification extends their procurement cycles compared to integrated buyers with captive laboratory infrastructure.
- Agricultural Cooperatives:Consolidated purchasing entities in Stavropol Krai aggregate member demand into bulk-ship configurations that qualify for blended NPK volume discounts. Their headquarters-level contracting displaces traditional trader intermediation.
- Retailers:Regional agrochemical dealers maintain last-mile inventory positioning for cash-and-carry smallholder demand.
- Distributors:Independent traders face margin compression as direct mine-to-farm relationships proliferate across the Black Earth zone.
Cooperative procurement is accelerating fastest. Independent distributor relevance is compressing.
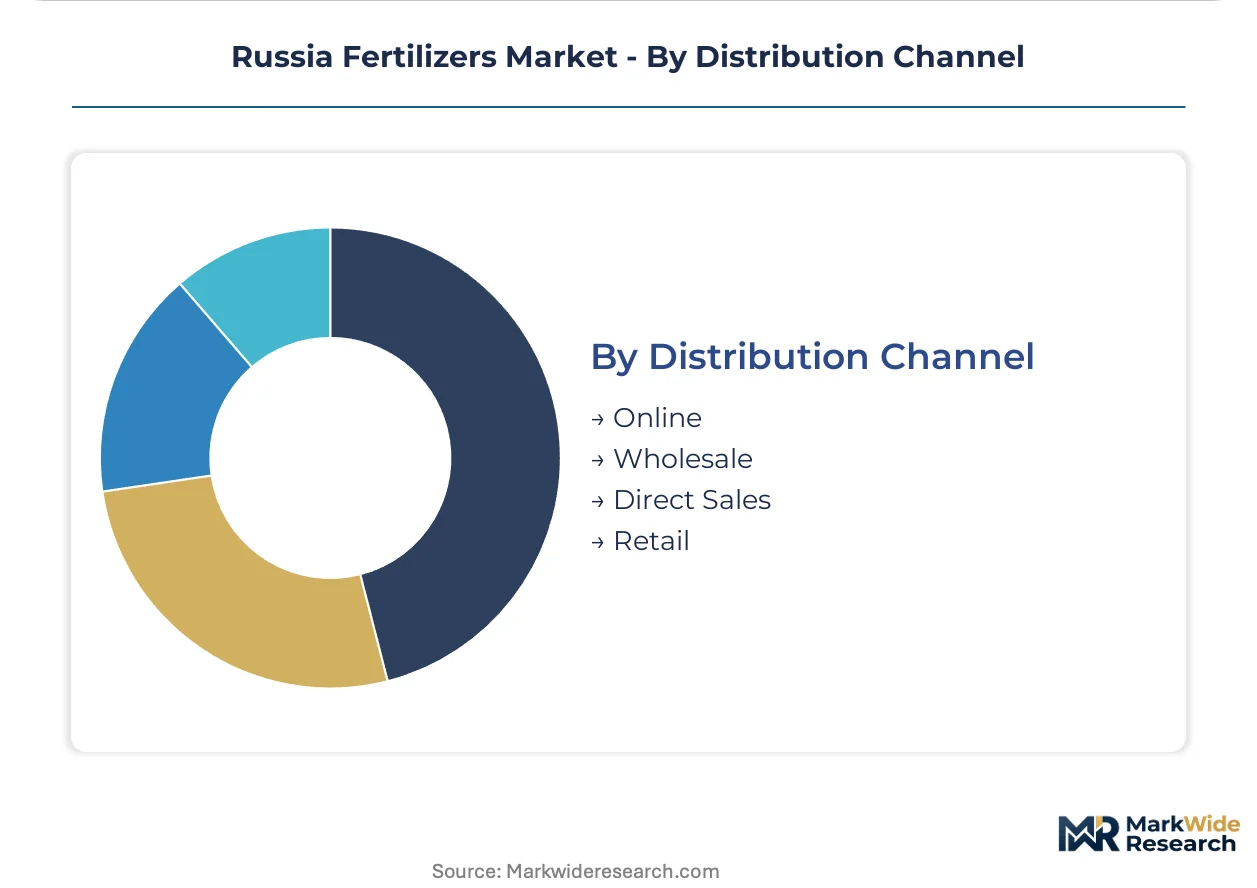
Distribution Channel:
Physical logistics infrastructure dominates, though digital platforms are penetrating spot-market procurement for specialty formulations.
- Wholesale:Bulk railcar and vessel shipments through Novorossiysk and Taman port complexes handle phosphate and potash export volumes alongside domestic redistribution. Federal Antimonopoly Service export quota allocations constrain producer pricing autonomy during spring planting windows.
- Direct Sales:Vertically integrated miners including PhosAgro and EuroChem contract directly with agricultural holding procurement departments, eliminating intermediary working capital requirements and enabling formulation customization.
- Online:E-commerce platforms are gaining traction for water-soluble specialty products and precision application equipment accessories.
- Retail:Branded packaged goods through garden center and agro-dealer networks serve small-scale horticultural and ornamental demand.
Wholesale tonnage commands producer attention. Direct sales relationships are displacing traditional channel structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Russia's fertilizer industry traces its modern scale to Soviet-era industrialization of the Volga-Ural petrochemical corridor and the 1930s development of the Berezniki potash basin. This legacy established concentrated production clusters that still define competitive geography today.
Central Black Earth Region
Wheat and barley producers in Voronezh and Kursk oblasts are expanding compound fertilizer application rates to combat accelerating soil organic matter depletion. The Ministry of Agriculture's mineral fertilizer production subsidy framework directs investment toward domestic nitrogen capacity expansion here. Large-scale agricultural holdings in Belgorod Oblast consolidate procurement through direct mine-linked contracts.
Krasnodar Krai
Open-field cereal and oilseed cultivation drives bulk compound fertilizer consumption across this southern grain belt. Federal Antimonopoly Service export quota allocations constrain producer pricing autonomy during spring planting windows. Novorossiysk port complexes handle phosphate redistribution alongside domestic offtake.
Rostov Oblast
Procurement concentration among agricultural cooperatives generates bulk-volume contracts that stabilize producer commitments. Small regional compounders face disproportionate GOST standard retrofit costs compared to integrated miners. The region's distributor networks are losing relevance as direct mine-to-farm relationships proliferate.
Volga Region
Greenhouse vegetable producers in Lipetsk and Volgograd oblasts are expanding water-soluble specialty uptake for drip irrigation systems. Rosstandart-administered Technical Regulation on Safety of Chemical Products governs heavy metal limit compliance here. Precision nutrient delivery requirements elevate formulation specificity.
Ural Federal District
Potash solution mining from Berezniki and Solikamsk deposits anchors global supply competitiveness through rail-to-port logistics scale. Black Sea corridor bottlenecks constrain shipment scheduling flexibility for export volumes. The region's captive laboratory infrastructure supports faster GOST certification timelines than downstream compounders.
Russia Fertilizers Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the backward integration spectrum, with mine-to-port operators capturing value that blenders cannot access. The vendor base organizes into three tiers: integrated miners with captive feedstock, mid-scale compounders with regional distribution, and trading intermediaries facing disintermediation pressure. Two dominant competitive moves are reshaping positioning: direct sales contracting with agricultural holding headquarters, and blended NPK bulk-ship configuration adoption at Black Sea ports.
Among Russia-based integrated producers, PhosAgro Group of Companies, EuroChem Group, and Uralkali occupy positions defined by their captive mineral reserves and port-linked logistics infrastructure. These entities exemplify the mine-to-port archetype that is displacing traditional distributor-mediated procurement across the Black Earth zone. Their scale-backed compliance capabilities with Rosstandart-administered GOST standards create separation from smaller regional compounders facing certification timeline extensions.
| Leading Market Players |
|---|
| PhosAgro Group of Companies |
| EuroChem Group |
| Uralkali |
| Acron Group |
| Yara International ASA |
| Uralchem |
| KuibyshevAzot PJSC |
| Grupa Azoty S.A. |
| ICL Group Ltd |
| Others |
Value Network & Pricing Analysis
Natural gas benchmark pricing at the TTF hub cascades through Russian ammonia synthesis operations into three-tier fertilizer pricing stratification across premium, standard, and economy levels, with integrated miners capturing margin that downstream compounders cannot access due to feedstock cost pass-through limitations.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between agricultural holding headquarters and mine-linked blenders, with price differentiation driven by volume scale and GOST certification grade. Premium tiers attach to water-soluble specialty formulations for greenhouse producers, while economy tiers serve bulk grain belt urea demand. Cost compression in nitrogen fertilizer margins is intensifying because natural gas feedstock volatility strips pricing power from non-integrated compounders. Smallholder farmers in Saratov and Penza oblasts exhibit highest price sensitivity due to seasonal credit constraints, whereas Krasnodar Krai holdings lock in multi-year commitments with lowest sensitivity.
Supply Chain Analysis
Rosstandart-administered GOST certification gating extends procurement cycles for regional compounders lacking captive laboratory infrastructure, creating compliance-driven supply segmentation. Production concentrates in Russia's Volga-Ural corridor and Ural Federal District, with phosphate rock drawn from Murmansk Oblast apatite deposits and potash sourced from Berezniki and Solikamsk solution mining operations. Single-source vulnerability around Black Sea port capacity constrains export shipment scheduling flexibility for rail-to-port movements. Distribution runs through wholesale bulk railcar and vessel configurations at Novorossiysk and Taman complexes, with direct sales relationships displacing traditional distributor mediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia fertilizers function as a geographic-arbitrage play where domestic natural gas feedstock costs undercut European nitrogen production economics, widening margin capture for integrated miners versus import-dependent competitors.
For Market Incumbents: Anticipate Federal Antimonopoly Service export quota reallocations by securing spring planting window supply contracts with agricultural holding procurement departments. Deepen backward integration into ammonia capacity through Ministry of Agriculture subsidy framework alignment, and invest in captive GOST certification laboratories to compress compliance timelines versus regional compounders facing Rosstandart testing burdens.
For New Entrants and Emerging Players: Enter via water-soluble specialty formulation penetration for greenhouse vegetable producers in Lipetsk and Volgograd oblasts, where precision nutrient delivery requirements justify premium pricing tiers. White-space exists in digital soil monitoring integration services and GPS-guided spreader calibration partnerships with Krasnodar Krai holdings. A technical sales force targeting cooperative procurement headquarters offers the cleanest go-to-market angle.
For Investors and Strategic Acquirers: Consolidation pressure builds where small regional compounders face disproportionate GOST retrofit costs compared to integrated miners with captive infrastructure. Long-term viability favors mine-to-port operators with rail-linked logistics scale and Black Sea port access. Watch for Federal Antimonopoly Service intervention intensity in spring pricing windows as the inflection signal for regulatory risk repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ammonia Capacity | Ministry of Agriculture subsidies compress import dependency for nitrogen fertilizer producers. |
| Long-term Supply Agreement with Agricultural Holdings | Direct mine-to-farm contracting strips distributor margins while locking in volume commitments. |
| Green Manufacturing Transition | EU Border Carbon Adjustment Protocol exposure threatens European export competitiveness for carbon-intensive production. |
| Joint Venture for Water-Soluble Specialty Formulations | Greenhouse producers in Lipetsk and Volgograd oblasts expand drip irrigation system uptake. |
| Capacity Expansion in Ural Federal District | Berezniki and Solikamsk potash deposits anchor global supply through rail-to-port logistics scale. |
Research Methodology
Direct dialogue with plant managers at nitrogen synthesis complexes, procurement leads at agricultural holding headquarters, distribution channel partners in Rostov Oblast, and technical R&D directors at compound fertilizer blenders grounded qualitative insights. Secondary validation drew from customs and trade data, SEC filings of listed fertilizer producers, Rosstandart GOST standard documentation, and Ministry of Agriculture subsidy disbursement records. Bottom-up and top-down triangulation cross-checked volume estimates against production capacity disclosures and regional consumption surveys.
Bottom-up modeling of urea, potash, and phosphate compound demand across agricultural, horticultural, and ornamental applications combined with top-down macroeconomic elasticity assumptions across the projection horizon. Segmentation dimensions included product chemistry tier, crop application intensity, procurement channel structure, and regional soil depletion indices. CAGRs were derived from trend extrapolation of application rate expansion and holding-level consolidation patterns, with natural gas price elasticity and Black Sea logistics throughput serving as key forecast inputs.
Inputs from producer facility disclosures and agricultural holding procurement records were available through the study window; gaps in real-time export quota allocation decisions and Federal Antimonopoly Service intervention timing introduce uncertainty bands around spring pricing season forecasts. A model refresh is warranted upon material change in EU Border Carbon Adjustment Protocol implementation timelines or Black Sea corridor shipping capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Fertilizer Tester Market
Fertilizers
Asia-Pacific Organic Fertilizer Market
Fertilizers
Potash Market
Fertilizers
South America Specialty Fertilizer Market
Fertilizers
Asia-Pacific Micronutrient Fertilizer Market
Fertilizers
Southeast Asia Fertilizer Market
Fertilizers
Phosphoric Fertilizer Market
Fertilizers
Biochar Fertilizer Market
Fertilizers
Vietnam Fertilizers Market
Fertilizers
Global Potash Fertilizer Market
Fertilizers
High-Brix Fruit Quality Enhancement Fertilizer Market
Fertilizers
Global NPK Fertilizer Market
Fertilizers
Africa Specialty Fertilizer Market
Fertilizers
Calcium Ammonium Nitrate Market
Fertilizers
Brazil Micronutrient Fertilizer Market
Fertilizers
Catalyst Fertilizers Market