
 Africa Potash Fertilizer Market | 2026-2036
Africa Potash Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Potash Fertilizer Market Outlook
ISO 8157 fertilizer terminology compliance is collapsing as a baseline filter, forcing suppliers to recertify under regionally adapted protocols. OCP Group leverages its Moroccan phosphate-potash integration to control input costs across North African supply corridors. Yara International sustains technical advisory networks that anchor premium pricing in East African commercial farming zones. Kore Potash Plc competes through pre-feasibility stage vertical control over Congolese sylvinite deposits.
Potash fertilizer comprises potassium-bearing salts—primarily potassium chloride (KCl) with K₂O equivalence typically graded at 60-62%—extracted through solution mining or conventional underground methods and applied to correct soil potassium deficiency that limits carbohydrate transport and drought resistance in plants. Granular formulations dominate volume flows due to mechanical spreading compatibility with smallholder equipment, while controlled-release variants capture margin pools from precision horticulture operators in South African and Kenyan export sectors. Liquid potash occupies a narrow but expanding niche among drip-irrigated vineyard and orchard systems where fertigation integration reduces labor intensity.
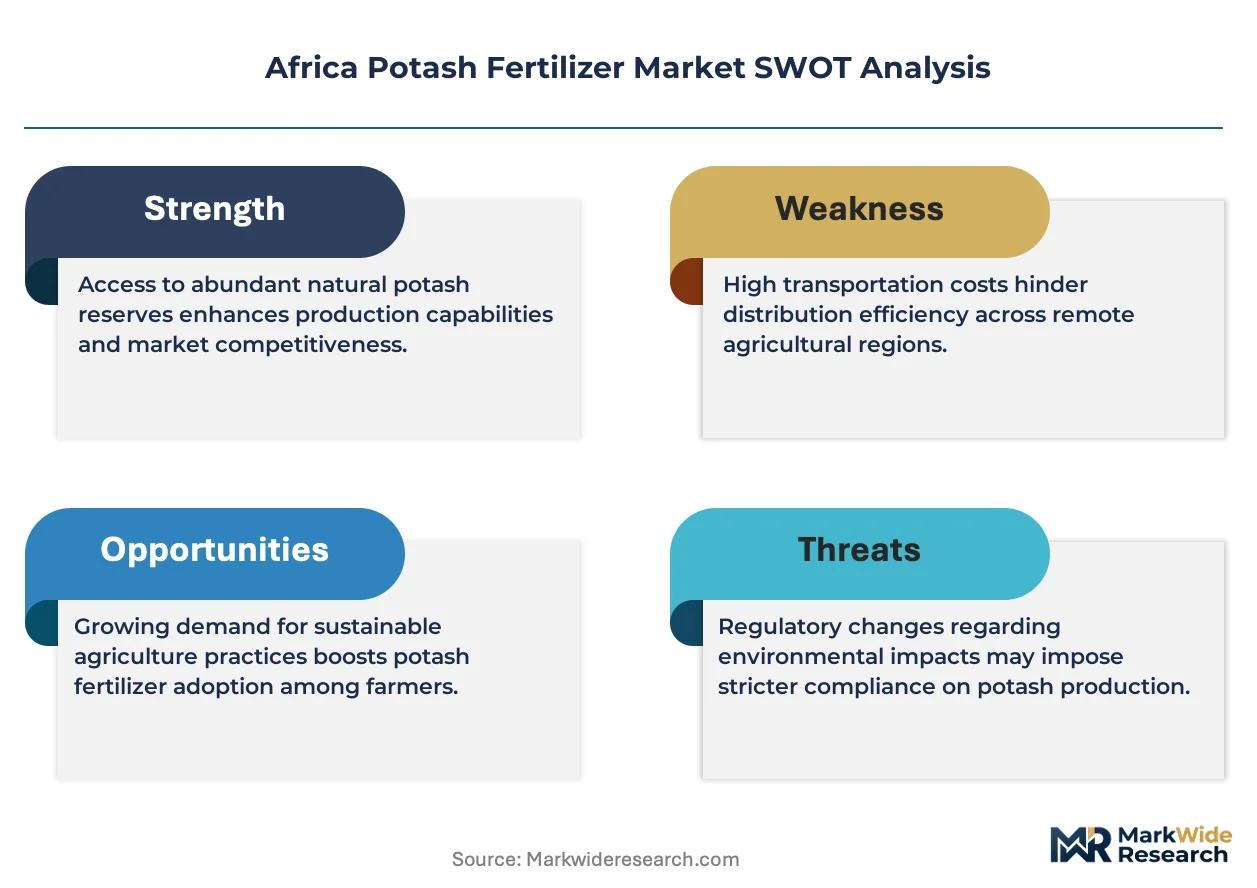
Nigeria's Standards Organisation regulates imported fertilizer quality through mandatory NPK verification, while South Africa's Department of Agriculture enforces Fertilizers, Farm Feeds, Seeds and Remedies Act labeling requirements that restrict uncertified product entry. The African Union's fertilizer bulk procurement framework is reshaping cross-border tender specifications, compelling distributors to align with harmonized nutrient content declarations. Stakeholders must monitor how the AfCFTA rules of origin evolve for blended versus straight potash classifications to preserve margin structures on intra-African trade lanes.
Market Dynamics
Soil potassium depletion in East African highland corridors is accelerating application rate expansion among smallholder grain producers, while the African Union's fertilizer subsidy harmonization redirects procurement flows toward certified granular grades and away from uncertified bulk imports.
Growth Catalysts
- Comprehensive Africa Agriculture Development Program subsidy harmonization:The African Union framework consolidates national tender specifications, creating volume aggregation that lowers per-unit procurement costs for Ethiopian and Nigerian distributors.
- Maize-teff rotation intensity:Highland farming corridors in Ethiopia exhaust potassium reserves faster than replacement rates, forcing systematic potash integration into crop management protocols.
- Granular formulation compatibility:Mechanical spreading equipment prevalent among smallholders favors certified granular grades over powder alternatives, locking in product form preferences.
Market Restraints
- Input cost volatility:Natural gas prices govern ammonia synthesis economics, transmitting cost instability through nitrogen-phosphate-potash composite fertilizer pricing.
- Supply concentration risk:Moroccan phosphate-potash integration controls North African supply corridors, limiting alternative sourcing options for landlocked Sahelian markets.
- Regulatory friction:Nigeria's Standards Organisation mandates NPK verification delays, creating customs bottlenecks that extend inventory cycles for importers.
Strategic Opportunities
- Underpenetrated Congo Basin:Kore Potash Plc's sylvinite deposit development offers captive supply integration for distributors seeking upstream control over Central African corridors.
- Drip-irrigation convergence:Liquid potash formulations paired with vineyard fertigation systems in South African export horticulture reduce labor intensity while commanding margin premiums.
- AfCFTA rules of origin evolution:Harmonized nutrient content declarations under the African Continental Free Trade Area create arbitrage potential for intra-African blended versus straight potash classifications.
Industry Challenges
- Certification timeline compression:ISO 8157 fertilizer terminology recertification under regionally adapted protocols forces suppliers to rebuild compliance documentation from baseline.
- Soil testing capability scarcity:Agronomic extension services lack portable potassium deficiency diagnostic equipment, delaying prescription accuracy for smallholder advisory networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Potash Fertilizer Market |
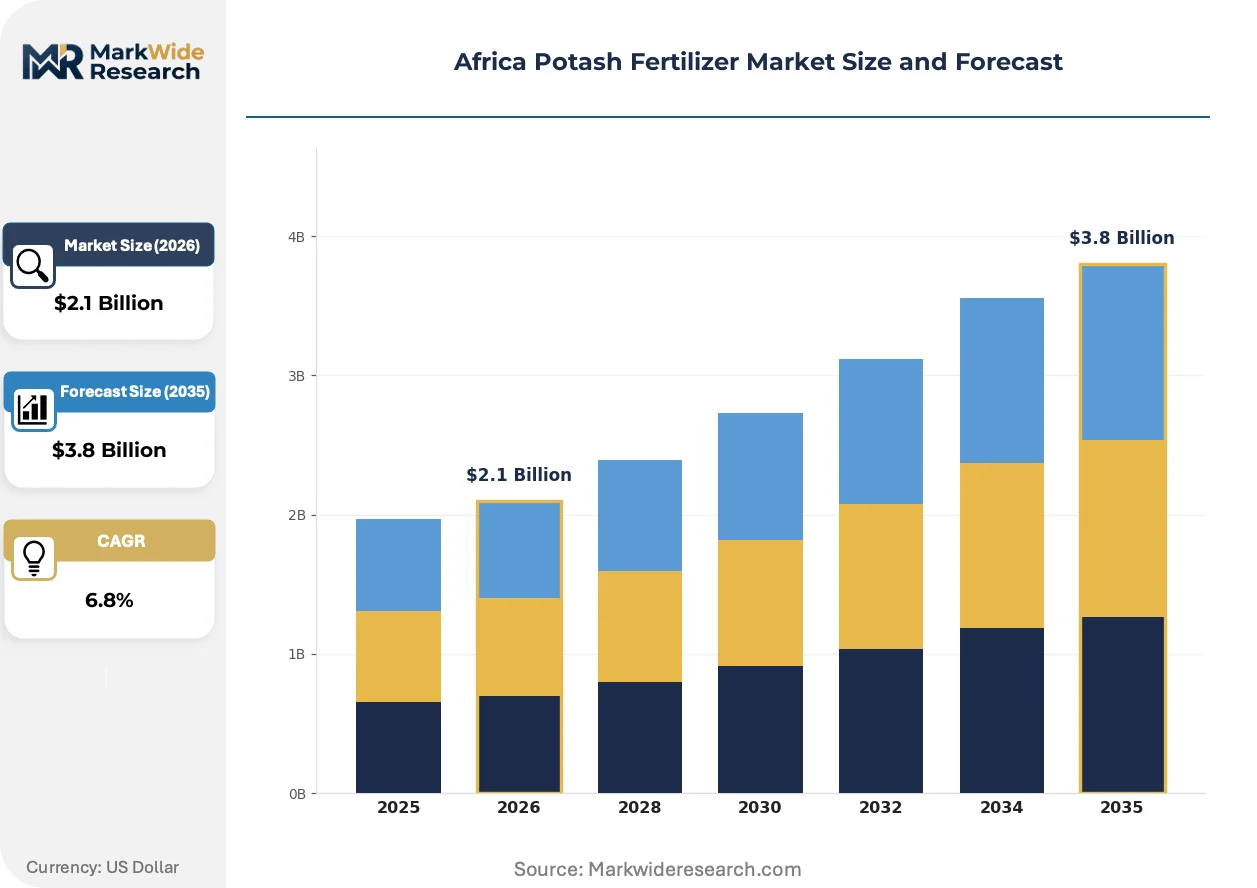
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Liquid, Controlled-Release, Soluble End User: Agricultural Producers, Distributors, Retailers, Food Processors Application: Crop Production, Soil Amendment, Horticulture, Pasture Management Packaging Type: Bags, Bulk, Drums, Containers |
| Companies Covered | K+S Aktiengesellschaft, ICL Group Ltd, Yara International, UPL, Kore Potash Plc, The Mosaic Company, OCP Group, Coromandel International Ltd, Millennial Potash, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Potash Fertilizer Market Strategic Shifts
Controlled-release potassium formulations and precision application technologies are reshaping product-mix economics, while regulatory convergence around harmonized nutrient declarations alters competitive positioning across African supply corridors.
Polymer-coated potash granules enable synchronized nutrient release matching crop uptake curves, reducing leaching losses in high-rainfall East African highlands. South African and Kenyan export horticulture operators adopt these formulations fastest, paying premiums for yield consistency. Standard granular grades are supplanting uncoated alternatives in premium contract negotiations, compressing margin pools for commodity suppliers.
The African Union's fertilizer bulk procurement framework mandates cross-border tender alignment with harmonized nutrient content declarations. Distributors must reconfigure labeling and testing protocols to satisfy multiple national regulators simultaneously. Ethiopian and Nigerian import channels face the steepest compliance adaptation costs as verification systems integrate.
Smallholder cooperatives in Ethiopia and Nigeria aggregate purchase volumes through digital platform coordination, consolidating formerly fragmented procurement into block tenders. Traditional distributor networks lose intermediation value as cooperative buying committees negotiate direct manufacturer relationships. This channel disintermediation concentrates most visibly in East African highland farming corridors where mobile penetration enables platform adoption.
Africa Potash Fertilizer Market Segmentation
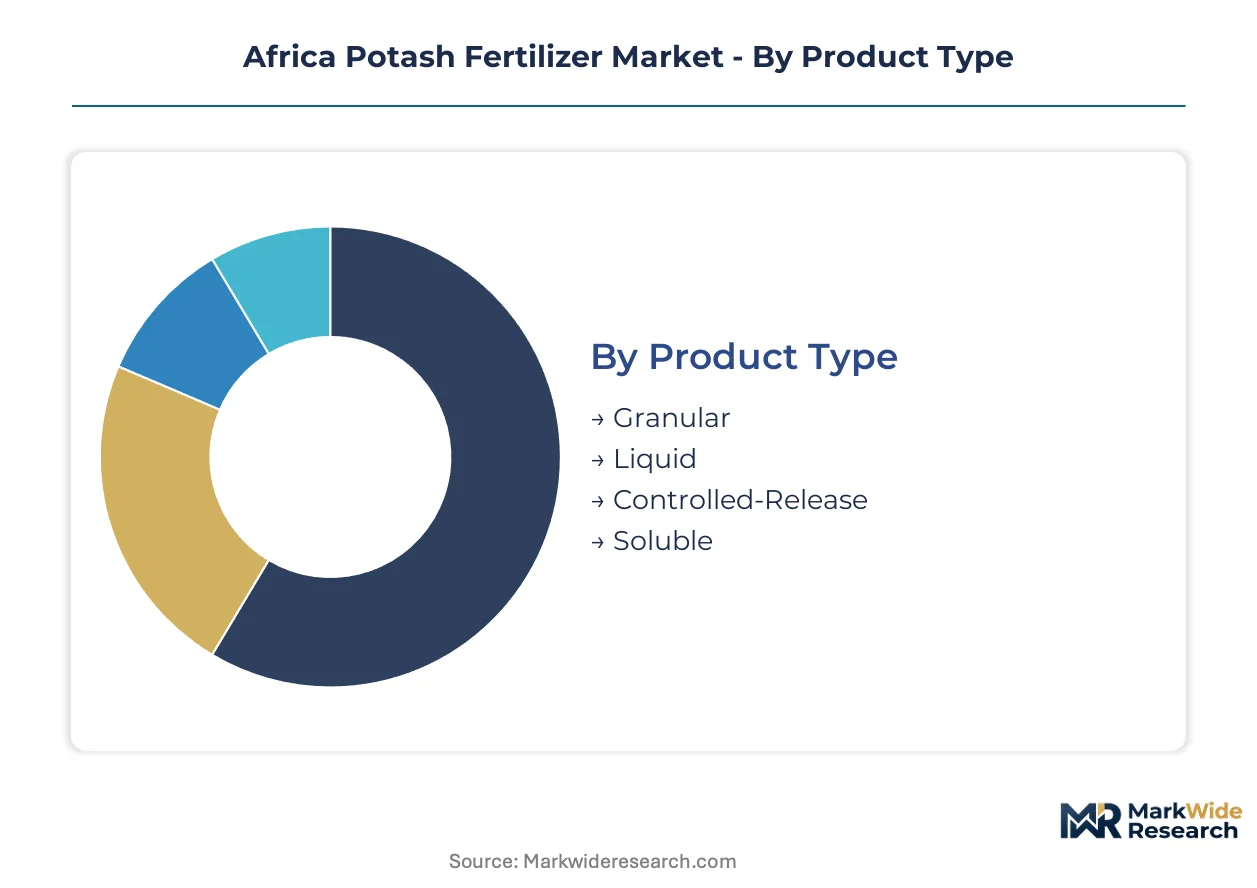
Product form, application method, and packaging configuration determine logistics costs and agronomic efficacy across African potash supply chains. Segmentation choices directly influence procurement patterns under subsidy harmonization frameworks and smallholder equipment constraints.
Product Type:
Granular formulations face substitution pressure from liquid alternatives in irrigated horticulture zones, while controlled-release variants displace standard grades in premium export agriculture.
- Granular:Mechanical spreading compatibility dominates smallholder adoption in Ethiopian and Nigerian grain corridors. Highland maize-teff rotations exhaust potassium reserves fastest here, locking in granular preference for broadcast application equipment.
- Liquid:Fertigation integration reduces labor intensity in South African vineyard and orchard drip systems. Kenyan export horticulture operators adopt these formulations for precision nutrient delivery, though infrastructure requirements limit penetration elsewhere.
- Controlled-Release:Polymer-coated granules synchronize nutrient release with crop uptake curves in high-rainfall East African highlands.
- Soluble:Rapid dissolution suits greenhouse and protected cultivation systems in Moroccan and Egyptian intensive agriculture zones.
Granular retains volume leadership; liquid holds the steepest expansion curve.
End User:
Cost tier stratification separates subsidized bulk procurement from premium advisory-linked sales, with distributor consolidation reshaping channel economics.
- Agricultural Producers:Smallholder cooperatives in Ethiopia and Nigeria aggregate purchase volumes through digital platform coordination, consolidating formerly fragmented procurement into block tenders that bypass traditional intermediaries.
- Distributors:Cross-border tender alignment under African Union harmonization mandates reconfigures labeling and testing protocols to satisfy multiple national regulators simultaneously.
- Retailers:Inventory cycles extend due to Nigeria's Standards Organisation NPK verification delays at port entry.
- Food Processors:Backward integration into contract farming drives direct fertilizer procurement for supply security in Kenyan and South African export supply chains.
Agricultural Producers dominate volume absorption; Distributors face the most acute margin compression from channel disintermediation.
Application:
Application method segmentation tracks soil depletion intensity across farming systems, with potassium correction priorities varying by crop carbohydrate transport demands.
- Crop Production:Maize-dominated systems in Nigerian savanna zones require systematic potash integration as intensification depletes native soil reserves below critical thresholds for yield maintenance.
- Soil Amendment:Corrective applications concentrate in East African highland corridors where historical nutrient mining exceeds replacement rates.
- Horticulture:South African and Kenyan export sectors pay premiums for yield consistency through controlled-release formulations.
- Pasture Management:Livestock grazing systems in Sahelian zones apply potash for forage quality improvement, though volume remains constrained by extensive production economics.
Crop Production anchors volume demand; Horticulture generates the highest margin per ton applied.
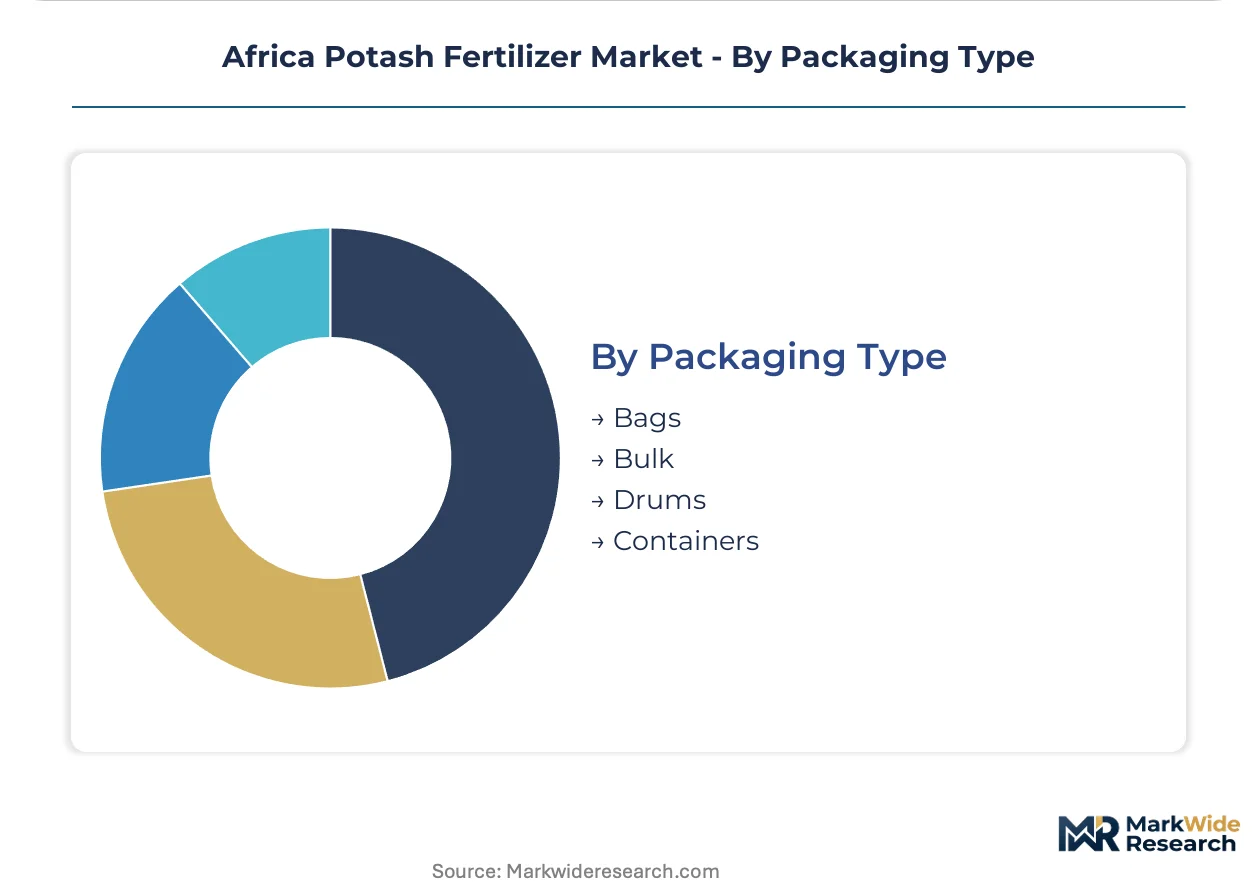
Packaging Type:
Packaging configuration determines last-mile distribution economics, with bulk formats favored by subsidy programs and unitized packaging serving fragmented retail channels.
- Bags:50kg woven polypropylene dominates smallholder retail in Ethiopian highland cooperatives, matching manual handling capacity and storage constraints.
- Bulk:Loose shipment formats minimize per-unit logistics costs for Nigerian and Kenyan distributor warehouse replenishment under consolidated tender awards.
- Drums:Liquid potash containment for South African vineyard fertigation systems requires chemical-resistant sealing.
- Containers:Intermediate bulk units serve medium-scale commercial farms in Moroccan phosphate-potash integrated supply corridors.
Bulk captures procurement volume under harmonized subsidy frameworks; Bags maintain retail channel indispensability for cooperative distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The African Union's fertilizer subsidy harmonization under the Comprehensive Africa Agriculture Development Program redirects procurement flows toward certified granular grades, consolidating tender specifications across national borders and lowering per-unit costs for distributors in high-volume corridors.
Ethiopia
Highland maize-teff rotations exhaust potassium reserves faster than replacement rates, forcing systematic potash integration into crop management protocols. The Ethiopian Agricultural Transformation Agency coordinates input distribution through regional warehouses, reducing last-mile fragmentation. Addis Ababa anchors procurement aggregation for smallholder cooperatives adopting digital platform coordination.
Nigeria
Savanna zone intensification depletes native soil potassium below critical yield maintenance thresholds, driving corrective application expansion. The Standards Organisation mandates NPK verification at port entry, creating customs bottlenecks that extend inventory cycles for importers. Kano and Kaduna corridors concentrate distributor warehousing for northern grain belts.
South Africa
Export horticulture operators in vineyard and orchard systems pay premiums for controlled-release formulations that reduce labor intensity through fertigation integration. The Department of Agriculture enforces Fertilizers, Farm Feeds, Seeds and Remedies Act labeling requirements that restrict uncertified product entry. Western Cape precision agriculture clusters adopt liquid potash fastest among commercial farming zones.
Morocco
Phosphate-potash integration controls North African supply corridors, limiting alternative sourcing options for landlocked Sahelian markets. OCP Group leverages captive input cost advantages across integrated production networks. Casablanca-Rabat logistics hubs coordinate bulk shipment consolidation for regional re-export.
Kenya
Export horticulture supply chains drive backward integration into contract farming with direct fertilizer procurement for supply security. The national fertilizer subsidy program channels granular grades through cooperative networks in highland tea and coffee zones. Nairobi anchors technical advisory service deployment for precision application adoption.
Africa Potash Fertilizer Market Competitive Environment
Listed leaders compete with private specialists across integrated supply chain control, with publicly traded entities leveraging capital market access for capacity positioning while private operators exploit regional relationship density. The vendor base fragments across phosphate-potash integrated conglomerates, standalone potash miners, and distribution-focused intermediaries. Three archetypes dominate: upstream resource owners with captive deposit control, midstream blenders with subsidy program accreditation, and advisory-linked premium marketers with technical service networks. Capacity expansion and strategic partnerships represent the dominant competitive moves, with players securing forward offtake agreements or integrating into cooperative procurement platforms.
Within the integrated resource tier, OCP Group and The Mosaic Company exemplify phosphate-potash convergence strategies that compress input costs for North African supply corridors. Yara International occupies a position among advisory-linked premium marketers, sustaining technical networks that anchor pricing power in East African commercial zones. Kore Potash Plc sits within the upstream development archetype, representing pre-feasibility stage vertical control over Central African sylvinite deposits.
| Leading Market Players |
|---|
| K+S Aktiengesellschaft |
| ICL Group Ltd |
| Yara International |
| UPL |
| Kore Potash Plc |
| The Mosaic Company |
| OCP Group |
| Coromandel International Ltd |
| Millennial Potash |
| Others |
Value Chain & Pricing Dynamics
Moroccan phosphate-potash integration generates scale economies that compress input cost floors across North African supply corridors, simultaneously concentrating pricing power among integrated producers and forcing independent distributors to absorb margin pressure through inventory cycle extensions.
Pricing Analysis
Certification level under African Union harmonized protocols creates the primary spread between premium granular grades and uncertified bulk alternatives. Pricing stratifies across certified premium, transitional standard, and uncertified economy tiers based on ISO 8157 compliance status and cooperative procurement volume scale. Cost compression in the economy tier is intensifying because Nigerian Standards Organisation NPK verification delays extend inventory carrying costs for importers. Smallholder cooperatives in Ethiopian highland corridors exhibit the highest price sensitivity due to subsidy-dependent purchasing power, while South African export horticulture operators demonstrate the lowest sensitivity as yield consistency premiums outweigh input cost fluctuations.
Supply Chain Analysis
Morocco and Russia anchor global potash extraction capacity, with Moroccan OCP Group leveraging captive phosphate-potash integration to control North African supply corridors. Congolese sylvinite deposits and Canadian prairie solution mining operations feed from distinct geological formations with varying K₂O equivalence grades. Single-source vulnerability concentrates in Moroccan-controlled re-export hubs serving landlocked Sahelian markets. Distribution runs through regional warehouse networks coordinated by Ethiopian Agricultural Transformation Agency and Nigerian Kano-Kaduna corridor distributors, with last-mile fragmentation addressed through cooperative aggregation platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward cooperative procurement platforms as Ethiopian and Nigerian smallholder aggregators consolidate fragmented demand into block tenders, compressing traditional distributor intermediation margins.
For Market Incumbents: Consolidate advisory-linked service networks to defend premium positioning against cooperative platform disintermediation. Secure backward integration into regional warehouse infrastructure under African Union harmonized tender specifications. Invest in portable soil testing capability deployment to differentiate technical service offerings from commodity suppliers facing price erosion. For New Entrants and Emerging Players: Differentiate on liquid potash formulation specialization for South African and Kenyan drip-irrigation vineyard systems. Target the underpenetrated Congo Basin corridor through direct distributor partnerships with Kore Potash Plc offtake arrangements. Deploy digital platform coordination tools to capture cooperative procurement channel share without legacy intermediary cost structures. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among advisory-linked premium marketers with technical service networks anchored in East African commercial farming zones. Long-term viability rests on upstream resource control or subsidy program accreditation durability. Monitor AfCFTA rules of origin evolution for blended versus straight potash classifications as the primary inflection signal for intra-African trade lane margin structures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sylvinite Deposits | Kore Potash Plc's Congolese asset development secures captive supply for Central African corridor expansion. |
| Digital Platform Coordination Deployment | Cooperative procurement aggregation in Ethiopian highlands bypasses traditional distributor intermediation. |
| Controlled-Release Formulation Scale-Up | Polymer-coated granule production addresses South African export horticulture premium demand. |
| Harmonized Certification Investment | ISO 8157 recertification under African Union protocols preserves tender eligibility across national borders. |
| Fertigation System Technical Partnership | Liquid potash integration with drip-irrigation infrastructure captures Kenyan vineyard operator adoption. |
Study Parameters
Operator-level perspectives from agronomic extension officers, cooperative procurement managers, fertilizer distributor logistics heads, and regulatory compliance specialists anchored the qualitative base. Primary interview data combined with secondary validation from African Union fertilizer subsidy framework documentation, Nigerian Standards Organisation import verification records, Ethiopian Agricultural Transformation Agency distribution reports, and OCP Group integrated supply chain disclosures. Bottom-up volume aggregation across product form and application segments triangulated with top-down market sizing from customs trade flows and regional production capacity assessments.
Sensitivity analysis tested forecast robustness across natural gas price volatility scenarios and AfCFTA implementation pace variations over the projection horizon. Segmentation dimensions modeled include product type, application method, end-user category, and packaging configuration, with regional regulatory cluster differentiation across East African highland, West African savanna, and Southern African export horticulture corridors. CAGRs derived from trend extrapolation of application rate expansion in maize-teff rotation systems and subsidy program enrollment growth curves, cross-referenced with potassium deficiency diagnostic survey data and cooperative platform adoption trajectories.
Material uncertainties — subsidy program fiscal sustainability, harmonized certification timeline slippage, and sylvinite project development delays — sit outside the modeled envelope. Forecasts reflect assumptions regarding African Union procurement framework implementation pace and soil testing capability deployment rates. Recalibration cycles align with material shifts in fertilizer subsidy harmonization progress and AfCFTA rules of origin adjudication outcomes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Fertilizer Additives Market
Fertilizers
Europe Organic Fertilizer Market
Fertilizers
Chelated Micronutrient Fertilizers Market
Fertilizers
Brazil Specialty Fertilizer Market
Fertilizers
Asia Pacific Controlled Release Fertilizers Market
Fertilizers
North America Controlled Release Fertilizer Market
Fertilizers
India Specialty Fertilizer Market
Fertilizers
Polymer Coated Urea Market
Fertilizers
India Urea Market
Fertilizers
China Fertilizers Market
Fertilizers
South Africa Fertilizer Market
Fertilizers
Africa Fertilizers Market
Fertilizers
Asia-Pacific Specialty Fertilizer Market
Fertilizers
Sulphur Coated Urea Market
Fertilizers
Organic Fertilizers Market
Fertilizers
Africa Specialty Fertilizer Market