
 Germany Fertilizer Market | 2026-2036
Germany Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Fertilizer Market Insights
Agronomist workforce shortages across eastern German farming cooperatives is redrawing competitive dynamics for domestic suppliers. K+S Aktiengesellschaft anchors its position through captive potash mining in the Zechstein deposits. BASF SE leverages integrated ammonia production at Ludwigshafen to sustain cost-advantaged nitrogen output. EuroChem Group AG competes via specialized phosphate blends tailored to Brandenburg's sandy soils.
Fertilizer denotes chemically or organically derived nutrient formulations containing specified nitrogen, phosphorus, and potassium concentrations, manufactured through Haber-Bosch synthesis, acidulation, or compaction granulation to replenish soil fertility and maximize crop yield. The nitrogenous segment dominates volume flows due to continuous wheat and rapeseed demand across northern plains, while compound fertilizers capture margin pools through precision-blended NPK ratios for horticultural greenhouse operators. Specialty phosphatic grades for organic viticulture in Baden-Württemberg represent the fastest-expanding niche within the product type architecture.
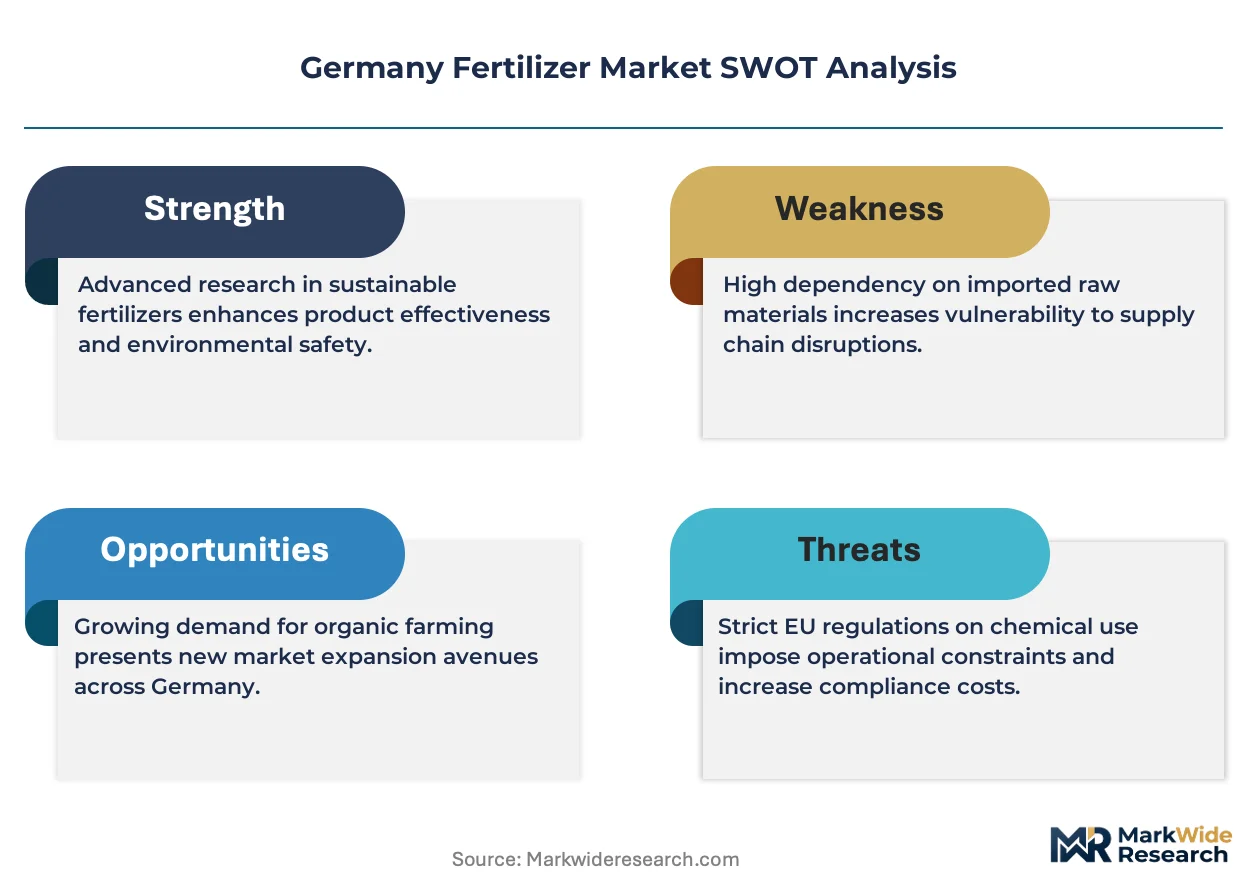
German fertilizer circulation falls under REACH chemical registration, the EU F-Gas Regulation for ammonia handling, and national fertilizer ordinances administered by the Federal Office for Agriculture and Food. These frameworks mandate emission-reduced application techniques and capped nutrient surpluses, pushing manufacturers toward stabilized and controlled-release formulations. Stakeholders must track how the EU Green Deal's 50% nutrient loss reduction target reshapes product registration pathways and farm subsidy eligibility.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is compressing nitrogen surplus allowances across German arable zones, forcing manufacturers to reformulate toward stabilized and controlled-release products that meet capped nutrient thresholds.
Growth Catalysts
- Rhine Valley Specialty Crop Expansion:Viticulture and vegetable operations in this corridor are accelerating micronutrient adoption to meet premium export certification standards.
- EU F-Gas Regulation:Ammonia handling protocols are tightening, rewarding domestic producers with captive synthesis infrastructure and integrated carbon capture systems.
- Precision Application Technologies:Variable-rate spreading systems and drone-based NDVI mapping are improving nutrient use efficiency in Bavaria's intensive greenhouse clusters.
Market Restraints
- Natural Gas Feedstock Volatility:Ammonia synthesis depends on natural gas inputs, exposing nitrogenous fertilizer margins to energy price swings from Norwegian and Dutch supply corridors.
- Potash Supply Concentration:Belarusian and Russian supply disruptions have concentrated available potash volumes through Canadian and German Zechstein deposits, creating geographic chokepoints.
- REACH Registration Friction:Novel biostimulant and microbial additive formulations face extended toxicity testing timelines, delaying commercialization of next-generation soil amendments.
Strategic Opportunities
- Brandenburg Sandy Soil Specialization:Phosphate retention deficiencies in this eastern region create demand for coated and acidulated formulations with enhanced root-zone availability.
- Carbon Farming Certification:The EU Carbon Removal Certification Framework creates revenue streams for manufacturers documenting emission-reduced production pathways.
- Controlled-Release Convergence:Polymer coating chemistry combined with nitrification inhibitor biochemistry enables premium pricing in organic transition zones.
Industry Challenges
- Agronomist Workforce Scarcity:Eastern German farming cooperatives face recruitment gaps in soil science and precision agriculture advisory roles, constraining technical sales force expansion.
- Legacy Equipment Integration:Retrofitting existing granulation plants with emission monitoring systems to comply with Federal Immission Control Act amendments demands capital deployment without immediate yield recovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Fertilizer Market |
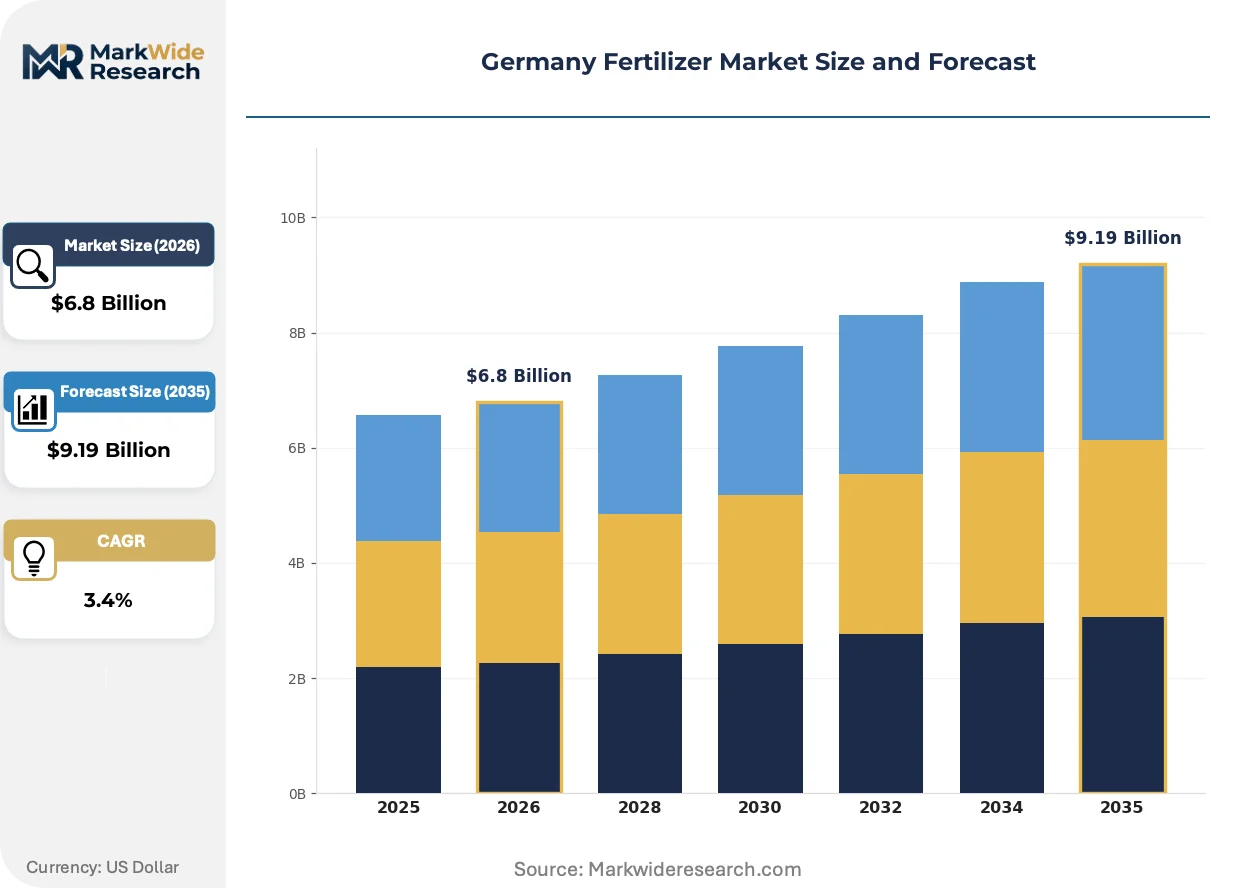
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.19 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nitrogenous, Phosphatic, Potassic, Compound Application: Agricultural, Horticultural, Landscaping, Turf Management Distribution Channel: Direct Sales, Wholesale, Retail, Online End User: Farmers, Agronomists, Retailers, Cooperatives |
| Companies Covered | EuroChem Group AG, Grupa Azoty S.A., K+S Aktiengesellschaft, AGLUKON Spezialduenger GmbH & Co. KG, ICL Group Ltd., Yara International ASA, AGROFERT A.S., BASF SE, SKW Stickstoffwerke Piesteritz GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Fertilizer Market Trends and Innovations
Digital soil mapping and sensor-driven variable-rate application are displacing blanket spreading practices across northern German wheat belts, compressing demand for standardized bulk blends while elevating demand for site-specific formulations.
Stabilized nitrogen formulations incorporating nitrification and urease inhibitors are displacing conventional urea in rapeseed and maize rotations. Large-scale farming cooperatives in Lower Saxony are adopting these products at accelerated rates. This chemistry shift is displacing commodity nitrogen margins and concentrating value capture with integrated manufacturers possessing in-house inhibitor synthesis capabilities.
The EU Green Deal's 50% nutrient loss reduction target is tightening discharge permits for fertilizer manufacturing facilities. Industrial consequence includes mandatory investment in scrubber systems and closed-loop water recycling. Northern German production sites along the Elbe watershed face the most stringent enforcement timelines and are accelerating capital deployment ahead of 2027 permit renewal cycles.
Certification-driven procurement is fragmenting traditional distributor relationships in Baden-Württemberg's organic viticulture sector. Wineries are bypassing agricultural merchants to source directly from manufacturers offering Demeter and Bioland-compliant micronutrient packages. This channel compression is most visible in the Ortenau and Kaiserstuhl sub-regions where estate bottlers command premium positioning.
Germany Fertilizer Market Segmentation
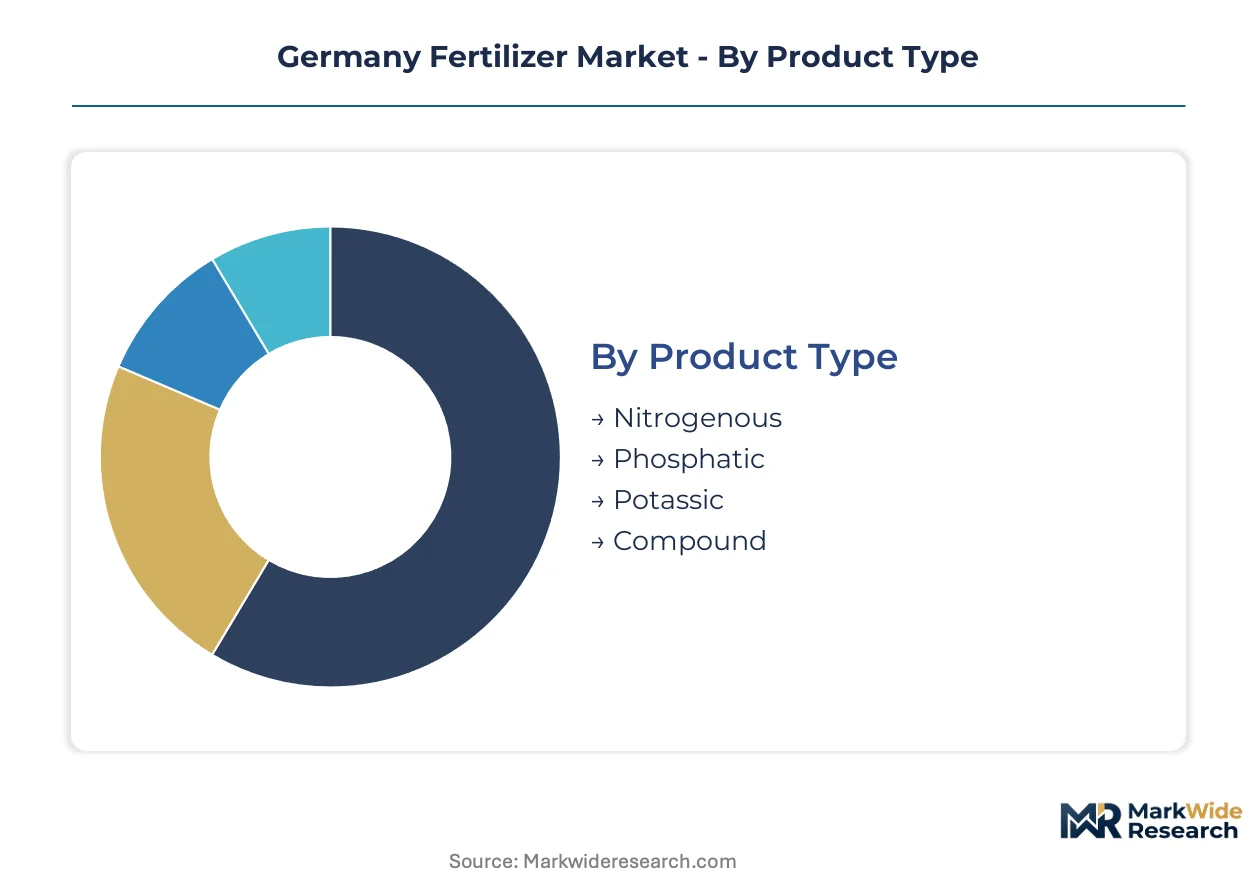
German fertilizer segmentation reflects divergent pressure from regulatory caps, farm consolidation, and precision agriculture adoption. Product type splits reveal where substitution risk concentrates, while application and channel dimensions expose margin migration paths under the EU Green Deal.
Product Type:
Stabilized and controlled-release formulations are displacing commodity grades fastest, with substitution pressure varying sharply by nutrient chemistry and application method.
- Nitrogenous:Ammonia- and urea-based formulations dominate tonnage flows across northern German wheat and rapeseed rotations. Continuous demand from Lower Saxony's large-scale farming cooperatives sustains volume, though nitrification inhibitor integration is compressing commodity margins.
- Compound:Precision-blended NPK ratios serve Bavaria's intensive greenhouse operators and Brandenburg's vegetable producers seeking single-application efficiency. Polymer coating chemistry enables premium positioning where labor costs drive consolidation of field passes.
- Phosphatic:Acidulated and coated grades address phosphate retention deficiencies in sandy eastern soils.
- Potassic:MOP and SOP varieties from Zechstein deposits supply potassium-critical crops in the Rhine Valley.
Nitrogenous anchors the volume base while compound gains share at the steepest rate.
Application:
Margin concentration follows certification intensity, with organic transition zones and export-oriented production commanding formulation premiums.
- Agricultural:Arable cropping across northern plains consumes standardized bulk blends at scale, though variable-rate technology adoption is fragmenting demand into site-specific prescriptions.
- Horticultural:Protected vegetable production in Bavaria and berry cultivation in Mecklenburg-Western Pomerania demand water-soluble and foliar formulations with micronutrient packages.
- Landscaping:Municipal and commercial turf maintenance in urban corridors drives slow-release demand.
- Turf Management:Golf course and sports field operators in Baden-Württemberg prioritize color response and wear recovery specifications.
Agricultural retains the largest revenue pool while horticultural climbs the fastest under protected cultivation expansion.
Distribution Channel:
Channel economics shift with farm size consolidation and advisory service bundling requirements.
- Direct Sales:Manufacturers bypass distributors to serve large cooperatives and estate farms with technical agronomy support, capturing margin pools previously allocated to wholesale intermediaries.
- Wholesale:Agricultural merchants aggregate volume across small and mid-scale farms, though procurement consolidation is compressing their supplier count.
- Retail:Local input dealers serve hobby farmers and specialty crop producers with bagged and packaged goods.
- Online:E-commerce platforms gain traction among younger farm operators seeking price transparency and rapid delivery.
Direct sales commands the highest margin per ton while online expands most quickly among digitized farm operations.
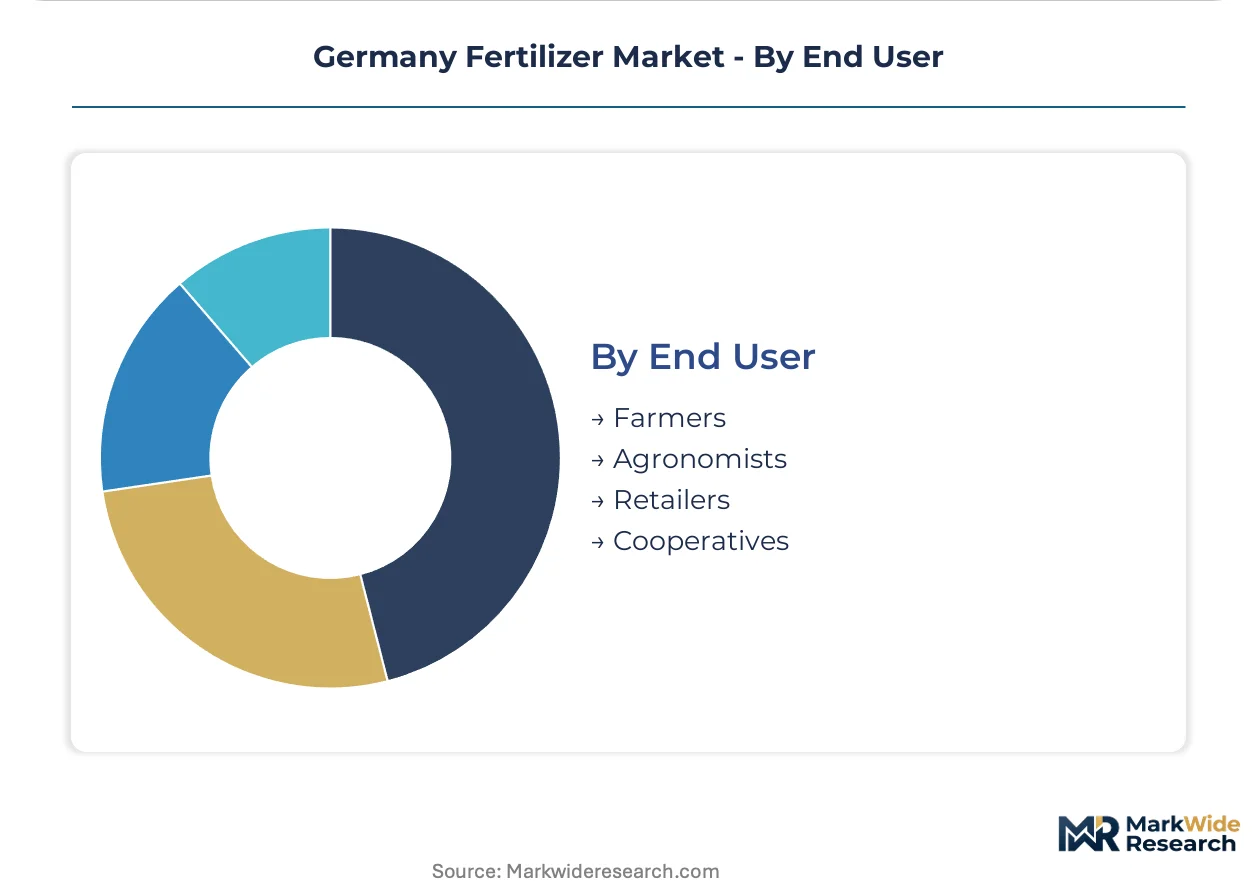
End User:
Technical sophistication requirements segment the customer base by advisory dependency and purchasing scale.
- Farmers:Individual and family operations across diverse cropping systems drive volume demand, with precision adoption rates splitting the segment into technology leaders and laggards.
- Cooperatives:Eastern German farming cooperatives consolidate procurement power and influence formulation specifications through collective tendering.
- Agronomists:Independent and manufacturer-employed advisors influence product selection through soil testing and prescription services, though workforce scarcity constrains coverage expansion.
- Retailers:Input dealers and garden centers serve fragmented smallholder and consumer segments with limited technical differentiation.
Farmers and cooperatives together dominate tonnage offtake while agronomists gain influence fastest under precision agriculture diffusion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across German sub-regions diverge sharply, with northern arable zones favoring bulk nitrogenous applications while southern specialty corridors drive micronutrient formulation premiums.
Bavaria
Intensive vegetable production in the Altmühl Valley and greenhouse clusters around Munich consume precision-blended NPK compounds with polymer coatings. The Bavarian State Ministry of Food, Agriculture and Forestry enforces strict nitrate action zone protocols. Ingolstadt's agritech corridor hosts spreading equipment manufacturers integrating variable-rate technology for cooperative farms.
North Rhine-Westphalia
Rhine-Ruhr industrial agriculture demands stabilized urea for continuous wheat rotations across Münsterland's large-scale operations. ECHA's REACH registration requirements govern novel additive formulations entering this market. Krefeld's chemical processing hub maintains ammonia synthesis infrastructure serving regional nitrogenous supply.
Baden-Württemberg
Organic viticulture in the Ortenau and Kaiserstuhl sub-regions purchases certified micronutrient packages bypassing traditional distributors. EU Green Deal Farm to Fork nutrient caps reshape procurement specifications for estate bottlers. Freiburg's precision agriculture research cluster advances drone-based NDVI mapping for site-specific application.
Lower Saxony
Large-scale farming cooperatives across the North German Plain drive volume demand for nitrification inhibitor-enhanced nitrogen. The Federal Immission Control Act mandates emission-reduced application equipment retrofits. Oldenburg's agricultural machinery sector supplies variable-rate spreaders consolidating field passes for labor-constrained operations.
Brandenburg
Sandy soils around Potsdam and Cottbus exhibit severe phosphate retention deficiencies requiring acidulated and coated formulations. The Federal Office for Agriculture and Food administers fertilizer ordinance compliance for eastern expansion zones. Berlin-Brandenburg's organic transition zones generate demand for controlled-release products meeting certification thresholds.
Germany Fertilizer Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive raw material access and in-house synthesis capabilities determining margin capture. K+S Aktiengesellschaft anchors potash supply through Zechstein deposit control, while BASF SE leverages Ludwigshafen ammonia integration for cost-advantaged nitrogen output. Strategic moves concentrate on backward integration into feedstock security and forward integration into precision advisory services bundling.
Within the integrated chemical conglomerate tier, BASF SE and K+S Aktiengesellschaft occupy positions defined by captive resource bases and multi-site manufacturing footprints. EuroChem Group AG exemplifies the specialized phosphate blender archetype, tailoring formulations to regional soil chemistry constraints. Among cooperative-linked suppliers, SKW Stickstoffwerke Piesteritz GmbH represents the eastern German production tradition with nitrogenous focus. AGLUKON Spezialduenger GmbH & Co. KG sits within the micronutrient specialist segment serving horticultural certification requirements.
| Leading Market Players |
|---|
| EuroChem Group AG |
| Grupa Azoty S.A. |
| K+S Aktiengesellschaft |
| AGLUKON Spezialduenger GmbH & Co. KG |
| ICL Group Ltd. |
| Yara International ASA |
| AGROFERT A.S. |
| BASF SE |
| SKW Stickstoffwerke Piesteritz GmbH |
| Others |
Pricing and Supply Chain Analysis
Sixty-day ammonia inventory cycles at Ludwigshafen synthesis hubs concentrate pricing power with integrated nitrogen producers while exposing spot-market buyers to feedstock volatility from Dutch TTF corridor fluctuations. This lead-time compression rewards manufacturers with captive natural gas offtake and carbon capture integration, while distributors without backward integration face margin erosion during energy price spikes.
Pricing Analysis
Long-term offtake contracts dominate procurement between K+S Aktiengesellschaft and Bavarian farming cooperatives, locking in volume commitments that insulate against spot ammonia volatility. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and micronutrient complexity, with Demeter-compliant formulations commanding substantial premiums over conventional bulk blends. Cost compression in commodity nitrogen is intensifying because nitrification inhibitor integration raises production costs without proportional price recovery. Smallholder retailers exhibit highest price sensitivity, while estate vineyards in Baden-Württemberg prioritize certification compliance over unit economics.
Supply Chain Analysis
Canada and Germany's Zechstein deposits anchor global potash supply, with Belarusian and Russian disruptions concentrating available volumes through these geographic chokepoints. Ammonia synthesis draws from Norwegian and Dutch natural gas corridors, while phosphate rock feeds from Moroccan and Tunisian extraction sites. Single-source vulnerability concentrates in Belarusian potash alternatives, where Canadian export capacity faces rail and port bottlenecks. Distribution runs through agricultural merchant networks in North Rhine-Westphalia and direct manufacturer relationships with Lower Saxony cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's Farm to Fork nutrient loss mandates are disrupting established formulation economics, creating asymmetric opportunities for manufacturers with stabilized-release chemistry capabilities and integrated carbon capture infrastructure.
For Market Incumbents: Consolidate advisory service bundling to offset agronomist workforce scarcity constraining eastern German cooperative coverage. Deepen backward integration into Zechstein potash reserves or captive ammonia synthesis to defend margin pools against feedstock volatility from Norwegian supply corridors. Prioritize polymer coating R&D investments that enable premium positioning under tightening EU discharge permits. For New Entrants and Emerging Players: Precision agronomy software gaps in Brandenburg's sandy soil zones offer white-space entry points where incumbents under-serve phosphate retention advisory. Target organic transition corridors around Berlin-Brandenburg with certified controlled-release formulations bypassing traditional distributor markups. Pursue direct-to-winery channel strategies in Ortenau and Kaiserstuhl sub-regions where estate bottlers seek Demeter-compliant micronutrient packages. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across emission-scrubber retrofits and closed-loop water recycling systems mandated by Federal Immission Control Act amendments. Five-to-ten-year viability favors manufacturers with integrated synthesis infrastructure and regional deposit control over pure-play blenders exposed to raw material volatility. Monitor EU Carbon Removal Certification Framework implementation as inflection signal for emission-reduced production pathway valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Feedstock | Zechstein potash control or Ludwigshafen ammonia synthesis insulates margins from TTF corridor volatility. |
| Controlled-Release Formulation Expansion | Polymer coating chemistry captures premium pools under EU Green Deal nutrient cap enforcement. |
| Direct Sales Channel Development | Bypassing agricultural merchants in Baden-Württemberg viticulture compresses distributor markups. |
| Carbon Capture Infrastructure Deployment | Integrated systems qualify manufacturers for EU Carbon Removal Certification revenue streams. |
| Precision Advisory Service Bundling | Technical agronomy teams offset workforce scarcity constraining eastern cooperative coverage. |
Research Methodology
Cross-validation between primary interviews with plant managers at nitrogen synthesis facilities and secondary trade data from customs records anchors the qualitative findings on feedstock flow patterns. Conversations with procurement leads at Lower Saxony farming cooperatives, distribution channel partners in North Rhine-Westphalia, and technical R&D directors at specialty blender operations combined with Federal Office for Agriculture and Food regulatory filings, ECHA REACH registration databases, and SEC 10-K disclosures from listed chemical conglomerates. Bottom-up volume modeling and top-down value reconciliation triangulate market size estimates.
Sensitivity analysis around natural gas price bands and potash supply disruption scenarios shapes the projection framework across the analysis window. Segmentation dimensions include product type chemistry, application intensity by cultivation system, distribution channel economics, and regional soil chemistry constraints. CAGRs derive from fitted growth curves incorporating EU Green Deal implementation timelines and precision agriculture diffusion rates. Modeled inputs include ammonia feedstock cost trajectories and certified organic land conversion pace.
Material uncertainties — regulatory enforcement variance across German federal states, Belarusian supply corridor reopening, and agronomist workforce recruitment gaps — sit outside the modeled envelope. Forecasts reflect documented assumptions about EU F-Gas Regulation implementation and REACH registration friction for novel biostimulants. Recalibration cycles align with material shifts in EU Green Deal nutrient loss targets and Federal Immission Control Act amendment timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
North America Fertilizers Market
Fertilizers
Nano Fertilizer Market
Fertilizers
Asia-Pacific Micronutrient Fertilizer Market
Fertilizers
Urea Fertilizers Market
Fertilizers
Nitrogen Fertilizer Additives Market
Fertilizers
Global Water Soluble Fertilizer Market
Fertilizers
Russia Micronutrient Fertilizer Market
Fertilizers
Global Controlled Release Fertilizer Market
Fertilizers
Phosphate Fertilizers Market
Fertilizers
Biochar Fertilizer Market
Fertilizers
Africa Micronutrient Fertilizer Market
Fertilizers
Global Phosphatic Fertilizers Market
Fertilizers
India Organic Fertilizer Market
Fertilizers
Global Nitrogenous Fertilizer Market
Fertilizers
Blue-Green Algae Fertilizer Market
Fertilizers
Potassium Thiosulfate Fertilizer Market