
 North America Micronutrient Fertilizers Market | 2026-2036
North America Micronutrient Fertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
North America Micronutrient Fertilizers Market Analysis
A widening capability gap between integrated manufacturers and regional blenders is reorganizing competitive tiers in North America. Nutrien Ltd. leverages its retail distribution network and captive mining assets to control input costs across the value chain. The Mosaic Company anchors phosphate-based micronutrient production through its Florida operations and backward integration into phosphate rock. Yara International ASA competes on liquid formulation technology and precision agriculture partnerships.
Micronutrient fertilizers are essential plant nutrition products containing trace elements—zinc, iron, manganese, boron, and others—typically applied at rates below ten pounds per acre to correct soil deficiencies and optimize metabolic enzyme function in crops. These formulations prevent hidden hunger in plants, where marginal deficiencies reduce yield without visible symptoms, and serve as the precision layer in modern fertility programs. Zinc dominates product type revenue due to widespread deficiency across calcareous soils in the Great Plains, while liquid form categories outpace granular growth as fertigation and foliar spraying expand in specialty agriculture. Horticultural crops command premium pricing per acre compared to broadacre grains, though agricultural crops still absorb the largest absolute volume.
The EPA oversees pesticide and fertilizer registration under FIFRA, while USDA conservation programs incentivize soil testing that reveals micronutrient gaps and triggers corrective purchases. State-level 4R Nutrient Stewardship initiatives in Iowa, Illinois, and Minnesota mandate right-source, right-rate, right-time, right-place application, effectively mandating micronutrient precision tools. Stakeholders must monitor evolving state fertilizer use restrictions and carbon intensity scoring for agricultural inputs, as these frameworks will determine which formulation technologies and delivery platforms secure preferential market access.
Market Dynamics
Precision agriculture adoption and tightening EPA nutrient management standards are forcing micronutrient fertilizer suppliers to rebuild formulation portfolios around site-specific delivery systems rather than commodity bulk blends.
Growth Catalysts
- 4R Nutrient Stewardship mandates:Iowa, Illinois, and Minnesota regulations require right-rate, right-place application, compelling growers to purchase micronutrient precision tools and soil testing services.
- Fertigation expansion in specialty crops:California and Florida vegetable and citrus operations are converting flood irrigation to drip systems, creating pull for liquid zinc and boron compatible with injection equipment.
- Hidden hunger recognition:USDA conservation program incentives for soil testing reveal subclinical deficiencies in Corn Belt monoculture systems, triggering corrective micronutrient purchases before yield loss manifests.
Market Restraints
- Sulfuric acid and phosphate rock cost volatility:Mosaic's Florida phosphate operations and imported sulfur dependencies expose blenders to input price swings that compress margin on micronutrient co-formulations.
- Single-source mining concentration:Domestic zinc sulfate production concentrates in Oklahoma and Tennessee smelter operations, creating geographic supply vulnerability for Great Plains blenders.
- Application rate ceiling:EPA FIFRA registration thresholds and crop phytotoxicity limits cap per-acre micronutrient volumes, constraining revenue expansion per treated acre.
Strategic Opportunities
- Underpenetrated Pacific Northwest orchards:Washington and Oregon tree fruit and hop operations show rising boron deficiency incidence with limited local blending capacity, opening territory for liquid formulation specialists.
- Carbon intensity scoring frameworks:Emerging state-level low-carbon fertilizer standards in California and pending federal procurement rules will favor micronutrient products with verified supply chain emissions data.
- Biostimulant convergence:Integration of micronutrients with microbial inoculants and seaweed extracts creates premium positioning in organic transition acres and regenerative agriculture contracts.
Industry Challenges
- Precision agronomy skill scarcity:Local cooperatives and independent retailers lack trained staff to interpret soil test results and prescribe variable-rate micronutrient programs, slowing technology adoption.
- Liquid storage infrastructure capex:Conversion from dry bulk handling to stainless steel tank systems and closed transfer equipment requires capital deployment that strains regional blender balance sheets.
- State-by-state registration fragmentation:Individual state fertilizer registration timelines and formulation disclosure requirements create compliance drag for multi-state product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Micronutrient Fertilizers Market |
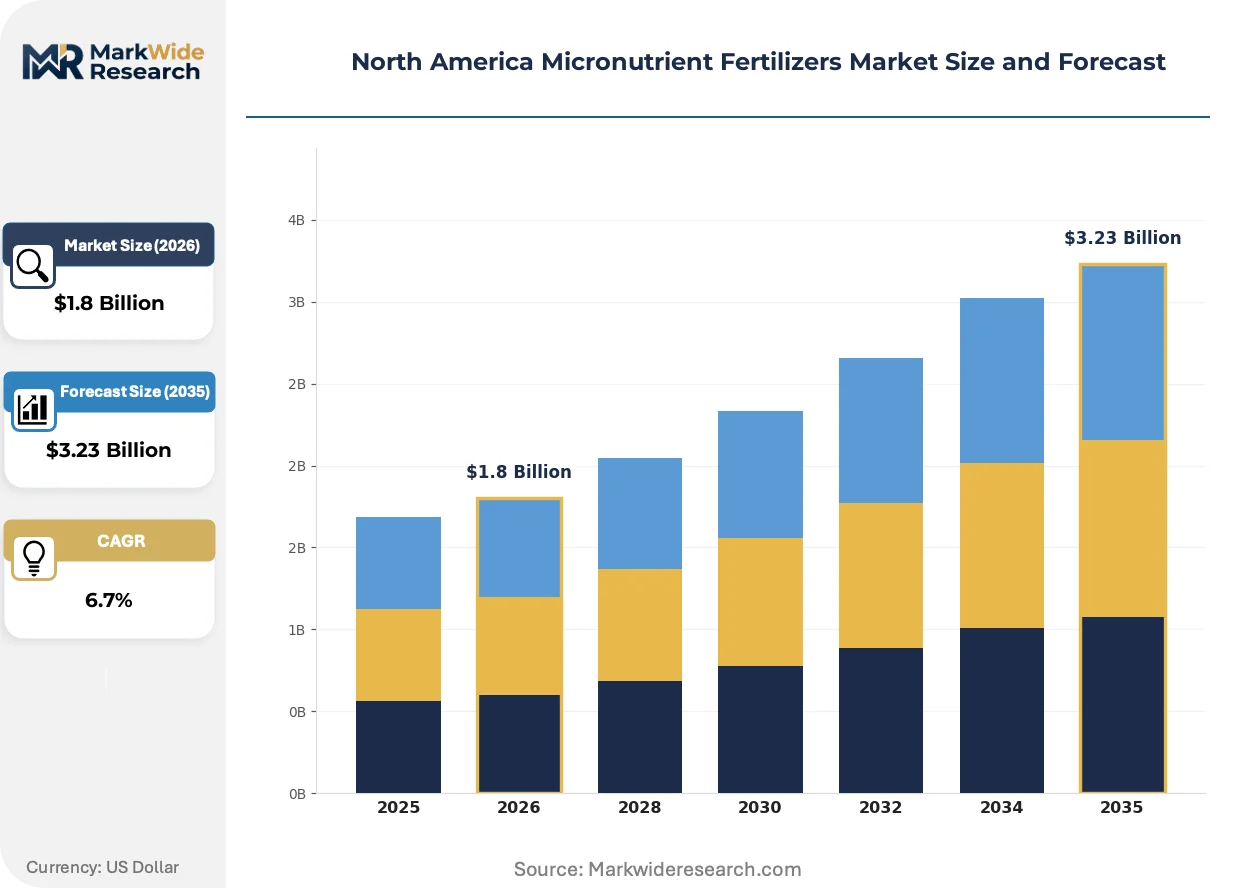
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Zinc, Iron, Manganese, Boron Application: Agricultural Crops, Horticultural Crops, Turf, Ornamental Plants Form: Granular, Liquid, Soluble, Powder Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | Nutrien Ltd., The Mosaic Company, CF Industries Holdings, Inc., Yara International ASA, Nouryon, The Andersons Inc., Wilbur-Ellis Company LLC, Haifa Group, Koch Agronomic Services, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Micronutrient Fertilizers Market Emerging Trajectories
Formulation chemistry and application hardware are converging to displace legacy broadcast granular systems with targeted delivery platforms that match micronutrient release to crop phenological stages.
Chelated zinc and iron formulations using EDTA and EDDHA ligands are displacing inorganic sulfate salts in high-pH calcareous soils across the Great Plains. Specialty crop growers in California's Central Valley and Florida's citrus belt are adopting these advanced chemistries at accelerated rates. The displacement of commodity sulfates is compressing margins for regional blenders lacking chelation capability while rewarding integrated manufacturers with captive organic synthesis.
EPA's emerging carbon intensity scoring for agricultural inputs under pending Inflation Reduction Act implementation is reshaping procurement criteria for federally subsidized conservation programs. Fertilizer suppliers must now document supply chain emissions from mining through formulation to qualify for preferred vendor status. Corn Belt cooperatives and large-scale grain operations are responding by demanding third-party verified carbon footprints on micronutrient products.
Site-specific variable-rate application is replacing flat-rate broadcast methods in Illinois and Iowa row-crop operations. Agronomy service providers are unbundling fertility recommendations from product supply, charging per-acre consulting fees tied to yield outcomes rather than input tonnage. This behavioral shift is most visible in the I-80 corridor where 10,000-acre grain farms contract directly with precision agriculture firms for prescription micronutrient programs.
North America Micronutrient Fertilizers Market Segmentation
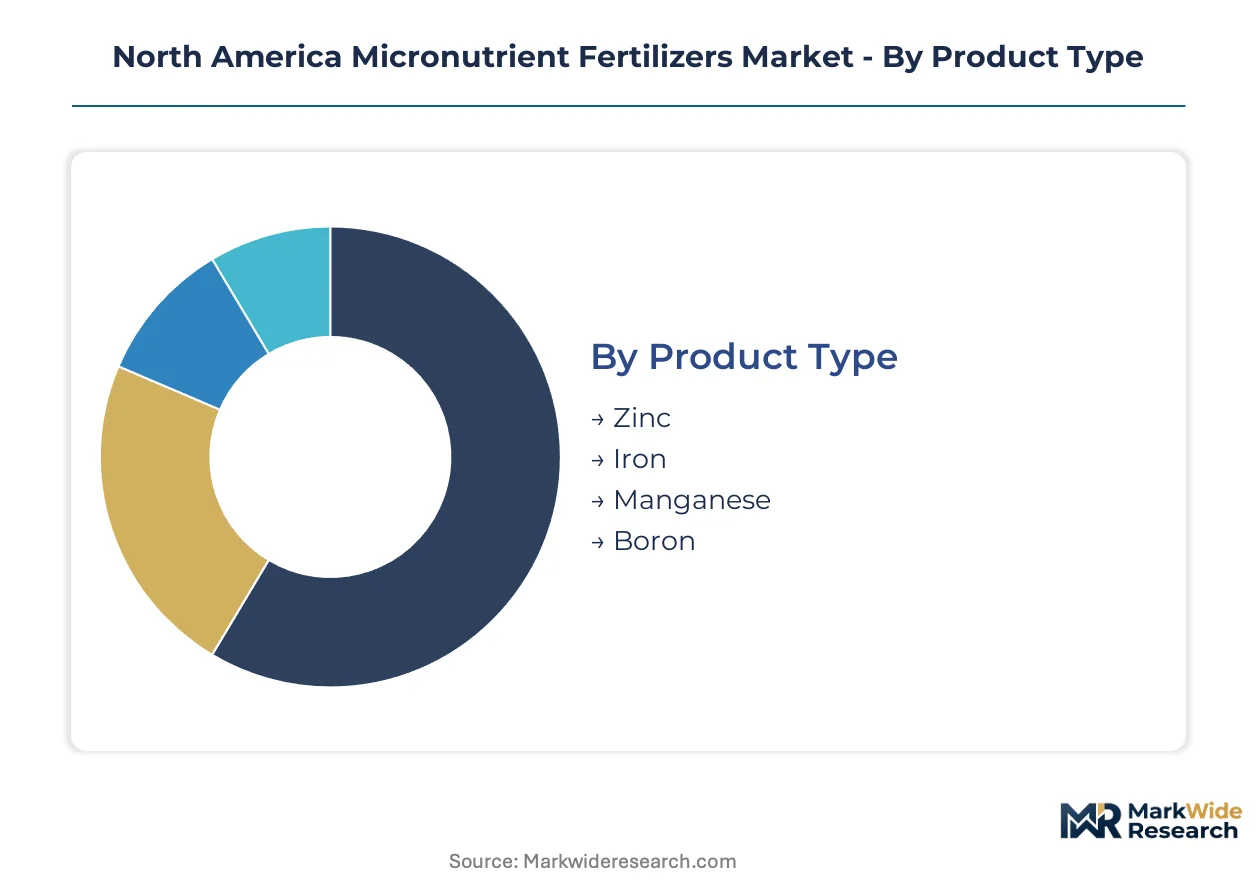
Micronutrient fertilizer segmentation reveals distinct margin architectures across product chemistry, crop destination, physical form, and channel economics. Suppliers optimize formulation investments based on where price premiums align with application complexity and grower purchasing behavior.
Product Type:
Margin pools concentrate in chelated formulations where organic synthesis capabilities create pricing power against commodity sulfate salts.
- Zinc:Zinc sulfate and chelated zinc formulations correct widespread deficiency in calcareous Great Plains soils. Corn Belt monoculture systems drive repeat purchases across Nebraska, Kansas, and the Dakotas where high-pH conditions lock native zinc in unavailable forms. The dominant share belongs to zinc, while boron is closing the gap fastest.
- Boron:Soluble borate and slow-release boron products address deficiency in intensive vegetable and tree fruit operations. California almond orchards and Florida citrus groves generate concentrated demand for precision boron delivery compatible with drip fertigation infrastructure.
- Iron:EDDHA-chelated iron prevents chlorosis in high-pH vineyard and orchard soils where inorganic iron precipitates before root uptake occurs.
- Manganese:Manganese sulfate and chelated variants serve soybean and wheat rotations in the Mississippi Delta and Upper Midwest where saturated soil conditions induce deficiency.
Specialty chelates capture value-added pricing in high-pH zones while commodity sulfates dominate volume in neutral-to-acidic soil regions.
Application:
Revenue per acre varies dramatically between broadacre grain systems and intensive specialty crop operations.
- Horticultural Crops:Vegetable, fruit, and nut operations in California's Central Valley and Florida's citrus belt apply micronutrients through precision drip systems at rates generating premium revenue per treated acre. Washington apple orchards and Oregon hop yards expand the addressable market for boron and zinc precision programs. Horticultural crops command the highest per-acre economics, while agricultural crops absorb the largest absolute tonnage.
- Agricultural Crops:Corn, soybean, and wheat rotations across the Corn Belt and Great Plains represent volume demand driven by soil testing revelations of hidden hunger in intensive monoculture systems.
- Turf:Golf course superintendents and sports field managers in Arizona, Texas, and Florida apply micronutrient packages through foliar programs to maintain aesthetic standards under stress conditions.
- Ornamental Plants:Nursery and greenhouse operations in California, Texas, and Florida purchase micronutrients as components of controlled-release fertilizer blends for container production.
Specialty crop penetration rates exceed broadacre grains, though grain acreage multiplies total volume.
Form:
Physical state determines compatibility with application infrastructure and storage capital requirements.
- Liquid:Suspension concentrates and true solutions integrate with fertigation and foliar spraying equipment. California and Florida specialty crop conversions from flood to drip irrigation accelerate liquid form expansion. Liquid formulations are gaining share fastest, though granular retains the largest installed base.
- Granular:Bulk-blended granular products compatible with existing dry fertilizer spreaders dominate Corn Belt row-crop application where broadcast methods persist.
- Soluble:Fully water-soluble crystalline products serve greenhouse and hydroponic operations requiring complete dissolution for recirculating systems.
- Powder:Fine-mesh powders support custom blending operations and export packaging for specialty agricultural markets.
Liquid infrastructure investments strain regional blender balance sheets while rewarding early movers with specialty crop lock-in.
Distribution Channel:
Channel economics fragment between integrated manufacturer control and independent retail competition.
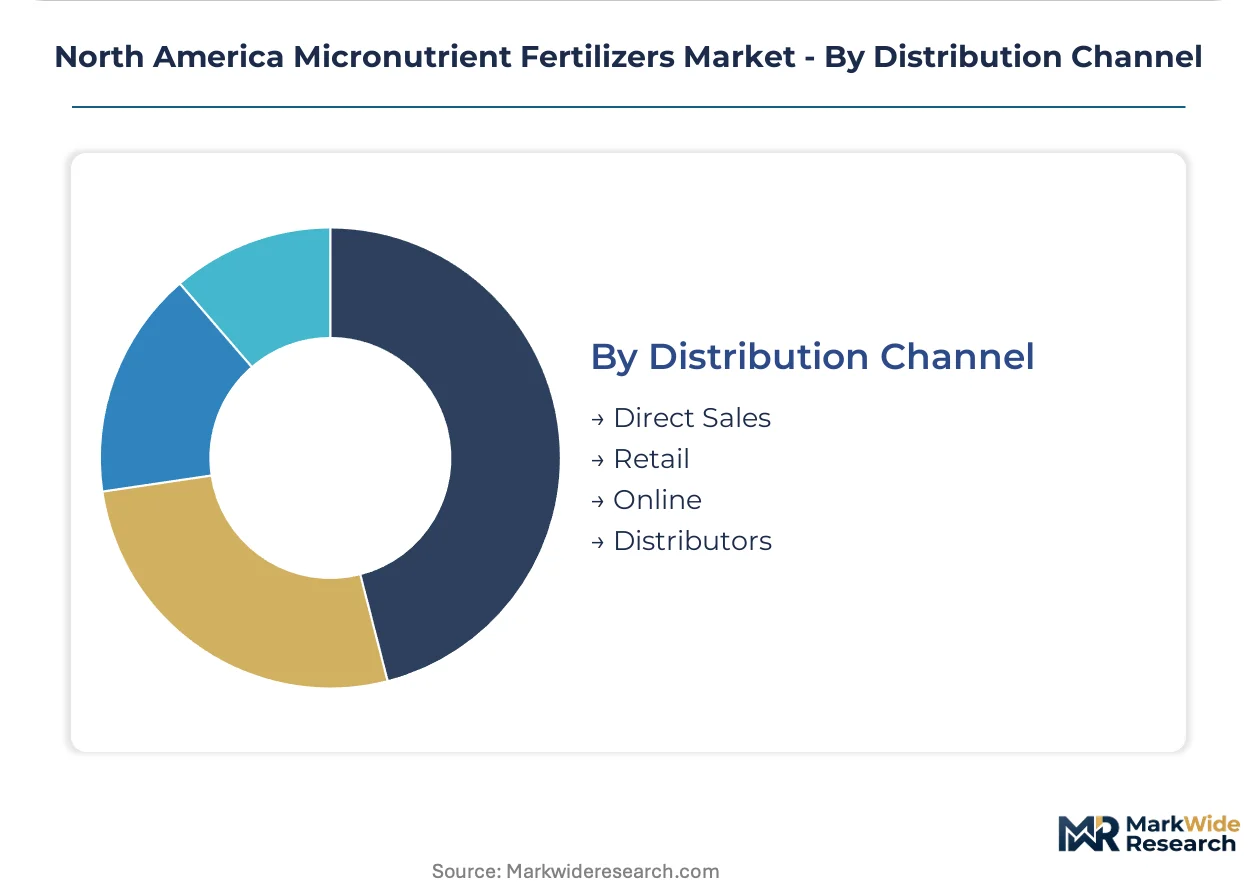
- Direct Sales:Large-scale grain operations and cooperative systems in Iowa and Illinois contract directly with manufacturers for volume micronutrient programs tied to precision agriculture services.
- Distributors:Regional agricultural distributors aggregate demand from independent retailers and custom applicators across multi-state territories.
- Retail:Local cooperatives and farm supply stores serve smaller operations with bagged and bulk products supported by agronomic recommendation services.
- Online:E-commerce platforms capture hobbyist and small-acreage growers with packaged micronutrient products for garden and specialty applications.
Direct sales and distributor channels concentrate commercial volume, while retail maintains penetration of mid-size operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Great Plains grain operations exhibit the highest price elasticity, squeezing margins on commodity zinc sulfate, while California specialty crop buyers absorb premium chelate pricing with minimal volume contraction.
United States
Corn Belt monoculture systems in Iowa and Illinois drive repeat zinc and boron purchases as intensive cultivation depletes native soil reserves. The EPA's FIFRA registration framework governs micronutrient formulation approvals, while USDA conservation programs subsidize soil testing that reveals hidden hunger. California's Central Valley anchors liquid formulation demand, where almond orchards and vegetable operations convert flood irrigation to precision drip systems.
Canada
Prairie canola and wheat rotations in Saskatchewan and Alberta generate concentrated demand for boron and manganese correction in high-pH soils. Health Canada's PMRA oversees fertilizer registration timelines that lag US approvals, creating product launch delays for multi-national suppliers. Ontario's corn-soybean belt mirrors US Midwest application patterns, with cooperatives in the Red River Valley expanding micronutrient blending capacity.
Mexico
Vegetable export zones in Sinaloa and Baja California pull liquid micronutrient formulations for protected agriculture supplying US winter markets. The country's national agricultural regulator, SADER, implements fertilizer quality standards that favor imported chelated products over domestic sulfate salts. Jalisco's berry operations and Michoacán's avocado orchards represent emerging precision agriculture adoption clusters.
North America Micronutrient Fertilizers Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with Nutrien Ltd. and The Mosaic Company controlling captive mineral inputs while regional blenders compete on formulation flexibility and local agronomic service. The structure rewards backward integration into phosphate rock and sulfuric acid, compressing margins for non-integrated competitors during input price spikes. Three archetypes dominate: mining-integrated manufacturers, formulation specialists with chelation capabilities, and distributor-owned blenders with retail footprint. Consolidation through cooperative mergers and precision agriculture partnerships represents the primary competitive vectors.
Within the integrated tier, Nutrien Ltd. and The Mosaic Company exemplify mining-backed market presence, with Nutrien leveraging its retail distribution network and The Mosaic Company anchoring phosphate-based micronutrient production through Florida operations. Yara International ASA occupies a position emphasizing liquid formulation technology and precision agriculture partnerships. These three entities represent contrasting strategic anchors: captive mineral control, phosphate integration, and technology-led precision delivery.
| Leading Market Players |
|---|
| Nutrien Ltd. |
| The Mosaic Company |
| CF Industries Holdings, Inc. |
| Yara International ASA |
| Nouryon |
| The Andersons Inc. |
| Wilbur-Ellis Company LLC |
| Haifa Group |
| Koch Agronomic Services |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day sulfuric acid inventory cycles in Great Plains blending operations tether pricing power to phosphate rock availability from Florida mining complexes and imported sulfur dependencies. This lead-time exposure concentrates margin compression risk among non-integrated regional blenders while rewarding mining-backed manufacturers with captive input control.
Pricing Analysis
After-sales agronomic consulting revenue tied to soil test interpretation and variable-rate prescription programs now drives lifetime customer value more than commodity product margins. Three-tier pricing structure across premium chelates, standard sulfates, and economy bulk blends stratifies the market, with EPA FIFRA registration tiers and organic synthesis capabilities as the primary differentiation drivers. Pricing pressure stems from sulfuric acid cost volatility transmitted through phosphate co-formulation supply chains. Corn Belt grain cooperatives exhibit acute price sensitivity, while California almond and Florida citrus operations absorb premium chelate pricing with minimal volume contraction.
Supply Chain Analysis
Just-in-time sulfuric acid procurement dominates Great Plains blending operations, though strategic stockpiling of phosphate rock concentrates at Mosaic's Florida facilities buffers input volatility. Geographic supply concentration centers on Florida phosphate mining complexes, Oklahoma and Tennessee zinc sulfate smelter operations, and imported sulfur from Canadian oil sands and offshore refining. Raw material dependencies span phosphate rock, sulfuric acid, and zinc concentrate feedstocks. Single-source mining concentration in domestic zinc sulfate production creates geographic supply vulnerability for Great Plains blenders. Distribution runs through manufacturer-direct channels for large-scale grain operations, regional distributors for multi-state territories, and local cooperatives for mid-size farm penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision agriculture adoption and EPA carbon intensity scoring for agricultural inputs constitute a high-growth disruption reshaping procurement criteria across federally subsidized conservation programs.
For Market Incumbents: Consolidate formulation capabilities through cooperative mergers in the I-80 corridor and precision agriculture partnerships that unbundle agronomic recommendations from product supply. Backward integration into phosphate rock and sulfuric acid production anchors margin defense against input price volatility. Channel control through retail distribution networks locks in Corn Belt volume against emerging liquid formulation specialists.
For New Entrants and Emerging Players: EPA FIFRA registration fast-tracks for chelated zinc and boron formulations open white-space penetration in Washington apple orchards and Oregon hop yards where local blending capacity remains underdeveloped. Pacific Northwest tree fruit operations represent the most penetrable geography given rising boron deficiency incidence and limited incumbent presence. Direct sales to 10,000-acre grain farms contracting for prescription micronutrient programs offers the strongest go-to-market angle.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across liquid storage infrastructure and stainless steel tank systems required for specialty crop lock-in. Long-term viability over the coming decade hinges on formulation technology differentiation and precision agriculture service bundling. Acquisition targets should display chelation synthesis capabilities and established EPA registration portfolios. The signal to watch is state-level low-carbon fertilizer standard adoption accelerating in California and pending federal procurement rules.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Rock | Captive mining assets in Florida compress input costs and insulate margin from sulfur price volatility. |
| Liquid Formulation Technology Partnership | Precision agriculture collaborations with drip irrigation equipment manufacturers accelerate specialty crop penetration. |
| Chelated Product Registration Expansion | EPA FIFRA approvals for EDTA and EDDHA formulations unlock premium pricing in high-pH Great Plains soils. |
| Carbon Intensity Certification Program | Third-party verified supply chain emissions data secures preferred vendor status under USDA conservation programs. |
| Cooperative Merger and Consolidation | Regional blender combinations build scale for stainless steel tank infrastructure and precision agronomy staffing. |
Methodological Framework
Operator-level perspectives from agronomy service providers, cooperative procurement managers, specialty crop growers, and precision agriculture technology vendors anchored the qualitative base for this analysis. Primary interviews across these stakeholder categories combined with secondary validation from USDA conservation program databases, EPA FIFRA registration filings, state 4R Nutrient Stewardship initiative documentation, and SEC 10-K disclosures from mining-integrated manufacturers. Bottom-up demand modeling from county-level soil test data and top-down supply analysis from phosphate rock production statistics enabled triangulation across independent estimation approaches.
Sensitivity analysis around sulfuric acid price volatility, EPA carbon intensity scoring implementation timelines, and precision agriculture adoption rates shaped the forecast framework across the projection horizon. Segmentation dimensions modeled include product chemistry tier, crop destination, physical form, and distribution channel economics, with regional regulatory cluster and soil pH zone as agriculture-specific forecast inputs. CAGRs derived from historical volume trajectories and elasticity-adjusted demand projections under varying input cost scenarios.
The analysis sits within stated boundaries; outcomes outside EPA regulatory enforcement intensity, sulfur market stability, and precision agriculture capital deployment rates would require recalibration. Forecasts reflect documented assumptions regarding conservation program funding continuity and state-level nutrient management mandate expansion. Revision becomes warranted when carbon intensity scoring thresholds for federal procurement cross implementation milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Europe Organic Fertilizer Market
Fertilizers
Indonesia Fertilizer Market
Fertilizers
Urea Fertilizers Market
Fertilizers
Polymer Coated Urea Market
Fertilizers
Nano Fertilizer Market
Fertilizers
Diammonium Hydrogen Phosphate (DAP) Market
Fertilizers
Brazil Specialty Fertilizer Market
Fertilizers
Southeast Asia Fertilizer Market
Fertilizers
Global Nitrogenous Fertilizer Market
Fertilizers
Fertilizer Applicators Market
Fertilizers
Fertilizer Mixtures Market
Fertilizers
United States Specialty Fertilizer Market
Fertilizers
Crop Micronutrients Market
Fertilizers
Compound Fertilizer Market
Fertilizers
Asia-Pacific Organic Fertilizer Market
Fertilizers
Global NPK Fertilizer Market