
 Vietnam Organic Fertilizer Market | 2026-2036
Vietnam Organic Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Organic Fertilizer Market Analytics
Specialty crop cooperatives are rotating toward bio-based soil amendments as rice-dominated procurement loses relative share. Song Gianh Joint Stock Corporation leverages its north-central manufacturing base to supply compost-dominant blends. Bioway Hitech Joint Stock Company differentiates through liquid microbial formulations tailored to Mekong Delta horticulture. Binh Dien Fertilizer Joint Stock Company anchors downstream distribution through its long-established dealer network in the Red River Delta.
Vietnam organic fertilizer comprises plant, animal, and microbial-derived materials processed through aerobic composting, anaerobic digestion, or fermentation to supply nitrogen, phosphorus, potassium, and soil organic matter without synthetic chemical additives. Compost and biofertilizer categories lead volume due to compatibility with existing smallholder application practices and lower per-hectare cost barriers. Granular and liquid forms capture diverging demand patterns: granules suit broad-acre rice and maize operations, while liquids gain traction in precision-drip horticulture systems around Da Lat and Ho Chi Minh City peri-urban zones.
Vietnam's Ministry of Agriculture and Rural Development sets national fertilizer quality benchmarks, while provincial Departments of Agriculture and Rural Development enforce organic certification compliance and extension training. The country's national standard TCVN on organic fertilizers and biofertilizers shapes product registration requirements and import substitution incentives. Stakeholders must monitor how provincial carbon-soil programs and EU-Vietnam trade agreement sanitary rules reshape input sourcing strategies and domestic blending investments.
Market Dynamics
Vietnam's organic fertilizer sector is restructuring around provincial carbon-soil programs and EU-Vietnam Free Trade Agreement sanitary rules, which are compressing synthetic input margins while redirecting procurement toward certified domestic blenders.
Growth Catalysts
- Provincial Extension Mandates:Mekong Delta and Central Highlands Departments of Agriculture and Rural Development are scaling farmer training programs that subsidize organic input trials and accelerate conversion from chemical-dependent rice systems.
- Export-Oriented Horticulture:Specialty fruit and vegetable cooperatives supplying EU and Japanese markets are adopting certified organic amendments to meet importer phytosanitary documentation requirements.
- Anaerobic Digestion Infrastructure:Agricultural waste-to-fertilizer processing facilities in livestock-intensive provinces are expanding feedstock supply chains for biofertilizer manufacturers.
Market Restraints
- Input Cost Volatility:Chicken manure and rice straw prices fluctuate with livestock cycle and harvest timing, compressing blender margins during peak demand windows.
- Technical Shelf-Life Limitations:Microbial inoculant viability degrades within 6-12 months in tropical storage conditions, constraining inventory management for liquid biofertilizer distributors.
- Substitution Pressure:Subsidized urea and NPK compounds from state-owned chemical fertilizer networks retain cost advantages for price-sensitive rice smallholders.
Strategic Opportunities
- Precision-Drip Horticulture Expansion:Da Lat greenhouse operators and Ho Chi Minh City peri-urban vegetable zones are converting to liquid microbial formulations compatible with fertigation infrastructure.
- Carbon Credit Monetization:Vietnam's national carbon market development under Ministry of Natural Resources and Environment guidelines may allow organic fertilizer users to generate verified emission reduction credits.
- Dealer Network Digitalization:Provincial agricultural input cooperatives are piloting mobile-order platforms that connect compost blenders directly to commune-level buying groups, bypassing traditional distributor markups.
Industry Challenges
- Microbiologist Talent Scarcity:Commercial-scale fermentation operations require trained technicians capable of strain isolation and contamination control, a skill set concentrated in Hanoi and Ho Chi Minh City research institutes.
- TCVN Certification Timelines:Product registration under Vietnam's national organic fertilizer standard involves multi-stage laboratory testing and field trials that extend market entry by 18-24 months for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Organic Fertilizer Market |
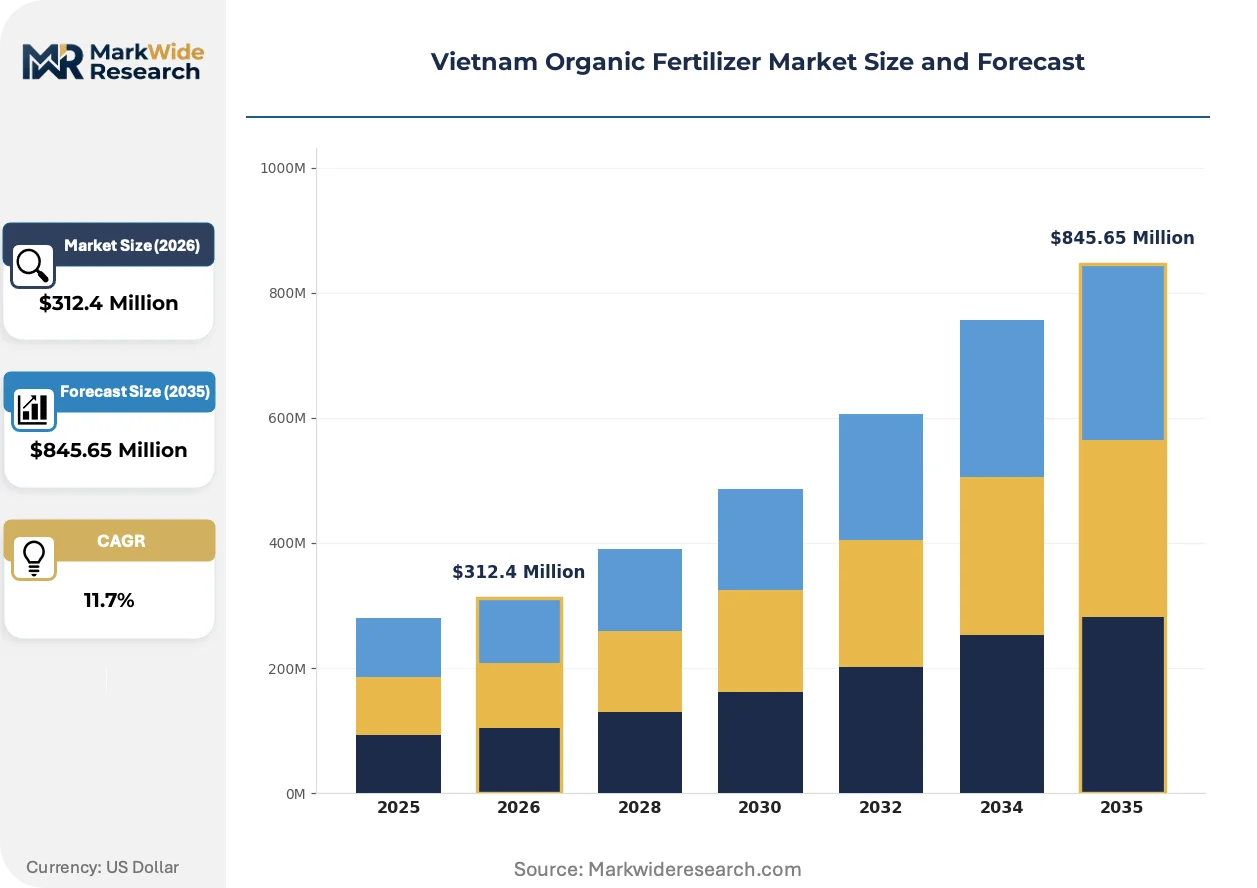
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $845.65 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compost, Manure, Biofertilizers, Humic Acid Form: Granular, Liquid, Powder, Pelleted Application: Agricultural Crops, Horticulture, Turf Management, Forestry End User: Farmers, Agricultural Cooperatives, Distributors, Retailers |
| Companies Covered | Song Gianh Joint Stock Corporation, Bioway Hitech Joint Stock Company, Binh Dien Fertilizer Joint Stock Company, Vedan Vietnam Enterprise Corporation Limited, Bio Agrosa Fertilizer, PetroVietnam Fertilizer and Chemicals Corporation, Baconco Company Limited, Ha Lan Fertilizer Corporation, Que Lam Group Joint Stock Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Organic Fertilizer Market Evolving Landscape
Biotechnology convergence and regulatory digitization are compressing product development cycles while fragmenting traditional distribution hierarchies across Vietnam's agricultural input landscape.
Microbial consortia formulations combining nitrogen-fixing bacteria with phosphate-solubilizing fungi are miniaturizing application rates per hectare while maintaining yield parity with chemical alternatives. Mekong Delta dragon fruit and mango exporters are adopting these concentrated inoculants to reduce shipping volumes and storage footprints. The technology is miniaturizing blender facility requirements, enabling commune-scale production units that previously required provincial-level capital investment.
Vietnam's Ministry of Agriculture and Rural Development is digitizing fertilizer product registration through an online portal integrated with provincial Department of Agriculture and Rural Development verification workflows. This streamlines TCVN compliance documentation and accelerates market authorization for domestic manufacturers. Small and mid-scale compost operators in the Red River Delta are responding by consolidating laboratory testing partnerships to meet accelerated documentation requirements.
Specialty crop cooperatives are unbundling input procurement from legacy dealer credit arrangements, shifting toward cash-based direct purchasing from certified blenders with transparent nutrient analysis reporting. This disintermediation is compressing distributor margins while rewarding manufacturers with in-house laboratory verification capabilities. The Central Highlands coffee and pepper growing zones exhibit the most pronounced migration away from commission-based dealer networks toward cooperative bulk buying structures.
Vietnam Organic Fertilizer Market Segmentation
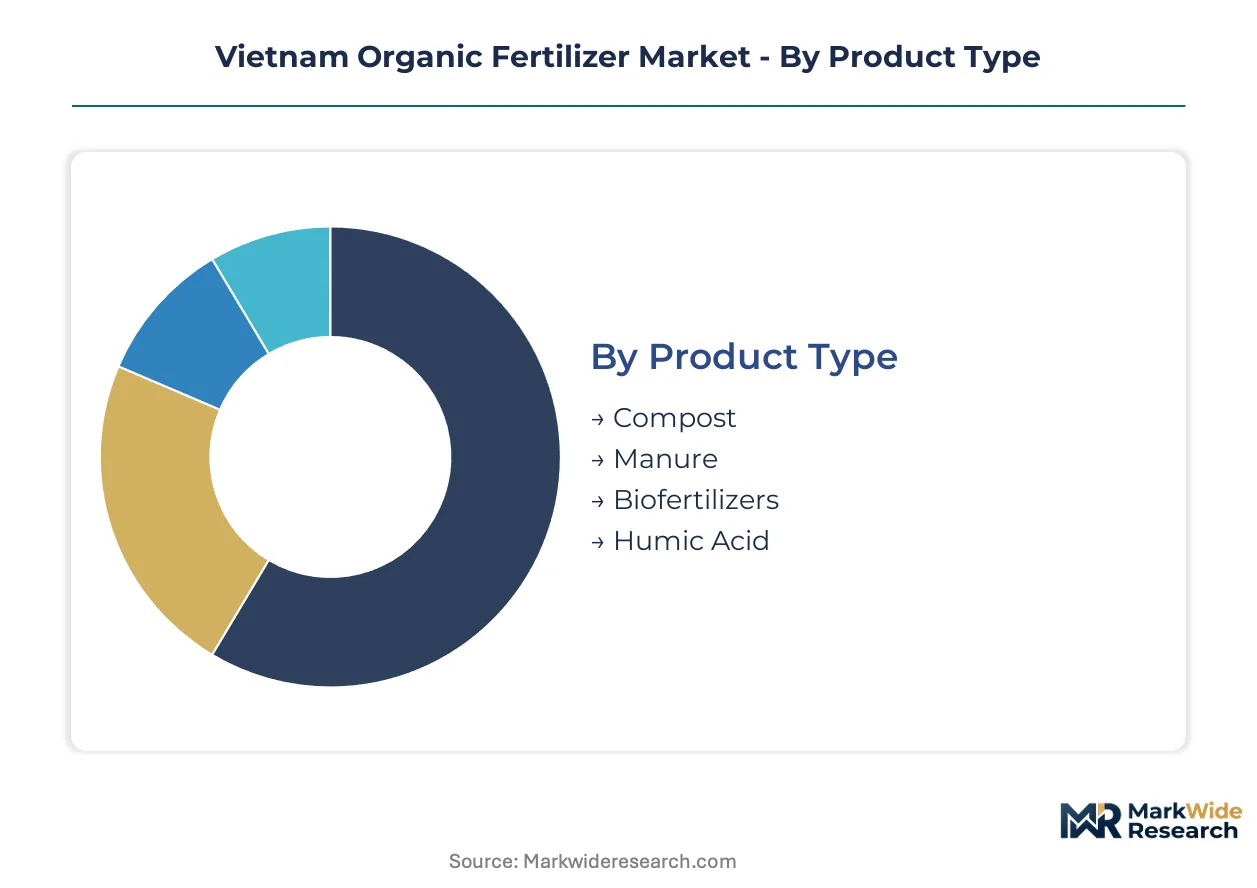
Vietnam's organic fertilizer market fragments across four critical dimensions that determine regulatory compliance pathways, distribution economics, and farmer adoption rates. Each segmentation axis carries distinct TCVN certification requirements and provincial extension program eligibility criteria that shape procurement decisions.
Product Type:
TCVN standards differentiate processing methods and microbial content thresholds, creating tiered registration timelines that favor established compost operations over novel biofertilizer entrants.
- Compost:Aerobically decomposed plant and animal residues processed through windrow or in-vessel systems. Mekong Delta rice straw and livestock waste feedstocks dominate procurement, with provincial extension programs subsidizing farmer conversion trials from chemical-dependent systems.
- Manure:Livestock excreta processed through aerobic composting or anaerobic digestion, concentrated in livestock-intensive provinces. Chicken manure from industrial poultry operations around Dong Nai and Binh Duong supplies nitrogen-dense amendments for vegetable cooperatives.
- Biofertilizers:Microbial inoculants containing nitrogen-fixing bacteria or phosphate-solubilizing fungi require strain registration with Vietnam's national agricultural regulator.
- Humic Acid:Extracted from peat or leonardite deposits, concentrated in northern provinces with established mining permits.
Established volume favors compost; emerging adoption favors biofertilizers.
Form:
Application infrastructure determines form selection, with irrigation system penetration in Central Highlands horticulture driving liquid preference against traditional hand-broadcasting regions.
- Granular:Compacted particles suited for mechanical spreading across broad-acre rice and maize operations. Red River Delta smallholders favor this form for compatibility with existing broadcast equipment and lower per-unit transportation costs.
- Liquid:Microbial suspensions or soluble extracts designed for fertigation systems. Da Lat greenhouse operators and Ho Chi Minh City peri-urban vegetable zones are converting to liquid formulations compatible with precision-drip infrastructure.
- Powder:Fine-ground compost or processed manure for soil incorporation prior to planting.
- Pelleted:Compressed organic matter with controlled-release characteristics, gaining traction in coffee and pepper plantations requiring reduced application frequency.
Granular forms anchor rice-dominant regions; liquid formulations are climbing the fastest in export-oriented horticulture clusters.
Application:
Export certification requirements fragment demand intensity, with EU-bound produce commanding premium organic input specifications versus domestic-market crops.
- Agricultural Crops:Rice, maize, and cassava systems consuming volume organic amendments. National food security programs maintain synthetic fertilizer subsidies that constrain organic penetration in this segment.
- Horticulture:Dragon fruit, mango, and vegetable production for Japanese and European export markets. Specialty cooperatives in Tien Giang and Lam Dong provinces mandate certified organic inputs to satisfy importer phytosanitary documentation.
- Turf Management:Golf course and sports field maintenance in urban centers.
- Forestry:Reforestation and plantation timber operations in central coastal provinces.
Horticulture commands premium pricing; agricultural crops represent volume scale.
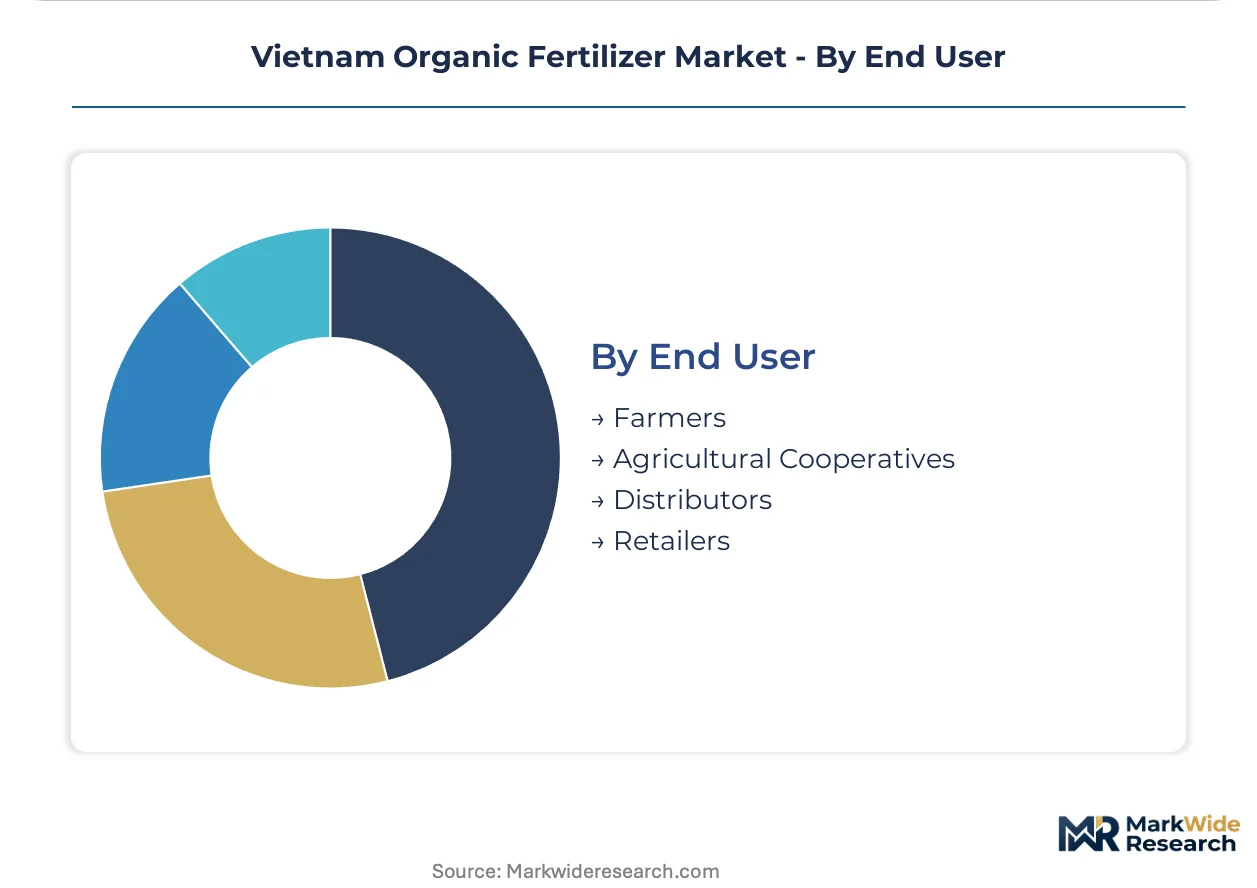
End User:
Procurement consolidation patterns separate price-sensitive individual operators from cooperative buyers leveraging collective bargaining power.
- Farmers:Individual smallholders operating under 2 hectares, concentrated in Mekong Delta rice systems. Direct purchasing from certified blenders is displacing traditional dealer credit arrangements in Central Highlands coffee zones.
- Agricultural Cooperatives:Collective buying groups aggregating demand across 50-200 member farms. Provincial Departments of Agriculture and Rural Development channel extension subsidies through these entities, accelerating organic input trials.
- Distributors:Provincial-level wholesalers managing inventory and logistics for dealer networks.
- Retailers:Commune-level input shops providing last-mile access and technical advice.
Cooperatives are gaining procurement share fastest; individual farmers remain the volume base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty fruit and vegetable cooperatives concentrate procurement in the Mekong Delta and Central Highlands, with provincial extension programs accelerating farmer conversion from chemical-dependent rice systems.
Mekong Delta
Rice straw and livestock waste feedstocks dominate compost production. Provincial Departments of Agriculture and Rural Development subsidize organic input trials. Tien Giang dragon fruit exporters mandate certified amendments to satisfy EU phytosanitary documentation.
Central Highlands
Da Lat greenhouse operators drive liquid microbial formulation demand for precision-drip infrastructure. Lam Dong coffee and pepper cooperatives are migrating from commission-based dealer networks toward bulk buying structures. The region exhibits the most pronounced disintermediation of legacy distribution channels.
Red River Delta
Granular compost anchors smallholder rice operations compatible with existing broadcast equipment. National food security programs maintain synthetic fertilizer subsidies that constrain organic penetration. Commune-level input shops remain the primary last-mile access point for individual farmers.
North-Central Coast
Livestock-intensive provinces expand agricultural waste-to-fertilizer processing facilities. Dong Nai and Binh Duong industrial poultry operations supply nitrogen-dense chicken manure amendments. Song Gianh Joint Stock Corporation leverages its manufacturing base to supply compost-dominant blends.
Ho Chi Minh City Peri-Urban Zone
Vegetable producers serving metropolitan markets convert to liquid formulations compatible with fertigation systems. Provincial carbon-soil programs redirect procurement toward certified domestic blenders. Mobile-order platforms pilot direct connections between compost blenders and commune-level buying groups.
Vietnam Organic Fertilizer Market Competitive Landscape
Player mix skews toward joint stock corporations with established dealer networks and specialized biofertilizer innovators. The vendor base fragments across compost-dominant blenders, liquid microbial formulators, and state-affiliated chemical fertilizer networks with organic portfolio extensions. Three strategic archetypes dominate: north-central manufacturing specialists, Mekong Delta horticulture-focused innovators, and Red River Delta distribution-anchored incumbents. Competitive moves center on dealer network digitalization and laboratory verification capability investments that accelerate TCVN certification timelines.
Among joint stock specialists, Song Gianh Joint Stock Corporation, Bioway Hitech Joint Stock Company, and Binh Dien Fertilizer Joint Stock Company occupy distinct positioning vectors. Song Gianh represents the north-central manufacturing archetype with compost-dominant production orientation. Bioway Hitech exemplifies the liquid microbial formulation specialist serving precision-drip horticulture clusters. Binh Dien anchors the downstream distribution archetype through long-established dealer network control in the Red River Delta. These three entities collectively illustrate the geographic and technological segmentation shaping competitive dynamics.
| Leading Market Players |
|---|
| Song Gianh Joint Stock Corporation |
| Bioway Hitech Joint Stock Company |
| Binh Dien Fertilizer Joint Stock Company |
| Vedan Vietnam Enterprise Corporation Limited |
| Bio Agrosa Fertilizer |
| PetroVietnam Fertilizer and Chemicals Corporation |
| Baconco Company Limited |
| Ha Lan Fertilizer Corporation |
| Que Lam Group Joint Stock Company |
| Others |
Value Network & Pricing Analysis
Six-to-nine-month microbial inoculant shelf-life constraints compress inventory turnover cycles and amplify pricing power for blenders with cold-chain capabilities, while feedstock seasonality in Vietnam's rice straw and poultry manure markets creates procurement cost volatility that propagates through to farmer-facing price tiers.
Pricing Analysis
Formulation-generation pricing gaps separate first-generation compost products from second-generation biofertilizers and emerging microbial consortia, with TCVN-certified organic amendments commanding premiums over uncertified alternatives. Price differentiation hinges on certification grade and volume scale, with agricultural cooperatives securing bulk discounts unavailable to individual smallholders. Pricing pressure stems from subsidized urea competition in rice-dominated provinces, compressing margins for compost-dominant blenders. Individual farmers operating under two hectares exhibit highest price sensitivity, while export-oriented horticulture cooperatives absorb premiums for phytosanitary-compliant inputs.
Supply Chain Analysis
Just-in-time feedstock procurement dominates among Mekong Delta compost operators, while strategic stockpiling of chicken manure concentrates among Dong Nai and Binh Duong processors managing livestock cycle volatility. Supply draws from Vietnam's rice straw harvests, industrial poultry operations, and peat deposits in northern provinces. Raw material dependencies center on seasonal agricultural residues, livestock waste streams, and leonardite mining permits. Single-source vulnerability runs through provincial extension program subsidies that can redirect overnight. Distribution runs through commune-level input shops and emerging mobile-order platforms connecting blenders directly to cooperative buying groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's organic fertilizer sector approaches a platform-economics inflection as provincial carbon-soil programs and EU-Vietnam sanitary rules create interoperability standards that favor certified blenders with integrated laboratory verification capabilities over fragmented legacy distributors.
For Market Incumbents: Compound dealer network digitalization investments with in-house fermentation capacity to defend against microbial consortia specialists eroding horticulture premiums. Accelerate TCVN certification pipeline throughput to outpace 18-24 month registration timelines constraining new entrants. Prioritize backward integration into anaerobic digestion feedstock contracts in livestock-intensive provinces to secure nitrogen-dense input supply against poultry cycle volatility. For New Entrants and Emerging Players: TCVN fast-track partnerships with provincial Department of Agriculture and Rural Development laboratories offer lowest-friction market entry for biofertilizer innovators. Target Central Highlands coffee and pepper cooperatives exhibiting fastest disintermediation away from commission-based dealer networks. Pursue white-space in liquid microbial formulations for Da Lat greenhouse fertigation infrastructure, where precision-drip compatibility commands sustained premium positioning. For Investors and Strategic Acquirers: Carve-out targets emerge from state-affiliated chemical fertilizer networks with organic portfolio extensions seeking to monetize non-core biofertilizer divisions. Long-term viability centers on blenders with captive laboratory verification capabilities and provincial extension program relationships. Watch for inflection when EU-Vietnam Free Trade Agreement phytosanitary enforcement intensifies documentation requirements for export-bound produce, accelerating certified input substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Dealer Network Digitalization | Mobile-order platforms bypass traditional distributor markups and connect compost blenders directly to commune-level buying groups. |
| Laboratory Verification Investment | In-house TCVN testing capabilities accelerate product registration timelines and satisfy cooperative procurement transparency demands. |
| Anaerobic Digestion Integration | Backward integration into livestock waste processing secures nitrogen-dense feedstock supply against poultry cycle price volatility. |
| Provincial Extension Partnership | Direct relationships with Departments of Agriculture and Rural Development channel subsidized organic input trials toward certified blenders. |
| Microbial Consortia Development | Nitrogen-fixing bacteria and phosphate-solubilizing fungi combinations miniaturize application rates while maintaining yield parity with synthetics. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of TCVN regulatory filings, provincial extension program documentation, and EU-Vietnam Free Trade Agreement sanitary rule implementations. Primary interviews engaged fermentation operations technicians, Department of Agriculture and Rural Development extension officers, agricultural cooperative procurement managers, and horticulture export compliance specialists. Secondary sources incorporated Vietnam Ministry of Agriculture and Rural Development fertilizer registration databases, customs trade data on organic input imports, and provincial carbon-soil program guidelines. Bottom-up demand modeling from individual farmer and cooperative purchasing patterns triangulates against top-down supply-side capacity assessments across compost, manure, and biofertilizer production facilities.
Segmentation dimensions modeled span product type, form, application, and end user across the projection horizon, with granular-versus-liquid form preferences and cooperative-versus-individual procurement patterns treated as dynamic variables. CAGRs derive from volume-weighted growth trajectories in horticulture versus agricultural crop applications, calibrated against provincial extension program subsidy allocations and EU-bound export certification trends. Forecast inputs incorporate TCVN registration pipeline velocity, anaerobic digestion infrastructure buildout timelines, and microbial inoculant viability degradation curves in tropical storage conditions.
Decision-makers should treat outputs as directional under assumptions of sustained EU phytosanitary enforcement and stable provincial extension subsidy levels; material deviation in either would warrant model refresh. Forecasts reflect these base conditions without incorporating extreme weather disruption to rice straw feedstock availability or abrupt synthetic fertilizer subsidy elimination. Revision becomes warranted when carbon credit monetization thresholds for organic fertilizer users cross implementation feasibility thresholds under Ministry of Natural Resources and Environment guidelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Brazil Organic Fertilizer Market
Fertilizers
Enhanced Efficiency Fertilizer Market
Fertilizers
GCC Organic Fertilizer Market
Fertilizers
China Fertilizers Market
Fertilizers
Thailand Fertilizers Market
Fertilizers
United States Organic Fertilizers Market
Fertilizers
Biochar Fertilizer Market
Fertilizers
Brazil Specialty Fertilizer Market
Fertilizers
China Organic Fertilizers Market
Fertilizers
Africa Micronutrient Fertilizer Market
Fertilizers
Italy Foliar Fertilizer Market
Fertilizers
Europe Specialty Fertilizer Market
Fertilizers
Boron Fertilizers Market
Fertilizers
Ammonium Thiosulfate Fertilizer Market
Fertilizers
Germany Fertilizer Market
Fertilizers
Biological Organic Fertilizers Market