
 Global Nanomembrane Market | 2026-2036
Global Nanomembrane Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nanomembrane Market Intelligence
The modularization of filtration systems, which bundles nanomembranes with pre-treatment and diagnostic controls, is realigning buyer preference toward integrated solutions. Dupont de Nemours, Inc. leverages its material science leadership to produce high-performance polymeric films. Koch Separation Solutions specializes in custom-engineered systems for challenging industrial streams. Toray Industries, Inc. maintains a strong market position through its vast manufacturing scale in composite and polymeric membranes.
Nanomembranes are engineered barriers with pore sizes typically below 100 nanometers, designed for precise molecular-level separation. These structures are created using processes like phase inversion to separate ions and molecules from liquids or gases. Polymeric products dominate the market due to their versatility and lower production costs, while ceramic variants are specified for high-temperature or chemically aggressive applications. Water purification continues to be the primary application, with gas separation emerging as a significant growth area.
Regulatory frameworks from the US EPA concerning water contaminants and the EU's REACH directive on chemical substances create stringent performance benchmarks. In China, MEE standards for industrial effluent directly influence demand for advanced separation technologies. These rules mandate the removal of specific micropollutants, driving market access for certified membrane products. The choice between lower-cost polymeric and durable ceramic membranes remains a central strategic consideration for end-users.
Market Dynamics
The central force shaping the nanomembrane market is the convergence of stringent industrial water purity regulations and the expansion of advanced manufacturing. Mandates for ultrapure water in semiconductor fabrication, particularly from regulators like China's MEE, are compelling investment in high-rejection filtration.
Growth Catalysts
- Stricter Effluent Standards:Regulations such as the EU's REACH directive, which governs chemical substances, and China's MEE standards for industrial wastewater, mandate the removal of micropollutants, directly benefiting certified nanomembrane products.
- Semiconductor Sector Demand:The production of ultrapure water for wafer cleaning is a primary catalyst, with demand concentrated in electronics fabrication clusters across Taiwan, South Korea, and Japan.
- Material Science Advances:The development of advanced polymeric and composite materials enhances membrane durability, selectivity, and resistance to fouling, broadening applicability in challenging industrial streams.
Market Restraints
- High Capital Expenditure:The significant initial investment required for ceramic nanomembrane systems, despite their durability, limits adoption in cost-sensitive sectors compared to lower-cost polymeric alternatives.
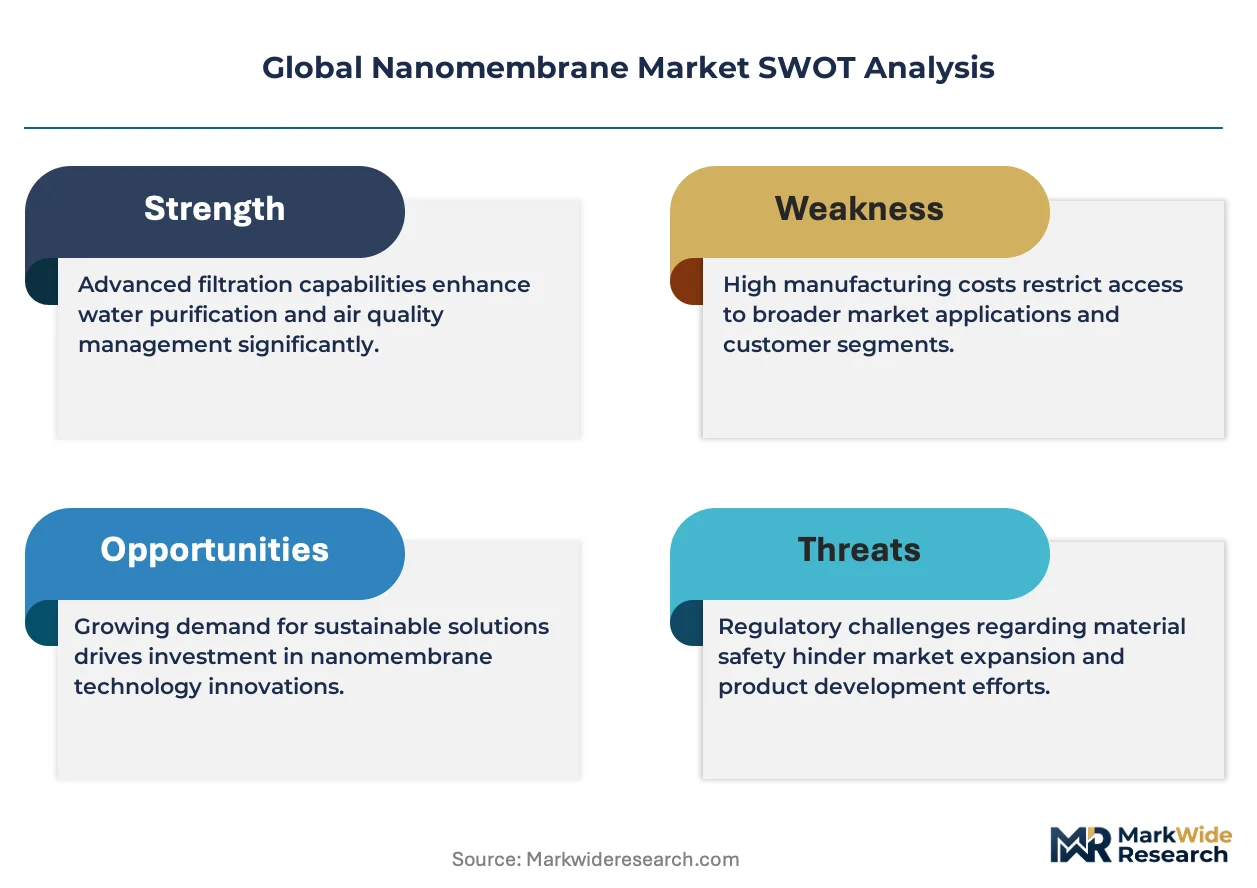
- Membrane Fouling:The persistent issue of membrane fouling requires frequent chemical cleaning and maintenance cycles, which increases operational costs, generates secondary waste streams, and causes process downtime.
- Input Material Volatility:The market's reliance on a concentrated supply of specialized polymer precursors and ceramic powders exposes manufacturers and end-users to price fluctuations and potential supply chain disruptions.
Strategic Opportunities
- Gas Separation Applications:A major opportunity lies in gas separation, particularly for carbon capture from industrial flue gas and hydrogen purification, creating a new, large-scale application vertical beyond water treatment.
- Pharmaceutical Filtration in India:The expansion of pharmaceutical and biotechnology manufacturing in India, supported by government incentives, opens new avenues for sterile filtration and bioprocessing applications.
- Smart Water System Integration:The convergence of nanomembranes with IoT sensors and AI-powered analytics enables predictive maintenance and optimized performance within modular, automated water treatment systems.
Industry Challenges
- Lack of Performance Standardization:A absence of universally accepted testing protocols and performance metrics for nanomembrane rejection and flux makes direct product comparisons difficult for end-users.
- System Integration Complexity:Retrofitting advanced nanomembrane modules into existing industrial water treatment plants often requires significant and costly modifications to legacy infrastructure and control systems.
- Specialized Engineering Talent:A shortage of process engineers with the expertise to design, commission, and operate sophisticated nanomembrane systems tailored to specific industrial waste streams constrains deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nanomembrane Market |
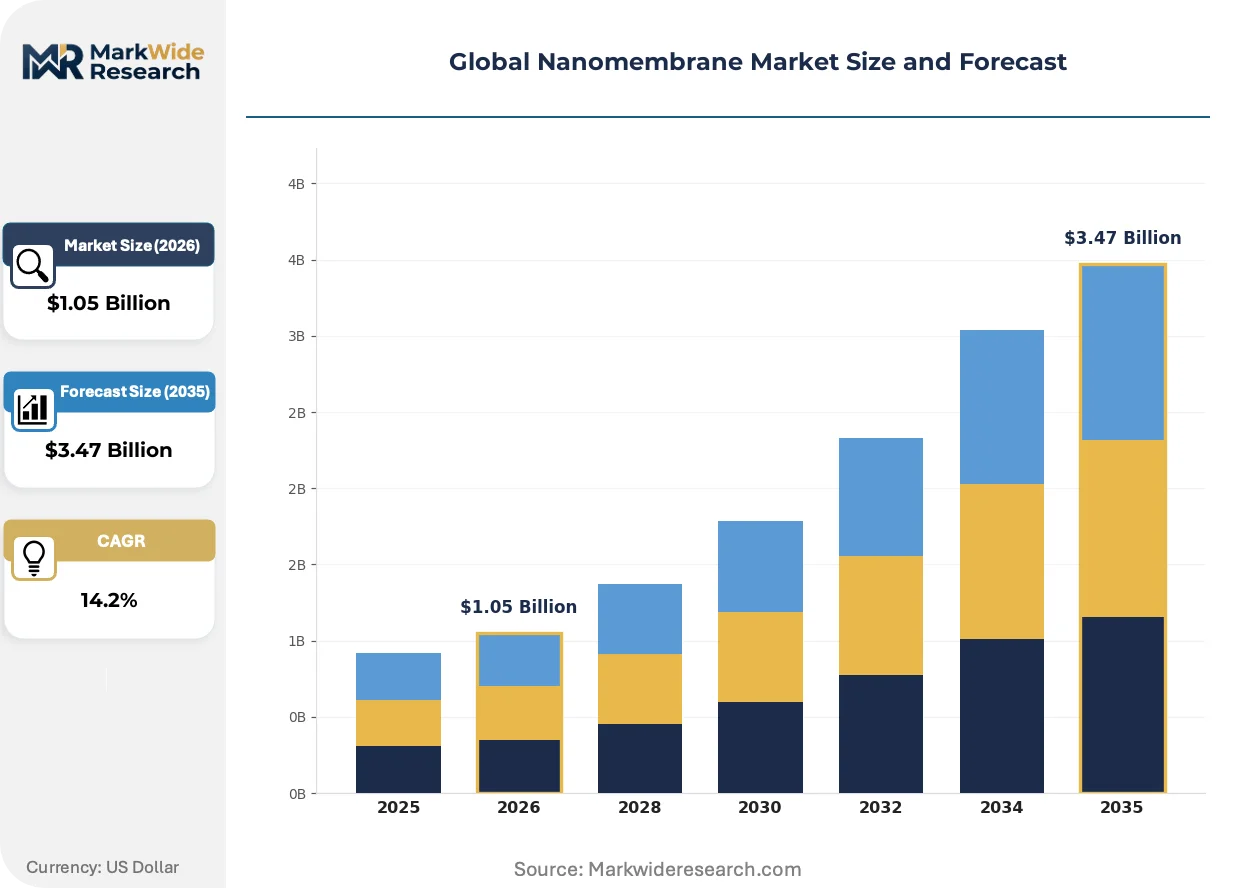
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $3.47 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymeric, Ceramic, Metallic, Composite, Carbon-Based Technology: Electrospinning, Phase Inversion, Atomic Layer Deposition, Chemical Vapor Deposition, Self-Assembly Application: Water Purification, Gas Separation, Energy Storage, Electronics Fabrication, Biomedical Engineering End User Industry: Pharmaceuticals, Semiconductor Manufacturing, Renewable Energy, Chemical Processing, Food & Beverage |
| Companies Covered | Pall Corporation, Microdyn-Nadir GmbH, Dupont de Nemours, Inc., Alfa Laval AB, Toray Industries, Inc., Nitto Denko Corporation, Synder Filtration, Inc., Pentair, Koch Separation Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nanomembrane Market Strategic Shifts & Innovations
System-level integration is fundamentally changing market dynamics, as end-users increasingly favor modular, pre-engineered filtration skids over discrete components. This shift places a premium on vendors who can bundle nanomembranes with pre-treatment, post-treatment, and diagnostic controls into a guaranteed performance package.
Biomimetic membranes, which incorporate aquaporin proteins into a polymer matrix, offer exceptionally high water permeability and selectivity. These advanced structures are gaining traction in municipal desalination and water reuse applications where energy efficiency is paramount. This biological design philosophy is converging with traditional polymer chemistry to create a new class of high-flux, low-fouling hybrid membranes.
The United States EPA's establishment of enforceable limits for PFAS contaminants in drinking water is a significant regulatory driver. This action compels municipal water utilities and industrial facilities to implement advanced filtration technologies capable of removing these persistent chemicals. Consequently, demand for polymeric nanomembranes specifically certified for high PFAS rejection is accelerating across the US.
A pronounced shift in procurement favors complete, modular filtration systems over individual membrane elements. This trend displaces the traditional model where end-users or their engineering contractors would design and assemble systems from components sourced from multiple vendors. This preference for integrated, turnkey solutions is most evident in the semiconductor and pharmaceutical sectors in Germany and South Korea.
Global Nanomembrane Market Segmentation
The nanomembrane market exhibits diverse segmentation, reflecting the varied material science, fabrication techniques, and specialized application requirements across different industries. Understanding these segments is critical for manufacturers to align product development with specific end-user demands and regulatory compliance mandates.
Product Type:
Specific product types face varying regulatory hurdles, influencing their market access and end-use applications. For example, ceramic membranes for high-temperature industrial effluents require different certifications than polymeric membranes used in drinking water treatment.
- Polymeric:These membranes, predominantly made from organic polymers, offer high versatility and cost-effectiveness for large-scale production. Demand concentrates in water purification for municipal and industrial use, with strict performance benchmarks from the US EPA concerning PFAS contaminants.
- Ceramic:Composed of inorganic materials like alumina or zirconia, ceramic membranes are specified for applications demanding high thermal stability and chemical resistance. These robust systems are critical for challenging industrial streams, often needing approval under China's MEE standards for effluent treatment.
- Metallic:Metallic nanomembranes provide high mechanical strength and precise pore size distribution for specialized gas separation.
- Composite:These multi-layered membranes combine different materials to enhance selectivity, flux, and fouling resistance for advanced filtration.
- Carbon-Based:Carbon nanomembranes, including graphene oxide and carbon nanotubes, offer novel separation properties for emerging applications.
Polymeric nanomembranes sit at the top of the volume ranking, with composite variants climbing the fastest.
Technology:
The choice of nanomembrane technology often correlates with capital expenditure thresholds and operational efficiency targets for industrial users.
- Electrospinning:This method creates non-woven nanofiber membranes with high surface area and porosity, suitable for air filtration and biomedical applications. Electrospinning enables the precise control of fiber diameter and membrane thickness for specific separation tasks.
- Phase Inversion:A widely adopted technique for polymer membrane fabrication, phase inversion involves converting a homogeneous polymer solution into a two-phase system, forming a porous structure. This process is fundamental for producing membranes used in water treatment and general industrial separations.
- Atomic Layer Deposition:This precise thin-film deposition technique enables the creation of highly uniform and ultrathin nanomembranes for advanced electronics.
- Chemical Vapor Deposition:Chemical vapor deposition forms dense, defect-free membrane layers through gas-phase reactions, used in specialized gas separation.
- Self-Assembly:Self-assembly techniques create highly ordered nanostructures, enabling the development of advanced membranes with tailored properties.
Phase inversion remains a foundational technology, while atomic layer deposition gains traction for precision applications.
Application:
The diverse range of nanomembrane applications reflects specialized separation needs across various industrial and environmental challenges.
- Water Purification:This primary application involves removing dissolved solids, ions, and micropollutants from various water sources, including municipal and industrial wastewaters. Demand is driven by strict regulatory limits from the US EPA on contaminants like PFAS and the need for ultrapure water in electronics fabrication.
- Gas Separation:Nanomembranes selectively separate specific gases from mixtures, critical for industrial processes such as carbon capture from flue gas and hydrogen purification. This segment represents a significant growth area due to global decarbonization efforts and energy transition initiatives.
- Energy Storage:Nanomembranes function as separators in batteries and fuel cells, influencing performance and safety characteristics.
- Electronics Fabrication:The semiconductor industry uses nanomembranes for ultrapure water production and chemical filtration during wafer manufacturing.
- Biomedical Engineering:Applications include drug delivery systems, diagnostic devices, and sterile filtration in pharmaceutical manufacturing.
Water purification accounts for the largest share, while gas separation expands rapidly.
End User Industry:
Different end-user industries drive demand for nanomembranes based on their unique purity requirements and process specifications.
- Pharmaceuticals:This sector utilizes nanomembranes for sterile filtration, bioprocessing, and purification of active pharmaceutical ingredients. The expansion of pharmaceutical manufacturing in India, supported by government incentives, creates new market avenues.
- Semiconductor Manufacturing:This industry relies heavily on nanomembranes for producing ultrapure water essential for wafer cleaning and other fabrication steps. Demand is concentrated in electronics fabrication clusters across Taiwan, South Korea, and Japan, driven by mandates for high-rejection filtration.
- Renewable Energy:Nanomembranes find use in fuel cells, hydrogen production, and other clean energy technologies requiring efficient separation.
- Chemical Processing:This industry employs nanomembranes for solvent recovery, product purification, and effluent treatment to meet environmental standards.
- Food & Beverage:Applications include clarification, sterilization, and concentration processes for various food and beverage products.
Semiconductor manufacturing dictates stringent specifications, compelling continuous innovation in membrane performance across all industries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The nanomembrane market initially scaled in regions with stringent industrial water purity requirements and advanced manufacturing bases. Early adoption centered on countries driving semiconductor innovation and those facing critical water scarcity. This foundational development established key demand hubs.
United States
United States demand for nanomembranes is driven by semiconductor needs for ultrapure water and municipal efforts to remove contaminants. The US EPA's enforceable limits for PFAS compel advanced filtration technology adoption. Major electronics fabrication facilities in Arizona and New York require high-rejection systems.
China
China's robust industrial expansion and stringent environmental mandates propel nanomembrane adoption for wastewater treatment. MEE standards for industrial effluent directly influence demand for advanced separation technologies. Electronics manufacturing hubs in the Pearl River Delta require continuous innovation in filtration.
Japanese
Japanese advanced manufacturing sectors, particularly electronics, necessitate high-performance nanomembranes for ultrapure water. Strict environmental regulations and water reuse initiatives stimulate demand for efficient filtration. Major fabrication plants in Kumamoto and Hiroshima continuously upgrade water treatment infrastructure.
South Korea
South Korea's dominant position in semiconductor and display manufacturing drives significant nanomembrane demand for ultrapure water. The country's environmental regulations, alongside MFDS standards, mandate high-efficiency separation technologies. Electronics fabrication clusters around Seoul and Suwon are early adopters of modular systems.
India
India's rapidly expanding pharmaceutical and biotechnology manufacturing sector creates new avenues for sterile filtration and bioprocessing applications. Government initiatives like the PLI scheme support this growth, increasing demand for certified membrane products. Major pharma clusters in Hyderabad and Ahmedabad integrate advanced nanomembrane systems.
Global Nanomembrane Market Key Industry Players
Premium-margin players sit above commodity-margin players across the nanomembrane market, driven by material science leadership and system integration capabilities. The market exhibits a tiered structure, with established chemical giants and specialized filtration companies coexisting with emerging technology providers. Strategic archetypes include integrated solution providers, material specialists, and custom-engineered system developers. Competitive moves center on portfolio diversification, strategic partnerships, and capacity expansion to meet diverse industrial needs.
On the premium-tier vector, Dupont de Nemours, Inc. leverages its material science leadership to produce high-performance polymeric films. Koch Separation Solutions exemplifies a specialist in custom-engineered systems for challenging industrial streams, offering integrated solutions. Toray Industries, Inc. maintains a strong market position through its vast manufacturing scale in composite and polymeric membranes, representing a high-volume material specialist. These companies anchor different segments of the market, from advanced material supply to comprehensive system deployment, shaping the competitive dynamics through their specialized offerings and global reach.
| Leading Market Players |
|---|
| Pall Corporation |
| Microdyn-Nadir GmbH |
| Dupont de Nemours, Inc. |
| Alfa Laval AB |
| Toray Industries, Inc. |
| Nitto Denko Corporation |
| Synder Filtration, Inc. |
| Pentair |
| Koch Separation Solutions |
Cost & Logistics Intelligence
Vertical integration into advanced material science anchors the competitive supply position for premium nanomembranes, directly influencing their pricing power and market access.
Pricing Analysis
Value-based pricing governs the nanomembrane market, reflecting specialized material science and application-specific performance. Price differentiation stems from certification levels for specific contaminants like PFAS, material durability, and the degree of system customization. Pricing softness runs through commodity polymeric membranes due to increased production scale and competition. Semiconductor and pharmaceutical end-users exhibit lower price sensitivity compared to general industrial wastewater treatment facilities.
Supply Chain Analysis
Specialized engineering talent availability in Japan and South Korea underpins the advanced nanomembrane supply chain. Raw material dependencies include specialized polymer precursors and high-purity ceramic powders like alumina and zirconia. A structural risk involves input material volatility, exacerbated by a concentrated supply base for these specialized chemicals. Distribution runs through a hybrid model, combining direct sales for custom-engineered systems with channel partners for standardized membrane elements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nanomembrane market acts as a regulatory compounder, with the US EPA's enforceable limits for PFAS contaminants driving significant demand for advanced filtration solutions.
For Market Incumbents:Hedge against the threat of membrane fouling by investing in advanced material science for self-cleaning or low-fouling membrane chemistries. Expand system integration capabilities through strategic partnerships to offer complete, modular filtration skids. Focus R&D on biomimetic membranes to deliver energy-efficient solutions for municipal desalination, countering rising operational costs. Reinforce market position by securing critical certifications for emerging contaminants like PFAS.
For New Entrants and Emerging Players:Cost-sensitive industrial facilities in developing markets represent an underserved buyer archetype for modular nanomembrane systems. Target the gas separation vertical, particularly carbon capture and hydrogen purification, by developing specialized metallic or carbon-based membranes. Penetrate the Indian pharmaceutical sector by offering certified sterile filtration solutions aligned with government incentives. A go-to-market angle focusing on integrated smart water systems with AI-powered analytics creates differentiation.
For Investors and Strategic Acquirers:Roll-up economics work for specialized system integrators because of the fragmented nature of component suppliers and the demand for turnkey solutions. Long-term viability rests on the indispensable role of nanomembranes in critical infrastructure and regulatory compliance. Target archetype includes technology providers with patented breakthroughs in biomimetic membranes or gas separation. The signal to watch is widespread commercial adoption of carbon capture technologies or a significant shift in pharmaceutical bioprocessing standards.
| Strategic Initiative | Industry Significance |
|---|---|
| Biomimetic Membrane R&D Acceleration | Enhances energy efficiency and selectivity for municipal desalination and water reuse applications. |
| Modular System Integration Partnerships | Addresses end-user preference for turnkey solutions, reducing installation complexity and operational risk. |
| PFAS Certification Investment | Secures market access in the United States by meeting stringent regulatory mandates for drinking water purification. |
| Gas Separation Pilot Programs | Validates membrane performance for large-scale industrial carbon capture and hydrogen purification projects. |
| AI-Powered Analytics Integration | Optimizes system performance and enables predictive maintenance for advanced water treatment facilities. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, integrating primary insights with extensive secondary data validation. Primary research involved discussions with R&D directors, plant managers, procurement leads, and regulatory compliance officers across key geographies. Secondary data sources included environmental protection agency reports, industry association publications, company annual reports, and academic journals on membrane science.
The forecast analysis anchored the projection horizon to historical performance across comparable periods, establishing baseline growth trajectories. The analytical framework modeled segmentation dimensions including product type, technology, application, end-user industry, and regional regulatory clusters. Compound annual growth rates were derived through a combination of regression analysis and expert consensus. Key industry-specific forecast inputs included semiconductor manufacturing expansion plans and global wastewater treatment infrastructure investment.
Underlying measurement precision varies by segment; established water purification applications carry tighter precision than emerging gas separation markets. Forecasts reflect assumptions regarding regulatory stability and material science breakthroughs. Material deviation in global trade policies or input material availability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Global Bitumen Membranes Market
Membrane Materials
Global Ultrafiltration Market
Membrane Materials
Global Polymer Nanomembrane Market
Membrane Materials
Liquid Applied Membranes Market
Membrane Materials
Reverse Osmosis (RO) Membrane Market
Membrane Materials
Oxygen Barrier Materials Market
Membrane Materials
Membrane Polymers Market
Membrane Materials
Global Geomembrane Market
Membrane Materials
Membrane Bioreactor Market
Membrane Materials
Membrane Filter Cartridge Market
Membrane Materials
PTFE Membrane Market
Membrane Materials
Global Tubular Membranes Market
Membrane Materials
Global Ceramic Membrane Market
Membrane Materials
Global Spiral Membrane Market
Membrane Materials
Global Chemical Separation Membranes Market
Membrane Materials
Geosynthetic Clay Liner Market