
 Global Membrane Structures Market | 2026-2036
Global Membrane Structures Market Size, Share, and Industry Trends Forecast 2026-2036
Global Membrane Structures Market Foresight
European PTFE coated fiberglass production is pivoting toward higher tensile strength specifications for long-span stadium roofs. Serge Ferrari leverages its laminate coating expertise to sustain premium positioning in retractable roof systems. Saint-Gobain anchors its competitive stance through integrated glass fiber supply chains. Seaman Corp differentiates via military-grade fabric durability standards transferred to civilian architecture.
Membrane structures employ high-performance polymer fabrics or foils tensioned across cable, frame, or pneumatic support systems to create enclosed or shaded volumes without rigid roofing; PTFE coated fiberglass achieves 50-year lifespans with 15% solar transmittance, while ETFE foils at 1% of glass weight enable 300-foot unsupported spans. Tensile structures and cable net configurations dominate commercial applications due to material efficiency and visual lightness. ETFE foils represent the fastest-expanding product category as botanical gardens and aquatic centers specify bi-layer pneumatic cushions. Sports facilities command the deepest margin pools among application segments given performance warranties and custom engineering requirements.
FDA material safety standards govern membrane contact surfaces in food processing and agricultural applications, while REACH compliance in Europe restricts perfluorinated compound formulations in coating chemistry. China's GB standards for fire resistance classification and Germany's KBA-adjacent building material approvals create divergent certification pathways that fragment supplier qualification costs. Stakeholders must monitor evolving fire performance codes in Qatar and Saudi Arabia as Gulf state stadium construction accelerates ahead of international sporting calendars.
Market Dynamics
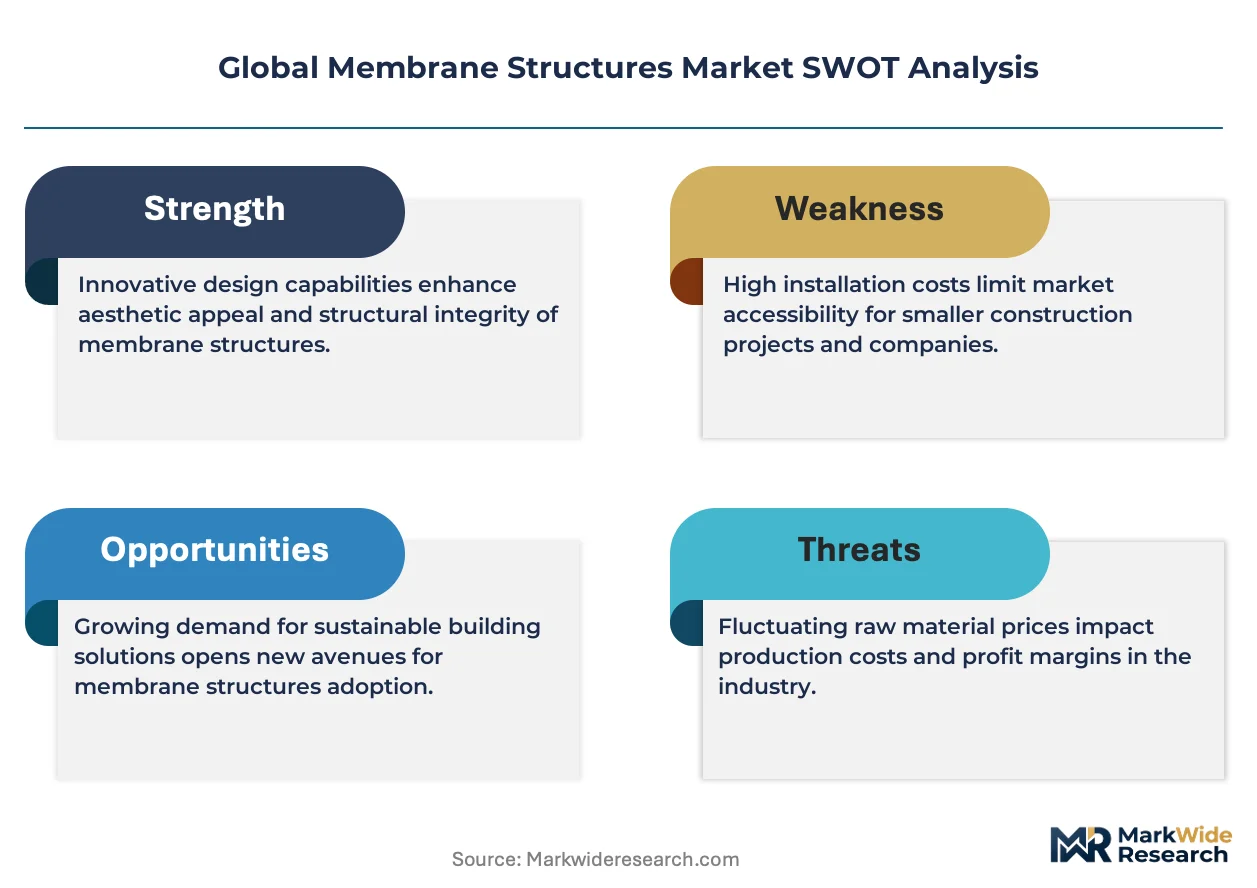
ETFE foil technology is compressing project timelines and expanding design freedom for long-span enclosures, forcing traditional PTFE suppliers to defend specification positions in sports and cultural infrastructure.
Growth Catalysts
- REACH compliance evolution:European coating chemistry restrictions are accelerating R&D investment in fluoropolymer alternatives that maintain UV resistance without restricted perfluorinated compounds.
- Sports facility construction:Qatar and Saudi Arabia stadium buildouts ahead of international sporting calendars are generating concentrated demand for performance-warranted tensile roof systems.
- Pneumatic cushion systems:Bi-layer ETFE configurations are displacing conventional glazing in botanical gardens and aquatic centers due to thermal performance and weight advantages.
Market Restraints
- Glass fiber supply concentration:European PTFE coated fiberglass production depends on integrated glass fiber supply chains concentrated in France and Germany, creating input vulnerability.
- Silicone raw material volatility:ETFE foil lamination requires specialized silicone adhesives subject to petrochemical feedstock price swings.
- Structural substitution:Mass timber and advanced steel space frames are capturing mid-span enclosure projects where membrane aesthetics do not justify premium engineering costs.
Strategic Opportunities
- China megacity infrastructure:GB standards fire resistance classification pathways are opening specification opportunities in Shanghai and Shenzhen transit hubs.
- Agricultural controlled-environment applications:FDA material safety standards for food contact surfaces are enabling membrane adoption in processing facilities and greenhouse complexes.
- Photovoltaic integration:Flexible solar film lamination onto tensile membranes is unifying energy generation with enclosure functions in Middle Eastern solar farms.
Industry Challenges
- Specialized tensile engineering talent:Cable net analysis and form-finding computation skills concentrate in German and Swiss engineering consultancies, limiting project execution capacity elsewhere.
- Multi-jurisdiction certification timelines:KBA-adjacent building material approvals in Germany diverge from Qatar civil defense fire performance codes, fragmenting supplier qualification costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Membrane Structures Market |
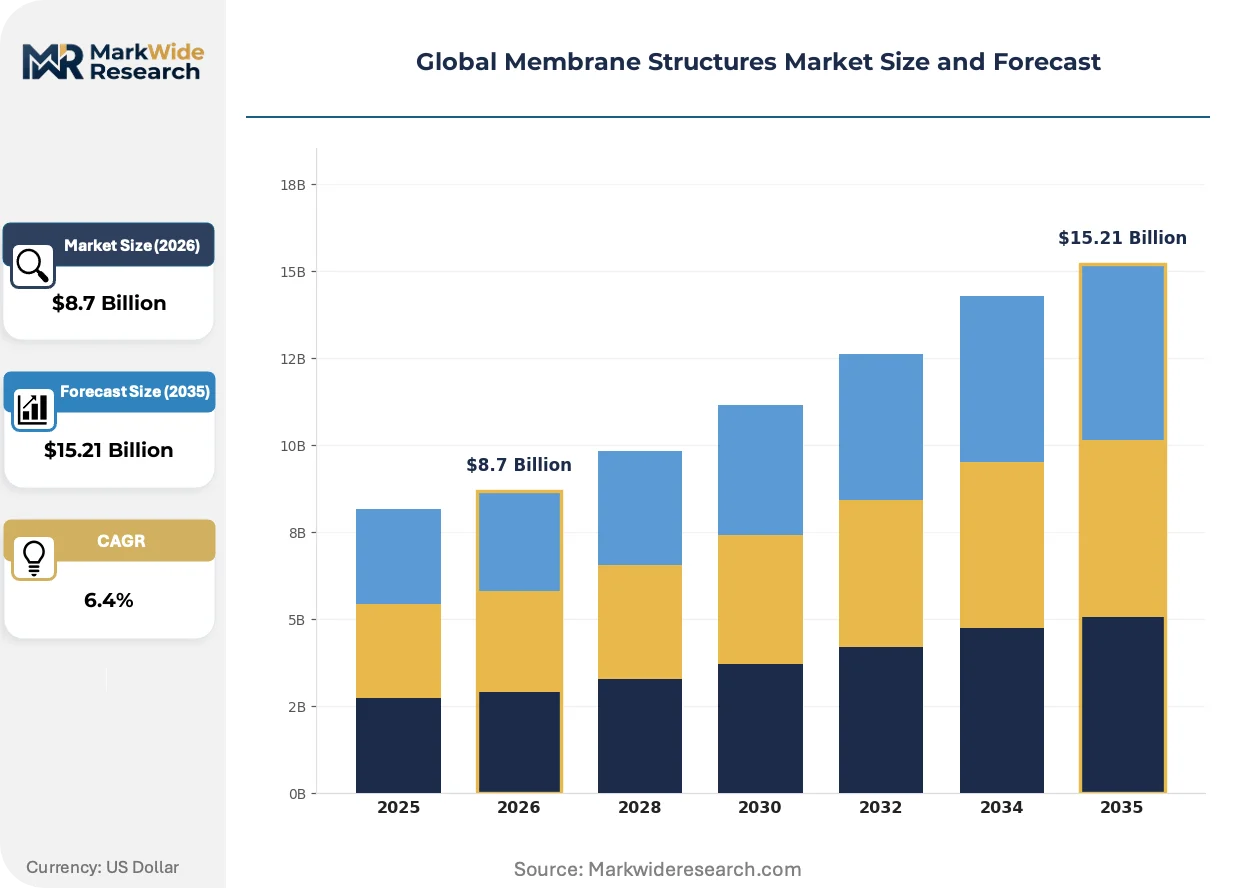
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fabric Membranes, PTFE Coated Fiberglass, ETFE Foils, PVC Coated Polyester, Silicone Coated Glass, PVDF Laminates Application: Sports Facilities, Exhibition Centers, Transportation Hubs, Commercial Complexes, Agricultural Coverings, Cultural Venues End User: Construction Firms, Event Organizers, Agricultural Producers, Equipment Manufacturers, Architectural Firms, Facility Managers Installation Type: Tensile Structures, Cable Net Structures, Air Supported Structures, Frame Supported, Retractable Roofs, Canopies |
| Companies Covered | Serge Ferrari, Seaman Corp, Chukoh Chem, Atex Membrane, Heytex, Sattler, Hiraoka, Saint-Gobain, Vector Foiltec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Membrane Structures Market Shifts & Advancements
Material science advances and computational design tools are compressing the traditional trade-off between structural efficiency and architectural expression in lightweight enclosure systems.
Adaptive membrane systems with embedded sensor networks and electroactive polymers are unifying real-time structural health monitoring with climate-responsive surface properties. Stadium operators in Germany and Qatar are specifying these intelligent skins for retractable roof applications where wind load and snow accumulation vary unpredictably. The technology is enabling predictive maintenance contracts that shift supplier revenue from capital equipment to performance-guaranteed service agreements.
REACH restrictions on perfluorinated compounds are forcing coating chemistry reformulation across European PTFE production. Manufacturers are investing in hybrid silicone-fluoropolymer laminates that maintain solar transmittance specifications while satisfying ECHA substance restrictions. Sports facility projects in France and Spain face extended material qualification timelines as suppliers navigate updated safety data sheet requirements.
Buyers are consolidating procurement around design-build-operate contracts that bundle membrane supply with decades-long maintenance obligations. Municipal clients in China's Yangtze River Delta are leading this shift, transferring technical risk to contractors in exchange for lifecycle cost certainty. The model is compressing traditional equipment supply margins while expanding recurring service revenue pools for qualified installers.
Global Membrane Structures Market Segmentation
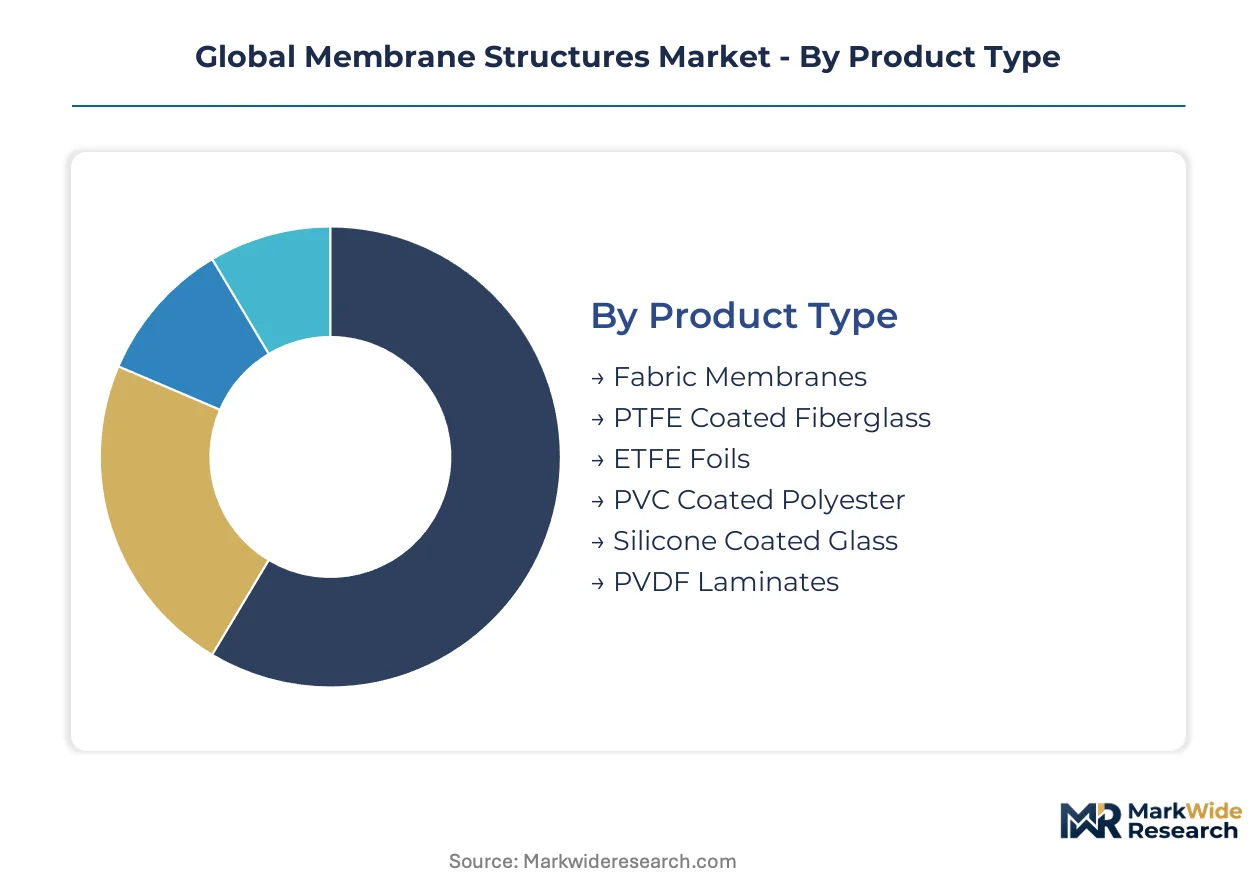
Membrane structures serve radically different performance requirements across stadium roofs, transit canopies, and agricultural enclosures. Supply chains for high-performance fluoropolymers concentrate among European coating specialists, while ETFE foil production clusters with petrochemical feedstock access. Specification patterns diverge sharply by load-bearing geometry and climatic exposure.
Product Type:
Raw material supply for coated fabrics clusters in France and Germany, where integrated glass fiber production anchors PTFE laminate manufacturing.
- PTFE Coated Fiberglass:High-tensile woven glass substrate with fluoropolymer coating achieves 50-year service life and 15% solar transmittance. Demand concentrates in Qatar and Saudi Arabia stadium projects where performance warranties mandate material traceability.
- ETFE Foils:Extruded fluoropolymer film at 1% of equivalent glass weight enables 300-foot unsupported spans with pneumatic cushion configurations. Bi-layer systems are displacing conventional glazing in German botanical gardens and aquatic centers due to thermal performance advantages.
- Fabric Membranes:Woven polyester or fiberglass base fabrics with polymer coatings serve cost-sensitive temporary installations.
- PVC Coated Polyester:Lower-cost alternative for short-span commercial canopies with 10-15 year design life.
- Silicone Coated Glass:High-temperature stability suits industrial ventilation and smoke exhaust applications.
- PVDF Laminates:Acrylic-modified fluoropolymer coatings balance UV resistance with manufacturing cost for mid-tier projects.
Today's leader: PTFE Coated Fiberglass. Tomorrow's challenger: ETFE Foils.
Application:
Project scale and engineering complexity create distinct margin tiers across installation categories.
- Sports Facilities:Long-span stadium roofs and retractable systems command premium engineering fees and performance warranties. Qatar's Lusail Stadium and Berlin's Olympic complex renovations specify custom cable net configurations with 25-year maintenance contracts.
- Transportation Hubs:Shenzhen and Shanghai metro entrance canopies drive specification volume for standardized tensile modules. GB standards fire resistance classification opens procurement pathways for qualified European suppliers.
- Exhibition Centers:Temporary-to-permanent flexibility requirements favor modular frame-supported systems.
- Commercial Complexes:Shopping atrium skylights and retail canopies prioritize cost efficiency over extreme durability.
- Agricultural Coverings:FDA material safety compliance enables membrane adoption in food processing facilities and controlled-environment greenhouses.
- Cultural Venues:Architectural signature projects specify custom form-finding for museum atriums and concert halls.
Sports Facilities capture the deepest margin pools. Transportation Hubs offer the steepest volume expansion trajectory.
End User:
Procurement authority is shifting from general contractors toward specialized design-build-operate consortia.
- Construction Firms:Traditional gatekeepers losing specification control to bundled service contracts. Yangtze River Delta municipal clients now transfer technical risk to contractors in exchange for lifecycle cost certainty.
- Architectural Firms:Form-finding computation capabilities concentrate in German and Swiss consultancies, creating bottleneck for complex geometry projects.
- Facility Managers:Stadium operators in Germany and Qatar are specifying intelligent membrane skins with embedded sensor networks for predictive maintenance.
- Event Organizers:Temporary installation demand for festival and exhibition infrastructure.
- Agricultural Producers:Controlled-environment greenhouse operators specifying FDA-compliant membrane surfaces.
- Equipment Manufacturers:OEM integration of membrane components into prefabricated building systems.
Construction Firms retain project volume leadership. Facility Managers are gaining procurement influence through performance-based contracts.
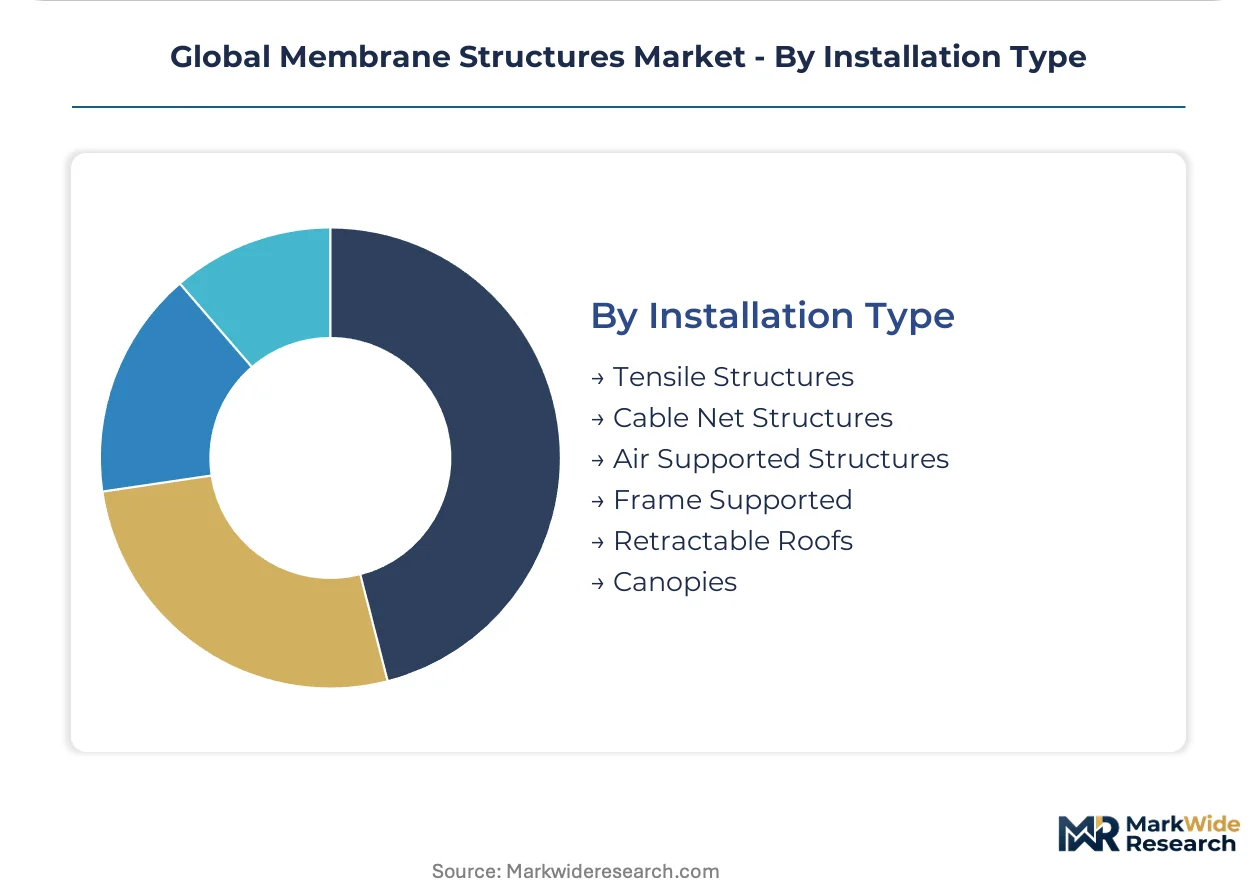
Installation Type:
Structural system selection determines engineering talent requirements and project risk allocation.
- Tensile Structures:Fabric tensioned between masts and boundary cables creates efficient pure-stress surface geometry. Dominates commercial applications due to material efficiency and visual lightness.
- Cable Net Structures:Double-curved mesh of prestressed cables supports membrane cladding for extreme long-span applications. German engineering consultancies control specialized analysis capabilities.
- Air Supported Structures:Internal pressure maintains form without rigid framework for temporary warehousing and sports domes.
- Frame Supported:Steel or aluminum trusses provide structural backup for simplified installation and maintenance access.
- Retractable Roofs:Mechanized folding or sliding systems command highest engineering complexity and maintenance obligations.
- Canopies:Small-to-mid span entrance coverings and shade structures with standardized component libraries.
Tensile Structures dominate current specification. Cable Net Structures face execution capacity constraints from specialized engineering scarcity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting membrane fabrication investment toward jurisdictions with streamlined fire certification pathways. European REACH compliance costs are pushing coating chemistry R&D toward Asian production bases with less restrictive substance controls.
China
Shanghai and Shenzhen transit hubs are driving specification volume for tensile entrance canopies. GB standards fire resistance classification creates procurement pathways for qualified European suppliers seeking market entry. The Yangtze River Delta municipal cluster is pioneering design-build-operate contracts that transfer technical risk to contractors.
Germany
Stadium operators in Berlin and Munich are specifying intelligent membrane skins with embedded sensor networks for predictive maintenance. KBA-adjacent building material approvals diverge from Gulf state codes, fragmenting supplier qualification costs. Engineering consultancies in Stuttgart and Munich control specialized cable net analysis capabilities.
Qatar
Lusail Stadium and other venues ahead of international sporting calendars are generating concentrated demand for performance-warranted tensile roof systems. Civil defense fire performance codes require material traceability documentation that extends qualification timelines. Doha's infrastructure cluster is importing German engineering expertise for long-span cable net configurations.
United States
Agricultural controlled-environment applications are expanding under FDA material safety standards for food contact surfaces. California and Florida greenhouse operators are specifying membrane surfaces for processing facilities. The Southeast manufacturing belt is developing fabrication capacity for mid-span commercial canopy systems.
Saudi Arabia
Stadium construction ahead of international sporting calendars is accelerating specification of PTFE coated fiberglass with 25-year performance warranties. SFDA-aligned building material approvals are creating certification pathways distinct from European REACH frameworks. Riyadh's infrastructure development cluster is consolidating procurement around bundled maintenance obligations.
Global Membrane Structures Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adaptive membrane systems with embedded sensor networks. The market structure reflects moderate consolidation among European coating specialists with integrated glass fiber supply chains, while Asian foil fabricators compete on ETFE production scale. Three archetypes dominate: laminate coating specialists, integrated glass fiber suppliers, and pneumatic cushion system integrators. Capacity expansion in bi-layer ETFE configurations and strategic partnerships for Middle Eastern stadium projects represent the dominant competitive moves.
Among European coating specialists, Serge Ferrari exemplifies the laminate expertise archetype, while Saint-Gobain anchors the integrated supply chain position. Seaman Corp occupies a distinct tier transferring military-grade fabric durability standards to civilian architectural applications. These three companies represent contrasting strategic positions: formulation specialization, upstream raw material control, and cross-sector technology transfer.
| Leading Market Players |
|---|
| Serge Ferrari |
| Seaman Corp |
| Chukoh Chem |
| Atex Membrane |
| Heytex |
| Sattler |
| Hiraoka |
| Saint-Gobain |
| Vector Foiltec |
| Others |
Supply & Pricing Matrix
Specialized silicone adhesive costs for ETFE foil lamination transmit petrochemical feedstock volatility directly into pneumatic cushion system pricing tiers, with European coating specialists passing through raw material swings while Asian foil fabricators absorb margin compression to defend specification positions.
Pricing Analysis
Distributor margins on PTFE coated fiberglass compress as direct procurement from Saint-Gobain and Serge Ferrari intensifies among Qatar stadium developers seeking material traceability documentation. Pricing stratifies across performance-warranted sports facility tiers, mid-span commercial canopy tiers, and temporary installation economy tiers. Cost compression in standard-grade fabric membranes runs through aggressive Asian import competition. Municipal clients in China's Yangtze River Delta demonstrate lowest price sensitivity due to lifecycle cost certainty priorities, while agricultural greenhouse operators in the United States exhibit highest sensitivity to upfront capital outlays.
Supply Chain Analysis
Single-source vulnerability sits with French and German integrated glass fiber production that anchors European PTFE laminate manufacturing. Raw material dependencies encompass E-glass fiber rovings, fluoropolymer resin formulations, and specialized silicone adhesives. Supply chain risk centers on REACH compliance evolution restricting perfluorinated compound formulations that fragment coating chemistry pathways. Distribution runs through design-build-operate consortia consolidating procurement authority away from traditional general contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where European REACH compliance costs for perfluorinated compound restrictions diverge from Saudi SFDA-aligned pathways, creating 15-20% qualification cost differentials that redirect coating chemistry R&D toward Asian production bases.
For Market Incumbents: Acquire specialized cable net engineering consultancies in Stuttgart and Munich to capture bottlenecked form-finding capabilities. Defend specification positions in Qatar and Saudi Arabia stadium projects through captive supply of performance-warranted PTFE coated fiberglass with 25-year maintenance contract bundling. Counter ETFE foil displacement by hybridizing silicone-fluoropolymer laminates that satisfy ECHA substance restrictions. For New Entrants and Emerging Players: Engineering consultancies represent the most penetrable channel partner type for adaptive membrane systems with embedded sensor networks. Target agricultural controlled-environment applications in California and Florida where FDA material safety compliance creates procurement barriers for unqualified suppliers. Pursue photovoltaic integration partnerships with Middle Eastern solar farm developers as the primary go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where specialized tensile engineering talent concentrates in German and Swiss consultancies amid project execution capacity constraints elsewhere. Long-term viability favors coating specialists with backward integration into glass fiber supply and demonstrated multi-jurisdiction certification navigation. Watch for bi-layer ETFE configuration adoption rates in botanical gardens as the inflection indicator signaling technology transition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glass Fiber Supply | Saint-Gobain's captive E-glass production insulates margin structures from raw material volatility. |
| Multi-Jurisdiction Certification Investment | Suppliers navigating KBA-adjacent German approvals alongside Qatar civil defense codes capture stadium specification priority. |
| Adaptive Membrane System Development | Electroactive polymer integration enables predictive maintenance contracts shifting revenue to service agreements. |
| Design-Build-Operate Contract Bundling | Yangtze River Delta municipal clients transfer technical risk to contractors in exchange for lifecycle cost certainty. |
| Photovoltaic Film Lamination Partnership | Flexible solar integration unifies energy generation with enclosure functions in Middle Eastern solar farms. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with tensile structure engineering directors, stadium facility managers, coating chemistry R&D leads, and municipal procurement officers in China's Yangtze River Delta with secondary validation against customs trade data, ECHA substance restriction updates, GB standards fire resistance classifications, and SEC filings of integrated glass fiber suppliers. Bottom-up project pipeline enumeration and top-down fluoropolymer consumption estimates were triangulated.
Segment-weighting approaches applied product type splits across PTFE coated fiberglass, ETFE foils, and fabric membrane categories; application splits across sports facilities, transportation hubs, and agricultural coverings; and end-user splits across construction firms, facility managers, and architectural consultancies. CAGRs were derived from elasticity-adjusted demand modeling incorporating stadium construction calendars, REACH compliance timeline assumptions, and ETFE pneumatic cushion adoption curves across botanical garden and aquatic center specifications.
Revisions become necessary when Gulf state fire performance code updates, Chinese GB standards revisions, or fluoropolymer feedstock price shocks materialize beyond modeled bands. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Global Roofing Membranes Market
Membrane Materials
Global Microfiltration Membranes Market
Membrane Materials
Global Breathable Membranes Market
Membrane Materials
Microporous Materials Market
Membrane Materials
Inorganic Ion Exchange Materials Market
Membrane Materials
Bitumen Membrane Sheets Market
Membrane Materials
Global Ion Exchange Membrane Market
Membrane Materials
Global Membrane Filters Market
Membrane Materials
Polymer Electrolyte Membrane Fuel Cells (Pemfcs) Market
Membrane Materials
Gas Barrier Membranes Market
Membrane Materials
Global Medical Membranes Market
Membrane Materials
Hollow Fibers Membrane Market
Membrane Materials
Global Transfer Membrane Market
Membrane Materials
Vapor Barrier Films Market
Membrane Materials
Global Spiral Membrane Market
Membrane Materials
Nafion Market