
 PVDF Membrane Market | 2026-2036
PVDF Membrane Market Size, Share, and Industry Trends Forecast 2026-2036
PVDF Membrane Market Outlook
ISO 10993 biocompatibility certification is reorganizing competitive entry in medical-grade membrane supply. Pall Corporation leverages its vertical integration in hollow fiber extrusion to sustain qualification timelines for pharmaceutical clients. Merck Millipore anchors its position through deep control over pore-size distribution protocols for sterile filtration. Cytiva Life Sciences competes on single-use system compatibility, extending its membrane formats into continuous bioprocessing workflows.
PVDF membrane denotes a fluoropolymer filtration medium manufactured through phase inversion or track-etching, typically achieving pore sizes from 0.03 to 10 micrometers with high chemical resistance and low protein binding. Its primary purpose spans sterile filtration, virus retention, and particulate removal in liquid processing industries. Ultrafiltration segments dominate value capture in biopharmaceutical tangential flow systems, while microfiltration occupies the largest volume position in municipal water treatment retrofit programs. Hollow fiber configurations are displacing flat sheet formats in high-solids wastewater applications due to packing density advantages and reduced footprint requirements.
FDA process validation guidelines and EMA Annex 1 sterile manufacturing revisions are elevating extractables and leachables testing burdens for membrane suppliers seeking pharmaceutical qualification. China's NMPA pharmaceutical GMP updates and the country's GB standards for membrane water treatment are converging to demand dual-certified product lines for domestic and export markets. Stakeholders must monitor regulatory divergence between FDA, EMA, and NMPA qualification protocols when configuring regional manufacturing and distribution strategies.
Market Dynamics
Biopharmaceutical manufacturers are consolidating membrane qualification around single-use continuous processing architectures, forcing suppliers to reconfigure validation protocols and extrusion capacity simultaneously. This structural pull is compressing traditional batch-format supply relationships while elevating extractables testing burdens.
Growth Catalysts
- EMA Annex 1 sterile manufacturing revisions:Pharmaceutical facilities across Europe are retrofitting filtration trains to meet revised aseptic processing guidelines, accelerating membrane replacement cycles in existing installations.
- Monoclonal antibody production scale-up:Tangential flow filtration systems for mAb concentration and diafiltration are absorbing larger membrane surface areas per manufacturing line.
- China's GB standards for membrane water treatment:Municipal water reuse infrastructure projects in tier-two cities are specifying PVDF hollow fiber modules for ultrafiltration retrofit programs.
Market Restraints
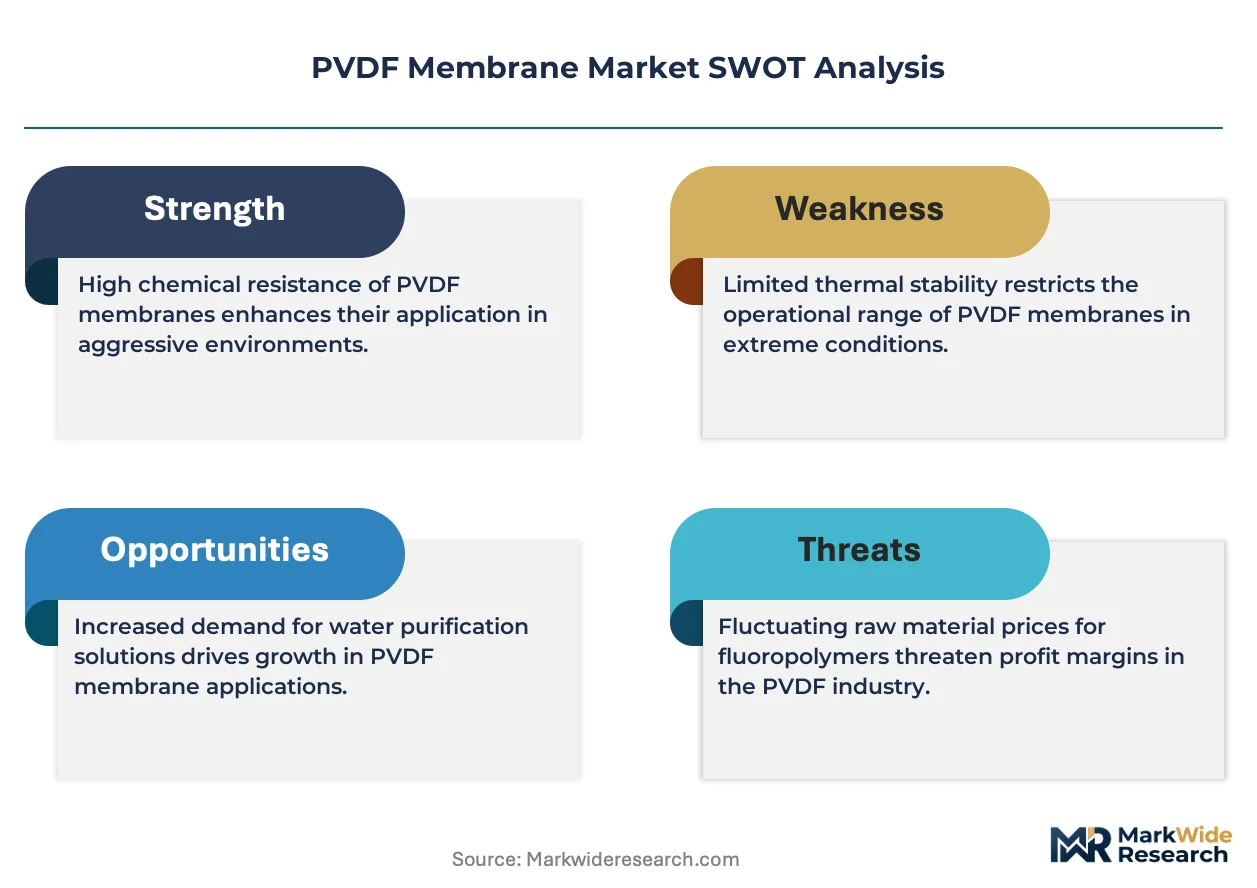
- Fluoropolymer feedstock concentration:Virgin PVDF resin supply concentrates among three chemical conglomerates, exposing membrane extruders to input cost volatility and allocation constraints.
- Per- and polyfluoroalkyl substance regulatory scrutiny:ECHA PFAS restriction proposals under REACH are creating qualification uncertainty for fluoropolymer-based medical devices and water treatment membranes.
- Polyethersulfone substitution in protein filtration:Lower-binding alternative polymers are capturing share in non-sterile bioprocessing applications where chemical resistance requirements moderate.
Strategic Opportunities
- India's PLI scheme for active pharmaceutical ingredients:Domestic biologics manufacturing incentives are attracting membrane suppliers to establish local qualification and distribution capabilities.
- Continuous bioprocessing convergence:Integration of perfusion cell culture with single-use downstream filtration is creating demand for membrane formats compatible with 24-hour operation cycles.
- Saudi Arabia's water reuse mandates:National targets for treated wastewater utilization are driving membrane procurement for industrial cooling and irrigation applications.
Industry Challenges
- ISO 10993-18 extractables study timelines:Chemical characterization protocols for medical-grade membranes are extending qualification cycles by 12-18 months for new product introductions.
- Hollow fiber extrusion technician scarcity:Specialized phase inversion process engineering expertise is concentrating among legacy membrane manufacturers, constraining capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PVDF Membrane Market |
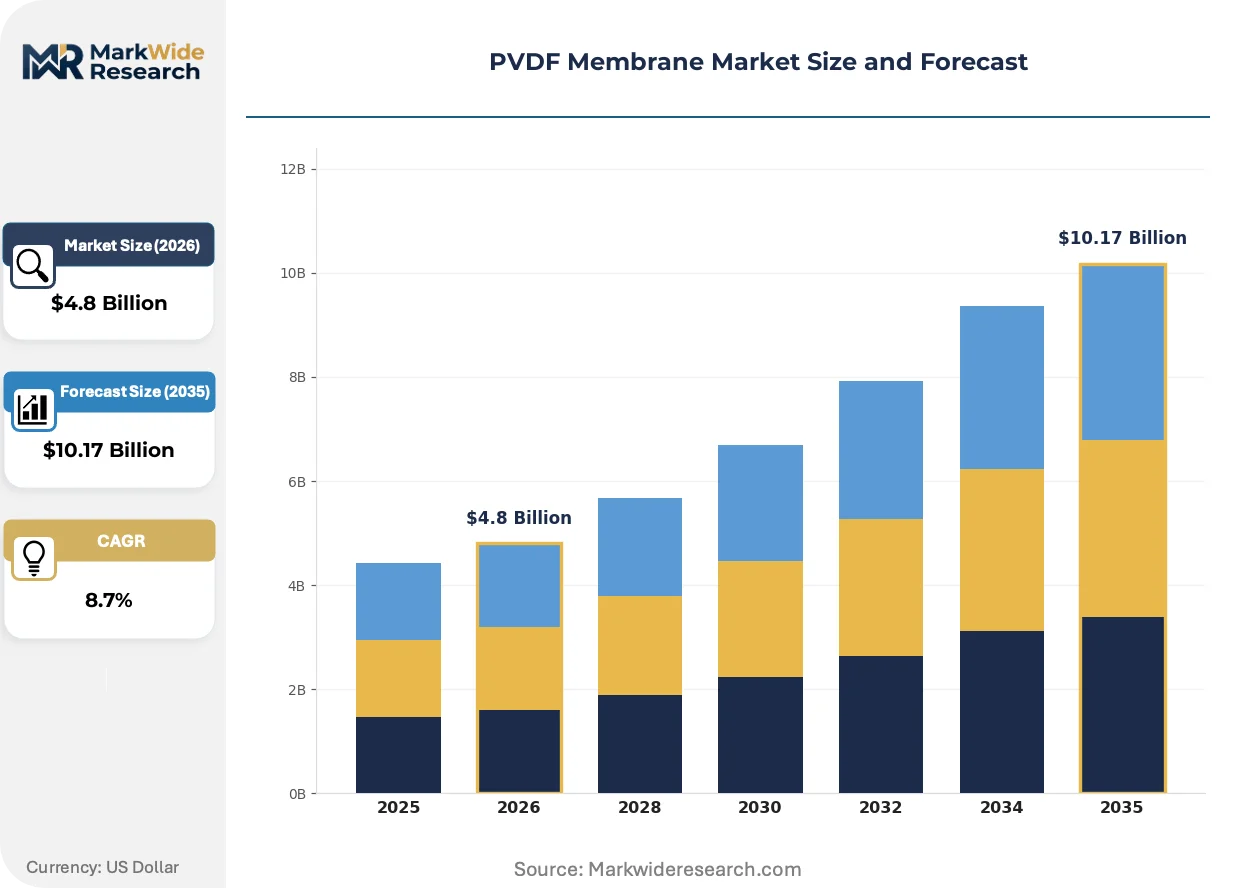
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microfiltration, Ultrafiltration, Nanofiltration, Reverse Osmosis Application: Water Treatment, Pharmaceutical, Food & Beverage, Chemical Processing End User: Utilities, Healthcare, Manufacturing, Research & Development Form: Flat Sheet, Hollow Fiber, Capillary, Composite |
| Companies Covered | Pall Corporation, CITIC Envirotech, Arkema S.A., Veolia Water Technologies, Toray Industries, Merck Millipore, Cytiva Life Sciences, Ecolab, KOCH Separation Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PVDF Membrane Market Strategic Shifts
Membrane architecture is fragmenting across application-specific formats as end-users reject universal product lines. Suppliers are engineering distinct surface chemistries and pore structures for biopharmaceutical versus water treatment deployment.
Track-etched membrane manufacturing is decomposing the dominance of phase-inversion casting in virus filtration applications. Vaccine producers are adopting precisely controlled cylindrical pore geometries for retention assurance. This precision is compressing validation variability and reducing batch release testing burdens for sterile filtration.
REACH PFAS restriction dossiers are forcing reformulation roadmaps across European medical device supply chains. Membrane converters are accelerating alternative polymer evaluations while defending existing fluoropolymer qualifications through derogation arguments. Sterile filtration segments are most affected, with manufacturers dual-sourcing PES and regenerated cellulose formats as contingency.
Biopharmaceutical procurement teams are consolidating membrane specifications around platform approvals rather than individual product qualifications. Large molecule manufacturers are pre-approving membrane formats across their entire pipeline, reducing supplier switching. This concentration is most visible in Massachusetts and North Carolina manufacturing clusters, where single-use system standardization is eliminating redundant validation work.
PVDF Membrane Market Segmentation
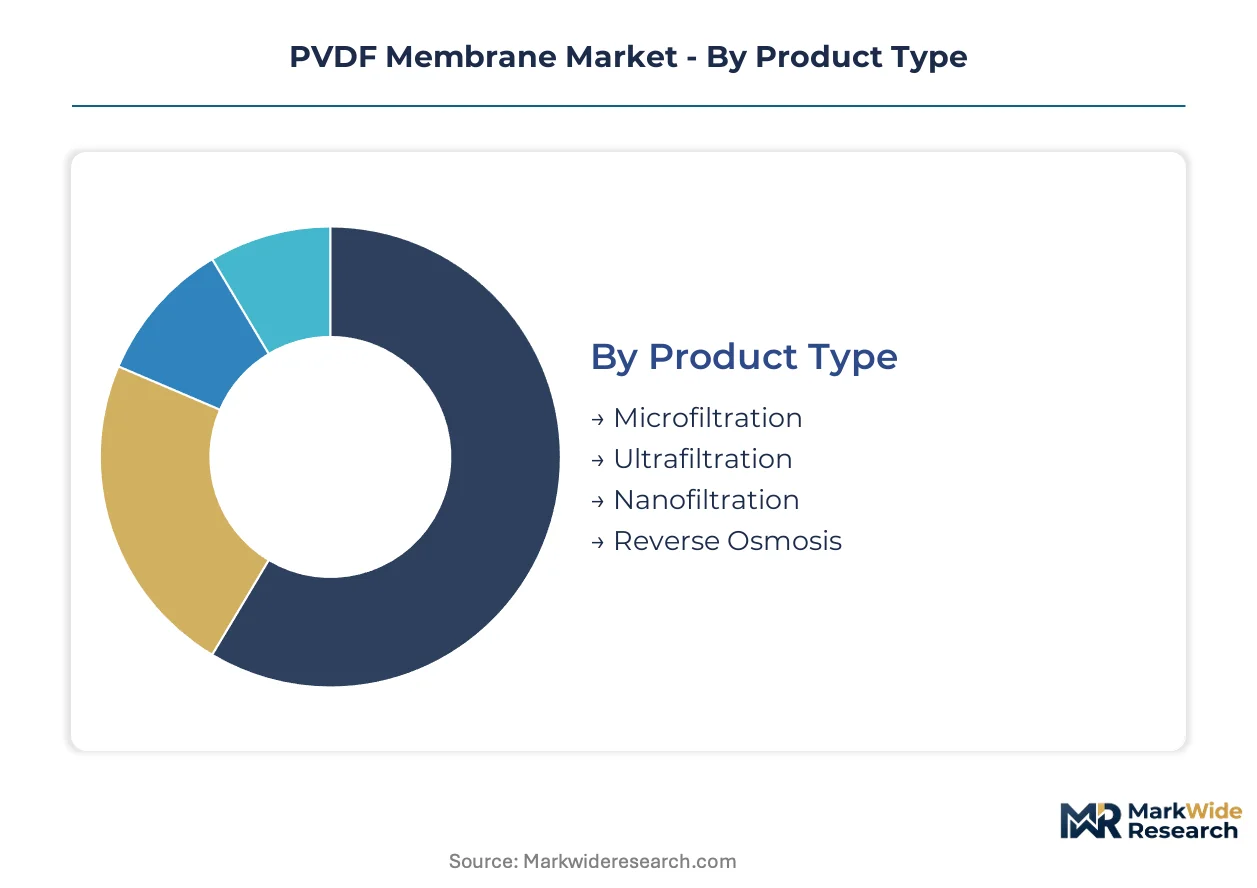
PVDF membrane architectures fragment sharply across end-use requirements. Suppliers engineer distinct pore structures, surface chemistries, and mechanical formats for biopharmaceutical sterile filtration versus municipal water reuse. This specialization prevents universal product lines from capturing premium qualification tiers.
Product Type:
Domestic Chinese manufacturers dominate microfiltration and ultrafiltration exports, while nanofiltration and reverse osmosis grades concentrate among European and Japanese suppliers serving pharmaceutical validation markets.
- Microfiltration:Pore sizes from 0.1 to 10 micrometers target particulate removal and sterile filtration. Municipal water treatment retrofit programs in China's tier-two cities absorb the largest volume positions, driven by GB standards compliance mandates for membrane bioreactor installations.
- Ultrafiltration:Molecular weight cutoffs between 1,000 and 500,000 Daltons enable protein concentration and virus retention. Tangential flow filtration systems for monoclonal antibody production in Massachusetts and North Carolina manufacturing clusters represent the highest-value demand concentration.
- Nanofiltration:Divalent ion selectivity suits pharmaceutical buffer preparation and specialized water purification. EMA Annex 1 sterile manufacturing revisions are elevating validation requirements for this precision tier.
- Reverse Osmosis:Dense skin-layer membranes achieve monovalent salt rejection for high-purity water generation. Saudi Arabia's industrial cooling and irrigation mandates are accelerating procurement for this format.
Ultrafiltration commands the established base. The steepest expansion runs through microfiltration hollow fiber configurations for water reuse infrastructure.
Application:
Cost tiers separate commodity water treatment membranes from pharmaceutical-grade products carrying ISO 10993 certification and extractables documentation packages.
- Water Treatment:Municipal reuse and industrial wastewater applications specify hollow fiber modules for packing density advantages. China's domestic infrastructure expansion and Saudi Arabia's national treated wastewater targets are converging on this segment.
- Pharmaceutical:Sterile filtration, virus retention, and single-use bioprocessing demand low-protein-binding surface chemistries. FDA process validation guidelines and EMA Annex 1 revisions are compressing supplier qualification timelines while elevating testing burdens.
- Food & Beverage:Clarification and concentration processes in dairy and beverage production utilize PVDF's chemical resistance for clean-in-place protocols. This segment tracks food safety regulator requirements across multiple jurisdictions.
- Chemical Processing:Aggressive solvent filtration and corrosive fluid separation exploit fluoropolymer stability. Process industry procurement emphasizes membrane lifetime and chemical compatibility over biocompatibility certification.
Pharmaceutical applications anchor premium pricing. Water treatment is climbing the fastest as infrastructure retrofit cycles accelerate across Asia-Pacific and Middle Eastern markets.
End User:
Customer type determines procurement sophistication, with utilities emphasizing total cost of ownership and healthcare facilities demanding batch release documentation.
- Utilities:Municipal water and wastewater operators specify membrane modules for ultrafiltration retrofit programs. China's state-owned water enterprises are consolidating procurement around domestic hollow fiber suppliers.
- Healthcare:Hospital pharmacies and central sterile supply departments require sterile filtration assurance for parenteral solutions. FDA and EMA qualification protocols dominate sourcing decisions.
- Manufacturing:Industrial bioprocessing and chemical production facilities balance membrane performance against capital expenditure constraints. Continuous bioprocessing convergence is reshaping format requirements.
- Research & Development:Laboratory-scale filtration and process development applications utilize smaller membrane surface areas with accelerated qualification cycles. Academic and contract research organizations prioritize flexibility over scale economies.
Manufacturing end users command the volume base. Healthcare procurement is expanding most quickly as biologics production scales and sterile filtration validation requirements tighten.
Form:
Supply concentration for hollow fiber extrusion expertise constrains capacity expansion, while flat sheet formats face substitution pressure from alternative polymers.
- Flat Sheet:Planar membrane configurations suit plate-and-frame filtration systems and laboratory-scale applications. Polyethersulfone alternatives are capturing share in non-sterile bioprocessing where chemical resistance requirements moderate.
- Hollow Fiber:Self-supporting tubular geometries maximize packing density and enable backwash cleaning for high-solids wastewater. Phase inversion process engineering expertise concentrates among legacy manufacturers, limiting new entrant capacity.
- Capillary:Small-diameter hollow fibers optimize surface-area-to-volume ratios for compact system designs. This format bridges laboratory and production scales in pharmaceutical process development.
- Composite:Multi-layer constructions combine PVDF separation layers with polypropylene or polyester support structures. Cost-sensitive water treatment applications favor this hybrid approach for mechanical durability.
Flat sheet formats retain the installed base. Hollow fiber configurations are gaining share fastest as high-solids wastewater applications expand and footprint constraints intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's container throughput underwrites China's dominance in membrane module distribution, while Rotterdam's chemical handling infrastructure anchors European fluoropolymer resin flows. These logistics assets shape regional supply security for PVDF membrane procurement.
United States
FDA process validation guidelines are accelerating membrane replacement cycles across Massachusetts and North Carolina biomanufacturing clusters. The country's pharmaceutical regulator has tightened extractables documentation requirements for sterile filtration applications. Greater Boston hosts concentrated monoclonal antibody production facilities that specify single-use tangential flow systems.
China
GB standards compliance for municipal water reuse infrastructure is absorbing hollow fiber ultrafiltration modules at scale. The country's environmental regulator has converged pharmaceutical GMP updates with membrane water treatment mandates. Tier-two cities across the Yangtze River Delta are retrofitting membrane bioreactor installations with domestic PVDF suppliers.
Germany
EMA Annex 1 sterile manufacturing revisions are elevating validation burdens for pharmaceutical-grade membrane supply. The country's chemical regulator is evaluating PFAS restriction proposals under REACH that affect fluoropolymer medical devices. Baden-Württemberg hosts specialized phase inversion engineering expertise concentrated among legacy membrane manufacturers.
India
PLI scheme incentives for active pharmaceutical ingredient manufacturing are attracting membrane suppliers to establish local qualification capabilities. The country's pharmaceutical regulator has updated GMP protocols that align with FDA and EMA standards. Maharashtra and Gujarat are consolidating biologics manufacturing capacity with integrated downstream filtration infrastructure.
Saudi Arabia
National treated wastewater utilization targets are driving membrane procurement for industrial cooling and irrigation applications. The country's water regulator has mandated membrane-based reuse for municipal and industrial end users. The Eastern Province is deploying PVDF ultrafiltration systems for petrochemical facility water recycling.
PVDF Membrane Market Competitive Environment
Listed leaders compete with private specialists across qualification timelines and vertical integration depth. The vendor base concentrates around chemical conglomerates controlling virgin PVDF resin supply, membrane extruders with phase inversion expertise, and system integrators bundling filtration trains. Three archetypes dominate: resin-integrated conglomerates, hollow fiber extrusion specialists, and single-use system platform providers. Competitive moves center on backward integration into resin supply and geographic expansion into regulatory-fast-track jurisdictions.
Among resin-integrated conglomerates, Arkema S.A. exemplifies upstream control over fluoropolymer feedstock that underwrites membrane converter relationships. Japanese industrial groups such as Toray Industries occupy positions spanning fiber extrusion and module assembly. Pall Corporation and Merck Millipore represent the premium-tier vector where pharmaceutical qualification protocols and extractables documentation create defensive positioning against commodity substitution.
| Leading Market Players |
|---|
| Pall Corporation |
| CITIC Envirotech |
| Arkema S.A. |
| Veolia Water Technologies |
| Toray Industries |
| Merck Millipore |
| Cytiva Life Sciences |
| Ecolab |
| KOCH Separation Solutions |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between resin-integrated conglomerates and membrane extruders lock in both virgin PVDF supply access and eighteen-month price visibility for pharmaceutical-grade hollow fiber output. These arrangements concentrate pricing power among three chemical conglomerates while forcing converters to absorb feedstock volatility through take-or-pay minimums.
Pricing Analysis
Certification level creates the primary spread across product tiers, with ISO 10993-18 extractables documentation and FDA Master File status commanding substantial premiums over industrial water treatment grades. Pharmaceutical procurement teams prioritize batch release reliability over unit cost, while municipal utilities negotiate on total cost of ownership metrics that favor hollow fiber packing density. Cost compression in commodity microfiltration runs through polyethersulfone substitution in non-sterile bioprocessing applications. Water treatment segments exhibit highest price sensitivity, whereas sterile filtration buyers accept premium positioning for validated supply security.
Supply Chain Analysis
France, Japan, and China anchor virgin PVDF resin production, with Arkema and Kureha controlling feedstock qualification pathways that membrane converters depend on for pharmaceutical-grade extrusion. Specialty phase inversion equipment and hollow fiber spinning lines draw from German and Italian precision engineering suppliers. Single-source vulnerability concentrates in fluoropolymer resin allocation, where three producers service global membrane demand. Distribution runs through system integrators bundling filtration trains with validation documentation packages for biopharmaceutical end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extractables testing services and validation protocol consulting now expand faster than membrane hardware sales, creating recurring revenue layers that offset cyclical capital equipment procurement. Service-attach models deepen customer switching costs while capturing margin from regulatory compliance burdens.
For Market Incumbents: Consolidate hollow fiber extrusion capacity through selective acquisition of phase inversion engineering specialists in Baden-Württemberg and Osaka manufacturing clusters. Backward integration into virgin resin supply insulates margin pressure from fluoropolymer feedstock concentration. Prioritize ISO 10993-18 documentation investments to defend positioning against polyethersulfone substitution in protein filtration segments.
For New Entrants and Emerging Players: Lead with track-etched membrane manufacturing for vaccine filtration applications, where precisely controlled pore geometries command validation premiums and reduce incumbent phase-inversion advantages. Target Saudi Arabia's industrial cooling and irrigation procurement, where membrane reuse mandates outpace qualified supplier capacity. Partner with domestic system integrators to bundle validation services with module supply.
For Investors and Strategic Acquirers: Hollow fiber extrusion specialists with captive phase inversion engineering expertise represent priority acquisition targets, given technician scarcity constraints on capacity expansion. Long-term viability hinges on regulatory derogation defenses for fluoropolymer qualifications under REACH PFAS restrictions. Monitor ECHA restriction proposal timelines as inflection indicators for alternative polymer substitution acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive virgin PVDF feedstock insulates membrane extruders from allocation constraints and price volatility. |
| Extractables Documentation Investment | ISO 10993-18 study capabilities compress pharmaceutical qualification timelines and defend premium positioning. |
| Regional Manufacturing Footprint | Local hollow fiber production in Maharashtra and Gujarat aligns with India's PLI scheme incentives for biologics capacity. |
| Track-Etched Technology Licensing | Precision pore geometry manufacturing reduces validation variability for vaccine filtration applications. |
| Service-Attach Revenue Model | Validation consulting and extractables testing create recurring revenue streams beyond hardware sales cycles. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and industry association reports. Interviews with membrane extrusion plant managers, pharmaceutical procurement directors, and water utility engineering heads inform supply-side capacity and demand-side specification trends. Secondary validation draws from FDA 510(k) filings, EMA Annex 1 revision commentaries, and China's GB standards documentation. Bottom-up module shipment analysis triangulates against top-down fluoropolymer resin consumption estimates.
Segmentation dimensions modeled include filtration grade tier, end-use application, membrane architecture format, and regional regulatory cluster across the projection horizon. CAGRs derive from trend extrapolation of monoclonal antibody production scale-up rates and municipal water reuse infrastructure deployment schedules. Industry-specific forecast inputs incorporate tangential flow filtration surface area requirements per manufacturing line and membrane bioreactor retrofit penetration in China's tier-two cities.
Forecasts assume regulatory continuity in FDA process validation guidelines, EMA Annex 1 sterile manufacturing revisions, and REACH PFAS restriction timelines; material policy shifts would require re-modeling. Specific risks include accelerated fluoropolymer substitution under ECHA dossiers and hollow fiber extrusion technician availability constraints. Recalibration cycles align with material shifts in biopharmaceutical continuous processing adoption and China's GB standards enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Global Tubular Membranes Market
Membrane Materials
Europe Gas Barrier Membrane Market
Membrane Materials
Expansion Vessel Membrane Market
Membrane Materials
Global Membrane Chromatography Market
Membrane Materials
Microporous Materials Market
Membrane Materials
Membrane Skinners Market
Membrane Materials
Global Membrane Water and Wastewater Treatment Market
Membrane Materials
Global Microfiltration Membranes Market
Membrane Materials
Global Membrane Structures Market
Membrane Materials
Liquid Roofing Market
Membrane Materials
Breathable Films and Membranes Market
Membrane Materials
Polyvinyl Butyral (PVB) Films and Sheets Market
Membrane Materials
Membrane Touch Switch Material Market
Membrane Materials
North America Ceramic Membranes Market
Membrane Materials
Reverse Osmosis Films Market
Membrane Materials
Polymer Electrolyte Membrane Fuel Cells (Pemfcs) Market