
 Membrane Chemicals Market | 2026-2036
Membrane Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Membrane Chemicals Market Outlook
Membrane cleaning and maintenance subscriptions is consolidating around bundled service contracts that shift capital expenditure into recurring operational spend. Ecolab leverages its global service technician network to embed long-term chemical supply agreements directly into plant operations. Solenis anchors its position through deep specialization in reverse osmosis antiscalants for high-salinity industrial feedwater. Kemira competes by controlling alumina- and silica-based coagulant supply chains that feed into integrated membrane pretreatment systems.
Membrane chemicals comprise formulated biocides, antiscalants, cleaners, and coagulants designed to prevent fouling, mineral scaling, and biological growth on polymeric or ceramic membrane surfaces, typically dosed at 2–10 ppm depending on feedwater chemistry and membrane pore structure. These formulations sustain permeate flux rates and extend membrane module lifespans in continuous filtration operations. Reverse osmosis chemicals command the largest product-type value pool due to energy-intensive desalination expansion, while membrane bioreactor applications in wastewater treatment represent the fastest-growing end-use segment driven by nutrient-removal mandates. Pressure-driven systems dominate installed technology bases, though electrodialysis chemistries are gaining traction in food and beverage demineralization where thermal damage to product streams must be avoided.
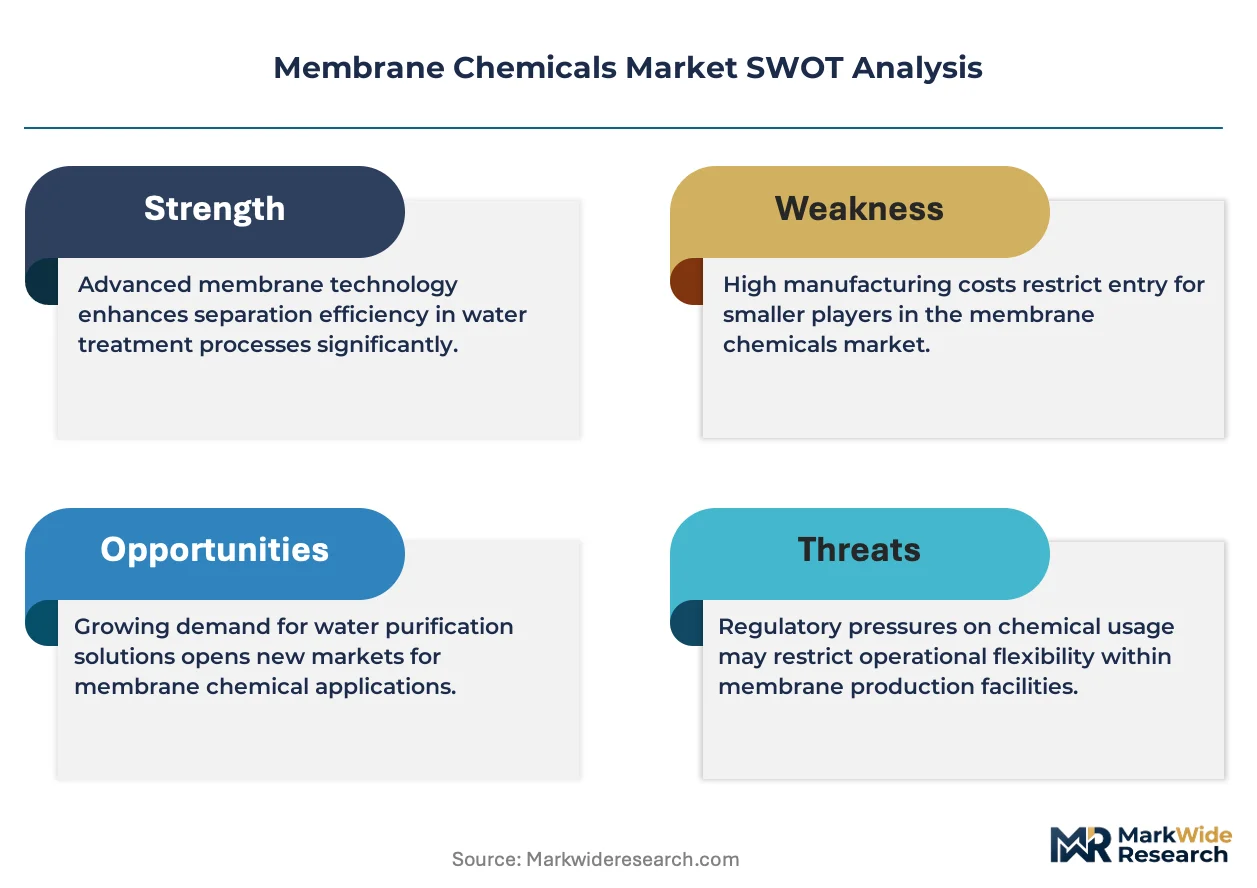
EPA effluent limitation guidelines and EU Urban Wastewater Treatment Directive revisions are tightening permissible discharge loads, forcing utilities to adopt higher-frequency membrane cleaning protocols and more aggressive pretreatment chemistries. China's MEE enforcement of industrial wastewater reuse quotas and India's CPCB mandates for zero liquid discharge in textile and tannery clusters are accelerating antiscalant and biocide consumption in Asia-Pacific process separation installations. ISO 23000 membrane performance benchmarking standards are further harmonizing product qualification requirements across export markets. Stakeholders must monitor how regional carbon-border adjustments reshape the cost structure of biocide active ingredients sourced from energy-intensive chlor-alkali chains.
Market Dynamics
Membrane chemical procurement is consolidating around bundled service contracts that embed chemical supply into long-term plant operations, shifting capital expenditure into recurring operational spend and locking in supplier relationships through embedded technical service networks.
Growth Catalysts
- EU Urban Wastewater Treatment Directive revisions:Tightening permissible discharge loads across European utilities is forcing higher-frequency membrane cleaning protocols and more aggressive pretreatment chemistries.
- China's MEE industrial wastewater reuse quotas:Enforcement of mandatory reuse rates in manufacturing corridors is accelerating antiscalant and biocide consumption in process separation installations.
- Membrane bioreactor nutrient-removal mandates:Biological nutrient removal requirements in municipal wastewater treatment are expanding chemical procurement for MBR systems in high-growth urban centers.
Market Restraints
- Chlor-alkali energy intensity:Biocide active ingredient costs fluctuate with regional electricity pricing, exposing formulators to margin compression from carbon-border adjustments on energy-intensive precursors.
- Specialized coagulant supply concentration:Alumina- and silica-based coagulant feedstocks for integrated membrane pretreatment systems concentrate among limited upstream chemical producers.
- Polymeric membrane thermal limitation:Standard polyamide thin-film composite membranes degrade above 45°C, restricting chemical cleaning protocol temperatures and extending downtime cycles.
Strategic Opportunities
- India's CPCB zero liquid discharge mandates:Textile and tannery clusters face compulsory ZLD implementation, creating concentrated demand for antiscalant and biocide formulations in membrane-based brine concentration systems.
- Electrodialysis-food processing convergence:Thermal-sensitive demineralization in dairy and beverage applications is opening specialty chemical formulations for electrodialysis stacks that avoid product damage.
- ISO 23000 membrane performance benchmarking:Harmonized qualification standards are reducing regional product registration friction and enabling formulation standardization across export markets.
Industry Challenges
- Membrane autopsy technician scarcity:Specialized failure analysis capabilities required to diagnose fouling mechanisms and prescribe corrective chemistries remain concentrated among senior field engineers at major suppliers.
- Legacy DCS integration complexity:Chemical dosing automation for membrane systems must interface with decades-old distributed control systems in retrofit municipal installations, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Membrane Chemicals Market |
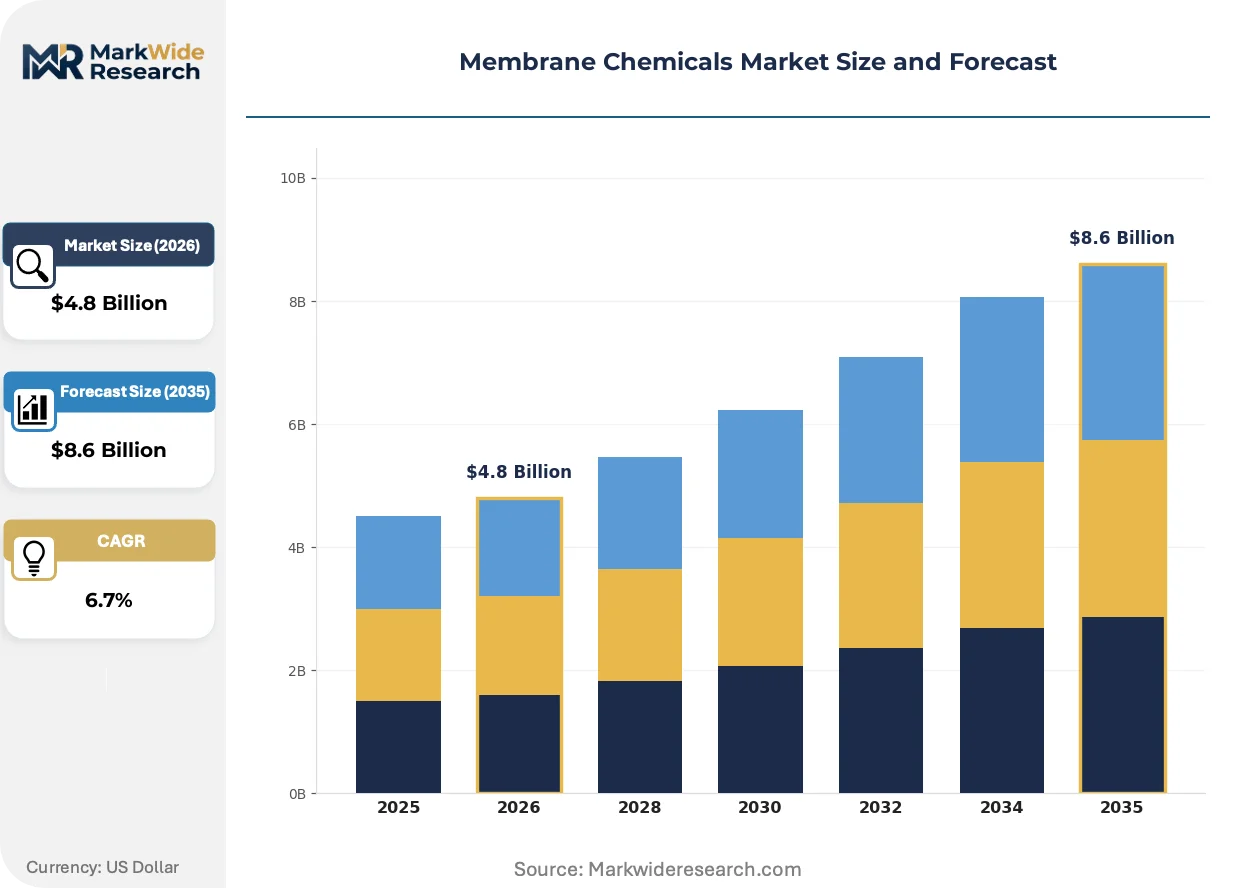
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrafiltration, Nanofiltration, Reverse Osmosis, Microfiltration End User: Water Treatment, Food & Beverage, Pharmaceuticals, Oil & Gas Application: Desalination, Wastewater Treatment, Process Separation, Water Purification Technology: Membrane Bioreactors, Electrodialysis, Forward Osmosis, Pressure-driven Systems |
| Companies Covered | Ecolab, Solenis, Kemira, Kurita Water Industries, Veolia, Genesys, BWA Water Additives, H2O Innovation, Lenntech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Membrane Chemicals Market Strategic Shifts
Formulation chemistry and service delivery models are converging around predictive membrane performance management, with digital monitoring systems enabling just-in-time chemical intervention before irreversible fouling occurs.
Enzymatic membrane cleaners are overtaking traditional caustic and oxidative formulations in food and beverage applications where protein and polysaccharide fouling dominates. Dairy processors and brewery operations are adopting these bio-based alternatives to reduce thermal sterilization requirements and extend membrane lifespans. This shift is compressing demand for conventional high-pH cleaners while creating formulation partnerships between chemical suppliers and industrial enzyme producers.
REACH authorization requirements for biocidal active substances are forcing reformulation of membrane preservation chemistries across European installations. The industrial consequence is accelerated phase-out of isothiazolinone-based products in favor of peracetic acid and chlorine dioxide alternatives. Reverse osmosis desalination plants in Spain and Italy are most affected, with operators stockpiling legacy chemistries while qualifying replacement formulations through extended field trials.
Subscription-based chemical supply agreements are displacing spot procurement in large industrial water treatment accounts. Buyers in semiconductor fabrication and power generation are bundling antiscalant, biocide, and cleaner consumption into fixed-fee contracts tied to permeate output guarantees. This model is most visible in Singapore's Jurong Island petrochemical cluster, where integrated water utilities are transferring dosage optimization risk to chemical suppliers in exchange for operational expenditure predictability.
Membrane Chemicals Market Segmentation
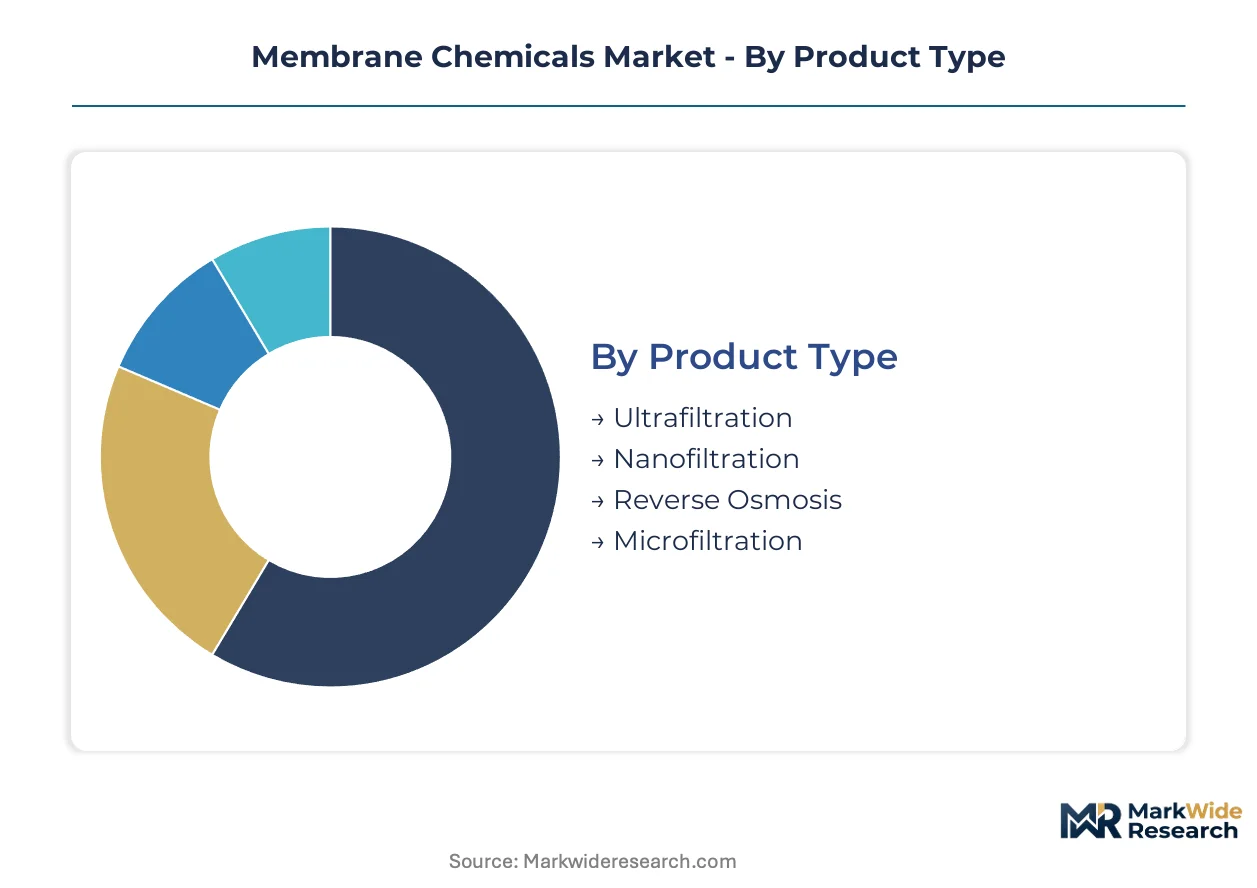
Membrane chemicals serve distinct performance requirements across filtration technologies, end-use sectors, and operational configurations. Segmentation reveals where formulation chemistry must adapt to membrane pore geometry, feedwater contamination profiles, and regulatory discharge standards.
Product Type:
Integration depth varies sharply—reverse osmosis chemicals operate in standalone desalination trains with dedicated pretreatment skids, while microfiltration formulations embed directly into membrane bioreactor process loops.
- Reverse Osmosis:Antiscalants and biocides formulated for polyamide thin-film composite membranes operating at 800–1,200 psi. Demand concentrates in Saudi Arabia's megadesalination plants and Australia's drought-response facilities where energy recovery device integration drives chemical dosing precision. Chlorine tolerance limitations force neutral-pH cleaner formulations.
- Ultrafiltration:Back-pulsable chemistries designed for hollow-fiber modules with 10–100 kDa molecular weight cutoffs. Municipal water reuse schemes in Singapore and California's Orange County Water District anchor procurement volumes. Fouling control emphasizes polysaccharide-dispersing surfactants over oxidative biocides to preserve membrane integrity.
- Nanofiltration:Selective ion rejection chemistries for divalent salt separation in food processing and groundwater softening. Dairy demineralization and textile dyehouse water recovery represent primary demand nodes.
- Microfiltration:Coagulant aids and mixed-oxidant biocides for 0.1–10 micron particulate removal. Wastewater tertiary filtration and beverage clarification drive steady consumption.
Reverse osmosis leads volumes today; ultrafiltration is gaining share fastest in municipal reuse corridors.
End User:
Cost tier stratification separates commodity water treatment procurement from premium pharmaceutical validation requirements and hazardous oilfield operating conditions.
- Water Treatment:Municipal and industrial utilities purchasing antiscalants, biocides, and cleaners under performance-based service contracts. China's Yangtze River Delta manufacturing clusters and India's Ganga rejuvenation project municipalities represent concentrated demand expansion zones. EPA and EU discharge tightening forces higher-frequency cleaning protocols.
- Pharmaceuticals:Validated low-endotoxin formulations for WFI (water for injection) and pure steam generation systems. FDA process validation requirements and EMA GMP Annex 1 revisions drive documentation intensity and supplier audit frequency. Single-use membrane bioreactor adoption is accelerating specialty chemical consumption.
- Food & Beverage:Enzymatic cleaners and food-grade antiscalants for dairy, brewery, and juice concentration applications. Thermal damage avoidance favors ambient-temperature membrane processing.
- Oil & Gas:High-pressure reverse osmosis and forward osmosis chemistries for produced water management and enhanced oil recovery. Permian Basin operators and Middle East offshore platforms face corrosive hydrogen sulfide challenges requiring specialized biocide formulations.
Water treatment dominates procurement value; pharmaceuticals exhibits the steepest margin expansion trajectory.
Application:
Volume concentration tracks freshwater stress geography—desalination clusters in water-scarce coastlines versus wastewater treatment expansion in dense urban corridors.
- Wastewater Treatment:Membrane bioreactor nutrient-removal chemistries for nitrogen and phosphorus compliance. China's MEE enforcement of industrial reuse quotas and India's CPCB zero liquid discharge mandates for textile and tannery clusters accelerate antiscalant and biocide deployment. Biological fouling control dominates formulation requirements.
- Desalination:Seawater reverse osmosis antiscalants targeting calcium sulfate and silica scaling at 45,000+ ppm TDS. Red Sea and Persian Gulf installations require boron-selective rejection chemistry and high-temperature tolerance formulations.
- Process Separation:Electrodialysis and nanofiltration chemistries for food demineralization, chemical recovery, and pharmaceutical purification. Dairy whey protein concentration and organic solvent nanofiltration represent growth nodes.
- Water Purification:Point-of-use and centralized polishing systems for semiconductor fabrication and power generation boiler feed. Ultrapure water specifications at 18.2 MΩ·cm resistivity drive sub-ppb contaminant control.
Wastewater treatment leads installed base; desalination commands the highest per-unit chemical intensity.
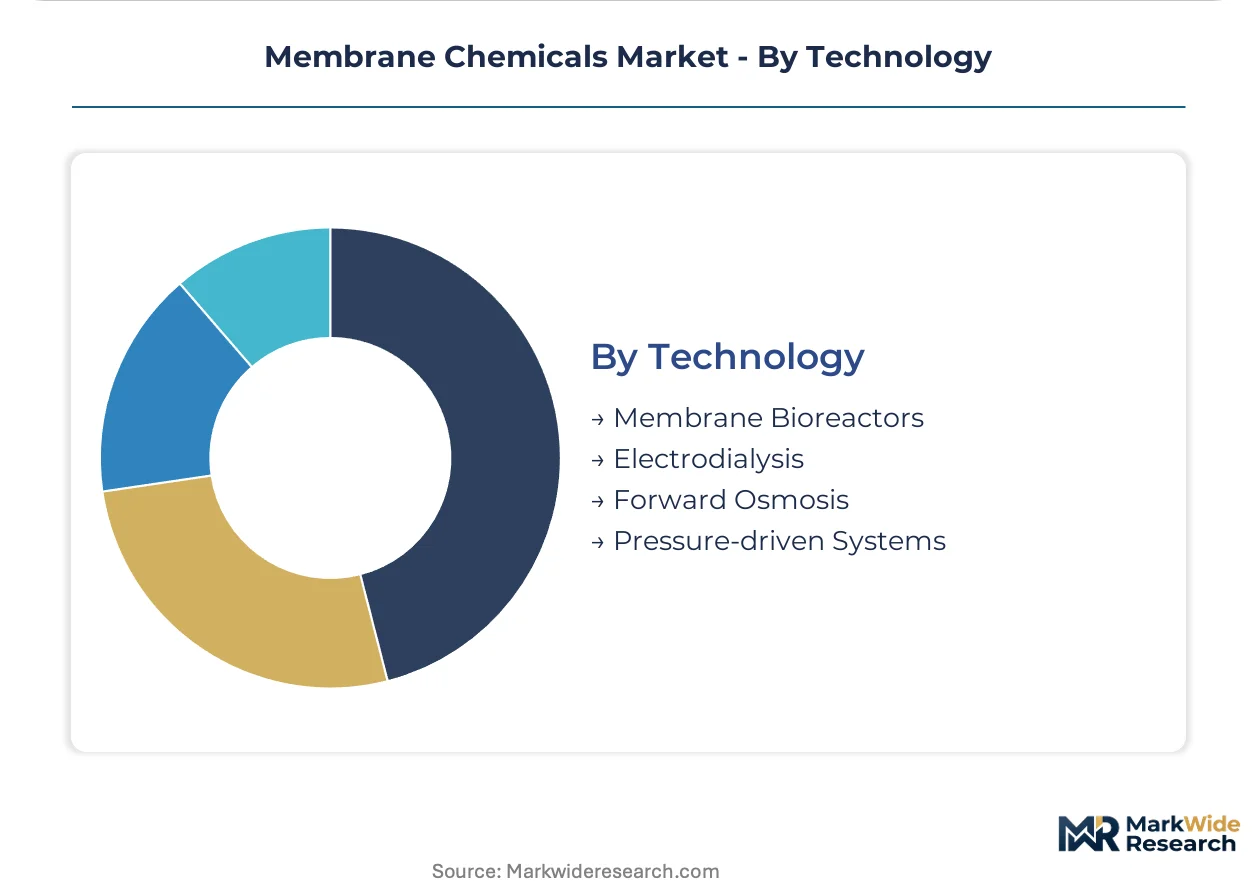
Technology:
Maturity differentiation separates decades-old pressure-driven system chemistries from emerging electrodialysis and forward osmosis formulation requirements.
- Pressure-driven Systems:Established reverse osmosis, nanofiltration, and ultrafiltration chemical portfolios with standardized dosing protocols. Energy recovery integration and variable frequency drive optimization enable precise chemical injection timing. Mediterranean and Australian utilities represent technology adoption anchors.
- Membrane Bioreactors:Immersed hollow-fiber and flat-sheet configurations combining biological treatment with membrane separation. Nutrient-removal mandates in Germany's Rhine-Ruhr urban corridor and China's Pearl River Delta manufacturing cities drive MBR chemical specialization. Mixed liquor suspended solids management requires unique fouling control strategies.
- Electrodialysis:Ion-exchange membrane stack chemistries for thermal-sensitive food and beverage demineralization. Japanese dairy processors and European whey protein manufacturers avoid product damage through electrodialysis substitution for evaporation.
- Forward Osmosis:Draw solution chemistries and membrane preservation formulations for emerging osmotic power and industrial wastewater concentration applications. Oilfield produced water and landfill leachate treatment represent pilot-scale deployment zones.
Pressure-driven systems anchor current procurement; membrane bioreactors are climbing the fastest in urban wastewater infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's megadesalination procurement dwarfs Australia's drought-response installations, while China's industrial reuse corridors outpace both in chemical intensity per membrane module.
China
MEE enforcement of industrial wastewater reuse quotas accelerates antiscalant consumption across manufacturing belts. The Yangtze River Delta manufacturing clusters embed membrane bioreactor systems under tightening freshwater allocation rules. Suzhou and Wuxi textile processors deploy zero-liquid-discharge configurations to meet provincial discharge standards.
United States
EPA effluent limitation guidelines force municipal utilities toward higher-frequency membrane cleaning protocols. The Orange County Water District anchors ultrafiltration procurement volumes for direct potable reuse schemes. Permian Basin oilfield operators consume specialized biocide formulations for produced water management under state environmental compliance frameworks.
Germany
Rhine-Ruhr urban corridor nutrient-removal mandates expand membrane bioreactor chemical specialization. REACH authorization requirements for biocidal active substances trigger reformulation of membrane preservation chemistries. Bavarian dairy processors adopt enzymatic cleaners to avoid thermal damage in whey protein concentration operations.
India
CPCB zero liquid discharge mandates for textile and tannery clusters concentrate antiscalant demand in membrane-based brine concentration systems. The Ganga rejuvenation project municipalities upgrade pretreatment chemistries under federal pollution control directives. Tirupur and Surat dyeing clusters face compulsory ZLD implementation with embedded chemical service contracts.
Singapore
Jurong Island petrochemical cluster transfers dosage optimization risk to chemical suppliers through fixed-fee contracts tied to permeate output guarantees. PUB's NEWater program sustains ultrapure water specifications driving sub-ppb contaminant control requirements. Integrated water utilities bundle antiscalant, biocide, and cleaner consumption under operational expenditure predictability models.
Membrane Chemicals Market Competitive Environment
Top-tier vendors anchor bundled service contracts, while mid-tier specialists compete on formulation depth for specific membrane technologies. The supplier base stratifies between global service networks with embedded technical capabilities and regional formulators with deep feedwater chemistry expertise. Two strategic archetypes dominate: integrated water treatment platforms leveraging technician density, and focused antiscalant specialists controlling alumina- and silica-based coagulant supply chains. Competitive moves center on subscription-based contract displacement of spot procurement and predictive membrane performance management through digital monitoring integration.
Among the named participants, Ecolab exemplifies the service-integrated archetype through its global technician network embedding long-term supply agreements directly into plant operations. Solenis occupies a position as a specialized formulator with concentrated expertise in reverse osmosis antiscalants for high-salinity industrial feedwater. Kemira represents the upstream-integrated model, controlling coagulant supply chains that feed into integrated membrane pretreatment systems. These three anchors illustrate how competitive positioning diverges between operational expenditure predictability, technical formulation depth, and raw material supply security.
| Leading Market Players |
|---|
| Ecolab |
| Solenis |
| Kemira |
| Kurita Water Industries |
| Veolia |
| Genesys |
| BWA Water Additives |
| H2O Innovation |
| Lenntech |
| Others |
Value Chain & Pricing Dynamics
Enzymatic cleaner adoption in dairy and beverage processing simultaneously compresses caustic formulation margins and concentrates procurement power among industrial enzyme suppliers with captive fermentation capacity. This technology transition rewards backward-integrated chemical formulators while squeezing spot-market biocide traders facing REACH-driven reformulation costs.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for antiscalant formulations serving zero-liquid-discharge installations. Subscription-based service contracts now dominate large-account procurement, transferring dosage optimization risk to suppliers in exchange for operational expenditure predictability. Price differentiation rests on ISO 23000 certification tier and embedded technical service density. Margins are tightening for commodity biocide traders exposed to chlor-alkali energy cost volatility, while validated pharmaceutical-grade formulations command premium pricing insulated from spot-market pressure.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese producers of specialized ion-exchange resins for electrodialysis stack maintenance. Raw material flows draw from Saudi Arabian bromine derivatives, Chinese chlor-alkali output, and Indian alumina-based coagulant feedstocks. Tariff exposure runs through energy-intensive precursor chains facing carbon-border adjustment mechanisms. Distribution runs through integrated water utilities on Jurong Island and technical service networks embedding directly into municipal plant operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane chemicals function as a regulatory compounder where EU Urban Wastewater Treatment Directive revisions and China's MEE enforcement protocols mechanically expand addressable demand through compliance mandates.
For Market Incumbents: Deepen backward integration into alumina- and silica-based coagulant supply chains to defend against Kemira's upstream-locked positioning. Expand predictive membrane performance management capabilities through digital monitoring integration, countering the threat of subscription-based contract displacement by service-integrated competitors. Prioritize ISO 23000 certification investment to reduce regional product registration friction across export markets. For New Entrants and Emerging Players: Enter via India's CPCB-mandated zero liquid discharge corridors in Tirupur and Surat textile clusters, where compulsory ZLD implementation outpaces established supplier technical service density. Target enzymatic cleaner formulation partnerships with industrial enzyme producers serving Bavarian dairy processors. Pursue electrodialysis specialty chemistry for Japanese whey protein concentration as the most penetrable white-space segment. For Investors and Strategic Acquirers: Valuations sit cheapest among regional formulators with deep feedwater chemistry expertise but limited global service technician networks. Long-term viability over the next decade hinges on regulatory enforcement durability across Asia-Pacific industrial reuse mandates. Watch for carbon-border adjustment implementation timing as the critical inflection signal for chlor-alkali-dependent biocide producer margins.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coagulant Feedstocks | Secures alumina supply chains feeding China's MBR procurement expansion. |
| Enzymatic Cleaner Formulation Partnership | Captures dairy processor demand in Germany's REACH-constrained preservation chemistry market. |
| Predictive Membrane Performance Platform | Enables just-in-time chemical intervention before irreversible fouling occurs in Singapore's NEWater facilities. |
| Zero Liquid Discharge Service Contract | Locks in recurring revenue from India's CPCB-mandated textile cluster compliance. |
| ISO 23000 Certification Harmonization | Reduces registration friction for antiscalant export into EU and Asia-Pacific municipal markets. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with municipal plant operators, membrane system OEM procurement leads, technical R&D directors at formulation houses, and chemical distribution channel partners. Secondary validation drew from EPA effluent limitation guideline filings, MEE enforcement disclosure databases, EU REACH authorization registers, and customs trade data tracking chlor-alkali precursor flows. Bottom-up membrane module shipment analysis and top-down water treatment capex triangulation anchored value estimates.
Segment-weighting applied technology-type splits across pressure-driven systems, membrane bioreactors, electrodialysis, and forward osmosis configurations, crossed with end-use industry tiers and regional regulatory enforcement intensity. CAGRs were derived from installed base expansion modeling and chemical intensity per membrane module trajectories. Forecast inputs incorporated freshwater quota tightening timelines and carbon-border adjustment mechanism implementation patterns.
Inputs from regulatory enforcement agencies and membrane system OEMs were available through the study window; gaps in proprietary chemical dosing rate data from bundled service contracts introduce uncertainty bands around operational expenditure estimates. Forecasts reflect documented assumptions about MEE and CPCB enforcement durability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
US Commercial Restoration Waterproofing Membranes Market
Membrane Materials
Polyarylsulfone (PAS) Market
Membrane Materials
Global Roofing Membranes Market
Membrane Materials
Global Ultrafiltration Market
Membrane Materials
Membranes Market
Membrane Materials
Breather Membranes Market
Membrane Materials
Asia-Pacific, Middle East and Africa Macrofiltration Market
Membrane Materials
TPO Roofing Membrane Market
Membrane Materials
Global Spiral Membrane Market
Membrane Materials
North America below Grade Waterproofing Membranes Market
Membrane Materials
Oxygen Barrier Films Market
Membrane Materials
Nafion Market
Membrane Materials
Fuel Cell Gas Diffusion Layer Market
Membrane Materials
Self-Adhered Roofing Membranes Market
Membrane Materials
Membrane Separation Market
Membrane Materials
Ultrafiltration Membrane Market