
 Polyvinyl Butyral (PVB) Films and Sheets Market | 2026-2036
Polyvinyl Butyral (PVB) Films and Sheets Market Size, Share, and Industry Trends Forecast 2026-2036
Polyvinyl Butyral (PVB) Films and Sheets Market Analytics
Chinese petrochemical producers is pivoting toward higher-grade PVB resin output to serve automotive and architectural laminators. Eastman Chemical Company leverages its integrated butyraldehyde-to-film pipeline to sustain cost discipline across North American and European supply routes. Sekisui Chemical Co., Ltd. anchors premium acoustic PVB capacity for luxury vehicle programs in Japan and Germany. Kuraray Co., Ltd. differentiates through specialized resin grades that command preference in photovoltaic encapsulation segments.
Polyvinyl butyral films and sheets are thermoplastic interlayers produced by condensation of polyvinyl alcohol with butyraldehyde, typically containing 15-20% plasticizer by weight to achieve the elastomeric properties required for glass adhesion and impact absorption. These materials function as the binding core in laminated safety glass, holding shattered fragments upon impact to prevent penetration injuries in automotive windshields and architectural facades. Transparent Films retain the dominant share of product type value due to their ubiquity in standard automotive and building glazing specifications, while Acoustic PVB commands disproportionate margin contribution from premium vehicle cabin insulation and urban noise-reduction retrofits. The Application dimension shows Automotive Glazing generating the highest absolute volume offtake, though Architectural Glazing is widening its share as energy-efficient building codes proliferate across temperate climate zones.
The US National Highway Traffic Safety Administration mandates laminated windshield construction under Federal Motor Vehicle Safety Standard 205, which directly structures PVB interlayer demand specifications for optical clarity and penetration resistance. Europe's REACH regulation and F-Gas framework constrain plasticizer chemistries and manufacturing emissions, elevating compliance costs for non-integrated compounders while advantaging producers with captive resin and additive synthesis. China's GB standards for automotive safety glass, administered by the Standardization Administration, impose parallel testing protocols that shape export qualification requirements for Asian suppliers. Stakeholders must monitor evolving fragmentation test protocols and plasticizer substitution timelines as regulatory divergence between major economies intensifies formulation complexity.
Market Dynamics
Automotive OEMs are consolidating laminated glass specifications across electric vehicle platforms, compressing formulation diversity while amplifying volume commitments to qualified resin-grade suppliers.
Growth Catalysts
- Electric vehicle platform expansion:Automotive laminators are specifying thicker acoustic interlayers for battery-enclosure windshields, pulling premium-grade PVB resin through dedicated supply agreements.
- REACH plasticizer compliance:Europe's ECHA enforcement timeline is accelerating substitution toward bio-based plasticizer chemistries, opening qualification windows for reformulated sheet producers.
- China's eastern coastal corridor:Concentrated automotive assembly and export glazing capacity in Jiangsu and Zhejiang provinces is sustaining dedicated resin-to-film infrastructure investments.
Market Restraints
- Butyraldehyde feedstock volatility:Naphtha-derived acetaldehyde price swings transmit directly to resin production economics, squeezing non-integrated compounders.
- Resin supply concentration:Captive butyraldehyde-to-PVB pipelines at three major chemical groups constrain third-party sheet producers to spot resin markets.
- Ethylene-vinyl acetate substitution:Photovoltaic encapsulation buyers are qualifying EVA alternatives for frameless module architectures, displacing specialized PVB grades in select solar applications.
Strategic Opportunities
- India's automotive safety mandate escalation:Proposed amendments to CMVR windshield penetration standards would replicate NHTSA-equivalent laminated glass requirements across domestic passenger vehicle production.
- Building-integrated photovoltaics:Architectural laminators are testing colored and patterned interlayers for solar facade applications, expanding addressable glazing surface area beyond conventional transparent specifications.
- F-Gas regulatory tailwind:Europe's phasedown of fluorinated greenhouse gases in manufacturing processes is advantaging water-based PVB sheet casting over solvent-intensive alternatives.
Industry Challenges
- Acoustic engineering talent scarcity:Formulation chemists capable of tuning loss factor profiles across temperature ranges are concentrated at Japanese and German specialty resin houses.
- Multi-jurisdictional certification timelines:Simultaneous NHTSA, ECE R43, and GB 9656 homologation cycles extend product launch intervals by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyvinyl Butyral (PVB) Films and Sheets Market |
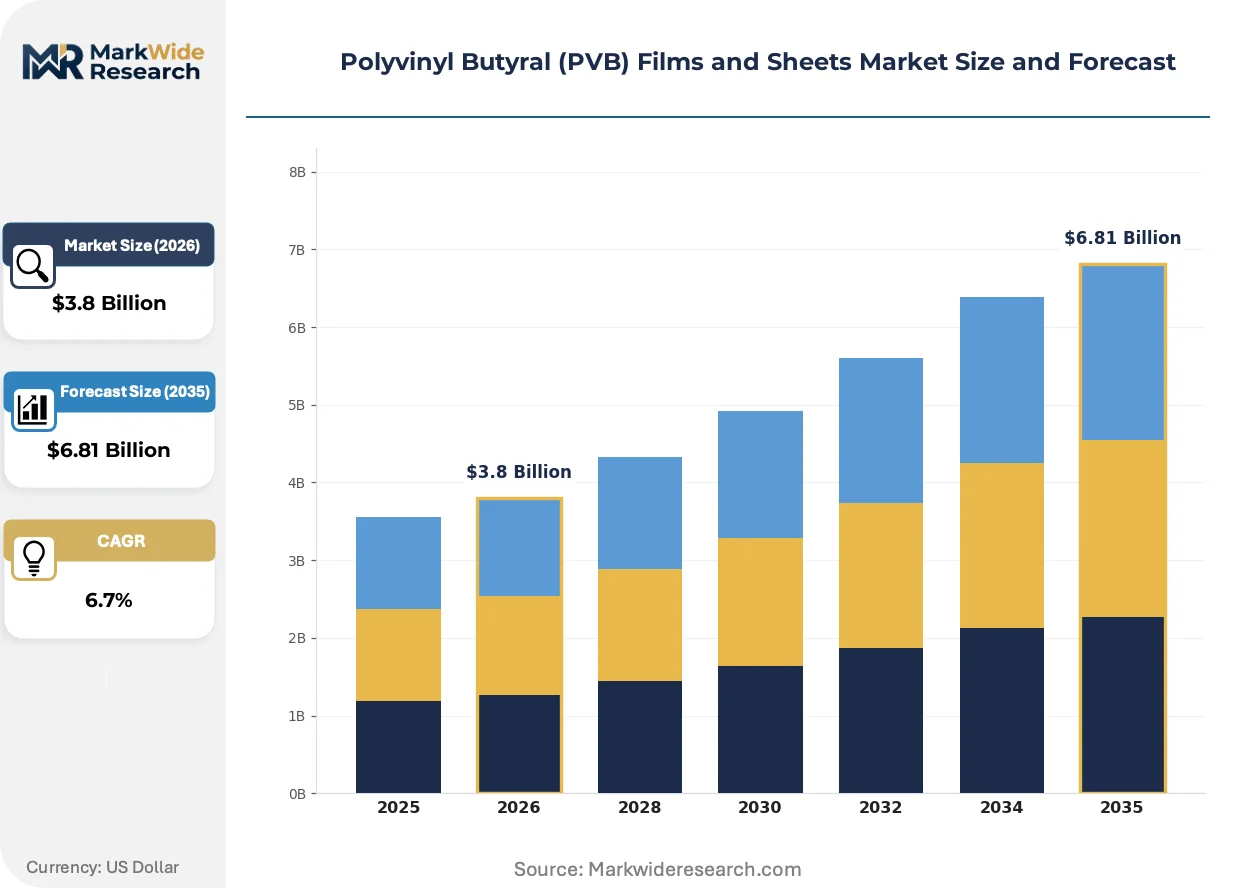
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transparent Films, Laminated Safety Glass, Acoustic PVB, Colored Sheets Application: Automotive Glazing, Architectural Glazing, Electronics, Retail Displays End User: Manufacturers, Construction Firms, Automotive OEMs, Design Studios Form: Rolls, Sheets, Custom Shapes, Laminates |
| Companies Covered | Chang Chun Group, EVERLAM, Eastman Chemical Company, Zhejiang Decent Plastic, Huakai Plastic, Sekisui Chemical Co., Ltd., Saint-Gobain, Kingboard Chemical Holdings, Kuraray Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyvinyl Butyral (PVB) Films and Sheets Market Evolving Landscape
Interlayer functionality is bifurcating between commodity safety specifications and engineered acoustic-thermal performance tiers, reshaping how resin grades align to end-use value pools.
Multilayer acoustic PVB is modularizing windshield construction by enabling discrete tuning layers for frequency-specific damping. Luxury vehicle programs in Germany and Japan are adopting three-ply configurations that separate structural adhesion from noise attenuation functions. This architecture is compressing single-sheet standard grades into economy replacement-glass channels while reserving premium resin capacity for OEM acoustic specifications.
Europe's F-Gas Regulation is constraining manufacturing emissions intensity across interlayer film casting operations. Integrated producers with captive solvent recovery systems are absorbing compliance costs more efficiently than toll-sheet converters dependent on third-party coating capacity. The regulatory friction is most acute for architectural glazing suppliers serving LEED-certified building projects with embodied-carbon documentation requirements.
Automotive laminators are consolidating procurement around qualified supplier matrices with dual-source resin pedigree requirements. Tier-one glass processors are displacing spot-market sheet purchases with multi-year resin-grade commitments that lock optical clarity tolerances and plasticizer migration limits. This concentration is most visible in China's Yangtze River Delta, where windshield fabricators serve both domestic EV brands and export luxury programs.
Polyvinyl Butyral (PVB) Films and Sheets Market Segmentation
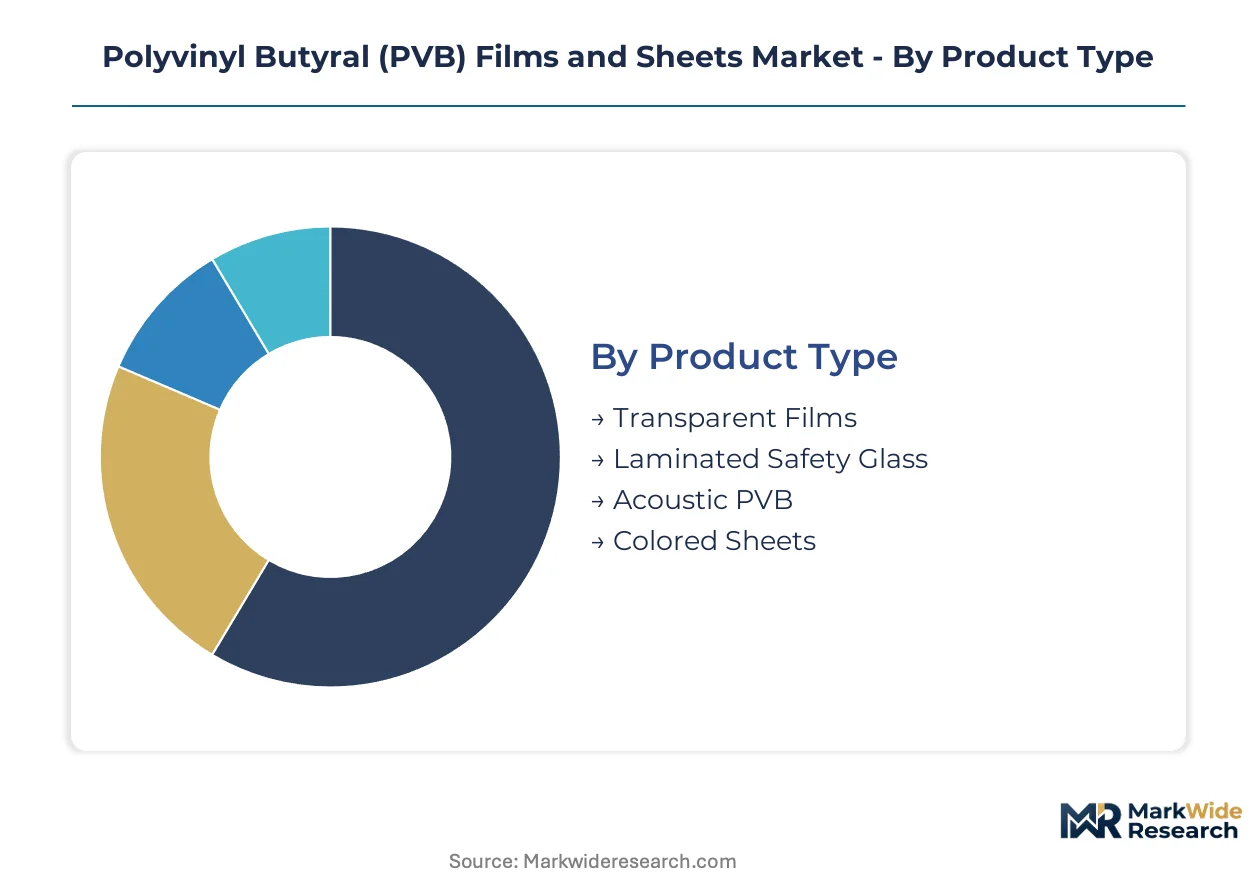
PVB film and sheet producers must navigate divergent specification requirements across automotive, architectural, and specialty electronics channels. Each segment imposes distinct optical clarity, acoustic damping, or thermal bonding demands that reshape resin formulation priorities and casting process investments.
Product Type:
Volume concentration favors standard transparent specifications, while acoustic and colored variants capture disproportionate margin contribution through performance premiums.
- Transparent Films:Standard optical-grade interlayers containing 15-20% plasticizer by weight serve the bulk of windshield and facade glazing applications. Demand clusters in China's Jiangsu and Zhejiang provinces, where integrated resin-to-film operations feed both domestic automotive assembly and export architectural markets.
- Acoustic PVB:Engineered multilayer constructions with frequency-tuned loss factors command specification in luxury electric vehicle platforms across Germany and Japan. Three-ply architectures separate structural adhesion from noise attenuation functions, pulling dedicated premium resin capacity through multi-year supply agreements with qualified laminators.
- Laminated Safety Glass:Pre-assembled interlayer-glass composites for replacement and retrofit channels require consistent penetration resistance under NHTSA FMVSS 205 and ECE R43 test protocols.
- Colored Sheets:Pigmented interlayers for decorative architectural and automotive accent applications serve design studios specifying custom tint matching for premium building facades and concept vehicle programs.
Mature deployment sits with Transparent Films. Newer deployment is concentrated in Acoustic PVB.
Application:
Automotive volume anchors resin capacity planning, though architectural qualification cycles are lengthening product development pipelines for energy-efficient building codes.
- Automotive Glazing:Laminated windshield construction mandated under NHTSA FMVSS 205 and parallel ECE R43 regulations structures the largest absolute volume channel. Electric vehicle platforms are specifying thicker acoustic interlayers for battery-enclosure windshields, consolidating procurement around qualified supplier matrices with dual-source resin pedigree requirements.
- Architectural Glazing:Temperate climate zone building codes are widening specification of low-emissivity and solar-control laminated assemblies. Europe's F-Gas Regulation and REACH compliance constrain plasticizer chemistries and manufacturing emissions, elevating qualification costs for LEED-certified projects with embodied-carbon documentation requirements.
- Electronics:Display bonding and touch panel encapsulation applications demand ultra-thin caliper control and optical clarity tolerances stricter than automotive specifications.
- Retail Displays:Shatter-resistant showcase and fixture glazing for high-traffic commercial environments utilizes standard-grade interlayers with emphasis on supply responsiveness over engineered performance tiers.
Procurement consolidation is most advanced in Automotive Glazing. Specification diversity is expanding fastest in Architectural Glazing.
End User:
Direct OEM relationships dominate premium acoustic and optical grades, while construction channel intermediaries handle commodity architectural volumes.
- Automotive OEMs:Tier-one glass processors specify resin-grade commitments that lock optical clarity tolerances and plasticizer migration limits, displacing spot-market sheet purchases. Procurement matrices require dual-source qualification extending eight to fourteen months across NHTSA, ECE R43, and GB 9656 homologation cycles.
- Construction Firms:Large-scale facade contractors serving commercial and institutional projects source through distributors with inventory positions in standard transparent and solar-control grades.
- Manufacturers:Integrated laminate producers with captive glass tempering and bending capabilities specify interlayer calipers and plasticizer loadings to match proprietary process parameters.
- Design Studios:Boutique architectural practices and automotive concept houses drive small-lot demand for colored and patterned interlayers with custom aesthetic specifications.
Contract security is strongest with Automotive OEMs. Volume volatility concentrates with Construction Firms.
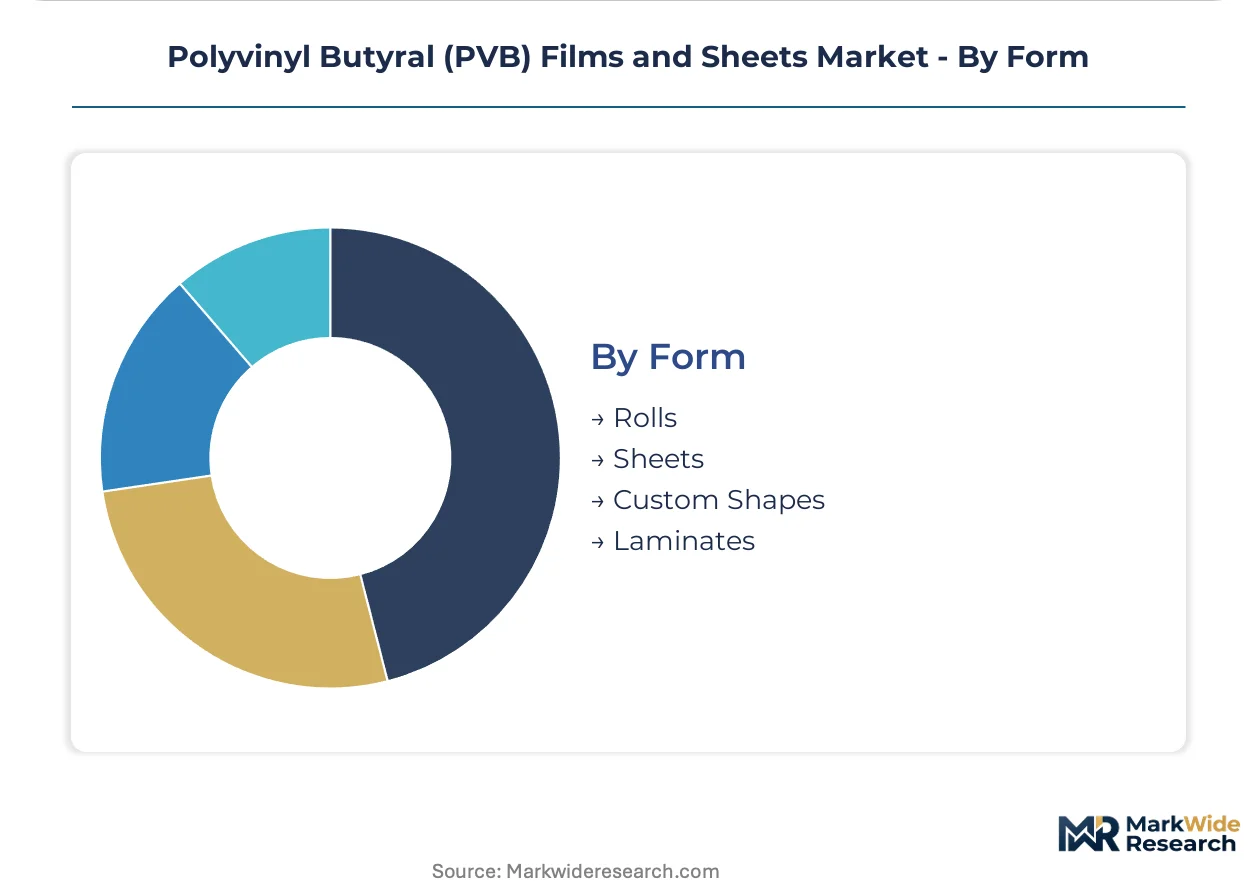
Form:
Roll format dominates high-volume continuous lamination, while sheet and custom configurations serve batch-processed specialty applications.
- Rolls:Continuous-web interlayers up to several thousand meters in length feed automated automotive and architectural laminating lines. Eastman Chemical Company and integrated petrochemical groups in China sustain dedicated resin-to-roll infrastructure investments along the Yangtze River Delta corridor.
- Sheets:Cut-to-size flat interlayers serve replacement glass fabricators and smaller architectural laminators without slitting capabilities.
- Custom Shapes:Pre-cut contours for complex-curved windshields and architectural free-form glazing reduce laminator waste and labor but require precision die-cutting or laser trimming investments.
- Laminates:Pre-bonded interlayer-glass assemblies for rapid installation in retrofit and repair channels.
Process automation is deepest in Rolls. Flexibility premiums are highest in Custom Shapes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Butyraldehyde feedstock availability anchors regional production economics, with naphtha-derived acetaldehyde supply chains clustering near major petrochemical complexes. Integrated resin-to-film operations concentrate where automotive assembly and architectural glazing demand overlap.
China
Eastman Chemical Company and domestic petrochemical groups sustain captive butyraldehyde-to-PVB pipelines along the Yangtze River Delta corridor. GB standards administered by the Standardization Administration shape export qualification requirements for automotive safety glass. Jiangsu and Zhejiang provinces host concentrated windshield fabrication capacity serving domestic EV brands and European luxury export programs.
United States
NHTSA mandates laminated windshield construction under Federal Motor Vehicle Safety Standard 205, structuring interlayer demand specifications for optical clarity and penetration resistance. The regulation directly binds Tier-one glass processors to qualified resin-grade suppliers with dual-source pedigree requirements. Southeast automotive assembly corridors sustain dedicated roll-format interlayer supply agreements.
Germany
Luxury electric vehicle programs specify three-ply acoustic PVB configurations that separate structural adhesion from noise attenuation functions. ECHA enforcement timelines under REACH accelerate substitution toward bio-based plasticizer chemistries, opening qualification windows for reformulated sheet producers. Southern German automotive clusters anchor premium-grade resin capacity through multi-year supply agreements.
Japan
Sekisui Chemical Co., Ltd. and Kuraray Co., Ltd. anchor specialized resin grades for acoustic and photovoltaic encapsulation segments. METI industrial standards shape formulation requirements for display bonding and touch panel applications demanding ultra-thin caliper control. Kanto and Kansai manufacturing belts concentrate loss-factor engineering talent scarce across other geographies.
India
Proposed amendments to CMVR windshield penetration standards would replicate NHTSA-equivalent laminated glass requirements across domestic passenger vehicle production. The Central Motor Vehicles Rules framework is tightening safety specifications faster than local resin capacity can qualify. Maharashtra and Gujarat automotive corridors currently import qualified interlayers pending domestic supply chain maturation.
Polyvinyl Butyral (PVB) Films and Sheets Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue acoustic specialization and regional toll-sheet conversion. The market structures around three major chemical groups with captive butyraldehyde-to-film pipelines, constraining third-party sheet producers to spot resin markets. Strategic archetypes include integrated petrochemical conglomerates, specialty resin houses with loss-factor engineering capabilities, and regional toll-sheet converters dependent on third-party coating capacity. Dominant competitive moves involve multi-year resin-grade commitments locking optical clarity tolerances and geographic expansion through qualified supplier matrix consolidation.
Among Asia-Pacific-based integrated producers, Chang Chun Group and Huakai Plastic exemplify the petrochemical conglomerate archetype with regional supply chain anchoring. Sekisui Chemical Co., Ltd. represents the specialty resin house positioned for premium acoustic and optical grade applications. These three occupy positions spanning standard through premium-tier value pools without overlapping strategic territory.
| Leading Market Players |
|---|
| Chang Chun Group |
| EVERLAM |
| Eastman Chemical Company |
| Zhejiang Decent Plastic |
| Huakai Plastic |
| Sekisui Chemical Co., Ltd. |
| Saint-Gobain |
| Kingboard Chemical Holdings |
| Kuraray Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Tier-one automotive laminators with dual-source qualification mandates are compressing spot-market transactions in favor of multi-year resin-grade commitments. This procurement consolidation across China's Yangtze River Delta and southern German automotive clusters is anchoring contract-based long-term offtake as the dominant pricing model for premium acoustic and optical grades.
Pricing Analysis
Warranty-backed penetration resistance certification and unbundled technical service agreements differentiate supplier offerings across the value chain. Three-tier pricing structure across premium, standard, and economy levels separates NHTSA/ECE R43 dual-qualified acoustic grades from commodity transparent interlayers and unbranded replacement-sheet tiers. Cost compression in standard transparent grades is intensifying because Chinese petrochemical groups are expanding captive resin-to-film capacity. Construction channel intermediaries serving commercial facade projects exhibit the highest price sensitivity, while luxury electric vehicle OEMs in Germany and Japan demonstrate minimal elasticity for frequency-tuned multilayer specifications.
Supply Chain Analysis
Dual-sourcing requirements mandated by automotive OEM procurement matrices are fragmenting resin supply concentration across qualified supplier pedigrees. Manufacturing gravity centers on China, the United States, and Germany, where integrated butyraldehyde-to-film operations anchor regional production economics. Feedstock dependencies rest on naphtha-derived acetaldehyde, plasticizer chemistries, and specialized resin grades with loss-factor engineering. Single-source vulnerability concentrates in Japanese and German specialty resin houses with scarce acoustic formulation talent. Distribution runs through qualified Tier-one glass processors with direct OEM relationships, bypassing spot-market sheet converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where Europe's REACH plasticizer substitution timeline and F-Gas manufacturing emissions constraints erect barrier-to-entry moats favoring integrated producers with captive solvent recovery and bio-based formulation capabilities.
For Market Incumbents: To counter ethylene-vinyl acetate substitution in photovoltaic encapsulation, Eastman Chemical Company and Sekisui Chemical Co., Ltd. should deepen backward integration into bio-based plasticizer synthesis and expand acoustic engineering capacity in Kanto and southern German manufacturing belts. Certification investment locking ECE R43 and GB 9656 homologation cycles ahead of regulatory divergence timelines preserves qualified supplier matrix positioning. For New Entrants and Emerging Players: Launch via toll-sheet conversion partnerships serving India's Maharashtra and Gujarat automotive corridors, where proposed CMVR amendments are replicating NHTSA-equivalent laminated glass requirements faster than domestic resin capacity can qualify. Building-integrated photovoltaics with colored and patterned interlayer specifications for solar facade applications represents the most penetrable white-space target, with boutique architectural practices as the initial go-to-market channel. For Investors and Strategic Acquirers: The window for entry favors regional toll-sheet converters with qualified coating capacity and dual-certification pedigree in the 5-10 year horizon. Acquisition targets should display captive relationships with integrated resin suppliers or proprietary loss-factor engineering talent concentrated in Japan and Germany. Watch for F-Gas enforcement acceleration in European manufacturing as the signal indicating margin compression for non-integrated compounders and consolidation opportunity for compliant integrated producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Plasticizer Synthesis | REACH compliance timelines under ECHA enforcement are advantaging producers with captive bio-based additive capacity over spot-market compounders. |
| Acoustic Engineering Talent Acquisition | Loss-factor formulation expertise concentrated at Sekisui Chemical Co., Ltd. and Kuraray Co., Ltd. commands premium positioning in luxury electric vehicle programs. |
| Dual-Certification Capacity Expansion | Simultaneous NHTSA FMVSS 205 and ECE R43 qualification extends addressable procurement matrices for Tier-one glass processors serving export markets. |
| Water-based Sheet Casting Transition | Europe's F-Gas phasedown is advantaging integrated producers with solvent recovery systems over toll converters dependent on third-party coating infrastructure. |
| India Market Entry via Qualified Partnership | Proposed CMVR windshield penetration amendments are creating first-mover windows for interlayer suppliers ahead of domestic resin capacity maturation. |
Research Methodology
Independent corroboration across plant managers at integrated resin-to-film operations, procurement leads at automotive Tier-one glass processors, distribution channel partners serving architectural laminators, and technical R&D directors at specialty resin houses underwrites the qualitative findings. Secondary validation draws from customs and trade data, ACC and Cefic chemical industry reports, SEC 10-K filings of listed petrochemical groups, and vehicle production databases. Bottom-up capacity and demand modeling triangulates against top-down macroeconomic anchors across the analysis window.
Comparable-period anchoring to historical automotive safety glass penetration rates and architectural glazing code adoption curves structures the forecast framework. Segmentation dimensions modeled include product type tier, end-use application channel, form factor, and regional production cluster. CAGRs derive from elasticity-adjusted volume projections incorporating electric vehicle platform expansion rates and building-integrated photovoltaics qualification timelines as industry-specific demand drivers throughout the forecast period.
Feedstock price volatility in naphtha-derived acetaldehyde, regulatory divergence in plasticizer chemistries between REACH and GB standards jurisdictions, and substitution acceleration in photovoltaic encapsulation are the dominant revision risks. Deviation in butyraldehyde feedstock economics would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Global Membrane Separation Technology Market
Membrane Materials
Global Ultrafiltration Market
Membrane Materials
Global Polymer Nanomembrane Market
Membrane Materials
Global Transfer Membrane Market
Membrane Materials
North America below Grade Waterproofing Membranes Market
Membrane Materials
Self-Adhered Roofing Membranes Market
Membrane Materials
Thermoplastic Polyolefin Membranes Market
Membrane Materials
North America Single-Ply Membrane Market
Membrane Materials
Nanoporous Membranes Market
Membrane Materials
Polymer Electrolyte Membrane Fuel Cells (Pemfcs) Market
Membrane Materials
Global Waterproofing Membrane Market
Membrane Materials
Membrane Chemicals Market
Membrane Materials
Nanofiltration Membrane Market
Membrane Materials
Hollow Fibers Membrane Market
Membrane Materials
Membrane Separation Market
Membrane Materials
APP and SBS Modified Bitumen Membrane Market