
 Asia Pacific Waterproofing Membrane Market | 2026-2036
Asia Pacific Waterproofing Membrane Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Waterproofing Membrane Market Analysis
High-performance polymer-grade specifications is collapsing the gap between commodity bituminous sheets and engineered synthetic systems across the region. Sika AG leverages its Swiss-Asian manufacturing footprint to supply self-adhered modified bitumen systems for transit infrastructure. Beijing Oriental Yuhong Waterproof Technology Co., Ltd. anchors the Chinese domestic market through captive resin compounding and national distribution density. BASF SE differentiates via polyurethane liquid membrane chemistry that competes directly with sheet goods in complex geometries.
Asia Pacific waterproofing membranes are flexible barrier sheets or fluid-applied coatings, typically formulated from modified bitumen, polyvinyl chloride, thermoplastic polyolefin, or ethylene propylene diene monomer rubber, designed to prevent water ingress across structural substrates. These systems achieve elongation ratings exceeding 300% and are manufactured through calendering, extrusion, or reactive casting processes to seal roofs, basements, and civil infrastructure against hydrostatic pressure. Bituminous membranes retain volume leadership across the region due to cost parity with conventional construction budgets, while TPO membranes represent the fastest-growing product category as green building certification expands commercial roofing retrofit activity. Among installation methods, mechanically attached systems dominate high-wind zones across coastal East Asia, whereas adhesive bonding captures premium specification in submerged foundation applications where pull-off strength thresholds exceed 2.0 N/mm².
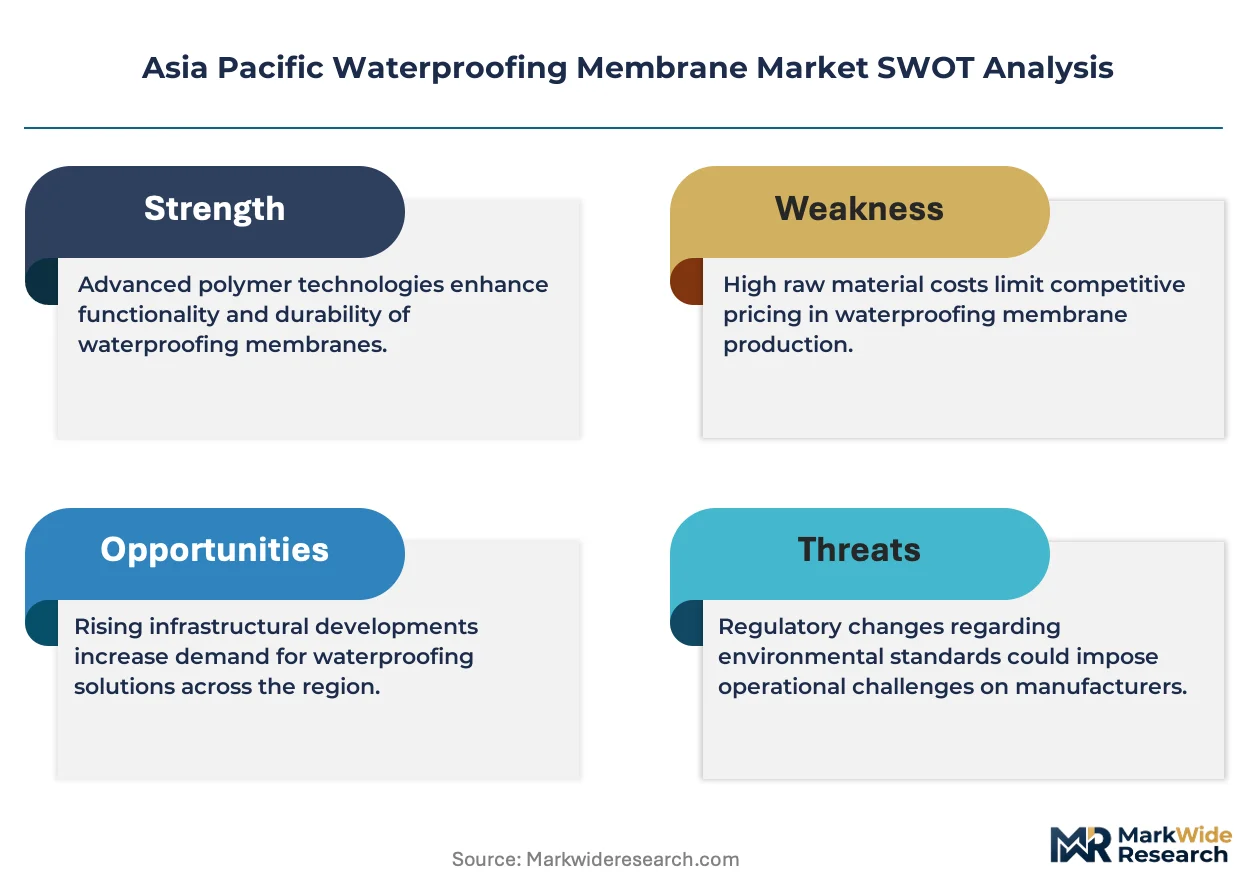
China's GB 18242 and GB 23441 standards, administered by SAMR, mandate tensile strength and heat resistance testing that disqualifies uncertified imports from public project bidding. India's BIS IS 13262 certification and Japan's JIS A 6008 framework similarly constrain market access to tested membrane constructions, creating compliance moats around established suppliers. Australia's TGA-adjacent building code provisions and South Korea's MFDS-aligned construction material safety protocols add further regulatory layering across the region. Stakeholders must monitor evolving polymer feedstock volatility and certification reciprocity negotiations between national standards bodies to anticipate sourcing cost shifts and qualification timelines.
Market Dynamics
China's GB standards and India's BIS certification mandates are tightening product compliance thresholds, forcing membrane manufacturers to restructure formulation chemistry and testing protocols to maintain market access across the region's largest construction corridors.
Growth Catalysts
- Commercial Infrastructure Development:Southeast Asian transit and mixed-use projects are accelerating specification-grade membrane procurement for high-performance building envelopes.
- GB 18242 and GB 23441 Standards:China's SAMR-administered tensile strength and heat resistance testing requirements are filtering out uncertified imports and consolidating domestic supply chains.
- Green Building Certification Expansion:TPO membrane demand is surging across commercial roofing retrofit activity as LEED-equivalent standards proliferate in tier-one Chinese and Indian metropolitan belts.
Market Restraints
- Polymer Feedstock Volatility:Ethylene and propylene derivative pricing swings compress margin stability for synthetic membrane producers dependent on petrochemical inputs.
- Import Certification Reciprocity Delays:Japan's JIS A 6008 framework and South Korea's MFDS-aligned protocols create asynchronous qualification timelines that fragment cross-border supply planning.
- Bituminous Cost Parity:Modified bitumen sheets retain volume leadership due to alignment with conventional construction budgets, limiting premium synthetic penetration in price-sensitive segments.
Strategic Opportunities
- Vietnam and Indonesia Infrastructure Buildout:Underpenetrated waterproofing specification in Southeast Asian manufacturing and logistics corridors offers first-mover positioning for certified suppliers.
- Self-Adhered System Adoption:Mechanically attached systems in coastal East Asian high-wind zones are yielding share to adhesive-bonded alternatives in submerged foundation applications.
- India's BIS IS 13262 Enforcement:Tightening certification mandates are creating compliance moats that favor established domestic compounders with captive resin production.
Industry Challenges
- Reactive Casting Process Expertise Gap:Polyurethane liquid membrane application requires specialized contractor training that remains scarce outside China's tier-one construction corridors.
- Multi-Jurisdiction Certification Burden:Australia's TGA-adjacent building code provisions and fragmented ASEAN national standards force redundant testing expenditure for regional suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Waterproofing Membrane Market |
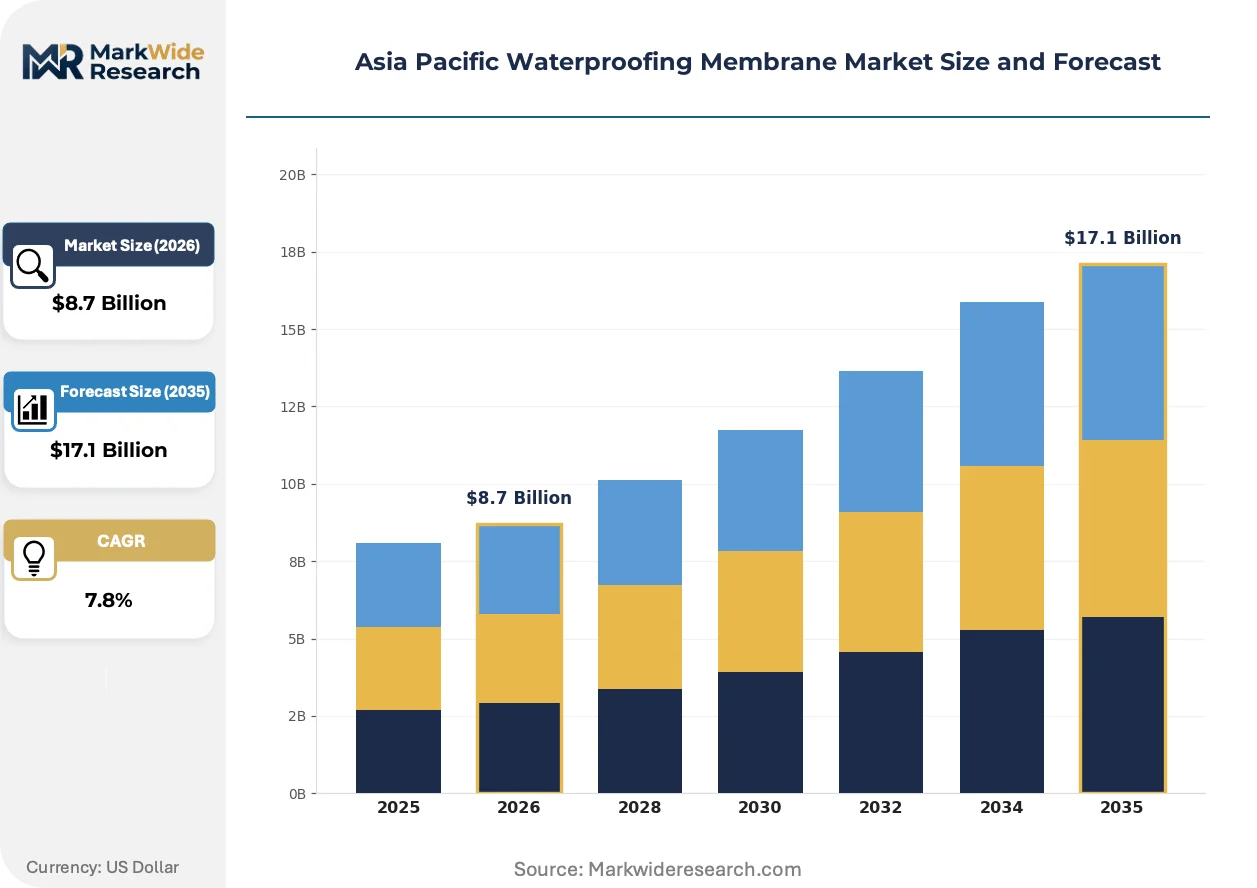
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bituminous Membranes, PVC Membranes, TPO Membranes, EPDM Membranes Application: Roofing, Walls, Foundations, Bridges End User: Construction Companies, Homeowners, Architects, Contractors Installation Type: Adhesive Bonding, Mechanically Attached, Loose Lay, Self-Adhered |
| Companies Covered | Sika AG, Beijing Oriental Yuhong Waterproof Technology Co., Ltd., Saint-Gobain, BASF SE, Fosroc International Ltd., Ardex Group, Pidilite Industries Ltd., KCC Corporation, Mapei S.p.A., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Waterproofing Membrane Market Emerging Trajectories
High-performance polymer specifications are collapsing the traditional performance gap between commodity bituminous systems and engineered synthetic membranes, reshaping competitive positioning across specification tiers.
Thermoplastic polyolefin (TPO) membrane technology delivers heat-welded seam integrity and reflective surface properties that reduce cooling loads in commercial roofing applications. Large-scale developers in Shanghai, Beijing, and Delhi metropolitan belts are specifying TPO for new construction and retrofit portfolios at accelerating rates. This material is supplanting EPDM rubber membranes in projects where energy performance certification and installation speed carry premium weight.
China's dual carbon goals and India's Bureau of Energy Efficiency mandates are tightening embodied carbon thresholds for construction materials entering public procurement channels. Waterproofing membrane suppliers must now submit lifecycle assessment documentation and regional manufacturing provenance to qualify for infrastructure tenders. Synthetic polymer systems with recycled content claims are capturing specification share in government-backed transit and utility projects where green procurement scoring determines award outcomes.
Specification-grade buyers are consolidating vendor relationships around full-system warranty providers capable of underwriting 20-year performance guarantees. Distributors in Japan and South Korea are shifting from commodity trading to technical specification support, embedding application engineers within contractor bidding processes. This channel transformation is most visible in Australia's commercial podium and basement waterproofing segments, where design-build contracts bundle membrane supply with certified installation labor.
Asia Pacific Waterproofing Membrane Market Segmentation
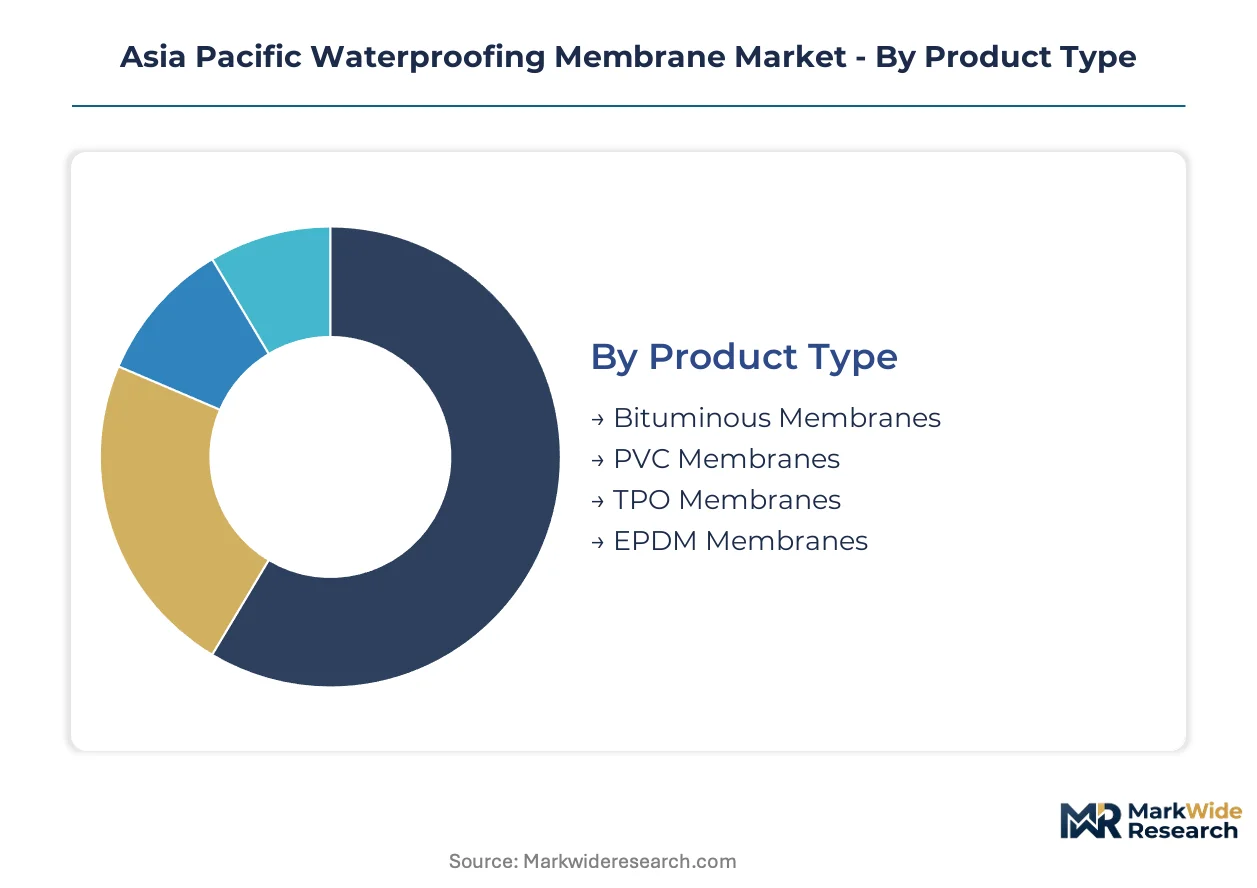
Waterproofing membrane procurement flows through distinct channel configurations that vary by product chemistry, application criticality, and end-user technical sophistication. Specification-grade synthetics route through distributor-engineer relationships, while commodity bituminous products move via construction material wholesalers serving price-sensitive contractors.
Product Type:
Channel mix varies sharply by chemistry: modified bitumen moves through high-volume construction supply yards, while engineered synthetics require specification support from technical distributors with in-house application engineering.
- Bituminous Membranes:These asphalt-modified sheets, reinforced with polyester or fiberglass carriers, dominate procurement through China's construction material wholesale networks and India's regional distributor hubs serving tier-two contractors. Cost parity with conventional roofing budgets sustains volume leadership across Southeast Asian public infrastructure corridors.
- TPO Membranes:Thermoplastic polyolefin sheets deliver heat-welded seam integrity and solar reflectance that reduces cooling loads. Demand concentrates in Shanghai, Beijing, and Delhi metropolitan belts where LEED-equivalent certification governs commercial roofing specification for new construction and retrofit portfolios.
- PVC Membranes:Polyvinyl chloride systems offer chemical resistance and dimensional stability for industrial roofing and containment applications across Japan's manufacturing zones and South Korea's heavy industrial corridors.
- EPDM Membranes:Ethylene propylene diene monomer rubber provides elastomeric performance for low-slope roofing in Australia's commercial podium developments and New Zealand's institutional building stock.
Bituminous membranes dominate installed base. TPO membranes are where expansion concentrates.
Application:
Cost tier stratification separates specification-grade submerged applications from above-grade commodity roofing, with foundation and bridge work commanding premium chemistry and certified installation labor.
- Roofing:Above-grade membrane specification splits between cost-driven bituminous systems in residential and light commercial, and TPO/PVC in certified green building projects across China's tier-one cities and India's metropolitan infrastructure belts.
- Foundations:Below-grade waterproofing demands adhesive-bonded or self-adhered systems with pull-off strength exceeding 2.0 N/mm². Procurement concentrates through design-build contractors in Australia's basement podium market and China's high-rise residential towers.
- Walls:Vertical envelope applications favor fluid-applied polyurethane and self-adhered sheet membranes for complex geometries where sheet goods prove impractical, particularly in Japan's seismic-resistant construction and South Korea's dense urban infill.
- Bridges:Civil infrastructure specification mandates heat-resistant, high-elongation systems compliant with GB 18242 and JIS A 6008 testing protocols, routing through state-owned contractor procurement channels in China and Japan's public works agencies.
Roofing commands the largest installed square footage. Foundation applications are climbing the fastest as below-grade construction intensifies in dense Asian metropolitan zones.
End User:
Customer type determines technical support intensity: architects and design-build contractors demand full-system warranties with 20-year performance guarantees, while homeowners and small contractors prioritize material cost and local availability.
- Construction Companies:Large developers and general contractors in China's state-backed infrastructure and India's metro rail projects specify certified membranes through centralized procurement with lifecycle assessment documentation requirements.
- Contractors:Installation specialists in Australia's commercial waterproofing segment and Japan's technical roofing trade increasingly bundle membrane supply with certified labor, shifting distributor relationships toward specification partnership rather than commodity trading.
- Architects:Design professionals in Singapore, Hong Kong, and Australia's green building corridors specify TPO and PVC systems for energy performance certification, embedding membrane selection within envelope system design.
- Homeowners:Residential repair and renovation demand routes through retail building material channels in Indonesia, Vietnam, and Philippines, where price sensitivity sustains bituminous sheet dominance.
Construction companies dominate specification-grade volume. Contractor-led bundled procurement is gaining share fastest as design-build contracts proliferate.
Installation Type:
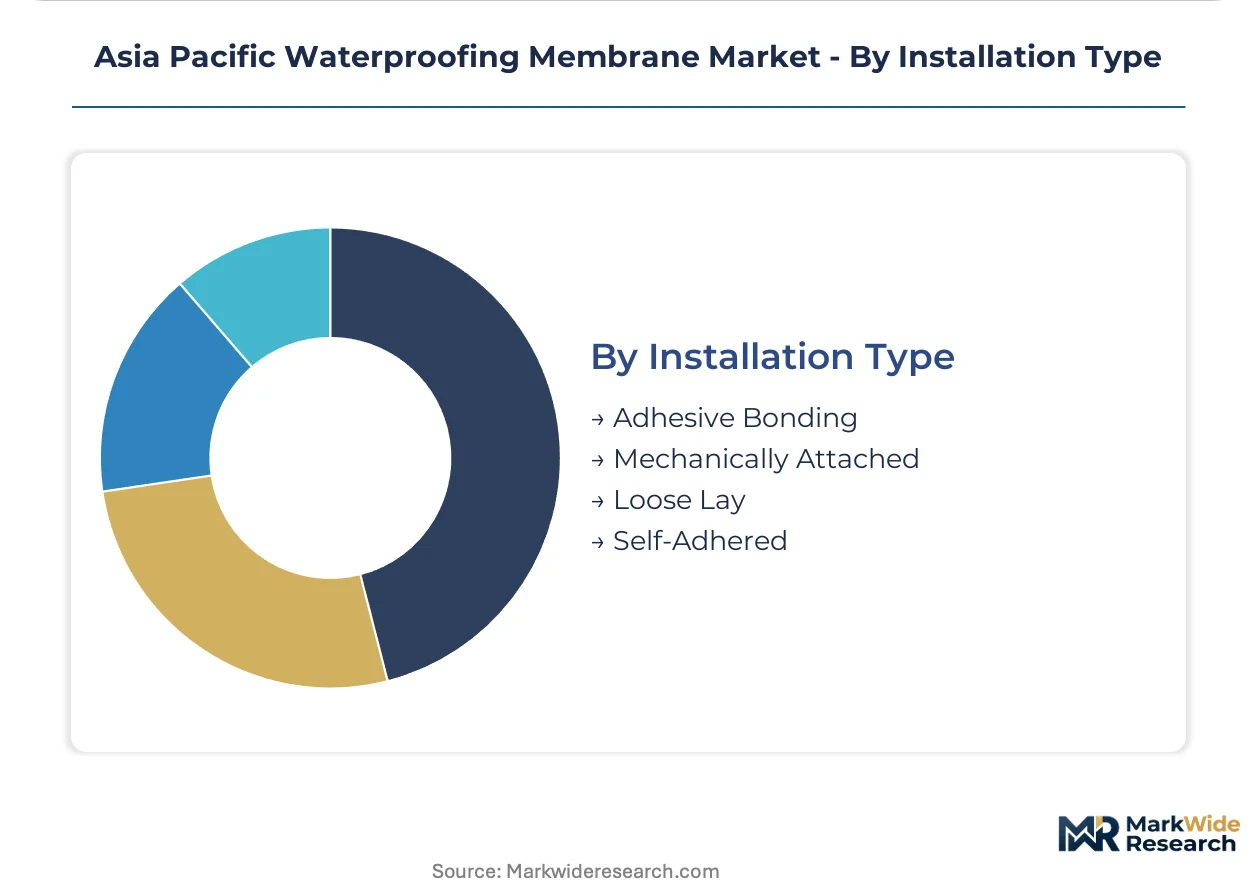
Volume concentration varies by geography and wind exposure: mechanically attached systems prevail in coastal East Asian typhoon zones, while adhesive and self-adhered methods capture submerged and high-wind-uplift applications.
- Mechanically Attached:Fastener-based systems dominate high-wind zones across coastal China, Japan, and South Korea where roofing membranes face typhoon exposure, installed through specialized roofing contractors with wind-uplift certification.
- Self-Adhered:Factory-applied adhesive layers eliminate torch hazards and accelerate installation in confined foundation and wall applications across Australia's podium waterproofing market and China's dense urban construction sites.
- Adhesive Bonding:Field-applied adhesive systems capture premium specification in submerged foundation work where pull-off strength thresholds exceed 2.0 N/mm², common in India's metro infrastructure and Singapore's deep basement developments.
- Loose Lay:Ballasted systems serve temporary roofing and select commercial applications where structural load capacity permits, primarily in Australia's industrial warehousing and New Zealand's agricultural building stock.
Mechanically attached systems dominate installed base. Self-adhered methods are where specification expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Vietnam and Indonesia exhibit acute price sensitivity toward bituminous sheet goods, while specification-grade procurement in Shanghai and Singapore commands premium synthetic systems without material cost elasticity.
China
State-backed infrastructure corridors in the Yangtze River Delta and Pearl River Delta drive specification-grade membrane volumes for transit and high-rise residential towers. SAMR-administered GB 18242 and GB 23441 standards mandate tensile strength and heat resistance testing that filters uncertified imports from public bidding. Beijing Oriental Yuhong anchors domestic supply through captive resin compounding and national distribution density concentrated in tier-one construction belts.
India
Metropolitan infrastructure belts around Mumbai, Delhi-NCR, and Bangalore generate accelerating demand for below-grade waterproofing in metro rail and commercial basement developments. BIS IS 13262 certification mandates tighten compliance thresholds, creating procurement moats around established domestic compounders. Pidilite Industries leverages its Indian manufacturing footprint to supply adhesive-bonded systems for foundation applications where pull-off strength exceeds regulatory minimums.
Japan
Seismic-resistant construction codes and dense urban infill projects in Tokyo and Osaka favor fluid-applied polyurethane membranes for complex wall geometries. METI-aligned JIS A 6008 testing protocols constrain market access to certified membrane constructions, fragmenting cross-border supply planning. Technical roofing contractors in the Kanto region increasingly bundle membrane specification with certified installation labor under design-build contracts.
Australia
Commercial podium and basement waterproofing segments in Sydney and Melbourne drive specification-grade procurement with 20-year performance guarantee requirements. TGA-adjacent building code provisions add regulatory layering that forces redundant testing expenditure for regional suppliers. Distributors are shifting from commodity trading to technical specification support, embedding application engineers within contractor bidding processes.
South Korea
Heavy industrial corridors in Busan-Ulsan and the Seoul Capital Area demand PVC membrane systems with chemical resistance for manufacturing and containment applications. MFDS-aligned construction material safety protocols create asynchronous qualification timelines with neighboring jurisdictions. KCC Corporation represents domestic supply capacity serving these industrial specifications through established compounder relationships.
Asia Pacific Waterproofing Membrane Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the Asia Pacific waterproofing membrane market. Swiss and European multinationals anchor premium specification tiers through polyurethane liquid chemistry and self-adhered modified bitumen systems, while Chinese and Korean compounders dominate volume production of bituminous and TPO sheet goods. Three strategic archetypes define competitive positioning: integrated resin compounders with captive feedstock control, specification-grade system houses with full-system warranty capabilities, and regional distributors evolving toward technical partnership models. Capacity expansion in Southeast Asian manufacturing corridors and backward integration into polymer feedstock represent the dominant competitive moves reshaping supply structure.
Among European-based system houses, Sika AG and BASF SE exemplify technology-led positioning through differentiated chemistry platforms. Sika leverages its Swiss-Asian manufacturing footprint to anchor transit infrastructure specification, while BASF SE occupies a position in polyurethane liquid membrane technology competing directly with sheet goods in complex geometries. Beijing Oriental Yuhong Waterproof Technology Co., Ltd. represents the integrated domestic compounder archetype in China, combining captive resin production with national distribution density to serve GB-certified public procurement channels. These three players illustrate the competitive tension between imported technology leadership and localized cost-engineered supply across the region's tiered specification markets.
| Leading Market Players |
|---|
| Sika AG |
| Beijing Oriental Yuhong Waterproof Technology Co., Ltd. |
| Saint-Gobain |
| BASF SE |
| Fosroc International Ltd. |
| Ardex Group |
| Pidilite Industries Ltd. |
| KCC Corporation |
| Mapei S.p.A. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Chinese state-backed infrastructure developers and domestic membrane compounders lock in both polymer feedstock access and price visibility across the Yangtze River Delta construction corridor. These arrangements insulate tier-one suppliers from ethylene derivative volatility while forcing uncertified imports to compete on spot terms against GB 18242-compliant domestic production.
Pricing Analysis
China's SAMR-administered GB 18242 and GB 23441 standards dictate the pricing tier structure by filtering uncertified imports from public project bidding and consolidating procurement around tested domestic supply. Three-tier pricing structure across premium synthetic, certified bituminous, and commodity sheet levels separates specification-grade TPO systems for green building portfolios from cost-driven modified bitumen for residential roofing. Price differentiation hinges on certification tier and volume scale, with BIS IS 13262 compliance in India adding parallel qualification costs. Cost compression in commodity bituminous tiers is intensifying because of feedstock volatility and Southeast Asian import competition. Homeowners and small contractors in Indonesia and Vietnam exhibit acute price sensitivity, while design-build contractors in Singapore and Sydney accept premium positioning for full-system warranties.
Supply Chain Analysis
Polymer resin import dependency through the Strait of Malacca creates chokepoint exposure for synthetic membrane producers across Southeast Asian manufacturing corridors. Supply concentrates in China, South Korea, and Japan for calendered sheet production, with India emerging as a regional compounding hub for bituminous systems. Raw material draws from naphtha crackers in East Asia, EPDM rubber feedstock from Singapore and Thailand, and tackifier resins from domestic Chinese sources. Single-source vulnerability in specialty polymer modifiers creates formulation risk for polyurethane liquid membrane suppliers. Distribution runs through technical distributors with in-house application engineering for specification-grade synthetics, while commodity bituminous moves via construction material wholesalers serving price-sensitive contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Green building certification mandates across China's tier-one cities and India's metropolitan belts are accelerating specification-grade membrane procurement faster than conventional construction growth would predict.
For Market Incumbents: Shield specification-grade positioning by deepening captive resin production in the Yangtze River Delta and Pearl River Delta corridors to offset polymer feedstock volatility. Invest in BIS IS 13262 and JIS A 6008 certification reciprocity to compress cross-border qualification timelines against emerging Korean and Southeast Asian compounders. Channel control through design-build contractor partnerships in Australia's podium waterproofing segment defends margin position against distributor disintermediation. For New Entrants and Emerging Players: Differentiate on fluid-applied polyurethane application expertise to capture wall and complex geometry specification in Japan's seismic-resistant construction and South Korea's dense urban infill. Target Vietnam and Indonesia infrastructure buildout for first-mover positioning in underpenetrated manufacturing and logistics corridors where certified supply remains scarce. Bundle membrane supply with certified installation labor under design-build contracts to bypass established distributor relationships. For Investors and Strategic Acquirers: Capital is best deployed toward integrated resin compounders with captive feedstock control and established GB or BIS certification moats across the Asia Pacific waterproofing membrane market. Long-term viability over the coming decade hinges on backward integration into polymer feedstock and regional manufacturing provenance documentation for green procurement scoring. Watch for MFDS-aligned protocol harmonization with China's SAMR standards as the signal indicating accelerated cross-border consolidation opportunity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Feedstock | Captive resin compounding insulates margin stability against ethylene and propylene derivative pricing swings. |
| Multi-Jurisdiction Certification Investment | Parallel GB 18242, BIS IS 13262, and JIS A 6008 qualification compresses regional supply planning fragmentation. |
| Design-Build Contractor Partnership | Technical specification embedding within contractor bidding processes shifts distributor relationships toward value-added partnership. |
| Southeast Asian Manufacturing Expansion | Localized production in Vietnam and Indonesia corridors captures infrastructure buildout demand with reduced logistics exposure. |
| Lifecycle Assessment Documentation Capability | Regional manufacturing provenance and embodied carbon scoring qualifies suppliers for China's dual carbon procurement mandates. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs and trade data, SAMR certification registries, BIS product directories, and SEC filings from listed chemical compounders. Primary interviews engaged membrane plant managers, procurement leads at state-backed infrastructure developers, technical roofing contractors in Japan's Kanto region, and distributor principals across Australia's commercial waterproofing segment. Secondary validation drew from construction material trade databases, green building certification agency disclosures, and polymer feedstock pricing benchmarks. Bottom-up membrane volume estimates triangulated against top-down construction spending projections across the analysis window.
Segmentation dimensions modeled include product chemistry tier, application criticality, end-user technical sophistication, installation method, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted construction spending trajectories and specification penetration curves for synthetic versus bituminous systems. Forecast inputs incorporated GB standards enforcement timelines, BIS certification mandate expansion, and green building certification adoption rates across Shanghai, Beijing, and Delhi metropolitan belts throughout the forecast period.
Forecasts assume regulatory continuity in China's SAMR-administered standards, India's BIS enforcement, and Japan's METI-aligned protocols; material policy shifts would require re-modeling supply access assumptions and qualification cost structures. Practitioners should keep alternative scenarios live as polymer feedstock volatility and certification reciprocity negotiations between national standards bodies evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Global Spiral Membrane Market
Membrane Materials
Vapor Barrier Films Market
Membrane Materials
Expansion Vessel Membrane Market
Membrane Materials
Nanoporous Membranes Market
Membrane Materials
Bitumen Membrane Sheets Market
Membrane Materials
Global Ceramic Membrane Market
Membrane Materials
Global Track Etched Membrane Market
Membrane Materials
Global Medical Membranes Market
Membrane Materials
Membrane Chemicals Market
Membrane Materials
Ultrafiltration Membrane Market
Membrane Materials
Global Breathable Membranes Market
Membrane Materials
PVDF Membrane Market
Membrane Materials
Liquid Applied Membranes Market
Membrane Materials
Membranes Market
Membrane Materials
Reverse Osmosis Films Market
Membrane Materials
Industrial Solvent Separation Membranes Market