
 Global Chemical Separation Membranes Market | 2026-2036
Global Chemical Separation Membranes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chemical Separation Membranes Market Foresight
The capital-intensity divergence between integrated polymer producers and specialized membrane fabricators is redrawing competitive boundaries in chemical separation. BASF SE leverages captive polyethersulfone resin production to control feedstock costs across its membrane portfolio. DuPont de Nemours, Inc. sustains technology leadership in hollow-fiber configurations for high-pressure gas separation. Toray Industries, Inc. anchors its position through backward integration into polyimide chemistry for solvent-resistant modules.
Chemical separation membranes are semipermeable barriers engineered from polymeric, ceramic, or composite materials with pore sizes ranging from 0.1 nanometers to 10 micrometers, manufactured through phase inversion, sintering, or interfacial polymerization to enable selective permeation based on molecular size, charge, or affinity. Polymeric membranes dominate installed volume due to cost-scalability in spiral-wound configurations, though ceramic segments command premium positioning in aggressive chemical environments above 80°C. Reverse osmosis and nanofiltration together capture the majority of value in water treatment and pharmaceutical applications where monovalent ion rejection determines process economics.
The EPA enforces maximum contaminant level goals that drive membrane replacement cycles in US municipal water systems, while REACH restricts perfluorinated chemistries in European membrane coatings and the EU Green Deal mandates energy-efficiency benchmarks for separation processes. China's MEE implements discharge standards that accelerate ceramic membrane adoption in industrial wastewater. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded product certifications and misaligned R&D allocation.
Market Dynamics
The capital-intensity divergence between integrated polymer producers and specialized membrane fabricators is redrawing competitive boundaries in chemical separation. BASF SE leverages captive polyethersulfone resin production to control feedstock costs across its membrane portfolio. DuPont de Nemours, Inc. sustains technology leadership in hollow-fiber configurations for high-pressure gas separation. Toray Industries, Inc. anchors its position through backward integration into polyimide chemistry for solvent-resistant modules.
Growth Catalysts
- EU Green Deal energy-efficiency mandates:The regulation tightens benchmarks for separation processes, forcing industrial facilities to retrofit with high-performance membranes that reduce thermal distillation loads.
- China's MEE discharge standards:Industrial wastewater rules in Jiangsu and Shandong provinces accelerate ceramic membrane deployment for heavy-metal removal in electroplating clusters.
- Polyimide chemistry advances:Solvent-resistant modules enable organic solvent nanofiltration in pharmaceutical active ingredient recovery, displacing energy-intensive evaporation.
Market Restraints
- Specialty polymer feedstock concentration:Polyethersulfone and polyimide resin supply concentrates among three Japanese and German chemical groups, exposing fabricators to allocation risk during upstream maintenance cycles.
- REACH perfluorinated chemistry restrictions:The regulation eliminates PTFE and PVDF coating options for European membrane producers, forcing reformulation of hydrophobic gas-separation layers.
- Thermal limitation of polymeric configurations:Spiral-wound modules degrade above 45°C in aggressive chemical streams, ceding high-temperature applications to sintered ceramics.
Strategic Opportunities
- India's pharmaceutical manufacturing corridor:The PLI scheme for active pharmaceutical ingredients creates membrane demand for solvent recovery and impurity rejection in bulk drug production.
- Biogas upgrading membrane systems:Siloxane-resistant hollow-fiber modules capture methane from landfill and agricultural digesters, enabled by EU renewable natural gas subsidies.
- Digital twin integration with membrane process control:Real-time fouling prediction algorithms reduce chemical cleaning frequency and extend module replacement intervals in municipal desalination.
Industry Challenges
- Interfacial polymerization expertise scarcity:Thin-film composite fabrication requires precision control of aqueous-organic interface chemistry, with qualified process engineers concentrated among legacy reverse-osmosis producers.
- REACH-SVHC certification timelines:Substance of very high concern declarations for novel monomers delay commercialization of modified polyamide chemistries by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chemical Separation Membranes Market |
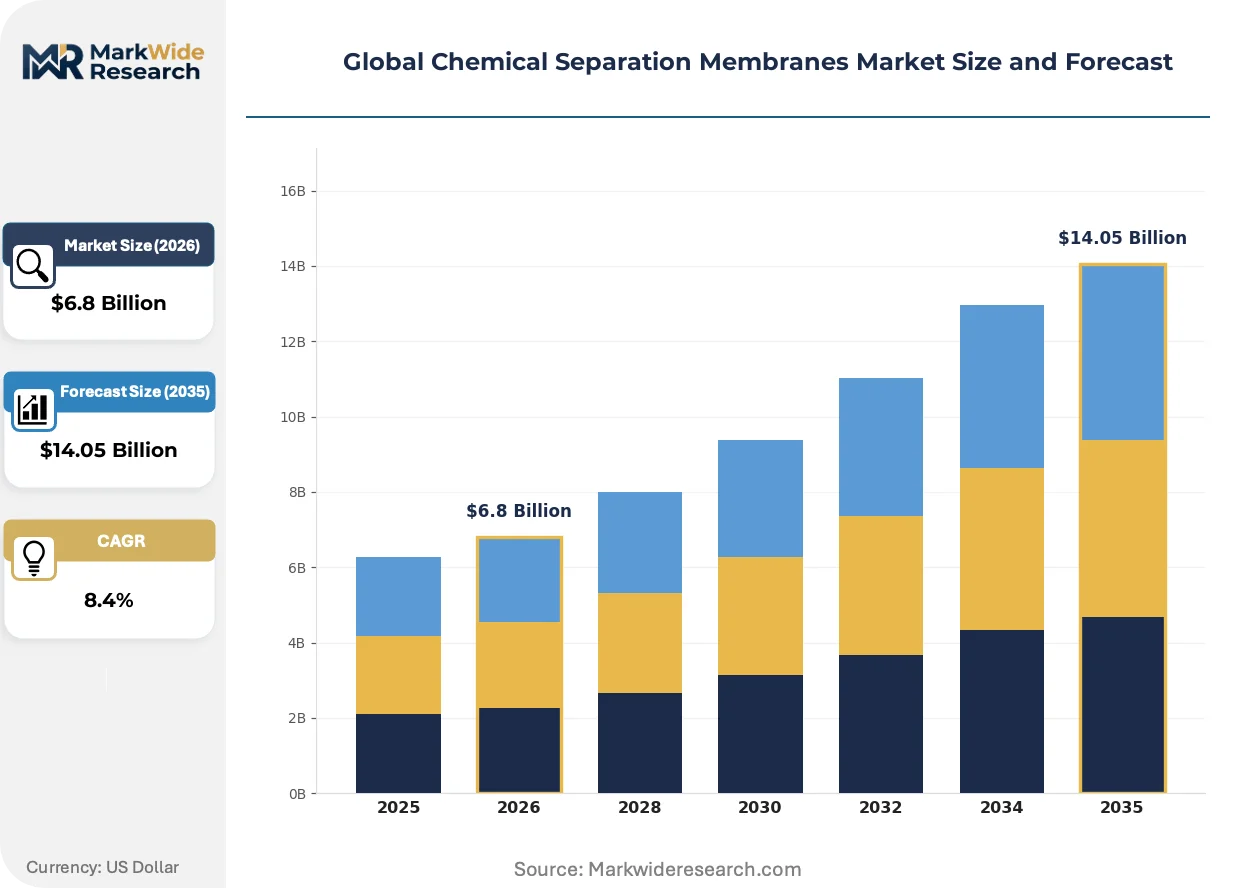
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymeric, Ceramic, Metal, Composite, Cellulose Acetate Separation Technology: Reverse Osmosis, Ultrafiltration, Nanofiltration, Microfiltration, Electrodialysis Application: Water Treatment, Food & Beverage Processing, Pharmaceutical Production, Petrochemical Refining, Wastewater Management End User Industry: Chemical Manufacturing, Oil & Gas, Pulp & Paper, Textile Production, Electronics Fabrication |
| Companies Covered | BASF SE, Air Liquide S.A., DuPont de Nemours, Inc., Pall Corporation, Linde Plc, Toray Industries, Inc., Air Products and Chemicals, Inc., Koch Membrane Systems, Inc., Asahi Kasei Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chemical Separation Membranes Market Shifts & Advancements
Material science breakthroughs and regulatory chemistry bans are compressing product lifecycles while opening substitution pathways. The convergence of process intensification goals with modular system architecture is redefining how separation assets are deployed and financed.
Metal-organic framework membranes is fragmenting the gas-separation landscape by offering molecular sieving precision previously achievable only through cryogenic distillation. Hydrogen purification facilities in Germany's Ruhr industrial cluster are piloting MOF-coated ceramic supports for carbon dioxide rejection. The technology is fragmenting incumbent hollow-fiber positions in high-value petrochemical streams where selectivity premiums justify unit cost multiples.
REACH restrictions on perfluorinated substances are eliminating PTFE surface treatments from European membrane production. Fabricators are pivoting to plasma-enhanced chemical vapor deposition of silicon oxide barriers for hydrophobicity without fluorinated chemistries. The pharmaceutical sterile filtration segment faces the steepest reformulation burden, with validation protocols requiring 12-18 month requalification cycles.
Performance-based membrane supply contracts are displacing traditional capital purchase models in North American municipal water systems. Operators in California and Texas now pay per thousand gallons treated, transferring fouling risk and replacement scheduling to OEM service arms. The shift concentrates procurement authority among regional water authorities with credit ratings sufficient to underwrite decade-long service agreements.
Global Chemical Separation Membranes Market Segmentation
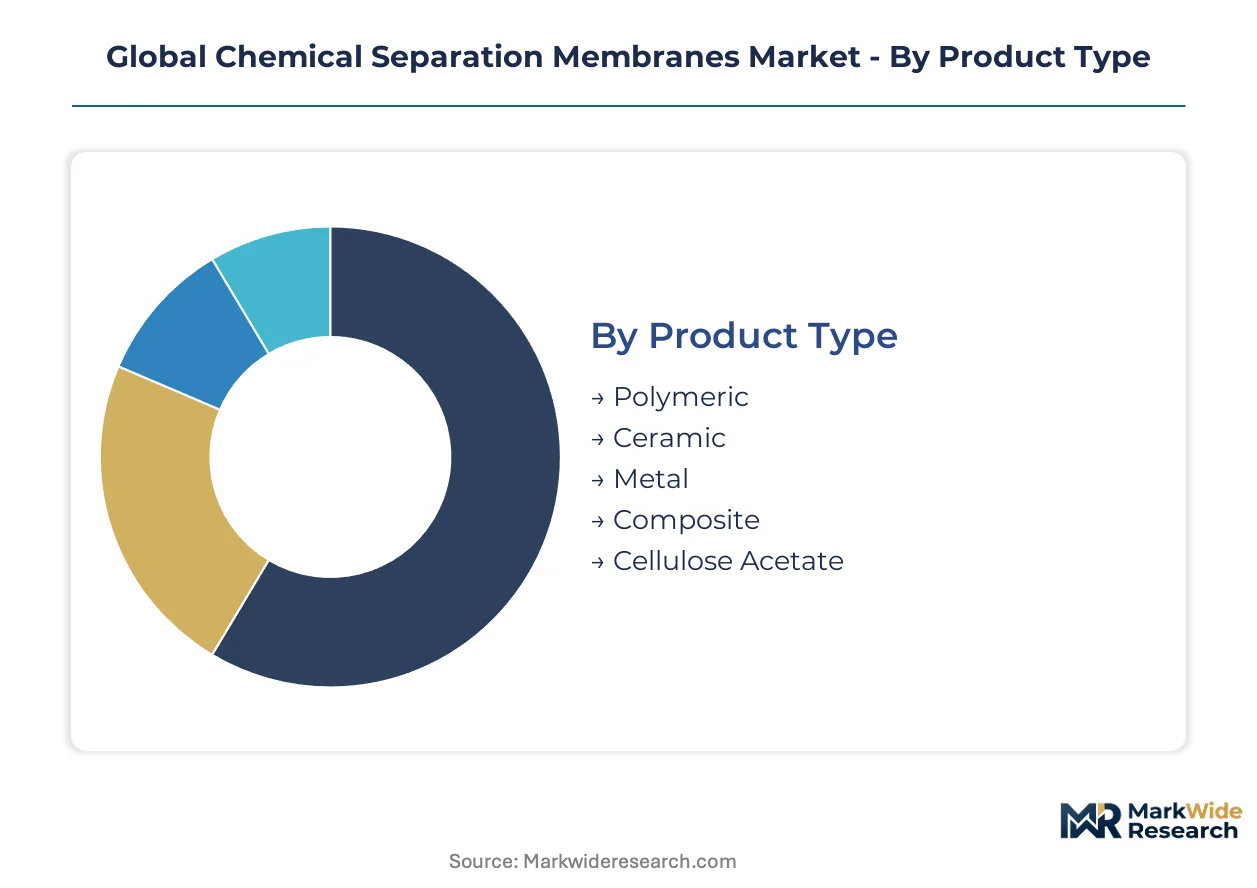
Membrane selection dictates capital efficiency and operating expenditure across chemical separation processes. Product type determines thermal tolerance and chemical resistance, while separation technology governs selectivity precision and energy requirements.
Product Type:
Margin pools concentrate in ceramic and composite configurations where performance premiums offset higher unit costs.
- Polymeric:Spiral-wound and hollow-fiber modules manufactured from polyethersulfone, polyamide, and polyimide dominate installed volume. Municipal desalination plants in California and Texas specify polymeric reverse osmosis for cost-scalability in brackish water treatment.
- Ceramic:Alumina, zirconia, and titania sintered supports withstand temperatures above 80°C and aggressive chemical streams. China's electroplating clusters in Jiangsu province deploy ceramic microfiltration for heavy-metal recovery under MEE discharge mandates.
- Metal:Porous stainless steel and titanium substrates serve high-pressure gas separation where mechanical integrity prevents catastrophic failure.
- Composite:Thin-film polyamide layers on polysulfone supports balance selectivity with permeability in pharmaceutical sterile filtration.
- Cellulose Acetate:Legacy material retains position in low-cost ultrafiltration for food and beverage clarification where chlorine tolerance matters.
The dominant share belongs to Polymeric, while Ceramic is closing the gap fastest.
Separation Technology:
Application requirements for ion rejection versus molecular weight cutoff determine technology selection intensity.
- Reverse Osmosis:Dense polyamide thin-film composites achieve >99% salt rejection for seawater and brackish desalination. Saudi Arabia's Rabigh and Yanbu facilities specify high-pressure spiral-wound modules for municipal water security.
- Nanofiltration:Looser polyamide chemistry enables divalent ion and small organic rejection at lower operating pressures. Germany's Rhine industrial corridor deploys solvent-resistant nanofiltration for pharmaceutical active ingredient concentration.
- Ultrafiltration:Porous polymeric or ceramic membranes separate macromolecules and colloids in dairy processing and biotechnology harvest.
- Microfiltration:Largest pore size category removes bacteria and suspended solids in beverage clarification and wastewater pretreatment.
- Electrodialysis:Ion-exchange membranes under electric potential drive selective ion transport for brine concentration and acid recovery.
Reverse Osmosis commands the largest installed base, though Nanofiltration is expanding most quickly in industrial process streams.
Application:
Regulatory stringency on discharge quality and product purity varies sharply across end-use contexts.
- Water Treatment:Municipal and industrial desalination, softening, and contaminant removal constitute the largest addressable need. EPA maximum contaminant level goals in US municipal systems drive replacement cycles every 5-7 years.
- Pharmaceutical Production:Sterile filtration and solvent recovery demand validated integrity and extractables compliance. India's PLI scheme for active pharmaceutical ingredients is accelerating membrane procurement in Hyderabad and Ahmedabad manufacturing clusters.
- Food & Beverage Processing:Dairy protein concentration, juice clarification, and wine filtration prioritize hygienic design and CIP compatibility.
- Petrochemical Refining:Hydrogen recovery and solvent dehydration in refinery off-gas streams require chemical and thermal resilience.
- Wastewater Management:Zero liquid discharge systems and industrial effluent polishing concentrate hazardous constituents for safe disposal.
Water Treatment retains the dominant position, while Pharmaceutical Production is gaining share fastest on regulatory validation requirements.
End User Industry:
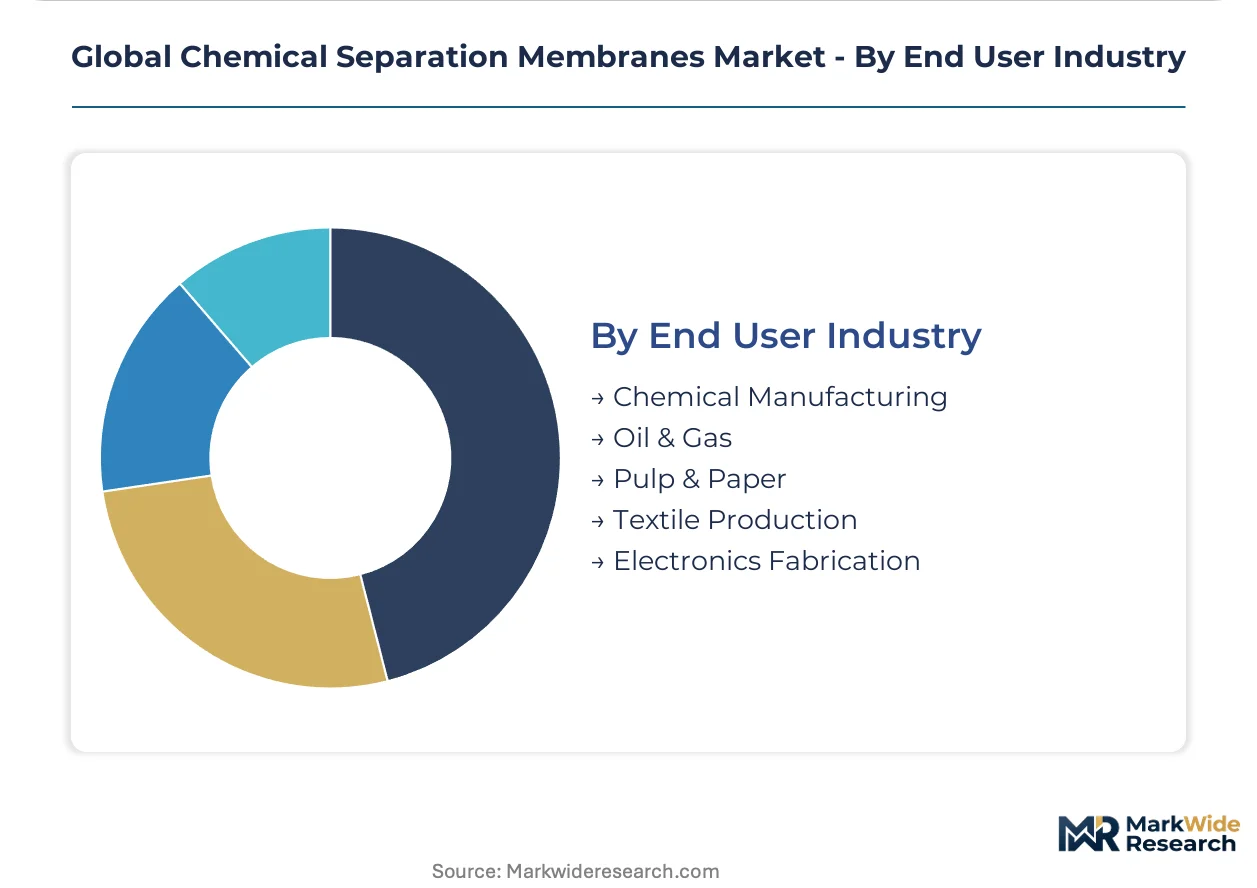
Process intensity and feedstock characteristics determine membrane replacement frequency and performance specifications.
- Chemical Manufacturing:Solvent recovery, catalyst separation, and product purification in batch and continuous processes. Germany's BASF Ludwigshafen complex integrates captive membrane fabrication for polyethersulfone-based modules.
- Oil & Gas:Produced water treatment, gas dehydration, and enhanced oil recovery chemical filtration. Permian Basin operators in Texas deploy ceramic ultrafiltration for frac flowback reuse under state water conservation mandates.
- Electronics Fabrication:Ultrapure water generation and chemical mechanical polishing slurry recovery demand sub-ppb contaminant control.
- Pulp & Paper:White water clarification and lignin recovery from black liquor reduce freshwater intake and effluent load.
- Textile Production:Dye bath recovery and desizing effluent treatment address water scarcity in manufacturing clusters.
Chemical Manufacturing holds the dominant share, while Electronics Fabrication is climbing the fastest on semiconductor capacity expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany's industrial chemical corridor show lowest price elasticity, accepting 40-60% premiums for solvent-resistant modules, while municipal utilities in India and China's inland provinces drive hard on unit costs for standardized polymeric configurations.
United States
EPA maximum contaminant level goals force membrane replacement cycles every 5-7 years in municipal water systems. The Infrastructure Investment and Jobs Act channels federal funding toward brackish water desalination retrofits. Permian Basin operators in Texas deploy ceramic ultrafiltration for frac flowback reuse under state water conservation mandates.
Germany
Rhine industrial corridor demand concentrates in pharmaceutical active ingredient concentration and solvent recovery applications. REACH restrictions on perfluorinated substances eliminate PTFE coating options, forcing reformulation of hydrophobic gas-separation layers. BASF Ludwigshafen complex integrates captive membrane fabrication for polyethersulfone-based modules.
China
MEE discharge standards in Jiangsu and Shandong provinces accelerate ceramic membrane deployment for heavy-metal removal. Dual carbon goals tighten energy-efficiency benchmarks for separation processes in chemical manufacturing. Yangtze River Delta electroplating clusters scale microfiltration systems for zero liquid discharge compliance.
India
PLI scheme for active pharmaceutical ingredients creates membrane demand for solvent recovery and impurity rejection. CDSCO validation requirements extend procurement timelines for sterile filtration modules. Hyderabad and Ahmedabad manufacturing clusters drive bulk drug production capacity expansion.
Saudi Arabia
Seawater desalination dominates membrane procurement for municipal water security. Rabigh and Yanbu facilities specify high-pressure spiral-wound modules. Vision 2030 industrial diversification targets localize membrane fabrication for chemical and petrochemical downstream integration.
Global Chemical Separation Membranes Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated polymer producers commanding feedstock economics and specialized fabricators retaining process expertise. The market structure concentrates margin pools among five to seven multinational chemical groups with captive resin production. Three archetypes dominate: backward-integrated polymer majors, hollow-fiber technology specialists, and ceramic module fabricators with sintering expertise. Competitive moves center on strategic partnerships for MOF coating licensing and geographic expansion into India's pharmaceutical corridor.
Among German and Japanese chemical groups, BASF SE and Toray Industries, Inc. exemplify the backward-integrated archetype through in-house production of polyethersulfone and polyimide feedstocks. DuPont de Nemours, Inc. occupies a position representing hollow-fiber technology leadership for high-pressure gas separation applications. These three anchors demonstrate how feedstock control and configuration specialization create defensible positioning against commoditized spiral-wound competitors.
| Leading Market Players |
|---|
| BASF SE |
| Air Liquide S.A. |
| DuPont de Nemours, Inc. |
| Pall Corporation |
| Linde Plc |
| Toray Industries, Inc. |
| Air Products and Chemicals, Inc. |
| Koch Membrane Systems, Inc. |
| Asahi Kasei Corporation |
| Others |
Supply & Pricing Matrix
REACH substance-of-very-high-concern declarations gate both European membrane supplier qualification and tiered price differentiation, forcing fabricators to absorb 18-24 month certification costs into premium module pricing while standard-grade Asian imports capture cost-sensitive municipal bids.
Pricing Analysis
After-sales service contracts and module replacement scheduling now drive lifetime value capture more than initial equipment sales. Three-tier pricing structure across premium, standard, and economy levels separates solvent-resistant polyimide modules for German pharmaceutical corridors from standardized polyethersulfone configurations for Asian desalination plants. Price differentiation rests on certification grade and captive resin production. Cost compression in economy-tier spiral-wound products is intensifying because Chinese fabricators are scaling phase-inversion capacity. Municipal utilities in India's inland provinces exhibit highest price sensitivity; Rhine industrial chemical buyers accept lowest.
Supply Chain Analysis
Inventory lead times for polyimide and polyethersulfone resins stretch to 16-20 weeks during Japanese and German chemical group maintenance cycles. Geographic supply concentrates in Japan, Germany, and China. Raw material dependencies draw from high-purity monomer feedstocks, ceramic oxide powders, and specialized coating chemistries. Single-source vulnerability in specialty polymer resin supply exposes fabricators to allocation risk. Distribution runs through OEM-direct channels for large industrial contracts and regional distributor networks for municipal water system retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market is cycling through a capital equipment replacement upswing as EPA-mandated membrane replacement intervals converge with EU Green Deal retrofit deadlines.
For Market Incumbents: Secure captive polyethersulfone or polyimide resin supply through backward integration or long-term offtake agreements to defend against Japanese chemical group allocation leverage. Deepen hollow-fiber technology moats in high-pressure gas separation before metal-organic framework coatings scale. Prioritize REACH-SVHC pre-certification investment to compress 18-24 month validation timelines for modified polyamide chemistries. For New Entrants and Emerging Players: Anchor in India's pharmaceutical manufacturing corridor where CDSCO validation requirements create procurement friction that favors agile specialists over legacy incumbents. Target solvent-resistant nanofiltration for active pharmaceutical ingredient recovery as the most penetrable white-space segment. Pursue performance-based supply contracts with municipal water authorities to transfer fouling risk from operator to fabricator. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed ceramic module fabricators possessing sintering expertise but lacking polymer chemistry integration. Five-to-ten year viability hinges on MOF coating licensing positions and geographic exposure to India's PLI scheme expansion. Watch for ceramic membrane adoption inflection in China's electroplating clusters as the signal for heavy-metal removal demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Resins | BASF Ludwigshafen demonstrates how captive polyethersulfone production controls feedstock costs across membrane portfolios. |
| MOF Coating Licensing Partnership | Ruhr industrial cluster pilots validate metal-organic framework precision for hydrogen purification carbon dioxide rejection. |
| Performance-Based Supply Contracting | California and Texas municipal authorities now pay per thousand gallons treated, transferring fouling risk to OEM service arms. |
| REACH-SVHC Pre-Certification Investment | Novel polyamide chemistries face 18-24 month commercialization delays without early ECHA engagement on substance declarations. |
| India Pharmaceutical Corridor Expansion | Hyderabad and Ahmedabad manufacturing clusters under PLI scheme drive solvent recovery membrane procurement acceleration. |
Research Methodology
A standing panel of membrane plant managers, downstream OEM procurement leads, ceramic sintering specialists, and municipal water authority engineers provided ongoing calibration across the study period. Primary interview intelligence combined with secondary validation from customs and trade data, SEC 10-K filings, ECHA REACH registration databases, and MEE discharge standard notifications. Bottom-up module shipment tracking and top-down chemical separation equipment capex analysis were triangulated to ensure consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including membrane material type, separation technology precision, end-use industry process intensity, and regional regulatory cluster stringency. CAGRs were derived from installed base replacement cycles and greenfield capacity expansion pipelines. Forecast inputs incorporated EPA maximum contaminant level enforcement timelines and EU Green Deal energy-efficiency mandate compliance deadlines.
Material uncertainties — regulatory chemistry bans, specialty polymer feedstock allocation disruptions, and metal-organic framework coating scale-up delays — sit outside the modeled envelope. Forecasts reflect documented assumptions about replacement cycle intervals and certification timeline compression. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Industrial Solvent Separation Membranes Market
Membrane Materials
Europe Gas Barrier Membrane Market
Membrane Materials
PVDF Membrane Market
Membrane Materials
Expansion Vessel Membrane Market
Membrane Materials
Global Breathable Membranes Market
Membrane Materials
North America Roofing Membranes Market
Membrane Materials
Fuel Cell Gas Diffusion Layer Market
Membrane Materials
Bitumen Membrane Sheets Market
Membrane Materials
Asia-Pacific, Middle East and Africa Macrofiltration Market
Membrane Materials
Global Track Etched Membrane Market
Membrane Materials
Membrane Touch Switch Material Market
Membrane Materials
Spiral Wound Membrane Market
Membrane Materials
Global Gas Separation Membranes Market
Membrane Materials
Global Medical Membranes Market
Membrane Materials
Global Transfer Membrane Market
Membrane Materials
PTFE Membrane Market