
 Nafion Market | 2026-2036
Nafion Market Size, Share, and Industry Trends Forecast 2026-2036
Nafion Market Outlook
Perfluorinated sulfonic acid membrane chemistry is narrowing the performance gap between laboratory prototypes and mass-manufactured electrolyzer stacks. DuPont de Nemours Inc. leverages its historical fluoropolymer expertise to sustain supply continuity for high-ion-exchange-capacity grades. The Chemours Company anchors North American capacity through integrated precursor production at its Fayetteville Works complex. Solvay SA competes via specialized dispersions for thin-film fuel cell electrodes.
Nafion consists of a perfluorinated backbone with pendant sulfonic acid groups, yielding proton conductivity exceeding 0.1 S/cm at 80°C and 100% relative humidity; manufacturers extrude it into membranes ranging from 25 to 175 micrometers for electrochemical cell separation. Proton exchange membrane applications lead volume absorption due to stationary and mobility electrolyzer deployment, while fuel cell membrane segments carry premium pricing tied to automotive qualification protocols. Coating formulations for sensor electrodes represent a concentrated margin pool given batch specificity and technical service requirements.
The U.S. Environmental Protection Agency regulates perfluorinated compound emissions under TSCA Section 5, while the EU REACH framework restricts long-chain perfluorinated substance manufacture, compelling reformulation investments. Japan's METI hydrogen roadmap and South Korea's MFDS chemical safety standards further segment product qualification requirements across export destinations. Stakeholders must monitor regulatory thresholds for perfluorooctanoic acid residuals and assess captive precursor strategies before capacity commitments crystallize.
Market Dynamics
Proton exchange membrane chemistry standardization is compressing qualification timelines for electrolyzer stack integrators while perfluorinated precursor supply concentration in North America creates procurement bottlenecks for Asian membrane fabricators.
Growth Catalysts
- Production Tax Credits:The U.S. Inflation Reduction Act's clean hydrogen production incentives are accelerating domestic electrolyzer manufacturing commitments and pulling forward membrane offtake agreements from project developers.
- Germany's Hydrogen Corridor:Industrial offtake clusters in the Rhine-Ruhr and Hamburg regions are anchoring demand for high-durability membrane grades in heavy transport and steel decarbonization applications.
- Thin-Film Electrode Coating:Catalyst layer deposition techniques requiring specialized Nafion dispersions are expanding addressable content per fuel cell stack as automotive OEMs pursue power density targets.
Market Restraints
- Fluoropolymer Feedstock Concentration:Tetrafluoroethylene precursor supply is captive to three integrated chemical complexes globally, exposing membrane producers to force majeure risks and allocation protocols.
- EU REACH Restrictions:Long-chain perfluorinated substance manufacturing limitations under ECHA authorization requirements are compelling reformulation investments and alternative chemistry evaluations.
- Membrane Thickness Trade-offs:Sub-50 micrometer films reduce ohmic losses but exhibit accelerated mechanical degradation in high-pressure differential electrolyzer operation, constraining design flexibility.
Strategic Opportunities
- Anion Exchange Membrane Convergence:Hybrid system architectures combining proton and hydroxide-conducting membranes in bipolar electrolyzer configurations are opening qualification pathways for modified sulfonic acid chemistries.
- Japan's METI Roadmap:The national hydrogen supply chain targets are creating dedicated procurement frameworks for imported membrane materials in ammonia cracking and power-to-gas installations.
- Sensor Electrode Formulations:Batch-specific coating services for electrochemical detection devices command technical service premiums and long-term supply agreements with industrial instrument manufacturers.
Industry Challenges
- Fluoropolymer Process Engineering Talent:Specialized expertise in perfluorinated ionomer extrusion and dispersion stabilization is concentrated among retiring cohorts at legacy chemical producers, constraining capacity expansion timelines.
- Automotive Qualification Cycles:Fuel cell membrane validation protocols spanning 10,000+ hour durability testing and thermal cycling regimes extend time-to-revenue for new grade introductions by 24-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nafion Market |
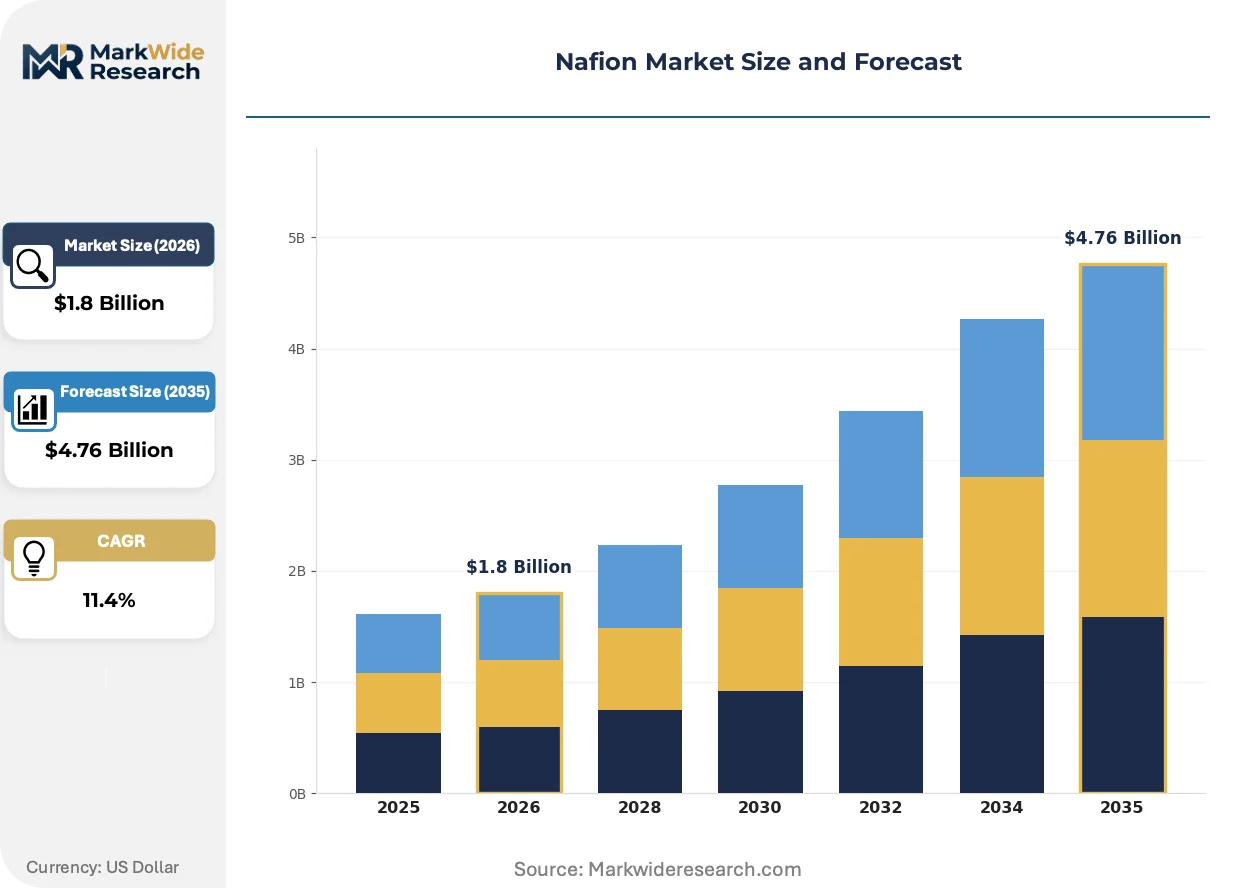
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proton Exchange Membrane, Fuel Cell, Coating, Additive Application: Fuel Cells, Electrolyzers, Water Treatment, Sensors End User: Automotive, Energy, Electronics, Utilities Distribution Channel: Online, Distributors, Direct Sales, Retail |
| Companies Covered | Solvay SA, Asahi Kasei Corp., DuPont de Nemours Inc., FUJIFILM Holdings Corp., Dongyue Group Ltd., The Chemours Company, 3M Company, Halma Plc, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nafion Market Strategic Shifts
Membrane manufacturing is bifurcating between commodity electrolyzer supply and precision fuel cell grades, with dispersion formulation expertise emerging as the decisive capability differentiator. Chemistry optimization now targets simultaneous conductivity and mechanical resilience improvements.
Reinforced composite membrane architectures incorporating porous polytetrafluoroethylene substrates are migrating from laboratory validation to production stack qualification at European electrolyzer OEMs. The migration is compressing pure homogeneous film market share in stationary hydrogen production while enabling thinner active layers and reduced precious metal catalyst loading. Stack integrators in Germany and the Netherlands are specifying these architectures for pressurized alkaline-PEM hybrid systems.
REACH authorization requirements for perfluorooctanoic acid residuals are tightening emission thresholds and batch testing protocols for membrane imports into the European Union. ECHA's restriction proposals are forcing precursor suppliers to accelerate C6 chemistry transitions and submit comprehensive substitution plans. Korean and Japanese membrane fabricators are establishing dedicated EU-compliant production lines to preserve market access.
Electrolyzer procurement is consolidating around long-term offtake contracts with integrated project developers rather than spot membrane purchases. Engineering firms are embedding membrane supply directly into electrolyzer system EPC agreements, compressing independent distributor margins. This pattern is most pronounced in Australian and Middle Eastern green hydrogen export projects where financing requirements demand supply chain certainty.
Nafion Market Segmentation
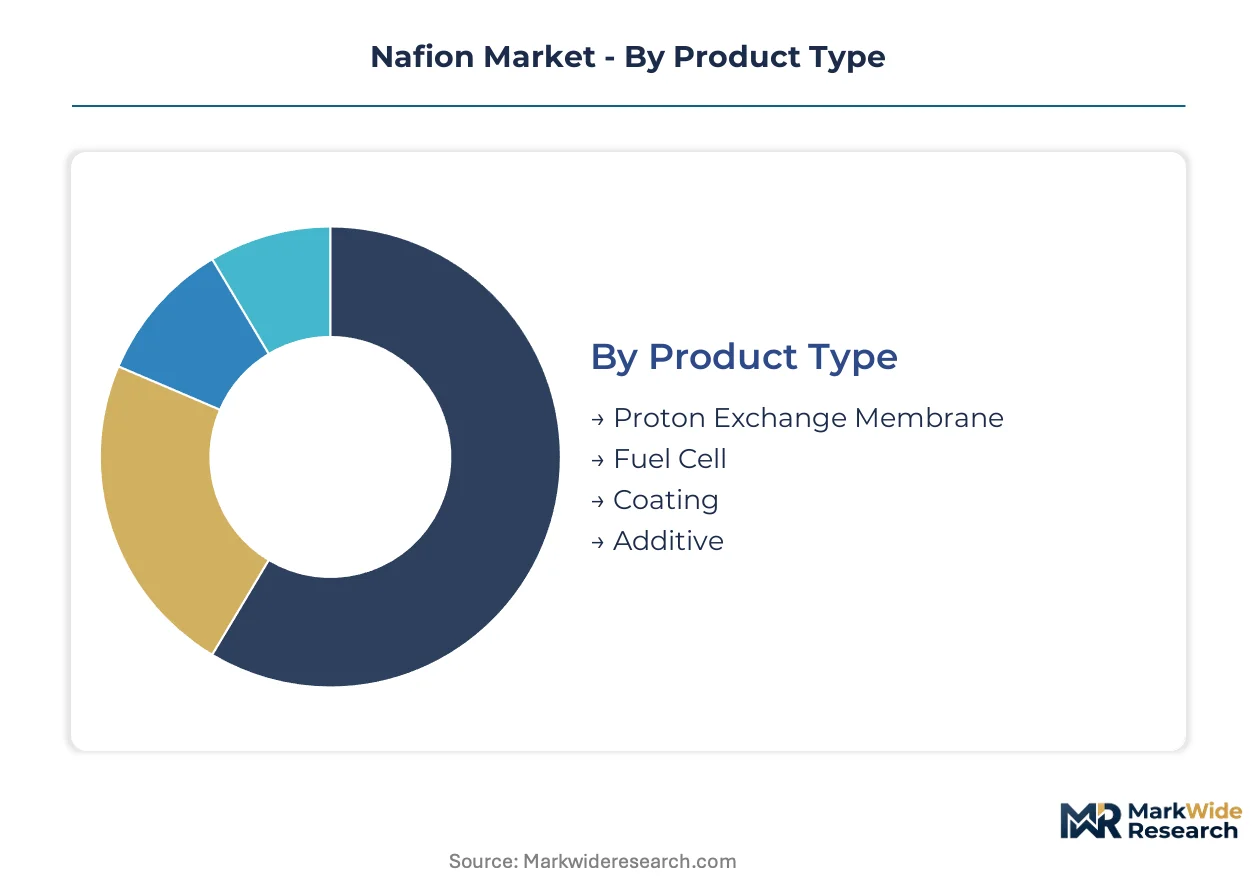
Nafion market segmentation reveals distinct performance tiers across product grades and end-use specifications. Membrane thickness, ion exchange capacity, and dispersion formulation drive pricing stratification. Application requirements in hydrogen infrastructure and automotive qualification protocols create divergent commercial pathways.
Product Type:
Mature electrolyzer membrane grades coexist with emerging thin-film fuel cell formulations, reflecting divergent qualification timelines and margin structures.
- Proton Exchange Membrane:Extruded films from 25 to 175 micrometers deliver proton conductivity exceeding 0.1 S/cm at 80°C and full humidity. Stationary electrolyzer deployment in Germany's industrial hydrogen corridor absorbs high-tonnage volumes under long-term offtake contracts.
- Fuel Cell:Precision grades undergo 10,000+ hour durability testing and thermal cycling validation per automotive OEM protocols. Japanese and Korean membrane fabricators are establishing EU-compliant production lines to preserve market access under tightening ECHA authorization requirements.
- Coating:Specialized dispersions for catalyst layer deposition command technical service premiums.
- Additive:Compounding applications for electrochemical device manufacturing.
Proton Exchange Membrane retains volume leadership; Fuel Cell holds the steepest expansion curve.
Application:
Cost tier differentiation separates commodity hydrogen production from premium automotive qualification pathways.
- Fuel Cells:Heavy transport and passenger vehicle integration requires sub-50 micrometer films with reinforced composite architectures. The U.S. Inflation Reduction Act production tax credits are accelerating domestic electrolyzer manufacturing commitments and pulling forward membrane offtake agreements.
- Electrolyzers:Pressurized alkaline-PEM hybrid systems in the Netherlands and Germany specify polytetrafluoroethylene-reinforced membranes. DuPont de Nemours Inc. and The Chemours Company anchor North American precursor supply through integrated fluoropolymer complexes.
- Water Treatment:Ion exchange applications for industrial purification systems.
- Sensors:Batch-specific electrode formulations for electrochemical detection devices.
Electrolyzers dominate current procurement volumes; Fuel Cells is expanding most quickly as automotive qualification timelines compress.
End User:
Customer type concentration clusters around integrated project developers versus spot purchasers in fragmented industrial segments.
- Automotive:OEM power density targets drive catalyst loading reduction and thinner active layer specifications. South Korea's MFDS chemical safety standards and Japan's METI hydrogen roadmap segment product qualification requirements across export destinations.
- Energy:Green hydrogen export projects in Australia and the Middle East embed membrane supply directly into EPC agreements, compressing independent distributor margins.
- Electronics:Instrument manufacturers for electrochemical detection devices.
- Utilities:Power-to-gas and grid-scale storage installations.
Energy sector procurement leads absolute volume; Automotive commands the highest unit economics.
Distribution Channel:
Supply concentration dynamics favor direct relationships with integrated manufacturers over fragmented intermediaries.
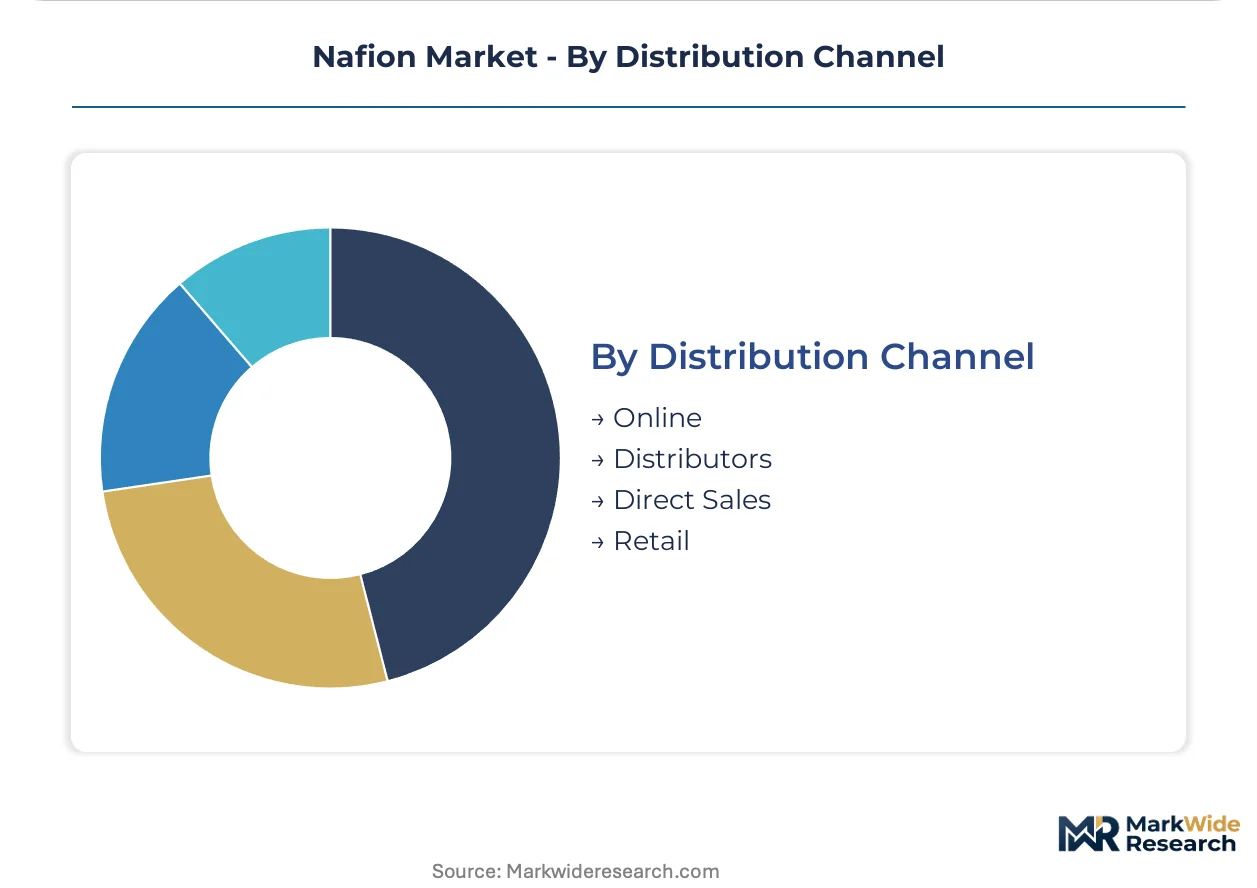
- Direct Sales:Long-term offtake contracts with electrolyzer stack integrators and fuel cell system developers. Engineering firms specify membrane supply within system EPC agreements to satisfy project financing requirements.
- Distributors:Regional stocking for maintenance, repair, and operations in water treatment and sensor applications.
- Online:Technical documentation and sample procurement for research institutions.
- Retail:Small-volume dispersion and specialty formulation sales.
Direct Sales captures the dominant procurement mode; Distributors retains relevance in aftermarket and technical service segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated project developers in Germany, the United States, Japan, and South Korea dominate membrane procurement through long-term offtake contracts. These buyers embed supply certainty into electrolyzer EPC agreements to satisfy green hydrogen project financing requirements.
United States
The Inflation Reduction Act's clean hydrogen production tax credits are pulling forward domestic electrolyzer manufacturing commitments. EPA regulations under TSCA Section 5 govern perfluorinated compound emissions and batch testing protocols. The Gulf Coast chemical corridor anchors integrated fluoropolymer precursor production at captive manufacturing complexes.
Germany
Industrial hydrogen offtake clusters in the Rhine-Ruhr and Hamburg regions absorb high-durability membrane grades for steel decarbonization and heavy transport applications. ECHA REACH restrictions on long-chain perfluorinated substances compel reformulation investments and C6 chemistry transitions. Dutch and German stack integrators specify polytetrafluoroethylene-reinforced membranes for pressurized alkaline-PEM hybrid systems.
Japan
METI's national hydrogen supply chain targets create dedicated procurement frameworks for imported membrane materials in ammonia cracking and power-to-gas installations. MFDS chemical safety standards segment product qualification requirements for export-bound fabricators. Osaka-based membrane specialists are establishing EU-compliant production lines to preserve market access under tightening ECHA authorization thresholds.
South Korea
Automotive OEM power density targets drive demand for sub-50 micrometer films with reinforced composite architectures. MFDS regulations align with Japanese METI standards to create dual qualification requirements for regional exporters. Seoul-area fabricators are investing in dedicated European-compliant production capacity to circumvent REACH authorization bottlenecks.
China
Domestic electrolyzer deployment for industrial hydrogen production absorbs commodity-grade membrane volumes under state-backed green hydrogen initiatives. MIIT standards and GB technical regulations govern fluoropolymer manufacturing emissions and product certification. Shandong Peninsula chemical complexes are expanding captive tetrafluoroethylene precursor capacity to reduce import dependency.
Nafion Market Competitive Environment
Channel-controlling players compete with product-specialist players across three structural tiers. Integrated chemical conglomerates with captive fluoropolymer precursor supply anchor the upper tier through backward integration into tetrafluoroethylene production. Mid-scale membrane fabricators occupy a middle tier focused on dispersion formulation expertise and thin-film electrode coatings. Regional distributors and technical service providers populate a fragmented lower tier serving aftermarket and research sample demand. Dominant competitive moves include capacity expansion at integrated precursor complexes and strategic partnerships between membrane fabricators and electrolyzer stack integrators.
Among North American integrated producers, DuPont de Nemours Inc. and The Chemours Company exemplify the captive-precursor archetype through historical fluoropolymer expertise and integrated manufacturing complexes. Solvay SA represents the European specialist tier with focused positioning in dispersion formulations for thin-film fuel cell electrodes. These three anchors demonstrate how geographic concentration of tetrafluoroethylene supply shapes competitive positioning across membrane fabrication tiers.
| Leading Market Players |
|---|
| Solvay SA |
| Asahi Kasei Corp. |
| DuPont de Nemours Inc. |
| FUJIFILM Holdings Corp. |
| Dongyue Group Ltd. |
| The Chemours Company |
| 3M Company |
| Halma Plc |
| BASF SE |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on tetrafluoroethylene precursor supply determines both pricing tier spreads and supply chain shape, compressing margins for membrane fabricators without captive fluoropolymer production while amplifying cost pass-through power for integrated North American producers.
Pricing Analysis
Cost-plus contracts with fluorspar indexation dominate long-term offtake agreements between electrolyzer stack integrators and membrane suppliers. Price differentiation rests on ion exchange capacity certification and automotive qualification tier, with fuel cell grades commanding substantial premiums over commodity electrolyzer volumes. Pricing pressure stems from REACH-driven reformulation investments as C6 chemistry transitions absorb R&D budgets. Project developers in green hydrogen export markets exhibit lowest price sensitivity due to embedded EPC financing structures, while sensor electrode coating buyers negotiate aggressively on batch-specific technical service fees.
Supply Chain Analysis
Contract manufacturing concentration sits with DuPont de Nemours Inc., The Chemours Company, and Solvay SA holding integrated precursor-to-membrane capacity. Geographic supply concentration centers on the United States, Belgium, and Japan for perfluorinated ionomer production. Raw material dependencies include fluorspar mining concentrates, sulfuric acid for sulfonation, and high-purity tetrafluoroethylene monomer. Single-source vulnerability pervades the tetrafluoroethylene feedstock tier with only three global manufacturing complexes. Distribution runs through direct sales to electrolyzer OEMs and fuel cell system developers, compressing independent distributor roles to aftermarket and research sample segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity pervades this market as automotive qualification timelines bifurcate procurement patterns between commodity electrolyzer supply and precision fuel cell grades, creating distinct competitive arenas for specialized versus integrated players.
For Market Incumbents: Entrench captive precursor advantages through capacity expansion at Fayetteville Works and similar integrated complexes while accelerating C6 chemistry transitions to preempt REACH authorization bottlenecks. Defend against anion exchange membrane substitution threats by embedding modified sulfonic acid chemistries into hybrid electrolyzer architectures. Prioritize dispersion formulation expertise as the decisive capability differentiator as thin-film electrode coatings expand addressable content per stack. For New Entrants and Emerging Players: Pursue white-space opportunities in EU-compliant production lines for Korean and Japanese fabricators seeking to circumvent ECHA authorization thresholds. Target sensor electrode coating services where batch specificity and technical service requirements sustain technical service premiums and long-term supply agreements. Exploit fluoropolymer process engineering talent scarcity by recruiting retiring cohorts at legacy chemical producers to compress qualification timelines for new grade introductions. For Investors and Strategic Acquirers: The market sits at a capacity-constrained phase that favors backward-integrated producers with captive tetrafluoroethylene supply over pure-play membrane fabricators. Long-term viability over the next decade hinges on regulatory compliance infrastructure and automotive qualification track records. Acquisition targets should demonstrate established EU REACH compliance and active METI or MFDS qualification pathways. Watch for inflection signals in anion exchange membrane adoption rates and C6 chemistry substitution progress as indicators of competitive displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captive tetrafluoroethylene production at Fayetteville Works insulates DuPont and Chemours from allocation risks. |
| EU-Compliant Production Line Establishment | Osaka-based fabricators preserve market access under tightening ECHA authorization thresholds for PFOA residuals. |
| Long-term Offtake Contract Structuring | Australian and Middle Eastern green hydrogen projects embed membrane supply into EPC agreements for financing certainty. |
| Reinforced Composite Membrane Qualification | Dutch and German stack integrators specify PTFE-reinforced architectures for pressurized alkaline-PEM hybrid systems. |
| Dispersion Formulation Capability Buildout | Specialized Nafion dispersions for thin-film fuel cell electrodes command technical service premiums from automotive OEMs. |
Study Parameters
A spread of perspectives from electrolyzer stack integrators, fluoropolymer plant managers, automotive fuel cell procurement leads, and EPC contractors converged on the working assumptions underlying this analysis. Primary interviews with membrane fabrication technical directors and regulatory affairs specialists at REACH compliance consultancies combined with secondary validation from SEC 10-K filings, ECHA authorization databases, and METI hydrogen roadmap disclosures. Customs data on perfluorinated compound trade flows and IEA hydrogen project tracking databases anchored volume estimates. Bottom-up electrolyzer deployment forecasts and top-down membrane content-per-stack calculations were triangulated against manufacturer capacity disclosures.
Demand-supply-balance framing structured the analytical approach across the projection horizon, modeling proton exchange membrane grades, fuel cell qualification tiers, coating dispersion formulations, and additive compounding applications as segmentation dimensions. CAGRs were derived from electrolyzer manufacturing commitments under the U.S. Inflation Reduction Act and Germany's hydrogen corridor offtake clusters, cross-referenced against automotive OEM power density targets and precious metal catalyst loading reduction trajectories. Forecast inputs incorporated EPC contract embedding patterns and REACH-driven reformulation investment timelines.
Macroeconomic conditions sit as an overlay; deviation in green hydrogen project financing costs, fluorspar commodity prices, or automotive fuel cell platform deployment schedules would shift the trajectory. Forecasts reflect documented assumptions on electrolyzer deployment rates, regulatory authorization timelines, and precursor capacity expansion plans. Quarterly review of ECHA restriction proposal progress, METI ammonia cracking procurement awards, and automotive OEM fuel cell stack qualification completions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Nanoporous Membranes Market
Membrane Materials
Global Transfer Membrane Market
Membrane Materials
Membrane Polymers Market
Membrane Materials
PVDF Membrane Market
Membrane Materials
Membrane Chemicals Market
Membrane Materials
Global Gas Separation Membranes Market
Membrane Materials
Global Membrane Technology Market
Membrane Materials
Global Track Etched Membrane Market
Membrane Materials
Membrane Separation Materials Market
Membrane Materials
Nanofiltration Membrane Market
Membrane Materials
Membranes Market
Membrane Materials
Global Ultrafiltration Market
Membrane Materials
Self-Adhered Roofing Membranes Market
Membrane Materials
Global Spiral Membrane Market
Membrane Materials
Ultrafiltration Membrane Market
Membrane Materials
Liquid Roofing Market