
 Global Breathable Membranes Market | 2026-2036
Global Breathable Membranes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Breathable Membranes Market Foresight
The capital-intensity divergence between integrated polymer producers and membrane converters is unwinding competitive stability in the sector. DuPont de Nemours, Inc. leverages its fluoropolymer heritage to dominate expanded polytetrafluoroethylene supply chains. BASF SE anchors its position through polyurethane chemistry leadership and backward integration into specialty polyols. Soprema Group differentiates via roofing-system bundling that captures specification authority with architects and contractors.
Breathable membranes are thin, engineered films that permit water vapor transmission while blocking liquid water and air infiltration, typically achieving permeance ratings of 1–30 perms depending on pore structure or monolithic chemistry. Their primary commercial purpose is to prevent condensation damage within building assemblies and to manage moisture in protective textiles. Microporous polypropylene dominates roofing applications where cost sensitivity and code compliance intersect, while monolithic polyurethane captures premium sportswear and medical textile volumes where stretch recovery and wash durability command margin premiums. Hybrid constructions are gaining specification share in automotive interiors as OEMs consolidate material counts under sustainability targets.
REACH registration requirements in Europe, EPA emissions guidelines in the United States, and China's GB standards for building materials collectively shape formulation choices and market access conditions for membrane suppliers. ECHA restrictions on per- and polyfluoroalkyl substances are forcing fluoropolymer producers to accelerate transition chemistries ahead of sunset dates. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and to align R&D pipelines with the most restrictive compliance horizon emerging across multiple geographies.
Market Dynamics
REACH restrictions on per- and polyfluoroalkyl substances are compressing formulation options for fluoropolymer membranes while simultaneously elevating polyurethane and bio-based alternatives across European construction and textile supply chains.
Growth Catalysts
- EU Green Deal energy-efficiency mandates:Germany's building renovation wave drives specification of high-perm membranes in retrofit envelopes, tightening vapor-control requirements for existing housing stock.
- China's dual carbon goals:GB standards for green building materials accelerate substitution of conventional vapor barriers with breathable alternatives in provincial construction codes.
- Microporous polypropylene cost-performance:Roofing contractors specify this material for code-compliant underlayment where cost sensitivity intersects with moisture-management performance thresholds.
Market Restraints
- Specialty polyol supply concentration:BASF and Covestro control upstream polyurethane precursors, exposing membrane converters to input cost volatility and allocation constraints during supply shocks.
- ECHA PFAS sunset timelines:Fluoropolymer producers face stranded inventory risk as registration restrictions advance, forcing premature write-downs of ePTFE production assets.
- Monolithic film thickness limitations:Polyurethane membranes below 20 microns suffer puncture susceptibility in rough-handling construction environments, constraining application range.
Strategic Opportunities
- India's affordable housing pipeline:PLI scheme incentives for construction materials create entry pathways for cost-optimized microporous membranes in mass residential projects.
- Automotive interior consolidation:OEM sustainability targets drive hybrid membrane adoption for seat ventilation and headliner applications, replacing multi-material stacks with single-film solutions.
- US IRA efficiency tax credits:Residential retrofit subsidies elevate specification authority for high-performance building envelope components in climate zones 4-8.
Industry Challenges
- Polymer science talent scarcity:Formulation chemists with monolithic film extrusion expertise command premium compensation, constraining R&D velocity at mid-scale converters.
- Multi-jurisdiction certification timelines:Simultaneous EPA emissions compliance, REACH registration, and GB standard testing extends product launch cycles by 18-24 months.
- Legacy vapor barrier replacement friction:Contractor training requirements and building inspector education slow substitution rates in established construction markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Breathable Membranes Market |
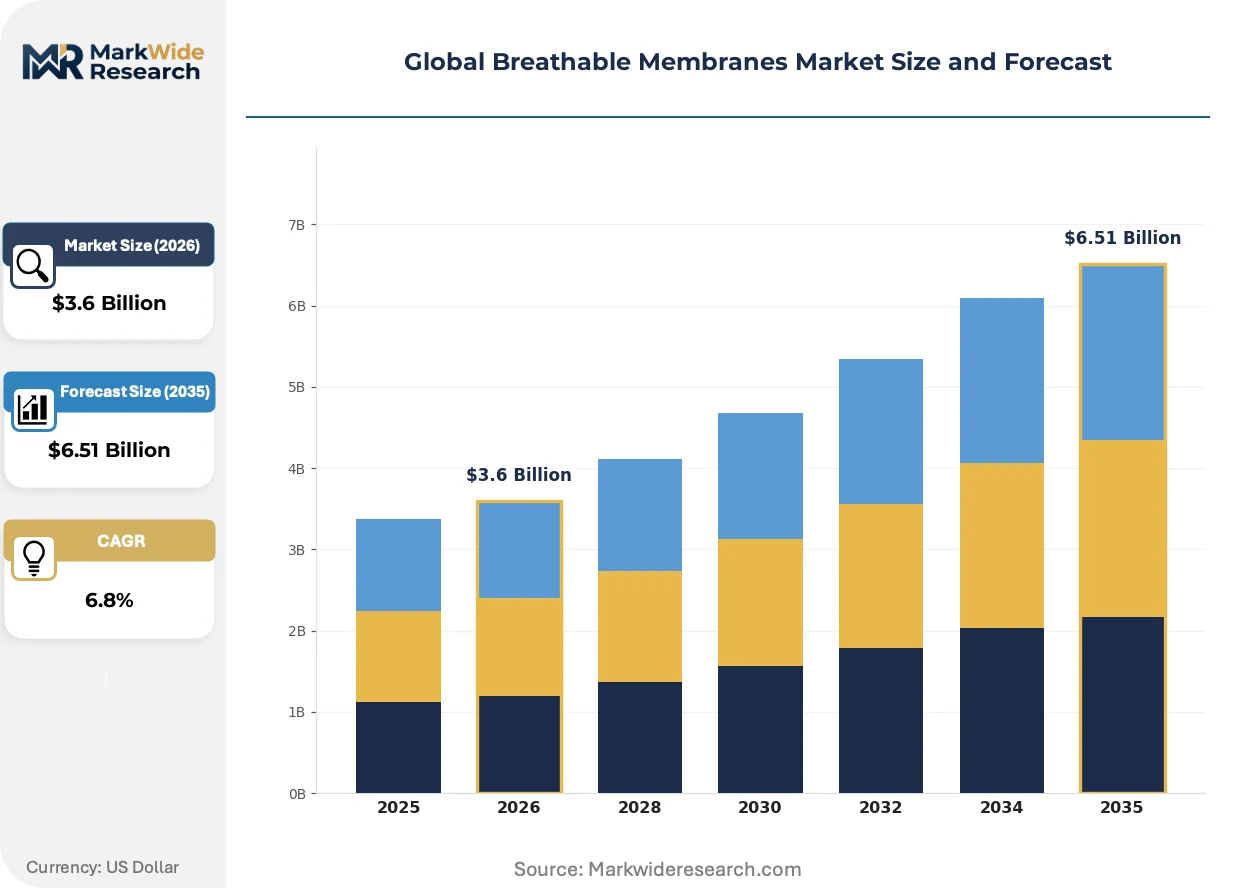
| Market Size in 2026 | $3.6 Billion |
| Market Size in 2035 | $6.51 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Membrane Type: Microporous, Monolithic, Expanded Polytetrafluoroethylene, Hybrid, Composite End Use Industry: Construction, Protective Apparel, Packaging, Agriculture, Electronics Application: Roofing, Footwear, Medical Textiles, Automotive Interiors, Sportswear Material Composition: Polypropylene, Polyurethane, Polyester, Polytetrafluoroethylene, Nylon |
| Companies Covered | DuPont de Nemours, Inc., Compagnie de Saint-Gobain S.A., Kingspan Group PLC, BASF SE, Soprema Group, GAF Materials Corporation, Mitsui Chemicals, Inc., Arkema S.A., Sika AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Breathable Membranes Market Shifts & Advancements
Active chemistry transitions, specification authority migration, and procurement model compression are restructuring competitive advantage in membrane supply chains. Incumbents must navigate simultaneous material substitution and channel consolidation pressures.
Monolithic thermoplastic polyurethane films with hydrophilic segment chemistry are miniaturizing active-layer thicknesses below 15 microns while maintaining MVTR performance above 15,000 g/m²/24hr. Sportswear brands at Arc'teryx and Patagonia specification desks accelerate adoption for stretch-woven garments. This thickness compression enables fabric designers to eliminate separate liner fabrics, collapsing bill-of-materials complexity in premium outerwear categories.
ECHA's proposed PFAS restriction under REACH Annex XVII is forcing fluoropolymer membrane producers to validate transition chemistries against 2027 sunset horizons. Industrial consequence includes accelerated R&D allocation toward silicone-modified polyurethanes and bio-based polyesters. Medical textile suppliers in Switzerland and Germany face the most acute compliance pressure, with Swissmedic and BfArM device filings requiring material traceability documentation.
Building envelope specification authority is migrating from general contractors to architect-led design-build consortia, compressing traditional distribution tiers. Distributors in the US Northeast and Pacific Northwest consolidate membrane portfolios around three-supplier maximums, displacing fragmented regional converter networks. This concentration is most visible in multifamily residential projects above 100 units, where repeat-builder procurement templates lock out non-preferred membrane brands.
Global Breathable Membranes Market Segmentation
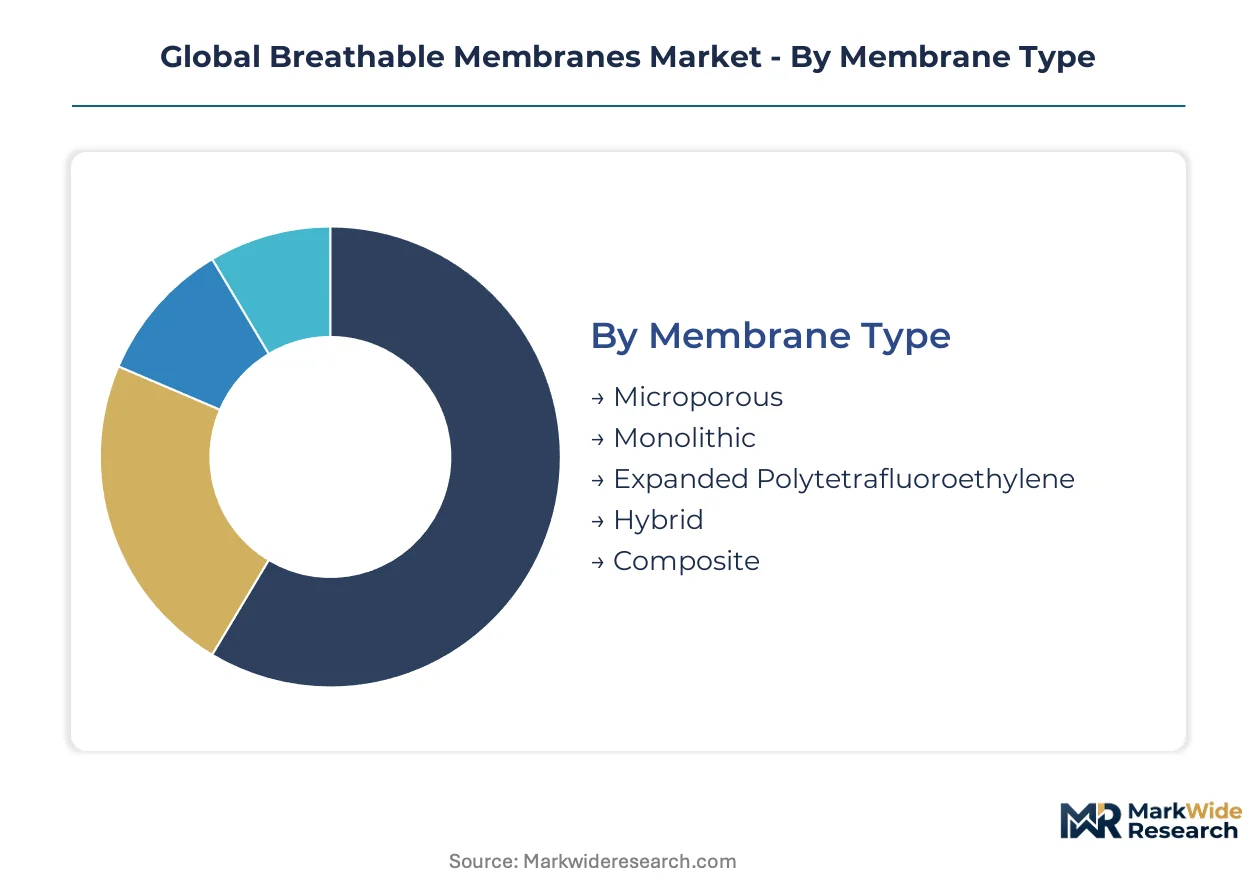
Membrane type determines which specification channels dominate procurement. Material composition locks converters into specific polymer supply chains with divergent regulatory exposure. End-use industry and application together dictate performance thresholds and certification requirements.
Membrane Type:
Microporous membranes flow through roofing distributor networks, while monolithic films reach sportswear brands via textile converters. ePTFE channels through medical device suppliers facing Swissmedic traceability mandates. Hybrid constructions consolidate automotive tier-1 procurement.
- Microporous:Polypropylene-based films with interconnected pore structures achieve 5–30 perms for roofing underlayment. Demand concentrates in Germany's building renovation wave where contractors prioritize code-compliant cost performance. ECHA PFAS restrictions accelerate substitution away from fluorinated alternatives.
- Monolithic:Hydrophilic polyurethane segments enable vapor transport without pores, delivering wash durability above 50 cycles for premium sportswear. Arc'teryx and Patagonia specification desks drive adoption as thickness compression below 15 microns eliminates liner fabrics. China's GB standards for green building materials are expanding construction applications.
- Expanded Polytetrafluoroethylene:Biaxially stretched fluoropolymer structures face stranded inventory risk from REACH Annex XVII sunset timelines. Medical textile suppliers in Switzerland and Germany confront acute compliance pressure.
- Hybrid:Laminated constructions combining microporous and monolithic layers serve automotive interior consolidation. OEM sustainability targets drive single-film replacement of multi-material stacks.
- Composite:Reinforced membranes with nonwoven backings address puncture susceptibility in rough-handling construction environments.
By volume, microporous leads. By growth pace, monolithic is ahead.
End Use Industry:
Construction absorbs the majority of membrane tonnage through building envelope specifications. Protective apparel commands margin premiums through performance certification tiers. Packaging, agriculture, and electronics represent emerging volume pools with distinct technical requirements.
- Construction:Building envelope applications for moisture management in walls and roofs. Germany, China, and the United States concentrate demand as energy-efficient codes spread. US IRA efficiency tax credits elevate specification authority in climate zones 4-8.
- Protective Apparel:Firefighter gear and industrial protective clothing requiring breathable barrier protection. Certification to NFPA 1971 and EN 469 drives material selection toward aramid-laminated constructions.
- Packaging:Modified atmosphere packaging for fresh produce extending shelf life through selective permeability.
- Agriculture:Greenhouse films and crop protection textiles balancing light transmission with humidity control.
- Electronics:Device protection membranes for smartphones and wearables requiring IP-rated ingress protection.
Construction dominates absolute volume. Protective apparel delivers the steepest margin expansion.
Application:
Roofing contractors specify through distributor networks with three-supplier maximum consolidation. Medical textiles require FDA, EMA, and Swissmedic device filings extending launch cycles. Sportswear brands exercise direct specification authority collapsing traditional converter tiers.
- Roofing:Underlayment and wall wrap applications in residential and commercial construction. India's PLI scheme for affordable housing creates entry pathways for cost-optimized microporous membranes in mass residential projects.
- Footwear:Waterproof-breathable bootie constructions for hiking and work boots. Thickness constraints below 0.3mm govern laminate design.
- Medical Textiles:Surgical gowns and sterile barrier packaging requiring biocompatibility certification. ECHA PFAS restrictions force accelerated transition chemistries ahead of 2027 horizons.
- Automotive Interiors:Seat ventilation and headliner applications consolidating material counts. OEM sustainability targets drive hybrid membrane adoption replacing multi-material stacks.
- Sportswear:Stretch-woven garments for alpine and endurance applications. Monolithic polyurethane miniaturization below 15 microns enables fabric designers to eliminate separate liner fabrics.
Roofing anchors volume share. Sportswear is expanding most quickly.
Material Composition:
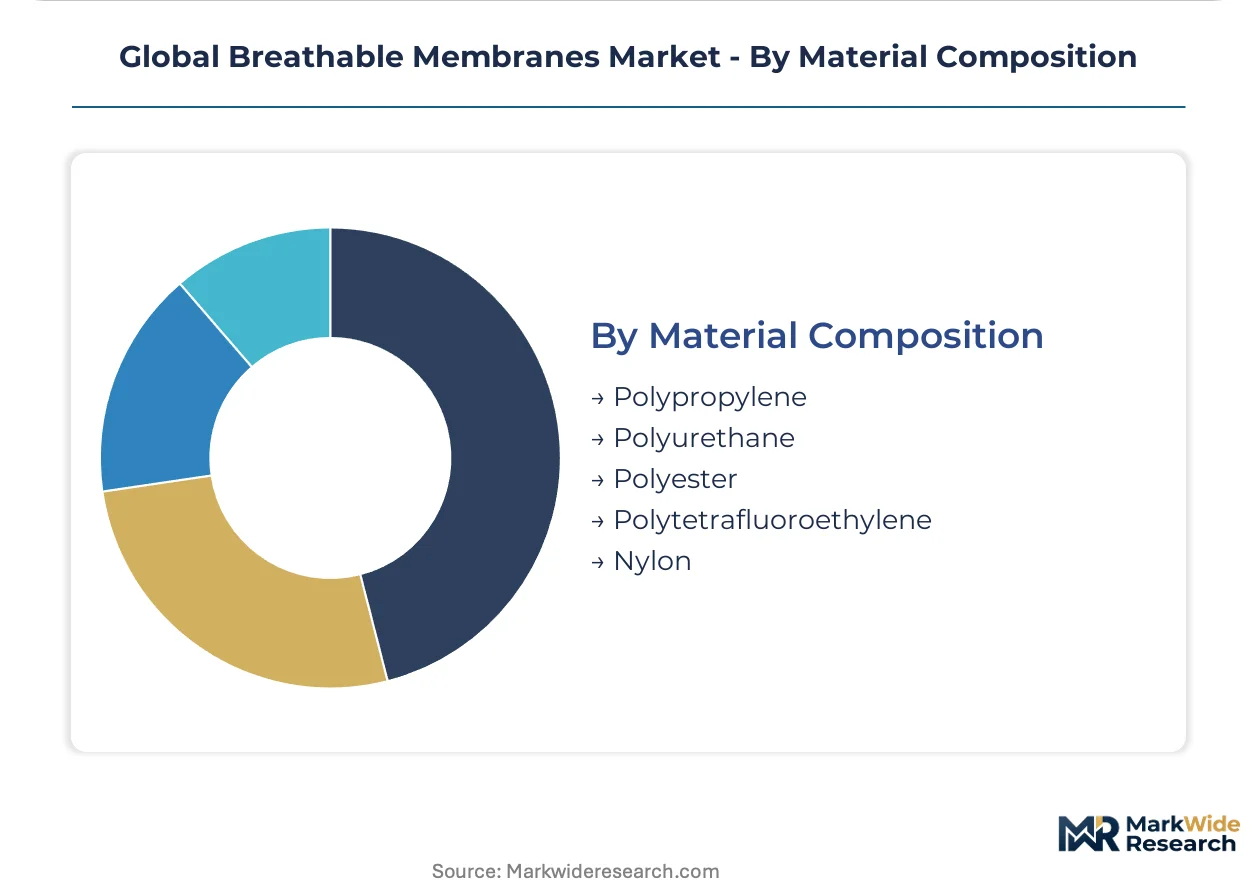
Polypropylene leverages cost-positioning in roofing codes. Polyurethane captures premium textile margins through chemistry differentiation. Polyester, PTFE, and nylon occupy specialized niches with concentrated supply chains.
- Polypropylene:Cost-optimized microporous films dominating roofing underlayment. China's dual carbon goals accelerate substitution of conventional vapor barriers in provincial construction codes.
- Polyurethane:Monolithic and thermoplastic variants commanding premium sportswear and medical textile volumes. BASF and Covestro control upstream specialty polyol supply exposing converters to allocation constraints.
- Polyester:Bio-based variants gaining specification share as ECHA restrictions compress fluoropolymer options.
- Polytetrafluoroethylene:Fluoropolymer heritage producers face stranded asset risk from REACH sunset timelines. DuPont de Nemours leverages ePTFE supply chain dominance while accelerating transition chemistry R&D.
- Nylon:High-tensile applications in protective apparel and industrial textiles requiring abrasion resistance.
Polypropylene leads by installed volume. Polyurethane is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys breathable membranes primarily for building envelope retrofits, while China absorbs volume through new construction codes and the United States concentrates demand in climate-resilient roofing upgrades.
Germany
Building renovation wave specifications drive high-perm membrane uptake in existing housing stock. EU Green Deal energy-efficiency mandates tighten vapor-control requirements through the national building code. Industrial clusters in North Rhine-Westphalia concentrate converter capacity serving Benelux export markets.
China
Provincial construction codes accelerate substitution of conventional vapor barriers in residential and commercial projects. GB standards for green building materials align with dual carbon goals to filter material procurement. Yangtze River Delta manufacturers scale microporous polypropylene output for domestic roofing underlayment demand.
United States
IRA efficiency tax credits elevate specification authority for building envelope components in climate zones 4-8. EPA emissions guidelines shape formulation choices for membrane suppliers seeking market access. Pacific Northwest distributor consolidation around three-supplier maximums locks out fragmented regional converter networks.
India
PLI scheme incentives for construction materials create entry pathways for cost-optimized microporous membranes in mass residential projects. BIS certification requirements extend product launch timelines for imported membrane technologies. Maharashtra and Gujarat industrial corridors attract membrane converter investments targeting affordable housing pipelines.
Switzerland
Medical textile suppliers face acute compliance pressure from Swissmedic device filings requiring material traceability documentation. ECHA PFAS restrictions force accelerated transition chemistries ahead of 2027 horizons. Basel-area polymer science clusters concentrate R&D allocation toward silicone-modified polyurethane alternatives.
Global Breathable Membranes Market Competitive Landscape
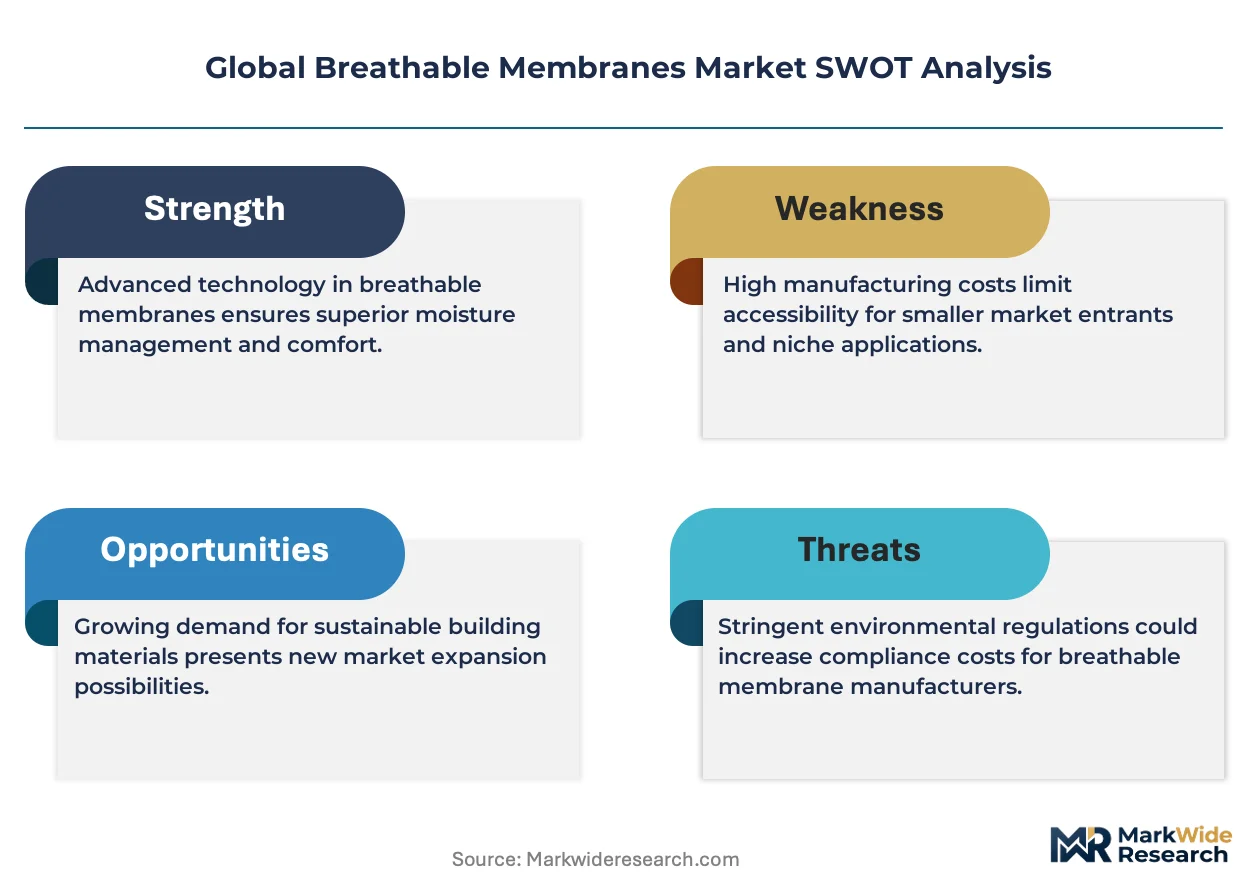
A small set of integrated leaders sits above a broader specialist tier, creating asymmetric competition around raw material access and specification authority. Polymer producers with captive specialty polyol supply anchor the upper tier, while membrane converters without upstream integration occupy dependent positions. Two strategic archetypes dominate: chemistry-integrated multinationals leveraging backward integration into polymer precursors, and roofing-system bundlers capturing architect specification authority through envelope solution packaging. Capacity expansion in Asian manufacturing hubs and portfolio diversification into bio-based formulations represent the dominant competitive moves reshaping supply-side positioning.
Within the chemistry-integrated tier, DuPont de Nemours, Inc. and BASF SE exemplify divergent pathways to membrane market participation. DuPont occupies a position anchored in fluoropolymer heritage, while BASF represents polyurethane chemistry leadership through upstream control over specialty polyols. Soprema Group sits within the system-bundler archetype, capturing specification authority through roofing-solution integration rather than material science differentiation.
| Leading Market Players |
|---|
| DuPont de Nemours, Inc. |
| Compagnie de Saint-Gobain S.A. |
| Kingspan Group PLC |
| BASF SE |
| Soprema Group |
| GAF Materials Corporation |
| Mitsui Chemicals, Inc. |
| Arkema S.A. |
| Sika AG |
| Others |
Supply & Pricing Matrix
Polyurethane substitution for fluoropolymer membranes simultaneously shifts supply geography toward German and Chinese chemical clusters and compresses pricing premiums as REACH compliance costs redistribute across converter tiers.
Pricing Analysis
After-sales technical service and specification support drive lifetime value for membrane converters serving architect-led design-build consortia. Three-tier pricing structure across premium, standard, and economy levels separates monolithic polyurethane films for sportswear brands from microporous polypropylene roofing underlayment and commodity-grade vapor barriers. Price differentiation rests on REACH registration tier and GB standard certification level. Cost compression in standard-tier microporous films is intensifying because Yangtze River Delta manufacturers scale output for India's affordable housing pipeline. Roofing contractors exhibit highest price sensitivity, while medical textile suppliers in Switzerland absorb premium pricing for traceability documentation.
Supply Chain Analysis
Germany and China anchor specialty polyol and microporous polypropylene production respectively, with the United States maintaining fluoropolymer conversion capacity for medical device applications. Raw material flows draw from BASF and Covestro polyurethane precursors, LyondellBasell polypropylene resins, and DuPont fluoropolymer feedstocks. Single-source vulnerability concentrates in specialty polyol allocation during supply shocks. Distribution runs through consolidated roofing distributors in the US Northeast and Pacific Northwest operating three-supplier maximum portfolios, displacing fragmented regional converter networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: REACH registration timelines and multi-jurisdiction certification requirements create switching costs that protect incumbent specification authority.
For Market Incumbents: Fortify backward integration into specialty polyol supply to offset BASF and Covestro allocation constraints during supply shocks. Deepen certification investment for ECHA PFAS transition chemistries ahead of sunset horizons to strand competitor inventory. Channel control through architect-led design-build consortia locks out non-preferred brands in multifamily residential projects above 100 units.
For New Entrants and Emerging Players: Contractor training and building inspector education gaps in legacy vapor barrier replacement create service-layer white space for specification support offerings. India's PLI scheme for affordable housing materials offers the most penetrable geography for cost-optimized microporous membranes. Target mass residential project developers with direct technical service bypassing consolidated distributor tiers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed membrane converters lacking upstream polymer integration. Long-term viability over the next decade hinges on successful navigation of fluoropolymer transition chemistry R&D. Watch for ECHA PFAS restriction finalization as inflection indicator accelerating stranded asset risk for ePTFE-dependent producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Polyols | Captive supply of polyurethane precursors insulates converters from BASF and Covestro allocation constraints. |
| REACH Transition Chemistry R&D | Silicone-modified polyurethane validation ahead of ECHA sunset timelines prevents stranded ePTFE inventory. |
| Architect-Led Distribution Consolidation | Three-supplier maximum portfolios in US Northeast and Pacific Northwest lock in specification authority. |
| India PLI Scheme Market Entry | Cost-optimized microporous membrane production for Maharashtra and Gujarat affordable housing pipelines. |
| Hybrid Membrane Automotive Adoption | Single-film solutions for seat ventilation and headliner applications consolidate OEM material counts. |
Research Methodology
Desk research of customs trade data, SEC 10-K filings, and ECHA registration databases preceded structured interviews with membrane converter plant managers, roofing contractor procurement leads, architect specification consultants, and BASF technical R&D directors. Primary fieldwork combined with secondary validation through trade association reports and building code documentation. Bottom-up volume modeling triangulated against top-down polymer precursor consumption estimates.
Variance decomposition across membrane type, material composition, end-use industry, and regional regulatory cluster shaped the analytical framework. CAGRs derived from segment-level volume trajectories and value-per-unit elasticity modeling. Forecast inputs included EU Green Deal implementation pace for building renovation specifications and China's dual carbon goal alignment with provincial construction code adoption.
Material uncertainties — ECHA PFAS restriction finalization timelines, specialty polyol supply shock recurrence, and contractor training adoption rates — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory harmonization across REACH, EPA emissions guidelines, and GB standards. Recalibration cycles align with material shifts in ECHA restriction enforcement and IRA efficiency tax credit allocation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Liquid Roofing Market
Membrane Materials
Bitumen Waterproofing Membrane Market
Membrane Materials
Membrane Chemicals Market
Membrane Materials
Global Nanomembrane Market
Membrane Materials
Oxygen Barrier Materials Market
Membrane Materials
Thermoplastic Polyolefin Membranes Market
Membrane Materials
Global Ion Exchange Membrane Market
Membrane Materials
Single-Ply Membranes Market
Membrane Materials
Polyvinyl Chloride Membranes Market
Membrane Materials
Membrane Skinners Market
Membrane Materials
Spiral Wound Membrane Market
Membrane Materials
Global Membrane Water and Wastewater Treatment Market
Membrane Materials
Reverse Osmosis (RO) Membrane Market
Membrane Materials
Membrane Polymers Market
Membrane Materials
Microporous Materials Market
Membrane Materials
North America Ceramic Membranes Market