
 Membrane Filter Cartridge Market | 2026-2036
Membrane Filter Cartridge Market Size, Share, and Industry Trends Forecast 2026-2036
Membrane Filter Cartridge Market Outlook
REACH compliance in Europe is shifting the cost-of-entry calculus for membrane filter cartridge suppliers, forcing reformulation of solvent-based manufacturing chemistries and expanded extractables testing protocols. Pall Corporation leverages its vertically integrated membrane casting operations to absorb these regulatory costs without outsourcing critical polymer synthesis steps. 3M Company anchors its position through fluoropolymer expertise that aligns with tightened per- and polyfluoroalkyl substance scrutiny across multiple jurisdictions.
A membrane filter cartridge consists of a pleated or stacked porous medium housed in a rigid polymeric support structure, with pore sizes ranging from 0.1 micron in microfiltration to sub-nanometer rejection layers in reverse osmosis, engineered to remove particulates, microorganisms, or dissolved solutes from fluid streams. The primary industrial purpose spans sterile product finishing in biopharmaceuticals, process water purification, and critical separation steps in food safety applications. Microfiltration and ultrafiltration product types dominate current volume owing to their established role in bioburden reduction, while nanofiltration registers the fastest structural expansion as pharmaceutical processors adopt tighter endotoxin control standards. Polyethersulfone material formulations command premium positioning due to superior hydrophilicity and low protein binding characteristics that reduce product loss during active pharmaceutical ingredient filtration.
The EPA's National Primary Drinking Water Regulations and the FDA's Current Good Manufacturing Practice framework collectively shape membrane specification requirements, with the former driving municipal system upgrades and the latter dictating validation protocols for pharmaceutical-grade cartridges. EMA's Annex 1 revision on sterile medicinal products reinforces single-use filtration trends that favor disposable cartridge formats over reusable stainless steel systems. Stakeholders must monitor evolving perfluorinated compound restrictions in the EU and several US states, as these chemistries underpin PTFE membrane performance and their phase-out would force material transitions across multiple application segments.
Market Dynamics
Single-use sterile filtration is displacing reusable stainless steel systems across biopharmaceutical manufacturing, driven by FDA's updated aseptic processing guidance and EMA's Annex 1 revision demanding validated closed-system operations.
Growth Catalysts
- EMA Annex 1 Revision:Mandatory closed-system requirements for sterile medicinal products accelerate cartridge replacement cycles in European fill-finish operations.
- Biopharmaceutical Manufacturing Clusters:Expansion of sterile filtration capacity in Germany's Heidelberg-Munich corridor concentrates demand for high-integrity membrane systems.
- Polyethersulfone Material Superiority:Low protein binding characteristics reduce active pharmaceutical ingredient loss during sterile filtration of high-value biologics.
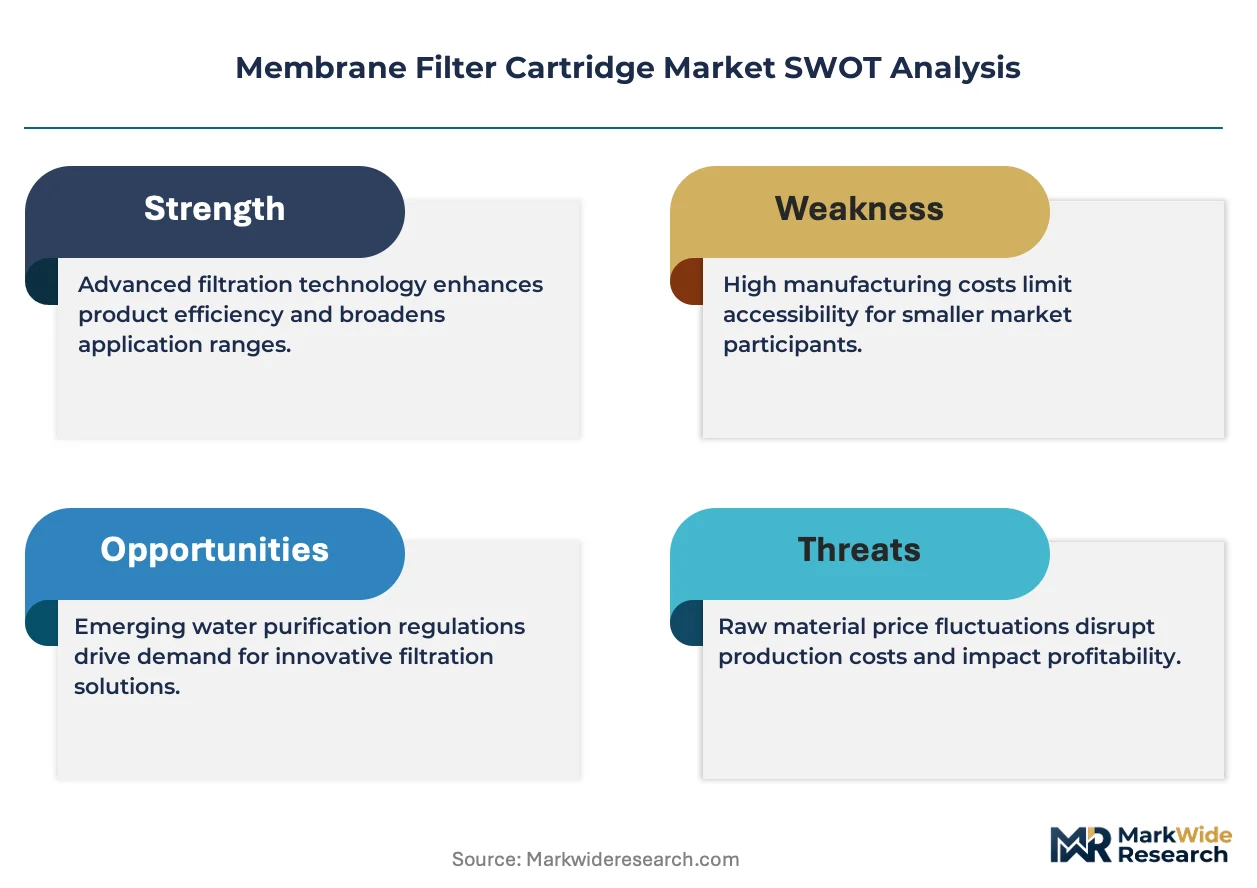
Market Restraints
- Perfluorinated Compound Phase-Out:EU and US state-level restrictions on PTFE precursor chemistries threaten membrane performance consistency across reverse osmosis applications.
- Specialized Polymer Supply Concentration:Captive production of membrane casting resins limits supplier base flexibility when reformulating for REACH compliance.
- Extractables Testing Burden:Expanded solvent-based chemistry validation protocols extend qualification timelines for new cartridge formulations entering pharmaceutical service.
Strategic Opportunities
- India Biologics Manufacturing:CDSCO's alignment with international GMP standards creates opening for validated sterile filtration systems in emerging biosimilar production facilities.
- Continuous Bioprocessing Integration:Convergence of perfusion cell culture with single-use downstream operations demands cartridge formats engineered for sustained high-flux operation.
- Point-of-Use Water Purification:EPA National Primary Drinking Water Regulations drive municipal system upgrades requiring nanofiltration modules for emerging contaminant removal.
Industry Challenges
- Membrane Casting Technical Talent:Scarcity of polymer chemists with expertise in asymmetric membrane formation limits in-house process development capacity.
- Validation Documentation Intensity:FDA Current Good Manufacturing Practice requirements for filter integrity testing create compliance backlog during facility qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Membrane Filter Cartridge Market |
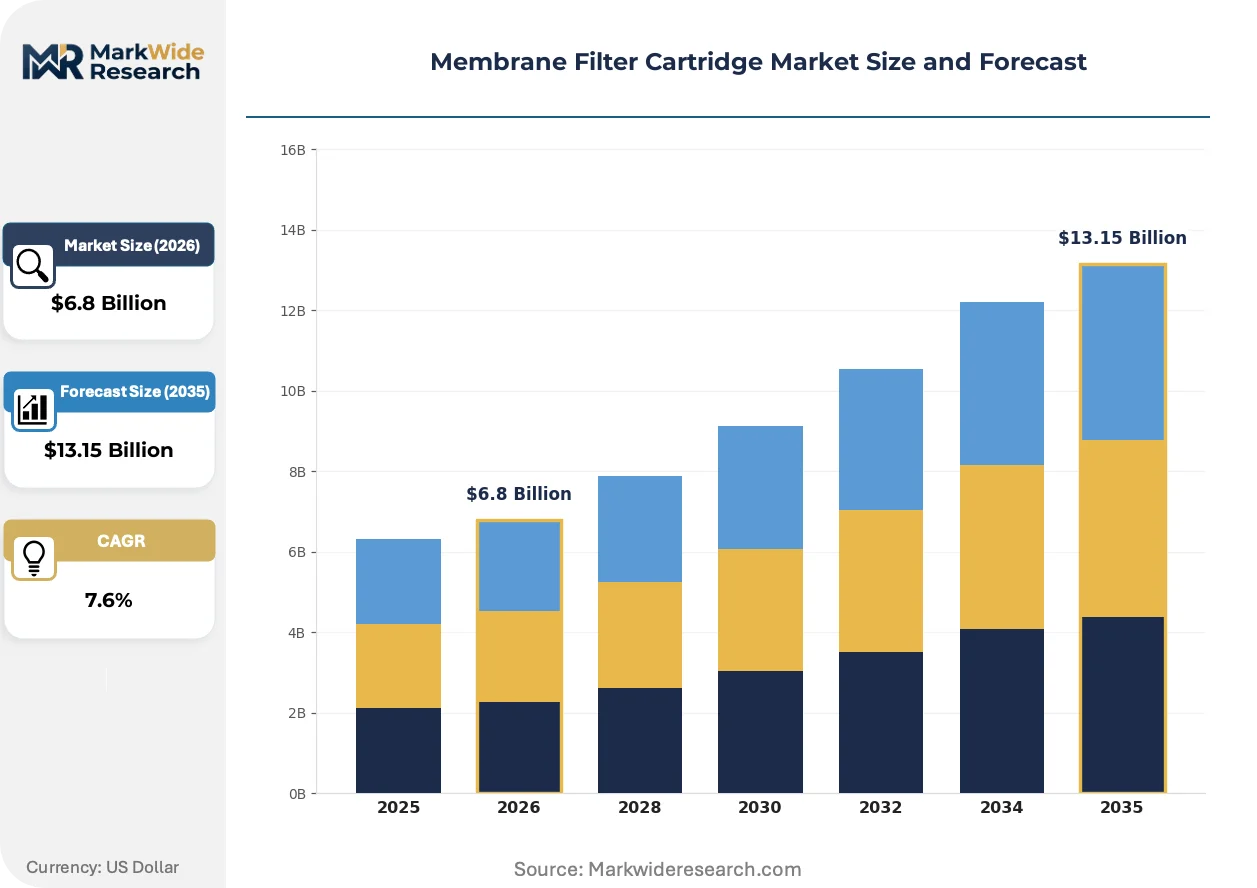
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microfiltration, Ultrafiltration, Nanofiltration, Reverse Osmosis Material: Polypropylene, Polyethersulfone, Ceramic, PTFE Application: Water Treatment, Pharmaceutical Processing, Food and Beverage, Wastewater Treatment End User: Industrial, Residential, Municipal, Healthcare |
| Companies Covered | Pall Corporation, 3M Company, Parker Hannifin Corp., Saint-Gobain Filtration Technologies, Eaton, Merck KGaA, Sartorius Stedim Biotech S.A., Graver Technologies, Koch Membrane Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Membrane Filter Cartridge Market Strategic Shifts
Membrane cartridge architecture is converging with process analytical technology, embedding sensors that enable real-time integrity monitoring rather than post-use destructive testing.
Layered composite membrane structures combining polyethersulfone microfiltration substrates with functionalized surface chemistries is electrifying endotoxin control performance in parenteral drug manufacturing. Large-molecule biologics producers in the United States adopt these formats within eighteen-month qualification cycles. The technology is compressing validation burden by integrating multiple separation mechanisms into single cartridge units.
REACH reformulation mandates from ECHA are forcing solvent-based manufacturing chemistry transitions across European membrane production facilities. Industrial consequence includes expanded extractables testing protocols that extend new product introduction timelines by six to nine months. Pharmaceutical-grade cartridge suppliers absorb these costs through backward integration into polymer synthesis rather than outsourcing critical material steps.
Consolidated procurement by contract manufacturing organizations is compressing supplier qualification cycles and unbundling after-sales technical service from hardware pricing. Large biopharmaceutical sponsors now mandate single-source filtration strategies across their CMO networks, displacing multi-vendor qualification approaches. This concentration is most visible in North American sterile fill-finish operations where three CMOs control majority of outsourced parenteral capacity.
Membrane Filter Cartridge Market Segmentation
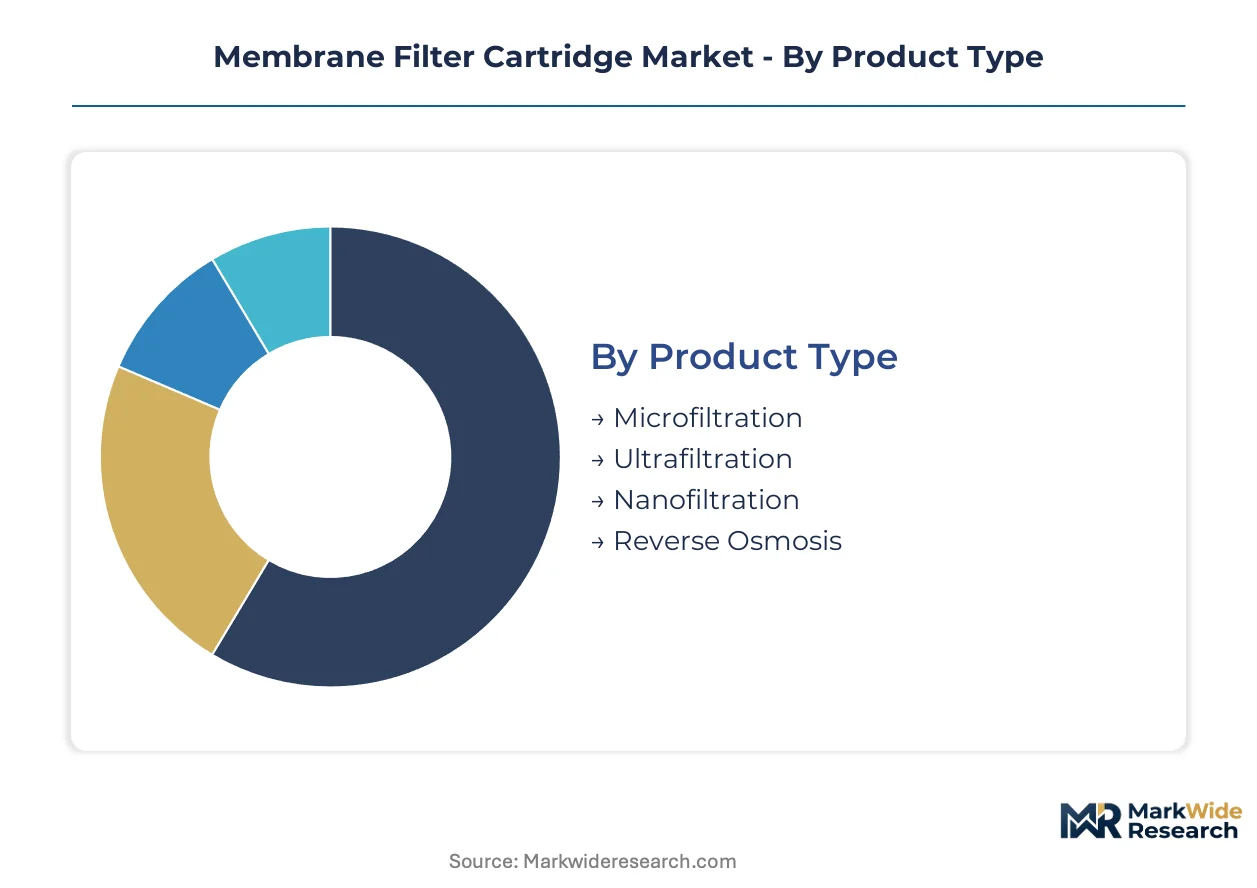
Membrane filter cartridge procurement diverges sharply across sterile pharmaceutical validation requirements versus bulk industrial volume applications. Technical specifications cascade from end-use regulatory burden down to material chemistry and pore architecture decisions.
Product Type:
Standardization dominates microfiltration and ultrafiltration formats where validated protocols reduce customization overhead, while nanofiltration and reverse osmosis retain higher engineering variability for site-specific contaminant profiles.
- Microfiltration:Pleated polymeric membranes with 0.1-10 micron retention ratings form the workhorse for bioburden reduction in parenteral drug filling lines. Demand concentrates in Germany's Heidelberg-Munich biopharmaceutical corridor where EMA Annex 1 compliance mandates closed-system sterile filtration.
- Ultrafiltration:Asymmetric membranes with molecular weight cutoffs of 1-1000 kDa enable protein concentration and buffer exchange in biologics downstream processing. Expansion accelerates in United States perfusion cell culture facilities integrating single-use concentration steps with continuous bioprocessing platforms.
- Nanofiltration:Tight rejection layers for divalent ion and small organic removal serve specialized pharmaceutical endotoxin control and emerging contaminant water treatment.
- Reverse Osmosis:Sub-nanometer dense polymer films deliver dissolved solids rejection for WFI generation and high-purity process water systems.
Most installed capacity flows through microfiltration. Expansion is steepest in nanofiltration.
Material:
Cost tier stratification separates commodity polypropylene from engineered polymers commanding qualification premiums and ceramic formats serving extreme chemical compatibility requirements.
- Polyethersulfone:Hydrophilic low-protein-binding chemistry reduces active pharmaceutical ingredient loss during sterile filtration of high-value monoclonal antibodies. Demand concentrates in North American fill-finish operations where FDA aseptic processing guidance emphasizes product recovery economics.
- PTFE:Hydrophobic fluoropolymer membranes deliver chemical inertness across aggressive solvent streams and vent filtration applications. European REACH perfluorinated compound restrictions threaten precursor supply chains serving reverse osmosis membrane casting operations.
- Polypropylene:Economical thermoplastic construction dominates prefiltration and coarse clarification steps in food and beverage processing.
- Ceramic:Sintered aluminum oxide or silicon carbide structures withstand steam sterilization cycles and caustic regeneration protocols in industrial wastewater reuse systems.
Polyethersulfone commands the highest unit economics. Polypropylene moves the largest absolute volumes.
Application:
Customer maturity separates pharmaceutical validation-intensive procurement from municipal specification-driven bidding and industrial performance contracting.
- Pharmaceutical Processing:Sterile filtration, virus removal, and active pharmaceutical ingredient clarification demand extractables documentation and integrity test validation. FDA Current Good Manufacturing Practice requirements extend qualification timelines for new cartridge formulations entering parenteral drug service.
- Water Treatment:Municipal and industrial potable water production employs microfiltration and ultrafiltration for pathogen and particulate removal. EPA National Primary Drinking Water Regulations drive system upgrades requiring nanofiltration modules for per- and polyfluoroalkyl substance removal in United States distribution networks.
- Wastewater Treatment:Membrane bioreactor configurations achieve effluent quality for industrial reuse and environmental discharge compliance.
- Food and Beverage:Cold sterilization of wine, beer, and dairy products replaces thermal pasteurization to preserve sensory characteristics.
Pharmaceutical processing absorbs the highest per-cartridge expenditure. Water treatment presents the broadest addressable installation base.
End User:
Volume concentration versus value capture splits between municipal bulk procurement and healthcare facility point-of-use specifications.
- Industrial:Power generation, chemical manufacturing, and electronics fabrication demand high-capacity systems with automated backwash and chemical cleaning protocols. Semiconductor fabs in South Korea and Taiwan drive ultrapure water specifications approaching parts-per-trillion contaminant limits.
- Healthcare:Hospital central sterile supply departments and dialysis centers require validated filtration for patient-contact fluids. Consolidated procurement by United States health systems compresses supplier qualification cycles and unbundles technical service from hardware pricing.
- Municipal:Drinking water treatment plants specify membrane trains for cryptosporidium removal and emerging contaminant control within rate-regulated capital budgets.
- Residential:Point-of-use and point-of-entry systems serve household drinking water and appliance protection in private well and municipal tap applications.
Industrial users deploy the largest individual system capacities. Healthcare segments sustain the highest replacement frequency and validation documentation intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer chemists with asymmetric membrane formation expertise concentrate in Germany's industrial southwest and the United States' mid-Atlantic corridor, anchoring regional production capabilities.
United States
FDA's updated aseptic processing guidance drives sterile filtration capacity expansion at biopharmaceutical contract manufacturers. EPA National Primary Drinking Water Regulations mandate municipal system upgrades for emerging contaminant removal. Greater Boston's perfusion cell culture facilities integrate single-use concentration steps with continuous bioprocessing platforms.
Germany
EMA Annex 1 revision on sterile medicinal products accelerates cartridge replacement cycles in European fill-finish operations. REACH compliance from ECHA forces solvent-based manufacturing chemistry transitions across membrane production facilities. The Heidelberg-Munich corridor concentrates demand for high-integrity membrane systems from expanding biopharmaceutical manufacturing clusters.
China
NMPA alignment with international GMP standards creates procurement openings for validated sterile filtration systems in biosimilar production facilities. Dual carbon goals from MIIT drive industrial wastewater reuse specifications requiring ceramic membrane durability. Yangtze River Delta semiconductor fabs demand ultrapure water specifications approaching parts-per-trillion contaminant limits.
India
CDSCO harmonization with international standards enables validated sterile filtration adoption in emerging biosimilar production facilities. PLI scheme incentives attract biologics manufacturing investment requiring single-use downstream operations. Maharashtra's contract manufacturing organizations consolidate procurement across sponsor networks, compressing supplier qualification cycles.
South Korea
MFDS enforcement of sterile product manufacturing standards elevates membrane integrity validation requirements for domestic biopharmaceutical exporters. National semiconductor cluster policies from METI sustain ultrapure water demand for advanced node fabrication. Seoul Capital Area electronics manufacturers specify automated backwash and chemical cleaning protocols for high-capacity filtration systems.
Membrane Filter Cartridge Market Competitive Environment
The competitive structure tilts toward vertically integrated polymer specialists with captive membrane casting capabilities. Tiered supplier concentration separates premium-grade pharmaceutical validators from industrial volume producers. Three archetypes dominate: diversified filtration conglomerates with fluoropolymer expertise, bioprocess-focused specialists with extractables documentation depth, and regional fabricators serving municipal water specifications. Consolidated procurement by contract manufacturing organizations and backward integration into polymer synthesis represent the dominant competitive moves reshaping supplier relationships.
Among diversified filtration conglomerates, Pall Corporation and 3M Company exemplify archetypes with distinct material science foundations. Pall Corporation represents the vertically integrated membrane casting model with in-house polymer synthesis operations absorbing regulatory compliance costs. 3M Company anchors the fluoropolymer expertise position aligned with tightened per- and polyfluoroalkyl substance scrutiny across multiple jurisdictions. Sartorius Stedim Biotech S.A. occupies a position within the bioprocess-focused specialist tier, reflecting European headquarters and single-use system integration capabilities.
| Leading Market Players |
|---|
| Pall Corporation |
| 3M Company |
| Parker Hannifin Corp. |
| Saint-Gobain Filtration Technologies |
| Eaton |
| Merck KGaA |
| Sartorius Stedim Biotech S.A. |
| Graver Technologies |
| Koch Membrane Systems |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between pharmaceutical-validated and industrial-volume tiers manifests in both pricing premiums and captive polymer synthesis requirements. Polyethersulfone formulations command qualification surcharges because EMA Annex 1 and FDA CGMP documentation burdens concentrate supply among backward-integrated specialists, while polypropylene prefiltration flows through distributed fabricators serving municipal bid markets.
Pricing Analysis
Bundled technical service and extractables documentation now unbundle from hardware pricing as contract manufacturing organizations consolidate procurement across sponsor networks. Three-tier pricing structure across premium, standard, and economy levels separates polyethersulfone pharmaceutical grades from PTFE chemical-process tiers from polypropylene prefiltration commodities. Cost compression in standard-tier PTFE intensifies because REACH perfluorinated compound restrictions threaten precursor supply chains. Municipal water treatment buyers exhibit highest price sensitivity, while biopharmaceutical fill-finish operations absorb premium positioning for low-protein-binding chemistries.
Supply Chain Analysis
Refurbishment and cartridge replacement cycles generate reverse-logistics flows concentrated in Germany's Heidelberg-Munich corridor and the United States' Greater Boston cluster. Membrane casting resin production centers on Germany, the United States, and Japan, drawing from specialized polyethersulfone and fluoropolymer feedstocks. Single-source vulnerability in perfluorinated compound precursors threatens PTFE membrane consistency as EU and US state-level restrictions expand. Distribution runs through direct technical sales for pharmaceutical grades and distributor networks for municipal industrial volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities emerge between REACH compliance costs in Europe and CDSCO-aligned GMP adoption in India, where regulatory harmonization lags create cost-advantaged manufacturing zones for export-oriented bioprocess equipment.
For Market Incumbents: Lock in polymer synthesis capabilities before perfluorinated compound restrictions tighten further, and anchor long-term offtake agreements with Germany's expanding Heidelberg-Munich biopharmaceutical corridor. Emerging biosimilar producers in India threaten to displace premium-tier pricing if validation documentation depth does not widen the capability moat. For New Entrants and Emerging Players: Sensor-embedded real-time integrity monitoring offers technology-first entry into the continuous bioprocessing segment where Pall Corporation and 3M Company have not yet consolidated. Target India's Maharashtra contract manufacturing organizations, where CDSCO harmonization creates procurement openings for validated single-use systems without legacy stainless steel replacement burdens. For Investors and Strategic Acquirers: Consolidation pressure builds where extractables testing documentation and captive membrane casting capabilities overlap. Long-term viability favors acquiring mid-cap specialists with polymer chemistry talent in asymmetric membrane formation rather than commodity fabricators. Watch EMA Annex 1 enforcement intensity as the inflection signal for cartridge replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Synthesis | Captive resin production absorbs REACH compliance costs without outsourcing critical material steps. |
| Sensor-Embedded Cartridge Development | Real-time integrity monitoring displaces post-use destructive testing in FDA-regulated fill-finish lines. |
| India Manufacturing Footprint Expansion | CDSCO-aligned facilities capture biosimilar production demand from PLI scheme incentives. |
| Continuous Bioprocessing Format Engineering | High-flux sustained-operation cartridges integrate with perfusion cell culture platforms in Greater Boston. |
| Extractables Testing Protocol Expansion | Extended solvent-based chemistry validation defends pharmaceutical-grade positioning against industrial-tier competition. |
Study Parameters
Bottom-up pharmaceutical and water treatment modeling reconciled against top-down membrane casting capacity tracking forms the analytical core of this study. Primary interviews with bioprocess engineers, regulatory affairs specialists at EMA-notified bodies, municipal procurement officers, and polymer chemists combined with secondary validation from FDA guidance documents, EMA Annex 1 revision texts, EPA National Primary Drinking Water Regulations, and REACH compliance filings from ECHA. Trade data and customs records for polyethersulfone and fluoropolymer feedstocks provided supply-side triangulation against end-use demand signals.
Input-output matrices map cartridge demand by pore architecture, material chemistry, and end-use regulatory intensity across the projection horizon. Segmentation dimensions include filtration technology tier, application validation burden, regional regulatory cluster, and buyer procurement consolidation level. CAGRs derive from installed base replacement cycles, capacity expansion announcements, and regulatory mandate timelines. Industry-specific forecast inputs incorporate EMA Annex 1 implementation pace and EPA emerging contaminant rulemaking trajectory.
The model holds under stable regulatory enforcement intensity; deviation in perfluorinated compound restriction scope or CDSCO inspection capacity would shift regional supply-demand balances. Forecasts reflect documented assumptions about polymer synthesis capacity expansion and qualification timeline norms. Practitioners should monitor ECHA SVHC candidate list updates and FDA aseptic processing guidance revision schedules for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Global Waterproofing Membrane Market
Membrane Materials
Global Polymer Nanomembrane Market
Membrane Materials
Global Nanomembrane Market
Membrane Materials
Reverse Osmosis (RO) Membrane Market
Membrane Materials
Gas Barrier Membranes Market
Membrane Materials
Reverse Osmosis Films Market
Membrane Materials
Liquid Roofing Market
Membrane Materials
Global Track Etched Membrane Market
Membrane Materials
Asia-Pacific, Middle East and Africa Macrofiltration Market
Membrane Materials
Hollow Fibers Membrane Market
Membrane Materials
Global Microfiltration Membranes Market
Membrane Materials
Global Vapor Permeability Films Market
Membrane Materials
Global Ultrafiltration Market
Membrane Materials
North America below Grade Waterproofing Membranes Market
Membrane Materials
Membrane Bioreactor Market
Membrane Materials
Microporous Materials Market