
 Expansion Vessel Membrane Market | 2026-2036
Expansion Vessel Membrane Market Size, Share, and Industry Trends Forecast 2026-2036
Expansion Vessel Membrane Market Foresight
Residential HVAC retrofits in Europe is recalibrating demand toward higher-durability membrane specifications. Spirotech leverages its Dutch engineering base to dominate hydronic system accessory supply across Northern Europe. Reflex Winkelmann GmbH anchors German manufacturing scale for heating system expansion vessels. Zilmet S.p.A. specializes in butyl and EPDM membrane formulations for potable water applications.
An expansion vessel membrane is a flexible, gas-impermeable barrier—typically manufactured from ethylene propylene diene monomer (EPDM), butyl rubber, or thermoplastic elastomers via compression molding or injection molding—that separates a pressurized gas cushion from the system fluid in closed-loop heating, cooling, and water supply networks. Rubber membranes occupy the largest share of product type demand due to proven elastic recovery and temperature resistance across -20°C to 120°C operating ranges. Plastic membrane variants represent the fastest-growing segment as thermoplastic elastomers gain traction in cost-sensitive commercial HVAC installations. Heating systems application demand leads value generation, though industrial processes command premium pricing for chemically resistant composite membrane configurations.
The EU F-Gas Regulation and CE marking requirements under the Pressure Equipment Directive shape material compliance and testing protocols for membrane suppliers accessing European markets. EPA lead-free standards and NSF/ANSI 61 certification govern potable water membrane eligibility in the United States. China's GB standards for pressure vessels and the MIIT green manufacturing framework influence local production specifications and import acceptance criteria. Stakeholders must monitor evolving polymer substitution timelines as regulatory pressure on synthetic rubber supply chains intensifies material sourcing decisions.
Market Dynamics
The EU F-Gas Regulation and China's MIIT green manufacturing framework are compressing polymer substitution timelines, forcing membrane suppliers to requalify material formulations against stricter impermeability and temperature-resistance benchmarks.
Growth Catalysts
- Residential heating retrofits:Germany's building energy efficiency programs are accelerating membrane replacement cycles in legacy hydronic systems, creating pull-through demand for higher-durability EPDM and butyl formulations.
- District heating expansion:China's municipal heating infrastructure buildout is driving volume procurement of expansion vessels with integrated membranes for centralized thermal distribution networks.
- Decarbonization mandates:The EU Green Deal and national building codes are tightening HVAC component specifications, compelling specification upgrades toward chemically resistant composite membrane configurations.
Market Restraints
- Synthetic rubber feedstock volatility:EPDM and butyl rubber supply chains face price instability tied to petrochemical feedstock fluctuations, compressing margin predictability for membrane manufacturers.
- Regional production concentration:Compression molding capacity clusters disproportionately in Germany and Northern Italy, creating geographic supply risk for non-European vessel assemblers.
- Thermoplastic elastomer performance ceiling:TPE membranes exhibit inferior elastic recovery below -10°C, limiting their deployability in Nordic and alpine heating applications.
Strategic Opportunities
- Industrial process heat:Chemical and food processing sectors command premium pricing for fluoropolymer-composite membranes resistant to aggressive thermal fluids, a segment with underpenetrated supplier presence.
- NSF/ANSI 61 certification gap:US potable water applications face constrained qualified supplier availability, creating entry latitude for European manufacturers with existing EPA lead-free compliance.
- Smart hydronics integration:Pressure-sensor-embedded membrane vessels are enabling predictive maintenance contracts, converging hardware supply with IoT-enabled service revenue streams.
Industry Challenges
- CE marking timeline compression:The Pressure Equipment Directive's evolving conformity assessment procedures are extending product validation cycles, delaying commercialization of reformulated membrane compounds.
- Cross-border material qualification:GB standards divergence from EN norms requires duplicate testing protocols for suppliers serving both Chinese and European vessel OEMs, inflating R&D overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Expansion Vessel Membrane Market |
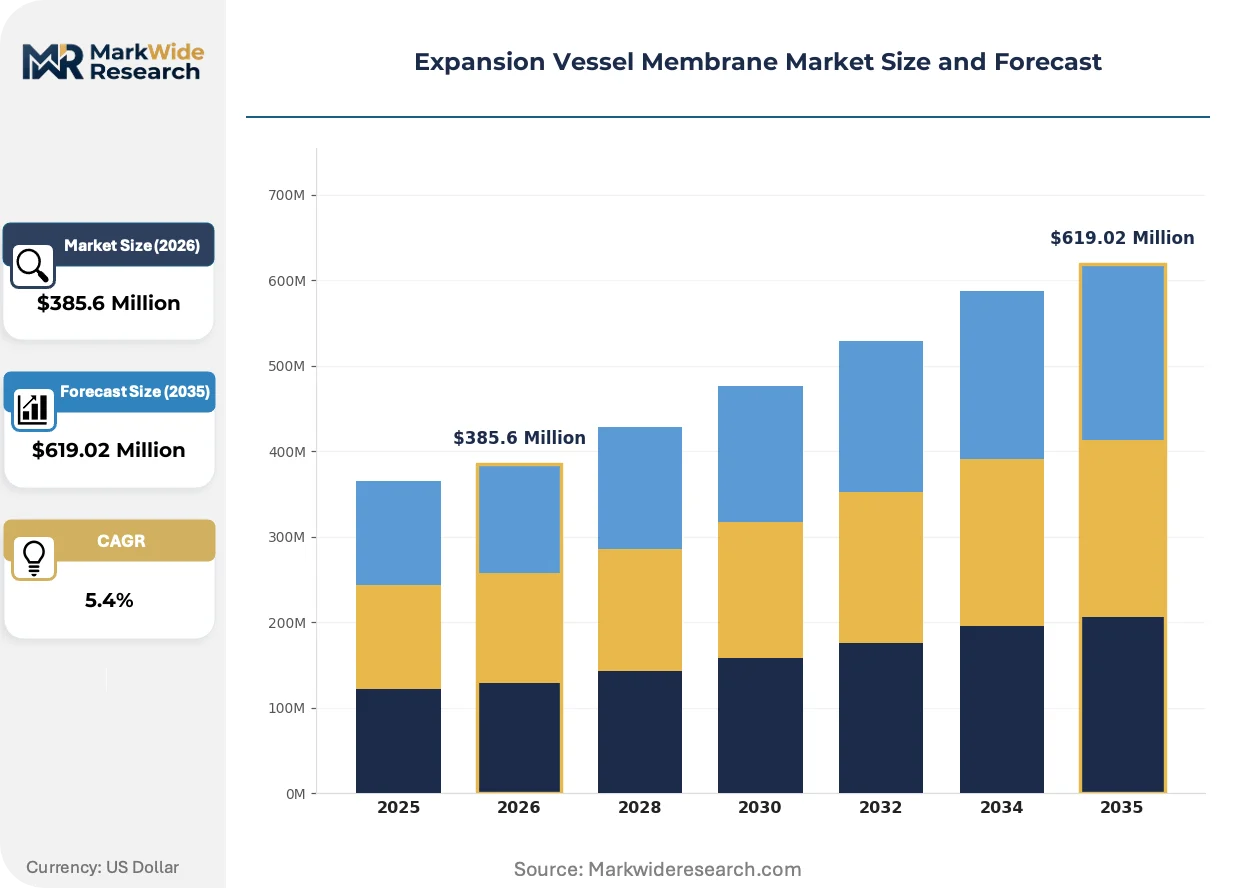
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $619.02 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber, Plastic, Metal, Composite Application: Heating Systems, Cooling Systems, Water Supply, Industrial Processes End User: Manufacturing, Construction, HVAC, Agriculture Installation Type: Indoor, Outdoor, Vertical, Horizontal |
| Companies Covered | Zilmet S.p.A., Spirotech, Aalberts N.V., Reliance Valves, Oldrati Group, Reflex Winkelmann GmbH, Pure Aqua, Inc., EDS Global, Flamco Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Expansion Vessel Membrane Market Shifts & Advancements
Material science advances and regulatory stringency are converging to reshape membrane specifications, manufacturing processes, and procurement patterns across heating, cooling, and water supply networks.
Thermoplastic elastomer compounds are modularizing expansion vessel design architectures by enabling injection-molded membrane production with faster cycle times and geometric complexity unattainable through compression molding. Commercial HVAC contractors in cost-sensitive segments are adopting TPE-based vessels for mid-scale installations. This shift is modularizing supplier production footprints, allowing regional mold-fabrication partnerships that reduce logistics exposure to transoceanic rubber compound shipping.
REACH substance restrictions and the EU F-Gas Regulation's extension to HVAC components are accelerating substitution away from halogenated polymer additives in membrane formulations. Industrial consequences include reformulation costs and extended compatibility testing with glycol-based heat transfer fluids. Heating system OEMs in Germany and the Netherlands are responding by pre-qualifying alternative plasticizer packages and demanding supply chain documentation from raw material tiers.
Specification-driven procurement is consolidating buyer decision authority toward M&E consultants and facilities management platforms, displacing traditional merchant distributor influence in large commercial projects. Engineering-procurement-construction firms are bundling expansion vessel selection into hydronic system design-build contracts. This concentration is most visible in UK and French commercial construction, where framework agreements with national heating contractors lock in membrane specifications across multi-site rollouts.
Expansion Vessel Membrane Market Segmentation
Membrane specification varies sharply across pressure ratings, thermal cycling demands, and fluid compatibility requirements. Procurement patterns diverge between replacement-driven residential retrofits and specification-heavy new commercial construction.
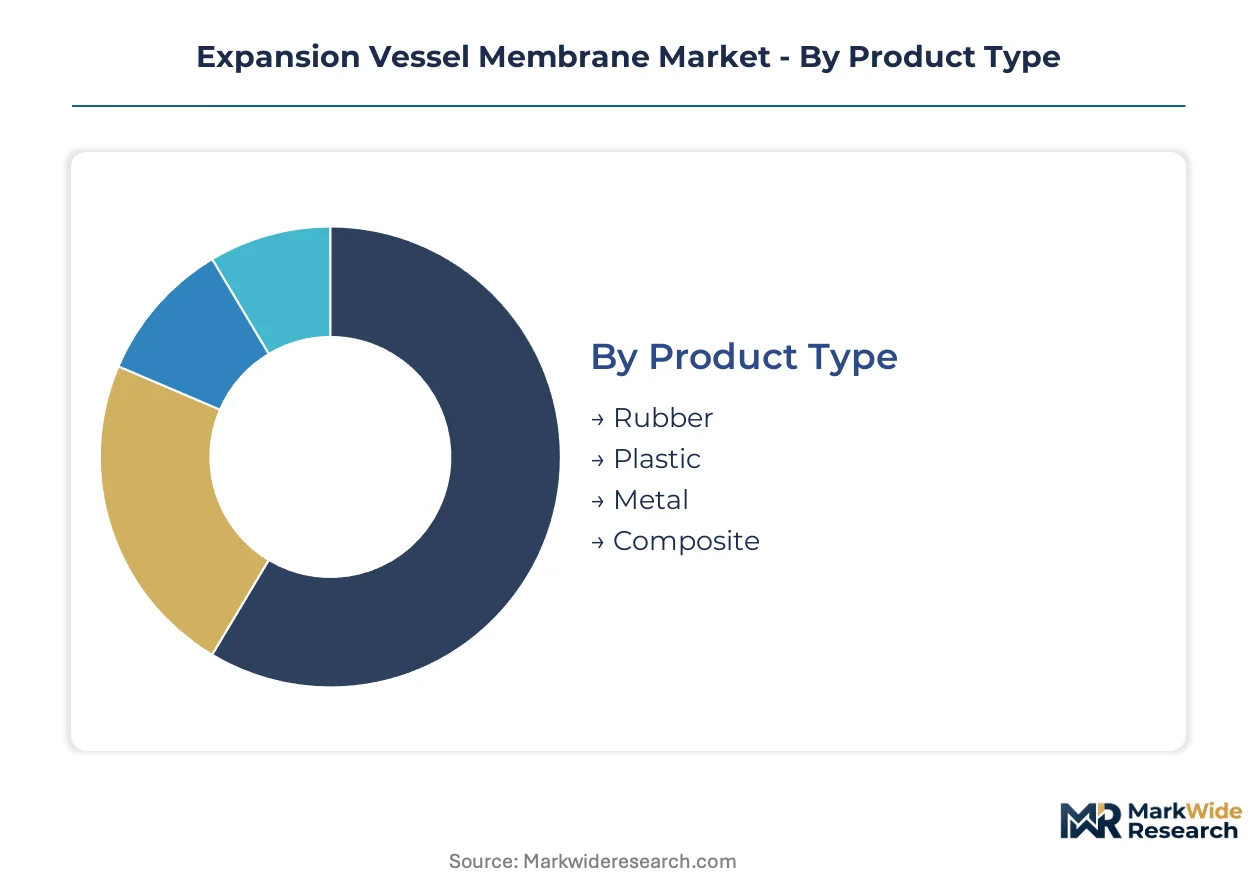
Product Type:
Capital intensity peaks with composite formulations requiring multi-layer lamination and fluoropolymer bonding equipment. Rubber and plastic segments demand lower upfront tooling investment but carry higher per-unit material costs at volume.
- Rubber:EPDM and butyl rubber formulations dominate through proven elastic recovery across -20°C to 120°C operating windows. German heating retrofits and China's district heating procurement are concentrating demand for higher-durometer compounds that withstand accelerated thermal cycling.
- Plastic:Thermoplastic elastomer membranes enable injection-molded production with faster cycle times than compression molding. Cost-sensitive commercial HVAC contractors in mid-scale installations are adopting TPE vessels, though inferior elastic recovery below -10°C limits Nordic deployment.
- Metal:Corrugated stainless steel diaphragms serve ultra-high-pressure industrial applications where polymer permeability is unacceptable.
- Composite:Fluoropolymer-rubber laminates command premium pricing for aggressive chemical resistance in process heat applications.
Most installed capacity flows through rubber. Expansion is steepest in plastic.
Application:
Volume concentration tracks building stock age and climate severity rather than new construction rates. Margin structure inverts between commoditized residential heating and specialized industrial process configurations.
- Heating Systems:Closed-loop hydronic networks in residential and commercial buildings generate the largest addressable volume. Germany's building energy efficiency programs are accelerating membrane replacement cycles in legacy systems.
- Industrial Processes:Chemical and food processing sectors require fluoropolymer-composite membranes resistant to aggressive thermal fluids. Premium pricing reflects limited qualified supplier presence and extended compatibility testing protocols.
- Cooling Systems:Chiller circuits and data center thermal management deploy standard EPDM formulations with glycol compatibility certification.
- Water Supply:Potable water applications face constrained NSF/ANSI 61 qualified supplier availability in the US market.
Replacement cycles dominate heating. Fastest volume gains are appearing in industrial process specifications.
End User:
Procurement authority concentrates differently across sectors: facilities management platforms in construction, M&E consultants in HVAC, and process engineers in manufacturing.
- HVAC:Engineering-procurement-construction firms bundle expansion vessel selection into hydronic system design-build contracts. UK and French framework agreements with national heating contractors are locking in membrane specifications across multi-site rollouts.
- Construction:Specification-driven procurement is displacing traditional merchant distributor influence in large commercial projects.
- Manufacturing:Process heat users command customized membrane configurations with chemical resistance validation.
- Agriculture:Irrigation and greenhouse heating systems deploy cost-optimized EPDM formulations with shorter replacement horizons.
Project concentration sits with HVAC. Manufacturing delivers the highest per-unit margins.
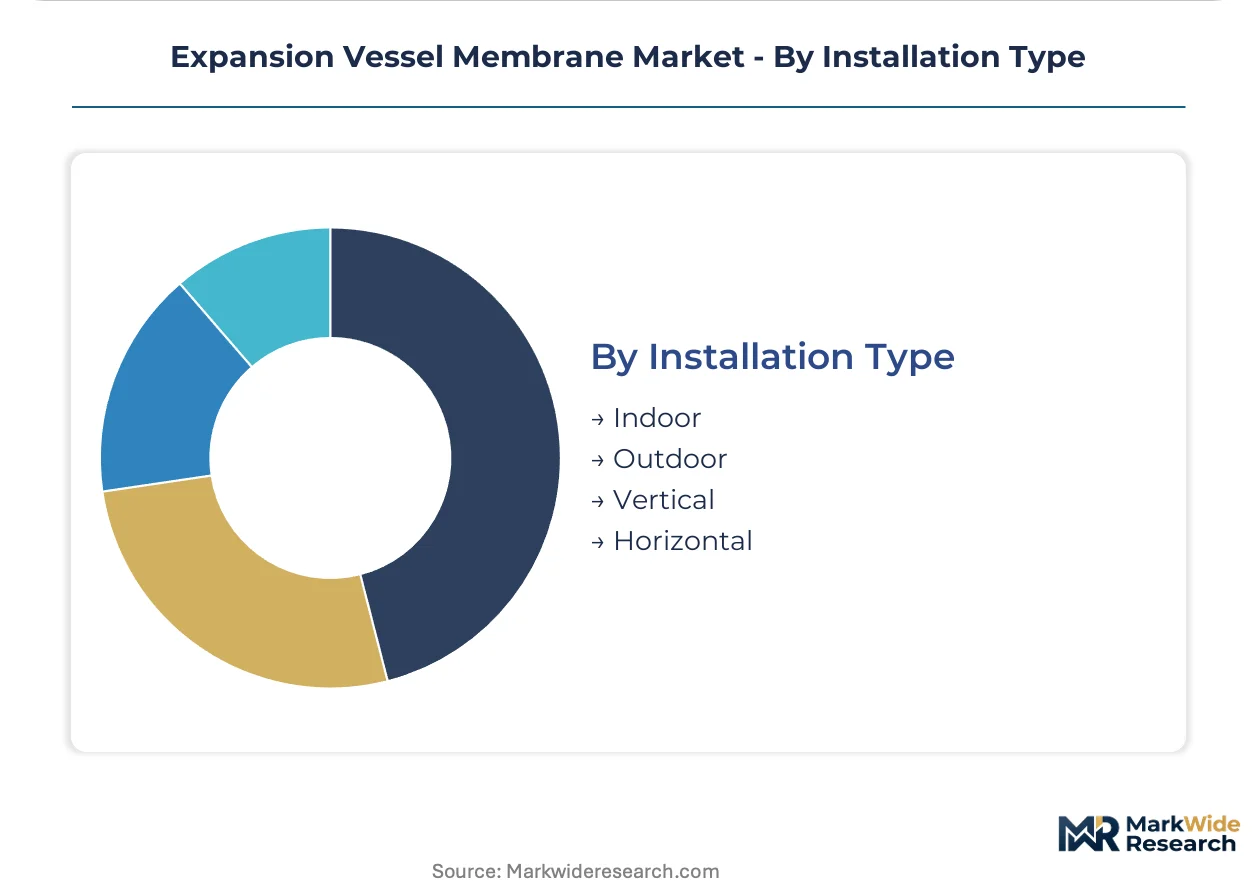
Installation Type:
Orientation and environmental exposure determine membrane material selection and vessel wall thickness requirements. Indoor specifications allow thinner, more flexible membrane formulations.
- Indoor:Climate-controlled mechanical rooms permit standard EPDM and butyl formulations without UV stabilization additives.
- Outdoor:Weather-exposed installations require UV-resistant compounds and reinforced vessel housings.
- Vertical:Upright mounting configurations dominate residential and light commercial applications for space efficiency.
- Horizontal:Low-clearance installations in industrial settings demand specialized membrane geometry to maintain gas-liquid separation.
Vertical vessels carry the largest installed base. Horizontal configurations are gaining traction in industrial retrofit applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as compliance cost gaps between jurisdictions widen. Membrane manufacturers are relocating compression molding capacity toward regions with streamlined certification pathways while maintaining technical sales presence in high-specification markets.
Germany
Building energy efficiency programs in Berlin and Munich are accelerating membrane replacement cycles in legacy hydronic heating systems. The KBA enforces CE marking under the Pressure Equipment Directive with conformity assessment timelines that extend product validation cycles. Manufacturing clusters in North Rhine-Westphalia concentrate EPDM and butyl rubber formulation expertise for premium heating applications.
China
District heating infrastructure buildout in Beijing and Harbin is driving volume procurement of expansion vessels with integrated membranes. MIIT's green manufacturing framework compresses polymer substitution timelines and tightens material sourcing documentation. Production gravity in the Yangtze River Delta serves both domestic municipal heating contracts and export assembly for European vessel OEMs.
United States
NSF/ANSI 61 certification requirements for potable water applications constrain qualified supplier availability across California and Texas installations. EPA lead-free standards govern membrane eligibility in residential and commercial water supply networks. Industrial demand clusters in the Midwest and Southeast favor EPDM formulations with glycol compatibility certification for data center cooling circuits.
Netherlands
Hydronic system engineering expertise in Rotterdam and Eindhoven anchors specification authority for Northern European heating retrofits. REACH substance restrictions accelerate reformulation away from halogenated polymer additives in membrane compounds. Dutch facilities management platforms are consolidating procurement authority through framework agreements that lock in membrane specifications across multi-site commercial rollouts.
Italy
Compression molding capacity in Northern Italy serves cost-optimized membrane supply for Mediterranean and Middle Eastern export markets. ECHA oversight of REACH compliance shapes plasticizer package selection for potable water and heating applications. Lombardy-based suppliers specialize in butyl rubber formulations for thermal cycling resistance in alpine climate installations.
Expansion Vessel Membrane Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with technical specification authority concentrating among engineering-driven European suppliers while Asian fabricators capture volume-driven commercial HVAC procurement. The vendor base organizes into three tiers: premium formulation specialists with in-house polymer compounding, mid-scale regional molders serving national vessel OEMs, and commodity assemblers dependent on imported rubber compounds. Competitive positioning hardens through M&A activity targeting complementary certification portfolios and strategic partnerships that secure raw material allocation during petrochemical feedstock volatility.
Within the premium formulation tier, Zilmet S.p.A. and Reflex Winkelmann GmbH exemplify engineering-centric positioning anchored in Italian and German manufacturing heritage. Spirotech occupies a position bridging branded distribution and technical specification influence across Northern European hydronic markets. These three entities represent distinct archetypes: the vertically integrated compounder-molder, the scale-focused national champion, and the specification-driven system integrator.
| Leading Market Players |
|---|
| Zilmet S.p.A. |
| Spirotech |
| Aalberts N.V. |
| Reliance Valves |
| Oldrati Group |
| Reflex Winkelmann GmbH |
| Pure Aqua, Inc. |
| EDS Global |
| Flamco Group |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between NSF/ANSI 61-qualified potable water membranes and standard heating-system formulations manifests in divergent margin structures and sourcing footprints. Premium-grade suppliers in Germany and Italy capture pricing power through captive compounding while commodity assemblers in Asia face margin compression from volatile EPDM feedstock costs.
Pricing Analysis
Distributor markups of 25-35% separate merchant channel pricing from direct OEM supply contracts in European markets. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden, with NSF/ANSI 61 and CE marking under the Pressure Equipment Directive commanding 40-60% premiums over uncertified alternatives. Price erosion runs through commodity rubber membrane tiers as Chinese district heating procurement shifts toward volume-based tendering. Facilities management platforms in the Netherlands and UK exhibit lowest price sensitivity due to lifecycle-cost procurement frameworks, while agricultural irrigation distributors in Southern Europe remain most margin-constrained.
Supply Chain Analysis
MIIT green manufacturing framework requirements are forcing foreign suppliers to establish domestic compounding partnerships or absorb 15-20% import duty penalties in China. Compression molding capacity clusters in Germany, Northern Italy, and the Yangtze River Delta feed global vessel assembly, with EPDM and butyl rubber compounds drawing from petrochemical feedstocks in Belgium, Singapore, and Saudi Arabia. Single-source vulnerability concentrates in halogenated plasticizer additives facing REACH substance restrictions. Distribution runs through hydronic system OEMs and national heating contractors rather than merchant distributors in specification-heavy Northern European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory compliance costs into sustainable competitive moats, with the EU F-Gas Regulation's extension to HVAC components accelerating material requalification timelines that favor incumbents with established testing protocols.
For Market Incumbents: Deepen backward integration into EPDM and butyl rubber compounding to insulate margin structures from petrochemical feedstock volatility. Expand compression molding capacity in Poland or Romania to service Eastern European retrofit demand while maintaining CE marking expertise in legacy German facilities. Pre-empt thermoplastic elastomer substitution threats by embedding pressure sensors and IoT connectivity into membrane vessels, converting hardware supply into predictive maintenance service contracts. For New Entrants and Emerging Players: Enter via NSF/ANSI 61 certification gap in US potable water applications, where qualified European suppliers face logistics cost disadvantages in California and Texas distribution. Target industrial process heat segments in Midwest US chemical corridors and Southeast food processing clusters, where fluoropolymer-composite membrane demand outruns specialized supplier presence. Pursue toll-compounding partnerships with established rubber formulators to bypass capital-intensive mixing equipment while building compatibility testing credentials. For Investors and Strategic Acquirers: Consolidation pressure builds where CE marking timelines and REACH reformulation costs outpace mid-scale regional molders' R&D absorption capacity. Five-to-ten year viability favors vertically integrated compounder-molders with diversified certification portfolios spanning EPA lead-free, NSF/ANSI 61, and GB standards. Monitor polymer substitution timelines under EU F-Gas Regulation as inflection signal for stranded asset risk in halogenated additive-dependent membrane formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rubber Compounding | Captive EPDM formulation insulates margins from petrochemical volatility and REACH supply disruptions. |
| NSF/ANSI 61 Certification Investment | EPA lead-free compliance unlocks premium US potable water segments with constrained supplier availability. |
| Smart Hydronics Sensor Integration | Pressure-embedded membranes enable predictive maintenance contracts with Dutch facilities management platforms. |
| Eastern European Capacity Expansion | Polish or Romanian molding footprint reduces logistics exposure while maintaining CE marking technical sales presence. |
| Fluoropolymer-Composite R&D Partnership | Industrial process heat applications in chemical and food processing command pricing premiums with limited qualified competition. |
Research Methodology
Direct dialogue with membrane manufacturing plant managers, hydronic system OEM procurement teams, EPC contractor M&E consultants, and facilities management platform technical directors grounded qualitative findings. Secondary validation drew from KBA conformity assessment databases, ECHA REACH substance restriction filings, MIIT green manufacturing framework disclosures, and customs trade data for EPDM and butyl rubber compound flows. Bottom-up vessel procurement volume estimates triangulated against top-down heating retrofit program allocations and district heating infrastructure investment disclosures.
Bottom-up modeling segmented demand across rubber, plastic, metal, and composite membrane types, further disaggregated by heating system, industrial process, cooling, and water supply applications. Top-down cross-checks applied macroeconomic filters for construction activity, building stock age distributions, and regulatory compliance cost pass-through assumptions across the projection horizon. CAGRs derived from elasticity-adjusted replacement cycle frequencies and new installation penetration curves, with specific inputs for Germany's building energy efficiency program acceleration and China's municipal heating infrastructure buildout timelines.
Inputs from KBA, ECHA, MIIT, and EPA regulatory filings were available through the study window; gaps in real-time vessel OEM inventory positioning and spot EPDM compound pricing introduce uncertainty bands around near-term volume estimates. Forecasts reflect documented assumptions regarding polymer substitution timelines and REACH plasticizer restriction implementation pacing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Reverse Osmosis Films Market
Membrane Materials
Polytetrafluoroethylene (PTFE) Filter Membranes Market
Membrane Materials
Global Chemical Separation Membranes Market
Membrane Materials
Middle East and Africa Ceramic Membranes Market
Membrane Materials
Global Bitumen Membranes Market
Membrane Materials
Global Microfiltration Membranes Market
Membrane Materials
Breathable Films and Membranes Market
Membrane Materials
Polyvinyl Chloride Membranes Market
Membrane Materials
Microporous Materials Market
Membrane Materials
Geosynthetic Clay Liner Market
Membrane Materials
Fuel Cell Gas Diffusion Layer Market
Membrane Materials
Breather Membranes Market
Membrane Materials
Global Breathable Membranes Market
Membrane Materials
Ultrafiltration Membrane Market
Membrane Materials
Single-Ply Membranes Market
Membrane Materials
Global Track Etched Membrane Market