
 Gastroesophageal Ph Meter Market | 2026-2036
Gastroesophageal Ph Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Gastroesophageal Ph Meter Market Analysis
Hospital purchasing consolidation is hardening across North American and European health systems, reducing vendor counts per IDN while raising technical qualification bars. Medtronic leverages its endoscopy ecosystem to bundle pH monitoring with motility testing platforms. Thermo Fisher Scientific anchors the research segment through calibrated reference standards and analytical instrument compatibility. Laborie, Inc competes on urology-gastroenterology cross-selling infrastructure in ambulatory settings.
A gastroesophageal pH meter measures hydrogen ion concentration in esophageal luminal fluid using glass electrode or ion-selective field-effect transistor sensors, typically sampling at 0.25 Hz to 1 Hz with accuracy within 0.01 pH units for reflux event detection. Portable meters now dominate procedural volume in clinics and home care settings where 24-48 hour ambulatory monitoring replaces inpatient catheterization. Digital technology segments carry higher margin pools due to embedded software for automated symptom association algorithms and cloud data transmission, while analog systems occupy cost-sensitive installed bases in emerging clinical networks. Wireless meters represent the fastest-growing product configuration as telemetric technology eliminates tethered catheter discomfort and improves patient compliance in prolonged monitoring protocols.
FDA 510(k) premarket notification and EU MDR conformity assessment shape device design cycles, with both agencies demanding biocompatibility validation for prolonged esophageal dwell times. EPA regulations on mercury-containing reference electrodes influence material substitution toward solid-state sensor architectures. Japan's PMDA and South Korea's MFDS impose additional electromagnetic compatibility testing that extends approval timelines for wireless telemetry models. Stakeholders must monitor evolving reimbursement thresholds for catheter-free pH capsule systems versus traditional transnasal probes, as payer decisions will redirect capital allocation between product platforms regardless of technical merit.
Market Dynamics
Hospital procurement consolidation across integrated delivery networks is compressing vendor rosters while elevating technical qualification thresholds for wireless pH monitoring systems. This structural concentration forces manufacturers to bundle diagnostic platforms rather than compete on single-device contracts.
Growth Catalysts
- Ambulatory surgery center expansion:Outpatient reflux diagnostic protocols in United States and German facilities are standardizing 48-hour wireless monitoring workflows, displacing traditional inpatient catheterization.
- FDA 510(k) clearance streamlining:Predicate device pathways for solid-state sensor architectures are accelerating approval timelines for catheter-free capsule systems versus legacy transnasal probes.
- Telemetric telemetry maturation:Bluetooth Low Energy and proprietary radio protocols are eliminating tethered catheter discomfort, driving patient compliance in prolonged monitoring regimens.
Market Restraints
- EU MDR conformity assessment complexity:Extended biocompatibility validation requirements for prolonged esophageal dwell times are stretching design cycles and certification costs for wireless capsule entrants.
- Glass electrode supply concentration:Specialized pH-sensitive membrane manufacturing concentrates in German and Japanese component suppliers, creating input vulnerability for analog system producers.
- Catheter-free capsule reimbursement uncertainty:Payer coding gaps between wireless pH capsule systems and traditional transnasal probes in United States commercial insurance create adoption friction despite technical superiority.
Strategic Opportunities
- Pediatric gastroenterology underpenetration:Miniaturized wireless sensors sized for neonatal and adolescent esophageal anatomy remain underserved in United States children's hospital networks.
- Japan PMDA electromagnetic compatibility pathway:Streamlined approval tracks for wireless telemetry models meeting JIS standards create first-mover positioning for manufacturers with existing FDA 510(k) predicates.
- Home-based monitoring channel emergence:Direct-to-patient distribution models bypassing traditional hospital procurement are opening margin pools in post-acute reflux management.
Industry Challenges
- Embedded software validation timelines:FDA scrutiny of automated symptom association algorithms in digital pH meters is extending 510(k) review periods beyond hardware-only submissions.
- Cross-platform data interoperability:Cloud transmission protocols from competing wireless systems lack standardized formats, forcing hospitals to maintain multiple vendor portals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gastroesophageal Ph Meter Market |
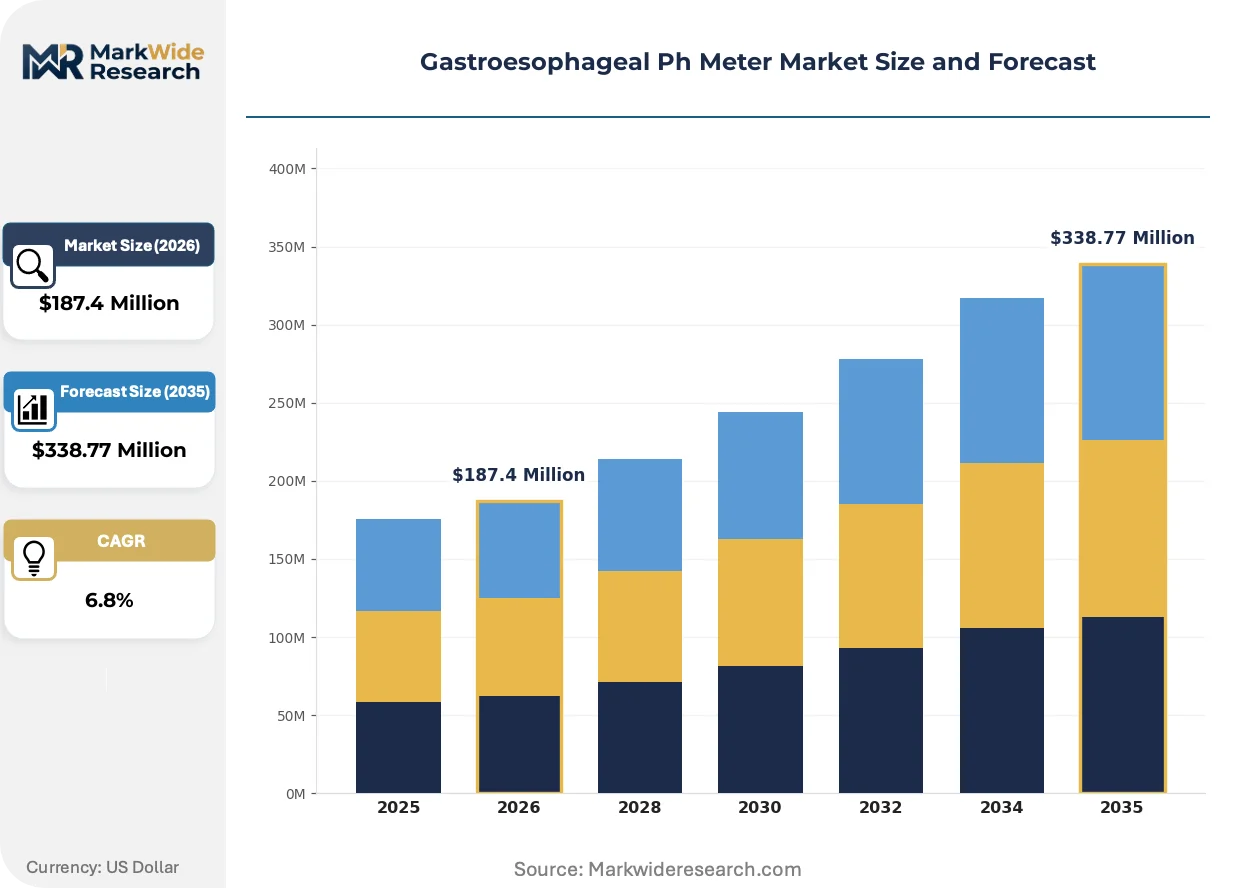
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Meters, Stationary Meters, Wireless Meters, Reusable Meters Application: Acid Reflux Diagnosis, Esophageal Monitoring, Research, Clinical Testing End User: Hospitals, Clinics, Research Labs, Home Care Settings Technology: Analog Technology, Digital Technology, Fiber Optic Technology, Telemetric Technology |
| Companies Covered | Thermo Fisher Scientific, Medica S.p.A, Diversatek, Inc., EB Neuro S.p.A, Laborie, Inc, Medtronic, METTLER TOLEDO, Metrohm, Medical Measurement Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gastroesophageal Ph Meter Market Emerging Trajectories
Digital pH monitoring platforms are converging with broader gastrointestinal diagnostic ecosystems, compressing standalone device margins while elevating software and data analytics value pools. This integration dynamic favors vendors with cross-modal platform breadth over single-product specialists.
Sensor fusion architectures combining pH detection with impedance monitoring are unifying reflux characterization capabilities in single catheter-free capsules. Academic medical centers in the United States and Germany are piloting these dual-modality systems for comprehensive esophageal function assessment. The technology is unifying previously separate diagnostic workflows into consolidated reimbursement codes, compressing capital equipment footprints in ambulatory settings.
EU MDR Article 10 post-market surveillance requirements are mandating systematic clinical follow-up data collection for esophageal dwell devices. Manufacturers must now maintain vigilance systems tracking biocompatibility events across multi-year implantation periods. Wireless capsule producers face the steepest compliance burden, as their extended monitoring protocols trigger more stringent periodic safety update reporting than traditional 24-hour transnasal systems.
Hospital supply chain rationalization is consolidating pH meter procurement through integrated delivery network central contracts. Group purchasing organizations are displacing individual facility purchasing autonomy, compressing vendor negotiation leverage. This concentration is most visible in United States health systems exceeding ten hospital affiliates, where standardization committees now mandate cross-platform compatibility with existing endoscopy inventory management systems.
Gastroesophageal Ph Meter Market Segmentation
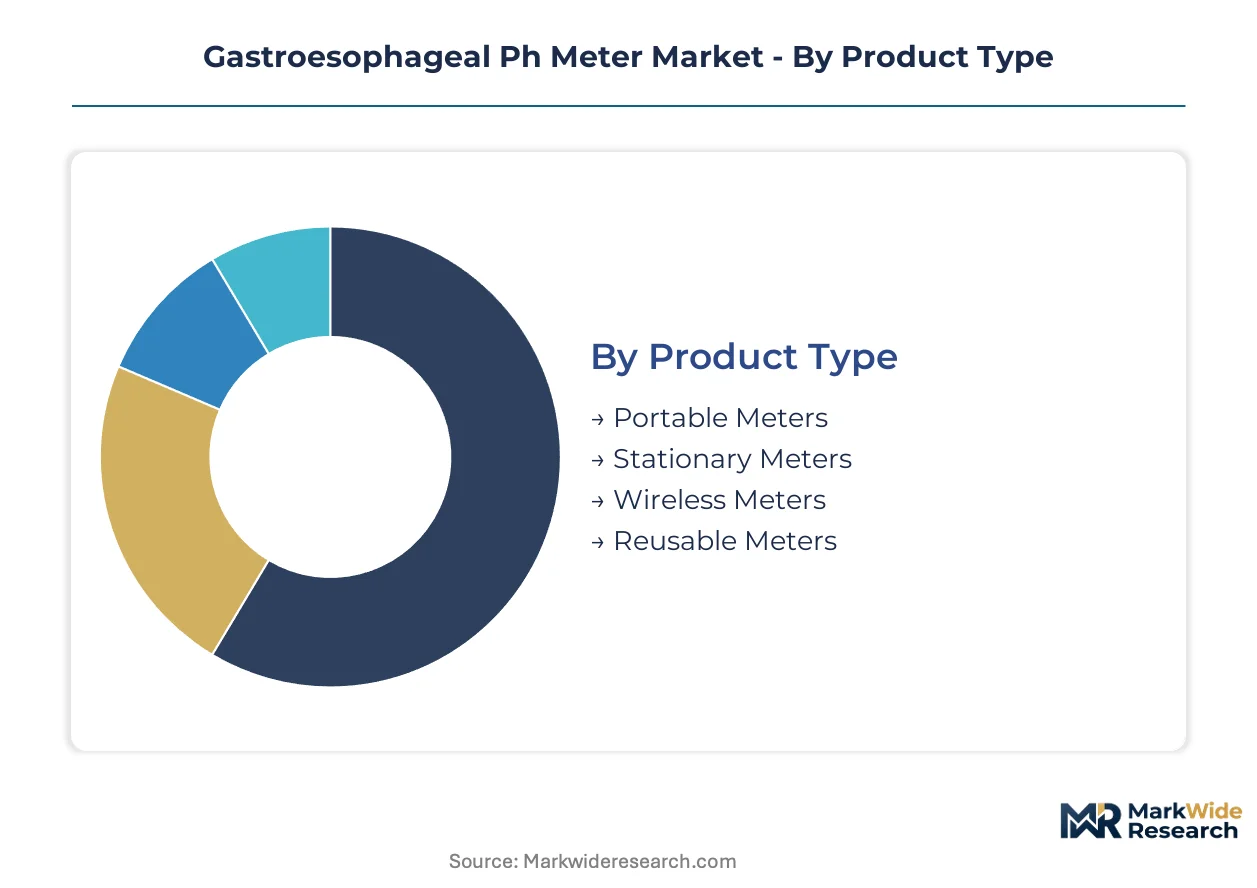
Product configuration and regulatory pathway complexity fragment the gastroesophageal pH meter landscape. Certification burden varies sharply across wireless telemetry versus analog systems, reshaping vendor investment priorities and geographic rollout sequencing.
Product Type:
FDA 510(k) clearance timelines stretch longest for wireless capsule architectures due to biocompatibility validation for prolonged esophageal dwell, while reusable meters face EPA scrutiny on mercury-containing reference electrodes.
- Portable Meters:Battery-powered units sampling at 0.25-1 Hz with glass electrode or ISFET sensors, accuracy within 0.01 pH units. Demand concentrates in United States ambulatory surgery centers where 24-48 hour outpatient monitoring displaces inpatient catheterization. FDA predicate device pathways favor established manufacturers with existing hardware clearances.
- Wireless Meters:Catheter-free capsules transmitting via Bluetooth Low Energy or proprietary radio protocols, eliminating tethered discomfort and improving patient compliance in prolonged regimens. Germany and Japan health systems lead procurement as reimbursement codes stabilize for telemetric monitoring.
- Stationary Meters:Hardwired laboratory-grade systems with calibrated reference standards, primarily serving research institutions and centralized hospital labs.
- Reusable Meters:Multi-use catheter-based platforms with sterilizable components, occupying cost-sensitive installed bases in emerging clinical networks.
Portable meters sit at the top of the volume ranking, with wireless meters climbing the fastest.
Application:
Reimbursement coding density determines margin structure across diagnostic use cases, with acid reflux protocols commanding fuller coverage than research applications.
- Acid Reflux Diagnosis:Standardized 48-hour wireless monitoring workflows in United States and German outpatient facilities, bundled with motility testing platforms under consolidated procedure codes.
- Esophageal Monitoring:Continuous pH tracking for pre- and post-surgical assessment, concentrated in academic medical centers piloting dual-modality pH-impedance fusion systems.
- Research:Calibrated reference standards and analytical instrument compatibility anchor demand at Thermo Fisher Scientific's installed base.
- Clinical Testing:Point-of-care validation in community hospital networks with cross-platform compatibility mandates from integrated delivery network standardization committees.
Acid reflux diagnosis commands the dominant revenue share, while esophageal monitoring gains share fastest through sensor fusion adoption.
End User:
Procurement authority concentration reshapes channel economics, with hospital group purchasing organizations displacing individual facility autonomy.
- Hospitals:United States health systems exceeding ten affiliates now mandate cross-platform compatibility with existing endoscopy inventory management systems, compressing vendor rosters.
- Clinics:Ambulatory settings in Germany and Japan standardizing wireless workflows as payer coding gaps narrow between capsule and transnasal systems.
- Research Labs:Analytical instrument compatibility requirements favor vendors with calibrated reference standard portfolios.
- Home Care Settings:Direct-to-patient distribution models emerging in post-acute reflux management, bypassing traditional hospital procurement channels.
Hospitals retain the largest procurement volume, though home care settings expand most quickly through telemetric telemetry maturation.
Technology:
Material substitution pressures and embedded software validation timelines differentiate competitive position across sensor architectures.
- Digital Technology:Embedded software for automated symptom association algorithms and cloud data transmission, carrying higher margin pools. FDA scrutiny of algorithm validation extends 510(k) review periods beyond hardware-only submissions.
- Telemetric Technology:Proprietary radio protocols and Bluetooth Low Energy eliminating tethered catheter discomfort. Japan PMDA electromagnetic compatibility testing creates approval timeline extensions for wireless entrants.
- Analog Technology:Glass electrode systems with pH-sensitive membranes, concentrated in German and Japanese component supply chains.
- Fiber Optic Technology:Solid-state sensor architectures substituting for mercury-containing reference electrodes under EPA regulations.
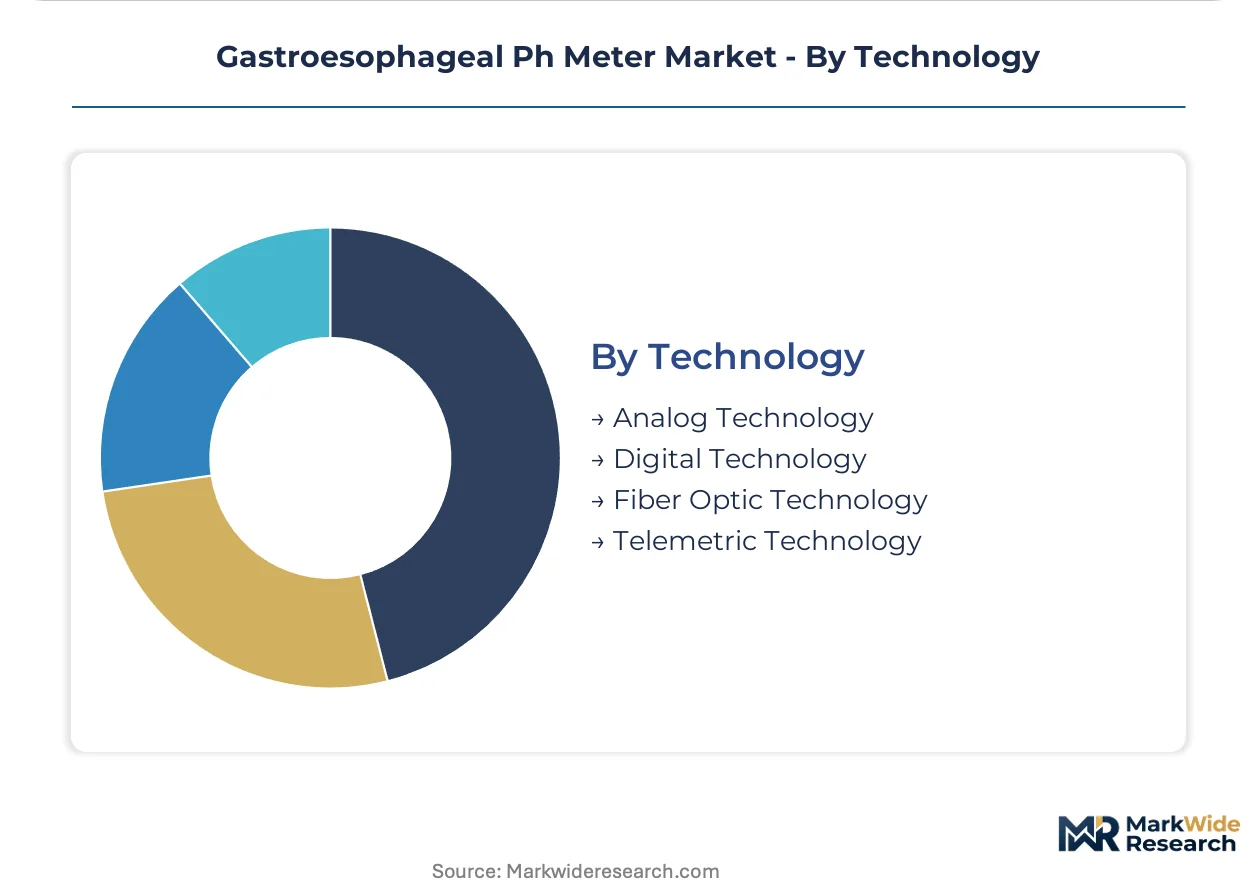
Digital technology leads installed value, with telemetric technology showing the steepest expansion trajectory through patient compliance advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States reimbursement stability contrasts with Germany's regulatory stringency, while Japan's electromagnetic compatibility requirements create divergent approval timelines for wireless pH capsule systems across major clinical markets.
United States
Ambulatory surgery centers in Texas and Florida are standardizing 48-hour wireless monitoring workflows, displacing traditional inpatient catheterization. FDA 510(k) clearance pathways for solid-state sensor architectures accelerate predicate device approvals. Cleveland Clinic and Mayo Clinic anchor pilot programs for dual-modality pH-impedance fusion systems in academic medical settings.
Germany
Glass electrode component manufacturing concentrates in Baden-Württemberg, creating supply vulnerability for analog system producers. EU MDR Article 10 post-market surveillance mandates systematic clinical follow-up data collection for esophageal dwell devices. Berlin and Munich health systems lead procurement of telemetric telemetry models as reimbursement codes stabilize for catheter-free monitoring.
Japan
PMDA electromagnetic compatibility testing extends approval timelines for wireless telemetry entrants, favoring manufacturers with existing FDA predicates. Kanto region hospitals in Tokyo and Yokohama integrate pH monitoring with motility testing platforms. JIS standards for Bluetooth Low Energy protocols create technical qualification barriers for non-domestic vendors.
United Kingdom
NHS supply chain rationalization consolidates pH meter procurement through integrated care system central contracts. MHRA conformity assessment aligns with EU MDR biocompatibility validation requirements for prolonged esophageal dwell. London and Manchester academic centers pilot home-based monitoring channels bypassing traditional hospital procurement.
South Korea
MFDS electromagnetic compatibility testing creates parallel regulatory burden for wireless capsule manufacturers. Seoul Capital Area clinics standardize outpatient reflux diagnostic protocols. Busan-Ulsan medical device clusters concentrate on miniaturized sensor development for pediatric gastroenterology applications.
Gastroesophageal Ph Meter Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the gastroesophageal pH meter landscape. Hospital procurement consolidation through integrated delivery networks compresses vendor rosters while elevating technical qualification thresholds. Three archetypes dominate: endoscopy ecosystem bundlers, analytical instrument platform anchors, and ambulatory setting cross-sellers. M&A activity concentrates on diagnostic platform integration, while geographic expansion targets streamlined regulatory pathways.
Among diversified medical technology conglomerates, Medtronic exemplifies the endoscopy ecosystem bundler archetype, leveraging cross-modal platform breadth to compress standalone device margins. Thermo Fisher Scientific anchors the research segment through calibrated reference standards and analytical instrument compatibility. Laborie, Inc occupies a position within the ambulatory-focused tier, competing on urology-gastroenterology cross-selling infrastructure.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Medica S.p.A |
| Diversatek, Inc. |
| EB Neuro S.p.A |
| Laborie, Inc |
| Medtronic |
| METTLER TOLEDO |
| Metrohm |
| Medical Measurement Systems |
| Others |
Supply Flow & Price Mechanics
EPA regulations on mercury-containing reference electrodes gate both qualified supply and premium-tier pricing access, as manufacturers must substitute solid-state sensor architectures to maintain FDA 510(k) eligibility and command tier-one positioning. This environmental mandate compresses margins for analog system producers while elevating entry costs for wireless capsule entrants seeking prolonged esophageal dwell certifications.
Pricing Analysis
Capacity additions in South Korea and Japan are reshaping price floors for telemetric telemetry components, intensifying cost compression in the wireless meter segment. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA clearance tier and embedded software complexity, with digital platforms carrying algorithm validation premiums. Pricing pressure stems from hospital procurement consolidation through integrated delivery networks, squeezing single-device vendors. Ambulatory surgery centers exhibit highest price sensitivity due to reimbursement coding gaps, while academic medical centers prioritize technical qualification over unit cost.
Supply Chain Analysis
Reverse-logistics flows for reusable catheter-based platforms concentrate refurbishment activity in Germany and the United States, where sterilization validation extends component lifecycles. Glass electrode membrane manufacturing draws from Baden-Württemberg and Osaka-based suppliers, creating single-source vulnerability for pH-sensitive inputs. Supply chain risk centers on EU MDR biocompatibility validation bottlenecks stretching certification timelines for wireless capsule producers. Distribution runs through group purchasing organization central contracts in United States health systems exceeding ten affiliates, displacing individual facility procurement autonomy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gastroesophageal pH meter market functions as a stable compounder, with ambulatory diagnostic protocol standardization driving predictable replacement demand across hospital networks.
For Market Incumbents: Cement cross-modal platform breadth by bundling pH monitoring with motility testing and endoscopy ecosystems, defending against pure-play wireless specialists. Prioritize backward integration into solid-state sensor production to offset glass electrode supply concentration in German and Japanese component markets. Secure FDA 510(k) predicate device clearances for catheter-free capsule architectures ahead of EU MDR timeline compression. For New Entrants and Emerging Players: Pediatric gastroenterology networks in United States children's hospitals remain underserved by miniaturized wireless sensors sized for neonatal esophageal anatomy. Home-based monitoring channels bypassing traditional hospital procurement offer direct-to-patient margin pools in post-acute reflux management. Pursue streamlined Japan PMDA electromagnetic compatibility pathways for wireless telemetry models meeting JIS standards, leveraging existing FDA predicates to accelerate first-mover positioning. For Investors and Strategic Acquirers: Roll-up economics work for diagnostic platform integrators because hospital procurement consolidation through integrated delivery networks compresses vendor rosters and elevates technical qualification thresholds. Target ambulatory-focused specialists with urology-gastroenterology cross-selling infrastructure and existing GPO contract access. Monitor reimbursement coding stabilization for catheter-free capsule systems versus traditional transnasal probes as the inflection indicator for wireless platform valuation expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Streamlining | Solid-state sensor architectures accelerate predicate device approvals for catheter-free capsules. |
| Hospital System Partnership | Integrated delivery network central contracts compress vendor rosters and elevate technical bars. |
| Software Companion Development | Automated symptom association algorithms extend 510(k) review periods but capture premium positioning. |
| Reimbursement Strategy | Payer coding gaps between wireless capsules and transnasal probes determine adoption velocity. |
| CE Marking Pathway | EU MDR Article 10 post-market surveillance mandates systematic clinical follow-up for esophageal dwell devices. |
Methodological Framework
Multiple input streams — primary interviews with biomedical engineers, hospital purchasing committees, and GPO contracts managers; secondary validation through FDA 510(k) filings, CMS Medicare reimbursement databases, and hospital procurement records; plus EU MDR conformity assessment documentation — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured procurement authority concentration dynamics across United States health systems exceeding ten affiliates. Secondary sources included SEC 10-K disclosures from diversified medical technology conglomerates and analytical instrument platform specifications.
Historical volume trajectories were cross-referenced against expert panel inputs spanning the projection horizon. Segmentation dimensions modeled include product configuration, application protocol, end-user procurement channel, and sensor technology architecture. CAGRs were derived from installed base replacement cycles, ambulatory surgery center expansion trajectories, and reimbursement coding stabilization patterns. Industry-specific forecast inputs incorporated wireless telemetry adoption curves and pediatric gastroenterology penetration rates.
Underlying measurement precision varies by segment; wireless meter and digital technology categories carry tighter precision than analog and reusable system estimates due to concentrated vendor disclosure. Forecasts reflect assumptions around FDA 510(k) timeline continuity and EU MDR implementation pacing. Practitioners should monitor payer coding decisions for catheter-free capsule systems and electromagnetic compatibility testing backlog at Japan PMDA for early signals of forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Instruments
Eye Testing Equipment Market
Diagnostic Instruments
Diagnostic Electrocardiograph Market
Diagnostic Instruments
Ultrasound-Guided Breast Biopsy Market
Diagnostic Instruments
Pachymeter Market
Diagnostic Instruments
Genetic Analyzers Market
Diagnostic Instruments
Visual Field Testing Equipment Market
Diagnostic Instruments
Dry Chemistry Analyzers Market
Diagnostic Instruments
Polygraph Instrument (Lie Detector) Market
Diagnostic Instruments
Immunoassay Analyzers Market
Diagnostic Instruments
Auto Chemistry Analyzers Market
Diagnostic Instruments
Europe Immunoassay-Gamma Counters Market
Diagnostic Instruments
Lower GI Series Market
Diagnostic Instruments
Dental Fluorescence Analyzer Market
Diagnostic Instruments
Blood Flow Measurement Devices Market
Diagnostic Instruments
Global Blood Gas and Electrolyte Analyzer Market
Diagnostic Instruments
Global Cell Surface Markers Detection Market