
 Europe Immunoassay-Gamma Counters Market | 2026-2036
Europe Immunoassay-Gamma Counters Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Immunoassay-Gamma Counters Market Foresight
CE-IVDR certification-grade performance is unwinding older open-counter architectures across European diagnostic networks. PerkinElmer, Inc. leverages its long-standing presence in radiometric detection to sustain installed-base loyalty in Nordic oncology centers. Berthold Technologies GmbH & Co. KG anchors its competitive stance through proprietary low-background shielding designs that dominate German nuclear medicine departments. Hidex Oy differentiates via compact benchtop configurations that occupy space-constrained research institutions in Finland and the Baltic states.
Immunoassay-gamma counters are instruments that detect gamma radiation emitted by radioisotope-labeled antigens or antibodies, typically employing sodium iodide or germanium detectors with energy resolution thresholds of 5-10% at 662 keV for quantitative binding assays in clinical and research settings. Automatic counters command the largest revenue share among product types due to throughput requirements in high-volume clinical laboratories, while portable counters represent the fastest-growing segment as point-of-care infectious disease testing expands in decentralized European health systems. Radioimmunoassay retains substantial installed-base volume, though chemiluminescent immunoassay is displacing legacy workflows in hormonal assay applications where non-radioactive alternatives satisfy ALARA principles.
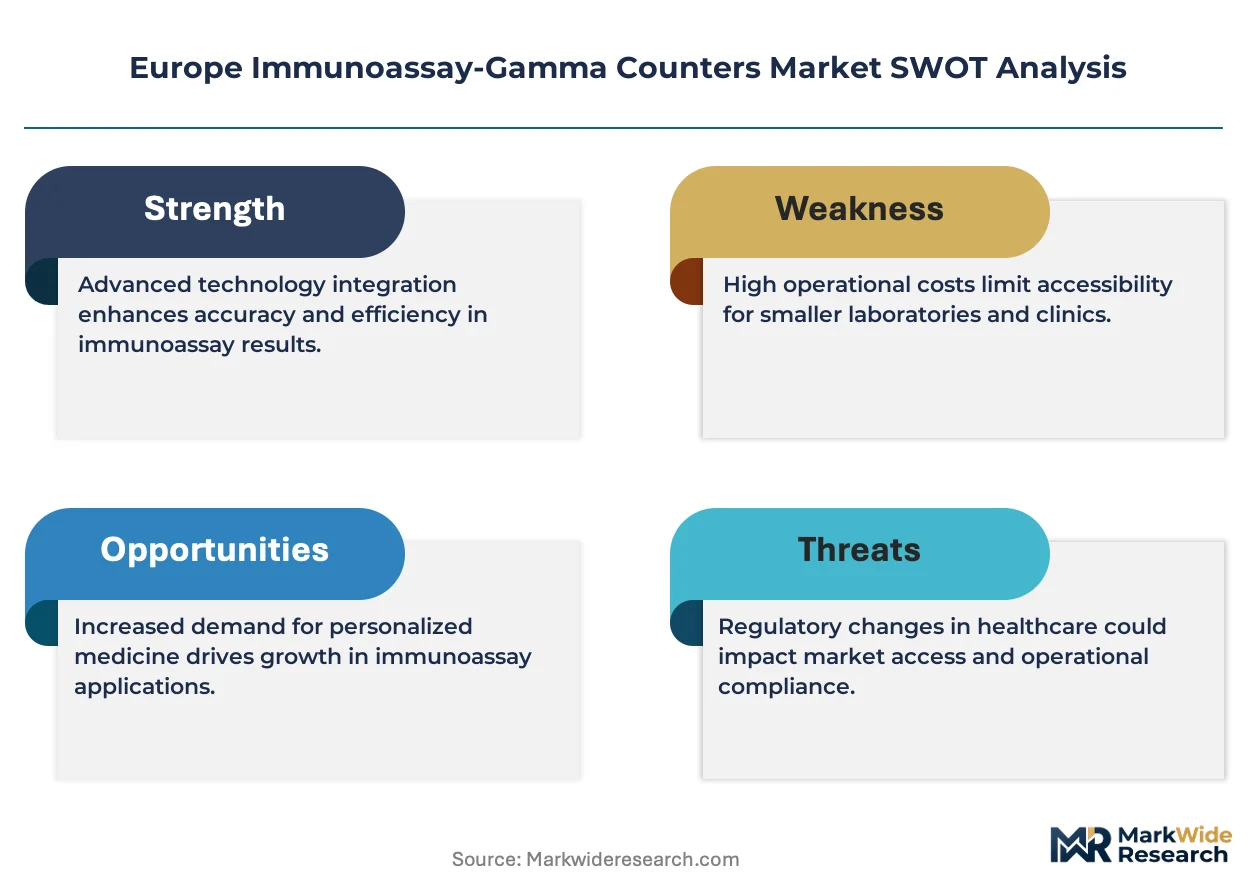
The EU In Vitro Diagnostic Regulation (IVDR) and CE marking requirements administered by notified bodies in Germany, France, and the Netherlands are elevating documentation burdens and conformity assessment costs for gamma counter manufacturers seeking European market access. EMA pharmacovigilance guidelines and national radiation safety authorities in France (ASN) and Germany (BfS) impose additional layer-specific controls on isotope handling protocols that shape equipment specification requirements. Stakeholders must monitor how IVDR transition deadlines and national reimbursement revisions for companion diagnostic testing reshape capital procurement timelines across European hospital networks.
Market Dynamics
The EU In Vitro Diagnostic Regulation (IVDR) is forcing wholesale replacement of legacy open-counter gamma counting systems across European hospital networks, compressing equipment refresh cycles and elevating conformity assessment costs for manufacturers seeking CE marking.
Growth Catalysts
- IVDR Transition Deadlines:The EU In Vitro Diagnostic Regulation mandates recertification of all diagnostic devices by notified bodies in Germany, France, and the Netherlands, creating mandatory equipment replacement demand across clinical laboratories.
- Oncology Biomarker Expansion:German university hospitals and reference laboratories are expanding automated gamma counting workflows for cancer biomarker detection, driving throughput-optimized system procurement.
- ALARA Principle Adoption:Chemiluminescent immunoassay alternatives are displacing legacy radioimmunoassay in hormonal applications, yet residual radioisotope testing for specific biomarkers sustains gamma counter demand in nuclear medicine departments.
Market Restraints
- Radioisotope Supply Concentration:Molybdenum-99 and iodine-125 supply chains concentrate in a handful of aging European reactors, creating vulnerability for diagnostic networks dependent on consistent isotope availability.
- IVDR Conformity Costs:The EU In Vitro Diagnostic Regulation elevates technical documentation and clinical evidence requirements, extending time-to-market for new gamma counter introductions by 12-18 months.
- Non-Radioactive Substitution:Chemiluminescent and electrochemiluminescent immunoassay platforms are capturing hormonal and thyroid testing volumes previously served by radioimmunoassay workflows.
Strategic Opportunities
- Decentralized Point-of-Care Expansion:Portable gamma counter configurations are penetrating space-constrained regional hospitals and satellite clinics in Finland and the Baltic states where full laboratory infrastructure is uneconomical.
- CE-IVDR Certification Differentiation:Early movers achieving notified body certification under the EU In Vitro Diagnostic Regulation capture replacement cycles ahead of laggard competitors still navigating conformity assessment.
- Companion Diagnostic Reimbursement:National reimbursement revisions for companion diagnostic testing in France and Germany are reshaping capital procurement timelines, creating bundled equipment-service purchasing opportunities.
Industry Challenges
- Radiation Safety Specialist Scarcity:Qualified personnel for isotope handling protocol compliance under ASN and BfS guidelines are in short supply across French and German nuclear medicine departments, constraining operational expansion.
- Legacy System Integration Complexity:New CE-IVDR certified gamma counters must interface with entrenched laboratory information systems and sample handling robotics, extending deployment timelines and elevating customization costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Immunoassay-Gamma Counters Market |
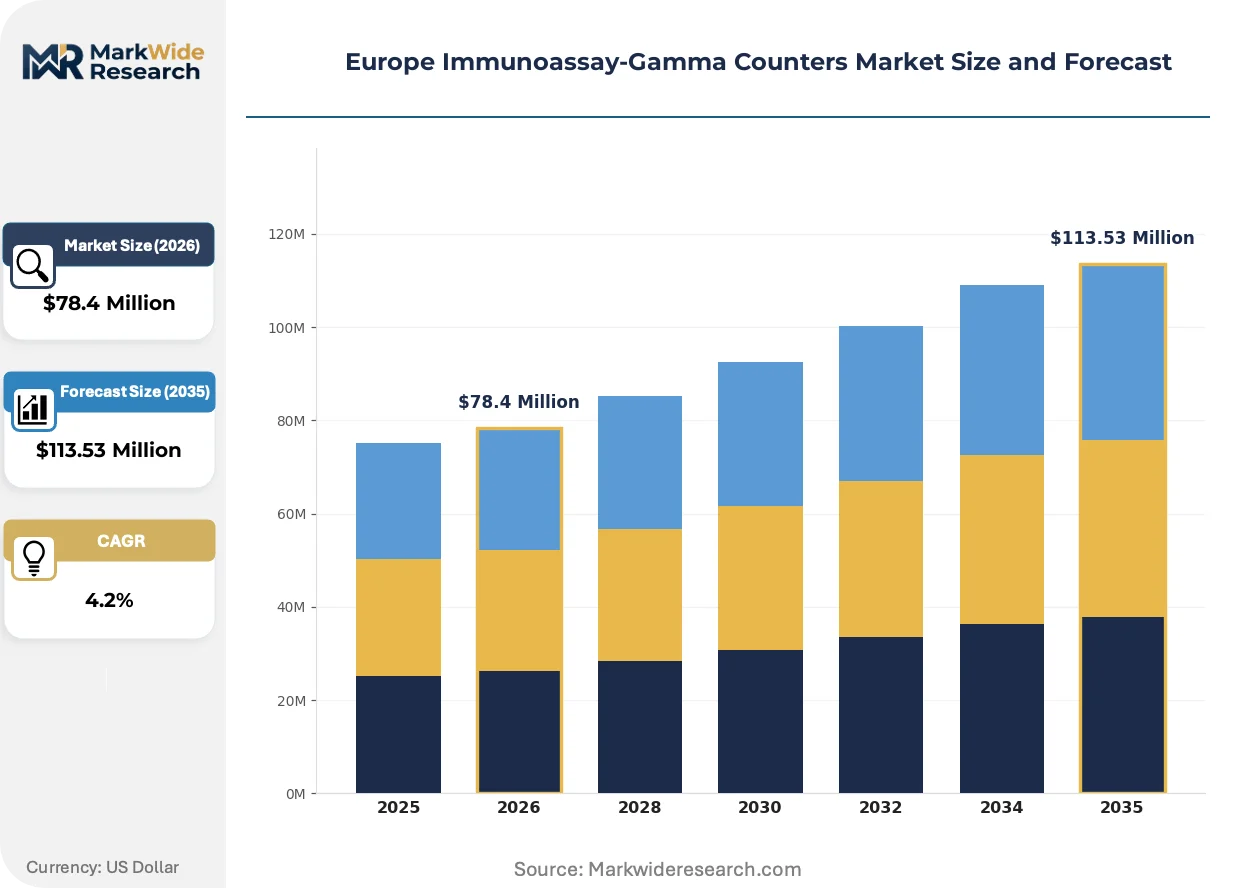
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $113.53 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Counters, Manual Counters, Portable Counters, Fixed Counters Technology: Radioimmunoassay, Enzyme-Linked Immunosorbent Assay, Chemiluminescent Immunoassay, Lateral Flow Assay End User: Clinical Laboratories, Research Institutions, Pharmaceutical Companies, Diagnostic Centers Application: Infectious Disease Testing, Hormonal Assays, Cancer Biomarker Detection, Drug Monitoring |
| Companies Covered | PerkinElmer, Inc., Hidex Oy, Berthold Technologies GmbH & Co. KG, Wallac Oy, LabLogic Systems Ltd., Eckert & Ziegler Group, Mirion Technologies, Thermo Fisher Scientific Inc., Mediso Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Immunoassay-Gamma Counters Market Shifts & Advancements
European gamma counter technology is pivoting toward compact, shielded configurations that reconcile radiation safety requirements with space constraints in aging hospital infrastructure. Three developments are compressing traditional equipment specifications.
Sodium iodide detector arrays with integrated multi-channel analyzers are miniaturizing without sacrificing the 5-10% energy resolution thresholds required for quantitative binding assays. Finnish and Baltic research institutions are adopting these benchtop configurations where floor space is severely constrained. The shift is compressing the addressable market for full-size automatic counters in sub-500-sample-per-day laboratories.
CE marking requirements administered by German, French, and Dutch notified bodies are elevating software validation and cybersecurity documentation for gamma counter control systems. Manufacturers must demonstrate conformity with IVDR Annex I general safety and performance requirements, including algorithm transparency for automated sample handling. High-throughput clinical laboratories in German university hospitals are prioritizing vendors with established notified body relationships.
Service contract unbundling is emerging as procurement departments in UK National Health Service trusts and French hospital groups separate equipment acquisition from maintenance and isotope supply agreements. Third-party service providers are capturing calibration and shielding integrity verification work previously captive to original equipment manufacturers. This fragmentation is most visible in UK cancer network consolidations where centralized procurement favors multi-vendor service flexibility.
Europe Immunoassay-Gamma Counters Market Segmentation
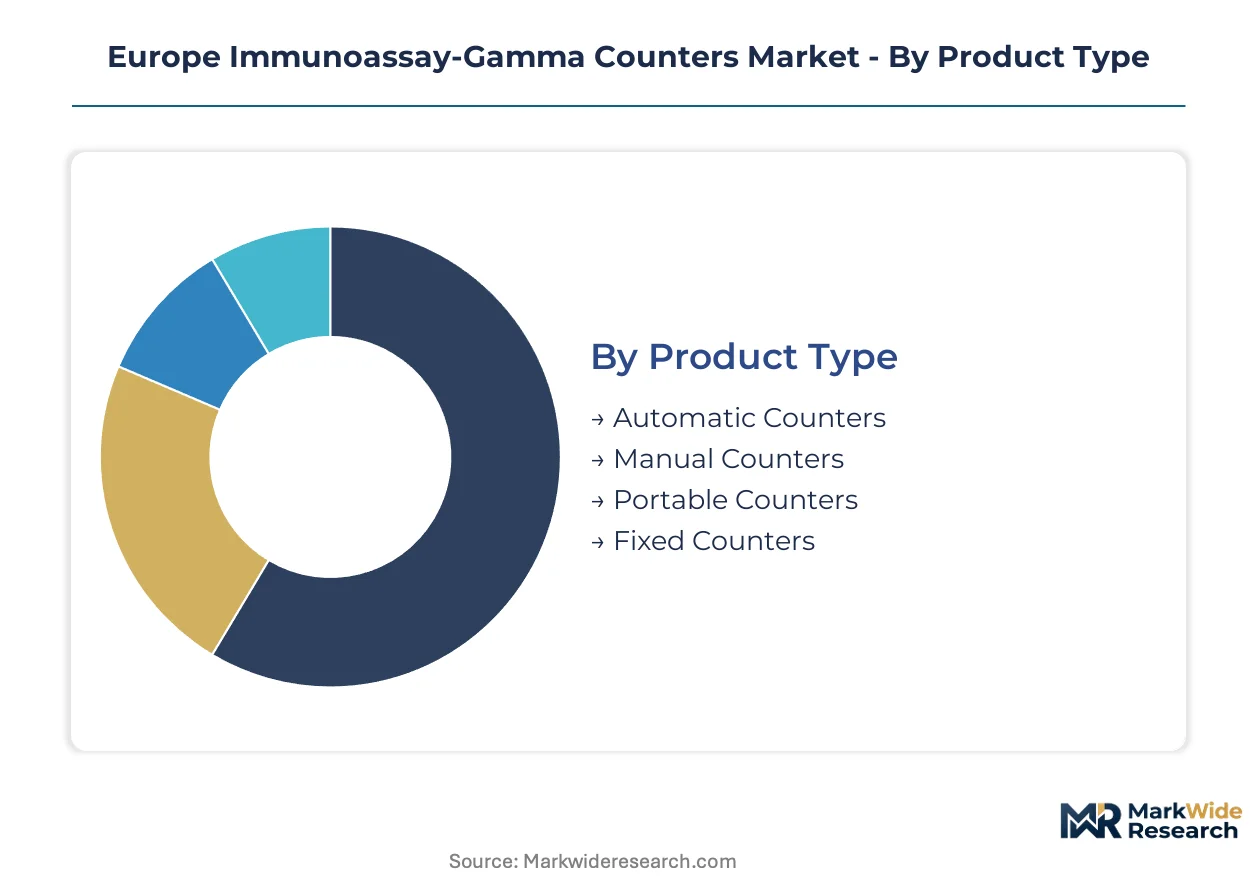
European gamma counter procurement channels diverge sharply by throughput requirements and regulatory complexity. Understanding these segment pathways clarifies where manufacturers must align certification strategies with customer operational constraints.
Product Type:
Automatic counters flow predominantly through group purchasing organizations serving German and French hospital networks, while portable configurations reach regional clinics via specialized diagnostic distributors.
- Automatic Counters:These systems integrate sodium iodide detector arrays with multi-channel analyzers for 500-plus sample daily throughput. German university hospitals and reference laboratories in France are consolidating procurement around these configurations to meet IVDR-mandated workflow automation.
- Portable Counters:Compact benchtop designs with integrated shielding occupy severely constrained floor space. Regional hospitals in Finland and the Baltic states are expanding most quickly here where full laboratory infrastructure proves uneconomical.
- Manual Counters:Open-counter architectures requiring operator intervention for sample loading. Remaining installed base concentrates in legacy research settings with limited capital replacement budgets.
- Fixed Counters:Permanent installation systems with embedded radiation shielding. Nuclear medicine departments in France and Germany favor these for high-volume isotope handling under ASN and BfS protocols.
Automatic counters dominate installed base. Portable counters are where expansion concentrates.
Technology:
Cost tiers separate legacy radioisotope methods from premium chemiluminescent platforms, with reimbursement differentials determining hospital laboratory adoption trajectories.
- Radioimmunoassay:Gamma-emitting isotope labels with quantitative binding measurement. Residual demand persists in German nuclear medicine departments for specific biomarkers where alternative sensitivity proves inadequate.
- Chemiluminescent Immunoassay:Non-radioactive signal generation satisfying ALARA principles. French hospital groups are displacing legacy workflows fastest here for hormonal and thyroid testing applications.
- Enzyme-Linked Immunosorbent Assay:Colorimetric detection without radiation handling requirements. Research institutions across the Netherlands deploy these for screening applications with lower sensitivity demands.
- Lateral Flow Assay:Single-use immunochromatographic strips for rapid qualitative results. Point-of-care infectious disease testing in UK NHS satellite clinics drives volume.
Radioimmunoassay retains substantial legacy volume. Chemiluminescent immunoassay is climbing the fastest.
End User:
Customer procurement sophistication varies from centralized tender processes in national health systems to discretionary research grant funding.
- Clinical Laboratories:High-throughput diagnostic facilities with integrated automation. UK cancer network consolidations and French hospital group centralization are reshaping equipment specifications toward vendor-neutral interfacing.
- Research Institutions:Academic and government laboratories with grant-dependent capital cycles. Finnish and Baltic universities prioritize compact configurations for multi-isotope flexibility.
- Pharmaceutical Companies:Drug development and clinical trial support operations. Companion diagnostic testing expansion in Germany is elevating demand for CE-IVDR certified systems with full audit trails.
- Diagnostic Centers:Independent or hospital-affiliated testing facilities. Decentralized regional networks in France are gaining share fastest as reimbursement shifts favor community-based testing.
Clinical laboratories command procurement volume. Diagnostic centers are where expansion concentrates.
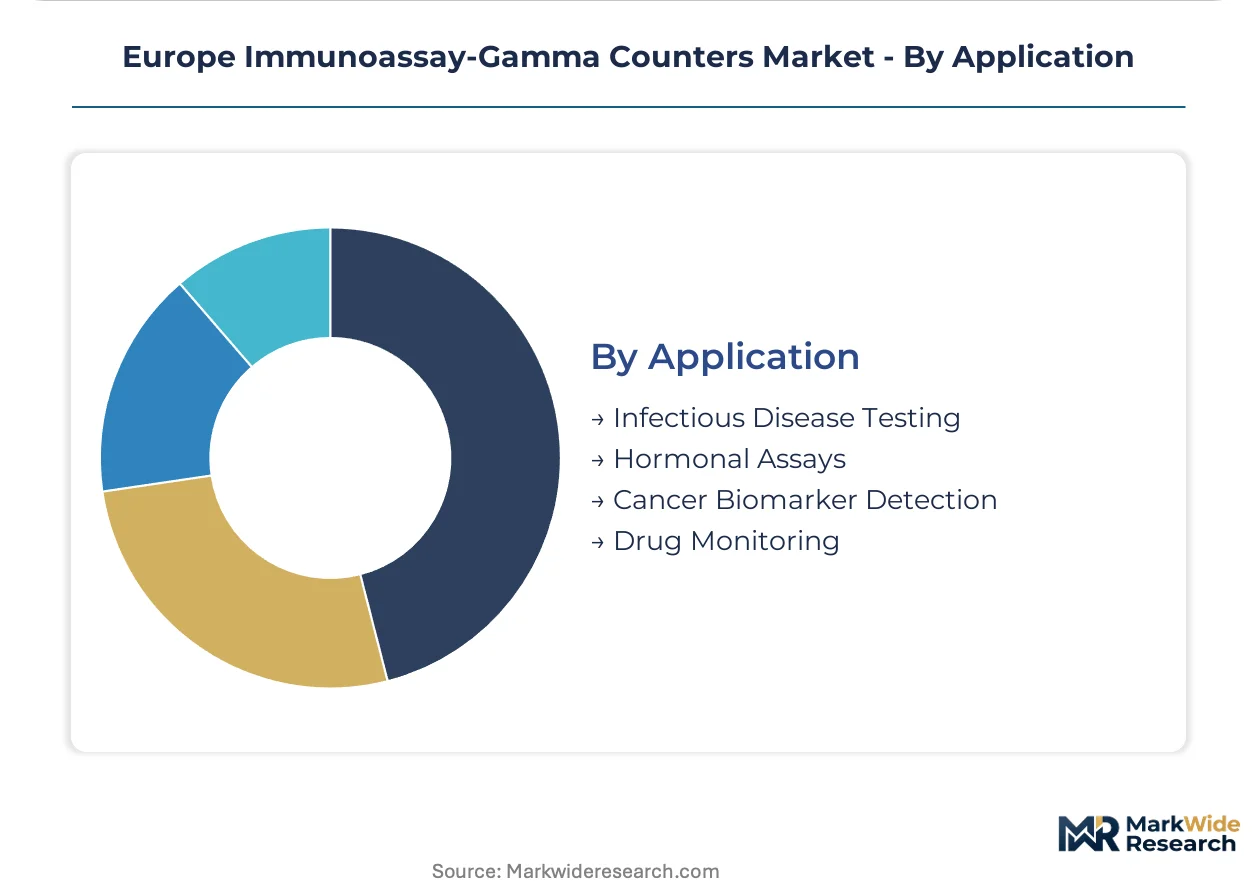
Application:
Volume distribution tracks disease burden and reimbursement policy, with oncology investment outpacing infectious disease in capital allocation.
- Cancer Biomarker Detection:Quantitative measurement of tumor-associated antigens and circulating markers. German university hospitals are expanding automated workflows here fastest as precision oncology programs scale.
- Hormonal Assays:Endocrine function testing including thyroid and reproductive hormones. Chemiluminescent displacement is compressing gamma counter share in French and UK laboratories.
- Infectious Disease Testing:Pathogen antigen and antibody detection. Point-of-care expansion in decentralized European health systems sustains portable counter demand.
- Drug Monitoring:Therapeutic drug level quantification and pharmacokinetic profiling. Pharmaceutical company contract research operations in the Netherlands and Germany concentrate procurement.
Cancer biomarker detection leads capital allocation. Infectious disease testing is expanding most quickly in portable configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European gamma counter trade flows reflect regional manufacturing specialization balanced against import dependence for high-end detector components. Germany and France export complete systems while sourcing sodium iodide crystals from North American suppliers.
Germany
University hospitals in Munich and Heidelberg are expanding automated gamma counting workflows for precision oncology programs. The BfS radiation safety authority enforces strict isotope handling protocols that shape equipment specifications for nuclear medicine departments. North Rhine-Westphalia hosts concentrated manufacturing activity around Dortmund and Cologne.
France
French hospital groups in Paris and Lyon are consolidating procurement around CE-IVDR certified systems for hormonal assay applications. ASN oversight of iodine-125 handling creates compliance-driven replacement cycles across diagnostic networks. The Île-de-France region anchors demand from major reference laboratories.
United Kingdom
NHS cancer network consolidations are reshaping equipment specifications toward vendor-neutral interfacing capabilities. MHRA post-Brexit regulatory alignment with IVDR timelines compresses procurement decision windows. London and Manchester metropolitan clusters concentrate high-throughput clinical laboratory demand.
Finland
Research institutions in Helsinki and Turku prioritize compact benchtop configurations for multi-isotope flexibility in space-constrained facilities. National radiation safety guidelines align with broader EU ALARA principles. The Baltic Sea region serves as a distribution hub for neighboring Baltic states.
Netherlands
Pharmaceutical contract research operations in Amsterdam and Rotterdam elevate demand for CE-IVDR certified systems with full audit trails. The Dutch notified body ecosystem accelerates conformity assessment timelines for manufacturers seeking European market access. Eindhoven's medical technology cluster supports component supply integration.
Europe Immunoassay-Gamma Counters Market Competitive Landscape
Concentration sits with diversified life science instrumentation conglomerates and specialized radiometric detection firms. The vendor base splits between full-line diagnostic platform suppliers and dedicated nuclear medicine equipment specialists. Two archetypes dominate: integrated conglomerates leveraging installed-base loyalty, and focused specialists commanding premium positioning through proprietary shielding designs. Competitive moves center on notified body certification speed and service contract unbundling to capture third-party maintenance revenue.
Among Nordic specialists, Hidex Oy exemplifies the compact-configuration archetype for space-constrained research markets. Berthold Technologies GmbH & Co. KG anchors the German specialist tier with radiation shielding expertise. PerkinElmer, Inc. occupies a position representing the integrated conglomerate model with long-standing radiometric detection heritage.
| Leading Market Players |
|---|
| PerkinElmer, Inc. |
| Hidex Oy |
| Berthold Technologies GmbH & Co. KG |
| Wallac Oy |
| LabLogic Systems Ltd. |
| Eckert & Ziegler Group |
| Mirion Technologies |
| Thermo Fisher Scientific Inc. |
| Mediso Ltd. |
| Others |
Supply & Pricing Matrix
Long-term service contracts with bundled isotope supply agreements lock in both iodine-125 access and price predictability for German and French hospital networks navigating CE-IVDR recertification cycles. These arrangements tether equipment procurement to multi-year maintenance and calibration commitments, compressing spot-market exposure for high-throughput clinical laboratories while elevating upfront capital outlays.
Pricing Analysis
Industrial OEM buyers anchor equipment pricing through group purchasing organizations serving consolidated German and French hospital networks. Three-tier pricing structure across premium automatic counters, standard benchtop configurations, and economy manual systems differentiates by throughput capacity and IVDR certification grade. Cost compression in the economy tier is intensifying because third-party service providers are capturing calibration work previously captive to original equipment manufacturers. Research institutions in Finland and the Baltic states exhibit highest price sensitivity, while German university hospitals prioritize certification speed over unit cost.
Supply Chain Analysis
Germany and France anchor complete system assembly and radiation shielding fabrication for European gamma counter manufacturing. Sodium iodide detector crystals draw from North American specialty suppliers, while molybdenum-99 for isotope generation rests on aging European reactor infrastructure concentrated in the Netherlands and Belgium. Single-source vulnerability in iodine-125 radiopharmaceutical supply creates procurement risk for diagnostic networks. Distribution runs through specialized diagnostic equipment distributors serving hospital networks and research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around CE-IVDR certification creates durable defensive moats for notified body-approved manufacturers, as switching costs for hospital laboratories extend 12-18 months for workflow revalidation.
For Market Incumbents: Shield installed-base loyalty through accelerated IVDR recertification for automatic counter portfolios ahead of laggard competitors, while deepening backward integration into proprietary low-background shielding production to defend margin position against third-party service encroachment in calibration and maintenance. For New Entrants and Emerging Players: Anchor in portable counter configurations for space-constrained regional hospitals in Finland and the Baltic states where full laboratory infrastructure proves uneconomical, penetrating via specialized diagnostic distributors rather than consolidated group purchasing organizations that favor established vendor relationships. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale specialists with established notified body relationships and proprietary detector shielding IP, as these assets compound regulatory compliance speed with technical differentiation over the medium-term horizon. The signal to monitor is national reimbursement revisions for companion diagnostic testing in France and Germany that reshape capital procurement timelines and bundled purchasing patterns.| Strategic Initiative | Industry Significance |
|---|---|
| CE-IVDR Certification Acceleration | Notified body approval in Germany or France captures mandatory replacement cycles ahead of regulatory deadlines. |
| Backward Integration into Shielding | In-house production of low-background detector enclosures defends margin against third-party service fragmentation. |
| Portable Configuration Development | Compact benchtop designs penetrate space-constrained regional hospitals in Finland and Baltic states. |
| Hospital System Partnership | Direct relationships with German university hospitals secure high-throughput automatic counter placements. |
| Reimbursement Strategy | Alignment with French and German companion diagnostic testing policies shapes bundled equipment-service procurement. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with nuclear medicine department heads, hospital procurement committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from EMA pharmacovigilance guidelines, BfS and ASN radiation safety protocols, hospital procurement databases, and notified body conformity assessment records. Bottom-up equipment shipment analysis and top-down diagnostic network expenditure triangulation anchored market sizing.
Across the analysis window, the forecasting framework modeled volume and value outputs by product type, technology, end user, and application dimensions. CAGRs were derived from regression analysis against IVDR transition timelines and oncology biomarker testing expansion trajectories. Industry-specific inputs included isotope supply chain reliability indices and national reimbursement policy revision schedules.
Decision-makers should treat outputs as directional under stable IVDR implementation timelines and intact European reactor infrastructure; material deviation in either would warrant model refresh. Recalibration cycles align with material shifts in regulatory enforcement intensity and radiopharmaceutical supply availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Instruments
Europe Immunoassay Analyzers Market
Diagnostic Instruments
Hair Mineral Analyzer Market
Diagnostic Instruments
Global Chemiluminescence Immunoassay (CLIA) Analyzers Market
Diagnostic Instruments
Trichoscope Devices Market
Diagnostic Instruments
Diagnostic Electrocardiograph Market
Diagnostic Instruments
Vascular Testing Devices Market
Diagnostic Instruments
Global Cell Surface Markers Detection Market
Diagnostic Instruments
Pathological Examination Market
Diagnostic Instruments
Luminometers Market
Diagnostic Instruments
Immunochemistry Analyzer Market
Diagnostic Instruments
Tympanometers Market
Diagnostic Instruments
Genetic Analyzers Market
Diagnostic Instruments
Polygraph Instrument (Lie Detector) Market
Diagnostic Instruments
Immunoassay Instruments Market
Diagnostic Instruments
Global Radioimmunoassay Market
Diagnostic Instruments
Global Blood Coagulation Analyzer Market