
 Platelet Aggregation Devices Market | 2026-2036
Platelet Aggregation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Platelet Aggregation Devices Market Intelligence
Hospital end-user demand is broadening as perioperative coagulation monitoring becomes standard across major surgical protocols. Sysmex Corporation leverages its hematology automation platforms to anchor distribution in Asia-Pacific clinical laboratories. Siemens Healthineers AG sustains R&D intensity across multi-channel aggregation platforms for integrated cardiovascular diagnostics. Haemonetics Corporation specializes in blood bank and transfusion medicine workflows, occupying a defensible niche in pre-procedural platelet function screening.
Platelet aggregation devices measure the rate and extent of platelet clumping in response to agonists, using optical light transmission or impedance-based detection with sample volumes typically below 500 microliters for clinical assays. These instruments serve primarily to guide antiplatelet therapy selection, particularly for patients undergoing coronary stenting or cardiac surgery. Optical aggregometers retain the largest installed base among product types due to decades of clinical validation and standardization in research institutions. Point-of-care devices represent the fastest-expanding segment as emergency departments and catheterization labs prioritize turnaround time over laboratory throughput. Microfluidic technology is concentrating investment from device developers seeking to miniaturize assays while preserving correlation with gold-standard light transmission methods.
FDA 510(k) clearance requirements and EMA In Vitro Diagnostic Regulation standards shape product development timelines and predicate device selection for manufacturers entering either market. ISO 15189 accreditation for clinical laboratories directly influences instrument purchasing criteria and service contract structures. Stakeholders must monitor evolving CLSI guidelines for platelet function testing as these recommendations increasingly determine payer coverage decisions and hospital formulary inclusion.
Market Dynamics
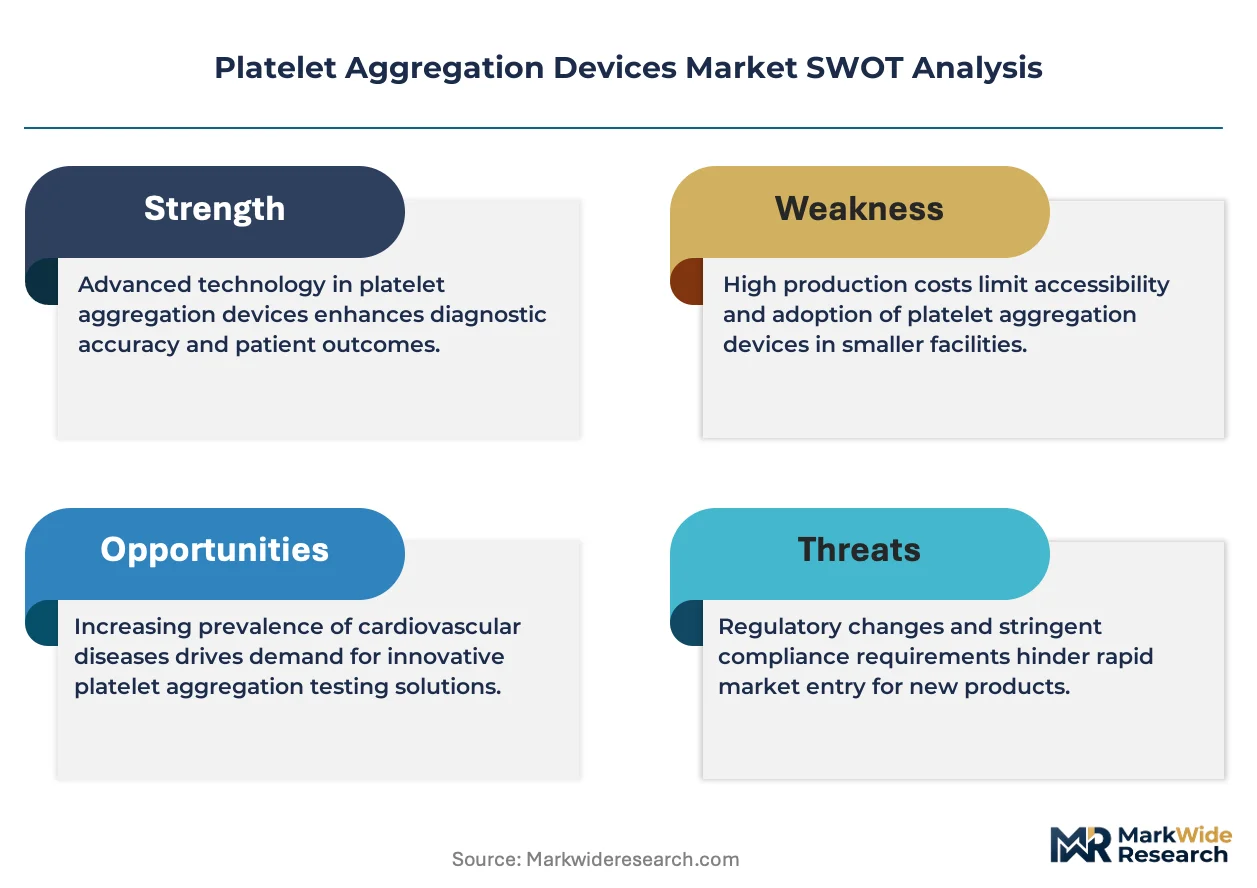
Perioperative coagulation protocols are hardening into mandatory standards across cardiac and orthopedic surgery suites, forcing device manufacturers to validate aggregation assays against specific antiplatelet regimens rather than generic reference ranges.
Growth Catalysts
- EMA In Vitro Diagnostic Regulation:The MDR framework mandates traceability and performance documentation that elevates barriers for low-cost competitors, protecting validated instrument vendors in European hospital procurement.
- Catheterization laboratory throughput pressure:Emergency departments in the United States now demand sub-15-minute turnaround for platelet function results, accelerating replacement of batch-mode laboratory aggregometers with cartridge-based systems.
- Impedance-based detection:Whole-blood methods eliminate centrifugation steps and reduce sample volume requirements, opening procedural applications in neonatal intensive care and trauma bays previously excluded from testing protocols.
Market Restraints
- Optical component supply concentration:Precision photodetectors and stabilized light sources for light-transmission aggregometry concentrate among Japanese and German component suppliers, exposing manufacturers to extended lead times.
- FDA 510(k) predicate device dependency:New entrants must demonstrate substantial equivalence to legacy optical platforms with decades of clinical literature, compressing design freedom for novel detection modalities.
- Point-of-care reimbursement compression:Medicare and commercial payers in the United States have narrowed coverage for platelet function testing outside of specific procedural codes, limiting expansion into routine monitoring indications.
Strategic Opportunities
- India's cardiac intervention expansion:Domestic stenting volumes are rising faster than laboratory infrastructure, creating demand for deployable aggregation devices that operate without centralized cold-chain logistics.
- ISO 15189 accreditation acceleration:Clinical laboratories pursuing quality certification require documented assay validation and instrument calibration protocols, favoring vendors with integrated quality management software.
- Microfluidic-electrochemical convergence:Miniaturized channels with integrated electrode arrays enable simultaneous aggregation and secretion measurements from single microliter samples, differentiating platforms in research-contract markets.
Industry Challenges
- CLSI guideline implementation lag:Updated recommendations for platelet function testing require substantial retraining of laboratory technologists and revision of standard operating procedures, delaying assay standardization.
- Integration with legacy laboratory information systems:Hospital IT departments resist middleware modifications for single-purpose devices, forcing vendors to absorb customization costs or cede procurement decisions.
- Anticoagulant interference compensation:Direct oral anticoagulants distort optical and impedance readouts in unpredictable patterns, requiring algorithmic corrections that extend regulatory validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Platelet Aggregation Devices Market |
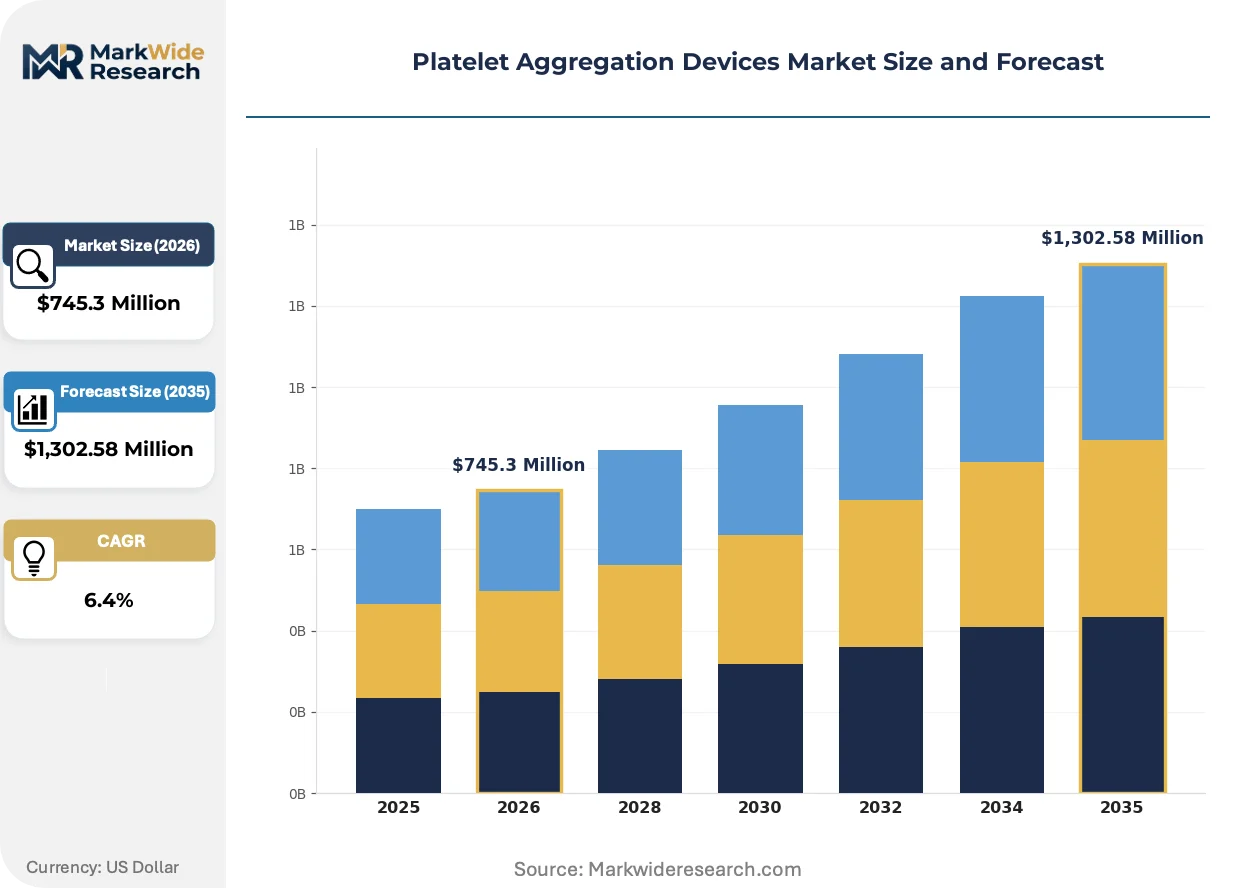
| Market Size in 2026 | $745.3 Million |
| Market Size in 2035 | $1,302.58 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Aggregometers, Electromechanical Devices, Multi-Channel Systems, Point-of-Care Devices End User: Hospitals, Clinical Laboratories, Research Institutions, Blood Banks Technology: Fluorescence-Based, Light Transmission, Impedance-Based, Microfluidic Application: Cardiovascular Disease, Hematological Disorders, Surgical Procedures, Drug Testing |
| Companies Covered | F. Hoffmann-La Roche Ltd, Sysmex Corporation, Haemonetics Corporation, Siemens Healthineers AG, Werfen, Bio/Data Corporation, Chrono-Log Corporation, AggreDyne Inc, Abbott, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Platelet Aggregation Devices Market Strategic Shifts & Innovations
Device architectures are fragmenting into configurable subsystems that hospitals mix according to procedural volume and space constraints, displacing monolithic platforms that dominated prior procurement cycles.
Microfluidic cartridge technology is modularizing platelet aggregation workflows into disposable, single-test units that plug into shared analyzer bases. Medium-volume hospitals in Germany and Japan are adopting these systems to preserve capital budgets while expanding test menus. The shift is compressing service revenue models toward consumable contracts and away from instrument-centric financing.
Japan's PMDA has tightened software validation requirements for Class II diagnostic devices with automated result interpretation, extending clearance timelines by 8-14 months for platforms with embedded clinical decision support. Manufacturers are responding by segregating software modules into separate regulatory submissions or stripping interpretive algorithms entirely. Point-of-care devices with locked result displays face the steepest compliance burden under this framework.
Hospital procurement committees are consolidating vendor relationships through multi-year enterprise agreements that bundle platelet function testing with coagulation and hematology platforms. Integrated delivery networks in the United States now favor vendors offering cross-platform quality control data management and unified service response. This concentration is marginalizing standalone aggregation specialists in favor of diversified diagnostics portfolios.
Platelet Aggregation Devices Market Segmentation
Platelet aggregation devices fragment into distinct technical and operational categories that determine integration depth, workflow placement, and procurement economics. Understanding these segment boundaries clarifies why certain configurations dominate catheterization laboratories while others anchor centralized laboratory infrastructure.
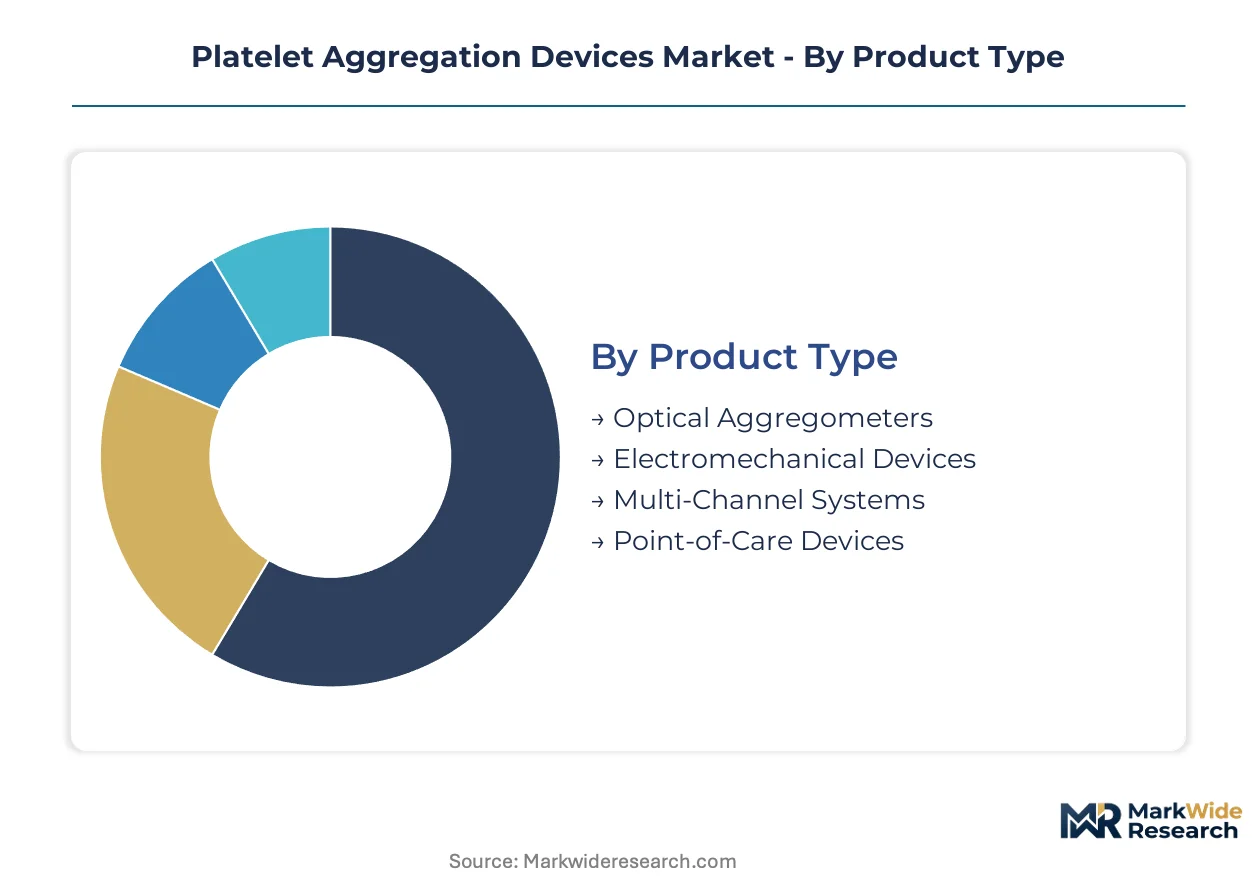
Product Type:
Standalone benchtop systems serve high-throughput environments, whereas cartridge-based platforms embed into distributed care settings with limited technical staff.
- Optical Aggregometers:Light-transmission systems measure platelet clumping through changes in sample turbidity using precision photodetectors and stabilized LED sources. These instruments concentrate in academic medical centers and reference laboratories across the United States and Germany where standardized protocols for antiplatelet therapy monitoring require documented correlation with decades of clinical literature.
- Point-of-Care Devices:Cartridge-based analyzers deliver results within 15 minutes without centrifugation, embedding directly into emergency departments and catheterization labs. Demand concentrates in Japanese and US hospital networks where per-procedural reimbursement codes justify premium consumable pricing over laboratory throughput.
- Electromechanical Devices:Force-displacement sensors detect aggregate formation through mechanical resistance changes in whole blood samples.
- Multi-Channel Systems:Parallel assay architectures enable simultaneous agonist testing across multiple sample positions for high-volume screening protocols.
Optical aggregometers lead volumes today; point-of-care devices are gaining share fastest.
End User:
Procurement authority shifts from laboratory directors to surgical department chairs as testing migrates from centralized facilities toward procedural suites.
- Hospitals:Integrated delivery networks bundle aggregation testing with coagulation and hematology platforms through multi-year enterprise agreements. These contracts favor vendors offering cross-platform quality control data management and unified service response, consolidating vendor relationships in US and German hospital systems.
- Clinical Laboratories:ISO 15189-accredited facilities require documented assay validation and instrument calibration protocols. Laboratories in Japan and Germany prioritize vendors with integrated quality management software that streamlines accreditation maintenance and audit preparation.
- Research Institutions:Academic centers demand configurable agonist panels and raw data export capabilities for protocol customization.
- Blood Banks:Pre-transfusion screening workflows prioritize high-throughput batch processing over rapid turnaround.
Hospitals command the largest procurement budgets; clinical laboratories retain the most standardized reagent consumption profiles.
Technology:
Detection modality determines sample preparation requirements, throughput capacity, and correlation with historical clinical data repositories.
- Light Transmission:Turbidimetric detection remains the gold-standard methodology with extensive clinical validation across cardiovascular and hematological applications. German and Japanese regulatory submissions continue to predicate novel devices against this established measurement principle.
- Impedance-Based:Whole-blood methods eliminate centrifugation steps and reduce sample volumes below 100 microliters. Neonatal intensive care units and trauma bays in US academic medical centers adopt these systems where sample conservation outweighs correlation with historical optical datasets.
- Fluorescence-Based:Label-dependent detection enables simultaneous aggregation and secretion measurements for research applications.
- Microfluidic:Miniaturized channel architectures integrate electrode arrays for multi-parameter analysis from single-microliter samples.
Light transmission anchors the largest installed base; impedance-based methods are expanding most quickly into previously untestable patient populations.
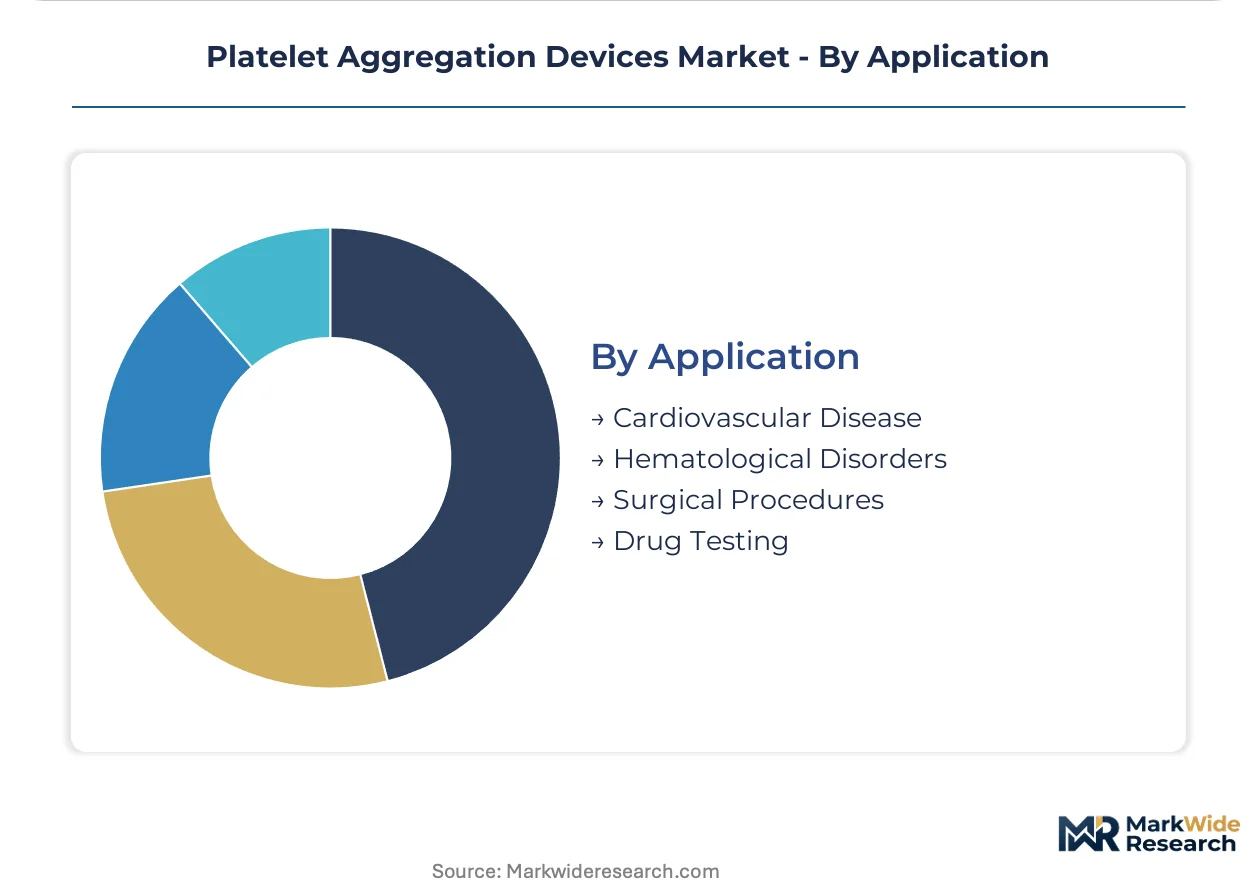
Application:
Clinical indication determines agonist selection, reference range validation, and reimbursement pathway eligibility.
- Cardiovascular Disease:Coronary stenting and cardiac surgery protocols mandate platelet function testing to guide P2Y12 inhibitor selection and dosing. Japanese and US catheterization laboratories drive procedural volume concentration where antiplatelet resistance testing influences interventional strategy.
- Surgical Procedures:Perioperative coagulation monitoring is hardening into mandatory standards across cardiac and orthopedic surgery suites. German hospital procurement committees now require validated aggregation assays against specific antiplatelet regimens rather than generic reference ranges.
- Hematological Disorders:Inherited platelet function defects and monitoring of myeloproliferative neoplasms require specialized agonist panels.
- Drug Testing:Pharmaceutical development programs utilize aggregation platforms for compound screening and mechanism-of-action studies.
Cardiovascular applications generate the highest test volumes; surgical procedure integration shows the steepest protocol adoption trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as device makers relocate assembly to jurisdictions with streamlined medical device pathways, particularly where FDA predicate equivalence requirements create cost-of-compliance gaps against emerging markets with adaptive approval frameworks.
United States
Catheterization laboratories in Cleveland Clinic and Mayo Clinic networks drive procedural volume concentration for antiplatelet resistance testing. FDA 510(k) clearance timelines average 90-150 days for optical aggregometer predicates, compressing design freedom for novel detection modalities. Boston's Route 128 corridor hosts contract manufacturers specializing in precision photodetectors for light-transmission systems.
Germany
Perioperative coagulation protocols in cardiac surgery suites at Charité Berlin and Heidelberg University Hospital mandate validated aggregation assays against specific antiplatelet regimens. EMA In Vitro Diagnostic Regulation traceability requirements elevate barriers for low-cost competitors, protecting validated instrument vendors in hospital procurement. The Baden-Württemberg medical technology cluster concentrates electromechanical device assembly.
Japan
Aging demographics at Tokyo's St. Luke's International Hospital and Osaka University Hospital sustain stenting volumes requiring platelet function guidance. PMDA software validation requirements for Class II devices with automated interpretation extend clearance timelines by 8-14 months, forcing modular regulatory strategies. The Kobe biomedical innovation cluster anchors hematology automation platform development.
India
Domestic cardiac intervention volumes at New Delhi's All India Institute of Medical Sciences and Mumbai's Asian Heart Institute outpace laboratory infrastructure expansion. CDSCO medical device rules for in-vitro diagnostics create predicate pathways for optical platform registrations. The Hyderabad medical device manufacturing zone attracts contract assembly for cartridge-based systems.
China
Coronary stenting growth at Fuwai Hospital Beijing and Zhongshan Hospital Shanghai generates demand for localized aggregation testing protocols. NMPA Class II medical device registration requires clinical trial data for novel detection modalities, extending timelines against 510(k) predicates. The Suzhou industrial park concentrates microfluidic cartridge manufacturing for Asia-Pacific distribution.
Platelet Aggregation Devices Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated diagnostics portfolios commanding hospital procurement committees through multi-year enterprise agreements. The vendor base concentrates around three strategic archetypes: diversified hematology platform vendors, transfusion medicine workflow specialists, and point-of-care cartridge innovators. M&A activity targets quality management software capabilities for ISO 15189 accreditation support, while geographic expansion focuses on India's cardiac intervention infrastructure gaps.
Within the diversified platform tier, F. Hoffmann-La Roche Ltd and Sysmex Corporation occupy positions anchoring laboratory automation workflows across United States and Asia-Pacific installations. Siemens Healthineers AG exemplifies the integrated cardiovascular diagnostics archetype, bundling aggregation testing with coagulation platforms. Haemonetics Corporation represents the transfusion medicine specialization vector, with Werfen occupying a position in hemostasis testing consolidation. These four entities collectively illustrate how vendor relationships harden around cross-platform quality control data management and unified service response capabilities.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Sysmex Corporation |
| Haemonetics Corporation |
| Siemens Healthineers AG |
| Werfen |
| Bio/Data Corporation |
| Chrono-Log Corporation |
| AggreDyne Inc |
| Abbott |
| Others |
Cost & Logistics Intelligence
Precision photonics engineering talent in Bavaria and Osaka commands wage premiums that widen spreads between premium optical aggregometers and economy-tier impedance systems. Labor-cost differentials in these clusters directly feed into tiered pricing architectures, with German and Japanese assembly carrying 40-60% overhead premiums against contract manufacturing in Hyderabad or Suzhou.
Pricing Analysis
Distributor margins for cartridge-based point-of-care devices absorb 25-35% of end-user price across US hospital networks, compressing manufacturer yields. Three-tier pricing structure across premium, standard, and economy levels segments by detection modality and software sophistication, with optical platforms commanding brand premiums tied to FDA 510(k) predicate lineage. Pricing pressure stems from Medicare reimbursement compression for routine platelet function monitoring outside procedural codes. Blood banks exhibit highest price sensitivity due to budget constraints, while catheterization laboratories prioritize turnaround time over per-test economics.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore anchor hub-and-spoke patterns for Asia-Pacific and European hospital procurement. Precision photodetectors and stabilized LED sources concentrate among Japanese and German component suppliers, with final assembly drawing from contract manufacturers in China and India. Single-source vulnerability runs through photonics component suppliers in Osaka and Munich, where specialized clean-room fabrication capacity remains captive to incumbent relationships. Distribution runs through diversified diagnostics distributors bundling aggregation testing with hematology and coagulation platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microfluidic miniaturization and consumable contract conversion are compressing capital-equipment margins while expanding recurring revenue pools. Premium-tier shifts toward integrated quality management software and ISO 15189 accreditation support packages justify pricing power against commodity hardware competitors.
For Market Incumbents: Cement cross-platform quality control data management capabilities that unify service response across hematology, coagulation, and aggregation portfolios. Lock in multi-year enterprise agreements with integrated delivery networks before emerging point-of-care specialists achieve FDA 510(k) clearance for cartridge-based alternatives. Vertical integration into precision photonics component supply buffers against lead-time volatility from Osaka and Munich suppliers. For New Entrants and Emerging Players: Impedance-based whole-blood detection without centrifugation requirements offers the most penetrable wedge for neonatal intensive care and trauma bay applications excluded from optical platform protocols. Target India's domestic stenting expansion where laboratory infrastructure lags procedural volume growth and cold-chain independence commands procurement priority. Pursue CDSCO optical predicate pathways to accelerate regulatory positioning against 510(k) timeline disadvantages. For Investors and Strategic Acquirers: Diversified hematology platform vendors are the most active acquirer in this space, targeting quality management software capabilities for ISO 15189 accreditation support. Five-to-ten year viability hinges on consumable contract conversion rates and microfluidic-electrochemical convergence R&D pipelines. Watch PMDA software validation timeline extensions for Class II devices with automated interpretation as inflection indicator for modular regulatory strategy adoption.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Predicate device selection against legacy optical platforms determines clearance timeline and design freedom constraints. |
| CE Marking Pathway | EMA In Vitro Diagnostic Regulation traceability requirements elevate barriers protecting validated European vendors. |
| Hospital System Partnership | Enterprise agreements bundling aggregation with coagulation platforms consolidate vendor relationships in US and German networks. |
| Software Companion Development | Integrated quality management modules streamline ISO 15189 accreditation maintenance for Japanese and German laboratories. |
| Reimbursement Strategy | Per-procedural coding alignment determines point-of-care expansion feasibility outside catheterization laboratory settings. |
Research Approach
Bottom-up hospital and clinical laboratory modeling reconciled against top-down precision photonics component tracking forms the analytical core of this study. Primary interviews with catheterization laboratory directors, biomedical engineers, hospital purchasing committee members, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EMA In Vitro Diagnostic Regulation documentation, hospital procurement databases, and CMS Medicare reimbursement schedules. Cross-referencing bottom-up installation data against top-down supplier shipment records tightens volume estimates across the analysis window.
Historical trendline analysis of optical aggregometer placement and point-of-care cartridge consumption established baseline growth trajectories. Segmentation modeling spans product type, detection technology, end-user facility tier, and regional regulatory cluster, with CAGRs derived from slope analysis of normalized adoption curves. Antiplatelet therapy protocol penetration rates and perioperative coagulation monitoring mandate expansion serve as procedure-volume proxies for device demand forecasting.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to PMDA software validation timeline shifts, Medicare reimbursement code revisions, and anticoagulant interference compensation algorithm breakthroughs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Instruments
Point-of-Care Diagnostic Analyzer Accuracy and Interference Test Equipment Market
Diagnostic Instruments
Auto Chemistry Analyzers Market
Diagnostic Instruments
Diagnostic Electrocardiograph Market
Diagnostic Instruments
Ultrasound-Guided Breast Biopsy Market
Diagnostic Instruments
Genetic Analyzers Market
Diagnostic Instruments
Dental Fluorescence Analyzer Market
Diagnostic Instruments
Pathological Examination Market
Diagnostic Instruments
Vascular Testing Devices Market
Diagnostic Instruments
Pathology Instruments Market
Diagnostic Instruments
Gram Staining System Market
Diagnostic Instruments
Global Radioimmunoassay Market
Diagnostic Instruments
Global Blood Coagulation Analyzer Market
Diagnostic Instruments
Dry Chemistry Analyzers Market
Diagnostic Instruments
Gastroesophageal Ph Meter Market
Diagnostic Instruments
Europe Immunoassay-Gamma Counters Market
Diagnostic Instruments
Global Chemiluminescence Immunoassay (CLIA) Analyzers Market