
 Luminometers Market | 2026-2036
Luminometers Market Size, Share, and Industry Trends Forecast 2026-2036
Luminometers Market Outlook
Consolidation among contract research organizations and large pharmaceutical quality control departments is repositioning purchasing power toward fewer buyers with larger fleet orders. Thermo Fisher Scientific leverages its installed base of analytical instruments to cross-sell multi-mode luminometer platforms into centralized lab networks. Berthold Technologies anchors its position through specialized detection sensitivity in low-light bioluminescence applications where precision thresholds are non-negotiable.
A luminometer measures light emission from chemical, biological, or enzymatic reactions, typically detecting photon counts in the range of 10⁻¹⁵ to 10⁻²¹ moles per second using photomultiplier tubes or charge-coupled devices. The instrument serves as a core analytical platform for quantifying ATP, luciferase reporter gene expression, and immunoassay signal amplification in regulated environments. Benchtop luminometers retain the largest installed base due to their balance of throughput and capital cost, while multi-mode configurations capture expanding margin pools as laboratories seek consolidated detection platforms. Chemiluminescence technology dominates routine clinical and pharmaceutical applications, though bioluminescence formats gain traction in live-cell kinetic assays where substrate specificity reduces background interference.
FDA 21 CFR Part 11 compliance requirements shape software architecture and validation documentation demands for luminometer vendors serving US clinical diagnostics and pharmaceutical quality control markets. ISO 13485 quality management standards and the EU In Vitro Diagnostic Regulation create parallel certification burdens for instruments deployed in European healthcare settings. Stakeholders must monitor evolving harmonization gaps between FDA predicate device pathways and EMA notified body expectations as dual-market product strategies face divergent evidentiary requirements.
Market Dynamics
Consolidation among pharmaceutical quality control departments and contract research organizations is concentrating purchasing power into fewer buyers placing larger fleet orders, while FDA 21 CFR Part 11 compliance requirements reshape software architecture investments across the vendor base.
Growth Catalysts
- High-throughput screening expansion:Pharmaceutical research laboratories are scaling luminometer procurement to support automated drug discovery workflows, with multi-mode detection platforms capturing preference for consolidated analytical infrastructure.
- FDA 21 CFR Part 11 mandates:Electronic records and signature requirements are accelerating validated software architectures among vendors serving US clinical diagnostics and pharmaceutical quality control markets.
- Bioluminescence sensitivity demands:Live-cell kinetic assay applications in precision medicine research are driving procurement of specialized low-light detection systems where photon threshold precision is non-negotiable.
Market Restraints
- Photomultiplier tube supply concentration:Core detector component manufacturing concentrates among specialized Japanese and German suppliers, creating vulnerability to semiconductor foundry allocation constraints.
- Validation documentation burdens:ISO 13485 quality management standards and EU In Vitro Diagnostic Regulation impose parallel certification requirements that extend product launch timelines for dual-market strategies.
- Charge-coupled device substitution:Solid-state imaging sensors are displacing traditional photomultiplier configurations in certain high-throughput applications, compressing margins for single-detector luminometer architectures.
Strategic Opportunities
- Point-of-care diagnostics expansion:Miniaturized luminometer platforms for decentralized clinical testing in India and Brazil present underpenetrated demand for portable ATP detection and rapid immunoassay systems.
- Environmental monitoring applications:Water quality testing and bioremediation assessment are emerging as adjacent use cases for bioluminescence-based toxicity screening outside traditional laboratory settings.
- AI-assisted data interpretation:Machine learning integration with luminometer software is automating complex kinetic analysis and reducing manual curve-fitting expertise requirements in high-throughput facilities.
Industry Challenges
- Photonics engineering talent scarcity:Specialized expertise in low-noise signal amplification and detector calibration is concentrating among legacy instrument manufacturers, constraining vendor R&D expansion.
- Legacy system integration complexity:Pharmaceutical quality control laboratories face friction connecting new luminometer platforms to established laboratory information management systems and electronic batch records infrastructure.
- Harmonization gap navigation:Divergent evidentiary requirements between FDA predicate device pathways and EMA notified body expectations complicate dual-market product development strategies for instrument vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luminometers Market |
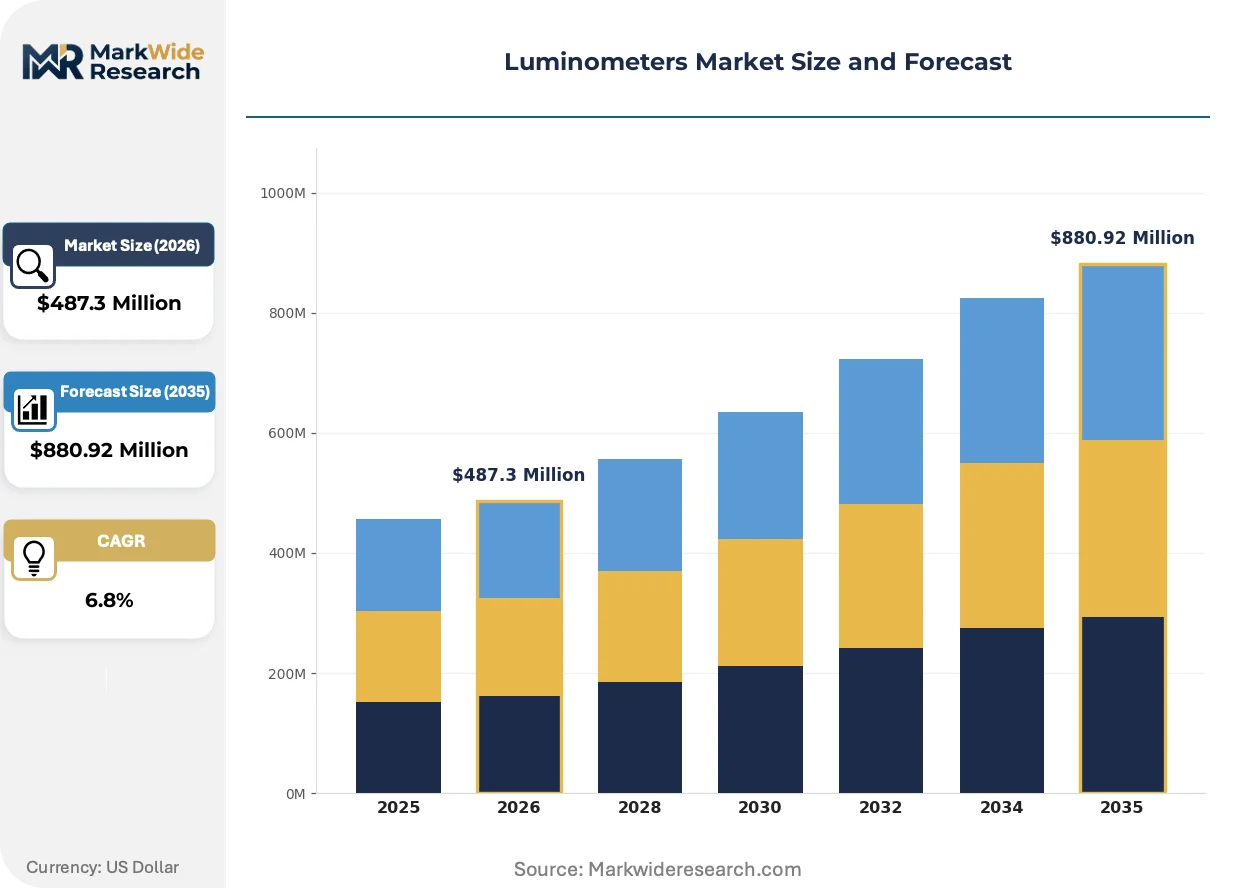
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Luminometers, Benchtop Luminometers, High-Throughput Luminometers, Multi-Mode Luminometers Application: Environmental Monitoring, Clinical Diagnostics, Food Safety Testing, Pharmaceutical Research End User: Hospitals, Laboratories, Research Institutions, Quality Control Departments Technology: Chemiluminescence, Bioluminescence, Fluorescence, Quantum Dots |
| Companies Covered | PerkinElmer, Thermo Fisher Scientific, Berthold Technologies, Bio-Rad Laboratories, Promega Corporation, Analytik Jena, BioTek Instruments, Agilent Technologies, Tecan Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luminometers Market Strategic Shifts
Detection platform convergence, regulatory software mandates, and procurement centralization are restructuring how luminometer capabilities are packaged, validated, and acquired across pharmaceutical and clinical laboratory networks.
Microplate-based luminometer systems with integrated fluid handling are automating sample preparation and reagent dispensing workflows that previously required separate robotic platforms. Large pharmaceutical screening facilities are adopting these configurations to compress assay turnaround times and reduce manual intervention error rates. The technology is automating technician-intensive steps that historically constrained throughput scaling in high-volume drug discovery operations.
The EU In Vitro Diagnostic Regulation's performance evaluation and post-market surveillance requirements are extending certification timelines for luminometers deployed in European healthcare settings. Manufacturers must now maintain technical documentation and clinical evidence packages that exceed predecessor directive standards. In vitro diagnostic instrument vendors serving dual US-European markets are restructuring quality management systems to accommodate divergent notified body expectations.
Centralized procurement by integrated delivery networks and pharmaceutical conglomerates is consolidating vendor relationships around multi-year service contracts with performance-based uptime guarantees. Independent laboratories and smaller research facilities are losing negotiating leverage as purchasing authority concentrates among fewer buyers with standardized fleet specifications. This concentration is most visible in the United States, where CLIA-certified laboratory networks and biopharma R&D consortia dominate replacement cycle timing.
Luminometers Market Segmentation
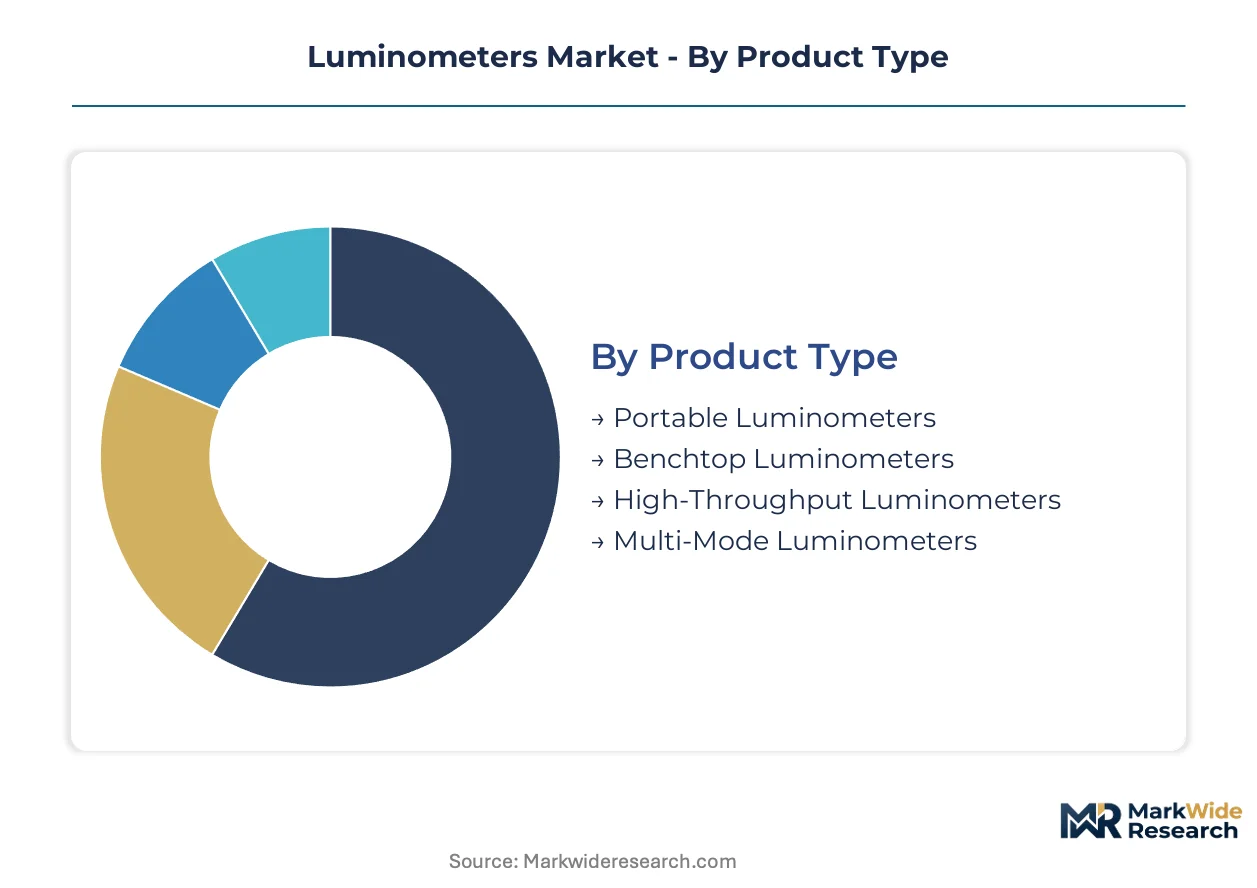
Luminometer procurement patterns diverge sharply across detection platforms and deployment contexts, with pharmaceutical conglomerates driving consolidation toward multi-mode systems while decentralized testing expands portable unit adoption. Segmentation reveals how capital intensity, regulatory compliance burdens, and throughput requirements reshape vendor-customer relationships across distinct operational environments.
Product Type:
Capital allocation thresholds and workflow automation requirements determine instrument selection across laboratory networks.
- Benchtop Luminometers:These systems balance detection sensitivity with moderate capital expenditure, typically housing single-mode photomultiplier configurations for routine ATP and reporter gene quantification. Demand concentrates in United States CLIA-certified clinical laboratories and mid-sized pharmaceutical quality control departments where instrument replacement cycles follow 5-7 year depreciation schedules.
- Multi-Mode Luminometers:Integrated detection platforms combine luminometric, fluorometric, and absorbance capabilities within unified software architectures. Large pharmaceutical screening facilities in Massachusetts and California prefer these configurations to consolidate analytical infrastructure and reduce per-assay capital footprint across high-throughput workflows.
- Portable Luminometers:Battery-operated units with simplified photodiode detectors serve field-based environmental monitoring and rapid ATP hygiene testing in food processing facilities.
- High-Throughput Luminometers:Robotic integration and 384/1536-well microplate compatibility characterize these systems for automated drug discovery pipelines.
Benchtop luminometers lead on scale; multi-mode luminometers lead on momentum.
Application:
Regulatory validation requirements and reimbursement pathways create divergent procurement timelines across use cases.
- Pharmaceutical Research:High-throughput screening and lead optimization workflows demand instruments with validated 21 CFR Part 11 software for electronic records compliance. Contract research organizations in Research Triangle Park and San Diego biotech clusters drive fleet orders with multi-year service contracts.
- Clinical Diagnostics:Immunoassay quantification and infectious disease detection require ISO 13485-certified instruments with documented analytical performance. United States hospital laboratories prioritize FDA-cleared platforms with established predicate device pathways to accelerate validation.
- Food Safety Testing:ATP bioluminescence systems verify surface hygiene and microbial contamination in processing facilities with rapid turnaround requirements.
- Environmental Monitoring:Toxicity screening and bioremediation assessment applications leverage bioluminescent bacterial reporters for water quality evaluation.
Clinical diagnostics commands the largest installed base; pharmaceutical research exhibits the steepest expansion trajectory.
End User:
Organizational scale and regulatory exposure shape specifications, service expectations, and vendor selection criteria.
- Quality Control Departments:Embedded within pharmaceutical manufacturing operations, these units require instruments with comprehensive IQ/OQ/PQ documentation and integration with electronic batch records systems. FDA inspection readiness drives preference for vendors with established validation support infrastructure.
- Research Institutions:Academic and government laboratories prioritize detection sensitivity and publication-grade reproducibility over throughput metrics, with NIH-funded facilities in Bethesda and university cores in Boston representing concentrated demand.
- Laboratories:Independent clinical reference laboratories and contract testing facilities balance capital constraints with CLIA proficiency testing requirements.
- Hospitals:Point-of-care and central laboratory units seek FDA-cleared platforms with streamlined operator training protocols.
Quality control departments anchor revenue concentration; research institutions show the most rapid technology adoption.
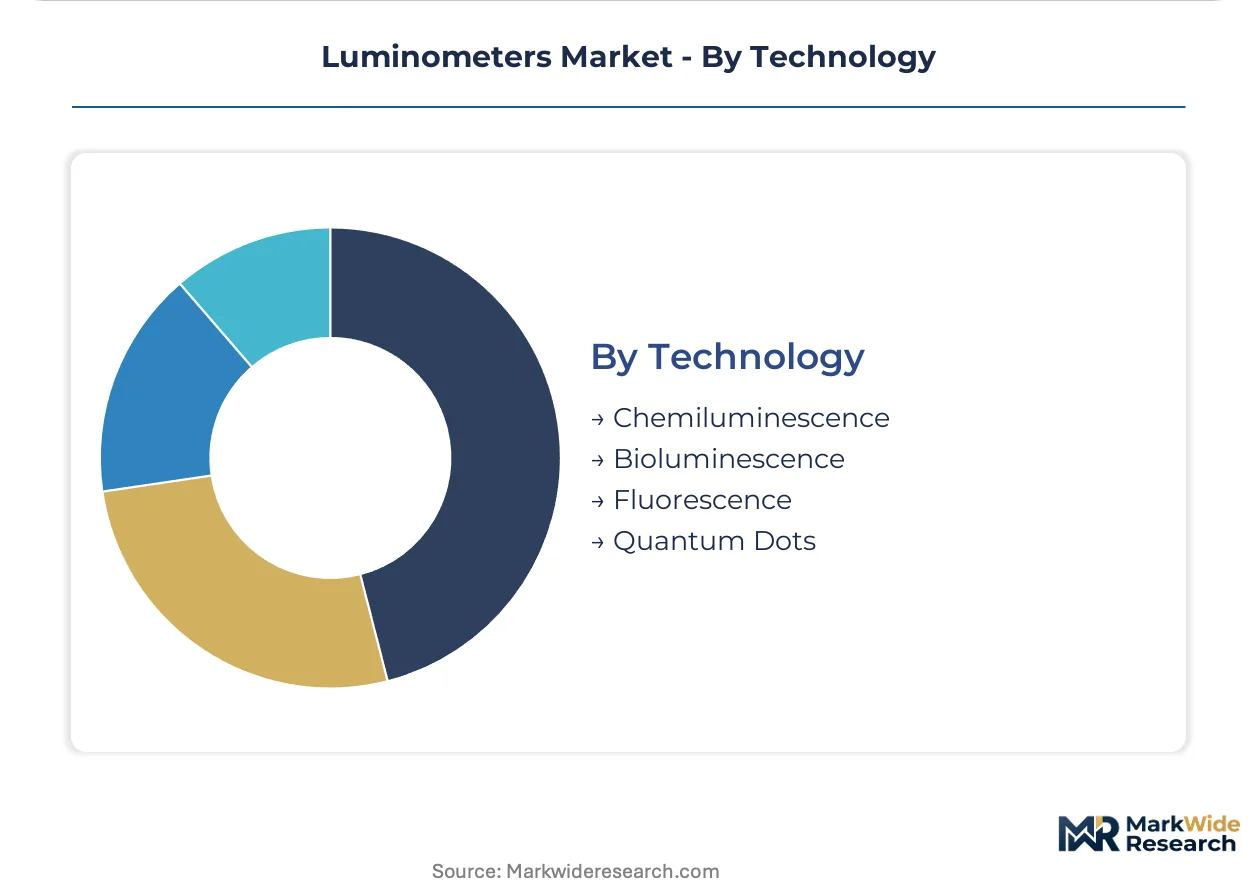
Technology:
Signal generation mechanisms determine sensitivity thresholds, reagent cost structures, and application compatibility.
- Chemiluminescence:Enzyme-catalyzed light emission with horseradish peroxidase or alkaline phosphatase conjugates dominates clinical immunoassays and Western blot detection. The technology's established reagent supply chains and broad assay compatibility sustain its prevalence in United States diagnostic laboratories.
- Bioluminescence:Luciferase-catalyzed photon production from ATP or reporter gene substrates enables attomole-level detection with minimal background interference. Live-cell kinetic applications in precision medicine research at Stanford and Broad Institute facilities drive specialized low-light detector procurement.
- Fluorescence:Excitation-emission detection extends multi-mode platform utility for protein quantification and cell viability assays.
- Quantum Dots:Semiconductor nanocrystal probes offer photostability and multiplexing capabilities for advanced imaging applications.
Chemiluminescence retains volume leadership; bioluminescence gains share fastest in high-sensitivity research segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States outspends Germany on biopharma R&D instrumentation by a factor of three, yet German precision engineering maintains tighter control over photomultiplier tube supply chains. Japan's domestic diagnostic networks favor compact benchtop configurations, while Chinese procurement accelerates toward multi-mode platforms. India and Brazil present divergent growth trajectories shaped by regulatory maturity and import dependency.
United States
FDA 21 CFR Part 11 mandates drive validated software procurement across Massachusetts and California biopharma clusters. CLIA-certified laboratory networks in Research Triangle Park sustain 5-7 year replacement cycles for benchtop systems. Thermo Fisher Scientific leverages its installed base to cross-sell multi-mode platforms into centralized lab networks.
Germany
EU In Vitro Diagnostic Regulation extends certification timelines for instruments serving European healthcare settings. Berthold Technologies anchors its position through specialized detection sensitivity in low-light bioluminescence applications. The Baden-Württemberg precision engineering corridor concentrates photonics component manufacturing for global supply.
Japan
PMDA quality management standards shape domestic instrument validation requirements for clinical diagnostics. METI industrial policy supports domestic production of high-sensitivity photodetector components. Tokyo and Osaka metropolitan laboratory networks prioritize compact footprint systems for space-constrained facilities.
China
NMPA medical device registration pathways accelerate for instruments with established FDA predicate device documentation. Domestic pharmaceutical R&D spending concentrates in Yangtze River Delta screening facilities. Multi-mode detection platforms capture preference as laboratories consolidate analytical infrastructure.
India
CDSCO medical device rules create compliance barriers for imported instruments lacking local validation support. Contract research organizations in Hyderabad and Bangalore expand luminometer procurement for pharmaceutical quality control. Point-of-care diagnostic expansion in tier-2 cities drives portable ATP detection demand.
Luminometers Market Competitive Environment
United States producers anchor one tier; German specialists hold another through component-level precision. The vendor base stratifies between diversified analytical instrument conglomerates and focused photonics engineering houses. Three archetypes dominate: full-spectrum life science platforms, specialized bioluminescence detection houses, and precision photonics component integrators. Competitive moves concentrate on cross-selling into installed bases and securing multi-year service contracts with uptime guarantees.
Within the diversified platform tier, Thermo Fisher Scientific and PerkinElmer exemplify scale-driven consolidation strategies. Berthold Technologies occupies a specialized position anchored on detection sensitivity thresholds. Bio-Rad Laboratories sits within the analytical instrumentation mid-tier, representing the research-reagent-integrated model. These three anchors illustrate how procurement centralization favors vendors with comprehensive validation documentation and established FDA compliance track records.
| Leading Market Players |
|---|
| PerkinElmer |
| Thermo Fisher Scientific |
| Berthold Technologies |
| Bio-Rad Laboratories |
| Promega Corporation |
| Analytik Jena |
| BioTek Instruments |
| Agilent Technologies |
| Tecan Group |
| Others |
Value Chain & Pricing Dynamics
Photonics engineering talent scarcity in Baden-Württemberg and Hamamatsu widens pricing spreads between premium multi-mode platforms and entry-level benchtop units, as labor-cost differentials in detector calibration and low-noise amplification cascade through finished-instrument tiers.
Pricing Analysis
Capacity additions in China are reshaping price floors for portable luminometer configurations serving environmental monitoring applications. Pricing stratifies across premium multi-mode platforms with validated 21 CFR Part 11 software, standard benchtop systems for CLIA-certified laboratories, and economy photodiode-based units for rapid ATP hygiene testing. Cost compression in the economy tier intensifies because solid-state detector substitution erodes photomultiplier tube premiums. Contract research organizations exhibit the highest price sensitivity due to fleet standardization mandates, while pharmaceutical quality control departments prioritize compliance documentation over unit cost.
Supply Chain Analysis
Refurbishment flows for legacy photomultiplier tube assemblies extend component lifecycles in European and North American service networks. Manufacturing concentrates in Germany, Japan, and the United States for precision detector components, with final instrument assembly distributed across these same markets. Core supply rests on specialized photomultiplier tubes, charge-coupled device sensors, and validated software modules. Single-source vulnerability concentrates in Japanese photonics foundries serving high-sensitivity bioluminescence applications. Distribution runs through direct vendor relationships with pharmaceutical conglomerates and regional distributors serving independent clinical laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The luminometer market functions as a regulatory compounder where FDA 21 CFR Part 11 electronic records mandates create sustained replacement demand across pharmaceutical quality control networks.
For Market Incumbents: To counter charge-coupled device substitution in high-throughput screening segments, anchor customer relationships through multi-year service contracts with uptime guarantees and deepen backward integration into photomultiplier tube refurbishment capabilities to secure detector supply continuity. For New Entrants and Emerging Players: Enter via point-of-care diagnostic expansion in Indian tier-2 cities where CDSCO compliance barriers have slowed multinational penetration, targeting portable ATP detection systems for food safety and environmental monitoring with localized validation support infrastructure. For Investors and Strategic Acquirers: Diversified analytical instrument conglomerates are the most active acquirer in this space, seeking specialized bioluminescence detection houses to fill sensitivity gaps in precision medicine research portfolios. Over a five-to-ten-year horizon, consolidation around multi-mode platforms favors targets with established FDA predicate device pathways. Monitor PMDA and NMPA harmonization progress with FDA standards as an inflection signal for dual-market product strategies.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 21 CFR Part 11 Software Validation | Accelerates procurement cycles in Massachusetts and California biopharma clusters requiring electronic records compliance. |
| Photomultiplier Tube Backward Integration | Secures detector supply continuity against Japanese and German foundry allocation constraints. |
| Multi-Mode Platform Convergence | Consolidates analytical infrastructure for large pharmaceutical screening facilities seeking reduced per-assay capital footprint. |
| Point-of-Care Miniaturization | Captures underpenetrated demand in Indian and Brazilian decentralized clinical testing markets. |
| AI-Assisted Kinetic Analysis | Reduces manual curve-fitting expertise requirements in high-throughput drug discovery operations. |
Study Parameters
Direct dialogue with pharmaceutical quality control directors, CLIA laboratory managers, regulatory affairs specialists, and photonics component procurement leads grounded the qualitative assessment, cross-referenced against FDA 510(k) filings, EU MDR technical documentation, ISO 13485 certification databases, and SEC 10-K disclosures from analytical instrument manufacturers. Bottom-up instrument shipment estimates and top-down R&D expenditure allocations were triangulated to validate market sizing.
Bottom-up modeling segmented the market by detection platform, application context, and end-user scale across the projection horizon, with CAGRs derived from regression analysis against biopharma R&D spending trajectories and CLIA laboratory network expansion rates. Modeled dimensions included technology type, regulatory certification tier, and geographic procurement cluster.
Inputs from primary fieldwork and secondary regulatory databases were available through the study window; gaps in real-time photomultiplier tube production capacity data introduce uncertainty bands around near-term supply constraints. Forecasts reflect documented assumptions about FDA-EMA harmonization progress and semiconductor foundry allocation priorities. Practitioners should monitor EU MDR notified body capacity expansion and Japanese METI industrial policy adjustments for early signals of certification timeline compression.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Instruments
Diagnostic Electrocardiograph Market
Diagnostic Instruments
Pathological Examination Market
Diagnostic Instruments
Global Blood Gas and Electrolyte Analyzer Market
Diagnostic Instruments
Global Blood Coagulation Analyzer Market
Diagnostic Instruments
Hair Mineral Analyzer Market
Diagnostic Instruments
Global Point of Care Ultrasound Market
Diagnostic Instruments
Platelet Aggregation Devices Market
Diagnostic Instruments
Dental Fluorescence Analyzer Market
Diagnostic Instruments
Genetic Analyzers Market
Diagnostic Instruments
Immunochemistry Analyzer Market
Diagnostic Instruments
Global Wavefront Aberrometers Market
Diagnostic Instruments
Blood Flow Measurement Devices Market
Diagnostic Instruments
Vascular Testing Devices Market
Diagnostic Instruments
US Medical Thermometer Market
Diagnostic Instruments
Nasometry Devices Market
Diagnostic Instruments
Europe Immunoassay-Gamma Counters Market